
 Chronic Granulomatous Disease (CGD) Management Market | 2026-2036
Chronic Granulomatous Disease (CGD) Management Market Size, Share, and Industry Trends Forecast 2026-2036
Chronic Granulomatous Disease (CGD) Management Market Outlook
Good Manufacturing Practice certification for advanced therapy medicinal products is collapsing as the decisive barrier between preclinical gene therapy programs and commercial viability. Orchard Therapeutics sustains one of the most mature clinical pipelines in ex vivo hematopoietic stem cell gene therapy for CGD. Pfizer leverages its global manufacturing infrastructure to navigate the complex cold-chain logistics required for patient-specific cellular therapies. Novartis anchors its position through deep expertise in CAR-T commercialization that translates directly to autologous gene therapy distribution models.
Chronic Granulomatous Disease management encompasses prophylactic antimicrobial regimens, interferon-gamma immunomodulation, curative hematopoietic stem cell transplantation, and investigational gene replacement therapies targeting the NADPH oxidase complex deficiency underlying recurrent life-threatening infections. Interferon-gamma remains the established immunomodulatory backbone despite limited efficacy in certain genetic subtypes, while gene therapy approaches now demonstrate sustained oxidase restoration in X-linked and autosomal recessive forms. Antibiotics and antifungals occupy the largest volume share as lifelong prophylactic mainstays, though margin pools increasingly concentrate in the subcutaneous administration route where patients and caregivers prefer home-based delivery over chronic intravenous access.
FDA orphan drug exclusivity provisions and EMA's Committee for Advanced Therapies frame the regulatory terrain that determines clinical trial design, manufacturing scale-up timelines, and ultimate reimbursement negotiations for CGD gene therapies. The FDA's Risk Evaluation and Mitigation Strategy requirements for long-term follow-up of genetically modified cells impose substantial post-market surveillance obligations that shape commercialization economics. Stakeholders must monitor how CMS and major European HTA bodies calibrate value frameworks for single-administration curative therapies against decades of prophylactic pharmaceutical spending.
Market Dynamics
Gene therapy commercialization timelines are compressing against prophylactic pharmaceutical lifecycles, forcing reimbursement frameworks to reconcile one-time curative interventions against decades of chronic antimicrobial spending.
Growth Catalysts
- EMA Accelerated Assessment Pathways:The Committee for Advanced Therapies streamlines manufacturing scale-up timelines for autologous hematopoietic stem cell gene therapies, collapsing preclinical-to-commercial barriers.
- Subcutaneous Administration Preference:Patient and caregiver demand for home-based delivery over chronic intravenous access is reshaping route-of-administration development priorities.
- Specialty Clinic Expansion:Prophylactic therapy programs in dedicated immunology centers concentrate treatment volume and standardize long-term patient monitoring protocols.
Market Restraints
- Plasmid Manufacturing Bottlenecks:Viral vector production capacity constraints in contract manufacturing organizations limit batch yields for lentiviral-based gene therapies.
- FDA Risk Evaluation and Mitigation Strategy Burden:Post-market surveillance obligations for genetically modified cells impose fifteen-year follow-up costs that distort commercialization economics.
- Interferon-Gamma Efficacy Gaps:Limited response in p47-phox and p67-phox autosomal recessive subtypes restricts immunomodulatory backbone utility across genetic variant populations.
Strategic Opportunities
- CMS Value Framework Calibration:Medicare's emerging models for single-administration curative therapies against lifetime prophylactic spending create precedent-setting reimbursement pathways.
- Allogeneic Platform Migration:Off-the-shelf gene-edited hematopoietic stem cells eliminate patient-specific manufacturing logistics and collapse cold-chain complexity.
- Pediatric Indication Prioritization:Orphan drug exclusivity provisions incentivize first-line curative intervention before irreversible organ damage accumulates.
Industry Challenges
- Vector Immunogenicity Management:Pre-existing neutralizing antibodies against AAV serotypes exclude substantial patient populations from in vivo gene therapy candidacy.
- Long-Term Oxidase Durability:Sustained NADPH complex restoration beyond five years remains unvalidated in clinical cohorts, complicating payer value demonstrations.
- Conditioning Regimen Toxicity:Myeloablative chemotherapy requirements for ex vivo gene therapy enrollment limit applicability in patients with pre-existing organ dysfunction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chronic Granulomatous Disease (CGD) Management Market |
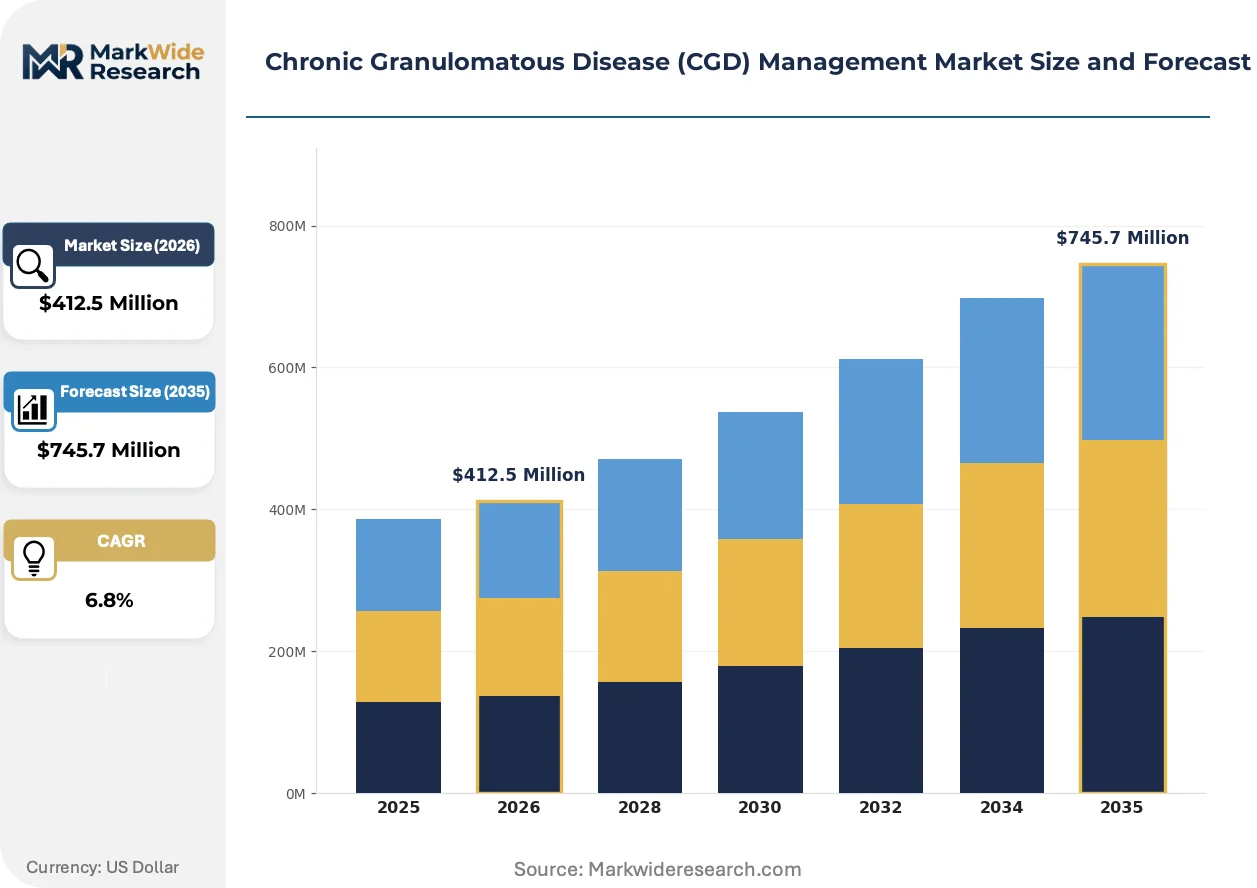
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interferon-gamma, Antibiotics, Antifungals, Corticosteroids Administration Route: Subcutaneous, Intravenous, Oral, Inhalation End User: Hospitals, Specialty Clinics, Home Care, Research Institutions Treatment Stage: Acute Phase, Maintenance Therapy, Preventive Care, Long-term Management |
| Companies Covered | Clinigen Group plc, Orchard Therapeutics plc, Horizon Therapeutics plc, Pfizer Inc., Amgen, Novartis AG, GlaxoSmithKline plc, Johnson & Johnson Services, Inc., Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chronic Granulomatous Disease (CGD) Management Market Strategic Shifts
Gene therapy manufacturing paradigms are fragmenting between centralized GMP facilities and distributed point-of-care production models, with regulatory harmonization lagging technical capability expansion.
Lentiviral vector production is bifurcating between stable producer cell lines and transient transfection systems. Large pharmaceutical manufacturers favor stable lines for batch consistency at commercial scale. Academic medical centers and mid-tier developers retain transient approaches for clinical trial flexibility. This technical divergence is compressing equipment supplier markets into platform-specific ecosystems with incompatible validation requirements.
FDA orphan drug exclusivity provisions now extend to gene therapy products with distinct vector designs targeting identical genetic defects. The industrial consequence is patent thicket formation around promoter and enhancer sequences. X-linked CGD programs face the most complex freedom-to-operate landscapes, with developers responding through licensing consortia and cross-royalty arrangements.
Caregiver-administered subcutaneous interferon-gamma is displacing clinic-based intravenous delivery in United States commercial channels. Home health nursing networks and specialty pharmacy distribution are capturing volume previously routed through hospital outpatient infusion centers. This channel rotation is most visible in employer-sponsored insurance populations where patient cost-sharing differentials drive site-of-care selection.
Chronic Granulomatous Disease (CGD) Management Market Segmentation
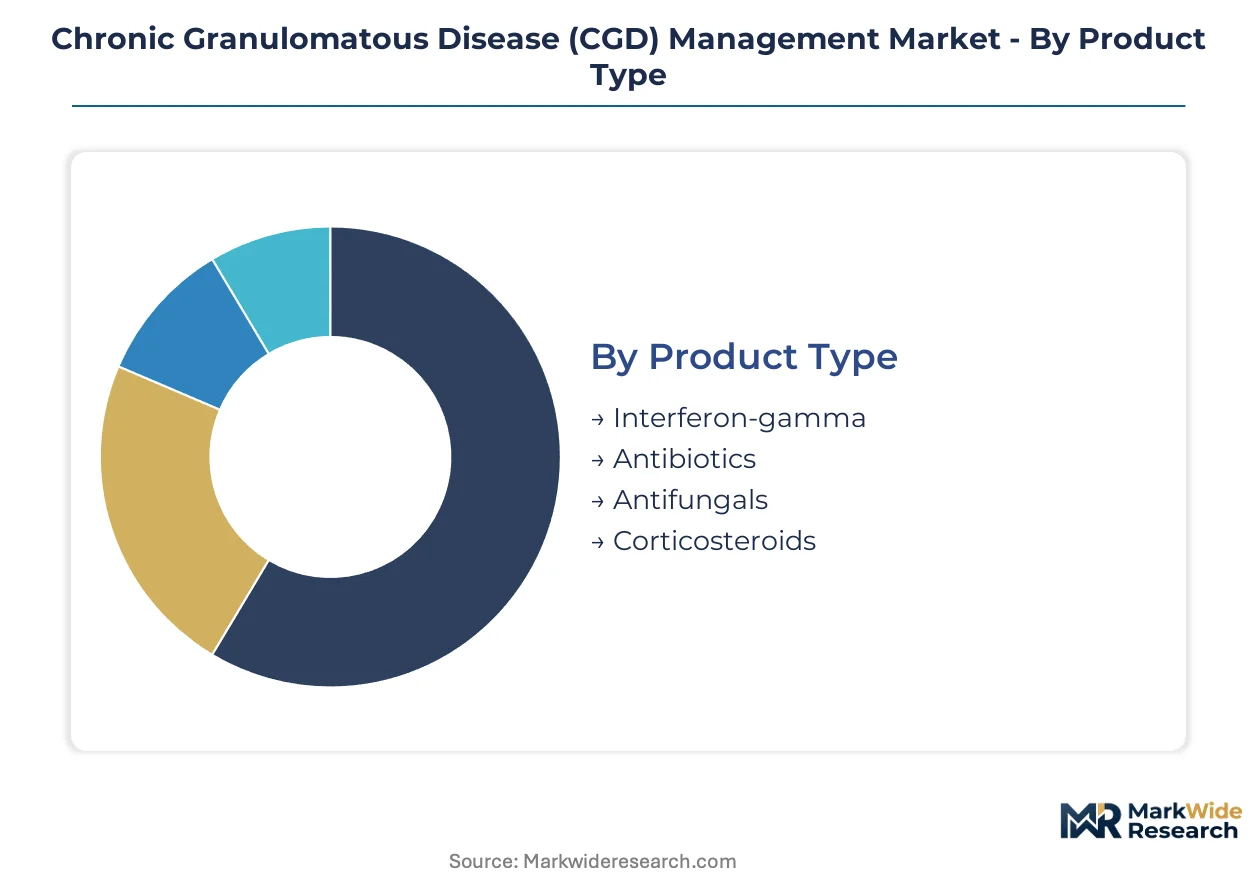
CGD management segmentation reveals how therapeutic modalities fragment across care settings and patient acuity levels. Product type and administration route combinations determine reimbursement codes, while end-user concentration shapes distribution infrastructure investments.
Product Type:
Antibiotics and antifungals dominate domestic prescription volumes in the United States, whereas interferon-gamma sees stronger export-linked manufacturing through European GMP facilities serving Middle Eastern and Asian markets.
- Antibiotics:Lifelong prophylactic trimethoprim-sulfamethoxazole constitutes the clinical backbone for infection prevention in X-linked and autosomal recessive subtypes. United States specialty pharmacies capture the majority of dispensed volume through 90-day maintenance programs. The established base commands here.
- Antifungals:Itraconazole and posaconazole prophylaxis targets Aspergillus species, the predominant fatal pathogen in CGD mortality. German and Swiss hospital networks drive concentrated demand for azole formulations with therapeutic drug monitoring protocols. The steepest expansion runs through this segment.
- Interferon-gamma:Recombinant human interferon-gamma 1b reduces infection frequency in compliant patients through macrophage priming. Japanese and South Korean regulators maintain distinct immunogenicity surveillance requirements affecting import logistics.
- Corticosteroids:Acute inflammatory exacerbations require pulsed glucocorticoid intervention, though chronic use risks immunosuppression in already compromised hosts. Indian generic manufacturers supply cost-sensitive markets across Southeast Asia.
Antibiotics command the established base. The steepest expansion runs through antifungals.
Administration Route:
Route selection stratifies across cost tiers, with subcutaneous delivery capturing premium reimbursement for home-based administration while oral generics compete on acquisition price.
- Subcutaneous:Patient-administered interferon-gamma via prefilled syringes eliminates infusion center dependency and reduces indirect medical costs. United States employer-sponsored plans increasingly mandate site-of-care optimization steering volume toward this modality. This route concentrates margin capture.
- Intravenous:Hospital outpatient departments retain control over acute antimicrobial administration and gene therapy conditioning regimens. United Kingdom NHS trusts and French university hospitals anchor European intravenous volume through centralized immunology centers.
- Oral:Azole antifungals and prophylactic antibiotics default to oral bioavailability for maintenance phases, with Brazilian and Mexican distribution networks expanding access in Latin American markets.
- Inhalation:Investigational liposomal amphotericin B formulations target pulmonary Aspergillus colonization directly, though nebulizer compliance limits adoption to highly monitored cohorts.
Subcutaneous delivery captures the highest reimbursement tier. Oral administration reaches the broadest patient population.
End User:
Customer type determines procurement sophistication, with research institutions driving investigational gene therapy demand while home care networks reshape chronic prophylactic fulfillment.
- Specialty Clinics:Dedicated immunology centers in Boston, London, and Tokyo concentrate longitudinal patient registries and standardized monitoring protocols that attract gene therapy trial sponsorship. These facilities coordinate the most complex care.
- Home Care:Skilled nursing networks and specialty pharmacies in California and Texas now administer subcutaneous interferon-gamma and monitor prophylactic compliance through remote patient platforms. This channel is expanding fastest.
- Hospitals:Academic medical centers manage acute infectious crises, hematopoietic stem cell transplantation, and myeloablative conditioning for ex vivo gene therapy enrollment.
- Research Institutions:NIH-funded centers and EU Framework Programme sites conduct natural history studies and early-phase gene therapy trials that shape regulatory precedent.
Specialty clinics anchor complex case management. Home care networks are expanding most quickly.
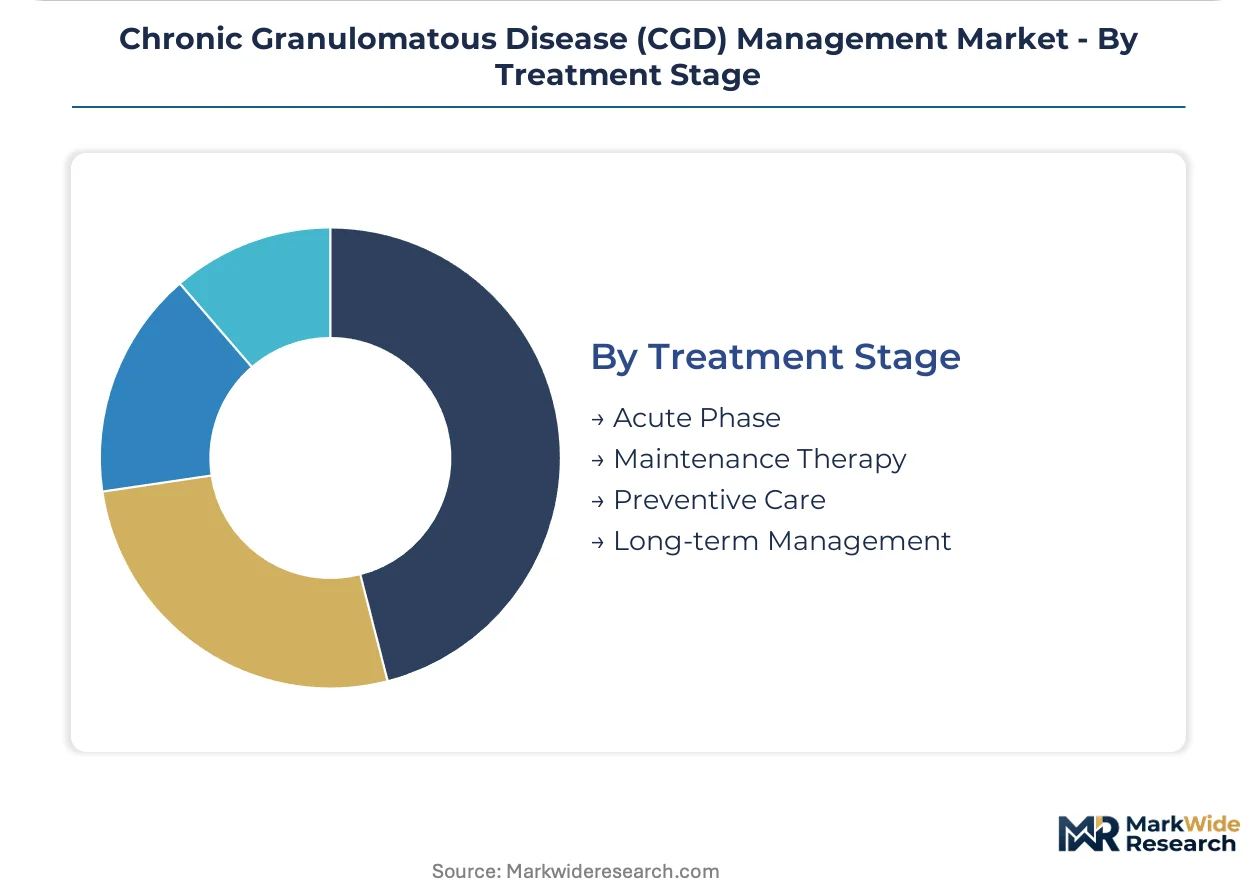
Treatment Stage:
Stage-based segmentation aligns with pharmaceutical lifecycle positioning, from acute rescue therapies to decades-long preventive regimens.
- Preventive Care:Daily antimicrobial prophylaxis and interferon-gamma immunomodulation constitute the perpetual baseline for all CGD patients regardless of genetic subtype. German and Austrian sick funds have established precedent for lifetime coverage commitments.
- Long-term Management:Curative gene therapy and allogeneic transplantation transition select patients off pharmaceutical dependency, though conditioning toxicity limits candidacy. This stage attracts the most capital investment.
- Acute Phase:Parenteral antibiotics and surgical intervention for deep-seated abscesses demand immediate hospitalization, with Staphylococcus aureus and Burkholderia cepacia complex driving empirical coverage decisions.
- Maintenance Therapy:Stabilized patients transition to oral suppressive regimens with quarterly infectious disease monitoring to detect breakthrough colonization.
Preventive care absorbs the majority of lifetime spending. Long-term management offers the only curative exit from chronic pharmaceutical dependency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Payer archetypes cluster around single-payer systems with lifetime coverage mandates and employer-sponsored plans favoring site-of-care optimization. Gene therapy trial sponsorship concentrates in academic medical centers with established immunology registries.
United States
Employer-sponsored insurance plans drive subcutaneous interferon-gamma demand through patient cost-sharing differentials. FDA orphan drug exclusivity provisions shape gene therapy commercialization timelines for developers targeting X-linked and autosomal recessive subtypes. Boston and San Francisco academic medical centers anchor the most mature clinical trial infrastructure for ex vivo hematopoietic stem cell gene therapy.
Germany
Sick funds have established precedent for lifetime coverage commitments to antimicrobial prophylaxis and interferon-gamma immunomodulation. EMA accelerated assessment pathways through the Committee for Advanced Therapies compress manufacturing scale-up timelines for autologous gene therapies. Frankfurt and Munich hospital networks concentrate therapeutic drug monitoring protocols for azole antifungal prophylaxis.
Japan
Distinct immunogenicity surveillance requirements for recombinant interferon-gamma affect import logistics and post-market pharmacovigilance obligations. PMDA consultations on regenerative medicine products frame clinical trial design for lentiviral-based gene therapies. Tokyo and Osaka immunology centers maintain longitudinal patient registries that attract multinational trial sponsorship.
United Kingdom
NHS trusts anchor European intravenous antimicrobial volume through centralized immunology centers with standardized monitoring protocols. NICE technology appraisals calibrate value frameworks for single-administration curative therapies against decades of prophylactic pharmaceutical spending. London and Cambridge academic medical centers coordinate EU Framework Programme sites conducting natural history studies.
Switzerland
Therapeutic drug monitoring protocols for posaconazole prophylaxis drive concentrated demand in German and Swiss hospital networks. Swissmedic licensing requirements for advanced therapy medicinal products impose GMP certification standards that prequalify manufacturers for broader European distribution. Basel and Zurich pharmaceutical clusters host contract manufacturing organizations serving viral vector production for gene therapy developers.
Chronic Granulomatous Disease (CGD) Management Market Competitive Environment
Player mix skews toward diversified pharmaceutical conglomerates with gene therapy platforms alongside specialty biotech developers with focused rare disease pipelines. Market structure exhibits tiered concentration with a handful of integrated manufacturers controlling viral vector production capacity and mid-tier developers dependent on contract manufacturing relationships. Strategic archetypes include platform-technology licensors, end-to-end gene therapy integrators, and prophylactic pharmaceutical incumbents. Competitive moves center on manufacturing capacity reservations in contract manufacturing organizations and cross-royalty arrangements to navigate patent thickets around promoter sequences.
Within the platform-technology tier, Orchard Therapeutics and Pfizer occupy positions exemplifying divergent scale advantages. Orchard Therapeutics represents the focused rare disease developer archetype with concentrated hematopoietic stem cell gene therapy expertise. Pfizer anchors the diversified conglomerate archetype leveraging global manufacturing infrastructure for patient-specific cellular therapy logistics. Novartis sits within the commercialization-expertise tier, translating CAR-T distribution models directly to autologous gene therapy market development.
| Leading Market Players |
|---|
| Clinigen Group plc |
| Orchard Therapeutics plc |
| Horizon Therapeutics plc |
| Pfizer Inc. |
| Amgen |
| Novartis AG |
| GlaxoSmithKline plc |
| Johnson & Johnson Services, Inc. |
| Merck KGaA |
| Others |
Value Chain & Pricing Dynamics
Subcutaneous interferon-gamma prefilled syringes displacing intravenous clinic administration are redrawing procurement geography toward United States specialty pharmacy networks while collapsing reimbursement differentials that previously sustained hospital outpatient margins. This substitution dynamic concentrates purchasing volume with distributors capable of cold-chain logistics at scale, compressing price realization for legacy infusion center providers.
Pricing Analysis
Cost-plus contracts with pharmaceutical price indexation anchor United States antimicrobial prophylaxis procurement, though Japanese and German sick funds employ reference pricing that caps reimbursement at lowest-cost therapeutic equivalent. Three-tier pricing structure across originator, authorized generic, and compound pharmacy levels stratifies by FDA approval status and bioequivalence documentation. Cost compression in oral azole antifungals is intensifying as Indian API manufacturers expand European DMF filings. Employer-sponsored plans demonstrate highest price sensitivity through mandatory site-of-care optimization, while Medicaid programs exhibit lowest sensitivity due to federal rebate structures.
Supply Chain Analysis
United States and Switzerland anchor lentiviral vector GMP production for ex vivo gene therapy programs, with German contract manufacturing organizations capturing plasmid supply for European clinical trials. Viral vector production draws from HEK293T cell banks, cationic lipid formulations, and synthetic promoter libraries. Single-source vulnerability concentrates in plasmid DNA supply where limited GMP-certified facilities service multiple developers. Distribution runs through cryogenic logistics networks with validated chain-of-custody protocols for patient-specific cellular products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is cycling through gene therapy commercialization maturation, with FDA and EMA regulatory precedent accumulation driving capital deployment timing toward manufacturing scale-up windows.
For Market Incumbents: Compound manufacturing capacity reservations in Swiss and German contract manufacturing organizations ahead of competitor lock-in. Secure orphan drug exclusivity provisions through pediatric indication prioritization before irreversible organ damage excludes patient candidacy. Gene therapy developers represent the primary threat through curative displacement of chronic prophylactic spending.
For New Entrants and Emerging Players: FDA breakthrough therapy designation fast-track offers the most penetrable regulatory pathway for X-linked CGD programs with preliminary oxidase restoration data. Target caregiver-administered subcutaneous delivery formats where United States specialty pharmacy networks seek differentiated service offerings. Pursue licensing consortia for promoter sequence access rather than freedom-to-operate litigation.
For Investors and Strategic Acquirers: Capital is best deployed toward platform-technology developers with validated lentiviral vector manufacturing processes and established EMA Committee for Advanced Therapies rapporteur relationships. Long-term viability hinges on five-to-ten-year oxidase durability data that validates single-administration curative claims against lifetime prophylactic spending comparisons. Watch CMS value framework calibration for single-administration therapies as the decisive reimbursement inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pursuit | FDA exclusivity provisions secure seven-year market protection for X-linked CGD gene therapies. |
| GMP Certification Investment | EMA advanced therapy medicinal product qualification enables centralized European manufacturing scale-up. |
| Subcutaneous Formulation Development | Home administration preference in United States employer plans drives site-of-care optimization capture. |
| Allogeneic Platform Migration | Off-the-shelf gene-edited hematopoietic stem cells eliminate patient-specific cold-chain logistics complexity. |
| Pediatric Indication Prioritization | First-line curative intervention before organ damage accumulates maximizes addressable patient population. |
Study Parameters
Operator-level perspectives from gene therapy manufacturing executives, EMA regulatory affairs leads, United States payer access specialists, and specialty pharmacy procurement managers anchored the qualitative base. Primary interview findings triangulated against FDA orphan drug designation filings, EMA Committee for Advanced Therapies assessment reports, ClinicalTrials.gov protocol registries, and CMS Medicare Part D formulary databases. Bottom-up patient population estimates and top-down pharmaceutical spending trajectories were reconciled through iterative validation.
Sensitivity analysis around gene therapy adoption curves, oxidase durability assumptions, and reimbursement timeline scenarios shaped the analytical framework across the projection horizon. Segmentation dimensions modeled encompass treatment modality, administration route, genetic subtype, and regional regulatory cluster. CAGRs were derived from logistic diffusion curves for curative therapies and linear extrapolation for chronic prophylactic maintenance. Forecast inputs incorporated EMA accelerated assessment pathway approval probabilities and CMS national coverage determination precedent.
Decision-makers should treat outputs as directional under assumptions of sustained FDA orphan drug exclusivity enforcement and stable interferon-gamma immunogenicity surveillance requirements; material deviation in gene therapy durability data or payer value framework calibration would warrant model refresh. Recalibration cycles align with material shifts in EMA advanced therapy medicinal product licensing standards and CMS single-administration therapy reimbursement methodologies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Muckle-Wells Syndrome Market
Rare Diseases
Chaple Syndrome Market
Rare Diseases
Menkes Syndrome Market
Rare Diseases
Dystrophic Epidermolysis Bullosa Market
Rare Diseases
Krabbe Disease Treatment Market
Rare Diseases
Hairy Cell Leukemia Market
Rare Diseases
Yellow Nail Syndrome Treatment Market
Rare Diseases
Global Tyrosine Hydroxylase Deficiency Market
Rare Diseases
Niemann-Pick Disease Type C Therapeutics Market
Rare Diseases
Turner Syndrome Market
Rare Diseases
Gastrointestinal Rare Diseases Treatment Market
Rare Diseases
Batten Disease Market
Rare Diseases
Asia-Pacific Down Syndrome Market
Rare Diseases
Pompe Disease Market
Rare Diseases
Europe Down Syndrome Market
Rare Diseases
Mucopolysaccharidosis (MPS) Treatment Market