
 Global Neuromyelitis Optica Spectrum Disorder Market | 2026-2036
Global Neuromyelitis Optica Spectrum Disorder Market Size, Share, and Industry Trends Forecast 2026-2036
Global Neuromyelitis Optica Spectrum Disorder Market Foresight
Specialty pharmacy distribution is narrowing as hospital networks consolidate procurement of high-cost biologics for rare neuroinflammatory conditions. Amgen leverages its established inflammation franchise to sustain channel access for complex injectable therapies. TG Therapeutics anchors its competitive position through deep specialization in B-cell directed mechanisms relevant to aquaporin-4 seropositive patient subsets.
Neuromyelitis optica spectrum disorder comprises a rare autoimmune condition characterized by pathogenic immunoglobulin G antibodies against aquaporin-4 water channels, producing inflammatory demyelination of the optic nerves and spinal cord with relapse-driven disability accumulation. Its primary commercial purpose centers on preventing irreversible neurological damage through chronic immunomodulation rather than episodic corticosteroid rescue. Monoclonal antibodies command the dominant margin pool given their targeted mechanism and chronic administration profile, while intravenous delivery mode retains structural importance for initial loading and acute relapse management despite subcutaneous formulations gaining traction in maintenance settings.
The FDA orphan drug program and EMA's priority medicines scheme jointly shape development incentives, accelerating clinical trial design and post-market surveillance requirements for novel biologics in seropositive populations. Japan's PMDA operates a similar sakigake designation that reduces review timelines for innovative neurology therapies. Stakeholders must monitor evolving biomarker standardization and health technology assessment methodologies as payers sharpen scrutiny of long-term patient-reported outcomes versus surrogate endpoints.
Market Dynamics
The FDA's orphan drug designation pathway is concentrating biologics development resources toward seropositive patient subsets, compressing clinical timelines while elevating post-market surveillance obligations for manufacturers targeting chronic immunomodulation.
Growth Catalysts
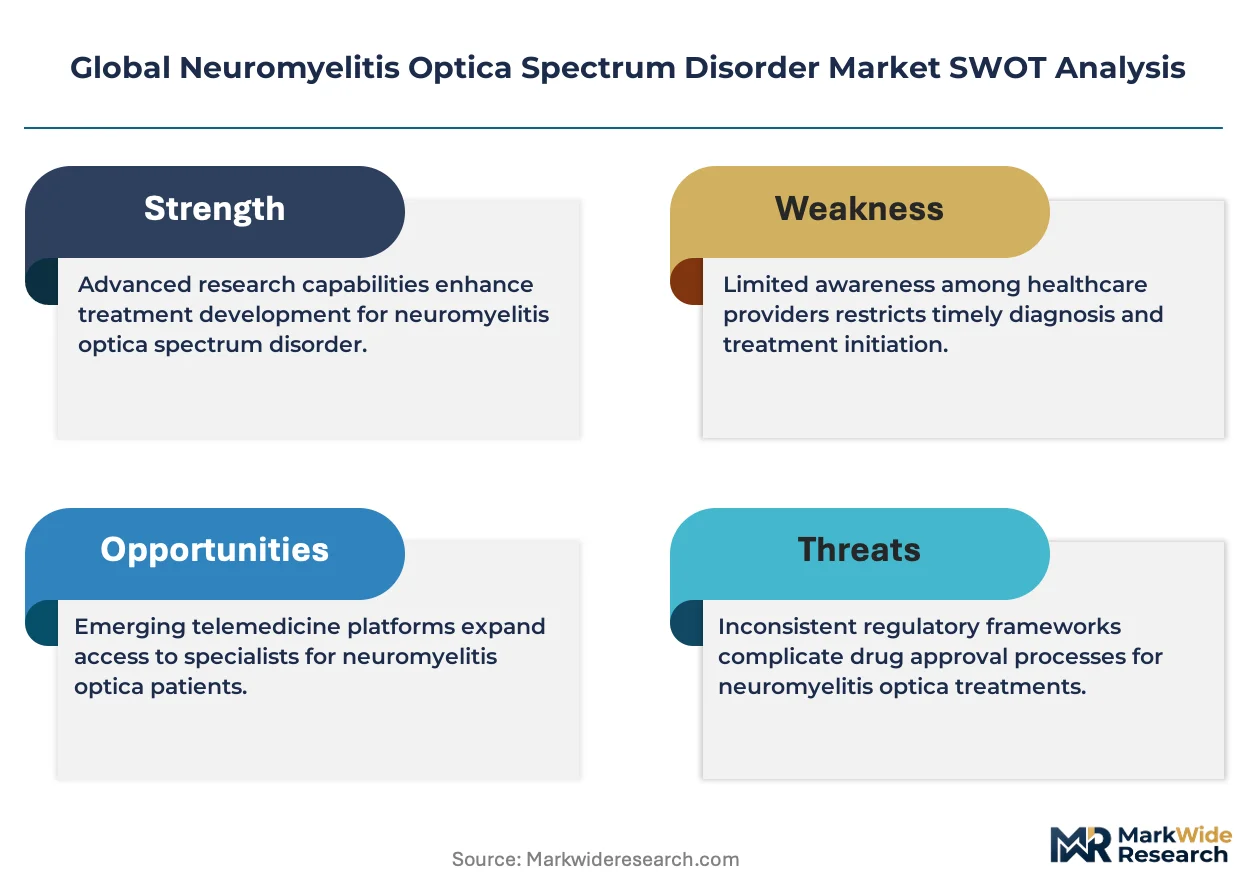
- EMA Priority Medicines Scheme:The European framework accelerates assessment timelines for innovative neurology therapies, channeling development investment toward aquaporin-4 antibody diagnostics.
- Specialty clinic consolidation:Hospital network procurement centralization for high-cost biologics is standardizing preventive care protocols across seropositive patient management pathways.
- Subcutaneous formulation advancement:Self-administration technology is extending maintenance therapy access beyond infusion center dependency into home-based settings.
Market Restraints
- Biologics manufacturing concentration:Contract development and manufacturing organization capacity for complex monoclonal antibodies clusters in Switzerland and Ireland, creating single-source vulnerability.
- Diagnostic infrastructure asymmetry:Cell-based assay and live cell immunofluorescence testing requires specialized laboratory certification unavailable in secondary care settings across Eastern Europe and Southeast Asia.
- Reimbursement latency:Health technology assessment bodies in Germany and France impose extended real-world evidence collection periods before chronic therapy coverage authorization.
Strategic Opportunities
- Brazil ANVISA accelerated pathway:The South American regulator's rare disease designation offers reduced review timelines for first-entry biologics in an underpenetrated seropositive population.
- Biomarker-guided patient stratification:Aquaporin-4 versus myelin oligodendrocyte glycoprotein antibody differentiation enables indication expansion into overlapping neuroinflammatory conditions.
- Digital therapeutics integration:Remote patient monitoring platforms are converging with subcutaneous delivery systems to capture real-time relapse prediction data for payers.
Industry Challenges
- Specialized immunology talent scarcity:B-cell biology expertise for monoclonal antibody development concentrates in Boston and Basel, constraining pipeline expansion for mid-cap developers.
- Multi-regional trial complexity:Harmonization gaps between FDA, EMA, and PMDA biomarker endpoints extend clinical program duration and inflate patient recruitment costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Neuromyelitis Optica Spectrum Disorder Market |
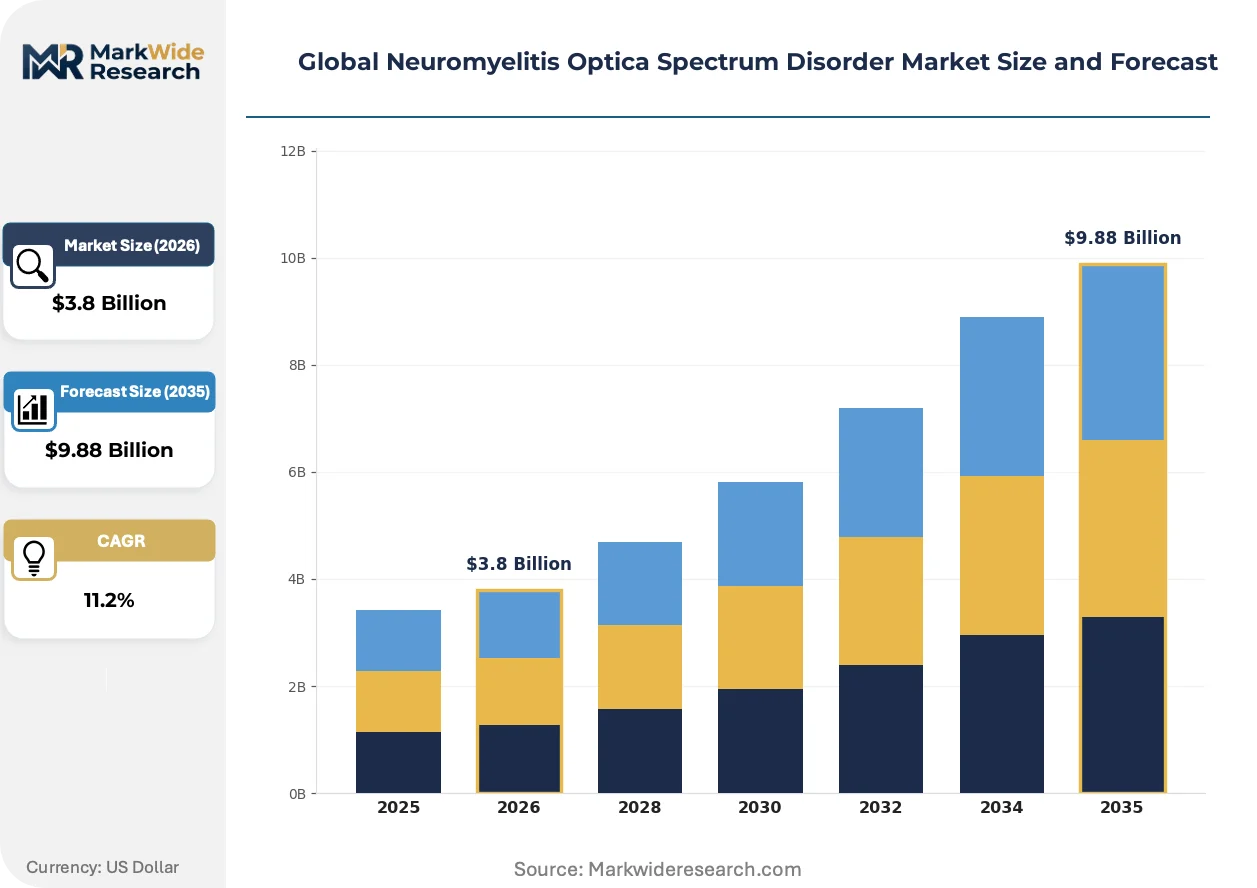
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $9.88 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Immunosuppressants, Corticosteroids, Plasma Exchange End User: Hospitals, Specialty Clinics, Homecare Settings, Research Institutions Delivery Mode: Intravenous, Subcutaneous, Oral, Inhalation Treatment Strategy: Preventive Care, Symptomatic Treatment, Rehabilitation, Long-term Management |
| Companies Covered | Amgen, TG Therapeutics, F. Hoffmann-La Roche Ltd, Biogen, Opexa Therapeutics, AstraZeneca, Mitsubishi Tanabe Pharma, RemeGen, Horizon Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Neuromyelitis Optica Spectrum Disorder Market Shifts & Advancements
Neuromyelitis optica spectrum disorder therapeutics are undergoing delivery mode transformation alongside biomarker standardization and procurement centralization, compressing traditional channel structures while elevating data requirements for market access.
Complement inhibition mechanisms are migrating from intravenous infusion to subcutaneous administration, enabling home-based maintenance therapy for seropositive patients. Specialty pharmacies in the United States and Japan are adopting these formulations at accelerated pace. The shift is compressing hospital outpatient revenue streams while expanding mail-order distribution infrastructure for chronic immunomodulation.
Japan's PMDA sakigake designation is compressing review timelines for novel neurology biologics, creating first-mover advantages for developers with manufacturing readiness. The framework mandates post-market registry enrollment, elevating real-world evidence collection obligations. Seropositive patient subsets in Tokyo and Osaka medical centers are experiencing earliest access to B-cell depleting therapies under this accelerated pathway.
Hospital network procurement consolidation is displacing independent specialty pharmacy distribution for high-cost biologics. Integrated delivery systems in Germany and the United States are negotiating outcome-based contracts directly with manufacturers, unbundling traditional wholesaler margins. The behavioral shift is most visible in academic medical centers where pharmacy and therapeutics committees now control formulary placement through centralized committee structures rather than physician-level prescribing autonomy.
Global Neuromyelitis Optica Spectrum Disorder Market Segmentation
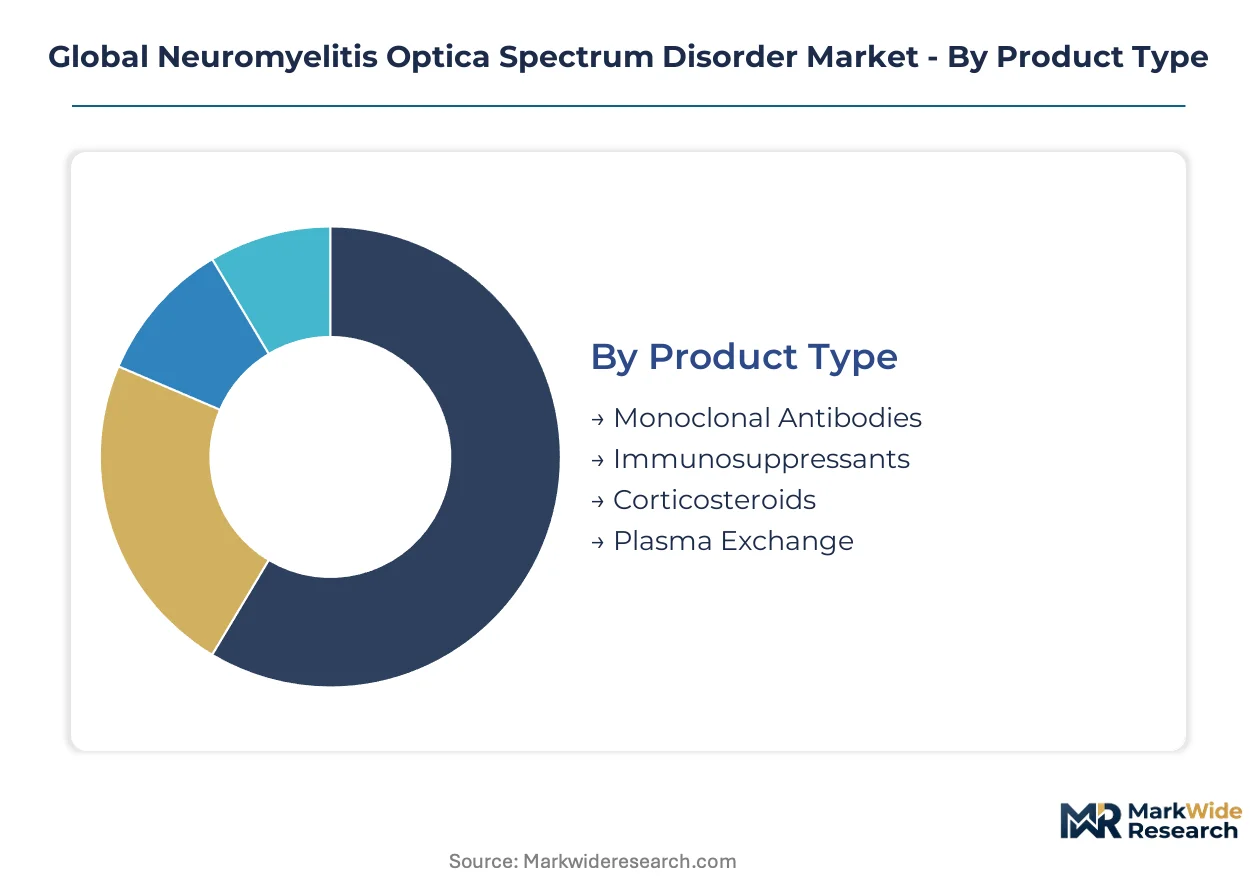
Segmentation in neuromyelitis optica spectrum disorder therapeutics reflects divergent clinical workflows across acute relapse management and chronic immunomodulation. Product differentiation by mechanism and delivery mode determines channel economics and patient access pathways.
Product Type:
Cost tier stratification separates chronic maintenance therapies from episodic rescue interventions, with biologics commanding premium positioning against generic immunomodulators.
- Monoclonal Antibodies:Engineered immunoglobulins targeting B-cell pathways or complement cascade components enable precise immunomodulation with reduced systemic toxicity. Demand concentrates in academic medical centers across the United States, Germany, and Japan where aquaporin-4 seropositive testing infrastructure supports patient stratification and reimbursement authorization for high-cost chronic therapy.
- Immunosuppressants:Small-molecule agents including azathioprine and mycophenolate mofetil provide oral maintenance options with established safety profiles but inferior relapse prevention versus biologics. Volume persists in Brazil and India where national health systems prioritize cost containment over mechanism specificity in rare neuroinflammatory conditions.
- Corticosteroids:High-dose methylprednisolone remains the acute relapse rescue standard.
- Plasma Exchange:Apheresis-based antibody removal addresses severe, treatment-refractory attacks in tertiary care settings.
Monoclonal antibodies command the established base. The steepest expansion runs through immunosuppressants in emerging markets.
End User:
Application concentration shapes procurement patterns, with integrated delivery systems consolidating purchasing power for biologics while fragmented outpatient settings sustain generic volume.
- Hospitals:Tertiary academic centers manage acute relapses through infusion-based loading doses and complex diagnostic workups requiring cell-based assay confirmation. Procurement committees in German university hospitals and US academic medical centers negotiate direct manufacturer contracts, displacing traditional specialty pharmacy intermediaries.
- Specialty Clinics:Dedicated neuroimmunology centers coordinate chronic maintenance therapy with embedded nursing support for subcutaneous administration training. Concentration in Tokyo, Osaka, and Boston creates localized expertise clusters that accelerate novel therapy adoption under accelerated regulatory pathways.
- Homecare Settings:Self-administration infrastructure for subcutaneous formulations is expanding in Japan and the United States.
- Research Institutions:Clinical trial sites in Basel and Cambridge drive biomarker validation and comparator studies.
Hospitals anchor the revenue base. The steepest expansion runs through specialty clinics as preventive protocols displace episodic care.
Delivery Mode:
Volume distribution reflects the tension between acute intervention requirements and chronic maintenance convenience, with administration setting determining reimbursement tier placement.
- Intravenous:Infusion center delivery enables rapid bioavailability for acute relapse rescue and initial biologic loading, retaining structural importance despite patient preference for alternatives. Centers in France and Italy maintain high utilization due to reimbursement frameworks that favor supervised administration for high-cost therapies.
- Subcutaneous:Prefilled syringe and autoinjector formats shift maintenance therapy from hospital outpatient departments to home settings, reducing healthcare system costs and improving adherence metrics. Adoption accelerates in Japan under PMDA sakigake-designated products with companion digital monitoring platforms.
- Oral:Small-molecule immunosuppressants sustain volume in cost-sensitive markets.
- Inhalation:Investigational routes for corticosteroid delivery remain preclinical.
Intravenous delivery commands the established base. The steepest expansion runs through subcutaneous formulations as home-based maintenance protocols gain payer acceptance.
Treatment Strategy:
Customer type differentiation separates curative-intent chronic immunomodulation from supportive care, with outcome measurement frameworks determining reimbursement durability.
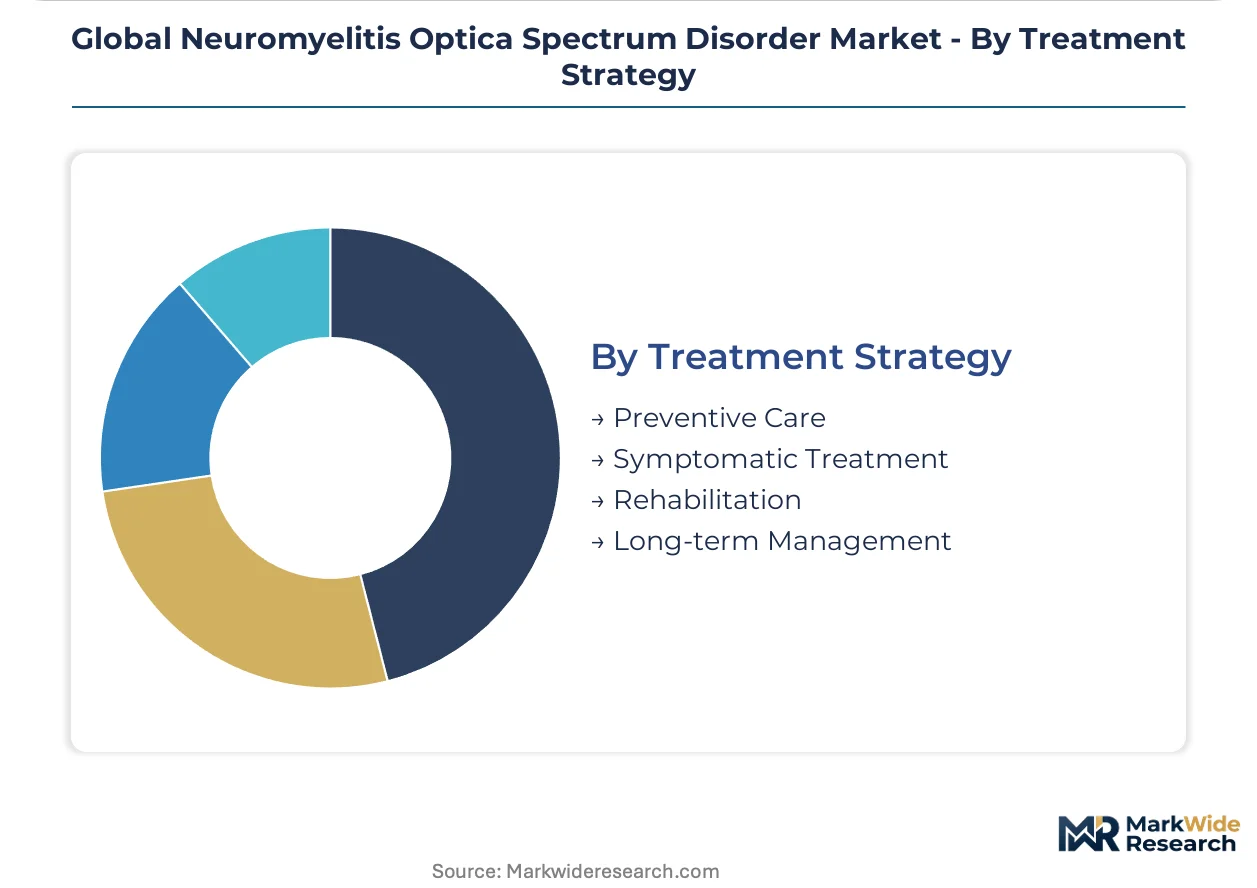
- Preventive Care:Chronic B-cell depletion or complement inhibition aims to eliminate relapse-driven disability accumulation, requiring sustained adherence and monitoring. Germany's health technology assessment bodies impose extended real-world evidence collection periods before granting permanent coverage authorization for preventive biologics.
- Symptomatic Treatment:Acute corticosteroid rescue and pain management address individual attacks without modifying long-term disease trajectory.
- Rehabilitation:Physical and occupational therapy restores function after optic neuritis or transverse myelitis episodes.
- Long-term Management:Coordinated multidisciplinary care integrates neurology, ophthalmology, and urology services for complex disability profiles.
Preventive care commands the established base. The steepest expansion runs through long-term management as integrated care models demonstrate total-cost-of-care reduction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Japan where diagnostic infrastructure and accelerated regulatory pathways command premium reimbursement tiers, while Germany enforces cost-containment through extended health technology assessment timelines that compress net returns for chronic immunomodulation therapies.
United States
FDA orphan drug designations compress clinical development timelines for aquaporin-4 seropositive biologics, attracting venture investment toward B-cell directed mechanisms. The agency's breakthrough therapy pathway enables rolling review for novel complement inhibitors. Academic medical centers in Boston and Baltimore anchor specialist referral networks that standardize cell-based assay confirmation protocols.
Japan
PMDA's sakigake designation reduces review timelines to six months for innovative neurology therapies, creating first-mover advantages for subcutaneous formulation developers. Post-market registry enrollment mandates elevate real-world evidence collection obligations. Tokyo and Osaka medical centers concentrate neuroimmunology expertise that accelerates novel therapy adoption under accelerated pathways.
Germany
The Federal Joint Committee's health technology assessment framework imposes extended real-world evidence collection periods before granting permanent coverage authorization for preventive biologics. Diagnostic infrastructure concentrates in university hospital networks across Bavaria and North Rhine-Westphalia. Pharmacy and therapeutics committees now control formulary placement through centralized structures rather than physician-level prescribing autonomy.
China
NMPA priority review pathways for rare diseases accelerate biologics registration timelines, though reimbursement negotiation lags behind approval speed. Domestic CDMO capacity expansion in Suzhou and Shanghai reduces import dependency for monoclonal antibody manufacturing. Tertiary hospital neurology departments in Beijing and Guangzhou drive seropositive testing standardization.
Brazil
ANVISA's rare disease designation offers reduced review timelines for first-entry biologics in an underpenetrated seropositive population. National health system procurement prioritizes cost containment over mechanism specificity in chronic immunomodulation. São Paulo's academic medical centers concentrate diagnostic capacity for aquaporin-4 antibody testing through cell-based assay platforms.
Global Neuromyelitis Optica Spectrum Disorder Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in mechanism-specific development. The competitive structure concentrates around large-cap biopharmaceuticals with established inflammation franchises and mid-cap developers with deep B-cell biology specialization. Three archetypes dominate: complement cascade inhibitors, B-cell depleting agents, and immunosuppressant portfolio diversifiers. Consolidation pressure runs through M&A targeting neurology-focused platforms and strategic partnerships for subcutaneous delivery technology licensing.
Within the inflammation franchise tier, Amgen anchors established channel access for complex injectable therapies through hospital network relationships. TG Therapeutics occupies a specialized position in B-cell directed mechanisms relevant to aquaporin-4 seropositive subsets. Among diversified biopharmaceuticals, F. Hoffmann-La Roche Ltd exemplifies platform breadth spanning diagnostic and therapeutic integration.
| Leading Market Players |
|---|
| Amgen |
| TG Therapeutics |
| F. Hoffmann-La Roche Ltd |
| Biogen |
| Opexa Therapeutics |
| AstraZeneca |
| Mitsubishi Tanabe Pharma |
| RemeGen |
| Horizon Therapeutics |
| Others |
Supply & Pricing Matrix
Single-source CDMO dependency for monoclonal antibody manufacturing in Switzerland and Ireland compresses pricing power for biologics developers while elevating procurement risk premiums across chronic immunomodulation therapies. This concentration simultaneously widens the spread between premium biologics and cost-contained small-molecule alternatives while forcing supply chain redundancy investments that pass through to list prices.
Pricing Analysis
The customization-premium spread separates patient-stratified biologics pricing from standard immunosuppressant tiers. Three-tier pricing structure across premium biologics, standard maintenance therapies, and economy rescue protocols dominates the market. Price differentiation rests on aquaporin-4 seropositivity confirmation and administration setting complexity. Cost compression in the immunosuppressant tier is intensifying because national health systems in Brazil and India prioritize mechanism-agnostic procurement. Hospital procurement committees exhibit lowest price sensitivity; retail pharmacy channels in emerging markets show highest elasticity.
Supply Chain Analysis
Tariff exposure between Switzerland and the United States dominates biologics supply risk given CDMO concentration for fill-finish operations. Manufacturing gravity centers on Basel, Boston, and Singapore for monoclonal antibody production. Raw material dependencies include Chinese hamster ovary cell lines, single-use bioreactor systems, and affinity chromatography resins. Single-source vulnerability for complement inhibitor active pharmaceutical ingredients creates procurement chokepoints. Distribution runs through consolidated hospital network procurement committees in Germany and the United States, displacing independent specialty pharmacy intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in a cyclical recovery phase driven by accelerated regulatory designations compressing development timelines for seropositive biologics. FDA orphan drug and PMDA sakigake pathways are shortening revenue realization horizons for mechanism-specific therapies.
For Market Incumbents: Harden manufacturing redundancy through dual-source CDMO qualification in Singapore and Switzerland to mitigate single-source exposure for complement cascade inhibitors. Deepen formulary control through outcome-based contracting with German hospital network procurement committees. Elevate real-world evidence collection infrastructure to satisfy extended health technology assessment timelines before permanent reimbursement authorization. For New Entrants and Emerging Players: Pursue white-space positioning in Brazil's underpenetrated seropositive population where ANVISA's rare disease designation offers reduced review timelines for first-entry biologics. Target subcutaneous formulation development with companion digital therapeutics integration to differentiate against infusion-dependent incumbents. Leverage biomarker-guided patient stratification into myelin oligodendrocyte glycoprotein antibody-positive subsets for indication expansion. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors neurology-focused platforms with deep B-cell biology specialization. Long-term viability over the next decade hinges on manufacturing readiness for subcutaneous delivery scale-up and post-market registry infrastructure. Acquisition target archetype: mid-cap developers with PMDA sakigake-designated assets and established Tokyo-Osaka clinical site relationships. Monitor biomarker standardization harmonization between FDA, EMA, and PMDA as the critical inflection signal for multi-regional trial cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Shifts maintenance therapy from hospital outpatient departments to home settings, reducing healthcare system costs and improving adherence metrics in Japan and the United States. |
| Biomarker-Guided Patient Stratification | Enables indication expansion into myelin oligodendrocyte glycoprotein antibody-positive subsets through aquaporin-4 differentiation protocols. |
| Dual-Source CDMO Qualification | Mitigates single-source vulnerability for monoclonal antibody manufacturing concentrated in Switzerland and Ireland. |
| Outcome-Based Hospital Contracting | Secures formulary placement through German and United States academic medical center procurement committee structures. |
| Real-World Evidence Infrastructure | Satisfies extended collection periods imposed by Germany's Federal Joint Committee before permanent preventive biologics coverage authorization. |
Research Methodology
The analysis maps monoclonal antibodies, immunosuppressants, corticosteroids, and plasma exchange modalities, each validated through drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Primary interviews combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases anchored the assessment. Bottom-up patient-flow modeling and top-down revenue triangulation cross-verified segment-level estimates.
Assumptions held regulatory pathway timelines and reimbursement authorization frameworks fixed while varying seropositive testing penetration rates and subcutaneous adoption curves across the analysis window. Segmentation dimensions modeled include product mechanism, delivery mode, treatment strategy, and regional regulatory cluster. CAGRs derived from patient population epidemiology, therapy switching patterns, and pricing trajectory assumptions. Forecast inputs incorporated biomarker standardization progress and health technology assessment methodology evolution.
Sensitivities concentrate around biomarker harmonization delays, CDMO capacity constraints, and reimbursement authorization timeline extensions. Forecasts reflect documented assumptions regarding regulatory pathway efficiency and payer evidence requirements. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Kounis Syndrome Market
Rare Diseases
Rare Neurodegenerative Disease Treatment Market
Rare Diseases
Alzheimer Disease Market
Rare Diseases
Methylmalonic Acidemia Market
Rare Diseases
Cri-Du-Chat Syndrome Treatment Market
Rare Diseases
Batten Disease Market
Rare Diseases
Hutchinson Gilford Progeria Syndrome (HGPS) Therapeutics Market
Rare Diseases
Hutchinson-Gilford Progeria Syndrome Market
Rare Diseases
Rare Neurological Disease Treatment Market
Rare Diseases
Hairy Cell Leukemia Market
Rare Diseases
Atypical Hemolytic Uremic Syndrome (Ahus) Treatment Market
Rare Diseases
Global Guillain-Barre Syndrome Market
Rare Diseases
Niemann-Pick Disease Type C Therapeutics Market
Rare Diseases
Rosai-Dorfman Disease (RDD) Therapeutics Market
Rare Diseases
Yellow Nail Syndrome Treatment Market
Rare Diseases
Spina Bifida Market