
 Middle East and Africa Down Syndrome Market | 2026-2036
Middle East and Africa Down Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Down Syndrome Market Foresight
Procurement from centralized government tenders toward distributed multi-source agreements is shifting across the Middle East and Africa Down Syndrome Market. Illumina sustains technology leadership in non-invasive prenatal testing platforms across Gulf state laboratories. Roche Diagnostics anchors diagnostic supply chains through long-term service contracts with Saudi Arabia's Ministry of Health. Siemens Healthineers competes on integrated imaging-workflow solutions for cardiac anomaly detection in Down syndrome patients.
Down syndrome encompasses a chromosomal condition caused by full or partial trisomy of chromosome 21, producing characteristic cognitive impairment, congenital heart defects, and elevated leukemia risk alongside protective solid-tumor profiles. Diagnostic tests dominate product type revenue, driven by mandatory newborn screening mandates in UAE and Qatar national health programs. Genetic testing represents the fastest-expanding technology segment as next-generation sequencing costs decline and prenatal cell-free DNA analysis penetrates South African private obstetrics networks. Educational tools occupy a mature, grant-dependent niche with concentrated demand from non-profit organizations serving Gulf state expatriate communities.
Saudi Arabia's SFDA and South Africa's SAHPRA regulate in vitro diagnostic quality standards, while UAE's Ministry of Health and Prevention enforces prenatal screening accreditation for private clinics. These frameworks shape market access by mandating CE-marked or FDA-cleared platforms for public sector procurement, effectively filtering regional distribution partnerships. Stakeholders must monitor evolving reimbursement eligibility for cell-free DNA screening as Gulf state health authorities recalibrate essential benefits packages.
Market Dynamics
Centralized government tenders across Gulf Cooperation Council states are fragmenting into distributed multi-source agreements, forcing diagnostic suppliers to rebuild channel strategies around laboratory accreditation networks rather than single-ministry relationships.
Growth Catalysts
- Neonatal screening mandates:UAE and Qatar national health programs now require mandatory newborn screening for chromosomal abnormalities, creating guaranteed demand pools for diagnostic platforms in public hospital networks.
- Cell-free DNA cost compression:Next-generation sequencing economies are penetrating South African private obstetrics practices, expanding prenatal testing access beyond historically insured populations.
- Cardiac anomaly protocols:Saudi Arabia's Ministry of Health has established echocardiogram referral pathways for Down syndrome patients, driving imaging service demand through tertiary care centers.
Market Restraints
- Reagent import dependency:Gulf state laboratories rely on temperature-controlled supply chains from European manufacturing hubs, exposing operations to shipping volatility and customs processing delays.
- Genetic counselor scarcity:South Africa and Saudi Arabia face acute shortages of trained genetic counselors, constraining patient throughput for prenatal testing services regardless of platform availability.
- SFDA platform certification timelines:Saudi Arabia's medical device registration process extends 18-24 months for novel diagnostic technologies, delaying market entry for updated sequencing chemistries.
Strategic Opportunities
- Telemedicine integration:Remote genetic counseling platforms are penetrating Egypt and Jordan's private healthcare networks, enabling prenatal screening access outside major metropolitan clusters.
- Non-profit educational channels:Grant-funded intervention programs across Gulf state expatriate communities represent underserved demand for cognitive development tools and early childhood assessment kits.
- Public-private laboratory partnerships:South Africa's National Health Insurance reforms are creating joint venture structures between provincial hospitals and accredited private genetic testing facilities.
Industry Challenges
- CE-marking equivalency disputes:UAE's Ministry of Health and Prevention maintains divergent technical documentation requirements from Saudi SFDA standards, forcing manufacturers to maintain multiple regulatory dossiers for regional access.
- Sample logistics infrastructure:Peripheral province referral networks in Saudi Arabia and South Africa's rural Eastern Cape lack cold chain reliability for time-sensitive amniocentesis and cell-free DNA specimen transport.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Down Syndrome Market |
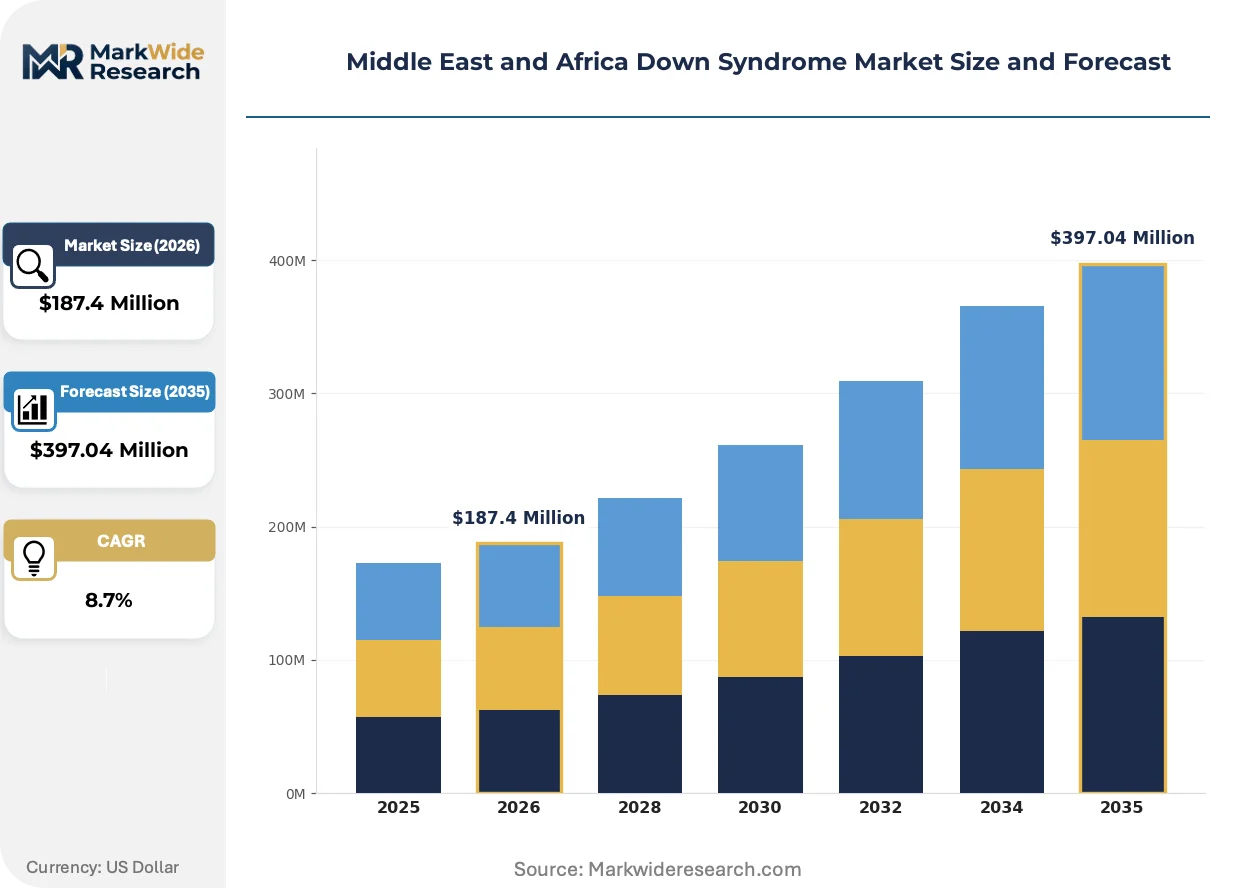
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Tests, Therapeutic Agents, Educational Tools, Support Services Application: Healthcare, Education, Family Support, Community Services End User: Hospitals, Clinics, Educational Institutions, Non-Profit Organizations Technology: Screening Methods, Genetic Testing, Treatment Technologies, Educational Platforms |
| Companies Covered | Roche Diagnostics, Illumina, Siemens Healthineers, Medtronic, Pfizer, Novartis, AC Immune, Natera, Myriad Genetics, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Down Syndrome Market Shifts & Advancements
Artificial intelligence-assisted karyotyping and automated fetal fraction analysis are compressing diagnostic turnaround times while Gulf state reimbursement frameworks recalibrate to capture technology-enabled efficiency gains.
Artificial intelligence-assisted karyotyping software is integrating chromosomal anomaly detection workflows into standard laboratory information management systems. Saudi Arabia's tertiary care centers and South Africa's academic hospital networks are adopting these platforms at accelerating rates. The technology is integrating cytogenetic technologist workflows with digital pathology archives, reducing manual microscopy time per sample.
SFDA's updated in vitro diagnostic quality standards now mandate traceable calibration documentation for non-invasive prenatal testing platforms procured through Ministry of Health contracts. This regulatory tightening is disqualifying distributors lacking certified service engineer networks. Saudi Arabia's centralized laboratory procurement segment is responding by consolidating vendor panels around manufacturers with established local technical support infrastructure.
Direct-to-consumer genetic testing awareness is shifting patient-initiated screening requests toward obstetric practices in South Africa's private healthcare sector. Traditional physician-channel prenatal testing is facing disruption from informed patients arriving with prior research on cell-free DNA options. Johannesburg and Cape Town metropolitan obstetrics networks are most visibly adapting consultation protocols to incorporate pre-visit education materials and standardized counseling scripts.
Middle East and Africa Down Syndrome Market Segmentation
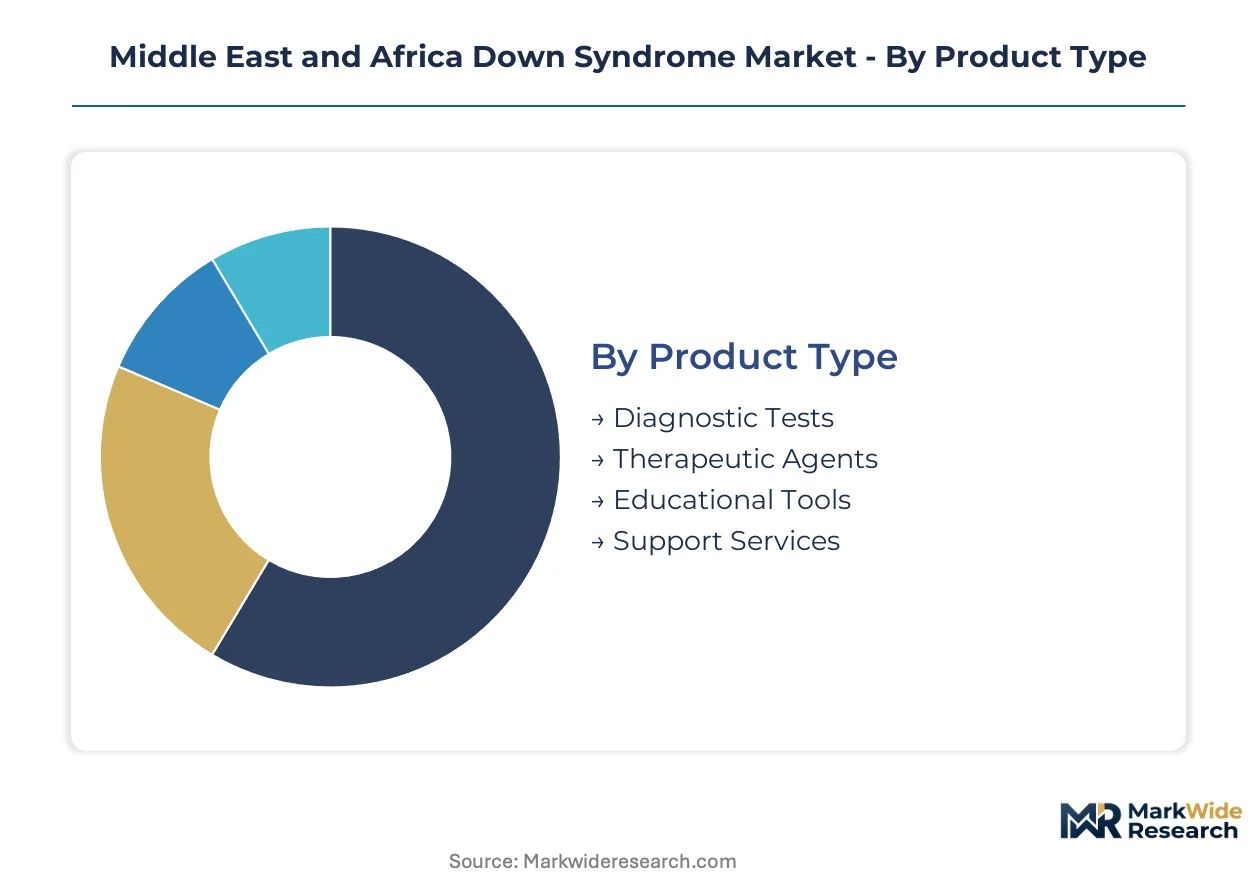
Down syndrome market segmentation in the Middle East and Africa reflects divergent procurement pathways across public health systems, private obstetrics networks, and grant-funded educational channels. Understanding these divides enables suppliers to align platform specifications with the distinct purchasing authority structures governing each segment.
Product Type:
Procurement authority determines tier positioning, with ministry-level tenders favoring integrated diagnostic platforms while educational tools flow through non-profit grant cycles.
- Diagnostic Tests:Chromosomal analysis platforms including karyotyping, fluorescence in situ hybridization, and microarray technologies form the revenue core. Saudi Arabia's Ministry of Health centralized procurement and South Africa's expanding neonatal screening mandates in public hospitals concentrate demand for CE-marked and FDA-cleared systems.
- Therapeutic Agents:Cardiac medications, thyroid hormone replacement therapies, and leukemia surveillance protocols address comorbidity management. Prescription volumes track tertiary care center referrals in Riyadh and Johannesburg academic hospital networks.
- Educational Tools:Early intervention assessment kits and cognitive development programs serve Gulf state expatriate communities through grant-funded non-profit distribution channels.
- Support Services:Care coordination and family counseling programs operate through community health worker networks in Egypt and Jordan.
Volume sits with Diagnostic Tests; growth tilts toward Genetic Testing technology integration within this category.
Application:
Reimbursement eligibility shapes segment boundaries, with mandatory screening creating guaranteed demand pools in healthcare while education and community services depend on discretionary budget allocations.
- Healthcare:Prenatal screening, postnatal diagnosis, and lifelong comorbidity management dominate transaction volumes. UAE and Qatar national health program mandates for newborn chromosomal screening anchor public hospital procurement.
- Education:Specialized curriculum development and teacher training programs serve integrated classroom settings. Gulf state ministries of education contract for Down syndrome-specific pedagogical materials.
- Family Support:Caregiver training and respite services operate through social welfare departments in Saudi Arabia and South Africa.
- Community Services:Vocational rehabilitation and independent living programs extend through municipal health authorities in Cairo and Casablanca metropolitan clusters.
Healthcare captures current spending concentration; family support channels are expanding most quickly as Gulf states broaden essential benefits definitions.
End User:
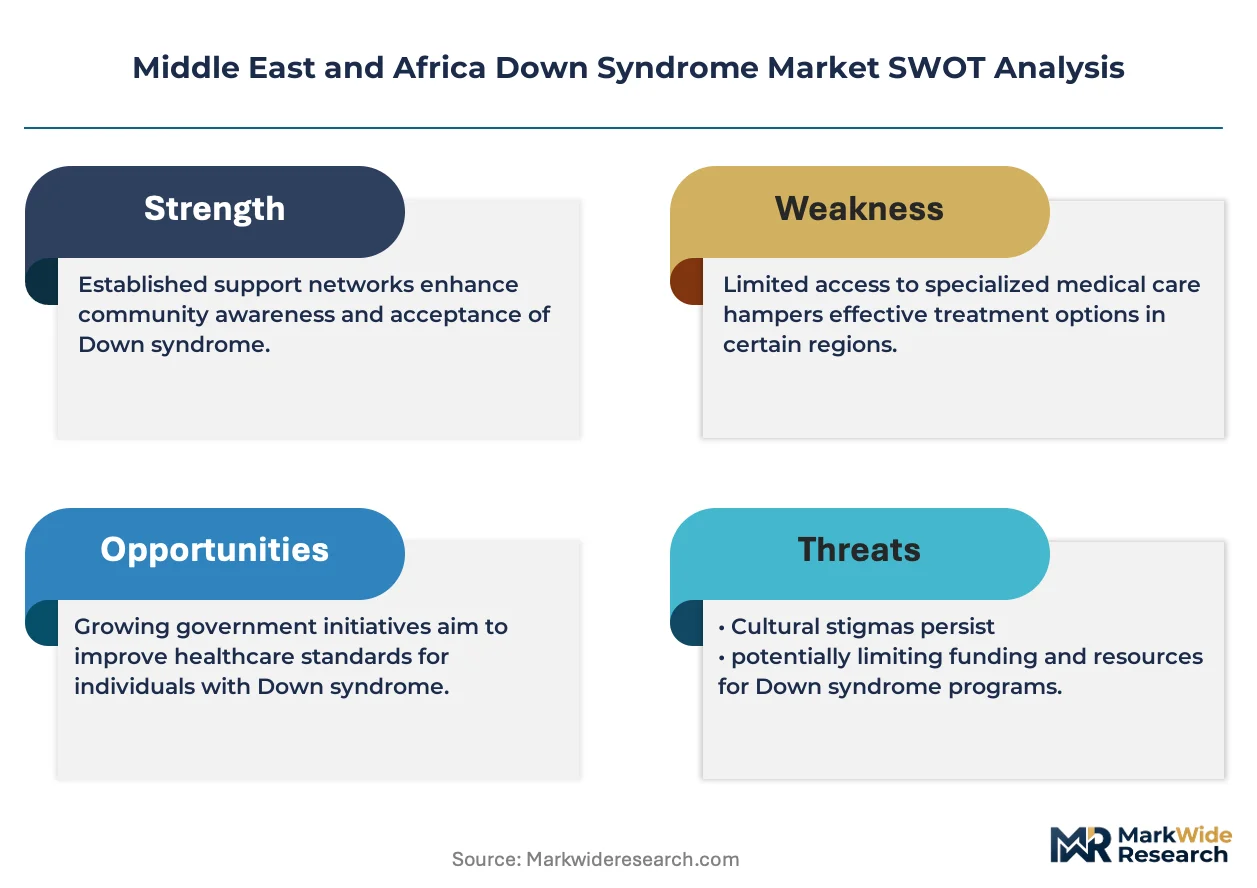
Facility accreditation requirements filter market access, with SFDA and SAHPRA quality standards determining which supplier tiers can serve institutional procurement.
- Hospitals:Tertiary care centers in Riyadh, Jeddah, and Johannesburg academic medical complexes perform complex cardiac surgeries and leukemia surveillance for Down syndrome patients.
- Clinics:Private obstetrics practices in Cape Town and Johannesburg metropolitan areas are adopting cell-free DNA screening as next-generation sequencing costs compress.
- Educational Institutions:Specialized schools and integrated mainstream programs across UAE and Qatar employ cognitive assessment specialists.
- Non-Profit Organizations:Expatriate community service providers in Dubai and Abu Dhabi distribute early intervention tools through grant-funded channels.
Hospitals maintain procurement volume leadership; clinics are gaining share fastest through private prenatal testing expansion.
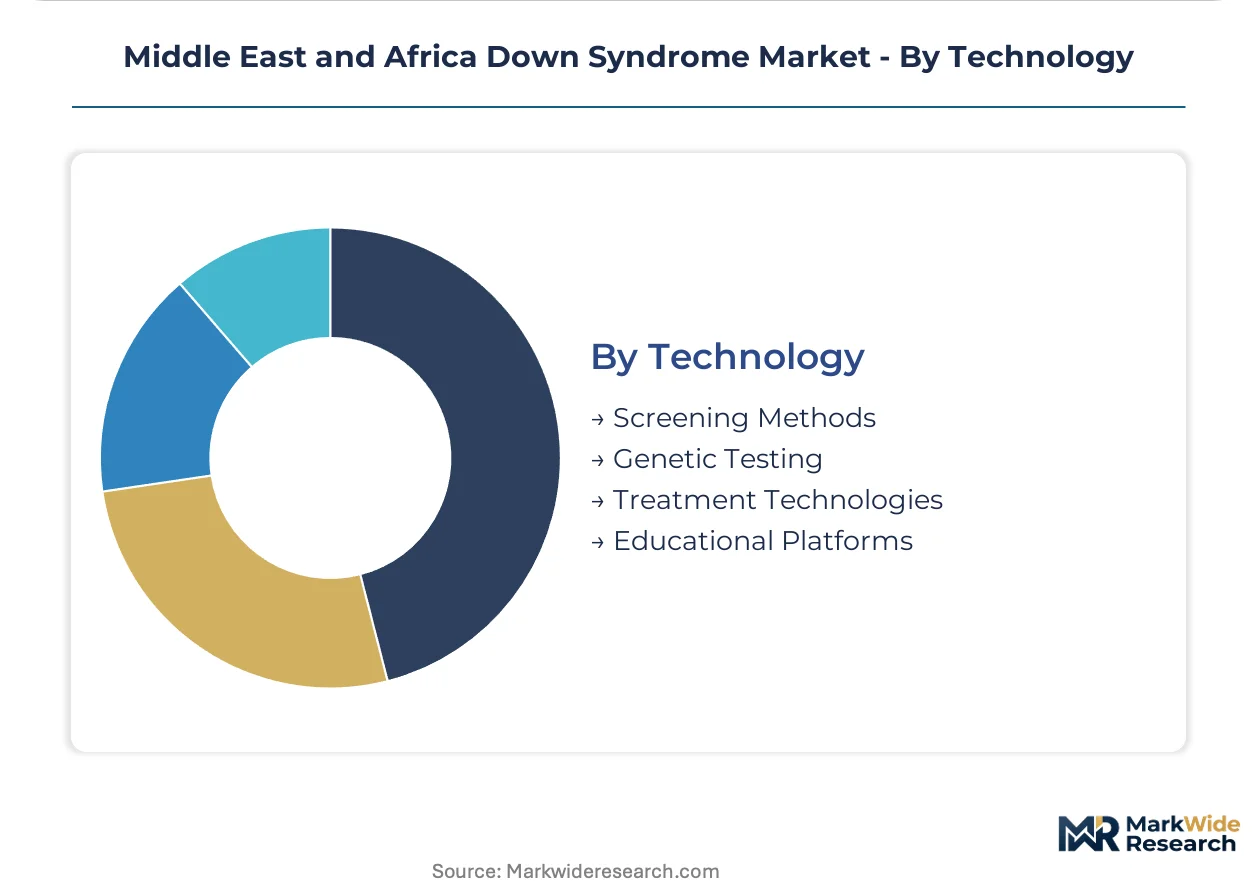
Technology:
Platform certification timelines and service engineer network requirements determine which manufacturers can sustain market presence across this segment.
- Screening Methods:First-trimester combined screening and second-trimester biochemical marker analysis remain standard in resource-constrained settings. Provincial hospital networks in Saudi Arabia's peripheral regions rely on these established protocols.
- Genetic Testing:Non-invasive prenatal testing via cell-free DNA analysis and next-generation sequencing-based diagnostic confirmation represent the technology frontier. South African private obstetrics networks and Saudi tertiary centers are adopting these platforms at accelerating rates.
- Treatment Technologies:Cardiac catheterization and surgical repair protocols for atrioventricular septal defects concentrate in Riyadh and Johannesburg specialist centers.
- Educational Platforms:Digital assessment tools and teletherapy delivery systems penetrate Egypt and Jordan private healthcare networks.
Screening Methods hold installed base dominance; genetic testing platforms are climbing the fastest as Gulf state reimbursement frameworks recalibrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Saudi Arabia's tertiary care centers, where centralized referral networks channel patients from peripheral provinces into Riyadh and Jeddah academic medical complexes. South Africa's public hospital neonatal screening expansion and Gulf Cooperation Council health insurance reforms are redistributing procurement authority across accredited genetic testing networks.
Saudi Arabia
Tertiary cardiac surgery volumes and leukemia surveillance protocols for Down syndrome patients drive hospital procurement in Riyadh and Jeddah. SFDA's 18-24 month platform certification timelines filter market entry for novel diagnostic technologies. The Eastern Province relies on cold chain referral networks to transport time-sensitive amniocentesis specimens to centralized laboratories.
United Arab Emirates
Mandatory newborn screening mandates in Dubai and Abu Dhabi public hospitals create guaranteed demand pools for chromosomal analysis platforms. MOHAP enforces prenatal screening accreditation requirements that diverge from Saudi SFDA technical documentation standards. Expatriate community non-profit organizations in Dubai distribute early intervention assessment kits through grant-funded channels.
South Africa
Expanding neonatal screening programs in Johannesburg and Cape Town public hospitals are broadening diagnostic service uptake. SAHPRA regulates in vitro diagnostic quality standards for provincial hospital procurement. Private obstetrics networks in metropolitan clusters are adopting cell-free DNA screening as next-generation sequencing costs compress.
Qatar
National health program mandates for mandatory newborn chromosomal screening anchor public hospital demand in Doha. The country's national pharmaceutical regulator shapes market access through essential benefits package recalibrations. Centralized laboratory procurement is fragmenting into distributed multi-source agreements requiring accredited vendor panels.
Egypt
Remote genetic counseling platforms are penetrating private healthcare networks in Cairo and Alexandria, enabling prenatal screening access outside major metropolitan clusters. The country's national health authority maintains evolving reimbursement eligibility frameworks for cell-free DNA screening. Community health worker networks operate care coordination programs for family support services.
Middle East and Africa Down Syndrome Market Competitive Landscape
Long-term service contracting dominates the current landscape as diagnostic suppliers rebuild channel strategies around laboratory accreditation networks. The vendor base organizes around three tiers: multinational platform manufacturers with established local technical infrastructure, regional distributors navigating divergent national documentation requirements, and specialized genetic testing laboratories pursuing public-private joint ventures. Technology licensing and portfolio diversification represent the dominant competitive moves as sequencing chemistry updates accelerate.
Among multinational diagnostic manufacturers, Roche Diagnostics, Illumina, and Siemens Healthineers exemplify distinct strategic archetypes. Roche Diagnostics anchors diagnostic supply chains through ministry-level relationships. Illumina occupies a position representing technology leadership in non-invasive prenatal testing platforms. Siemens Healthineers sits within the integrated imaging-workflow solutions segment for cardiac anomaly detection. These three entities collectively illustrate how platform certification timelines and service engineer network requirements determine sustainable market presence across Gulf state and South African procurement frameworks.
| Leading Market Players |
|---|
| Roche Diagnostics |
| Illumina |
| Siemens Healthineers |
| Medtronic |
| Pfizer |
| Novartis |
| AC Immune |
| Natera |
| Myriad Genetics |
| Others |
Supply & Pricing Matrix
Centralized government tenders in Saudi Arabia and Qatar demanding CE-marked or FDA-cleared platforms are compressing supplier margins while fragmenting procurement into multi-source agreements, forcing distributors to absorb certification costs and extend service engineer networks across peripheral provinces.
Pricing Analysis
High-volume ministry contracts trade margin for guaranteed offtake while premium-tier genetic testing platforms in South African private clinics command price premiums through bundled genetic counseling. Three-tier pricing structure across premium, standard, and economy levels separates Illumina's NIPT systems from mid-range karyotyping platforms and basic biochemical screening kits. Price differentiation hinges on SFDA certification status and local technical support infrastructure. Cost compression in South African private obstetrics networks is intensifying because next-generation sequencing economies are democratizing cell-free DNA access. Public hospital procurement committees exhibit highest price sensitivity; Gulf state tertiary cardiac centers show lowest sensitivity due to bundled imaging-workflow solutions.
Supply Chain Analysis
Dual-sourcing requirements embedded in UAE Ministry of Health and Prevention contracts mandate accredited vendor panels with redundant technical service networks, disqualifying single-source distributors and elevating manufacturers with established Gulf state infrastructure. Reagent manufacturing concentrates in Germany, the Netherlands, and the United States, with temperature-controlled logistics feeding Saudi and South African laboratory hubs. Supply chains draw from European sequencing chemistry manufacturers, diagnostic consumables producers, and specialized cold-chain logistics providers. Single-source vulnerability in temperature-controlled shipping from European hubs exposes Gulf state operations to customs delays and seasonal freight volatility. Distribution runs through ministry-accredited laboratory networks, private obstetrics clinic consortia, and non-profit grant-funded educational channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SFDA's 18-24 month platform certification timelines erect a cost-of-compliance barrier that favors incumbents with established local technical infrastructure and service engineer networks, creating a moat that filters out undercapitalized entrants.
For Market Incumbents: Hedge against margin compression in centralized tenders by cultivating direct relationships with South African provincial hospitals navigating National Health Insurance reforms. Secure backward integration into sequencing chemistry supply through captive European manufacturing partnerships. Invest in telemedicine-enabled genetic counseling platforms to offset acute counselor scarcity constraining patient throughput in Riyadh and Johannesburg. For New Entrants and Emerging Players: SAHPRA's evolving in vitro diagnostic quality standards in South Africa open a window for accredited private genetic testing laboratories pursuing public-private joint ventures with provincial hospital networks. Target Cairo and Alexandria metropolitan clusters where remote genetic counseling platforms penetrate private healthcare networks underserved by established Gulf state distributors. Lead with educational tool grant applications to Dubai and Abu Dhabi expatriate community non-profits as a low-friction beachhead. For Investors and Strategic Acquirers: The window for entry favors vertically integrated diagnostic manufacturers with CE-marked platforms and existing Gulf state service infrastructure. Long-term viability rests on capturing recurring reagent revenue streams rather than capital equipment placement. Watch for SAHPRA reimbursement eligibility recalibrations for cell-free DNA screening as the inflection signal indicating South African market acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | SFDA recognition of CE-marked platforms accelerates market entry for European manufacturers. |
| Hospital System Partnership | Long-term service contracts with Saudi Arabia's Ministry of Health anchor diagnostic supply chains. |
| Software Companion Development | AI-assisted karyotyping integration with laboratory information management systems compresses turnaround times. |
| Reimbursement Strategy | Alignment with Gulf state essential benefits package recalibrations determines cell-free DNA screening access. |
| Geographic Expansion | Peripheral province laboratory accreditation in Saudi Arabia's Eastern Province extends cold chain referral networks. |
Research Methodology
Multi-period observation of neonatal screening mandate implementation, genetic testing platform adoption curves, and ministry procurement pattern shifts anchored the trend analysis, supplemented by interviews with laboratory directors at Saudi tertiary care centers, South African provincial hospital procurement officers, UAE private obstetrics clinic operators, and Gulf state non-profit program managers. Secondary validation drew from SFDA medical device registration databases, SAHPRA quality standards documentation, UAE Ministry of Health and Prevention accreditation records, and Gulf Cooperation Council health insurance reform policy papers. Bottom-up platform shipment data and top-down healthcare expenditure estimates were triangulated to construct segment-level demand projections.
Segment-weighting across product type, application, end user, and technology dimensions informed the analytical framework, with genetic testing platforms receiving elevated weighting reflecting their fastest-expanding trajectory across the projection horizon. CAGRs were derived from fitted adoption curves incorporating next-generation sequencing cost compression rates and Gulf state reimbursement framework evolution assumptions. Industry-specific inputs included genetic counselor workforce pipeline data, cold chain logistics reliability metrics for peripheral province specimen transport, and telemedicine platform penetration rates in Egyptian and Jordanian private networks.
The model assumes a particular technology adoption path; alternative pathways for cell-free DNA screening reimbursement eligibility in Gulf state essential benefits packages would alter the outlook. Forecasts reflect assumptions regarding SFDA certification timeline stability, European reagent supply chain continuity, and South African National Health Insurance implementation pace. Deviation in any of these triggers would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Churg Strauss Syndrome Market
Rare Diseases
Dystrophic Epidermolysis Bullosa Management Market
Rare Diseases
Down Syndrome Market
Rare Diseases
Asia-Pacific Down Syndrome Market
Rare Diseases
Von Hippel-Lindau Market
Rare Diseases
Pompe Disease Market
Rare Diseases
Behcets Disease Market
Rare Diseases
Lennox-Gastaut Syndrome Market
Rare Diseases
Rare Neurological Disease Treatment Market
Rare Diseases
Hairy Cell Leukemia Market
Rare Diseases
Global Gaucher Disease Market
Rare Diseases
Spina Bifida Market
Rare Diseases
Alzheimer Disease Market
Rare Diseases
Pure Red Cell Aplasia Market
Rare Diseases
Rett Syndrome Market
Rare Diseases
Alpha-1 Antitrypsin Deficiency Market