
 Dry Yogurt Market | 2026-2036
Dry Yogurt Market Size, Share, and Industry Trends Forecast 2026-2036
Dry Yogurt Market Foresight
A capital-intensity divergence between spray-drying facility scale and artisanal probiotic preservation is reorganizing competitive tiers in dry yogurt production. Glanbia Nutritionals leverages large-scale dairy protein infrastructure across multiple geographies. Kerry Inc. sustains flavor-system integration that locks in bakery and snack manufacturer contracts. Bluegrass Dairy & Food, Inc. anchors regional milk sourcing networks in the Upper Midwest.
Dry yogurt is a dehydrated dairy product manufactured through spray-drying or freeze-drying of fermented milk, typically retaining live cultures at counts between 10^6 and 10^9 CFU per gram depending on process temperature and protective matrix encapsulation. The resulting powder delivers shelf-stable acidity, protein content near 35-40%, and functional gelling properties for industrial food formulation. Powdered yogurt occupies the volume core as legacy bakery and confectionery buyers prioritize cost-stable bulk supply, while organic yogurt powder captures premium margin pools from clean-label commitments at retail-facing food manufacturers. Non-dairy yogurt powder, though nascent, is expanding fastest as oat and coconut bases penetrate plant-based smoothie and snack applications where allergen-free claims command price premiums.
FDA standards for acidified food classification and EFSA health claim assessments on live cultures shape product labeling and cross-border market access for dry yogurt suppliers. The EU F-Gas Regulation and USDA organic certification requirements further constrain processing equipment and raw material sourcing decisions. Stakeholders must monitor evolving probiotic shelf-life validation protocols and alternative protein fermentation advances to preserve formulation relevance.
Market Dynamics
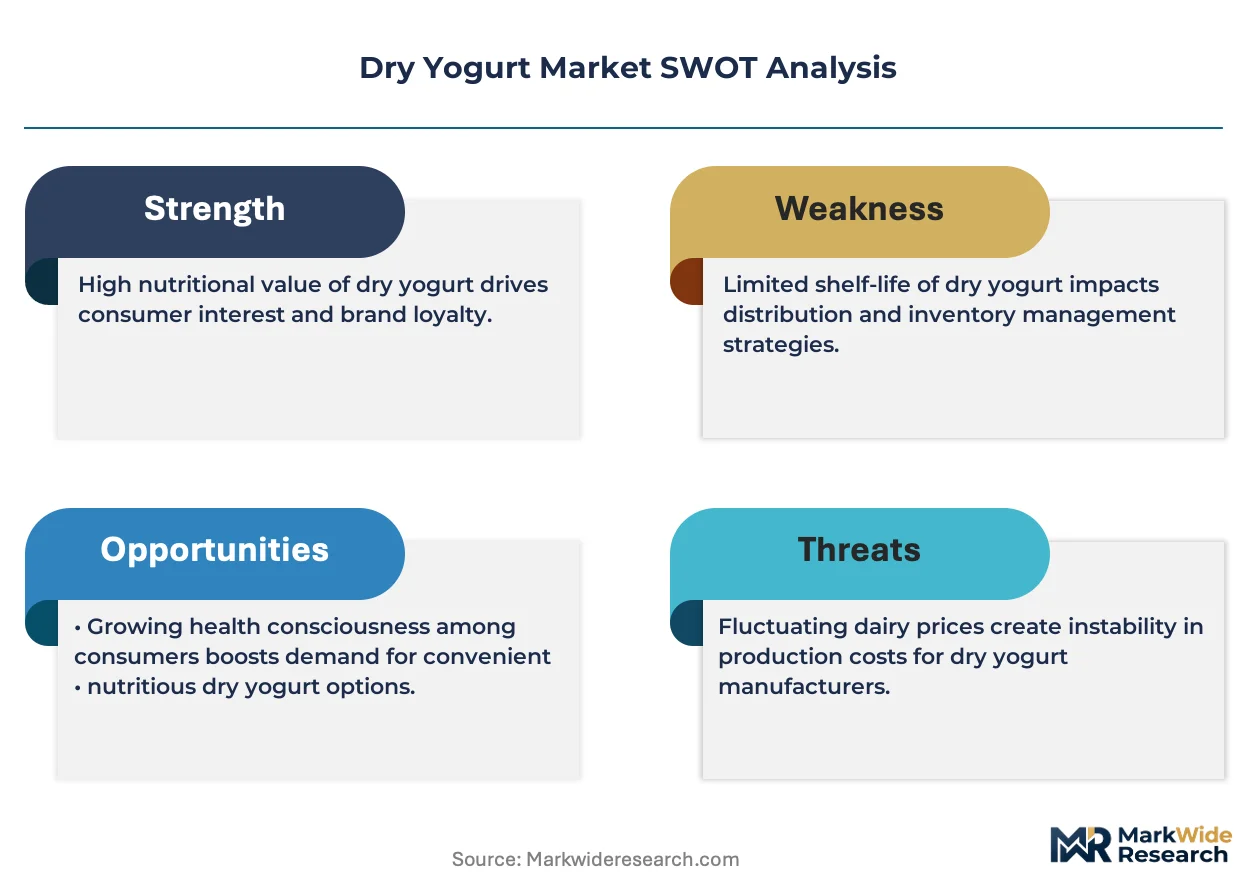
Freeze-drying technology is decomposing the traditional spray-drying cost advantage in live-culture preservation, forcing facility investment recalculations across dairy processing networks as probiotic viability claims tighten under FDA and EFSA scrutiny.
Growth Catalysts
- EFSA health claim assessments:Validated live-culture counts on finished products command shelf-space premiums at retail-facing food manufacturers in Germany and France, accelerating clean-label procurement.
- Plant-based smoothie formulation:Oat and coconut yogurt powders penetrate allergen-free snack applications where coconut-derived bases replace dairy in functional beverage blends.
- Bakery sector bulk purchasing:Industrial confectionery buyers in Japan consolidate powdered yogurt contracts to lock in protein cost stability against fluid dairy volatility.
Market Restraints
- Milk powder input cost volatility:Regional dairy commodity swings in the Upper Midwest constrain margin predictability for spray-drying operators without backward integration into milk sourcing.
- EU F-Gas Regulation compliance:Refrigeration-dependent freeze-drying facilities face equipment retrofit mandates that extend payback periods on probiotic-preservation capacity expansions.
- Fresh yogurt substitution:Cold-chain improvements in emerging markets erode shelf-stable powder advantages for immediate consumption applications.
Strategic Opportunities
- USDA organic certification pipeline:Premium-tier food manufacturers in the United States source certified organic yogurt powder to meet retailer clean-label mandates with verified supply chain documentation.
- Sports nutrition powder blends:Whey-yogurt protein hybrids capture formulation slots in recovery beverages where fermented dairy acidity enhances flavor masking.
- Direct-to-manufacturer e-procurement platforms:Bulk ingredient marketplaces displace traditional distributor layers for mid-scale bakery and snack producers seeking transparent pricing.
Industry Challenges
- Encapsulation chemistry expertise scarcity:Protective matrix formulation for 10^9 CFU/g stability requires specialized food science talent concentrated at legacy dairy research institutes.
- Dual validation timeline compression:Simultaneous FDA acidified food classification and EFSA novel food assessments extend product launch windows for cross-border suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dry Yogurt Market |
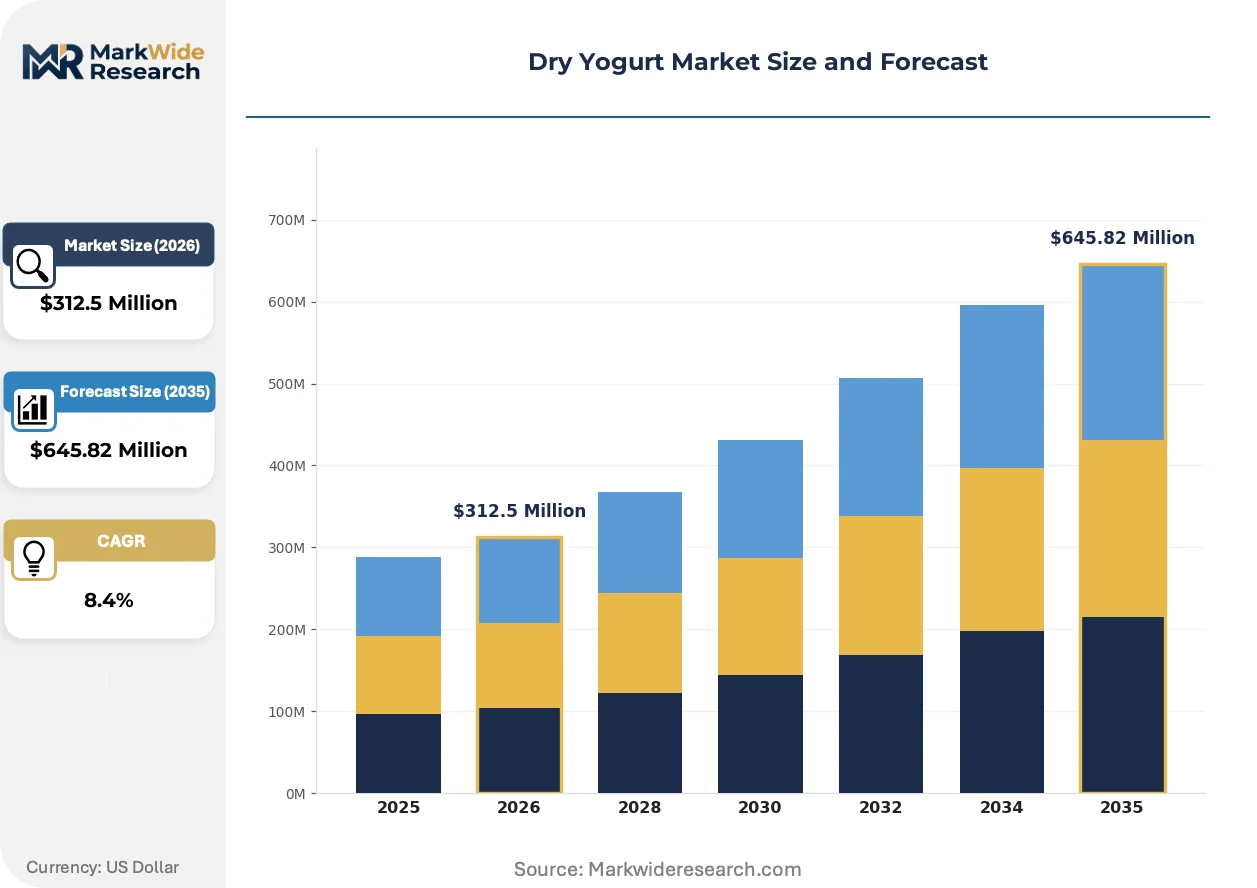
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $645.82 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered Yogurt, Flavored Yogurt Powder, Organic Yogurt Powder, Non-Dairy Yogurt Powder End User: Food Manufacturers, Bakeries, Restaurants, Home Consumers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Food Service Application: Baking, Smoothies, Snacks, Dressings |
| Companies Covered | Ace International LLP, PreGel America, Inc., Glanbia Nutritionals, Bluegrass Dairy & Food, Inc., C.P. Ingredients Ltd., Epi Ingredients, Almil AG, Dr. Suwelack, Kerry Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dry Yogurt Market Shifts & Advancements
Process innovation is fragmenting the historical scale advantage of centralized spray-drying infrastructure. Three developments are compressing competitive timelines across the value chain.
Microencapsulation via fluidized bed coating is decomposing the temperature-degradation tradeoff that historically forced probiotic suppliers toward premium freeze-drying. Bakery and confectionery formulators in the United States adopt these intermediate-cost powders at accelerating rates. The technology is decomposing the binary cost-viability structure that locked mid-tier players out of live-culture claims.
REACH chemical safety dossier requirements for processing aids are extending substance approval timelines for European yogurt powder facilities using novel encapsulation polymers. Industrial consequence includes reformulation toward pre-approved additive lists that limit performance optimization. German and Dutch dairy processors are responding by consolidating regulatory affairs functions across multi-site operations.
Clean-label ingredient declarations now dominate RFP specifications from retail-facing food manufacturers, displacing technical performance metrics as primary supplier selection criteria. This specification shift compresses switching cycles as buyers rotate toward certified organic and non-GMO verified sources. The pattern concentrates in United States and German processed food sectors where retailer sustainability scorecards determine listing access.
Dry Yogurt Market Segmentation
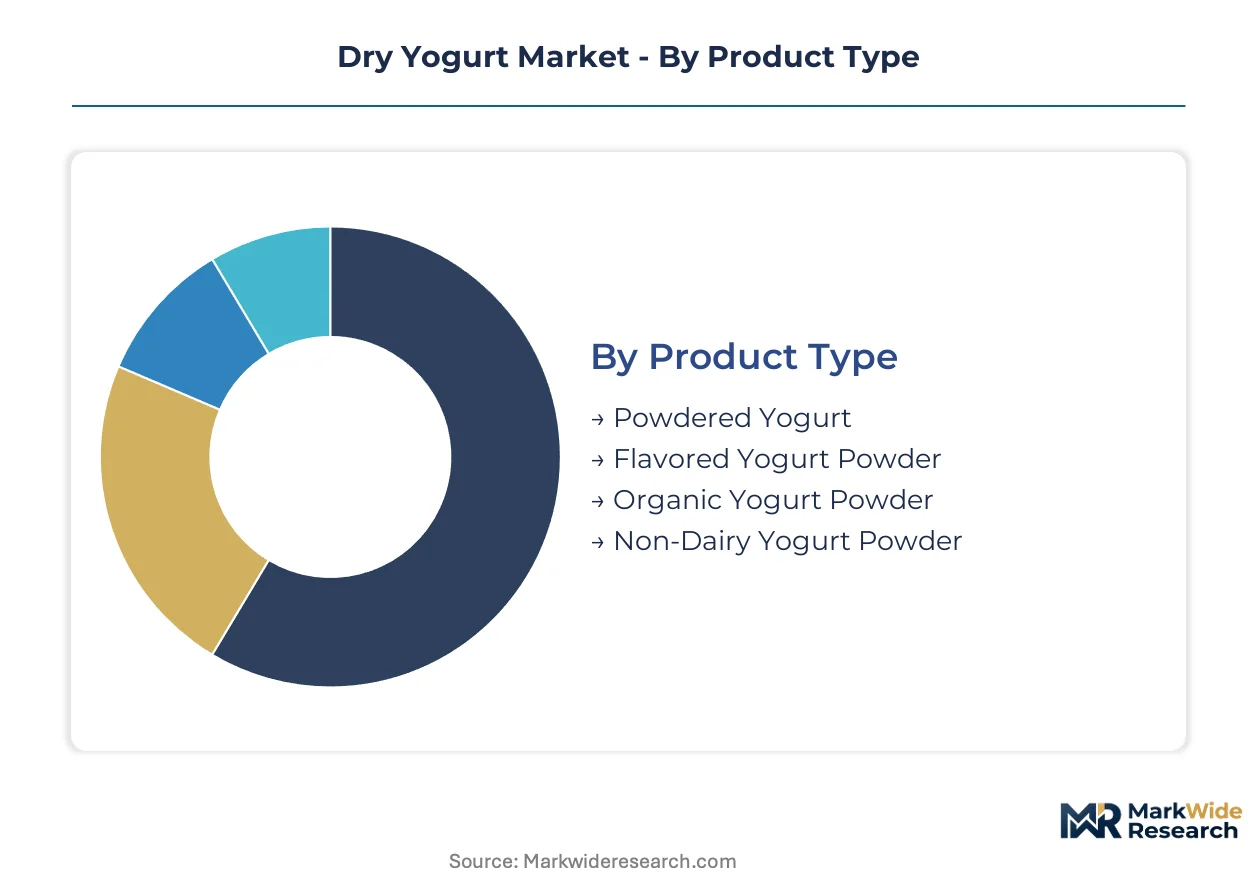
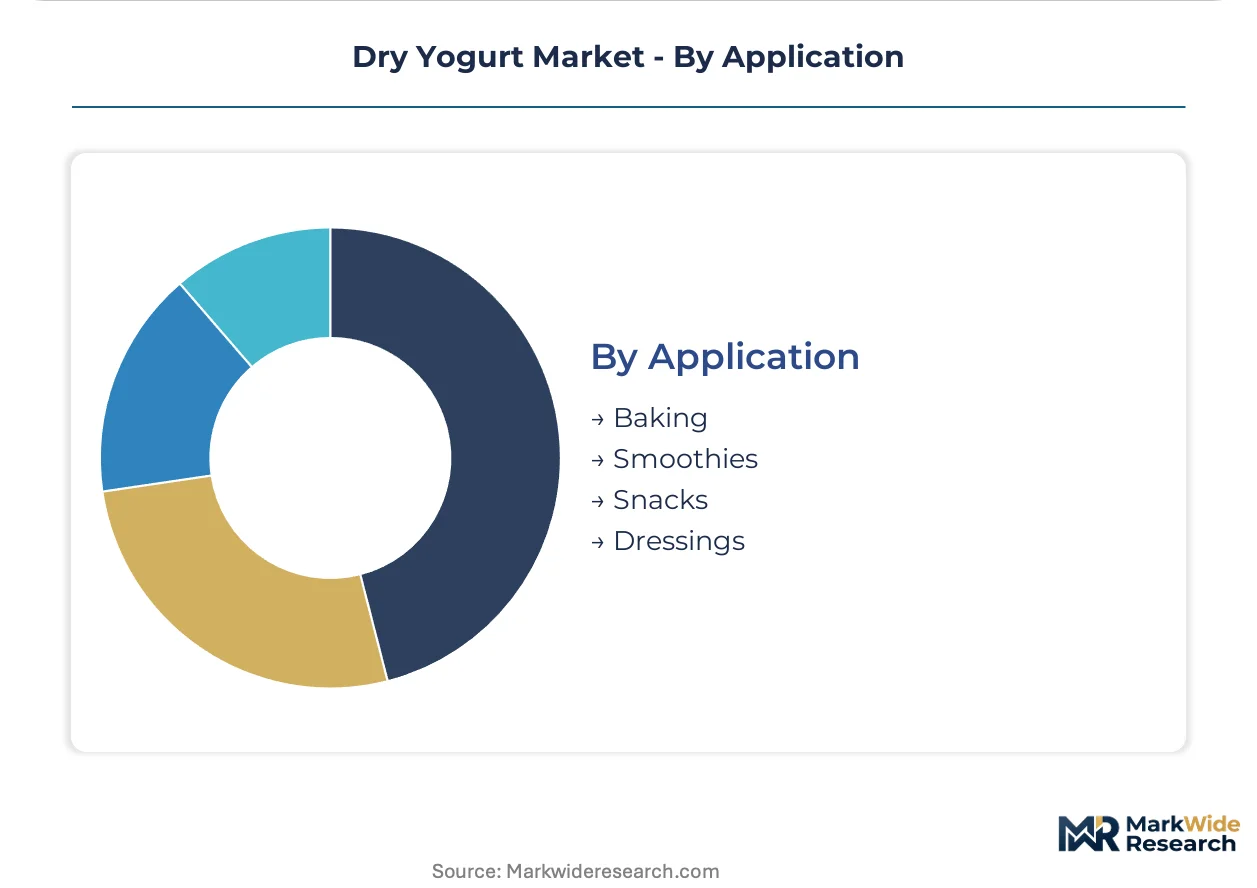
Dry yogurt segmentation reveals how processing technology and certification tiers fragment procurement patterns across industrial buyers. Powder formats, end-user scale, channel efficiency, and application-specific functionality each create distinct margin architectures that suppliers must navigate simultaneously.
Product Type:
FDA acidified food classification and EFSA live-culture validation protocols create divergent compliance burdens across product tiers, reshaping supplier qualification requirements.
- Powdered Yogurt:Standard spray-dried format with 35-40% protein content and shelf-stable acidity profiles. Industrial bakeries in Japan consolidate bulk contracts for cost-stable protein sourcing against fluid dairy volatility. Established volume favors this segment; emerging adoption favors organic and non-dairy alternatives.
- Organic Yogurt Powder:USDA-certified production with verified supply chain documentation and non-GMO verification. Retail-facing food manufacturers in the United States pay premium pricing to meet retailer clean-label mandates with transparent provenance claims.
- Flavored Yogurt Powder:Pre-blended vanilla, strawberry, and fruit variants with integrated sweetener systems. Quick-service restaurant chains deploy these for consistent smoothie base preparation without additional flavor compounding steps.
- Non-Dairy Yogurt Powder:Oat and coconut fermented bases targeting allergen-free formulation. Plant-based snack manufacturers in Germany source these for functional beverage blends where coconut-derived bases replace dairy protein.
Cost tier separation runs from commodity bulk powder through certified organic premiums to nascent plant-based positioning.
End User:
Scale of formulation operation determines whether buyers prioritize unit cost stability or technical service intensity from suppliers.
- Food Manufacturers:Large-scale industrial processors running continuous production lines. These buyers lock in annual powdered yogurt contracts with backward-integrated dairy processors to secure protein cost predictability.
- Bakeries:Mid-scale artisanal and industrial operations incorporating yogurt powder for moisture retention and tang profiles. German and French confectionery specialists specify microencapsulated live-culture variants for clean-label positioning.
- Restaurants:Food service operators deploying dry yogurt for sauce bases, marinades, and beverage applications. Chains favor flavored yogurt powders to reduce kitchen labor and ingredient inventory complexity.
- Home Consumers:Retail-packaged formats through e-commerce and specialty channels. Direct-to-consumer subscription models in the United States feature organic and non-diary variants with probiotic count transparency.
Procurement concentration tilts toward food manufacturers for volume; service intensity demands concentrate with bakeries and restaurants.
Distribution Channel:
Channel selection reflects buyer urgency, lot size requirements, and the need for technical specification verification.
- Online Retail:E-procurement platforms and direct manufacturer portals. Mid-scale snack producers in the United States displace traditional distributor layers through bulk ingredient marketplaces with transparent pricing.
- Supermarkets:Mass retail placement for home consumer formats. Shelf-space premiums in Germany and France reward EFSA-validated live-culture claims with dedicated health-food aisle positioning.
- Specialty Stores:Organic and natural product retailers with certified supply chain requirements. These channels concentrate premium-tier organic yogurt powder distribution with verified documentation.
- Food Service:Distributor networks serving restaurant and institutional accounts. Broadline operators consolidate powdered yogurt into dairy ingredient portfolios with volume-based contract structures.
Channel maturity favors food service and supermarkets; digital penetration is climbing fastest among mid-scale industrial buyers.
Application:
Functional requirements for acidity, protein content, and gelling behavior vary sharply across end-use categories.
- Baking:Powdered yogurt provides moisture retention, protein enrichment, and subtle acidity in cakes, muffins, and bread formulations. Japanese industrial confectionery buyers prioritize cost-stable bulk supply with consistent hydration performance.
- Smoothies:Instant reconstitution properties and protein fortification drive formulation choices. Sports nutrition brands in the United States blend whey-yogurt hybrids where fermented dairy acidity masks off-notes from alternative proteins.
- Snacks:Dry yogurt coatings and inclusions for granola, protein bars, and savory applications. Plant-based snack manufacturers source non-dairy yogurt powders for allergen-free positioning in functional bars.
- Dressings:Emulsion stability and tangy flavor profiles for shelf-stable and refrigerated sauces. Food manufacturers specify microencapsulated variants to preserve probiotic viability through acidic dressing matrices.
Application maturity centers on baking; smoothie and snack segments are gaining share fastest through plant-based formulation expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for dry yogurt powder varies sharply across geographies. Japanese industrial buyers prioritize cost-stable bulk contracts, while German and French manufacturers pay premiums for EFSA-validated live-culture claims. United States procurement splits between commodity volume and certified organic premiums.
United States
Food manufacturers in the Midwest and California drive bulk powdered yogurt procurement for bakery and snack applications. USDA organic certification requirements constrain raw material sourcing for premium-tier suppliers. Wisconsin and New York State concentrate spray-drying capacity where dairy processors backward-integrate into regional milk sourcing networks.
Germany
Clean-label ingredient substitution accelerates demand for EFSA-validated probiotic powders among retail-facing processed food producers. REACH chemical safety dossier requirements extend approval timelines for novel encapsulation polymers. The Bavarian dairy processing cluster consolidates regulatory affairs functions across multi-site operations to manage compliance burdens.
Japan
Industrial confectionery buyers consolidate annual contracts to lock in protein cost stability against fluid dairy price volatility. The national pharmaceutical regulator maintains strict import standards for acidified food classification. Tokyo and Osaka metropolitan areas concentrate formulation R&D for functional beverage applications.
France
Bakery and confectionery specialists specify microencapsulated live-culture variants for clean-label positioning in premium product lines. EFSA health claim assessments on live cultures shape finished product labeling requirements. The Rhône-Alpes region anchors dairy ingredient innovation clusters serving pan-European distribution.
India
Mid-scale snack producers adopt dry yogurt powder for moisture retention in traditional sweet and savory applications. FSSAI food safety standards govern acidified dairy product classification for domestic and export markets. Maharashtra and Gujarat concentrate emerging spray-drying capacity serving South Asian and Middle Eastern export demand.
Dry Yogurt Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in dry yogurt production. Scale-driven dairy processors leverage captive milk supply and multi-plant spray-drying networks to secure bulk bakery contracts. Niche operators concentrate on live-culture preservation through freeze-drying or advanced microencapsulation. Two dominant competitive moves define current positioning: backward integration into regional milk sourcing to control input costs, and strategic partnerships with flavor-system integrators to lock in food service and snack manufacturer relationships.
Among Ireland-based nutritionals specialists, Glanbia Nutritionals occupies a position exemplifying scale-driven dairy protein infrastructure across multiple geographies. Kerry Inc., also Ireland-originated, represents the flavor-system integration archetype that sustains bakery and snack manufacturer contracts through technical service intensity. Bluegrass Dairy & Food, Inc. anchors the regional milk sourcing archetype through Upper Midwest network concentration.
| Leading Market Players |
|---|
| Ace International LLP |
| PreGel America, Inc. |
| Glanbia Nutritionals |
| Bluegrass Dairy & Food, Inc. |
| C.P. Ingredients Ltd. |
| Epi Ingredients |
| Almil AG |
| Dr. Suwelack |
| Kerry Inc. |
| Others |
Supply & Pricing Matrix
Annual offtake contracts with backward-integrated dairy processors lock in both milk powder input access and protein cost visibility for Japanese industrial confectionery buyers facing fluid dairy volatility. This contract structure concentrates pricing power with spray-drying operators in Wisconsin and New York State who control regional milk sourcing networks.
Pricing Analysis
Technical service contracts for live-culture validation drive lifetime value beyond commodity powder sales. Three-tier pricing structure across certified organic, EFSA-validated probiotic, and commodity bulk tiers separates premium-mid-economy differentiation. Cost compression in standard spray-dried powder is intensifying because microencapsulation technology decomposes historical freeze-drying cost barriers. Food manufacturers running continuous production lines show least price sensitivity; mid-scale artisanal bakeries in Germany exhibit highest sensitivity to unit cost fluctuations.
Supply Chain Analysis
Inventory cycles for probiotic viability testing extend lead times beyond standard dairy ingredient procurement. Supply concentrates in the United States, Germany, and Japan where spray-drying capacity clusters near regional milk production. Raw material flows draw from fluid milk, protective matrix polymers, and live culture concentrates. Single-source vulnerability runs through specialized encapsulation chemistry expertise concentrated at legacy dairy research institutes. Distribution runs through food service broadline operators and direct e-procurement portals serving mid-scale industrial buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Live-culture shelf-life validation services represent a service-attach opportunity expanding faster than commodity powder sales as EFSA and FDA scrutiny tightens viability claim requirements.
For Market Incumbents: Fortify backward integration into Upper Midwest milk sourcing networks to defend against margin pressure from regional dairy commodity swings. Secure exclusive technical service partnerships with flavor-system integrators to lock in quick-service restaurant chain contracts before microencapsulation technology commoditizes live-culture preservation. For New Entrants and Emerging Players: Microencapsulation technical consulting gaps where incumbents under-serve present white-space targets for mid-scale bakery and snack producers seeking EFSA-validated probiotic claims without freeze-drying capital investment. Penetrable entry points concentrate in German and French clean-label confectionery specialists requiring certified organic supply chain documentation. Go-to-market positioning should anchor on rapid regulatory dossier preparation for dual FDA-EFSA validation timelines. For Investors and Strategic Acquirers: Regional spray-drying specialists with captive organic milk supply and established USDA certification pipelines offer acquisition targets with defensible margin structures. Long-term viability hinges on formulation relevance preservation through alternative protein fermentation advances and probiotic shelf-life protocol evolution. Watch for inflection signals in oat and coconut base fermentation yields that would accelerate non-dairy yogurt powder cost parity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Milk Sourcing | Wisconsin and New York State processors secure protein cost predictability against fluid dairy volatility. |
| Microencapsulation Technology Licensing | Fluidized bed coating partnerships decompose freeze-drying cost barriers for mid-tier live-culture suppliers. |
| Dual Certification Pipeline Investment | Simultaneous FDA acidified food and EFSA novel food preparation compresses cross-border product launch windows. |
| Direct E-Procurement Platform Launch | Bulk ingredient marketplaces displace distributor layers for transparent pricing to mid-scale snack producers. |
| Organic Supply Chain Verification Program | USDA-certified documentation meets retailer clean-label mandates with transparent provenance claims. |
Research Methodology
Cross-validation between primary interviews with spray-drying plant managers, dairy procurement leads at industrial bakeries, regulatory affairs directors, and flavor-system integrators anchors the qualitative findings. Secondary validation draws from FDA acidified food classification records, EFSA health claim assessment databases, USDA organic certification listings, and customs trade data on dairy protein flows. Bottom-up volume modeling triangulates against top-down expenditure analysis across the projection horizon.
Sensitivity analysis around milk powder input cost assumptions and probiotic viability degradation rates shapes the analytical framework. Segmentation dimensions span product type, end-user scale, distribution channel efficiency, and application-specific functionality across the modeling period. CAGRs derive from fitted growth curves applied to validated baseline estimates, with industry-specific inputs including EFSA validation timeline compression and REACH chemical safety dossier approval rates.
Underlying assumptions cover sustained clean-label procurement acceleration and freeze-drying equipment retrofit compliance, with deviation risk concentrated in EU F-Gas Regulation enforcement intensity and fresh yogurt cold-chain substitution in emerging markets. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Organic Milk Replacers Market
Dairy Alternatives
Sugar-Free Soy Milk Powder Market
Dairy Alternatives
United States Oat Milk Market
Dairy Alternatives
Plant-Based Cheese Wedges Market
Dairy Alternatives
Europe Dairy Alternatives Market
Dairy Alternatives
Vegan Milk Alternatives Market
Dairy Alternatives
Camel Milk Products Market
Dairy Alternatives
Clarified Butter Market
Dairy Alternatives
Pea Milk Market
Dairy Alternatives
Breast Milk Substitutes Market
Dairy Alternatives
North America Non-Dairy Cheese Market
Dairy Alternatives
A2 Lactose-free Milk Market
Dairy Alternatives
Cheese Alternative Market
Dairy Alternatives
Europe Almond Milk Market
Dairy Alternatives
Asia-Pacific Coconut Milk Market
Dairy Alternatives
Soy Milk Powder Market