
 Organic Milk Replacers Market | 2026-2036
Organic Milk Replacers Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Milk Replacers Market Outlook
European organic dairy capacity is reshaping supply dynamics for milk replacer manufacturers. Cargill, Incorporated leverages its grain procurement networks to secure certified organic soy and whey protein inputs. Land O'Lakes sustains strong brand recognition among North American dairy cooperatives seeking organic calf nutrition protocols. Milk Specialties Global anchors its position through specialized spray-drying capabilities for heat-sensitive organic lipid systems.
Organic milk replacers constitute formulated feed products designed to substitute whole milk in young animal diets, typically containing spray-dried dairy or plant proteins combined with organic-certified fat sources and micronutrient premixes at precise osmolality targets. Powdered form dominates current manufacturing output due to extended shelf stability and reduced freight costs relative to liquid alternatives. Protein-enriched variants command premium positioning as dairy producers prioritize accelerated rumen development in replacement heifers, while omega-3 enhanced formulations represent the fastest-growing nutritional content category reflecting consumer demand for enriched end-product profiles.
USDA Organic certification and EU Organic Regulation govern ingredient traceability and processing integrity across major production regions, with FDA feed safety rules imposing additional manufacturing controls on domestic suppliers. The EU F-Gas Regulation indirectly affects spray-drying energy costs through refrigeration system compliance requirements. Stakeholders must monitor evolving organic livestock feed standards in key importing jurisdictions to anticipate reformulation mandates and certification burden shifts.
Market Dynamics
EU Organic Regulation ingredient traceability mandates are compressing supplier qualification timelines while simultaneously fragmenting procurement options across spray-dried protein concentrate sourcing networks.
Growth Catalysts
- Biodynamic farming certification expansion:German dairy cooperatives are mandating Demeter-compliant calf nutrition protocols, creating pull-through demand for premium organic lipid formulations.
- USDA Organic livestock feed standard updates:Revised pasture access requirements for dairy replacement heifers are accelerating whole milk substitution rates with certified organic replacers.
- Spray-drying energy recovery systems:Heat exchanger retrofits at European processing facilities are reducing organic-certified production cost premiums by capturing waste thermal energy.
Market Restraints
- Organic soy protein concentrate supply concentration:Over 60% of EU-certified organic soy processing capacity resides in three member states, creating geographic vulnerability to weather-driven crop failures.
- F-Gas Regulation compliance costs:EU refrigeration system retrofits for spray-drying operations are adding capital intensity to organic lipid handling infrastructure.
- Whole milk price volatility:Spot market fluid milk discounts during spring flush periods periodically invert organic replacer cost economics for price-sensitive calf rearing operations.
Strategic Opportunities
- Polish organic dairy sector expansion:Rapid conversion of conventional calf rearing operations in Masovia and Podlaskie voivodeships is creating first-mover positioning for certified feed suppliers.
- Omega-3 fatty acid enrichment protocols:Algal DHA integration into organic lipid matrices addresses end-consumer demand for functional dairy without compromising certification integrity.
- Veterinary prescription channel development:Direct veterinarian dispensing relationships bypass traditional distributor markups while embedding replacer selection into herd health protocols.
Industry Challenges
- Organic certification timeline compression:Three-year land conversion requirements for feed crop sourcing outpace calf rearing operation expansion plans in emerging organic dairy regions.
- Spray-drying operator skill scarcity:Specialized knowledge of heat-sensitive organic protein denaturation thresholds is concentrated among aging workforce cohorts at European processing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Milk Replacers Market |
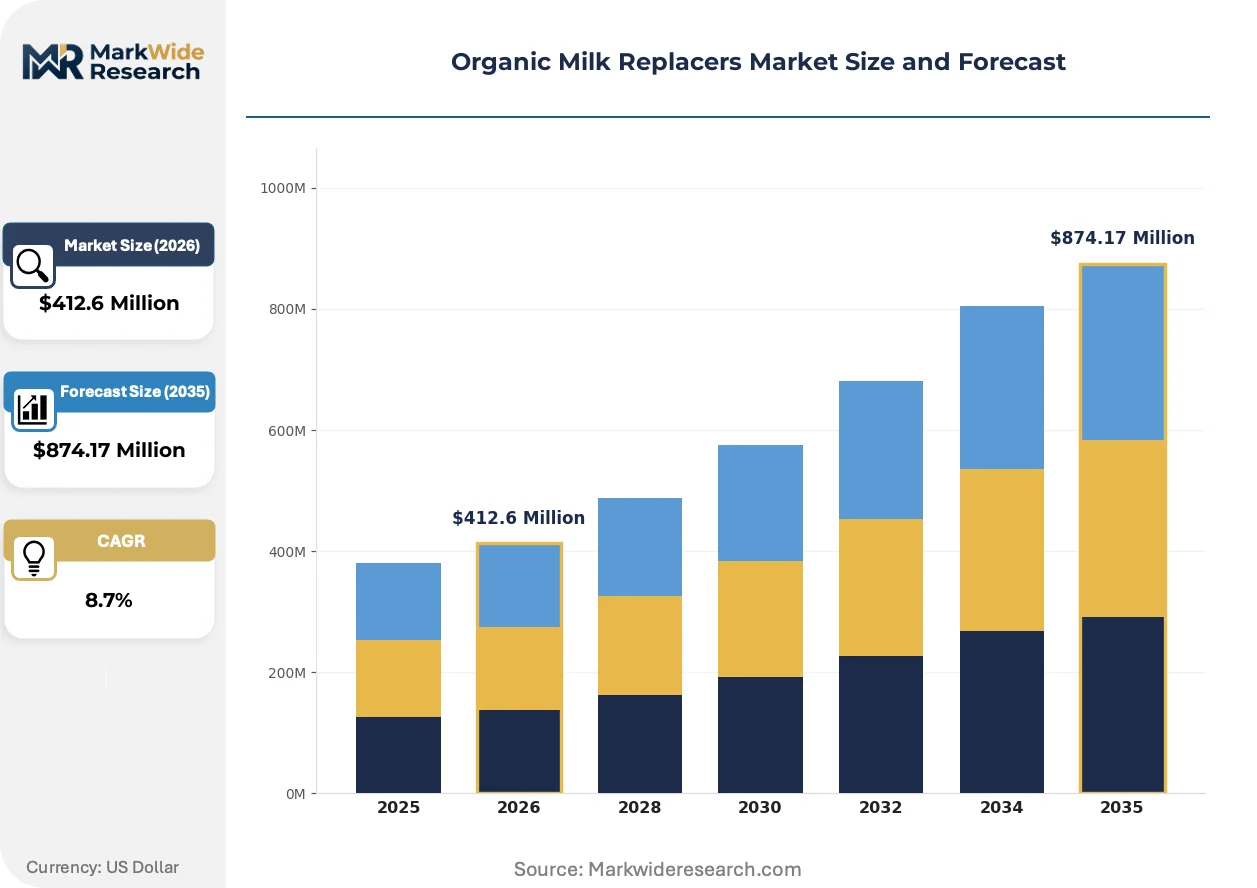
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered Form, Liquid Form, Concentrate, Ready-to-Feed Age Group: Infants, Toddlers, Young Children, Adults Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Health Food Stores Nutritional Content: Protein-Enriched, Lactose-Free, Fortified with Vitamins, Omega-3 Enhanced |
| Companies Covered | I.N. Hellas, Calva Products, Kent Nutrition Group, Cargill, Incorporated, Land O'Lakes, Royal Milc, Inc., Biocom, Milk Specialties Global, Manna Pro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Milk Replacers Market Strategic Shifts
Digital feed formulation platforms are compressing the interval between nutritional research breakthroughs and commercial organic replacer deployment, collapsing traditional product development cycles.
Precision fermentation-derived whey protein is virtualizing the conventional dairy protein supply chain for organic calf nutrition manufacturers. Specialty ingredient houses in the Netherlands and Denmark are scaling pilot facilities to commercial volumes. This technology is virtualizing the geographic constraints that historically tethered organic replacer production to milk-shed proximity.
EU F-Gas Regulation phase-down schedules are forcing refrigeration-dependent spray-drying operations toward ammonia-based cooling systems or process redesign. German processing clusters are absorbing disproportionate compliance costs due to older installed equipment bases. Organic lipid handling facilities in Bavaria are responding with accelerated heat pump adoption to maintain production economics.
Direct-to-farm digital ordering platforms are displacing traditional agricultural distributor networks for organic calf nutrition procurement. Large-scale dairy cooperatives in Wisconsin and California are consolidating purchasing through proprietary procurement portals. This channel shift is most visible in North American markets where cooperative membership concentration enables platform economics.
Organic Milk Replacers Market Segmentation
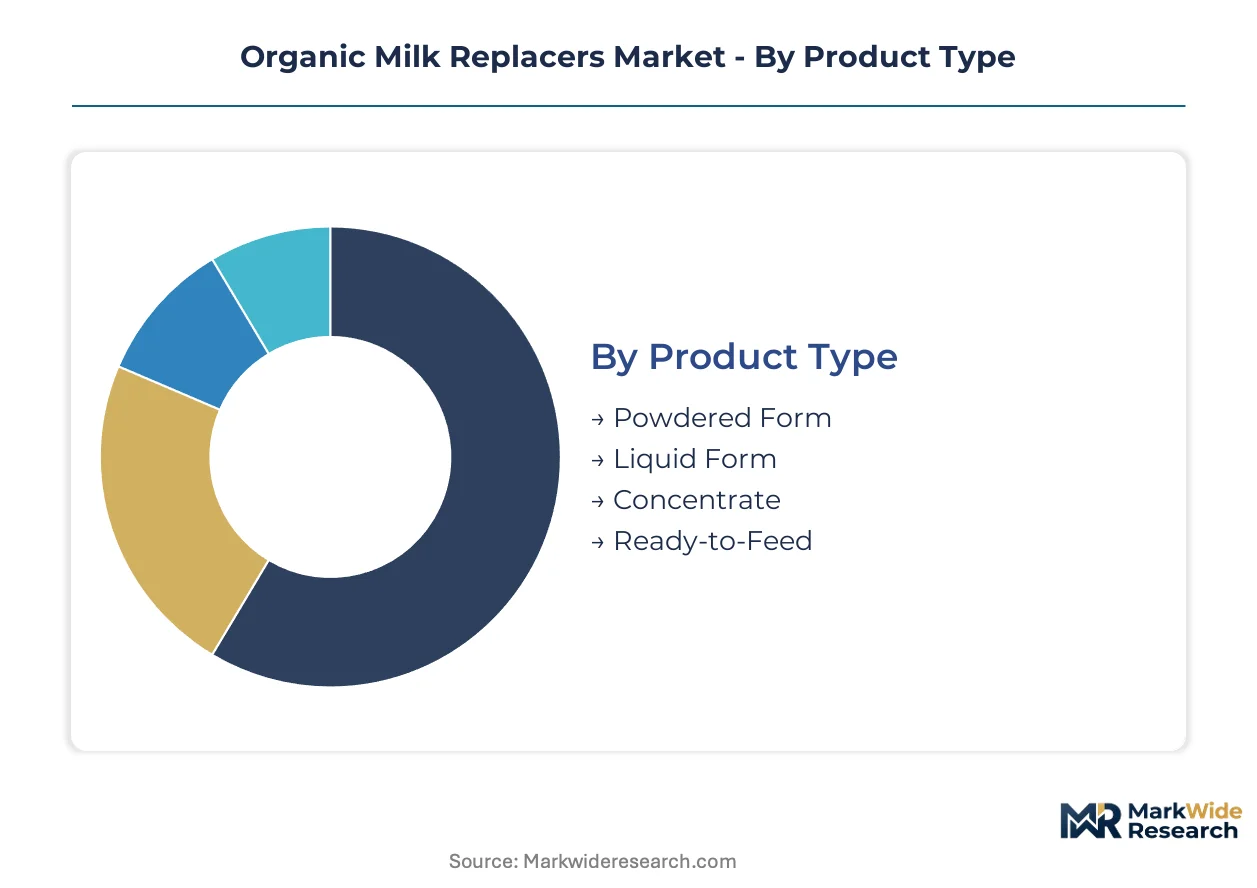
Segmentation in organic milk replacers reveals how formulation chemistry, age-specific digestive physiology, and procurement channel economics intersect to create distinct competitive arenas. Manufacturers must align spray-drying capabilities, certification protocols, and distribution investments with the specific performance thresholds each segment demands.
Product Type:
Cost tier differentiation separates commodity-scale operations from precision-formulated premium positioning across manufacturing infrastructure investments.
- Powdered Form:Spray-dried dairy and plant protein matrices combined with organic lipid microencapsulation deliver extended shelf stability and reduced freight density. Dairy calf rearing operations in Germany specify powdered replacers for automated mixing systems, though spring flush whole milk price volatility periodically compresses substitution economics.
- Liquid Form:Aseptically processed emulsions requiring refrigerated logistics chains and shorter rotation cycles. Ready-to-feed convenience commands premium positioning in veterinary-supervised neonatal intensive care protocols where osmolality precision and contamination risk reduction outweigh per-liter cost premiums.
- Concentrate:Reduced-moisture intermediates requiring on-farm dilution, balancing storage efficiency against mixing consistency risks.
- Ready-to-Feed:Terminal consumption formats eliminating preparation variables, concentrated in institutional procurement channels with strict HACCP compliance requirements.
Powdered Form holds installed capacity. Liquid Form is rotating up the share rankings.
Age Group:
Application-specific digestive maturation stages dictate protein hydrolysate complexity, fat globule sizing, and micronutrient premix calibration.
- Infants:Whey-dominant protein ratios mimicking maternal milk composition, with strict osmolality targets below 400 mOsm/L to prevent neonatal dehydration. Demeter-certified biodynamic farming operations in Germany mandate infant-stage organic lipid sourcing with documented pasture access verification.
- Toddlers:Transition formulations incorporating gradual casein ratio increases and emerging prebiotic fiber inclusion to support developing gut microbiota.
- Young Children:Growth-optimized protein concentrations with iron and zinc fortification addressing nutritional gaps in plant-based household diets.
- Adults:Functional positioning around sports recovery and metabolic health, with algal DHA and MCT oil integration gaining formulation priority.
Infants maintains volume concentration. Toddlers is climbing the fastest as biodynamic certification expansion extends feeding protocol duration requirements.
Distribution Channel:
Customer type procurement behavior separates price-sensitive bulk purchasers from specification-driven protocol adopters across channel touchpoint investments.
- Online Retail:Direct-to-farm digital platforms enabling cooperative-scale procurement with batch-level certificate documentation. Wisconsin and California dairy cooperatives are consolidating replenishment through proprietary portals, displacing traditional agricultural distributor markups.
- Supermarkets:Mass-market shelf presence requiring organic certification logo prominence and competitive unit economics against conventional alternatives.
- Specialty Stores:Curated assortment environments supporting premium narrative and staff consultation for conversion of conventional calf rearing operations.
- Health Food Stores:Demographic alignment with biodynamic and regenerative agriculture values, commanding highest margin positioning through relationship-based repeat purchase.
Online Retail is gaining share fastest in North American cooperative concentration zones. Specialty Stores holds margin leadership in European biodynamic corridors.
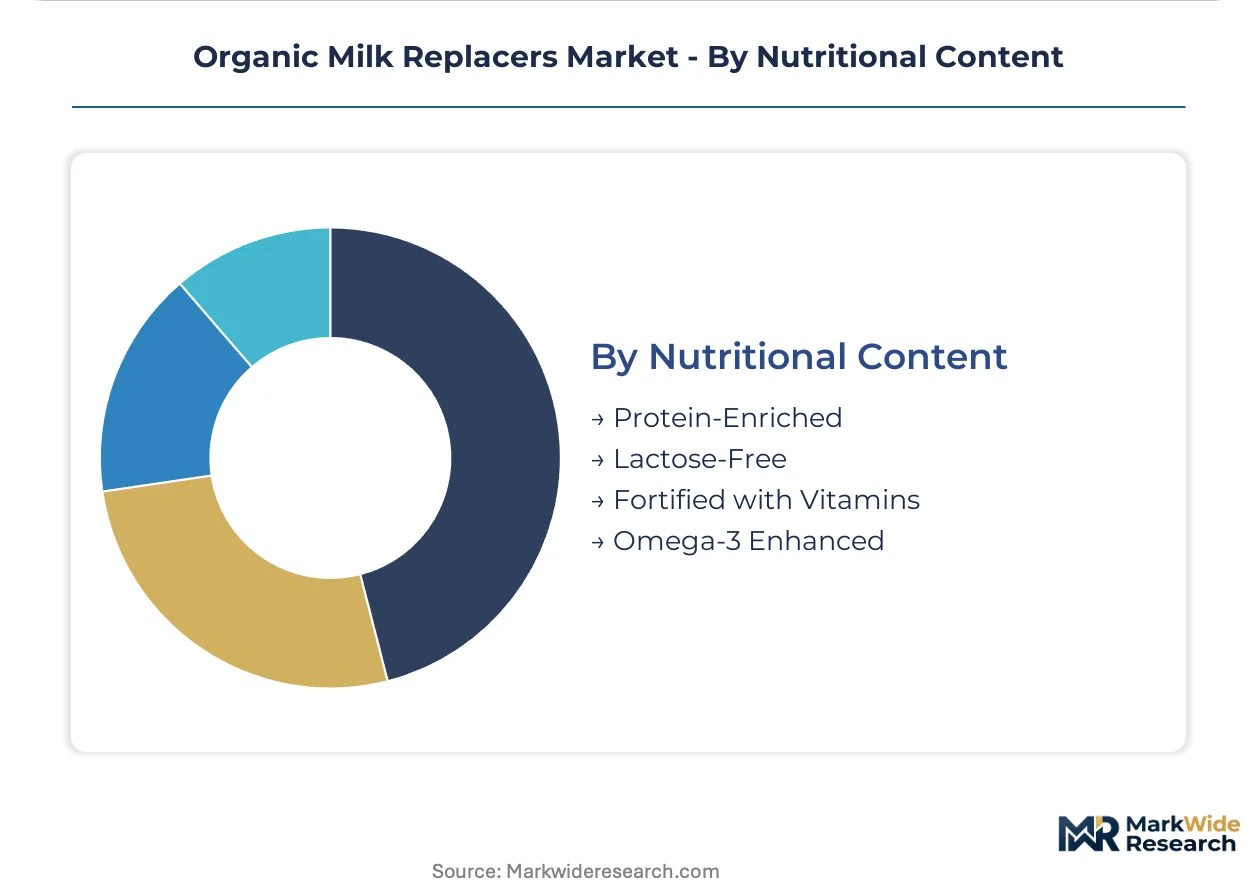
Nutritional Content:
Margin architecture separates commodity protein fortification from patented lipid delivery systems and clinical-grade micronutrient precision.
- Protein-Enriched:Elevated amino acid density accelerating rumen papillae development in replacement heifers, with spray-dried plasma protein and hydrolyzed wheat gluten expanding organic-certified input options. Polish dairy sector conversion in Masovia voivodeship is driving volume concentration for accelerated growth protocols.
- Omega-3 Enhanced:Algal DHA and organic flaxseed oil integration addressing end-consumer functional dairy demand without compromising EU Organic Regulation certification integrity. This segment is expanding most quickly as precision fermentation-derived lipid sources virtualize traditional marine oil supply constraints.
- Lactose-Free:Carbohydrate substitution with organic maltodextrin or glucose polymers for enzymatic deficiency management.
- Fortified with Vitamins:Fat-soluble vitamin microencapsulation ensuring stability through spray-drying thermal exposure.
Protein-Enriched dominates current manufacturing allocation. Omega-3 Enhanced is rotating up the share rankings as algal sourcing scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spray-dried organic protein processing clusters in Germany, the United States, and the Netherlands supply the majority of formulated milk replacer output, with regulatory divergence between USDA Organic and EU Organic Regulation certification systems fragmenting cross-border procurement strategies.
Germany
Demeter-certified biodynamic dairy cooperatives in Bavaria and Lower Saxony mandate pasture-verified organic lipid sourcing for calf nutrition protocols. The EU Organic Regulation enforces three-year land conversion requirements for feed crop traceability. Processing facilities in Bavaria retrofit ammonia-based cooling systems to maintain F-Gas Regulation compliance while preserving organic-certified production economics.
United States
Wisconsin and California dairy cooperatives consolidate organic calf nutrition procurement through proprietary digital platforms, displacing traditional agricultural distributor networks. USDA Organic livestock feed standard updates accelerate whole milk substitution rates with certified organic replacers. Spray-drying operations in the Midwest leverage grain procurement networks to secure certified organic soy and whey protein inputs.
Poland
Masovia and Podlaskie voivodeships experience rapid conversion of conventional calf rearing operations, creating first-mover positioning for certified feed suppliers. EU Organic Regulation ingredient traceability mandates compress supplier qualification timelines while fragmenting procurement options. Dairy sector expansion in central Poland drives volume concentration for protein-enriched accelerated growth protocols.
Netherlands
Specialty ingredient houses in Randstad and Brabant scale precision fermentation-derived whey protein from pilot to commercial volumes. The EU F-Gas Regulation phase-down schedules force refrigeration-dependent operations toward process redesign. Dutch processing clusters virtualize geographic constraints that historically tethered organic replacer production to milk-shed proximity.
France
Île-de-France and Auvergne-Rhône-Alpes anchor organic dairy capacity expansion with stringent EFSA feed safety oversight on micronutrient premix calibration. ANSM monitors veterinary prescription channel development for direct farm dispensing relationships. French biodynamic corridors maintain margin leadership through relationship-based repeat purchase in curated specialty retail environments.
Organic Milk Replacers Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with certified ingredient sourcing and spray-drying capabilities. The vendor base organizes around three strategic archetypes: diversified agribusiness conglomerates with grain procurement networks, dairy cooperative-aligned nutrition formulators, and specialized spray-drying operators with heat-sensitive organic lipid expertise. Dominant competitive moves include backward integration into certified organic protein supply and geographic expansion into emerging organic dairy conversion regions.
Within the diversified agribusiness tier, Cargill, Incorporated and Land O'Lakes occupy positions that exemplify procurement-scale advantages and cooperative-aligned distribution reach. Milk Specialties Global represents the specialized processing archetype, anchoring competitive positioning through technical capabilities in organic-certified spray-drying operations. These three entities collectively illustrate how certification integrity, manufacturing precision, and channel access define sustainable advantage in organic calf nutrition supply.
| Leading Market Players |
|---|
| I.N. Hellas |
| Calva Products |
| Kent Nutrition Group |
| Cargill, Incorporated |
| Land O'Lakes |
| Royal Milc, Inc. |
| Biocom |
| Milk Specialties Global |
| Manna Pro |
| Others |
Value Chain & Pricing Dynamics
Organic soy protein concentrate processing in Germany, France, and the Netherlands anchors upstream supply concentration, directing margin capture toward spray-drying operators with F-Gas Regulation-compliant cooling infrastructure and certified organic lipid handling capabilities. Buyers in price-sensitive calf rearing operations face asymmetric leverage against this concentrated supplier base.
Pricing Analysis
EU Organic Regulation dictates the pricing tier structure across the organic milk replacers market. Three-tier pricing structure across premium biodynamic, standard organic, and economy conventional levels separates Demeter-certified formulations from USDA Organic equivalents and non-certified alternatives. Price differentiation stems from certification grade and volume scale, with cooperative-scale procurement portals compressing distributor markups in North America. Pricing pressure stems from spring flush whole milk spot discounts that periodically invert substitution economics for dairy calf rearing operations. Smallholder calf rearing operations exhibit highest price sensitivity, while biodynamic cooperatives in Germany demonstrate lowest sensitivity due to protocol-mandated feeding requirements.
Supply Chain Analysis
Extended payment terms from dairy cooperatives and supply-chain finance facilities at grain procurement networks lubricate working capital across the organic milk replacer supply chain. Geographic supply concentration centers on Germany, the United States, and the Netherlands for spray-dried protein processing. Raw material dependencies rest on certified organic soy protein concentrate, organic whey protein, and algal DHA lipid sources. Single-source vulnerability concentrates in EU-certified organic soy processing capacity clustered in three member states. Distribution runs through direct-to-farm digital platforms displacing traditional agricultural distributor networks, particularly in Wisconsin and California cooperative zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation-derived whey protein commercialization represents a technological inflection disrupting geographic constraints that historically tethered organic replacer production to milk-shed proximity, opening white-space for non-dairy protein suppliers and virtualizing conventional supply chains.
For Market Incumbents: Entrench certification integrity advantages through accelerated heat pump adoption at Bavarian processing facilities to preserve organic-certified production economics against F-Gas Regulation compliance cost pressures. Deepen backward integration into certified organic protein supply through grain procurement network expansion in Poland's Masovia voivodeship, securing first-mover positioning as conventional calf rearing operations convert. Channel control through proprietary cooperative procurement portals defends margin position against distributor displacement. For New Entrants and Emerging Players: Establish a beachhead in Poland's Podlaskie voivodeship organic dairy conversion corridor, where EU Organic Regulation supplier qualification timelines compress incumbent response windows. Target omega-3 enhanced formulation segments where algal DHA sourcing scales fastest and precision fermentation virtualizes marine oil supply constraints. Go-to-market through veterinary prescription channel development embeds replacer selection into herd health protocols, bypassing traditional distributor markups. For Investors and Strategic Acquirers: Capital is best deployed toward specialized spray-drying operators with heat-sensitive organic lipid expertise and aging workforce knowledge concentration, capturing capability scarcity premiums across the analysis window. Acquisition archetype: mid-scale European processors with ammonia-based cooling retrofits completed and Demeter certification pathways established. Signal to watch: precision fermentation-derived protein cost parity milestones indicating supply chain virtualization acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Organic Protein Supply | Cargill's grain procurement networks secure soy and whey inputs against EU Organic Regulation traceability mandates. |
| Heat Pump Adoption at Spray-Drying Facilities | Bavarian processors preserve production economics while absorbing F-Gas Regulation refrigeration compliance costs. |
| Direct-to-Farm Digital Platform Launch | Wisconsin and California cooperatives consolidate purchasing through proprietary portals displacing distributor markups. |
| Precision Fermentation-Derived Whey Protein Scale-Up | Dutch specialty ingredient houses virtualize geographic constraints tethering production to milk-shed proximity. |
| Veterinary Prescription Channel Development | ANSM-monitored direct dispensing relationships in France embed replacer selection into herd health protocols. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of EU Organic Regulation filings, USDA Organic certification databases, and F-Gas Regulation compliance disclosures. Primary interviews engaged spray-drying facility operators, organic dairy cooperative procurement managers, veterinary nutrition specialists, and specialty ingredient R&D directors. Secondary validation drew from customs trade data on organic soy protein concentrate flows, SEC filings of diversified agribusiness conglomerates, and EFSA feed safety oversight records. Bottom-up volume modeling triangulated against top-down value estimates across certification tier and geographic production cluster segmentation.
Forecast inputs incorporate spray-drying capacity utilization rates, organic dairy herd expansion trajectories, and precision fermentation commercialization timelines across the projection horizon. Segmentation dimensions modeled include product form, age group digestive maturation stage, distribution channel procurement behavior, and nutritional content formulation chemistry. CAGRs derived from regression analysis against historical organic livestock feed standard adoption curves and pasture access requirement implementation schedules. Industry-specific inputs encompass Demeter certification expansion rates in German biodynamic corridors and Polish conventional-to-organic conversion velocity in Masovia and Podlaskie voivodeships.
Stress conditions across organic soy crop yield volatility, F-Gas Regulation phase-down acceleration, and whole milk price discount depth were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on certification integrity maintenance and spray-drying operator skill succession. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Fat Free Yogurt Market
Dairy Alternatives
Low Calorie Cream Cheese Market
Dairy Alternatives
Chickpea Milk Market
Dairy Alternatives
North America Almond Milk Market
Dairy Alternatives
North America Dairy Alternative Market
Dairy Alternatives
Canada Dairy Alternatives Market
Dairy Alternatives
Cultured Dairy Blends Market
Dairy Alternatives
US Lactose-Free Dairy Market
Dairy Alternatives
Middle East and Africa Dairy Alternatives Market
Dairy Alternatives
Macadamia Milk Market
Dairy Alternatives
Europe Almond Milk Market
Dairy Alternatives
Plant-Based Cheese Wedges Market
Dairy Alternatives
Coconut Milk Products Market
Dairy Alternatives
Dairy-Free Spreads Market
Dairy Alternatives
Dairy-Free Ice Creams Market
Dairy Alternatives
Dry Yogurt Market