
 North America Non-Dairy Cheese Market | 2026-2036
North America Non-Dairy Cheese Market Size, Share, and Industry Trends Forecast 2026-2036
North America Non-Dairy Cheese Market Insights
Asset-light contract manufacturing and co-packing arrangements is tilting competitive dynamics toward brands that lack captive production facilities. Miyoko's Creamery leverages fermentation-derived fat technologies to differentiate its premium positioning. Kite Hill anchors its operations in almond-milk curd systems that sustain consistent texture profiles. Daiya Foods competes through broad retail distribution control across conventional grocery channels.
North America non-dairy cheese comprises plant-derived protein and fat matrices formulated to replicate the melt, stretch, and flavor characteristics of conventional cheese, typically achieving protein content between 2-6 grams per serving through cashew, almond, or coconut base emulsification. Shredded formats dominate food service procurement due to operational compatibility with existing pizza and sandwich assembly lines. Coconut-based sources lead retail velocity in conventional supermarkets while cashew-derived products occupy premium positioning in specialty stores. Cream cheese alternatives represent the fastest-growing product type as bagel chains and bakery applications expand plant-based breakfast menus.
The FDA's draft guidance on plant-based milk labeling and the USDA's oversight of school nutrition programs shape product formulation and institutional procurement eligibility across the United States. Health Canada regulates analog cheese products under its Food and Drug Regulations, affecting cross-border formulation standardization for manufacturers operating in both countries. Stakeholders must monitor evolving protein fortification standards and allergen disclosure requirements as state-level labeling initiatives proliferate.
Market Dynamics
The FDA's updated labeling guidance for plant-based dairy alternatives is forcing manufacturers to reformulate protein matrices and fat emulsification systems to meet compositional thresholds while maintaining sensory parity with conventional cheese.
Growth Catalysts
- Quick-service restaurant integration:Major pizza and sandwich chains in the United States now feature plant-based cheese on permanent menu lines, creating institutional demand pull that stabilizes procurement volumes for contract manufacturers.
- Fermentation-derived fat technologies:Precision fermentation processes enable lipid profiles that replicate dairy mouthfeel without allergen-bearing nut bases, expanding addressable consumer segments beyond traditional plant-based buyers.
- California food manufacturing corridor concentration:Dense clustering of ingredient suppliers, co-packers, and R&D facilities in the Los Angeles-San Francisco corridor reduces formulation-to-shelf cycle times for regional brands.
Market Restraints
- Cashew supply concentration:Premium non-dairy cheese relies on Vietnamese and Indian cashew processors, exposing margins to raw material price volatility and shipping lane disruptions.
- Protein fortification compliance costs:Meeting FDA protein content claims requires expensive pea or fava bean isolate additions that compress gross margins versus conventional cheese inputs.
- Coconut oil input inflation:Retail velocity leaders depend on Philippine and Indonesian coconut fat sources where climate volatility and labor shortages drive recurring cost pressure.
Strategic Opportunities
- USDA school nutrition program eligibility:Reformulation to meet Child Nutrition Program protein and calcium standards opens institutional procurement channels with multi-year contract potential.
- Mexico market underpenetration:Limited retail distribution and food service adoption in Mexican metropolitan areas present first-mover expansion potential for brands with Spanish-language packaging capabilities.
- Cream cheese alternative breakfast channel:Bagel chain partnerships and bakery applications represent whitespace beyond pizza and sandwich formats where shredded formats currently dominate.
Industry Challenges
- Fermentation scientist talent scarcity:Commercial-scale precision fat production requires specialized biochemical engineering expertise that outpaces current North American university program output.
- Cross-border formulation standardization:Divergent Health Canada and FDA allergen disclosure requirements force dual-label production runs that complicate supply chain planning for manufacturers operating in both countries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Non-Dairy Cheese Market |
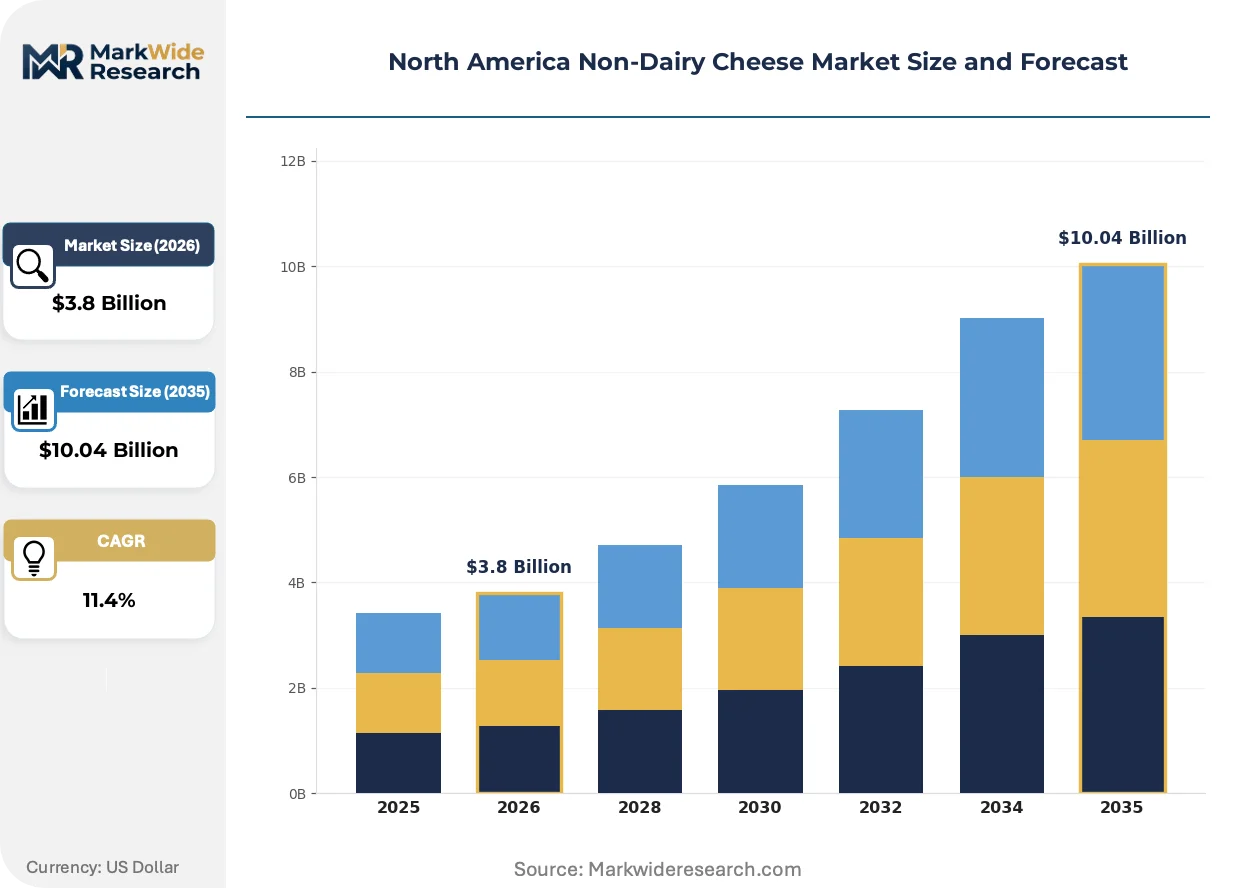
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shredded, Slices, Blocks, Cream Cheese Source: Coconut, Almond, Cashew, Soy Distribution Channel: Supermarkets, Online, Specialty Stores, Convenience Stores End User: Retail Consumers, Food Service, Food Manufacturers, Restaurants |
| Companies Covered | Miyoko's Creamery, Kite Hill, Daiya Foods, Follow Your Heart, Good Planet Foods, Tofutti Brands, GreenSpace Brands, Maple Leaf Foods, Danone SA, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Non-Dairy Cheese Market Trends and Innovations
Fermentation science and protein engineering are converging to reshape how plant-based fats replicate dairy functionality, while regulatory clarity and institutional procurement standards accelerate product-category maturation beyond early-adopter segments.
Precision fermentation is hybridizing lipid production by generating dairy-identical fat molecules without animal agriculture inputs. Quick-service restaurant chains and contract manufacturers are adopting these ingredients at pilot-scale volumes to reduce reliance on tropical oil supply chains. This convergence is compressing the performance gap between plant-based and conventional cheese in high-heat applications where melt and stretch characteristics determine purchase decisions.
The FDA's draft guidance on plant-based milk labeling establishes compositional benchmarks that extend to cheese analogs through precedent-setting enforcement patterns. Manufacturers must now fortify products to protein and calcium thresholds that match dairy equivalents or face restricted use of dairy-evocative terms. Shredded pizza cheese alternatives face the highest compliance burden given their central role in food service procurement specifications.
Bagel chains and bakery cafés are consolidating breakfast-menu procurement around single-source cream cheese alternatives that simplify inventory management. This buyer concentration is displacing fragmented specialty-distributor relationships with direct manufacturer partnerships. The shift is most visible in California and New York metropolitan clusters where plant-based breakfast penetration exceeds national averages by substantial margins.
North America Non-Dairy Cheese Market Segmentation
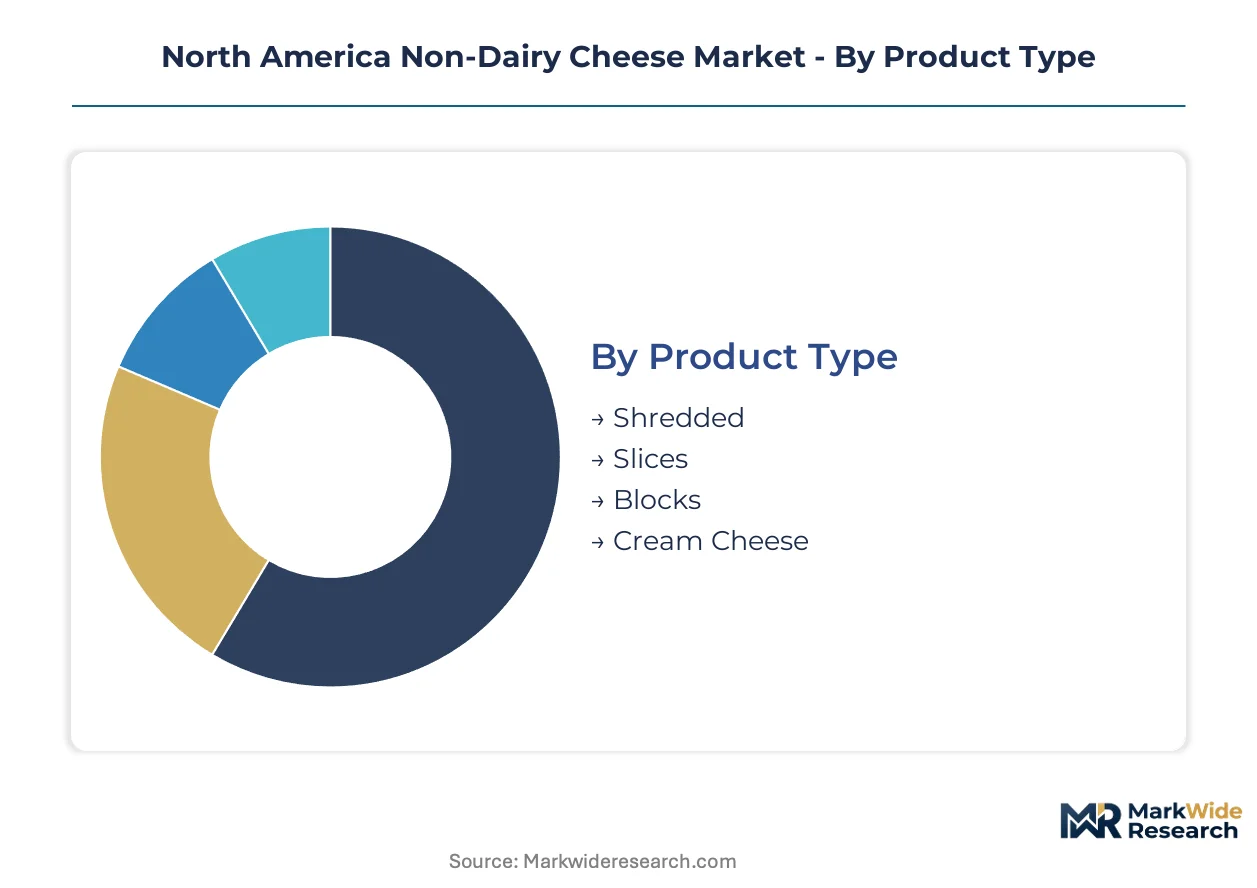
Segmentation in the North America non-dairy cheese market reveals how formulation choices, procurement channels, and end-use requirements create distinct competitive battlegrounds. Manufacturers must align R&D investments and distribution strategies with the specific technical and commercial demands of each slice.
Product Type:
Mature formats dominate food service procurement while emerging alternatives reshape breakfast and snacking occasions.
- Shredded:Optimized for melt and stretch performance in high-heat pizza applications, shredded formats command the largest procurement volumes from quick-service restaurant chains. California-based pizza chains and sandwich franchises specify these products for operational compatibility with existing assembly lines.
- Cream Cheese:Bagel chains and bakery cafés are consolidating procurement around single-source alternatives, displacing fragmented specialty-distributor relationships with direct manufacturer partnerships. New York and California metropolitan clusters show penetration rates substantially above national averages.
- Slices:Engineered for sandwich assembly with controlled moisture release and clean peel characteristics.
- Blocks:Targeting deli counters and food manufacturers requiring portion control flexibility.
Shredded retains volume leadership; cream cheese holds the steepest expansion curve.
Source:
Cost tier positioning separates commodity inputs from premium positioning strategies across the region.
- Coconut:Philippine and Indonesian coconut fat supplies drive retail velocity in conventional supermarkets through cost-competitive emulsification. Climate volatility and labor shortages in Southeast Asian growing regions create recurring input inflation pressure.
- Cashew:Vietnamese and Indian processor concentration supports premium texture profiles in specialty retail channels. Raw material price volatility and shipping lane disruptions expose margins to supply shocks.
- Almond:California's Central Valley almond orchards provide domestic sourcing for brands emphasizing local supply chains.
- Soy:Midwest soybean processing infrastructure offers the most cost-efficient protein fortification pathway for mass-market formulations.
Coconut retains volume leadership; cashew commands the premium pricing tier.
Distribution Channel:
Customer type concentration determines margin structure and brand control requirements.
- Supermarkets:Conventional grocery placement demands slotting fee negotiations and promotional calendar alignment with regional retail banners. Velocity leaders compete through broad distribution control and private-label supply relationships.
- Online:Direct-to-consumer subscriptions and third-party marketplace presence enable trial-size sampling and subscription bundling for emerging brands.
- Specialty Stores:Curated assortments favor fermentation-derived and artisan-positioned products with premium price points.
- Convenience Stores:Grab-and-go refrigerated formats target impulse purchase occasions in urban corridors.
Supermarkets retain volume leadership; online channels are climbing the fastest.
End User:
Application requirements differentiate procurement specifications across institutional and consumer-facing segments.
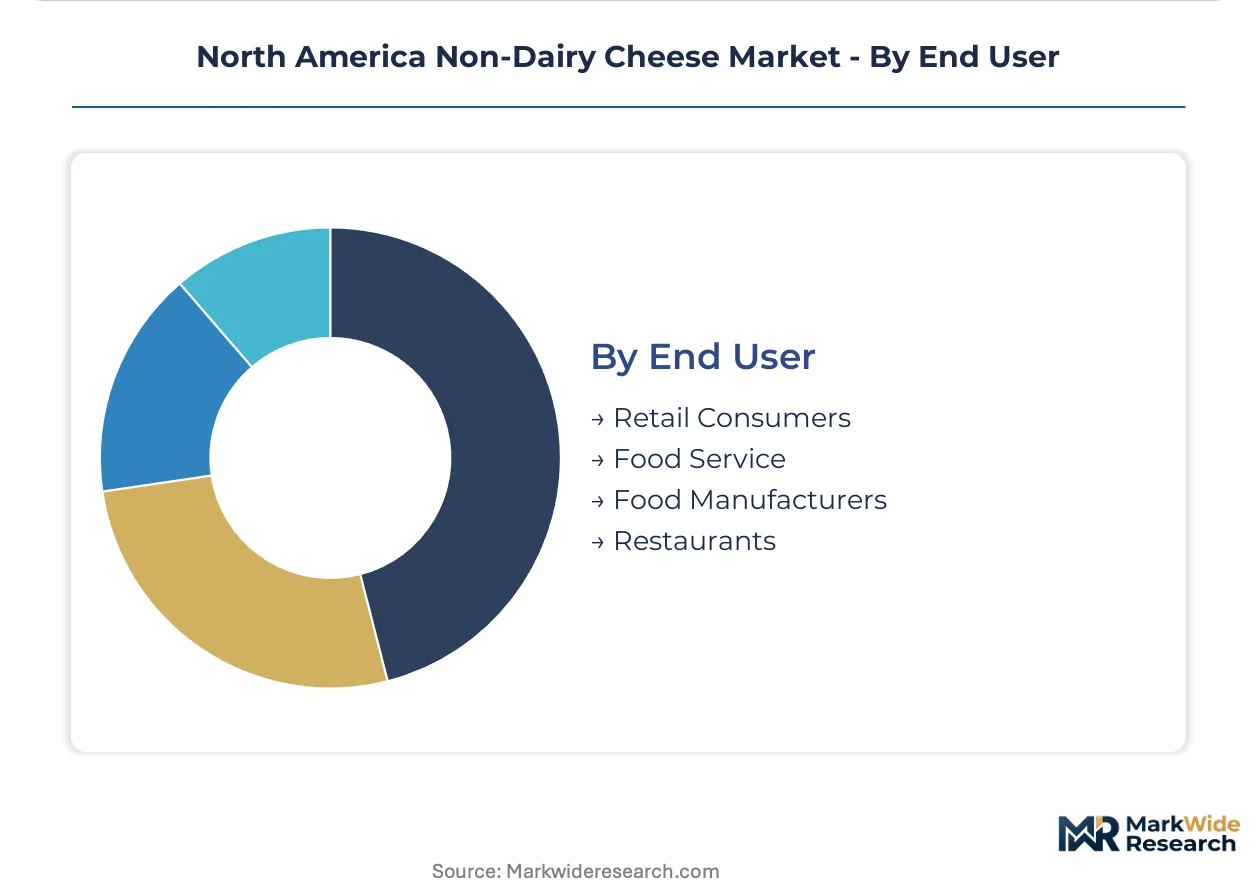
- Food Service:Quick-service restaurant chains specify melt-point consistency and shelf-life stability for multi-unit operational standardization. Permanent menu line integration creates institutional demand pull that stabilizes contract manufacturer volumes.
- Restaurants:Independent operators prioritize flavor differentiation and supplier flexibility over procurement scale.
- Food Manufacturers:Ingredient buyers require precise functional specifications for processed food and frozen meal applications.
- Retail Consumers:Household purchase decisions respond to allergen labeling clarity and protein content claims shaped by FDA guidance.
Food service retains volume leadership; restaurants show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North America runs a structural trade deficit in non-dairy cheese, with the United States importing specialty cashew-based formulations while exporting coconut-oil commodity products to Canadian and Mexican retail channels.
United States
Quick-service restaurant chains anchor procurement volumes through permanent menu line integration. The FDA's draft guidance on plant-based milk labeling forces protein fortification reformulation for cheese analogs seeking dairy-evocative terminology. California's Los Angeles-San Francisco corridor concentrates ingredient suppliers, co-packers, and R&D facilities that compress formulation-to-shelf cycle times.
Canada
Health Canada regulates analog cheese products under Food and Drug Regulations that diverge from FDA allergen disclosure standards. The country's national food regulator mandates bilingual labeling that complicates cross-border production runs for manufacturers serving both markets. Ontario and Quebec host the densest retail distribution networks for plant-based alternatives.
Mexico
Limited retail distribution and food service adoption in Mexican metropolitan areas present first-mover expansion potential. The country's consumer protection agency oversees labeling standards that remain less prescriptive than US or Canadian frameworks. Mexico City Metro and Nuevo León show nascent quick-service restaurant trial programs for plant-based cheese integration.
North America Non-Dairy Cheese Market Competitive Landscape
On the supply side, the industry is consolidating around contract manufacturing networks that favor asset-light brands over captive production facilities. Tiered competitive positioning separates fermentation-derived premium specialists from coconut-oil commodity suppliers. Two strategic archetypes dominate: technology licensors leveraging precision fat platforms, and distribution controllers securing slotting fees across conventional grocery banners. Dominant competitive moves include co-packing arrangement expansion and direct-to-bagel-chain partnership consolidation.
Within the premium fermentation tier, Miyoko's Creamery occupies a technology-forward position, while Kite Hill exemplifies almond-milk curd system specialization. Daiya Foods anchors the mass-market vector through broad retail distribution control. These three represent the dominant archetypes reshaping procurement relationships across quick-service restaurant chains and conventional supermarket channels.
| Leading Market Players |
|---|
| Miyoko's Creamery |
| Kite Hill |
| Daiya Foods |
| Follow Your Heart |
| Good Planet Foods |
| Tofutti Brands |
| GreenSpace Brands |
| Maple Leaf Foods |
| Danone SA |
| Others |
Pricing and Supply Chain Analysis
Cashew supply concentration in Vietnamese and Indian processing corridors determines both the premium-to-commodity pricing spread and the geographic shape of contract manufacturing networks across North America. Manufacturers hedge raw material volatility through coconut oil substitution in mass-market tiers while fermentation-derived fats command price premiums that decouple from tropical commodity cycles.
Pricing Analysis
Quick-service restaurant procurement teams anchor three-tier pricing structure across premium, standard, and economy levels. Price differentiation separates fermentation-derived specialty positioning from coconut-based retail velocity leaders and soy-fortified institutional formulations. Pricing pressure stems from FDA protein fortification compliance costs that compress margins in shredded pizza cheese alternatives. Food service buyers exhibit lowest price sensitivity due to operational standardization requirements, while retail consumers respond aggressively to promotional calendar shifts.
Supply Chain Analysis
Co-packing networks in California's Los Angeles-San Francisco corridor hold dominant contract manufacturing capacity for regional brands lacking captive production. Raw material sourcing draws from Philippine and Indonesian coconut fat suppliers, Vietnamese and Indian cashew processors, and California Central Valley almond orchards. Single-source vulnerability concentrates in Southeast Asian tropical oil supply chains exposed to climate volatility and labor shortages. Distribution runs through conventional grocery slotting fee negotiations, direct-to-bagel-chain partnerships, and food service contract manufacturer arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation breakthroughs and FDA labeling guidance convergence create a high-growth disruption window. Regulatory clarity on protein content claims and dairy-evocative terminology accelerates category maturation beyond early-adopter segments.
For Market Incumbents: Insulate premium positioning by deepening captive fermentation capacity and securing exclusive lipid technology licensing. Accelerate backward integration into California-based R&D corridors to compress formulation-to-shelf cycle times. Defend against commodity tier erosion by locking multi-year co-packing arrangements with quick-service restaurant chains.
For New Entrants and Emerging Players: Pursue Mexico metropolitan whitespace where retail distribution and food service adoption remain underpenetrated relative to US benchmarks. Target cream cheese alternative partnerships with bagel chains in New York and California clusters where plant-based breakfast penetration exceeds national levels. Anchor go-to-market strategy through Spanish-language packaging capabilities and direct manufacturer relationships displacing fragmented specialty-distributor networks.
For Investors and Strategic Acquirers: FDA draft guidance finalization reshapes the acquisition landscape by elevating compliance infrastructure value. Five-to-ten year viability favors fermentation technology licensors with commercial-scale biochemical engineering expertise over commodity coconut-oil suppliers. Target acquisition archetype: asset-light brands with proven quick-service restaurant procurement relationships and scalable co-packing networks. Signal to monitor: USDA Child Nutrition Program eligibility approvals opening institutional procurement channels.
| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Technology Licensing | Precision fat platforms reduce tropical oil dependency and expand allergen-free addressable segments. |
| Quick-Service Restaurant Partnership Consolidation | Direct manufacturer relationships displace fragmented distributors and stabilize procurement volumes. |
| USDA School Nutrition Program Certification | Protein and calcium standard compliance opens multi-year institutional contract channels. |
| Mexico Market Entry | First-mover Spanish-language packaging capabilities capture underpenetrated metropolitan retail and food service. |
| Co-Packing Network Expansion | Asset-light contract manufacturing tilts competitive dynamics toward brands without captive facilities. |
Research Methodology
Initial hypotheses were tested against primary input from food service procurement directors, contract manufacturing executives, fermentation technology R&D leads, and retail category buyers and refined through secondary validation. Primary fieldwork combined structured interviews with quick-service restaurant supply chain managers and almond processor operations heads. Secondary sources included FDA guidance documents, Health Canada Food and Drug Regulations, USDA Child Nutrition Program specifications, and Nielsen retail velocity data. Bottom-up segment sizing and top-down macroeconomic triangulation anchored volume and value estimates.
Demand-supply balance modeling across the analysis window integrated quick-service restaurant menu integration trajectories, fermentation capacity buildout pipelines, and raw material price volatility scenarios. Segmentation dimensions spanned product type, source material, distribution channel, and end-user application with regional regulatory cluster overlays. CAGRs derived from weighted average of historical velocity trends and forward-looking procurement contract visibility. Industry-specific inputs included California food manufacturing corridor concentration metrics and cross-border formulation standardization compliance costs.
Sensitivities concentrate around FDA final guidance timing, cashew supply chain disruption severity, and fermentation scientist talent pipeline constraints. Forecasts reflect documented assumptions on protein fortification cost pass-through rates and quick-service restaurant adoption curves. Quarterly review of USDA school nutrition program eligibility approvals, Health Canada labeling enforcement patterns, and Philippine coconut harvest yield indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Asia-Pacific Walnut Milk Market
Dairy Alternatives
Plant-Based Cheese Wedges Market
Dairy Alternatives
Australia Dairy Alternatives Market
Dairy Alternatives
Lactose-Free Milk Market
Dairy Alternatives
Vegan Ice Cream Market
Dairy Alternatives
Global Vegan Sour Cream Market
Dairy Alternatives
Clarified Butter Market
Dairy Alternatives
Chickpea Milk Market
Dairy Alternatives
Cheese Alternative Market
Dairy Alternatives
Dairy Alternatives Market
Dairy Alternatives
Banana Milk Market
Dairy Alternatives
Coconut Milk Powder Market
Dairy Alternatives
Walnut Milk Market
Dairy Alternatives
Plant Milk Market
Dairy Alternatives
North America Dairy Alternative Market
Dairy Alternatives
United States Non-Dairy Milk Market