
 Organic Yogurt Market | 2026-2036
Organic Yogurt Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Yogurt Market Outlook
Premium grass-fed certification is rotating toward the center of organic yogurt positioning. Danone leverages its global dairy infrastructure to secure consistent organic milk supply across multiple continents. Stonyfield Farm sustains its competitive edge through deep supplier partnerships with Northeast U.S. organic dairy cooperatives. Organic Valley anchors its market presence through farmer-owned cooperative governance that guarantees supply transparency from pasture to cup.
Organic yogurt is a fermented dairy product manufactured from milk sourced from livestock raised under certified organic protocols prohibiting synthetic hormones, antibiotics, and pesticides, with live bacterial cultures including Lactobacillus bulgaricus and Streptococcus thermophilus converting lactose to lactic acid to produce its characteristic texture and tangy flavor profile. The product serves commercial and retail channels as a protein-dense, probiotic-functional food supporting digestive health claims. Greek yogurt within the product type dimension commands disproportionate shelf space and margin contribution due to its strained, higher-protein format that justifies price premiums over plain and drinkable alternatives. Household end users dominate volume throughput, while health food stores and online retail distribution channels capture the fastest velocity among shoppers prioritizing subscription-based replenishment and specialty diet alignment.
USDA Organic certification governs U.S. market access, requiring 95% organic ingredients and prohibiting synthetic additives, while EU Organic Regulation enforces equivalent standards across European supply chains with mandatory on-farm inspections. FDA oversight of live and active culture labeling shapes how brands communicate probiotic counts to health-conscious consumers. Stakeholders must monitor evolving pasture-access requirements and animal-welfare add-on certifications that threaten to fragment compliance costs across otherwise unified organic standards.
Market Dynamics
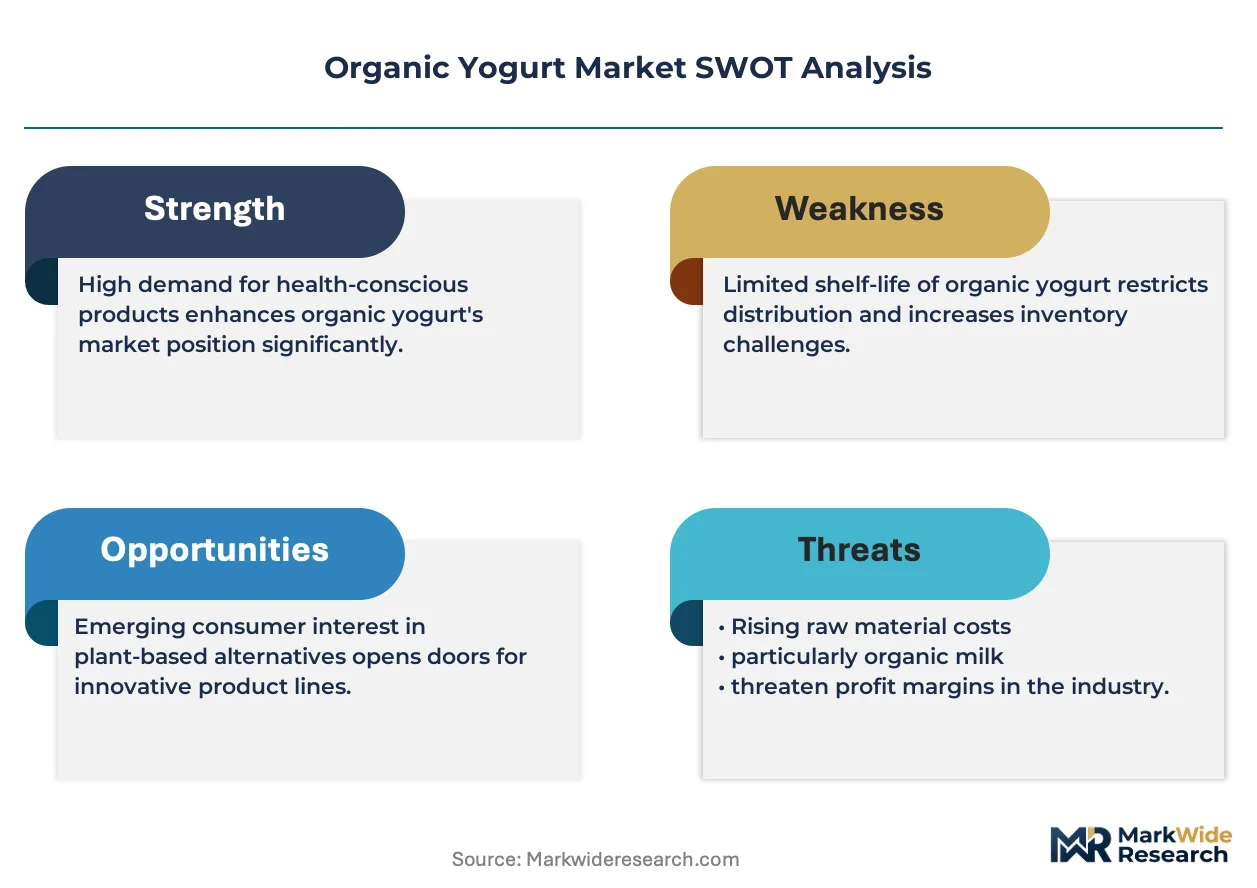
Pasture-access mandates and animal-welfare add-on certifications are fragmenting compliance costs across organic yogurt supply chains, forcing processors to navigate divergent national standards while maintaining unified product positioning.
Growth Catalysts
- EU Organic Regulation enforcement:Mandatory on-farm inspections and 95% organic ingredient requirements across member states are standardizing quality benchmarks that reduce consumer skepticism and expand retail shelf access for certified producers.
- Probiotic functional claims:FDA oversight of live and active culture labeling is legitimating digestive health positioning, enabling brands to command price premiums in health food stores and subscription channels.
- Greek yogurt format adoption:Higher-protein strained varieties are capturing disproportionate refrigerated aisle space in US and German retail, justifying margin expansion over plain and drinkable alternatives.
Market Restraints
- Organic feed cost volatility:Corn and soybean price swings directly compress dairy cooperative margins, with pasture-based operations in the US Northeast and Bavaria facing acute input inflation during drought cycles.
- Milk supply concentration:Northeast US organic dairy cooperatives and Alpine pasture collectives control disproportionate raw material flows, creating procurement bottlenecks when weather or disease disrupts regional output.
- Plant-based substitution threat:Oat and coconut yogurt alternatives are capturing breakfast-staple occasions among lactose-intolerant and flexitarian households, eroding addressable market for traditional dairy-based organic lines.
Strategic Opportunities
- Grass-fed certification tiering:Premium positioning around 100% pasture-raised protocols is creating white space above baseline organic, with Danish and Irish producers pioneering seasonal grazing transparency programs.
- Subscription channel expansion:Direct-to-consumer replenishment models are bypassing conventional retail slotting fees, enabling smaller cooperatives to build recurring revenue with diet-aligned households in metropolitan clusters.
- EU Green Deal alignment:Carbon-neutral dairy production incentives are subsidizing methane-reduction investments and renewable energy adoption at farm level, lowering compliance costs for early-adopting processors.
Industry Challenges
- Microbiologist talent scarcity:Live culture strain optimization and shelf-stability engineering require specialized fermentation expertise that outpaces agricultural university output in organic-specialized regions.
- Multi-certification complexity:Simultaneous USDA Organic, EU Organic, and emerging animal-welfare label maintenance demands redundant audit trails and documentation systems that strain mid-sized cooperative administrative capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Yogurt Market |
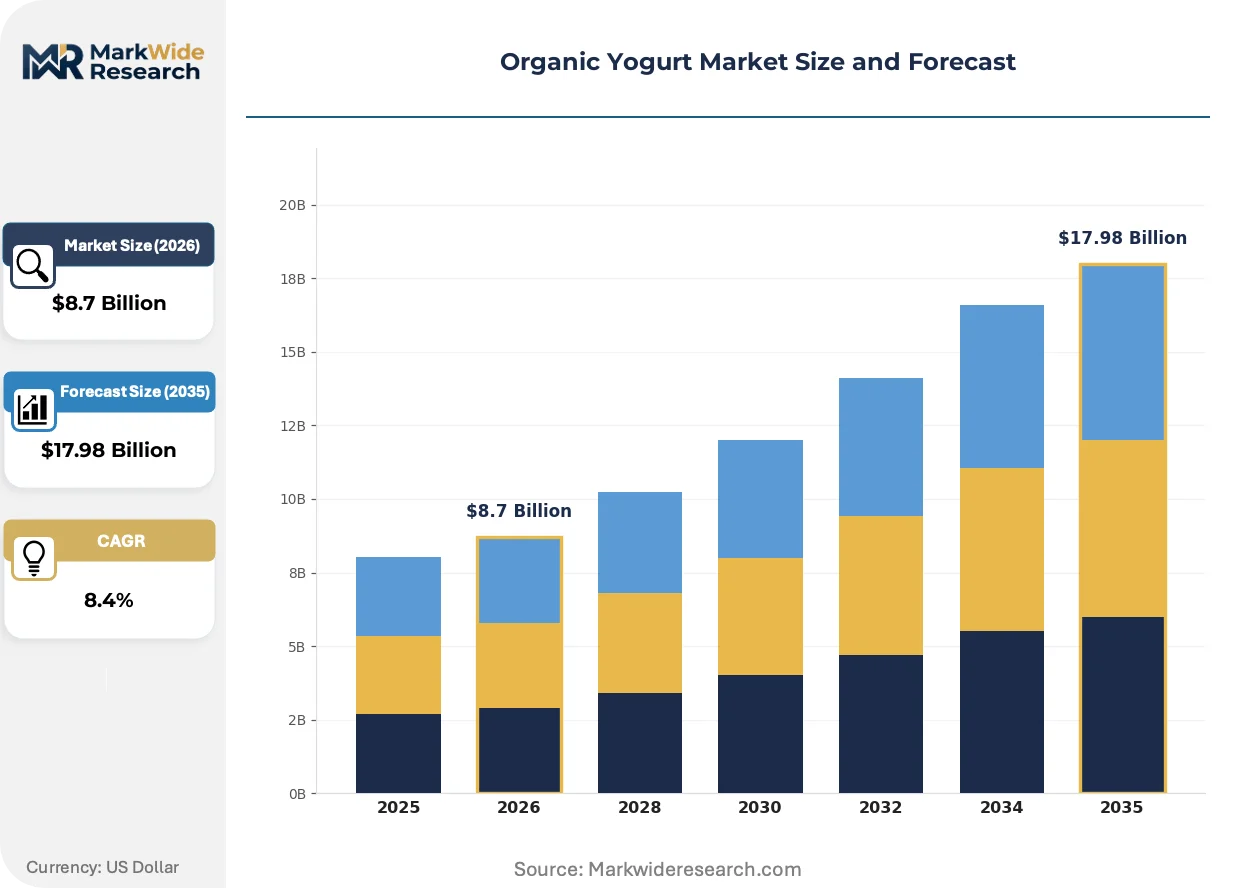
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plain, Flavored, Greek, Drinkable End User: Households, Restaurants, Retailers, Fitness Centers Packaging Type: Cups, Pouches, Jars, Tubs Distribution Channel: Supermarkets, Health Food Stores, Online Retail, Convenience Stores |
| Companies Covered | Danone, Stonyfield Farm, Nestlé, Organic Valley, Arla Foods, FAGE, Horizon Organic, Maple Hill Creamery, Aurora Organic Dairy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Yogurt Market Strategic Shifts
Precision fermentation and culture-banking technologies are rewriting how organic yogurt producers secure strain consistency and supply chain resilience, compressing traditional reliance on heritage starter repositories.
Aseptic processing with extended-shelf-life packaging is supplanting conventional cold-chain dependence for ambient-stable organic yogurt formats. German and Japanese retail buyers are adopting these lines for convenience-store and workplace distribution channels where refrigeration infrastructure remains limited. This technology is enabling geographic expansion into Southeast Asian and Middle Eastern markets previously inaccessible to perishable dairy exports.
EU Green Deal methane-reduction mandates are forcing organic dairy cooperatives to invest in anaerobic digesters and feed additives that suppress enteric emissions. French and Dutch regulators are piloting farm-level carbon accounting protocols that will soon determine subsidy eligibility and export certification status. Greek-style yogurt producers with concentrated manufacturing footprints face disproportionate compliance timelines due to higher milk throughput per unit output.
Subscription-based replenishment is consolidating household purchasing into predictable monthly cycles that bypass conventional retail velocity metrics. Health food stores and direct-to-consumer platforms are capturing these shoppers through algorithmic flavor rotation and probiotic strain customization. This pattern is most visible in urban US coastal markets and London metropolitan zones where time-constrained professionals prioritize automated restocking over aisle browsing.
Organic Yogurt Market Segmentation
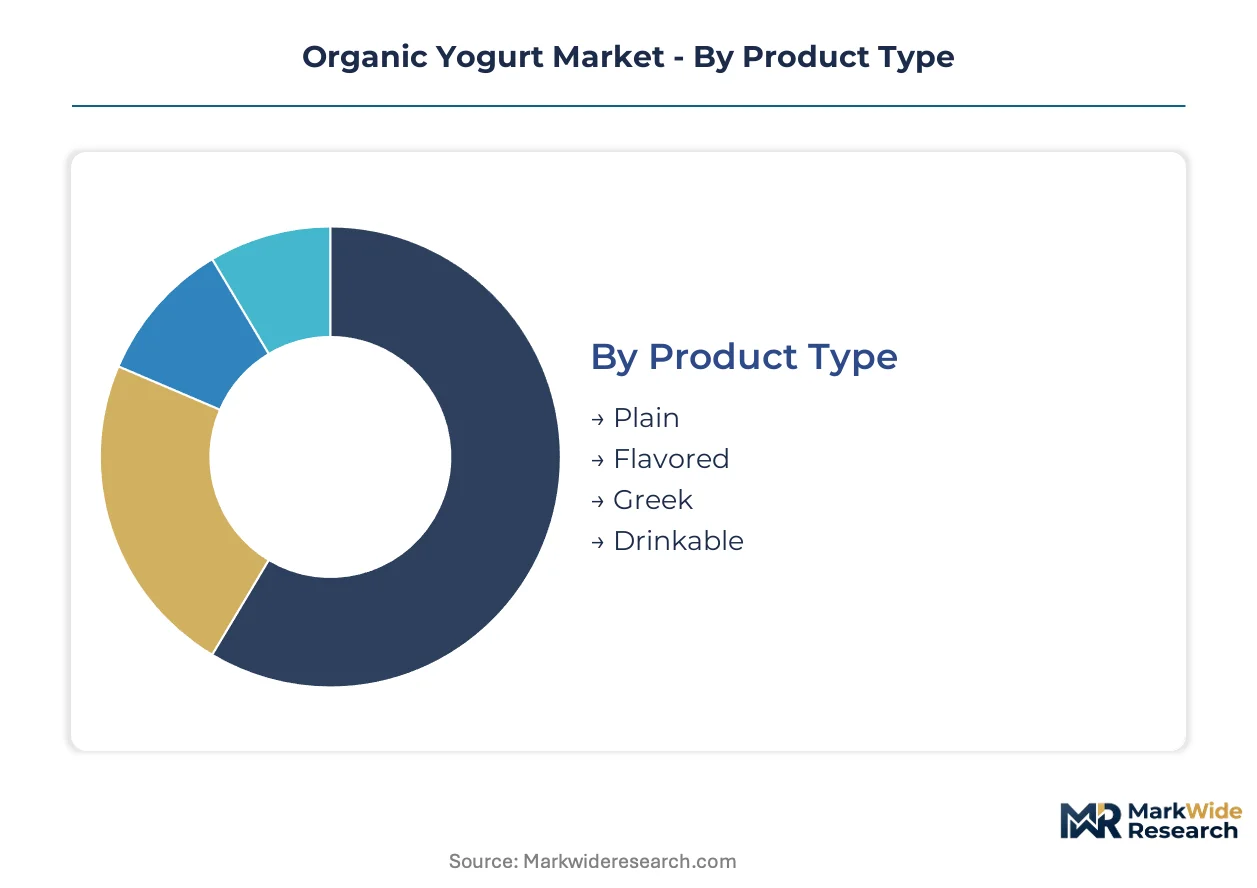
Organic yogurt segmentation reveals divergent growth vectors across consumption occasions and channel economics. Product format and packaging choices determine cold-chain requirements, shelf-life constraints, and margin structures that reshape competitive positioning.
Product Type:
Greek yogurt concentrates manufacturing investment in the US Northeast and Bavaria, while drinkable formats drive export-led expansion into Southeast Asian convenience channels.
- Plain:Unstrained traditional fermentation yields lower protein density but broader recipe versatility for cooking and baking applications. German household consumers anchor baseline demand through breakfast staple repetition, though price compression limits margin expansion.
- Greek:Strained processing removes whey to concentrate protein content above 10 grams per serving. US refrigerated aisles allocate disproportionate shelf space to this format, with USDA Organic certification commanding price premiums over conventional alternatives.
- Flavored:Fruit-infused and vanilla varieties target children's lunchbox occasions and post-workout recovery moments. Clean-label demands restrict artificial sweetener use, compressing formulation flexibility.
- Drinkable:Beverage-format yogurt with extended portability for on-the-go consumption. Japanese and South Korean retail buyers are piloting ambient-stable aseptic lines for workplace vending distribution.
Plain yogurt commands the established base. The steepest expansion runs through Greek formats.
End User:
Cost tier stratification separates premium subscription households from price-sensitive foodservice procurement.
- Households:Primary volume engine across all geographies, with probiotic health claims driving repeat purchase loyalty. Subscription-based replenishment is consolidating purchasing into predictable monthly cycles in London and coastal US metropolitan zones.
- Restaurants:Foodservice procurement prioritizes bulk tubs for recipe ingredient use and breakfast buffet presentation. Greek yogurt's thicker texture supports plating stability for savory applications.
- Retailers:Private-label organic yogurt programs at German discounters and US supermarket chains are capturing price-sensitive shoppers through simplified flavor ranges.
- Fitness Centers:Post-workout protein recovery positioning targets gym-based vending and café partnerships. Higher-protein Greek formats align with macronutrient tracking consumer behavior.
Households absorb the volume concentration. Fitness centers are climbing the fastest as wellness positioning deepens.
Packaging Type:
Material choice directly determines recycling compliance costs under EU Packaging and Packaging Waste Regulation and emerging US state extended producer responsibility laws.
- Cups:Single-serve polypropylene containers dominate US and European refrigerated dairy cases. German retailers are mandating minimum recycled content thresholds that reshape supplier qualification.
- Tubs:Multi-serve formats reduce per-ounce packaging cost for family households and foodservice accounts. Wider mouth diameters support spoon-accessible Greek yogurt consumption.
- Pouches:Flexible packaging for children's portable snacking occasions. Japanese convenience stores are expanding shelf space for resealable drinkable yogurt pouches.
- Jars:Premium glass packaging supports artisan positioning and reuse programs at health food stores. Higher freight costs limit geographic distribution radius.
Cups hold the volume base. Pouches are gaining share fastest through convenience-channel expansion.
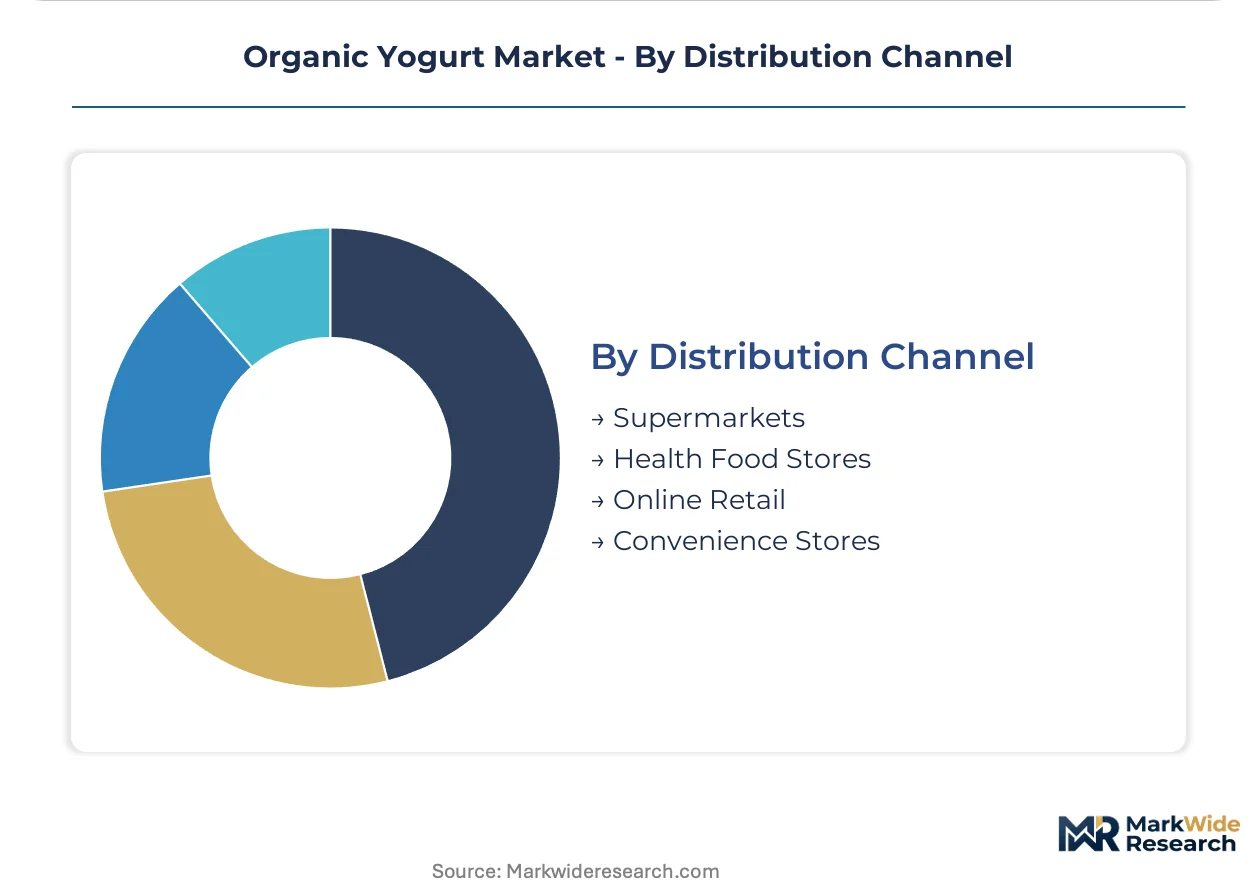
Distribution Channel:
Channel selection fragments between high-velocity supermarket slotting and direct-to-consumer margin retention.
- Supermarkets:Dominant volume channel requiring substantial slotting fee investment and promotional discounting. US Northeast and German retail chains are consolidating shelf space behind fewer certified organic SKUs.
- Online Retail:Subscription algorithms enable probiotic strain customization and flavor rotation for diet-aligned households. Cold-chain logistics costs constrain geographic reach beyond metropolitan clusters.
- Health Food Stores:Specialty retail captures premium pricing through staff education and local supplier storytelling. Smaller cooperatives bypass conventional slotting economics here.
- Convenience Stores:Ambient-stable aseptic formats are unlocking this channel for drinkable yogurt in Southeast Asian and Middle Eastern markets where refrigeration infrastructure remains limited.
Supermarkets anchor the established volume. Online retail is expanding most quickly through subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Organic milk procurement clusters tightly in the US Northeast and Alpine Europe, with processing capacity following pasture availability and cooperative infrastructure. Germany and the United States absorb the dominant consumption share, while export-oriented production concentrates in Denmark and France.
United States
Household probiotic demand and Greek yogurt format preference drive refrigerated aisle expansion. USDA Organic certification governs interstate commerce with mandatory pasture-access documentation. Northeast dairy cooperatives around Vermont and New York anchor supply, with Stonyfield Farm exemplifying cooperative-to-processor integration.
Germany
Breakfast-staple consumption and discounter private-label programs sustain volume throughput. EU Organic Regulation enforces 95% organic ingredient thresholds with mandatory on-farm inspections. Bavarian pasture collectives and Alpine cooperatives concentrate raw milk flows, with Munich and Frankfurt retail clusters driving premium positioning.
France
Artisan positioning and glass-jar premium formats support health food store penetration. ANSM and DGCCRF oversee labeling compliance alongside EU Organic standards. Brittany and Normandy dairy basins supply strained yogurt processors, with Paris metropolitan subscription channels expanding fastest.
Denmark
Grass-fed certification tiering and seasonal grazing transparency programs pioneer premium segmentation. EU Green Deal methane-reduction subsidies accelerate anaerobic digester adoption at farm level. Arla Foods anchors cooperative processing in Aarhus and Copenhagen corridors, with export capacity targeting German and UK retail.
Japan
Drinkable format adoption and workplace vending distribution reshape consumption occasions. METI standards and FSSC 22000 certification govern import eligibility for organic dairy. Tokyo and Osaka convenience store chains pilot ambient-stable aseptic lines, with Hokkaido dairy cooperatives supplying strained yogurt ingredients.
Organic Yogurt Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Global dairy conglomerates leverage multi-continent milk sourcing infrastructure against regional cooperatives that optimize for traceability and local pasture narratives. Three archetypes dominate: multinational scale players with integrated supply chains, farmer-owned cooperatives with governance transparency, and specialty artisans with certification stacking. M&A activity concentrates among scale players acquiring regional organic brands, while cooperative partnerships deepen backward integration into captive milk supply.
Within the multinational tier, Danone and Nestlé occupy positions defined by cross-border organic milk procurement and refrigerated distribution infrastructure. Among cooperative structures, Organic Valley and Stonyfield Farm exemplify farmer-owned governance models that guarantee supply transparency. Arla Foods sits at the intersection of cooperative ownership and export-scale processing capacity, anchoring European supply into Asian convenience channels.
| Leading Market Players |
|---|
| Danone |
| Stonyfield Farm |
| Nestlé |
| Organic Valley |
| Arla Foods |
| FAGE |
| Horizon Organic |
| Maple Hill Creamery |
| Aurora Organic Dairy |
| Others |
Value Chain & Pricing Dynamics
USDA Organic certification gates both supply qualification and price differentiation simultaneously, requiring processors to absorb compliance costs that stratify final shelf pricing while locking out uncertified competitors from premium refrigerated placement.
Pricing Analysis
USDA Organic and EU Organic Regulation dictate the pricing tier structure across conventional, certified organic, and grass-fed premium tiers. Price differentiation rests on certification grade and pasture-access transparency, with Danish and Irish producers commanding premiums through seasonal grazing documentation. Cost compression in baseline organic tiers is intensifying because corn and soybean feed price volatility squeezes cooperative margins. Discounter private-label programs in Germany capture the most price-sensitive households, while subscription-based direct-to-consumer channels in London and coastal US metros show the least sensitivity.
Supply Chain Analysis
Just-in-time cold-chain logistics dominate perishable Greek yogurt distribution, while strategic stockpiling of ambient-stable aseptic formats enables Southeast Asian market entry. Raw milk supply concentrates in the United States, Germany, and Denmark, with Northeast dairy cooperatives and Bavarian pasture collectives anchoring procurement. Production draws from organic corn, soybean meal, and heritage starter cultures. Single-source vulnerability runs through concentrated cooperative milk supply in the US Northeast and Alpine Europe. Distribution runs through refrigerated supermarket chains, direct-to-consumer subscription platforms, and ambient convenience channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certification fragmentation is creating white-space niches for specialized players, as divergent pasture-access mandates and animal-welfare add-ons splinter what was once a unified organic standard.
For Market Incumbents: Fortify backward integration into captive organic milk supply through cooperative equity stakes in Vermont and Bavaria. Deepen strain-banking capabilities to reduce dependence on external microbiologist talent. Oat and coconut yogurt substitution threatens breakfast-staple volumes; defend through probiotic strain differentiation and grass-fed certification tiering above plant-based alternatives. For New Entrants and Emerging Players: EU Organic Regulation fast-track certification enables entry into German discounter private-label programs with simplified flavor ranges. Target fitness center vending partnerships in metropolitan US zones with higher-protein Greek formats. Exploit underpenetrated ambient-stable aseptic distribution in Japanese and South Korean convenience channels. Lead with algorithmic subscription replenishment to bypass conventional retail slotting economics. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across precision fermentation and extended-shelf-life packaging sub-segments. Long-term viability favors processor-acquirer targets with cooperative milk supply agreements and multi-certification administrative capacity. Watch for EU Green Deal methane-reduction subsidy thresholds as inflection signal for farm-level compliance cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Grass-Fed Certification Tiering | Danish seasonal grazing transparency programs justify price premiums above baseline organic tiers. |
| Subscription Channel Expansion | Direct-to-consumer algorithms bypass supermarket slotting fees for metropolitan household clusters. |
| Anaerobic Digester Investment | EU Green Deal subsidies lower methane compliance costs for early-adopting French and Dutch cooperatives. |
| Aseptic Processing Adoption | Ambient-stable formats unlock Middle Eastern and Southeast Asian markets lacking refrigeration infrastructure. |
| Strain-Banking Technology | Precision fermentation secures starter culture consistency against microbiologist talent scarcity. |
Study Parameters
The analysis maps product type, end user, packaging format, and distribution channel segments, each validated through cooperative procurement managers, retail category buyers, fermentation technology specialists, and organic certification auditors. Primary interview findings triangulate against secondary sources including USDA National Organic Program filings, EU Organic Regulation enforcement reports, FDA live and active culture labeling guidance, and refrigerated dairy case velocity data. Bottom-up volume modeling and top-down value estimation cross-validate through the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions include product format, certification tier, end-use occasion, packaging material, and channel economics. CAGRs derive from historical trajectory analysis adjusted for regulatory enforcement timing and technology adoption curves. Forecast inputs incorporate organic feed cost indices and pasture-access compliance timeline assumptions.
Decision-makers should treat outputs as directional under stable certification regime enforcement and cooperative supply concentration assumptions; material deviation would warrant model refresh. Revision becomes warranted when EU Green Deal methane-reduction subsidy thresholds or FDA labeling guidance crosses implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Food and Beverages
Global Organic Chocolate Spreads Market
Organic Food and Beverages
Brazil Organic Food Market
Organic Food and Beverages
Global Organic Soup Market
Organic Food and Beverages
Italy Organic Food Market
Organic Food and Beverages
Organic Soy Products Market
Organic Food and Beverages
Europe Organic Food and Beverages Market
Organic Food and Beverages
Organic Acai Juice Market
Organic Food and Beverages
Organic Yeast Market
Organic Food and Beverages
Global Natural and Organic Food Market
Organic Food and Beverages
Saudi Arabia Organic Food Market
Organic Food and Beverages
Organic Pasta Market
Organic Food and Beverages
Europe Organic Food Market
Organic Food and Beverages
Germany Organic Food Market
Organic Food and Beverages
United States Organic Skin Care Market
Organic Food and Beverages
Australia Organic Food Market
Organic Food and Beverages
Global Organic Coconut Water Market