
 Dry Shampoo Market | 2026-2036
Dry Shampoo Market Size, Share, and Industry Trends Forecast 2026-2036
Dry Shampoo Market Intelligence
The growing influence of retail consumers over professional stylists is rebalancing the dry shampoo market's channel strategy. This shift favors large consumer-packaged goods companies with broad distribution capabilities. L'Oréal S.A. leverages its extensive brand portfolio to capture both salon and retail segments. Unilever plc sustains its market position through strong penetration in supermarkets and hypermarkets, while Procter & Gamble competes via product formulation innovations and marketing scale.
Dry shampoo is a waterless hair care product designed to absorb excess sebum and oils from the scalp and hair. Formulations typically rely on an absorbent starch or mineral base, such as corn or rice starch, delivered as an aerosol spray or a loose powder. Aerosol spray formats dominate the product type segment due to their ease of application, though powder forms are gaining traction among consumers seeking non-propellant options. Products specifically formulated for oily hair represent the largest application segment, directly addressing the core functional purpose of the category.
Product formulation and marketing are shaped by stringent cosmetic regulations globally. Compliance with the US FDA’s guidelines on aerosol contaminants, the EU’s Cosmetics Regulation (EC) No 1223/2009 for ingredient safety, and China’s NMPA pre-market approval processes is mandatory for market access. Navigating the evolving consumer preference for 'clean' ingredients and sustainable, non-aerosol formats will define future competitive success.
Market Dynamics
The central dynamic shaping the dry shampoo market is the conflict between consumer demand for convenient, water-free cleansing and heightened regulatory scrutiny over aerosol propellant safety, particularly concerning benzene contamination, which is forcing a fundamental re-evaluation of product formulations.
Growth Catalysts
- Urbanization in Asia:The adoption of fast-paced lifestyles in major Chinese and Indian urban centers creates sustained demand for time-saving personal care products, including dry shampoo.
- Ingredient Innovation:The commercialization of highly absorbent, plant-based starches such as rice and tapioca provides a 'clean label' alternative to talc, appealing to ingredient-conscious consumers.
- E-commerce Channel Expansion:The growth of direct-to-consumer and third-party online retail platforms provides a low-cost route to market for niche and emerging brands, bypassing traditional retail gatekeepers.
Market Restraints
- Regulatory Scrutiny:The US FDA's focus on carcinogenic contaminants like benzene in aerosol products creates significant compliance burdens, potential for product recalls, and negative consumer perception.
- Product Performance Limitations:A persistent challenge for many formulations is the creation of a visible white or gray residue, particularly on darker hair shades, which limits user satisfaction and repeat purchases.
- Threat of Substitution:Traditional hair washing remains the primary cleansing method, while other styling products like texturizing sprays or mousses can offer overlapping benefits, competing for consumer spend.
Strategic Opportunities
- Targeted Formulations:Development of products for specific hair concerns beyond oiliness, such as color-safe formulas, volumizing agents for fine hair, or scalp-soothing ingredients, opens new application segments.
- Non-Aerosol Formats:Growing consumer and regulatory aversion to aerosols creates a significant market opportunity for innovative powder-based formats, including loose powders with brushes and non-aerosol pump sprays.
- Geographic Expansion:Market development in regions with high hair care expenditure but low dry shampoo penetration, such as Brazil and Mexico, presents a substantial growth frontier for established brands.
Industry Challenges
- Packaging Reconfiguration:The pivot from standard aerosol cans to alternative delivery systems like pump sprays or powder dispensers requires significant investment in new manufacturing lines and supply chain adjustments.
- Consumer Education on Usage:Brands face the ongoing challenge of educating consumers on proper application techniques to maximize efficacy and avoid common issues like residue, which is critical for customer retention.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dry Shampoo Market |
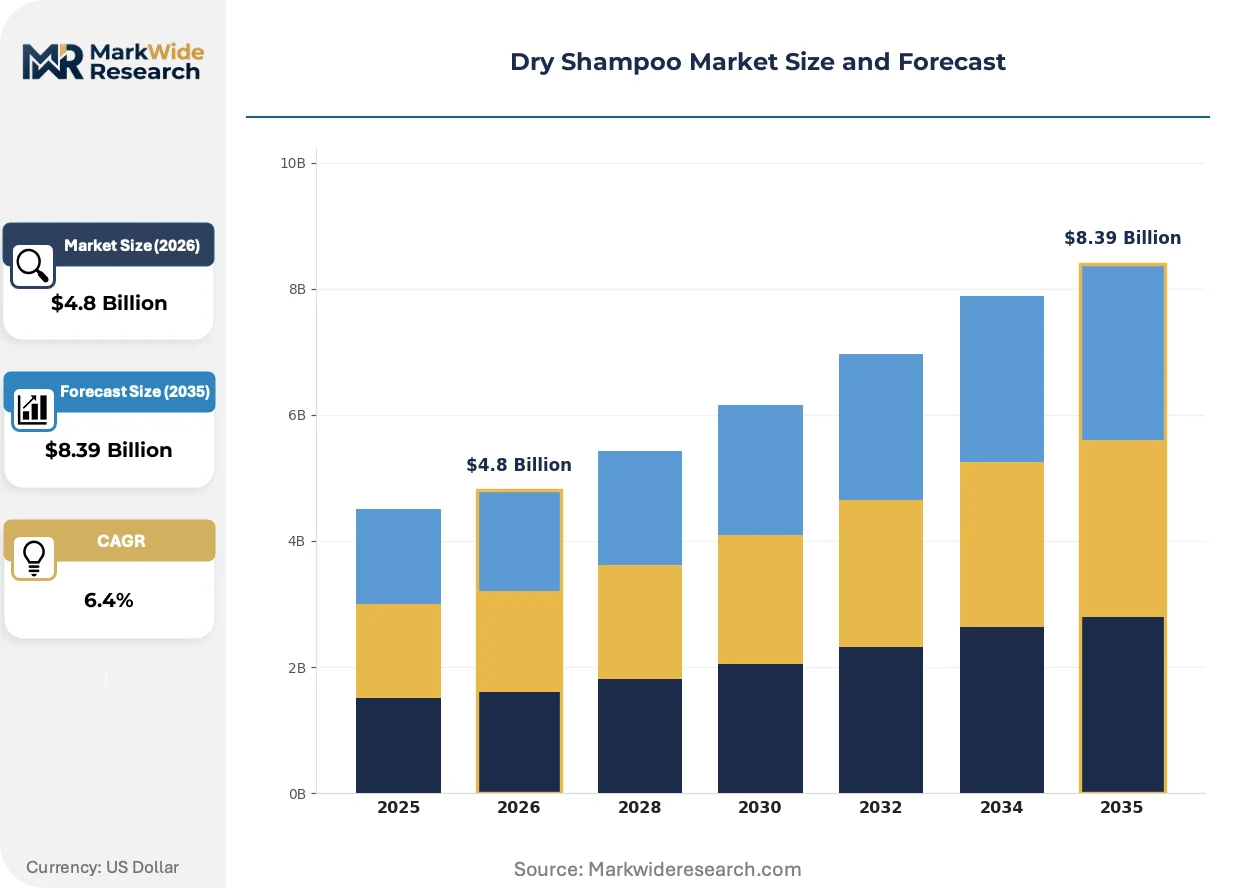
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aerosol Spray, Powder, Foam, Cream, Gel Application: Oily Hair, Normal Hair, Curly Hair, Thin Hair, Colored Hair End User: Salons, Personal Care, Professional Stylists, Retail Consumers Distribution Channel: Pharmacies, Supermarkets & Hypermarkets, Specialty Stores, Online Retail, Independent Retailers |
| Companies Covered | Kao Corporation, Henkel AG & Co. KGaA, Unilever plc, Coty Inc., Shiseido Company, Limited, Procter & Gamble, Church & Dwight Co., Inc., Estée Lauder Companies Inc., L'Oréal S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dry Shampoo Market Strategic Shifts & Innovations
Formulation science is evolving rapidly to meet dual demands for improved performance and 'clean' ingredient profiles. This shift is driven by consumer advocacy and stricter regulatory frameworks, pushing innovation away from traditional aerosol propellants and toward sustainable, multi-functional products.
Advanced plant-based starches, including rice, tapioca, and arrowroot powder, are replacing minerals as the primary absorbent agents in new formulations. Consumers focused on ingredient transparency and safety are driving the adoption of these natural alternatives. This ingredient evolution is integrating scalp-care benefits, such as soothing botanicals, directly into the product's primary oil-absorbing function, creating a hybrid cosmetic-treatment category.
The European Union's Cosmetics Regulation (EC) No 1223/2009 sets a high bar for ingredient safety and product claims, influencing global formulation standards. This framework mandates rigorous safety assessments and transparent labeling, which increases development timelines and compliance overhead for manufacturers. Products utilizing aerosol propellants face the most intense scrutiny, accelerating the industry's research into alternative delivery systems to ensure market access within the EU.
A distinct consumer preference for product specialization is disrupting the traditional one-size-fits-all market approach. The search for customized solutions now drives purchasing behavior, with consumers seeking products formulated for specific hair colors, textures, or added benefits like UV protection. This demand-side shift is most visible within the direct-to-consumer e-commerce channel in North America, where digital marketing enables niche brands to connect with highly specific user segments.
Dry Shampoo Market Segmentation
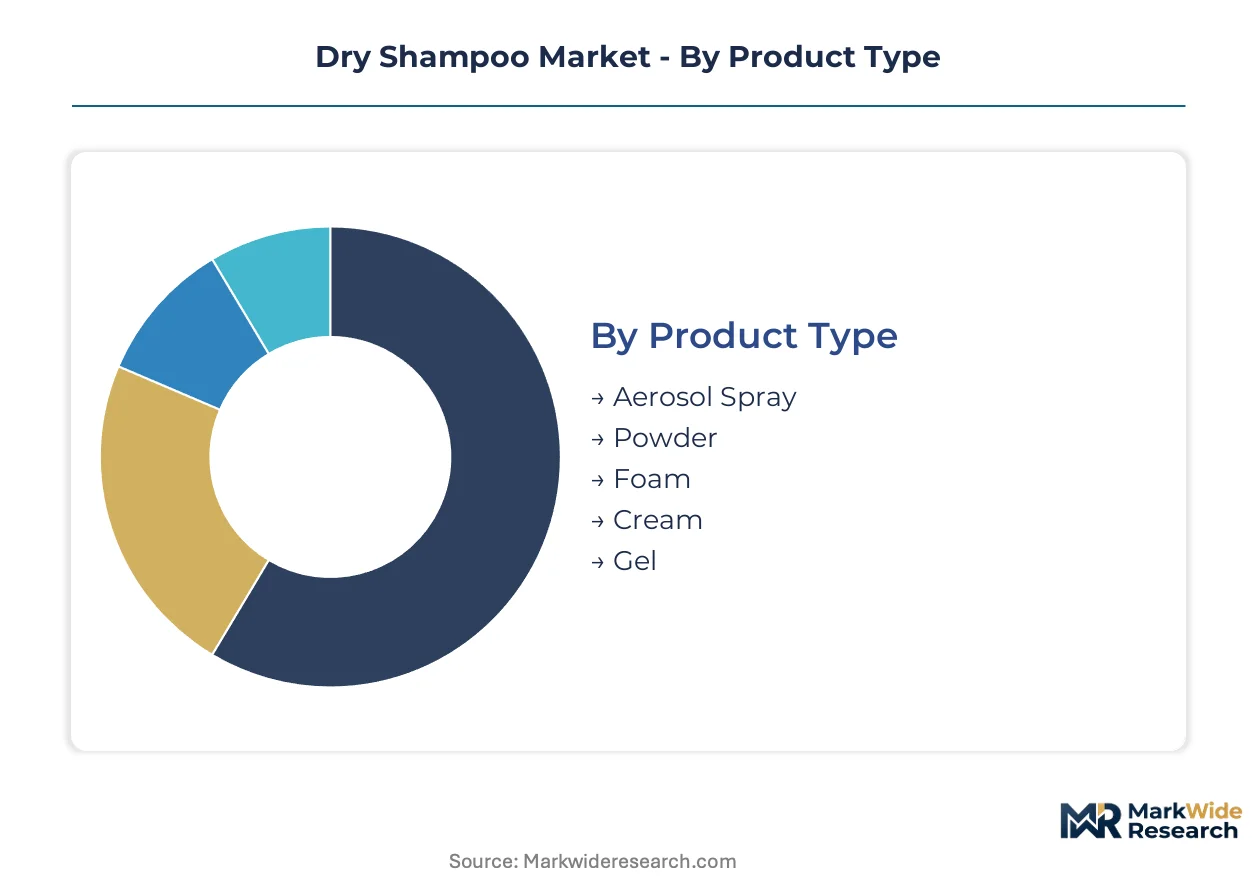
Understanding the dry shampoo market's segmentation is critical for stakeholders to identify growth pockets and refine product strategies. The diverse needs of consumers, coupled with evolving product technologies, necessitate a granular view of category performance. This analysis dissects the market across key dimensions, revealing where innovation and demand intersect.
Product Type:
The dry shampoo market's product type segmentation reflects an ongoing cycle of innovation and consumer preference shifts, driving upgrades in delivery systems and formulations.
- Aerosol Spray:These products deliver absorbent powders via a pressurized propellant system, offering quick and even distribution across hair strands. Demand for aerosol sprays remains high due to their convenience, particularly among urban consumers seeking fast personal care solutions.
- Powder:Powder formats typically consist of loose absorbent starches or minerals applied directly to the scalp and hair, often without chemical propellants. Consumer preference for 'clean label' ingredients and non-aerosol options drives expansion in this segment, addressing environmental and health concerns.
- Foam:Foam dry shampoos offer a lightweight, conditioning application that can absorb oil while providing a refreshing feel.
- Cream:Cream formulations provide a moisturizing and less visible alternative, suitable for specific hair types or styling needs.
- Gel:Gel dry shampoos represent a niche offering, focusing on targeted application and residue-free absorption for specific hair concerns.
Volume placements concentrate in Aerosol Spray; the faster expansion belongs to Powder.
Application:
Market segmentation by application highlights how specific hair concerns drive product development and consumer purchasing decisions within the dry shampoo category.
- Oily Hair:Formulations for oily hair are designed with higher concentrations of absorbent agents like corn or rice starch to effectively manage excess sebum. This segment represents the largest application area, directly addressing the primary functional purpose of dry shampoo for many users globally.
- Colored Hair:Products for colored hair often include color-safe ingredients and gentle formulations to prevent fading or dullness, alongside oil absorption. Demand for these specialized products is rising among consumers who seek to extend the life of their hair color while maintaining freshness.
- Normal Hair:Dry shampoos for normal hair offer general oil absorption and refreshing benefits for regular use between washes.
- Curly Hair:Products for curly hair focus on oil absorption without disrupting curl patterns or causing frizz, often incorporating moisturizing agents.
- Thin Hair:Formulations for thin hair provide volume and lift in addition to oil absorption, avoiding heavy residues that could weigh hair down.
The Oily Hair segment commands significant market share, while specialized solutions for Colored Hair are experiencing robust uptake.
End User:
Analyzing the dry shampoo market by end user reveals distinct customer types with varying product needs and purchasing behaviors.
- Retail Consumers:This segment encompasses individual purchasers who buy dry shampoo for personal use through various retail channels. The shift from professional stylists to retail consumers is rebalancing channel strategy, favoring large consumer-packaged goods companies with broad distribution capabilities.
- Professional Stylists:Professional stylists utilize dry shampoo in salon settings for quick refreshes, styling, and extending blowouts for clients. Their influence on product trends and brand recommendations remains significant, impacting consumer choices.
- Salons:Salons serve as a point of sale and application for dry shampoo, particularly for premium or professional-grade formulations.
- Personal Care:This segment refers to the broad individual use of dry shampoo as part of a daily grooming routine, emphasizing convenience and hygiene.
Retail Consumers represent the largest and fastest-growing end-user group, influencing product innovation and distribution strategies.
Distribution Channel:
The distribution channel segmentation illustrates how product availability and supply chain concentration shape consumer access to dry shampoo products.
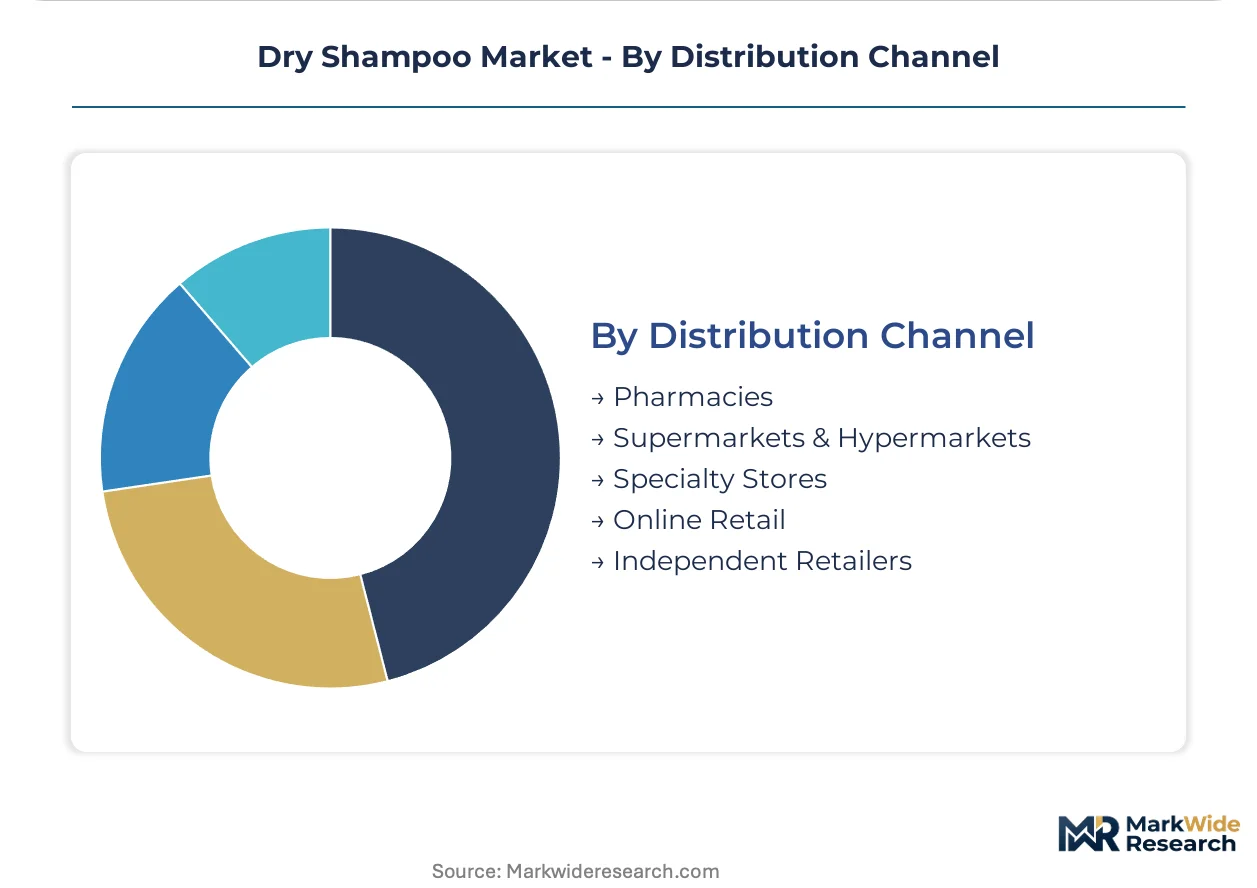
- Supermarkets & Hypermarkets:These large-format retail stores offer broad product assortments and competitive pricing, making them primary channels for mass-market dry shampoo brands. Unilever plc sustains its market position through strong penetration in these retail environments, leveraging extensive reach.
- Online Retail:E-commerce platforms, including direct-to-consumer websites and third-party marketplaces, provide a convenient purchasing option and access to niche brands. The expansion of this channel offers a low-cost route to market for emerging brands, bypassing traditional gatekeepers.
- Pharmacies:Pharmacies distribute dry shampoo, often alongside other personal care and health-related products, appealing to health-conscious consumers.
- Specialty Stores:Specialty beauty stores offer a curated selection of dry shampoo, including premium and professional brands, catering to specific consumer preferences.
- Independent Retailers:Independent retailers provide localized access and often feature artisanal or unique dry shampoo brands, fostering community engagement.
Supermarkets & Hypermarkets account for the largest sales volume, while Online Retail is gaining share most quickly due to convenience and broader selection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dry shampoo consumption patterns diverge significantly from its manufacturing base globally. Demand in urban centers across China and India drives much of the market expansion. However, product innovation and regulatory compliance often originate in established Western markets.
China
Busy lifestyles in Chinese urban centers create sustained demand for time-saving personal care products like dry shampoo. China’s NMPA pre-market approval processes are mandatory for market access, influencing product development. Market expansion notably concentrates in urban centers across cities such as Guangzhou, where convenience products gain traction.
United States
US consumers seek specialized dry shampoo formulations and 'clean' ingredient profiles, driving innovation. The US FDA’s focus on carcinogenic contaminants like benzene creates significant compliance burdens for aerosol products. Direct-to-consumer e-commerce channels in regions like California enable niche brands to connect with specific user segments.
Germany
German consumers prioritize product safety and efficacy within the high hair care expenditure market. The EU’s Cosmetics Regulation (EC) No 1223/2009 mandates rigorous safety assessments for all cosmetic products. Advanced formulation research in regions such as Baden-Württemberg focuses on developing sustainable, non-aerosol options.
Brazil
Brazil represents a substantial growth frontier with high hair care expenditure but relatively low dry shampoo penetration. ANVISA’s regulatory framework for cosmetics influences product formulations and market entry strategies. Geographic expansion opportunities exist within urban centers like São Paulo, where consumer education on usage is key.
India
Rapid urbanization in Indian metropolitan areas creates sustained demand for convenient, time-saving personal care products. The CDSCO ensures cosmetic product safety and quality, impacting market access and ingredient approvals. E-commerce channel expansion in cities like Bangalore provides a low-cost route to market for emerging dry shampoo brands.
Dry Shampoo Market Key Industry Players
Top-tier vendors anchor the mass-market segment, while specialized brands target niche consumer preferences. The market exhibits a tiered structure, with large consumer-packaged goods companies coexisting with agile, innovation-driven entrants. Strategic archetypes include diversified beauty conglomerates, dedicated hair care specialists, and ingredient-focused clean beauty brands. Portfolio diversification into new formats and geographic expansion into emerging markets are dominant competitive moves.
At the scale-driven end, L'Oréal S.A., a French multinational personal care company, and Unilever plc, a British consumer goods giant, exemplify global consumer-packaged goods companies. L'Oréal S.A. leverages its extensive brand portfolio to capture both salon and retail segments across diverse geographies. Unilever plc sustains its market position through strong penetration in supermarkets and hypermarkets, reaching a vast consumer base. Procter & Gamble, a US-based consumer goods corporation, also occupies a significant position through product formulation innovations and marketing scale, anchoring broad market access. These entities maintain market leadership through established brand recognition and extensive distribution networks.
| Leading Market Players |
|---|
| Kao Corporation |
| Henkel AG & Co. KGaA |
| Unilever plc |
| Coty Inc. |
| Shiseido Company, Limited |
| Procter & Gamble |
| Church & Dwight Co., Inc. |
| Estée Lauder Companies Inc. |
| L'Oréal S.A. |
| Others |
Cost & Logistics Intelligence
Outsourced manufacturing relationships anchor the dry shampoo market's supply position, influencing pricing power through specialized ingredient sourcing and production efficiency. This model allows brands to leverage external expertise for complex formulations, impacting cost structures and consumer price points.
Pricing Analysis
Premium pricing for rapid delivery options reflects the urgency of consumer demand for immediate hair care solutions. The dominant pricing model is per-unit transactional, with costs varying significantly based on brand premium and specialized 'clean' ingredient formulations. Pricing pressure stems from intense competition within the mass-market segment, particularly for aerosol formats. Retail consumers exhibit the highest price sensitivity, often seeking value options, while professional stylists prioritize performance and brand reputation.
Supply Chain Analysis
Regional distribution centers facilitate efficient product movement from manufacturing hubs to diverse retail channels, supporting market reach. Manufacturing of dry shampoo and its raw materials concentrates in countries like China and the United States, with Germany also contributing to formulation innovation. The market relies on key inputs such as plant-based starches and aerosol propellants; regulatory restriction on specific propellants presents a significant supply chain risk. Downstream distribution primarily operates through supermarkets and hypermarkets, complemented by expanding online retail platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dry shampoo market is evolving into a vertical-integration race, as companies seek to control ingredient sourcing and formulation expertise. This strategy aims to secure 'clean label' raw materials and enhance product differentiation.
For Market Incumbents: To counter heightened regulatory scrutiny over aerosol contaminants, established brands must invest in alternative propellant systems and advanced plant-based absorbent research. L'Oréal S.A. can leverage its R&D capabilities to develop benzene-free formulations, maintaining consumer trust and market access. Unilever plc should fortify its distribution networks in emerging urban centers, like those in India, to defend against niche entrants. This requires continuous investment in regulatory compliance and supply chain resilience.
For New Entrants and Emerging Players: Direct-to-consumer e-commerce platforms offer emerging brands a low-cost route to market, bypassing traditional retail gatekeepers. Niche players can target specific hair concerns beyond oiliness, such as color-safe formulations or volumizing agents for fine hair. Underpenetrated geographies like Brazil present a substantial growth frontier for innovative non-aerosol formats. A strong go-to-market angle involves transparent ingredient sourcing and sustainable packaging narratives.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialized ingredient innovators and niche brands with strong intellectual property in non-aerosol formats. The market shows long-term viability over the next decade, driven by evolving consumer preferences for 'clean' and convenient products. Acquisition targets include agile companies developing advanced plant-based starches or unique delivery systems. A signal to watch involves the successful commercialization of truly residue-free non-aerosol dry shampoos across diverse hair types.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop benzene-free propellant systems | This initiative addresses US FDA regulatory concerns and enhances consumer safety perceptions. |
| Expand non-aerosol powder format production | Increased capacity for powders meets consumer preference for 'clean' and sustainable options. |
| Invest in plant-based starch research | Advanced botanical absorbents offer superior performance and align with 'clean label' demands. |
| Target distribution in Indian urban centers | Market penetration in Bangalore captures demand from fast-paced lifestyles and e-commerce expansion. |
| Launch color-safe dry shampoo formulations | This product specialization caters to a growing segment of consumers with treated hair. |
Research Approach
Independent corroboration across industry reports, regulatory filings, and trade publications underwrites the qualitative findings of this study. Primary interviews with brand managers, R&D directors, and retail category buyers provided critical market insights. Secondary validation utilized data from the EU Cosmetics Regulation (EC) No 1223/2009 and China’s NMPA pre-market approval processes. A bottom-up and top-down triangulation approach ensured comprehensive market sizing and forecast accuracy.
Rate-of-change decomposition analyzes market evolution by assessing shifts in product type, application segment, and geographic penetration over the projection horizon. The analytical framework integrates these dimensions to model market value and volume. Segmentation included aerosol spray, powder formats, oily hair applications, and retail consumer end-users. Compound annual growth rates were derived from historical data and projected adoption trends, factoring in regulatory shifts concerning ingredient safety.
The model holds under current regulatory frameworks and consumer preference trajectories; deviation in major ingredient bans or unexpected shifts in water conservation policies would shift market projections. Forecasts reflect assumptions regarding product innovation and distribution channel expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Underarm Antiperspirant and Deodorant Market
Beauty & Personal Care
Eyelash Serum Market
Beauty & Personal Care
Hand Soap in Retail Market
Beauty & Personal Care
Japan Aromatherapy Products Market
Beauty & Personal Care
Asia-Pacific Bath and Shower Products Market
Beauty & Personal Care
Global Shampoo Bars Market
Beauty & Personal Care
Cosmetic Oil Market
Beauty & Personal Care
Beard Oil Market
Beauty & Personal Care
Russia Beauty and Personal Care Market
Beauty & Personal Care
United States Male Grooming Products Market
Beauty & Personal Care
Cruelty-Free Makeup Market
Beauty & Personal Care
Facial Care Products Market
Beauty & Personal Care
Beauty Products Market
Beauty & Personal Care
Color Cosmetics Market
Beauty & Personal Care
Organic Liquid Soaps Market
Beauty & Personal Care
Global Electric Head and Scalp Massager Market