
 Cosmetic Oil Market | 2026-2036
Cosmetic Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Cosmetic Oil Market Analysis
Project finance for sustainable plantations and asset-light contract manufacturing is rewriting competitive entry barriers in cosmetic oils. BASF SE leverages backward integration into shea and jojoba sourcing to control raw material quality. Estée Lauder anchors its premium positioning through captive R&D labs that formulate proprietary oil blends. Kao Corporation competes via specialized fermentation-derived squalane that reduces reliance on shark liver extraction.
Cosmetic oils are lipid-based formulations extracted through cold-pressing, solvent extraction, or supercritical CO2 methods, with fatty acid profiles and peroxide values determining shelf stability and skin compatibility; they function as emollients, carriers for active ingredients, or sensory modifiers in topical products. Vegetable oils lead volume due to plant-based marketing claims and biodegradability advantages, while essential oils command margin pools through aromatherapy positioning and concentration economics. E-commerce as an end-user channel is expanding fastest, driven by direct-to-consumer sampling models that bypass traditional beauty retail gatekeepers.
REACH registration requirements in Europe mandate full toxicological dossiers for imported essential oils, raising compliance costs for non-EU suppliers. The FDA's cosmetic ingredient labeling rules and MoCRA enforcement framework in the United States demand substantiated safety data for fragrance allergens in leave-on products. India's BIS quality standards for ayurvedic oils create a dual certification path that exporters must navigate. Stakeholders should monitor how evolving fragrance allergen thresholds across Brussels, Washington, and New Delhi reshape formulation portfolios and supplier qualification timelines.
Market Dynamics
Clean-label mandates and fragrance allergen disclosure rules are compressing formulation timelines while elevating raw material traceability requirements across cosmetic oil supply chains.
Growth Catalysts
- REACH Registration:Full toxicological dossiers for imported essential oils into Europe are consolidating supplier bases around compliant mid-scale producers with in-house testing capabilities.
- Ayurvedic Export Channels:India's BIS dual certification path for traditional oils is opening premium positioning for domestic brands in North American and European direct-to-consumer channels.
- Fermentation-Derived Squalane:Biotechnology platforms are displacing shark liver extraction, satisfying vegan positioning requirements in prestige skincare formulations.
Market Restraints
- Shea Butter Price Volatility:West African supply concentration and climate-induced harvest variability create margin compression for emollient-dependent product lines.
- Supercritical CO2 Equipment Costs:High capex requirements for solvent-free extraction limit capacity expansion among contract manufacturers serving mid-tier brands.
- MoCRA Compliance Burden:FDA's substantiated safety data requirements for fragrance allergens in leave-on products extend new product development cycles by 8-14 months.
Strategic Opportunities
- Indonesia's Untapped Plantation Base:Underdeveloped nutmeg and mace oil extraction infrastructure offers first-mover advantages for sustainable sourcing claims in European markets.
- Biodegradable Carrier Oils:Regulatory tailwinds from EU Green Deal packaging directives favor vegetable oil formulations over petroleum-derived emollients in rinse-off applications.
- Direct-to-Consumer Sampling:E-commerce subscription models bypass traditional beauty retail gatekeepers, enabling margin capture previously lost to distributor markups.
Industry Challenges
- Peroxide Value Stabilization:Maintaining shelf stability in cold-pressed oils requires specialized antioxidant formulation expertise that outpaces current technical training pipelines.
- Dual Certification Complexity:Navigating simultaneous BIS ayurvedic standards and REACH dossier requirements demands dedicated regulatory affairs headcount that strains emerging brand budgets.
- Legacy ERP Integration:Batch-level traceability systems for ingredient genealogy conflict with established manufacturing execution platforms at mid-scale facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cosmetic Oil Market |
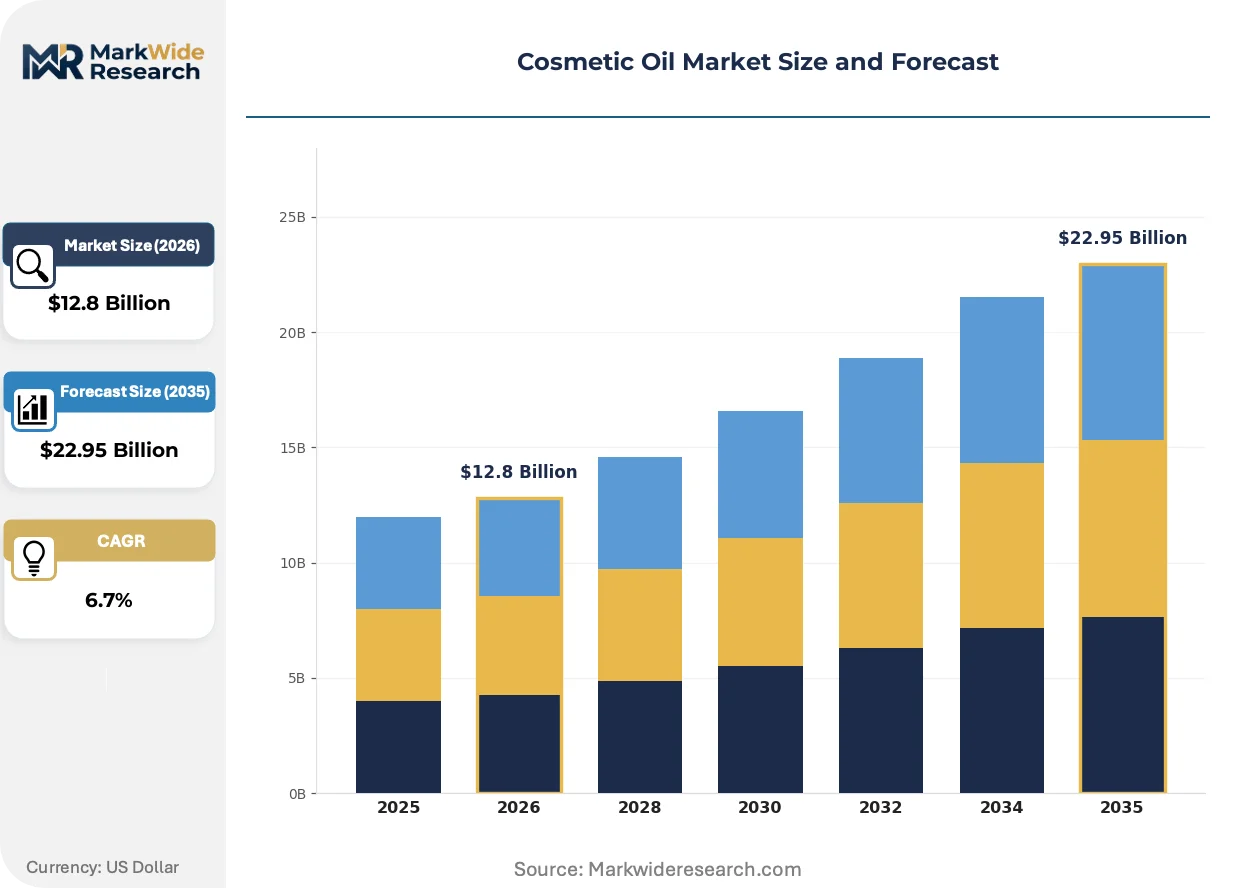
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carrier Oils, Essential Oils, Mineral Oils, Vegetable Oils End User: Beauty Salons, Personal Care, Skincare Brands, E-commerce Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales Packaging Type: Glass Bottles, Plastic Containers, Jars, Sachets |
| Companies Covered | L'Oréal, BASF SE, Unilever, Givaudan SA, Estée Lauder, Shiseido, Coty Inc., Kao Corporation, Procter & Gamble, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cosmetic Oil Market Emerging Trajectories
Extraction technology convergence and disclosure-driven formulation transparency are redefining competitive advantage in cosmetic oil procurement and product development cycles.
Supercritical CO2 extraction is hybridizing with traditional cold-pressing protocols to preserve heat-sensitive phytonutrients in marula and baobab oils. Prestige skincare laboratories in France and California are adopting these hybrid systems to support "raw" marketing claims. The technology is hybridizing quality tiers by enabling small-batch producers to achieve pharmaceutical-grade purity metrics previously exclusive to industrial solvent facilities.
REACH fragrance allergen threshold revisions are forcing reformulation of legacy essential oil blends across European leave-on product portfolios. The European Chemicals Agency's 2023-2025 dossier updates specifically target limonene and linalool oxidation products. Brands serving German and Benelux markets are responding by reducing essential oil concentrations or substituting with fermented botanical extracts.
Ingredient genealogy verification is replacing certificate-of-analysis reliance among North American clean beauty retailers. Sephora and Ulta's clean certification programs now mandate farm-level traceability for carrier oils in private-label skincare. This behavioral shift is most visible in jojoba and argan supply chains, where blockchain-enabled provenance tracking commands 12-18% procurement premiums.
Cosmetic Oil Market Segmentation
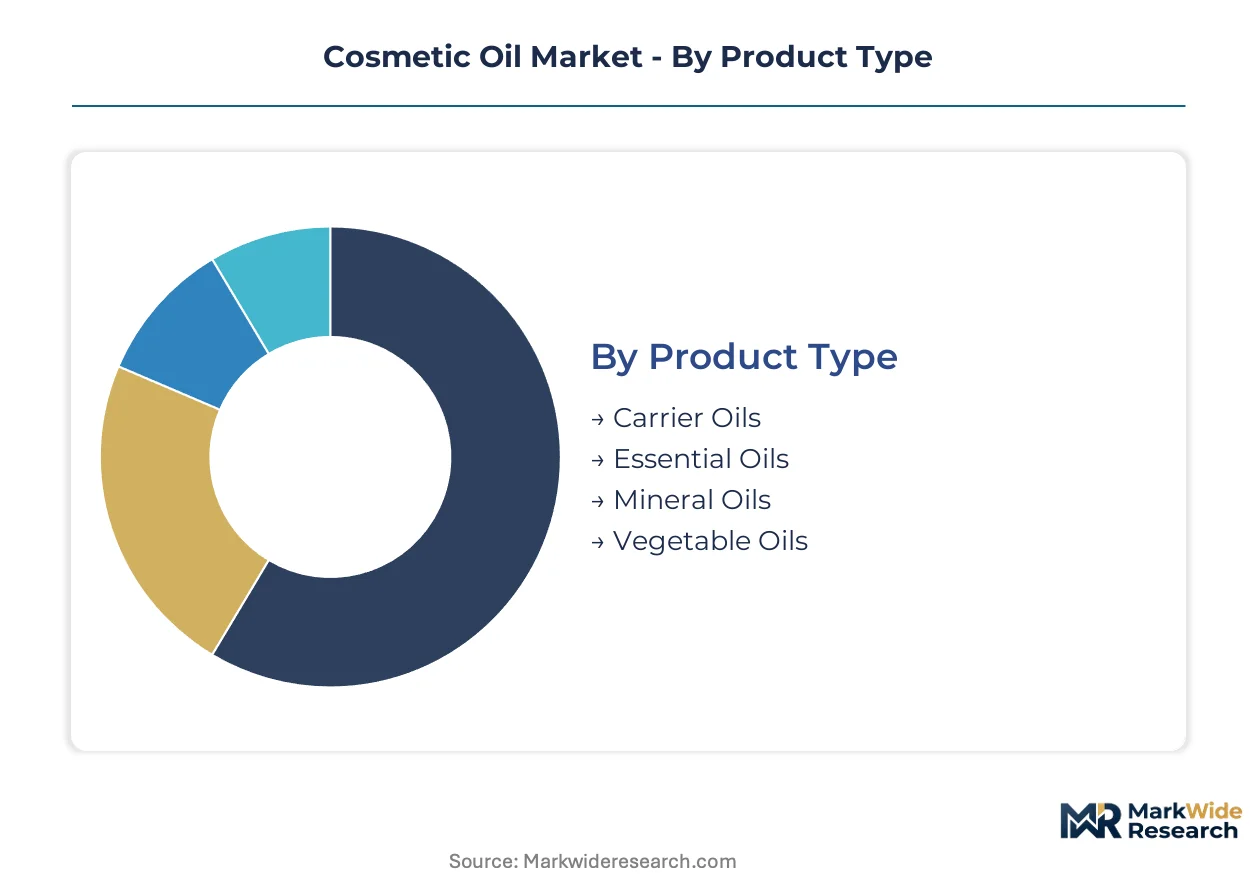
Segmentation in cosmetic oils reveals how formulation requirements, channel economics, and packaging specifications create distinct procurement behaviors across buyer types. Each dimension carries regulatory implications that reshape supplier qualification criteria.
Product Type:
Mature extraction methods anchor volume leadership while biotechnology platforms are emerging as margin drivers.
- Carrier Oils:These lipid-based formulations derived from jojoba, argan, and coconut serve as delivery vehicles for active ingredients in serum and moisturizer applications. Demand concentrates in prestige skincare brands across France and California, where cold-pressed purity claims command procurement premiums from clean beauty retailers.
- Essential Oils:Highly concentrated aromatic extracts from lavender, tea tree, and eucalyptus function as fragrance components and purported therapeutic agents. European REACH compliance costs are consolidating supplier bases around mid-scale producers with in-house toxicological testing capabilities in Germany and the Netherlands.
- Mineral Oils:Refined petroleum derivatives remain cost-effective emollients in mass-market personal care formulations.
- Vegetable Oils:Plant-derived lipids from shea, marula, and baobab satisfy biodegradability requirements under EU Green Deal packaging directives.
Vegetable oils handle the majority of throughput; fermentation-derived squalane within carrier oils is expanding most quickly on share.
End User:
Channel concentration varies sharply by order scale and formulation complexity requirements.
- Skincare Brands:These buyers specify fatty acid profiles and peroxide values for proprietary oil blends manufactured through captive R&D laboratories or contract manufacturing arrangements. Procurement in India targets BIS-certified ayurvedic oils for domestic positioning and North American export channels.
- E-commerce:Direct-to-consumer sampling models bypass traditional beauty retail gatekeepers, enabling margin capture through subscription-based replenishment cycles. Sephora and Ulta's clean certification programs now mandate farm-level traceability for carrier oils in private-label offerings.
- Beauty Salons:Professional service providers purchase bulk formats for in-treatment applications and retail resale.
- Personal Care:Individual consumers select smaller pack sizes through mass retail and digital channels.
E-commerce is gaining share fastest; skincare brands retain the largest absolute procurement volumes.
Distribution Channel:
Margin structure and customer acquisition economics diverge across physical and digital touchpoints.
- Online Retail:Digital platforms enable direct-to-consumer sampling models that reduce customer acquisition costs compared to brick-and-mortar retail. India's domestic brands leverage these channels for ayurvedic oil export into North American and European markets.
- Specialty Stores:Curated beauty retailers provide educational environments for premium oil positioning and ingredient storytelling.
- Supermarkets:Mass-market volume placement depends on price-competitive vegetable oil formulations.
- Direct Sales:Network marketing organizations distribute essential oil kits through personal relationship channels.
Online retail shows the steepest expansion trajectory; specialty stores maintain the highest margin realization.
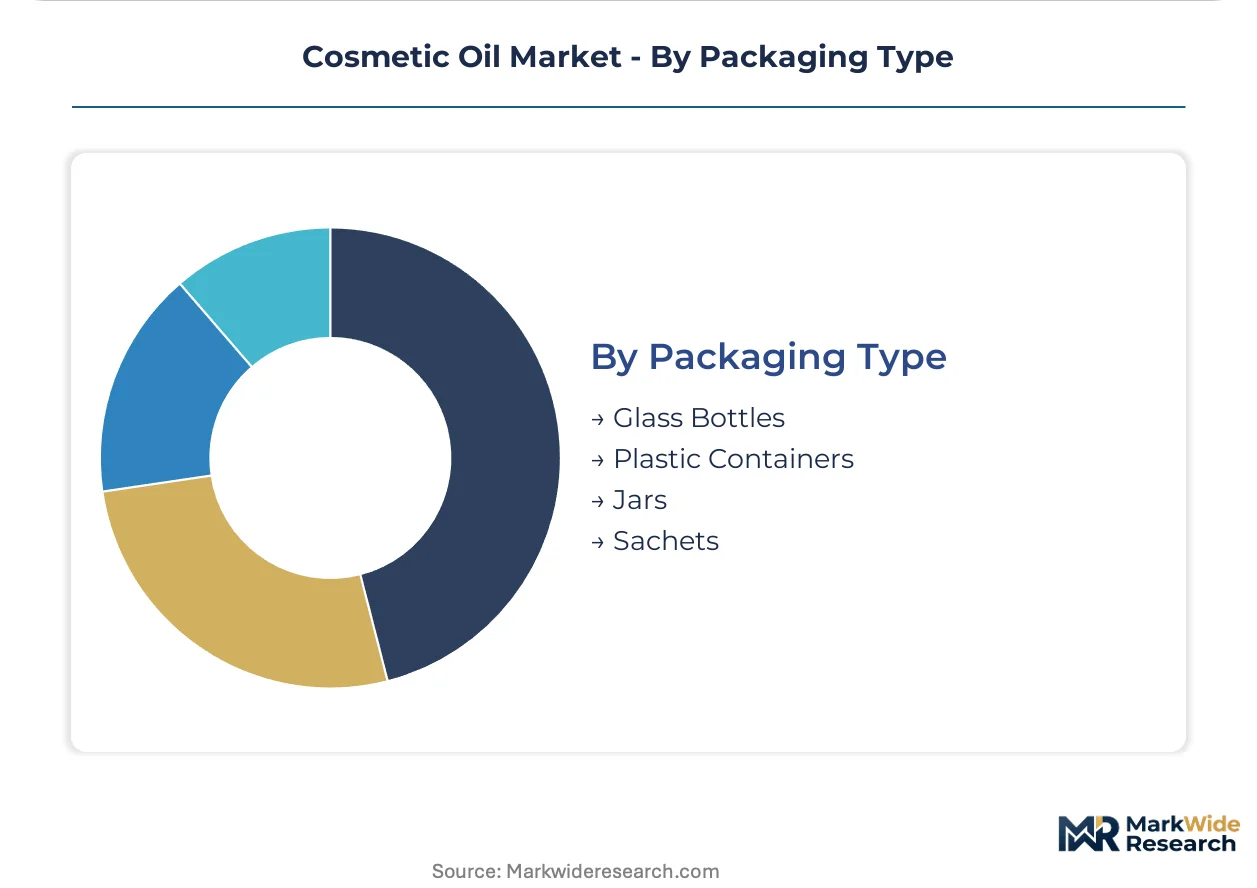
Packaging Type:
Sustainability credentials and product protection requirements drive material selection.
- Glass Bottles:Amber and cobalt glass containers provide UV protection for photosensitive essential oils while supporting premium positioning through recyclability claims. European brands favor this format for REACH-compliant fragrance products targeting German and Benelux markets.
- Plastic Containers:Lightweight PET and HDPE formats reduce shipping costs for high-volume carrier oil distribution.
- Jars:Wide-mouth containers accommodate solid and semi-solid oil formulations like shea butter balms.
- Sachets:Single-use foil packets serve sampling programs and travel-size distribution in e-commerce channels.
Glass bottles dominate premium essential oil segments; sachets are climbing fastest in subscription box applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skincare brands and direct-to-consumer platforms concentrate procurement across five distinct national markets, each shaped by unique regulatory frameworks and ingredient sourcing traditions.
United States
Prestige skincare laboratories in California and New York Metro drive demand for cold-pressed carrier oils with documented fatty acid profiles. FDA's MoCRA enforcement framework demands substantiated safety data for fragrance allergens in leave-on products. Los Angeles-based clean beauty retailers now mandate farm-level traceability for jojoba and argan supply chains through blockchain-enabled verification systems.
Germany
Mid-scale producers with in-house toxicological testing capabilities consolidate market position as REACH registration requirements raise compliance barriers for imported essential oils. ECHA's 2023-2025 dossier updates target limonene and linalool oxidation products in leave-on formulations. The Cologne-Düsseldorf corridor hosts specialized extraction facilities serving Benelux markets with pharmaceutical-grade purity metrics.
France
Prestige fragrance houses and skincare laboratories anchor European demand for hybrid extraction technologies combining supercritical CO2 with cold-pressing protocols. ANSM oversees cosmetic ingredient safety assessments alongside EU REACH alignment. Grasse and the Provence-Alpes-Côte d'Azur region concentrate traditional essential oil distillation capacity for luxury aromatherapy positioning.
India
Ayurvedic beauty traditions drive premium vegetable oil consumption through domestic channels and North American export markets. BIS quality standards for traditional oils create dual certification requirements that domestic brands navigate for international positioning. Maharashtra and Gujarat host extraction infrastructure serving both ayurvedic domestic demand and contract manufacturing for global skincare brands.
Japan
Specialized fermentation-derived squalane production reduces reliance on marine extraction while satisfying vegan positioning requirements. METI oversees industrial biotechnology development and cosmetic ingredient safety frameworks. The Kansai region around Osaka concentrates fermentation technology platforms supplying prestige skincare formulations across Asia-Pacific markets.
Cosmetic Oil Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered market positions defined by extraction technology ownership and regulatory compliance depth. The vendor base clusters around three strategic archetypes: vertically integrated chemical conglomerates controlling raw material sourcing, captive R&D laboratories serving prestige brand portfolios, and biotechnology platforms displacing traditional extraction methods. Competitive moves concentrate on backward integration into plantation assets and fermentation technology licensing arrangements that bypass agricultural supply volatility.
Within the integrated chemical tier, BASF SE exemplifies upstream control over shea and jojoba sourcing to secure raw material quality consistency. Estée Lauder occupies a position representing captive R&D laboratory investment for proprietary oil blend formulation. Kao Corporation anchors the biotechnology-specialist segment through fermentation-derived squalane production that eliminates shark liver extraction dependencies. These three players represent distinct competitive vectors—supply security, formulation exclusivity, and technology substitution—shaping procurement relationships across skincare brand customers.
| Leading Market Players |
|---|
| L'Oréal |
| BASF SE |
| Unilever |
| Givaudan SA |
| Estée Lauder |
| Shiseido |
| Coty Inc. |
| Kao Corporation |
| Procter & Gamble |
| Others |
Supply Flow & Price Mechanics
West African shea butter cooperatives in Burkina Faso and Ghana anchor global emollient supply, with harvest volatility translating directly into price premiums for cosmetic brands lacking long-term offtake agreements. This geographic concentration grants plantation holders significant leverage over mid-tier formulators while fermentation-derived alternatives reshape competitive benchmarks.
Pricing Analysis
Certification level creates the primary spread between commodity-grade and pharmaceutical-grade cosmetic oils. Three-tier pricing structure across premium cold-pressed, standard refined, and economy solvent-extracted tiers reflects peroxide value thresholds and REACH dossier completeness. Cost compression in standard-grade carrier oils is intensifying because contract manufacturers pass through supercritical CO2 equipment depreciation. Mass-market personal care brands exhibit highest price sensitivity; prestige skincare laboratories absorb premiums for documented fatty acid profiles and blockchain-enabled provenance.
Supply Chain Analysis
Extended payment terms from European skincare brands strain working capital across Indian and Indonesian extraction facilities. Raw material sourcing concentrates in India for ayurvedic oils, West Africa for shea, and Argentina for jojoba. Supply chains draw from cold-pressing infrastructure, fermentation bioreactors, and supercritical CO2 systems. Single-source vulnerability runs through West African shea harvests exposed to climate-induced yield variability. Distribution runs through direct-to-consumer e-commerce platforms, specialty beauty retailers, and contract manufacturing networks serving skincare brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation-derived squalane biotechnology is disrupting traditional marine and agricultural extraction, creating asymmetric growth opportunities for capitalized platforms against legacy supply chains. MoCRA fragrance allergen enforcement and REACH threshold revisions accelerate formulation turnover, rewarding regulatory affairs depth.
For Market Incumbents: Pre-empt biotechnology substitution by acquiring fermentation platform licenses or captive squalane production capacity. Lock in multi-year offtake agreements with West African shea cooperatives before harvest volatility intensifies. Channel control through direct-to-consumer subscription models defends margin position against distributor markup compression.
For New Entrants and Emerging Players: Build out Indonesia's underdeveloped nutmeg and mace oil extraction infrastructure for sustainable sourcing claims in European markets. Target India's BIS-certified ayurvedic oil export channel where dual certification complexity deters mid-scale competitors. Launch through e-commerce sampling models that bypass Sephora and Ulta's farm-level traceability gatekeeping.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among contract manufacturers with captive R&D laboratories serving prestige brand portfolios. Long-term viability centers on backward integration into plantation assets or fermentation technology ownership that decouples from agricultural volatility. Monitor ECHA fragrance allergen dossier updates as inflection signal for reformulation demand spikes.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Assets | Shea and jojoba sourcing control secures raw material quality consistency against harvest volatility. |
| Fermentation Technology Licensing | Squalane production platforms eliminate shark liver extraction dependencies while satisfying vegan positioning. |
| Direct-to-Consumer Channel Launch | Subscription sampling models capture margins previously lost to beauty retail distributor markups. |
| REACH Dossier Investment | In-house toxicological testing capabilities consolidate supplier position for European essential oil imports. |
| Blockchain Provenance Implementation | Farm-level traceability systems command procurement premiums from Sephora and Ulta clean certification programs. |
Methodological Framework
Cross-validation between primary interviews with extraction facility operators, regulatory affairs directors at skincare brands, and contract manufacturing procurement leads anchors the qualitative findings. Secondary validation draws from ECHA REACH registration databases, FDA MoCRA guidance documents, BIS certification records, and customs trade data for shea butter and jojoba oil imports. Bottom-up capacity assessments across West African cooperatives, Indian ayurvedic processors, and Japanese fermentation facilities triangulate against top-down demand estimates from prestige brand R&D spending and e-commerce channel growth.
Calibration against historical price volatility in shea butter markets and adoption curves for fermentation-derived squalane refines projection parameters. Segmentation modeling spans product type, extraction method, end-user channel, and geographic regulatory cluster. CAGRs derive from elasticity-adjusted demand functions incorporating REACH compliance cost pass-through and MoCRA enforcement timeline assumptions. Industry-specific inputs include peroxide value stability curves, supercritical CO2 capacity expansion pipelines, and BIS-REACH dual certification completion rates.
Stress conditions across West African harvest variability, ECHA fragrance allergen threshold revisions, and biotechnology scale-up timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory enforcement intensity and substitution elasticity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Sunless Tanners Market
Beauty & Personal Care
Global Heated Eyelash Curlers Market
Beauty & Personal Care
United States Bath Soap Market
Beauty & Personal Care
Canada Dermocosmetics Market
Beauty & Personal Care
India Antibacterial Soap Market
Beauty & Personal Care
E-Pharmacy Beauty and Personal Care (BPC) Market
Beauty & Personal Care
In-Wash Scent Booster Market
Beauty & Personal Care
Europe Sustainable Personal Care Market
Beauty & Personal Care
Japan Beauty Fridges Market
Beauty & Personal Care
Beauty Products Market
Beauty & Personal Care
Cosmetology Market
Beauty & Personal Care
Salon Products Market
Beauty & Personal Care
Europe Shampoo Market
Beauty & Personal Care
Beauty Tools Market
Beauty & Personal Care
Russia Beauty and Personal Care Market
Beauty & Personal Care
North America Cosmetics Market