
 North America Pet Diet Market | 2026-2036
North America Pet Diet Market Size, Share, and Industry Trends Forecast 2026-2036
North America Pet Diet Market Insights
Market Context
Canadian co-manufacturing capacity for grain-free formulations is hardening as US brands seek tariff-advantaged production alternatives. Mars Incorporated leverages backward integration into protein rendering to secure supply chain stability across Midwestern processing corridors. Nestlé Purina anchors its position through veterinary channel exclusivity, while Hill's Pet Nutrition differentiates via prescription diet R&D partnerships with teaching hospitals.
Technical Definition and Segment Structure
North America Pet Diet comprises nutritionally formulated feed products manufactured to AAFCO nutrient profiles, with dry extrusion typically achieving moisture content below 10 percent and wet canning processes yielding 60-78 percent moisture for palatability-sensitive species. Dry Food occupies the largest volume share due to shelf stability and cost efficiency in mass retail, while Treats capture disproportionate margin pools through premiumization and humanization positioning. Plant-Based ingredient formulations represent the fastest-growing structural segment as sustainability-conscious pet owners in Pacific Coast states drive trial rates.
Regulatory Frame and Outlook
FDA Center for Veterinary Medicine oversees ingredient safety and facility inspections, while AAFCO model regulations govern labeling and nutritional adequacy claims across US state jurisdictions. Canadian Food Inspection Agency parallel oversight creates dual-compliance burdens for cross-border manufacturers. Stakeholders must monitor evolving state-level raw feeding restrictions and proposed FDA modernization rules affecting traceability requirements.
Market Dynamics
Millennial pet humanization is compressing product lifecycles and forcing rapid SKU proliferation across North American manufacturing corridors. This demographic cohort treats companion animals as family members, demanding clinical-grade nutrition transparency and traceable ingredient sourcing that legacy mass-market formulations cannot deliver.
Growth Catalysts
- AAFCO Nutrient Profile Modernization:Updated canine and feline nutritional adequacy standards are compelling manufacturers to reformulate legacy portfolios, creating upgrade cycles across dry, wet, and treat segments.
- Veterinary Channel Expansion:Prescription diet authorization through licensed practitioners is locking in recurring revenue streams and elevating clinical credibility for therapeutic formulations.
- Protein Rendering Infrastructure:Midwestern processing corridor investments in captive poultry and fish meal production are insulating margin structures from agricultural commodity volatility.
Market Restraints
- Input Cost Volatility:Wild-caught marine protein and human-grade meat byproduct pricing swings compress gross margins for premium positioning tiers dependent on fresh ingredient claims.
- Regulatory Friction:FDA Center for Veterinary Medicine facility inspection backlogs delay new product approvals, extending time-to-market for novel ingredient introductions by 12-18 months.
- Substitution Threat:Raw feeding and home-prepared diet communities in Pacific Coast metropolitan clusters divert spending from commercial formulations despite safety advisories.
Strategic Opportunities
- Insect Protein Scale-Up:Black soldier fly larvae farming in Texas and Tennessee offers tariff-advantaged domestic protein sourcing with substantially lower land and water intensity than conventional livestock.
- Veterinary Telehealth Integration:Digital prescription diet fulfillment platforms bypass traditional clinic inventory constraints and capture subscription revenue from rural and exurban pet owner cohorts.
- Canadian Co-Manufacturing:Cross-border production utilizing CFIA-registered facilities provides US brands tariff shelter and access to European export certification pathways.
Industry Challenges
- Formulation Talent Scarcity:Veterinary nutritionist PhD hiring pipelines cannot match manufacturer demand, inflating compensation and slowing R&D cycle times for therapeutic diet launches.
- Legacy System Integration:ERP modernization to achieve FDA traceability mandates requires capital deployment that mid-tier private labels struggle to finance without dilutive equity raises.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Pet Diet Market |
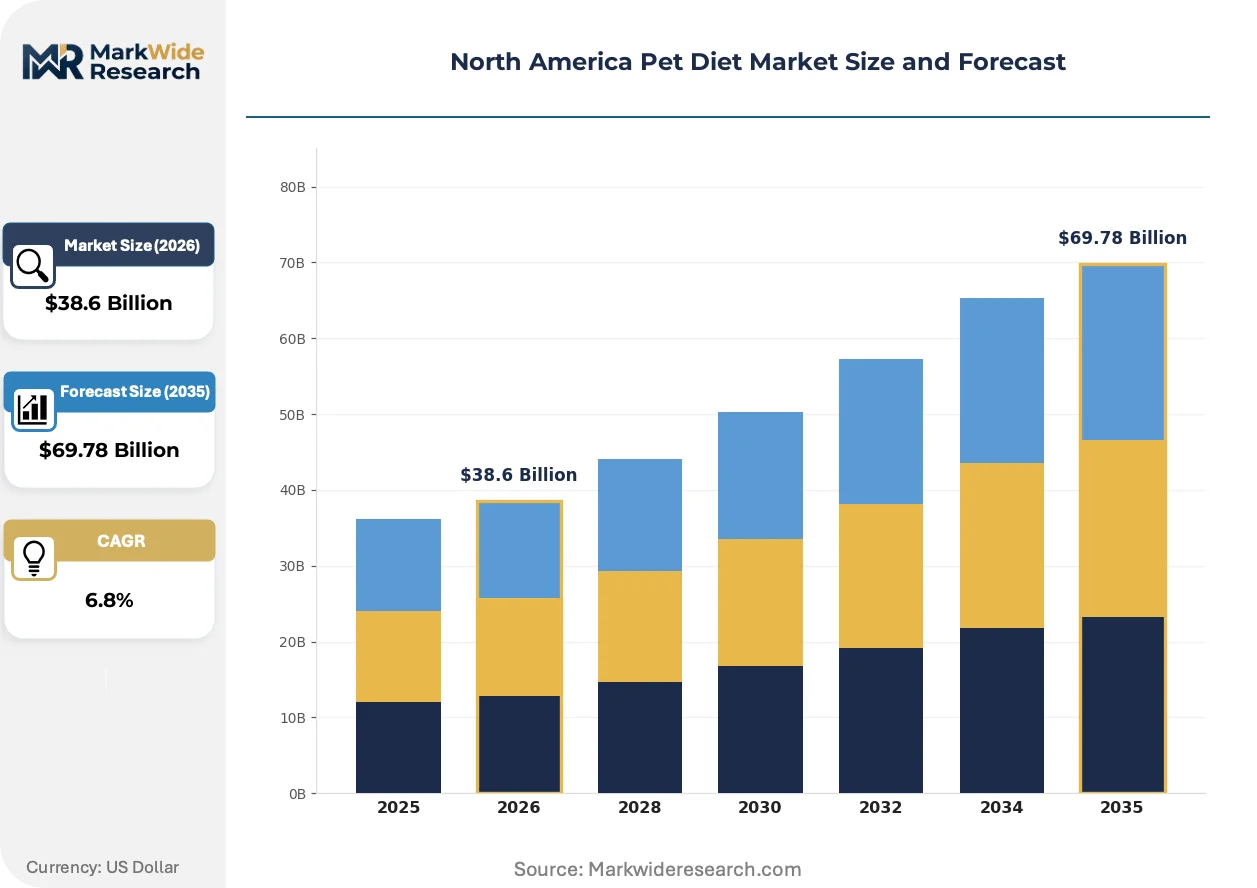
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Supplements End User: Pet Owners, Pet Retailers, Veterinarians, Pet Cafés Ingredient Type: Meat-Based, Plant-Based, Grain-Free, Organic Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Veterinary Clinics |
| Companies Covered | Mars Incorporated, Nestlé Purina, Hill’s Pet Nutrition, The J.M. Smucker Company, Blue Buffalo, Diamond Pet Foods, General Mills, Colgate-Palmolive Company, Champion Petfoods, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Pet Diet Market Trends and Innovations
Precision fermentation and cellular agriculture are migrating from human food into companion animal applications, restructuring protein sourcing economics. These technologies promise to sever the link between pet nutrition and conventional animal agriculture, appealing to sustainability-motivated owner segments.
Cultivated chicken and fish protein produced via bioreactor systems is converging with premium wet food formulations targeting allergen-sensitive breeds. Early adopters in California and New York metropolitan markets accept 40-60 percent price premiums for slaughter-free claims. This convergence is compressing the timeline for novel protein regulatory approval as FDA establishes parallel evaluation frameworks for cell-cultured pet ingredients.
State-level raw feeding restriction proposals in California and New York are forcing commercial manufacturers to defend processing safety narratives. The regulatory pressure is accelerating pasteurization technology investments and third-party pathogen testing protocols. Wet canning and high-pressure processing segments are capturing displaced demand from frozen raw formats as veterinarians counsel against uncontrolled bacterial exposure.
Subscription direct-to-consumer models are displacing mass retail replenishment cycles for premium and super-premium tiers. Millennial and Gen Z pet owners in Texas and Florida urban corridors prioritize auto-ship convenience and personalized portioning over in-store brand discovery. This channel migration is compressing trade promotion effectiveness and forcing legacy brands to rebuild digital-native fulfillment infrastructure.
North America Pet Diet Market Segmentation
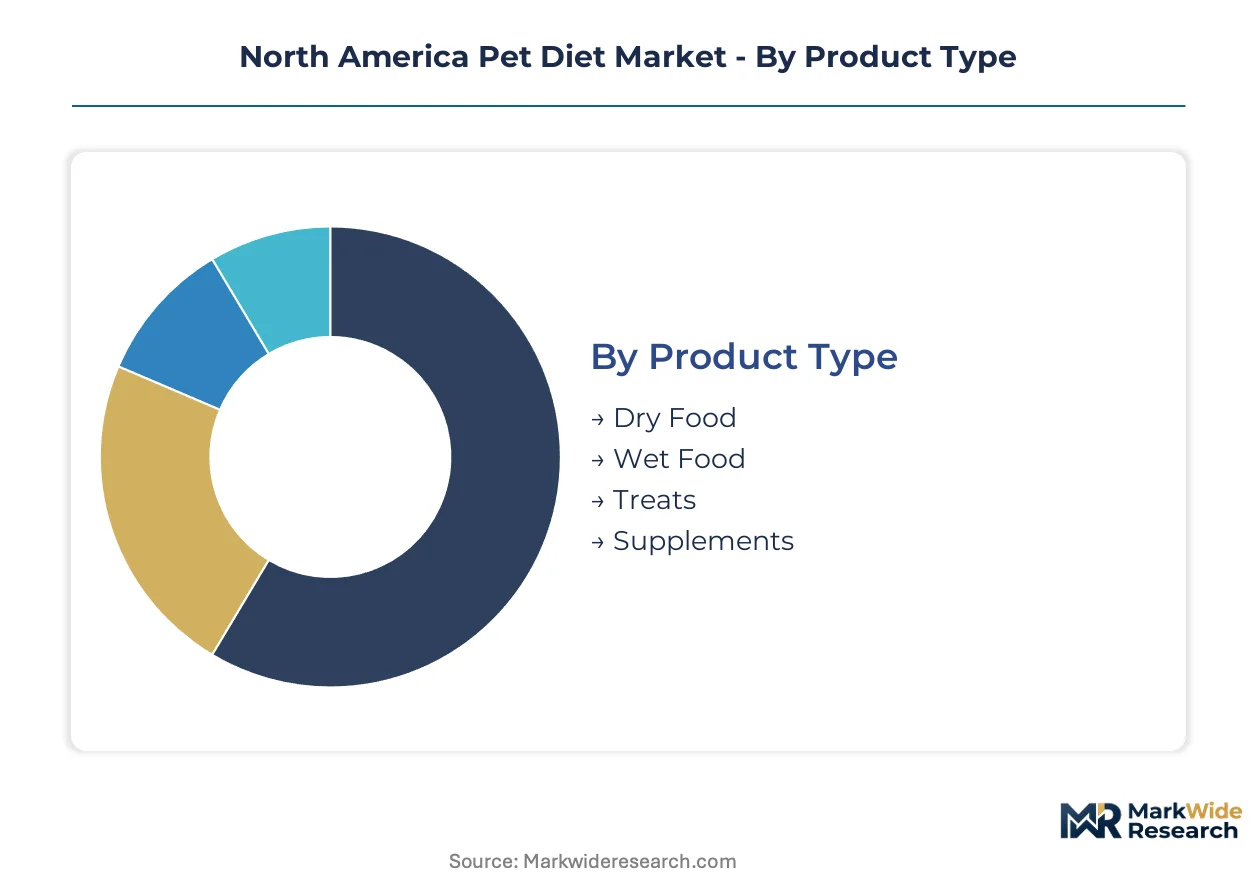
Pet diet manufacturers configure production lines around moisture content thresholds and protein sourcing economics. Segmentation reveals where capital equipment concentrates and which formulation types command premium positioning across North American retail and professional channels.
Product Type:
Extrusion and canning infrastructure concentrates in Midwestern and Southeastern manufacturing corridors where energy costs and protein rendering access align.
- Dry Food:Extruded kibble formulations achieve sub-10 percent moisture through twin-screw extrusion, enabling shelf-stable distribution without refrigeration. Mass retail channels in Texas and Florida metropolitan areas drive volume procurement for standard and premium positioning tiers.
- Wet Food:Retort canning processes yield 60-78 percent moisture content, requiring sterilization equipment and shorter production runs. Pacific Coast pet owners in California and Washington state clusters demonstrate disproportionate willingness to pay for palatability claims in therapeutic and senior life-stage applications.
- Treats:Functional and reward categories leverage freeze-drying and air-drying equipment with lower capital barriers.
- Supplements:Soft-chew and powder formats occupy co-manufacturing capacity with human nutraceutical producers.
Dry Food absorbs the bulk of installed capacity; Treats is expanding most quickly.
End User:
Purchasing authority fragments across emotional decision-makers and clinical gatekeepers with divergent margin expectations.
- Pet Owners:Direct consumers in millennial and Gen Z cohorts research ingredient provenance through digital channels before trial. Subscription auto-ship adoption concentrates in Texas and Florida urban corridors where convenience positioning overrides in-store discovery.
- Veterinarians:Licensed practitioners control prescription diet authorization, locking in recurring revenue through clinic inventory or fulfillment partnerships. Teaching hospital networks in California and New York metropolitan areas influence therapeutic formulation R&D priorities.
- Pet Retailers:Independent and chain specialty stores curate premium and super-premium assortments with higher service intensity than mass channels.
- Pet Cafés:Experiential venues in Canadian urban centers trial limited-run formulations for consumer feedback before scaled launch.
Veterinarians capture the steepest margin tier; Pet Owners drive absolute volume throughput.
Ingredient Type:
Protein sourcing economics and regulatory scrutiny intensity vary sharply across formulation philosophies.
- Meat-Based:Poultry, beef, and fish meal formulations dominate AAFCO-compliant complete diets, with rendering infrastructure anchoring Midwestern supply corridors. FDA Center for Veterinary Medicine oversight of facility sanitation and ingredient traceability elevates compliance costs for smaller manufacturers.
- Plant-Based:Pea protein, lentil, and chickpea formulations address sustainability-motivated owner segments in Pacific Coast states. Black soldier fly larvae and precision fermentation proteins are emerging as novel inputs requiring novel regulatory pathways.
- Grain-Free:Legume-substituted formulations face FDA investigation into dilated cardiomyopathy correlations, compressing retail shelf space allocation.
- Organic:USDA Organic certification restricts synthetic additive use and elevates ingredient procurement costs for niche positioning.
Meat-Based commands the largest production footprint; Plant-Based is climbing the fastest.
Distribution Channel:
Fulfillment infrastructure investments reflect divergent customer acquisition economics and inventory velocity requirements.
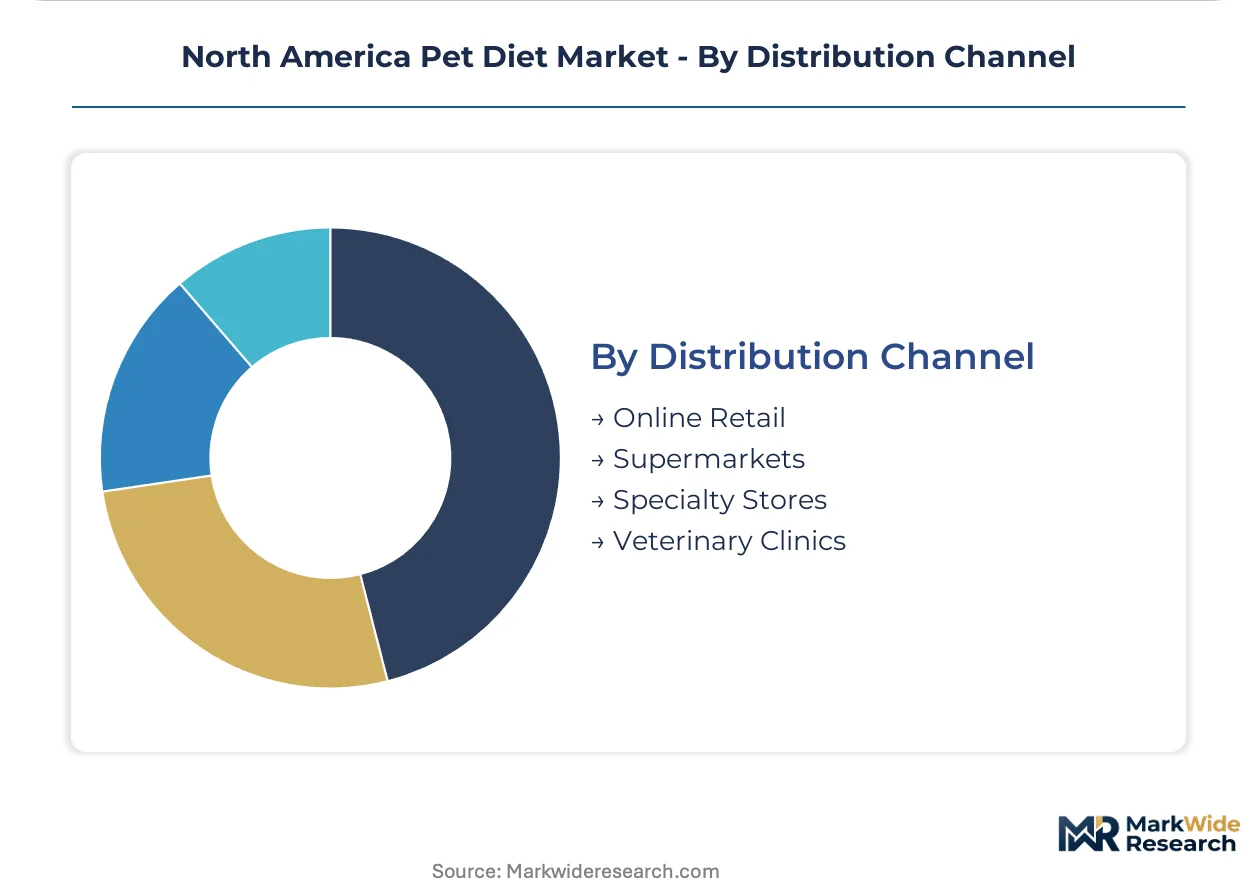
- Online Retail:Direct-to-consumer platforms and third-party marketplaces capture subscription revenue with personalized portioning algorithms. Texas and Florida urban corridors show highest auto-ship penetration for premium and super-premium tiers.
- Supermarkets:Mass retail chains in California and Texas metropolitan areas optimize shelf space for high-velocity dry food SKUs with trade promotion dependency.
- Specialty Stores:Independent pet retailers curate premium assortments with staff consultation services that justify price positioning.
- Veterinary Clinics:Prescription diet fulfillment through licensed practitioners captures therapeutic segment spending with clinical credibility endorsement.
Supermarkets retain the widest geographic footprint; Online Retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Midwestern rendering infrastructure anchors protein supply for North American pet diet manufacturing, with Kansas and Nebraska poultry meal processing corridors feeding extrusion plants across the continent. This feedstock geography shapes where formulation capacity concentrates and how brands configure cross-border production strategies.
United States
Millennial pet humanization in Texas and Florida metropolitan corridors drives subscription auto-ship adoption for premium tiers. FDA Center for Veterinary Medicine facility inspections create compliance bottlenecks extending new product approval timelines. Midwestern extrusion clusters in Kansas and Iowa leverage captive rendering access to insulate margin structures from commodity volatility.
Canada
Pacific Coast sustainability-motivated owners in British Columbia and Alberta accelerate plant-based formulation trial rates. Canadian Food Inspection Agency dual-compliance requirements create tariff-advantaged production pathways for US brands seeking European export certification. Ontario co-manufacturing corridors near Toronto concentrate CFIA-registered capacity for cross-border fulfillment.
Mexico
Middle-class pet ownership expansion in Mexico City and Monterrey metropolitan areas drives mass-market dry food volume procurement. Federal Commission for the Protection against Sanitary Risk (COFEPRIS) regulatory alignment with FDA standards facilitates integrated North American supply chains. Northern border states concentrate maize and poultry byproduct sourcing for cost-competitive kibble production.
North America Pet Diet Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue precision fermentation and alternative protein niches to bypass legacy rendering economics. The market structures around three concentration nodes: multinational CPG conglomerates with veterinary channel control, mid-tier private labels dependent on co-manufacturing partnerships, and specialty challengers leveraging direct-to-consumer subscription models. Dominant competitive moves include backward integration into protein rendering infrastructure and geographic expansion through Canadian tariff-advantaged production platforms.
Within the multinational tier, Mars Incorporated and Nestlé Purina exemplify scale-driven players with captive supply chain control, while Hill's Pet Nutrition occupies a position emphasizing clinical credibility through prescription diet authorization. These three entities anchor the competitive structure by representing divergent strategic archetypes: diversified CPG integration, veterinary channel exclusivity, and therapeutic formulation R&D partnership models respectively.
| Leading Market Players |
|---|
| Mars Incorporated |
| Nestlé Purina |
| Hill's Pet Nutrition |
| The J.M. Smucker Company |
| Blue Buffalo |
| Diamond Pet Foods |
| General Mills |
| Colgate-Palmolive Company |
| Champion Petfoods |
| Others |
Pricing and Supply Chain Analysis
Millennial subscription auto-ship adoption in Texas and Florida corridors forces manufacturers to absorb last-mile fulfillment costs, compressing gross margins and accelerating backward integration into captive rendering infrastructure to recoup pricing power.
Pricing Analysis
Veterinary channel bundling of prescription authorization with clinic inventory fulfillment anchors the highest pricing tier, while unbundled direct-to-consumer subscriptions compete on convenience premiums. Three-tier pricing structure across premium, standard, and economy levels stratifies by ingredient provenance claims and clinical endorsement depth. Cost compression in mass-market dry food is intensifying because trade promotion effectiveness is deteriorating against digital-native challenger brands. Price sensitivity concentrates among mass retail procurement teams in California and Texas metropolitan clusters, whereas Pacific Coast sustainability-motivated owners accept substantial premiums for novel protein and plant-based positioning.
Supply Chain Analysis
Single-source vulnerability sits with Midwestern poultry rendering corridors in Kansas and Nebraska, where captive meal production feeds extrusion plants across the continent. The North American pet diet supply chain draws from US protein rendering infrastructure, Canadian CFIA-registered co-manufacturing platforms, and Mexican maize and poultry byproduct sourcing in northern border states. Tariff exposure threatens cross-border production economics as US brands seek shelter through Canadian facilities. Distribution runs through veterinary clinic fulfillment partnerships, mass retail chains, and direct-to-consumer auto-ship platforms with divergent inventory velocity requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race: control over protein rendering infrastructure determines margin defense against input cost volatility and secures supply chain stability across Midwestern processing corridors.
For Market Incumbents: Lock in veterinary channel exclusivity through teaching hospital R&D partnerships and prescription diet authorization workflows before precision fermentation challengers establish clinical credibility. Expand captive rendering capacity in Kansas and Nebraska corridors to insulate margin structures from agricultural commodity swings. Defend against insect protein and cell-cultured novel ingredient entrants by accelerating FDA approval timelines for legacy therapeutic formulations. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the most penetrable route for precision fermentation and plant-based challengers to bypass mass retail slotting fee barriers. Target Pacific Coast sustainability-motivated owner segments in California and Washington state clusters with novel protein claims and slaughter-free positioning. Leverage Canadian co-manufacturing partnerships to access tariff-advantaged production and European export certification pathways. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier private labels possessing CFIA-registered Canadian production assets given FDA facility inspection backlogs extending approval timelines. Long-term viability favors manufacturers with backward integration into protein rendering and veterinary channel control. Watch FDA modernization rule implementation on traceability requirements as the inflection signal for ERP modernization investment cycles and consolidation pressure on capital-constrained challengers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Protein Rendering | Captive poultry and fish meal production insulates margin structures from commodity volatility in Midwestern corridors. |
| Veterinary Channel Exclusivity Expansion | Prescription diet authorization through teaching hospital networks locks in recurring revenue with clinical credibility endorsement. |
| Canadian Co-Manufacturing Scale-Up | CFIA-registered facilities provide US brands tariff shelter and European export certification access. |
| Precision Fermentation Protein Launch | Bioreactor-produced cultivated chicken and fish proteins command 40-60 percent price premiums in California and New York metropolitan markets. |
| Direct-to-Consumer Subscription Buildout | Auto-ship platforms bypass mass retail trade promotion dependency and capture millennial convenience premiums in Texas and Florida urban corridors. |
Research Methodology
Independent corroboration across FDA Center for Veterinary Medicine facility inspection records, AAFCO model regulation filings, and Canadian Food Inspection Agency registration databases underwrites the qualitative findings. Primary interviews with veterinary nutritionist PhDs, pet food formulation directors, procurement leads at Midwestern rendering facilities, and clinic inventory managers at teaching hospital networks combined with secondary validation from SEC 10-K filings, customs/trade data, and Nielsen retail audit records. Bottom-up capacity modeling and top-down demand estimation triangulate volume and value outputs.
Comparable-period anchoring to historical AAFCO nutrient profile modernization cycles and veterinary channel expansion phases structured the forecast window across the analysis window. Segmentation dimensions modeled include product type, ingredient sourcing philosophy, distribution channel, and end-user purchasing authority. CAGRs were derived from elasticity-adjusted demand curves and capacity-constrained supply assumptions. Industry-specific forecast inputs incorporated FDA approval timeline distributions and subscription auto-ship adoption velocity curves.
Inputs from primary stakeholder interviews and regulatory filing databases were available through the study window; gaps in real-time proprietary subscription platform transaction data introduce uncertainty bands around direct-to-consumer channel share estimates. Forecasts reflect assumptions on regulatory modernization rule implementation pace and protein rendering capacity expansion schedules. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Dog Dental Chews Market
Pet Care Products
Dog Life Jacket Market
Pet Care Products
Dog Collars Market
Pet Care Products
Animal Bedding Products Market
Pet Care Products
Europe Organic Pet Food for Cats and Dogs Market
Pet Care Products
Dog Bowl Market
Pet Care Products
Cat Food Toppers Market
Pet Care Products
Dog Clothing and Accessories Market
Pet Care Products
Pet Clean-Up and Odor-Control Products Market
Pet Care Products
Cat Accessories Market
Pet Care Products
Pet Beds Market
Pet Care Products
South Korea Organic and Natural Pet Food Market
Pet Care Products
DTC Pet Food Market
Pet Care Products
Australia Pet Food Market
Pet Care Products
UAE Cat Food Market
Pet Care Products
Pet Tag Market