
 Global Shampoo Bars Market | 2026-2036
Global Shampoo Bars Market Size, Share, and Industry Trends Forecast 2026-2036
Global Shampoo Bars Market Outlook
Subscription-based replenishment programs is broadening how shampoo bars move from trial to repeat purchase. Lush Retail Ltd. leverages its direct-to-consumer subscription infrastructure to sustain high retention rates among eco-conscious buyers. L'Oréal S.A. anchors its solid haircare portfolio through specialty retail partnerships that control premium shelf positioning. Ethique Limited competes through concentrated product specialization in plastic-free formulations, while HiBAR, Inc. differentiates via salon-grade performance claims that extend its addressable base beyond environmental advocates.
Shampoo bars are solid surfactant-based cleansing formulations, typically containing sodium cocoyl isethionate or sodium lauryl sulfoacetate as primary active ingredients, manufactured through cold-press or melt-and-pour processes that eliminate water content and reduce shipping weight. Their commercial purpose centers on delivering hair cleansing functionality without liquid packaging, addressing both logistics efficiency and post-consumer waste reduction objectives. Organic and sulfate-free product types lead current volume, though color-protecting variants command disproportionate margin pools due to ingredient complexity and professional channel positioning. Online retail channels exhibit the fastest expansion trajectory, while specialty stores retain outsized influence on brand discovery and premium pricing acceptance among luxury buyer segments.
The EU Green Deal and REACH frameworks in Europe, FDA cosmetic labeling requirements in the United States, and China's GB standards for personal care products collectively shape formulation transparency, ingredient disclosure, and market access conditions for shampoo bar manufacturers. EMA and ECHA guidelines on preservative restrictions and allergen labeling directly influence R&D allocation toward natural stabilizer systems. Stakeholders must monitor how divergent national implementation timelines for packaging-free retail regulations will reshape channel strategy and geographic prioritization decisions.
Market Dynamics
Corporate sustainability mandates from hospitality chains and EU packaging waste directives are forcing rapid reconfiguration of personal care supply chains toward solid-format alternatives.
Growth Catalysts
- EU Green Deal packaging directives:Binding reduction targets for single-use plastics accelerate reformulation investments across European personal care manufacturers.
- Hotel amenity procurement:Marriott, Hilton, and independent boutique chains consolidate purchasing around solid formats to meet Scope 3 emissions pledges.
- Sodium cocoyl isethionate availability:Expanded production capacity for this mild surfactant in Southeast Asia reduces input cost volatility for bar formulators.
Market Restraints
- Preservative system limitations:ECHA restrictions on phenoxyethanol and formaldehyde-releasing compounds force expensive natural stabilizer R&D cycles.
- Coconut oil price volatility:Weather-driven supply disruptions in Indonesia and the Philippines compress margins for cold-press manufacturers dependent on this base oil.
- Waterless formulation learning curve:Consumer adaptation to application techniques differs sharply from liquid shampoo habits, slowing repeat purchase velocity in trial-heavy segments.
Strategic Opportunities
- India's urban refill infrastructure:Mumbai and Bangalore retail networks demonstrate scalable distribution models for unpackaged personal care in emerging middle-class segments.
- Color-protecting variant expansion:Professional salon channels in Germany and France accept premium positioning for specialized bars targeting treated hair.
- Subscription platform integration:Direct-to-consumer replenishment models bypass shelf-space competition and capture lifetime value from eco-conscious households.
Industry Challenges
- Formulation chemist scarcity:Talent pipelines for anhydrous surfactant systems lag behind liquid cosmetic chemistry programs at European technical universities.
- Multi-jurisdictional labeling compliance:Divergent FDA, REACH, and GB standards for allergen disclosure force SKU fragmentation and inventory complexity.
- Cold-chain logistics reconfiguration:Melt-and-pour manufacturing requires temperature-controlled transport that conflicts with carbon-neutral shipping pledges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Shampoo Bars Market |
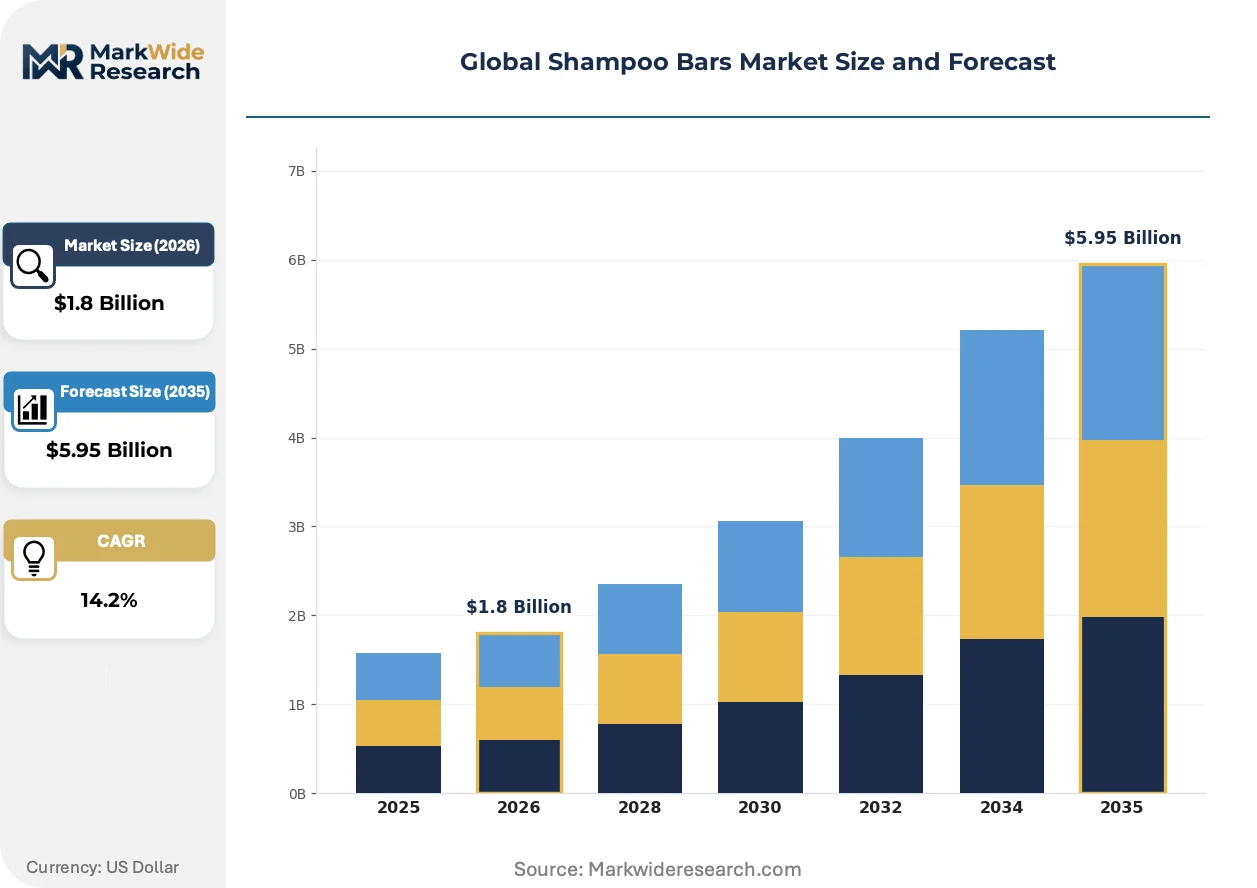
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Sulfate-Free, Fragrance-Free, Color-Protecting Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Salons Target Consumer: Eco-Conscious Consumers, Luxury Buyers, Students, Professionals Formulation: Moisturizing, Herbal, Volumizing, Anti-Dandruff |
| Companies Covered | Lush Retail Ltd., L'Oréal S.A., The Procter and Gamble Company, Ethique Limited, Shiseido Company Limited, L'OCCITANE Group, grüum Europe Ltd., HiBAR, Inc., Davines S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Shampoo Bars Market Strategic Shifts
Automation of manufacturing processes and tightening regulatory disclosure requirements are compressing product development cycles while reshaping how brands reach environmentally motivated consumers.
Supercritical CO2 extraction technology is automating the concentration of botanical actives for bar formulations. Premium manufacturers in Switzerland and France deploy these systems to standardize ingredient potency previously subject to harvest variability. This precision is compressing quality assurance timelines from months to weeks.
REACH authorization requirements for synthetic musks and certain UV filters are forcing reformulation of fragrance and protection-oriented bars. The European Chemicals Agency's 2024 updated candidate list expands testing obligations for imported personal care products. German and Dutch formulators are accelerating partnerships with natural fragrance houses to preempt compliance disruptions.
Direct-to-consumer sampling programs are displacing traditional retail discovery for shampoo bar trial. Subscription boxes and hotel amenity partnerships expose travelers to solid formats during stays, converting them to home purchase. This pattern concentrates in urban Germany and Scandinavian markets where sustainability credentialing drives purchase decisions.
Global Shampoo Bars Market Segmentation
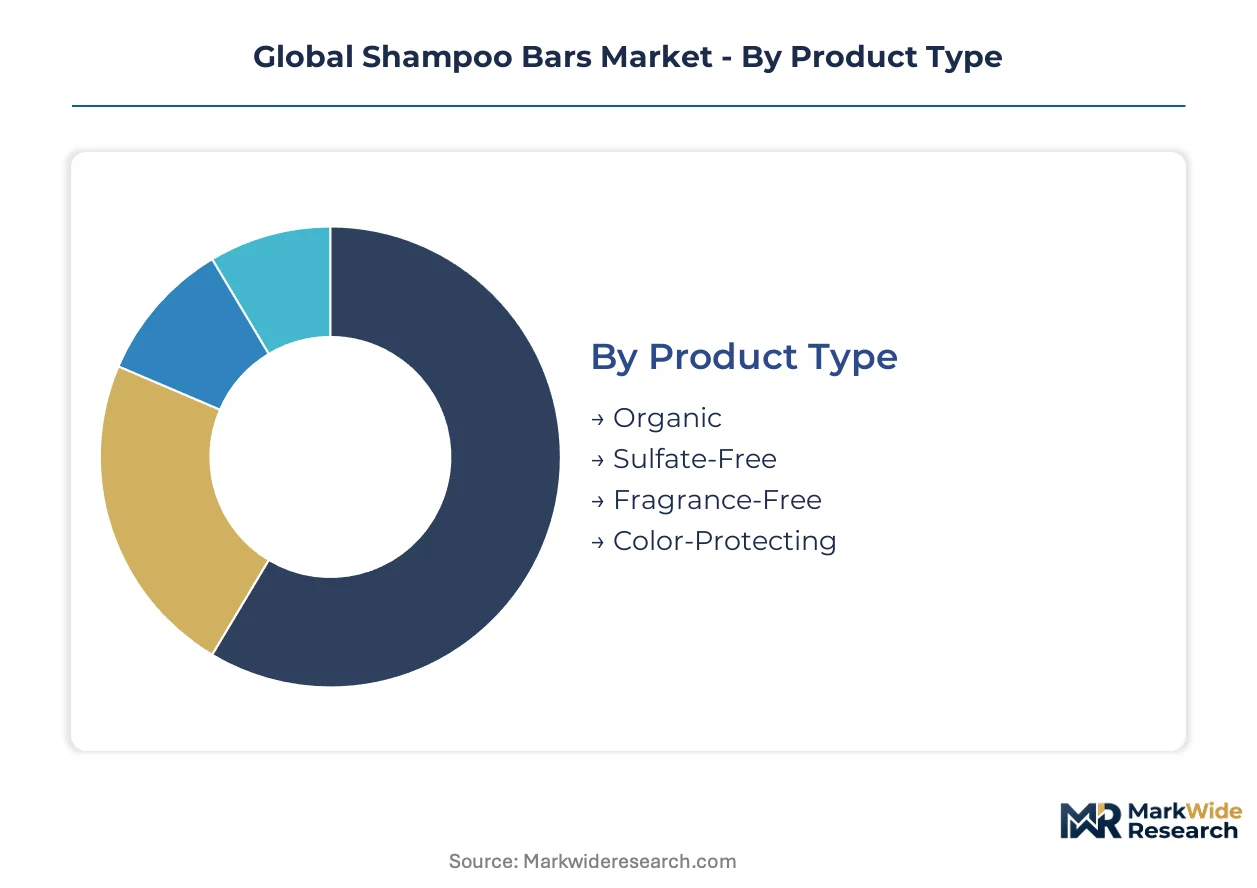
Shampoo bar purchasing decisions split across formulation chemistry, retail access patterns, and consumer identity markers. Manufacturers must align R&D investment and channel partnerships with the specific technical and behavioral segments where margin pools concentrate.
Product Type:
Ingredient certification and chemical exclusion criteria define how consumers navigate product selection and price acceptance.
- Organic:Formulations rely on certified agricultural inputs and restricted synthetic additive lists. Demand clusters in Germany and Scandinavian urban centers where retail certification infrastructure validates premium positioning.
- Sulfate-Free:Bars substitute sodium cocoyl isethionate or sodium lauryl sulfoacetate for traditional surfactants. Curly and color-treated hair specialists in France and US coastal metros drive repeat purchase velocity for this specification.
- Fragrance-Free:Elimination of synthetic and natural scent compounds serves dermatological sensitivity and workplace neutrality requirements. Hospital procurement and allergy-prone households in Switzerland and the Netherlands sustain this niche.
- Color-Protecting:UV filter integration and pH buffering systems target professional salon channels. German colorists command the steepest price premiums for bars demonstrating measurable fade reduction on treated hair.
Mature deployment sits with Sulfate-Free. Newer deployment is concentrated in Color-Protecting.
Distribution Channel:
Channel selection determines discovery mechanics, pricing authority, and consumer education burden for solid-format unfamiliarity.
- Online Retail:Direct-to-consumer platforms and marketplace listings bypass shelf-space competition and enable subscription replenishment. Urban German and UK households with established eco-conscious purchasing habits convert most efficiently through this channel.
- Specialty Stores:Curated assortments in zero-waste shops and natural beauty retailers provide tactile trial and staff consultation. French and Italian boutique networks sustain premium positioning through controlled brand adjacencies.
- Supermarkets:Mass-market shelf placement demands formulation cost compression and packaging standardization. Price-sensitive segments in Spain and Poland drive volume through this access point.
- Salons:Professional endorsement and in-chair demonstration convert clients to home-use purchase. German and French color specialists anchor the highest-margin segment through technical credibility transfer.
Volume concentrates in Supermarkets. Margin expansion runs through Salons.
Target Consumer:
Consumer self-identification shapes willingness to absorb price premiums and tolerate application learning curves.
- Eco-Conscious Consumers:Plastic-elimination and carbon-footprint reduction motivate purchase regardless of price premium. German refill infrastructure and Scandinavian retail networks serve this segment with concentrated efficiency.
- Luxury Buyers:Premium fragrance, packaging design, and brand heritage drive selection. Paris and Milan specialty retail channels capture this demand through controlled scarcity and aesthetic differentiation.
- Students:Compact dorm storage and travel convenience prioritize portability over performance specifications. UK university towns and Dutch student housing clusters show concentrated trial behavior.
- Professionals:Time-compressed routines and gym bag portability favor solid formats with rapid lather development. London and Frankfurt business districts sustain subscription replenishment for this segment.
Established loyalty sits with Eco-Conscious Consumers. Fastest conversion velocity appears among Professionals.
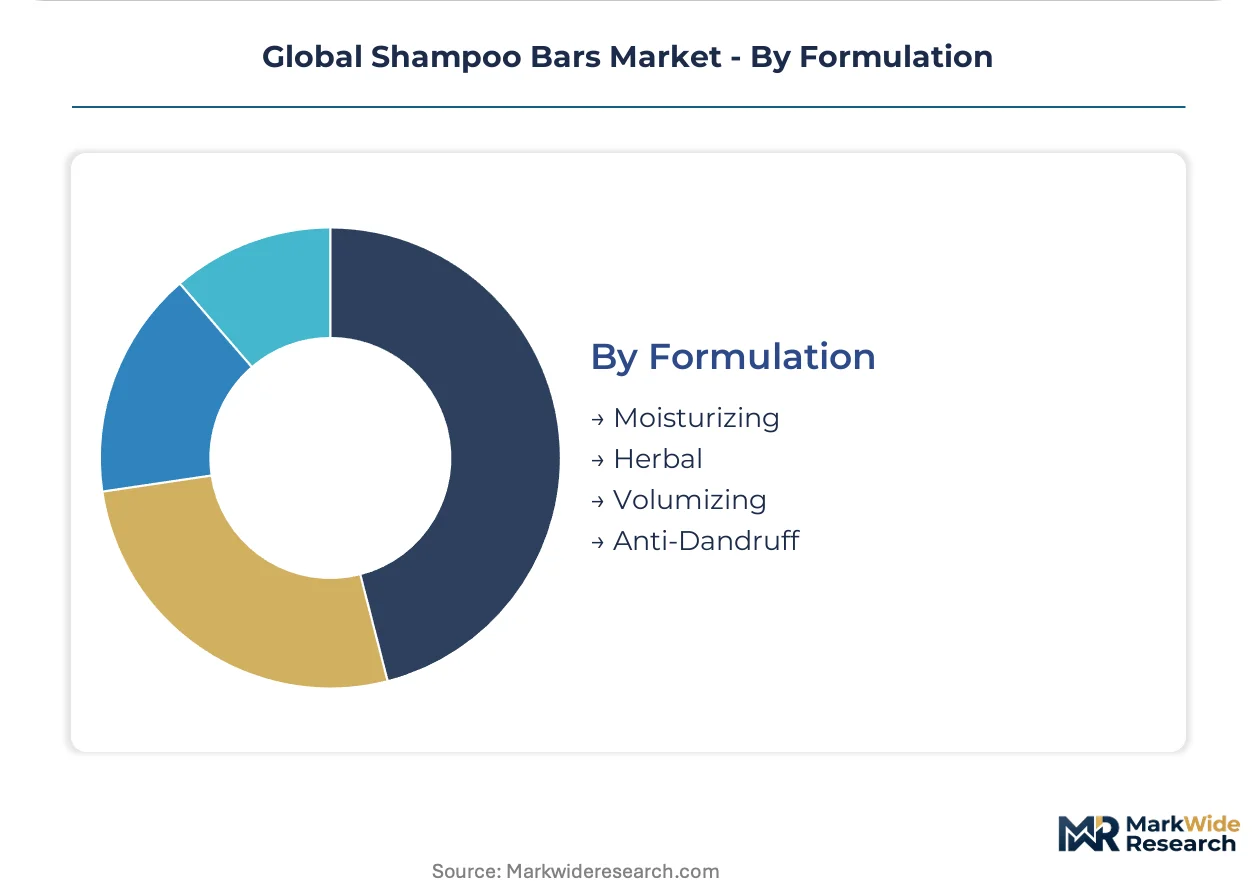
Formulation:
Functional claim specificity determines R&D allocation and clinical substantiation requirements for regulatory defense.
- Moisturizing:High glycerin and butter content targets dry and damaged hair restoration. Cold-press manufacturers in Indonesia and the Philippines leverage local coconut oil access for cost-advantaged production.
- Herbal:Botanical extract inclusion requires standardization investment to manage harvest variability. Swiss and French supercritical CO2 extraction adopters compress quality assurance timelines for this specification.
- Volumizing:Lightweight surfactant ratios and residue-minimizing systems target fine hair density concerns. Salon channels in Germany and the US accept technical performance claims with professional endorsement.
- Anti-Dandruff:Active ingredient inclusion triggers pharmaceutical or cosmetic classification depending on concentration. FDA and EMA borderline determinations force SKU fragmentation for this claim category.
Technical maturity centers on Moisturizing. Regulatory complexity peaks with Anti-Dandruff.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
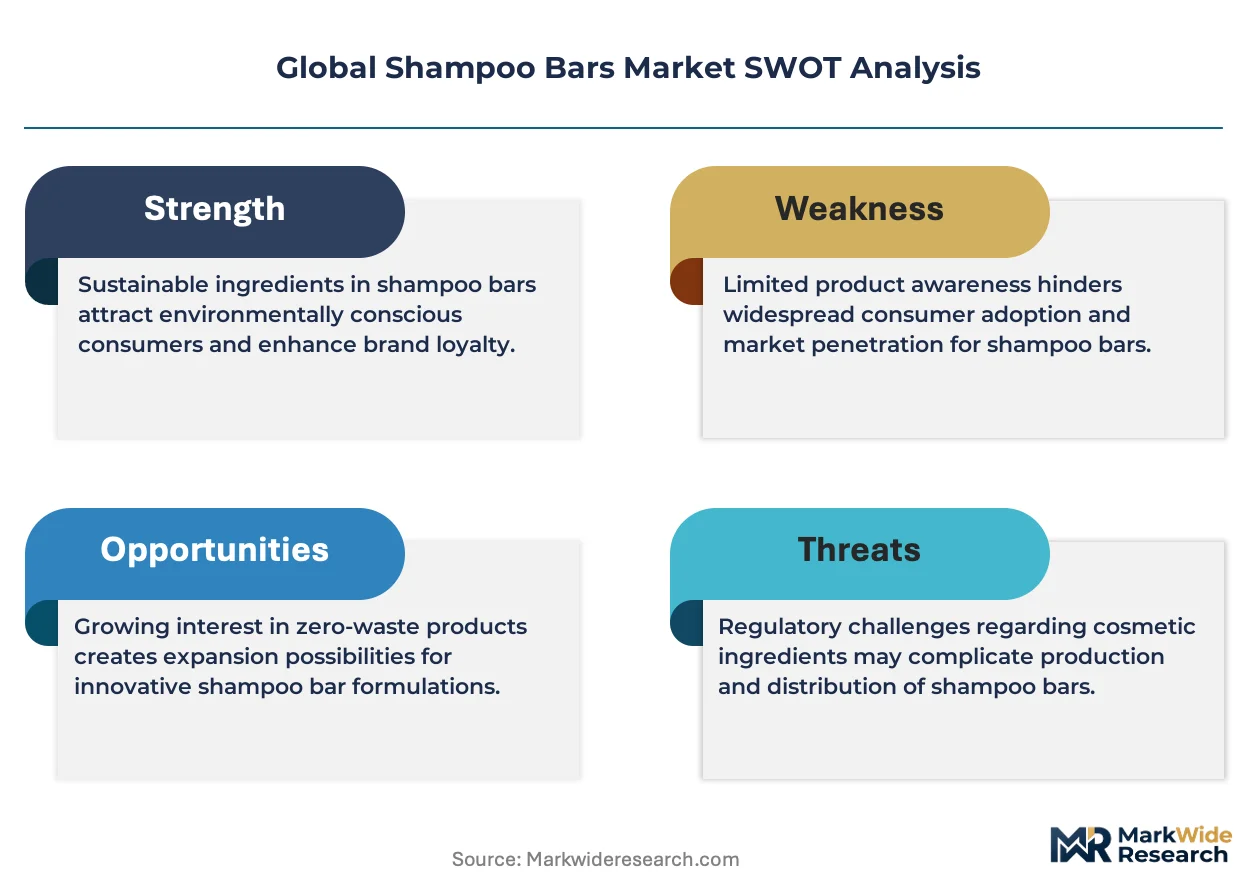
Production concentrates in Southeast Asian surfactant manufacturing zones while consumption clusters in European urban centers with established refill retail infrastructure. Germany and Scandinavian cities drive premium adoption through sustainability credentialing. Emerging trial behavior in Indian metros and US coastal cities is reshaping geographic prioritization for brand expansion.
Germany
Refill retail infrastructure and green consumer purchasing power create the densest adoption cluster for solid-format personal care. The EU Green Deal's packaging waste directives accelerate manufacturer reformulation investments targeting German distribution channels. Berlin and Hamburg anchor concentrated demand for sulfate-free and color-protecting variants through zero-waste shop networks and professional salon channels.
United States
Curly and color-treated hair specialists in coastal metros drive repeat purchase velocity for sulfate-free specifications. FDA cosmetic labeling requirements enforce ingredient disclosure standards that influence formulation transparency investments. New York and Los Angeles sustain premium positioning through specialty retail partnerships and direct-to-consumer subscription platforms targeting eco-conscious households.
France
Professional salon channels and boutique retail networks validate premium pricing for aesthetic-differentiated solid haircare. ANSM fragrance allergen regulations push reformulation toward natural stabilizer systems and botanical extract standardization. Paris and Lyon concentrate luxury buyer demand through controlled scarcity distribution and heritage brand positioning in specialty beauty retailers.
India
Mumbai and Bangalore retail networks demonstrate scalable distribution models for unpackaged personal care in emerging middle-class segments. BIS standards for personal care products shape local manufacturing compliance requirements for domestic and imported bar formulations. Maharashtra and Karnataka industrial zones host expanding sodium cocoyl isethionate production capacity serving regional formulators.
United Kingdom
University towns and dense urban housing sustain concentrated trial behavior among students prioritizing compact storage and travel convenience. REACH framework implementation drives alignment with EU-wide preservative restriction and allergen labeling obligations. London anchors subscription platform adoption and professional channel positioning for time-compressed business district consumers.
Global Shampoo Bars Market Competitive Environment
Capital-heavy producers compete with asset-light designers across distinct manufacturing and brand-building specializations. The vendor base spans multinational personal care conglomerates with captive surfactant supply, mid-scale specialty formulators, and direct-to-consumer pure-plays. Three archetypes dominate: heritage beauty houses leveraging retail scale, plastic-free specialists concentrating R&D in anhydrous systems, and salon-grade performance brands extending beyond environmental advocates. Competitive moves center on specialty retail partnership consolidation and subscription infrastructure acquisition to capture lifetime customer value.
Within the heritage beauty house tier, L'Oréal S.A. and The Procter and Gamble Company occupy positions defined by retail scale and portfolio breadth. Among plastic-free specialists, Ethique Limited exemplifies concentrated product specialization, while HiBAR, Inc. anchors salon-grade performance claims. Lush Retail Ltd. sits within the direct-to-consumer infrastructure archetype, leveraging subscription retention systems and tactile retail discovery formats.
| Leading Market Players |
|---|
| Lush Retail Ltd. |
| L'Oréal S.A. |
| The Procter and Gamble Company |
| Ethique Limited |
| Shiseido Company Limited |
| L'OCCITANE Group |
| grüum Europe Ltd. |
| HiBAR, Inc. |
| Davines S.p.A. |
| Others |
Value Chain & Pricing Dynamics
Premium-mid-economy pricing differentiation between salon-grade color-protecting bars and mass-market supermarket offerings manifests in divergent supply chain configurations across Germany, Indonesia, and the Philippines. Certification tiers for organic and sulfate-free formulations command upstream investment in supercritical CO2 extraction systems and cold-press manufacturing, while commodity segments tolerate melt-and-pour processes with higher coconut oil input volatility.
Pricing Analysis
Margin tightening in mass-market tiers reflects coconut oil price volatility and supermarket buyer consolidation, while salon channels sustain premium positioning through performance substantiation. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and professional endorsement depth. Cost compression accelerates in supermarket segments as private-label entrants absorb shelf space. Students and price-sensitive households in Spain and Poland exhibit highest elasticity, whereas German luxury buyers and color specialists accept steep premiums for fade-reduction claims.
Supply Chain Analysis
REACH and BIS certification requirements gate supplier qualification for European and Indian market access, forcing documentation investment upstream. Manufacturing concentrates in Indonesia, the Philippines, and Maharashtra industrial zones where sodium cocoyl isethionate capacity expansion reduces surfactant cost volatility. Raw material flows draw from Southeast Asian coconut plantations, Swiss supercritical extraction equipment, and German specialty chemical distributors. Single-source vulnerability sits with Indonesian coconut oil harvests exposed to El Niño disruption. Distribution runs through direct-to-consumer subscription platforms, zero-waste specialty retailers, and hospitality procurement consolidators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration momentum is accelerating as manufacturers pursue captive sodium cocoyl isethionate production and subscription platform ownership to defend margin pools against input volatility and channel disintermediation.
For Market Incumbents: Anchor salon channel exclusivity through professional education programs and colorist certification partnerships that preempt HiBAR's performance positioning. Acquire or build cold-press manufacturing in Maharashtra to reduce coconut oil exposure and BIS compliance friction for Indian expansion. Defend against direct-to-consumer pure-plays by consolidating subscription infrastructure through hospitality amenity partnerships that convert trial to home purchase. For New Entrants and Emerging Players: Boutique hotel chains represent the most penetrable channel partner type for bypassing saturated retail shelf competition and capturing business traveler trial. Target India's emerging middle-class segments in Bangalore and Mumbai where unpackaged retail infrastructure scales without legacy liquid-format incumbent presence. Pursue white-space in fragrance-free dermatological positioning for Swiss and Dutch hospital procurement channels underserved by current specialty formulators. For Investors and Strategic Acquirers: Re-rating potential sits with plastic-free specialists possessing anhydrous formulation IP and established subscription retention systems given EU Green Deal packaging directive acceleration. Long-term viability favors targets with backward integration into surfactant manufacturing and multi-jurisdictional labeling compliance infrastructure. Monitor ECHA preservative restriction updates as inflection signal for natural stabilizer R&D valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Surfactant Manufacturing | Captive sodium cocoyl isethionate production insulates margin from Southeast Asian supply volatility. |
| Subscription Platform Acquisition | Lush's direct-to-consumer retention infrastructure demonstrates lifetime value capture from eco-conscious households. |
| Professional Salon Channel Partnership | German colorist endorsement transfers technical credibility that justifies premium positioning against mass-market alternatives. |
| Zero-Waste Retail Distribution Expansion | Berlin and Hamburg specialty networks validate organic certification premiums through controlled brand adjacencies. |
| Hotel Amenity Procurement Consolidation | Marriott and Hilton Scope 3 pledges convert traveler trial into sustained home-use subscription conversion. |
Study Parameters
Document review covered EU Green Deal implementation timelines, ECHA candidate list updates, FDA cosmetic labeling guidance, and BIS personal care standards, complemented by interviews with formulation chemists at European technical universities, procurement directors at hospitality chains, zero-waste retail buyers in Germany and France, and surfactant plant managers in Maharashtra. Secondary validation drew from customs trade data, SEC filings of listed personal care conglomerates, and REACH registration databases. Bottom-up channel volume estimates and top-down category spend analysis were triangulated against manufacturer capacity disclosures.
Historical volume trajectories were cross-referenced against panel input from industry stakeholders to model growth across the projection horizon. Segmentation dimensions included formulation chemistry, distribution channel, target consumer archetype, and geographic regulatory cluster. CAGRs were derived from elasticity-adjusted adoption curves incorporating subscription conversion rates and hospitality procurement shift assumptions. Industry-specific inputs captured sodium cocoyl isethionate capacity expansion timelines and refill retail infrastructure development in urban India.
Caveats apply where ECHA preservative restriction enforcement, El Niño-driven coconut oil supply disruption, or divergent national packaging-free retail regulation implementation could materially shift the outlook. Forecasts reflect assumptions about consumer adaptation to waterless application techniques and professional channel endorsement velocity. A model refresh is warranted upon material change in EU Green Deal binding target acceleration or major hospitality chain amenity format conversion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Rice Shampoo Bar Market
Beauty & Personal Care
Beauty Products Market
Beauty & Personal Care
Personal Care and Cosmetic Preservatives Market
Beauty & Personal Care
France Sustainable Personal Care Market
Beauty & Personal Care
Japan Beauty Fridges Market
Beauty & Personal Care
Personal Care Shower and Bath Market
Beauty & Personal Care
North America Beauty Devices Market
Beauty & Personal Care
Germany Beauty Industry Market
Beauty & Personal Care
Shaving Foam Market
Beauty & Personal Care
Lip Care Market
Beauty & Personal Care
United States Bath Soap Market
Beauty & Personal Care
Global Probiotic Cosmetic Products Market
Beauty & Personal Care
Leave-In Conditioner Market
Beauty & Personal Care
Europe Lip Care Products Market
Beauty & Personal Care
Facial Care Products Market
Beauty & Personal Care
Luxury Bath and Body Products Market