
 Global Shampoo Market | 2026-2036
Global Shampoo Market Size, Share, and Industry Trends Forecast 2026-2036
Global Shampoo Market Outlook
The shampoo category is pivoting on a widening gap between premium formulations and commodity refill packs. L'Oréal S.A. anchors its position through biotechnology-driven ingredient labs in France and Brazil. Procter & Gamble Company leverages mass-market distribution density across India and Nigeria. Unilever PLC competes via sustainability-certified supply chains that trace palm-derived surfactants to plantation level.
Shampoo comprises aqueous surfactant systems—typically sodium lauryl sulfate or gentler glucoside bases—combined with conditioning quaternary ammonium compounds, functional actives, and preservative buffers, manufactured through continuous hot-mix processes followed by rheological stabilization; its commercial purpose is to cleanse sebum and environmental particulates from hair and scalp while delivering secondary benefits such as volume or color retention. Conditioning variants occupy the largest volume share as consumers prioritize hair health over basic cleansing. E-commerce channels represent the fastest-growing distribution pathway, with subscription models capturing recurring revenue pools. Professional salon end users command the highest per-unit margins due to stylist recommendation authority and bulk institutional purchasing.
FDA cosmetic labeling requirements, EU REACH chemical registration mandates, and China's GB standards for cosmetic safety collectively determine which preservative systems and active ingredients gain market access across major economies. These frameworks push manufacturers toward biodegradable surfactants and away from formaldehyde-releasing preservatives. Stakeholders must monitor regulatory divergence between jurisdictions to avoid reformulation costs that erode margin structures.
Market Dynamics
Professional salon channels now drive premium formulation adoption as stylists prescribe specialized products, while EU REACH chemical registration and California's evolving disclosure rules force simultaneous reformulation across multiple jurisdictions.
Growth Catalysts
- Biotechnology-driven actives:Enzyme-based scalp treatments and fermented ingredient complexes attract consumers seeking clinically proven hair health outcomes beyond basic cleansing.
- China's urban premium shift:Tier-1 city consumers now integrate multi-step haircare routines, expanding addressable market for conditioning variants and treatment masques.
- E-commerce subscription models:Direct-to-consumer platforms capture recurring revenue pools through personalized refill cycles and algorithm-driven product matching.
Market Restraints
- Palm-derived surfactant volatility:RSPO-certified supply chains face price pressure from competing biofuel demand and Southeast Asian weather disruptions.
- Preservative system constraints:EU REACH restrictions on formaldehyde-releasing compounds force costly reformulation of legacy antimicrobial buffers.
- Professional channel concentration:Salon distributor consolidation in North America and Western Europe limits brand access to independent stylists.
Strategic Opportunities
- India's mass-market digitization:Vernacular-language e-commerce platforms unlock tier-2 and tier-3 city penetration for affordable sulfate-free variants.
- Waterless formulation expansion:Concentrated powder and solid bar formats reduce shipping costs and align with EU Green Deal packaging reduction targets.
- Scalp microbiome science:Prebiotic and postbiotic ingredient positioning opens clinical credibility gaps between cosmetic and dermatological product boundaries.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in natural preservation systems and rheology stabilization commands premium compensation and extends R&D timelines.
- Multi-jurisdiction compliance synchronization:Divergent FDA cosmetic labeling, EU REACH Annex XVII updates, and China's GB standard revisions create parallel testing requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Shampoo Market |
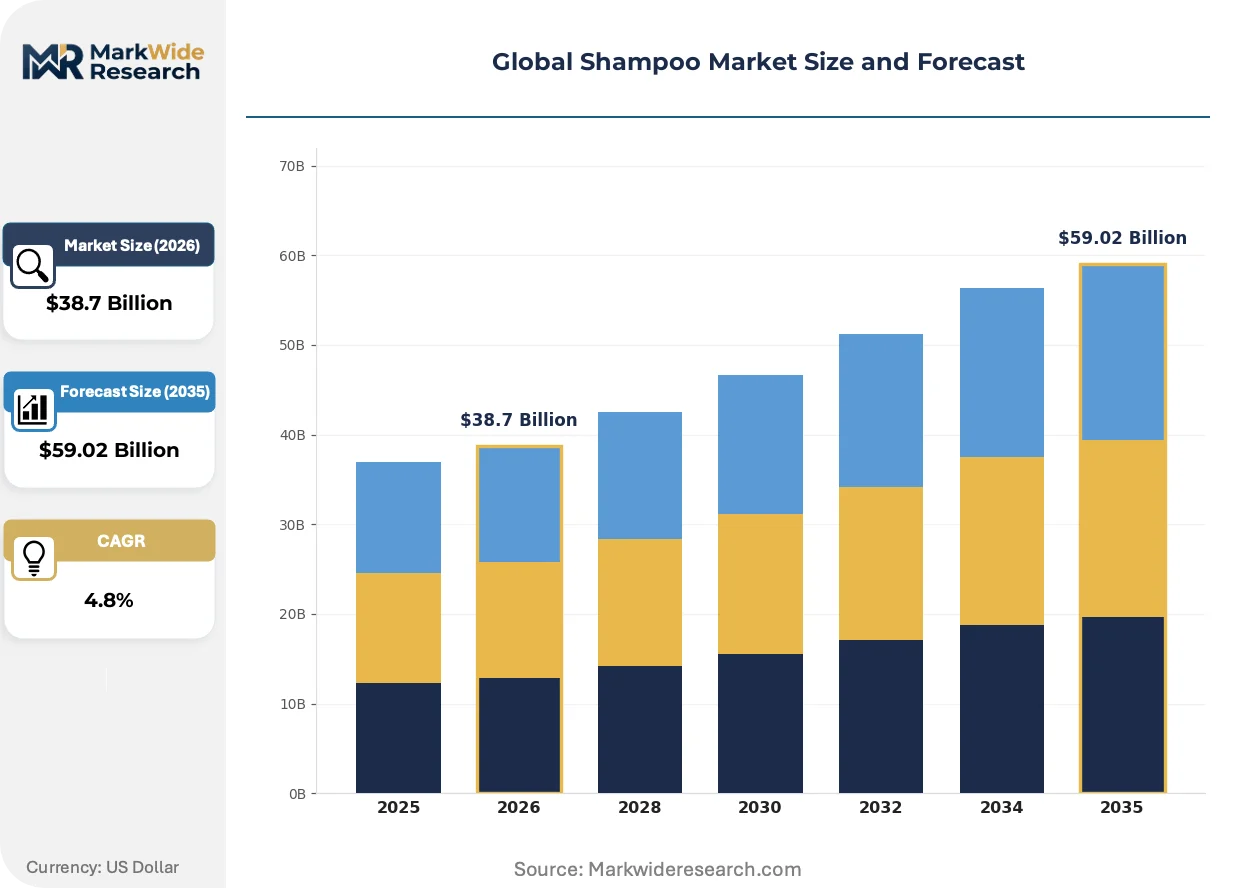
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $59.02 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conditioning, Anti-dandruff, Volumizing, Color Protection End User: Men, Women, Children, Professional Salons Distribution Channel: Supermarkets, E-commerce, Specialty Stores, Drugstores Price Tier: Premium, Mid-Range, Economy, Luxury |
| Companies Covered | Henkel AG & Co. KGaA, Kérastase, L'Oréal S.A., Shiseido Company, Limited, Olaplex, Procter & Gamble Company, Kao Corporation, Amorepacific Corporation, Unilever PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Shampoo Market Strategic Shifts
Formulation science and distribution architecture are converging to compress traditional brand hierarchies, with biotechnology and regulatory chemistry now determining competitive access rather than marketing spend alone.
Biotechnology-derived active ingredients—specifically fermented ceramides and enzymatic scalp exfoliants—are decentralizing R&D capability away from established multinational labs toward specialized biotech suppliers and contract manufacturers. Regional beauty brands in South Korea and Brazil now access clinically validated actives previously restricted to premium multinational portfolios. This capability diffusion is decentralizing ingredient innovation across mid-tier players who previously relied on commodity surfactant sourcing.
EU REACH Annex XVII restrictions on microplastic-containing rinse-off cosmetics entered full enforcement in 2023, mandating replacement of synthetic film-forming agents with biodegradable alternatives. Manufacturers serving European distribution must now validate biodegradability through OECD testing protocols or forfeit shelf placement. Conditioning and styling-adjacent shampoo variants face the steepest reformulation burden, with several major retailers now requiring third-party certification prior to listing approval.
Salon professionals increasingly prescribe take-home maintenance protocols tied to in-treatment services, compressing the traditional retail-salon boundary. Stylists in France and Japan now capture recurring product revenue through captive brand partnerships or white-label arrangements, displacing conventional wholesale distribution. This channel integration is most pronounced in premium urban clusters where appointment-based consultation builds sustained product adherence.
Global Shampoo Market Segmentation
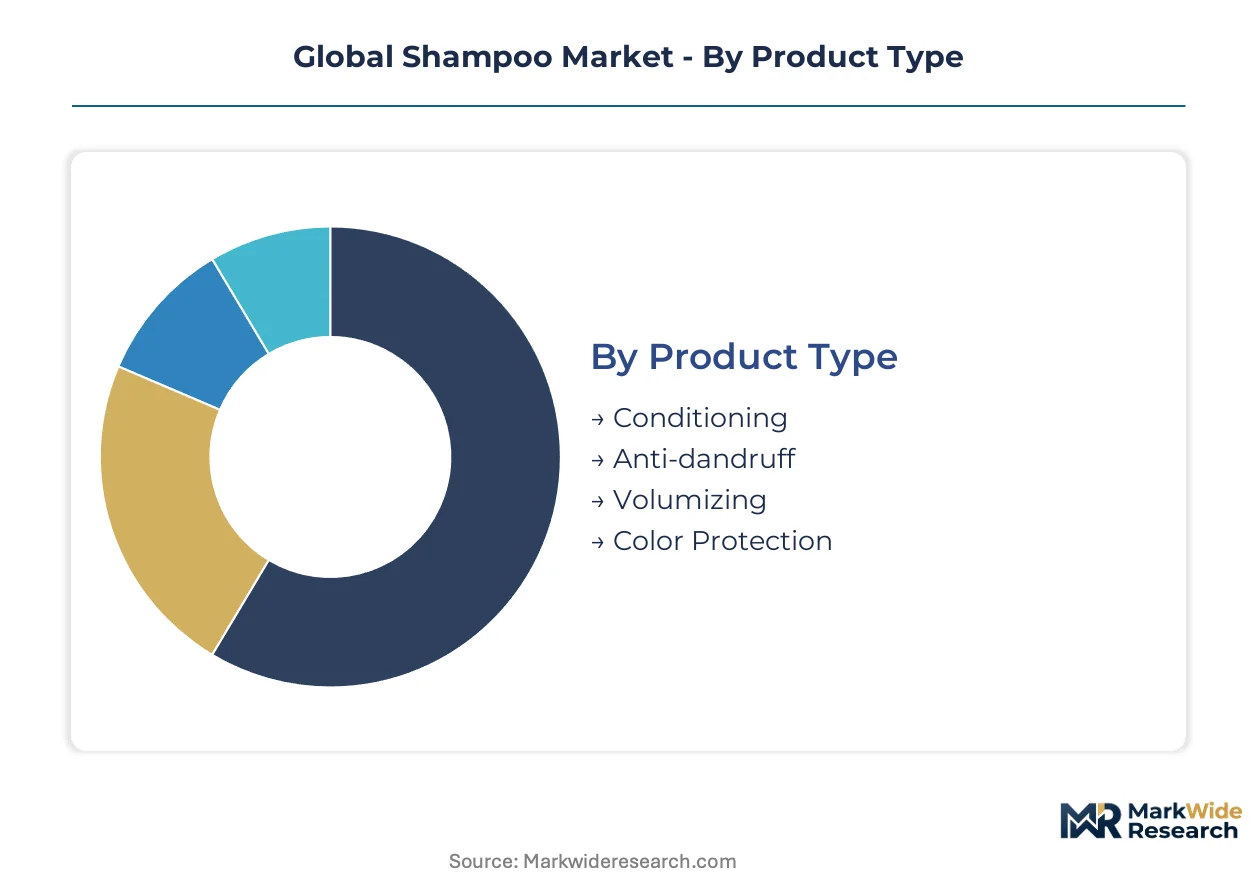
Shampoo market segmentation reveals divergent capital requirements across formulation complexity, channel infrastructure, and regulatory compliance. Manufacturers must align production scale with specific segment economics rather than pursuing uniform capacity expansion.
Product Type:
Capital intensity peaks with active-ingredient synthesis and clinical validation protocols, creating tiered barriers to entry across functional formulations.
- Conditioning:Quaternary ammonium compounds and silicone emulsions require precision rheology control in continuous hot-mix manufacturing. Professional salons in France and Japan prescribe conditioning variants as take-home protocols, locking in recurring revenue streams through stylist authority.
- Anti-dandruff:Pyrithione zinc and selenium sulfide actives demand pharmaceutical-grade GMP compliance and stability testing under FDA over-the-counter monograph standards. Clinical efficacy claims concentrate demand in Germany and South Korea where consumers prioritize dermatological credibility over basic cleansing.
- Volumizing:Lightweight polymer film-formers replace conditioning oils to achieve lift without residue.
- Color Protection:UV absorbers and pH-balanced surfactant systems prevent dye oxidation in treated hair.
Conditioning absorbs the bulk of installed capacity; anti-dandruff is expanding most quickly.
End User:
Customer-specific formulation drives divergent R&D priorities, with professional-grade products commanding specialized chemist allocation and salon channel investment.
- Women:Multi-step routine integration spans cleansing, conditioning, and treatment masques with ingredient complexity driving premium positioning. China's tier-1 cities anchor volume as urban consumers adopt Korean-influenced layered haircare regimens.
- Professional Salons:Bulk institutional purchasing and stylist prescription authority require dedicated salesforce deployment and education infrastructure. Captive brand partnerships in Italy and Brazil displace conventional wholesale distribution through revenue-sharing arrangements.
- Men:Simplified two-in-one formats dominate with convenience-oriented positioning.
- Children:Tear-free surfactant systems and allergen-free preservative buffers mandate pediatric safety testing.
Women's segments anchor revenue concentration; professional salons deliver steepest margin expansion.
Distribution Channel:
Channel selection determines working capital intensity, with inventory velocity and return logistics creating divergent cash conversion cycles.
- E-commerce:Direct-to-consumer platforms require algorithm-driven personalization engines and subscription fulfillment infrastructure. Vernacular-language interfaces unlock tier-2 and tier-3 penetration in India while reducing customer acquisition costs versus physical retail.
- Supermarkets:Mass-market shelf placement demands trade promotion budgets and packaging differentiation at point-of-purchase. Nigeria and Indonesia concentrate volume through modern grocery expansion in urban corridors.
- Specialty Stores:Curated assortment and trained staff support premium positioning and ingredient education.
- Drugstores:Pharmacist recommendation channels reinforce therapeutic claims for medicated variants.
Supermarkets retain the largest throughput base; e-commerce climbs the fastest on subscription model adoption.
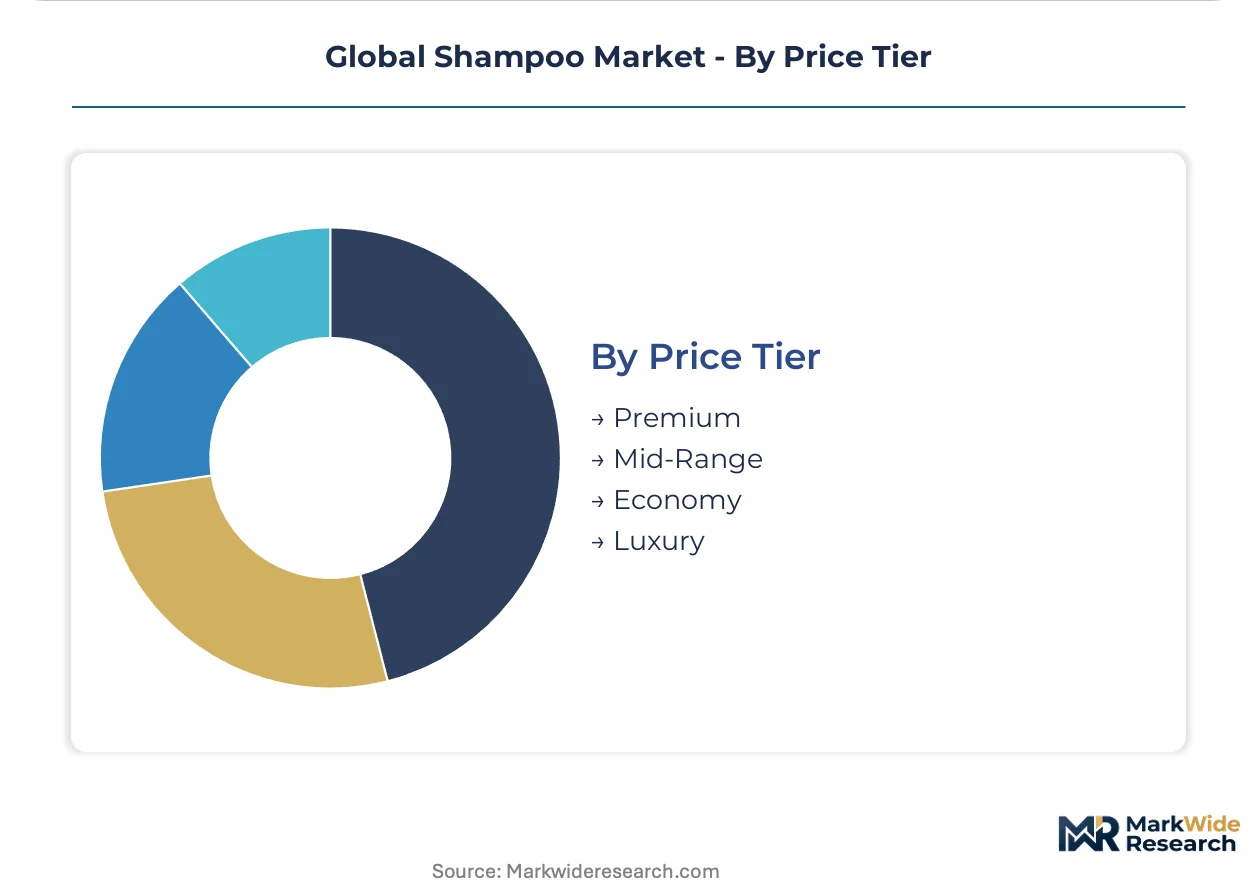
Price Tier:
Pricing architecture reflects ingredient sourcing depth, with biotechnology-derived actives and supply chain traceability commanding tier premiums.
- Premium:Fermented ceramides and scalp microbiome prebiotics require biotech supplier partnerships and clinical validation studies. EU REACH-compliant preservative systems and RSPO-certified surfactants add cost layers that mass-market formulations bypass.
- Luxury:Artisanal batch production and limited distribution through department stores and hotel amenities create scarcity positioning. Japanese consumers in Tokyo and Osaka drive regional concentration for ritual-oriented packaging and fragrance complexity.
- Mid-Range:Balanced surfactant performance with recognizable brand equity dominates volume.
- Economy:Commodity sulfates and bulk refill formats minimize per-unit cost for price-sensitive markets.
Premium tiers capture disproportionate margin contribution; luxury segments gain share fastest in Asia-Pacific urban clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors formulation demand as Chinese consumers adopt multi-step haircare routines. Stylists in Paris and Tokyo prescribe premium take-home protocols. Regulatory divergence between EU REACH, FDA cosmetic labeling, and China's GB standards forces parallel compliance investment.
United States
Salon distributor consolidation in California and New York limits independent stylist access while driving captive brand partnerships. FDA cosmetic labeling requirements and evolving state-level chemical disclosure rules in California reshape preservative system selection. Los Angeles and Manhattan concentrate premium service revenue through appointment-based consultation models.
Germany
Clinical efficacy claims concentrate demand for anti-dandruff variants where consumers prioritize dermatological credibility. EU REACH Annex XVII restrictions on formaldehyde-releasing compounds force reformulation of legacy antimicrobial buffers. Düsseldorf and Hamburg anchor professional channel distribution through specialized salon supply networks.
China
Tier-1 city consumers integrate Korean-influenced layered haircare regimens spanning cleansing, conditioning, and treatment masques. GB standards for cosmetic safety determine preservative system market access alongside dual carbon goals pushing biodegradable surfactant adoption. Shanghai and Beijing concentrate premium positioning through e-commerce subscription models and algorithm-driven personalization.
Japan
Ritual-oriented packaging and fragrance complexity drive luxury segment concentration in Tokyo and Osaka. METI standards align with EU REACH on microplastic-containing rinse-off cosmetics, mandating OECD-validated biodegradability. Kansai region manufacturing clusters supply fermented ceramide actives to regional beauty brands.
Brazil
Vernacular-language e-commerce platforms unlock tier-2 and tier-3 city penetration for affordable sulfate-free variants. ANVISA cosmetic regulations govern preservative approval timelines while RSPO-certified palm-derived surfactant sourcing faces price pressure from competing biofuel demand. São Paulo anchors mass-market distribution density through modern grocery expansion.
Global Shampoo Market Competitive Environment
Premium-margin players sit above commodity-margin players across biotechnology-driven active ingredient sourcing and supply chain traceability certification. The vendor base organizes into three tiers: multinational conglomerates with captive R&D infrastructure, regional specialists leveraging contract manufacturing flexibility, and biotech suppliers decentralizing clinically validated actives. Consolidation pressures concentrate among salon distributor networks while formulation chemist scarcity extends R&D timelines. Parallel compliance investment across FDA, EU REACH, and China's GB standards favors players with dedicated regulatory affairs capacity.
Among multinational conglomerates, L'Oréal S.A. and Unilever PLC exemplify divergent strategic positioning. The French S.A. anchors biotechnology-driven ingredient labs in France and Brazil. The British PLC competes via sustainability-certified supply chains tracing palm-derived surfactants to plantation level. Procter & Gamble Company represents mass-market distribution density across India and Nigeria. These three players occupy distinct archetype positions without direct overlap in capability investment.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Kérastase |
| L'Oréal S.A. |
| Shiseido Company, Limited |
| Olaplex |
| Procter & Gamble Company |
| Kao Corporation |
| Amorepacific Corporation |
| Unilever PLC |
| Others |
Value Chain & Pricing Dynamics
Captive surfactant synthesis in Southeast Asian plantation networks anchors both supply security and margin control for multinational formulators. This backward integration into RSPO-certified palm supply buffers against biofuel competition while supporting premium positioning through traceability certification.
Pricing Analysis
Outcome-based pricing tied to scalp health metrics anchors premium tier positioning. Three-tier pricing structure across premium, standard, and economy levels separates biotechnology-validated actives from commodity sulfates and bulk refill formats. Price differentiation rests on clinical validation depth and supply chain certification grade. Cost compression in economy tiers intensifies because vernacular-language e-commerce platforms compress customer acquisition expenses. Mass-market buyers in India's tier-2 cities exhibit highest price sensitivity; professional salon channels in Paris and Tokyo demonstrate lowest sensitivity due to stylist prescription authority.
Supply Chain Analysis
Formulation chemist scarcity in French and Brazilian biotechnology hubs constrains batch scale-up velocity for fermented active production. Manufacturing concentrates in China, Brazil, and Germany, with each feeding distinct regional regulatory clusters. Raw material dependencies center on palm-derived surfactants, quaternary ammonium conditioning agents, and preservative buffer systems. Single-source vulnerability runs through Southeast Asian oleochemical supply exposed to El Niño precipitation patterns. Distribution runs through salon supply networks in Western Europe, modern grocery in Nigeria and Indonesia, and algorithm-driven subscription platforms in China's tier-1 cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained: formulation chemist scarcity in natural preservation systems props pricing power across premium tiers by extending competitor R&D timelines.
For Market Incumbents: Cement biotechnology supplier partnerships in France and Brazil to lock in fermented ceramide access before capability diffusion accelerates. Expand captive salon distribution in Italy through revenue-sharing arrangements that displace wholesale intermediaries. Prioritize EU REACH compliance infrastructure to synchronize multi-jurisdiction product launches and avoid parallel testing delays. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the lowest customer acquisition cost route for sulfate-free variants in India's tier-2 and tier-3 cities. White-label scalp microbiome positioning creates entry white-space between cosmetic and dermatological boundaries. Target waterless powder and solid bar formats to bypass EU Green Deal packaging reduction compliance burdens incumbent liquid formulators face. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational conglomerates seeking biotechnology capability fill-ins. Five-to-ten year viability favors regional specialists with contract manufacturing flexibility and vernacular-language e-commerce infrastructure. Watch ANVISA approval timelines in Brazil as inflection signal for Latin American market access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Biotechnology Supplier Partnership | Fermented ceramide access locks in premium tier positioning against commodity competitors. |
| Salon Distribution Captivation | Revenue-sharing arrangements in France and Italy displace wholesale margin extraction. |
| Waterless Format Expansion | Powder and solid bar production aligns with EU Green Deal packaging reduction mandates. |
| Vernacular E-commerce Launch | Tier-2 and tier-3 Indian city penetration reduces customer acquisition costs versus physical retail. |
| Multi-jurisdiction Compliance Buildout | Parallel FDA, EU REACH, and GB standard testing infrastructure accelerates product launch velocity. |
Study Parameters
Independent corroboration across formulation chemists, salon supply distributors, and e-commerce platform operators underwrites the qualitative findings on channel dynamics. Primary interviews with biotechnology R&D directors, regulatory affairs leads at multinational conglomerates, and procurement managers at RSPO-certified plantation networks combined with secondary validation from ECHA REACH registration databases, ANVISA cosmetic approval filings, and China customs surfactant import records. Bottom-up capacity modeling and top-down demand triangulation cross-checked segment outputs.
Comparable historical reference periods anchored volume and value projections across the analysis window. Segmentation dimensions modeled include product type complexity, end-user routine integration depth, distribution channel working capital intensity, and regional regulatory cluster alignment. CAGRs derived from slope consistency checks against surfactant raw material price trajectories and salon channel prescription volume indices.
The model holds under stable regulatory enforcement timelines; deviation in EU REACH Annex XVII expansion scope or China's GB standard revision cadence would shift formulation investment requirements. Forecasts reflect documented assumptions on palm oil price correlation with biofuel demand and salon distributor consolidation velocity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hair Care
Australia Hair Removal Market
Hair Care
South Africa Hair Care Market
Hair Care
Hair Care Products Market
Hair Care
Mexico Hair Care Market
Hair Care
Hair Mask Market
Hair Care
United Arab Emirates Hair Care Market
Hair Care
France Haircare Market
Hair Care
Hair Oil Market
Hair Care
Artificial Hair Integration Market
Hair Care
Brazil Hair Care Market
Hair Care
Hair Tonic Market
Hair Care
Middle East and Africa Hair Care Market
Hair Care
Latin America Hair Care Market
Hair Care
South Africa Cosmetics and Personal Care Products Market
Hair Care
Hair Clay Market
Hair Care
India Hair Care Market