
 Japan Aromatherapy Products Market | 2026-2036
Japan Aromatherapy Products Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Aromatherapy Products Market Insights
Market Dynamics
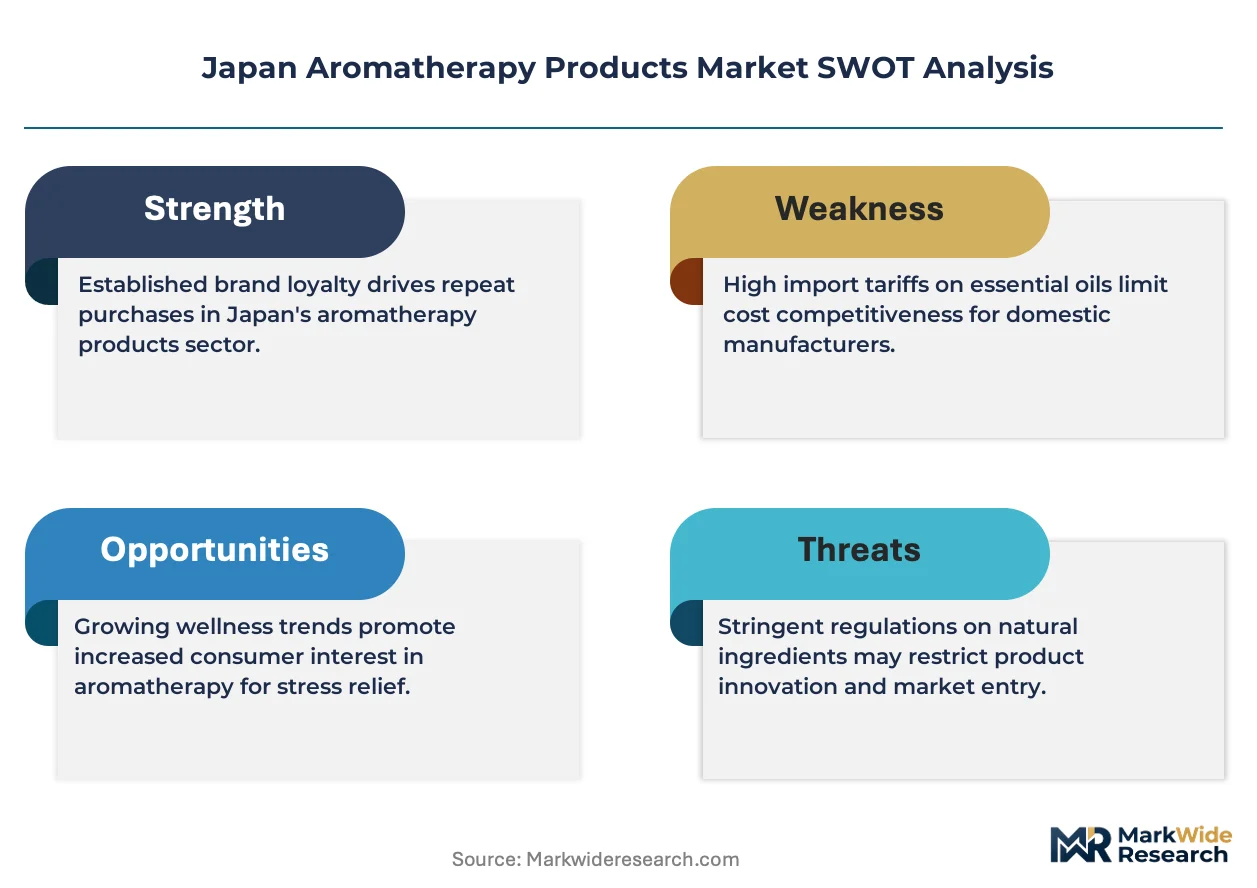
Certified aromatherapy practitioner supply is collapsing across Japan's wellness sector, constraining professional service expansion while pushing consumer demand toward home-use product formats. Shiono Koryo Kaisha leverages its century-old fragrance compounding expertise to dominate industrial essential oil supply. Ryohin Keikaku Co., Ltd. (MUJI) anchors the mass-market diffuser segment through minimalist design integration with its lifestyle retail network. ARTQ ORGANICS specializes in organic-certified single-origin oils, competing on traceability credentials that resonate with discerning Japanese consumers.
Aromatherapy products encompass volatile plant-derived extracts and their delivery mechanisms formulated for therapeutic or ambient scenting purposes, with essential oils typically steam-distilled or cold-pressed to preserve terpene profiles at concentrations between 0.5% and 100% depending on application. These products serve stress reduction, sleep enhancement, and air quality management functions across residential and commercial environments. Essential oils command the dominant revenue share within product type segmentation due to repeat purchase frequency and premium pricing tolerance for therapeutic-grade formulations. Online retail channels within distribution channel segmentation demonstrate the fastest structural expansion, driven by subscription models and influencer-driven discovery patterns that bypass traditional pharmacy and specialty store gatekeepers.
PMDA oversight of quasi-drug claims and METI enforcement of household goods quality standards create dual compliance layers that filter market entrants and elevate formulation documentation requirements. JIS standards for electrical diffusers impose safety testing protocols that shape product development timelines and manufacturing partnerships. Stakeholders must monitor evolving interpretations of therapeutic versus cosmetic claims as regulatory scrutiny intensifies on social media marketing practices.
Market Dynamics
Certified aromatherapy practitioner supply is collapsing across Japan's wellness sector, constraining professional service expansion while pushing consumer demand toward home-use product formats. This structural shortage is reshaping competitive positioning between industrial fragrance houses and direct-to-consumer wellness brands.
Growth Catalysts
- Household wellness penetration:Japanese households represent the primary demand segment for essential oil diffusers and aromatic wellness products, with urban density supporting compact-format adoption.
- METI labeling protocols:The Ministry of Economy, Trade and Industry's promotion of natural ingredient labeling standards elevates consumer trust in domestically formulated products.
- Tokyo-Osaka corridor concentration:Metropolitan wellness retail density and spa service penetration in these urban corridors generate concentrated demand pull for premium formulations.
Market Restraints
- Practitioner certification bottleneck:The collapsing supply of certified aromatherapy practitioners limits professional service channel expansion and constrains B2B demand.
- PMDA quasi-drug oversight:The Pharmaceuticals and Medical Devices Agency's strict therapeutic claim enforcement creates dual compliance layers that elevate documentation burdens and extend product launch timelines.
- JIS electrical safety mandates:Japanese Industrial Standards for diffuser electrical components impose testing protocols that shape manufacturing partnerships and development costs.
Strategic Opportunities
- Subscription commerce models:Online retail channels demonstrate structural expansion potential through recurring revenue formats that bypass traditional pharmacy gatekeepers.
- Traceability-driven premiumization:Single-origin organic certification resonates with discerning Japanese consumers, creating white space for transparent supply chain positioning.
- Osaka secondary market depth:Wellness service penetration in Japan's second metropolitan corridor remains underdeveloped relative to Tokyo, offering geographic expansion headroom.
Industry Challenges
- Social media claim compliance:Evolving PMDA interpretations of therapeutic versus cosmetic claims intensify scrutiny on influencer marketing practices and create enforcement uncertainty.
- Formulation documentation intensity:METI household goods quality standards require extensive raw material traceability that strains supplier relationship management capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Aromatherapy Products Market |
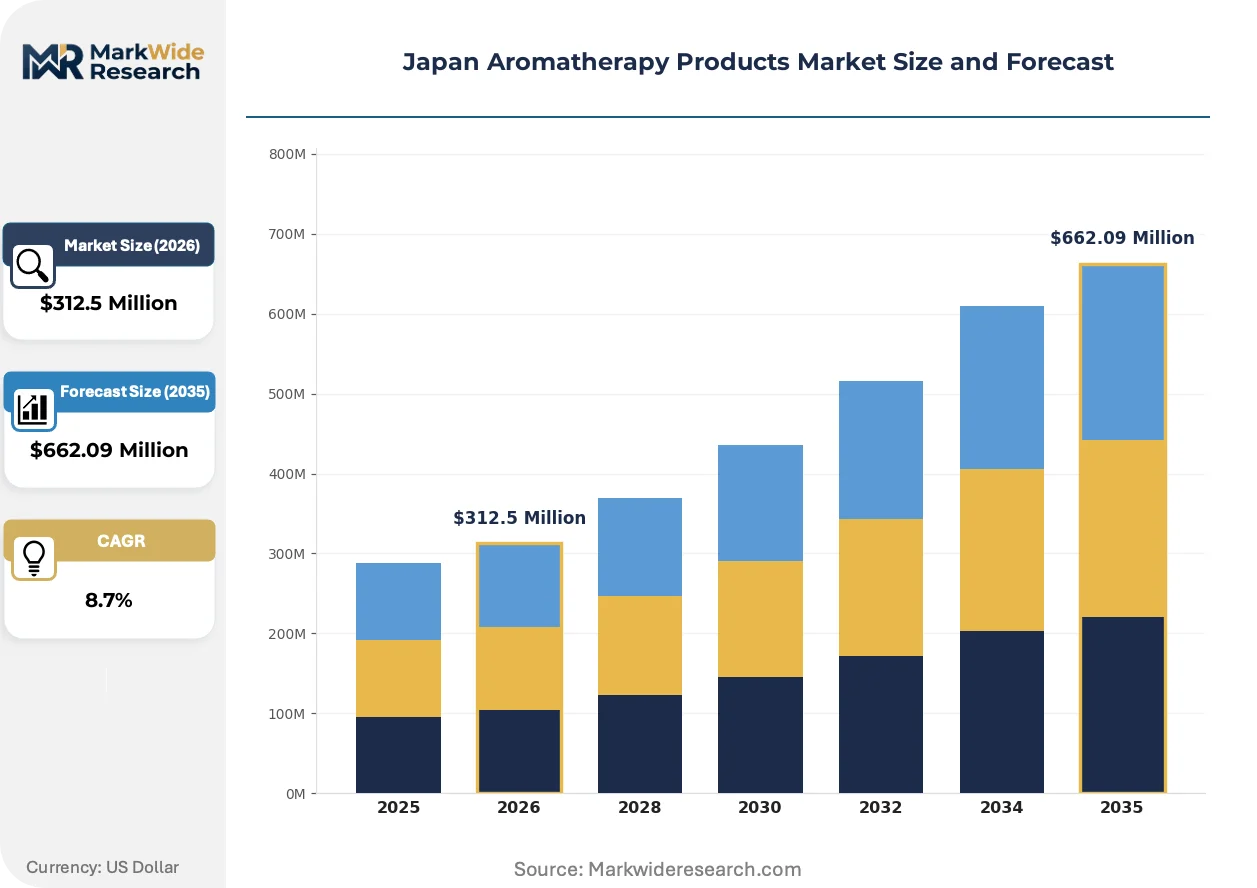
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $662.09 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oils, Diffusers, Candles, Sprays End User: Households, Wellness Centers, Spas, Retailers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Pharmacies Form: Liquid, Solid, Gel, Aerosol |
| Companies Covered | ARTQ ORGANICS, Shiono Koryo Kaisha, Ltd., Ryohin Keikaku Co., Ltd. (MUJI), Shizen Ryoho, Yuica (Takasho Co., Ltd.), Flavor Life Co., Ltd., Ecology Shimanto, Young Living Essential Oils, HONO KA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Aromatherapy Products Market Trends and Innovations
Smart diffusion technology and molecular delivery systems are actively reshaping product architecture in Japan's aromatherapy sector. These innovations are compressing replacement cycles while elevating performance expectations across residential and commercial installations.
Ultrasonic nebulization with programmable terpene preservation is bifurcating the diffuser category between precision wellness devices and commodity ambient scenting units. Wellness-focused households in Tokyo's 23 wards are adopting app-controlled systems at accelerated rates. This technology compression is enabling premium pricing for connected formats while commoditizing basic ultrasonic alternatives.
PMDA's evolving guidance on quasi-drug versus cosmetic classification is tightening claim substantiation requirements for topical essential oil applications. Industrial formulators must now navigate pre-market consultation pathways that extend commercialization timelines. Small-batch organic producers face disproportionate compliance burdens relative to established fragrance houses with dedicated regulatory affairs functions.
Japanese consumers are consolidating purchases through influencer-curated subscription boxes that disintermediate traditional department store fragrance counters. Direct-to-consumer channels now capture discovery and loyalty formation that previously occurred in physical retail. This behavioral shift is most visible among urban professional households seeking stress-management solutions without practitioner consultation.
Japan Aromatherapy Products Market Segmentation
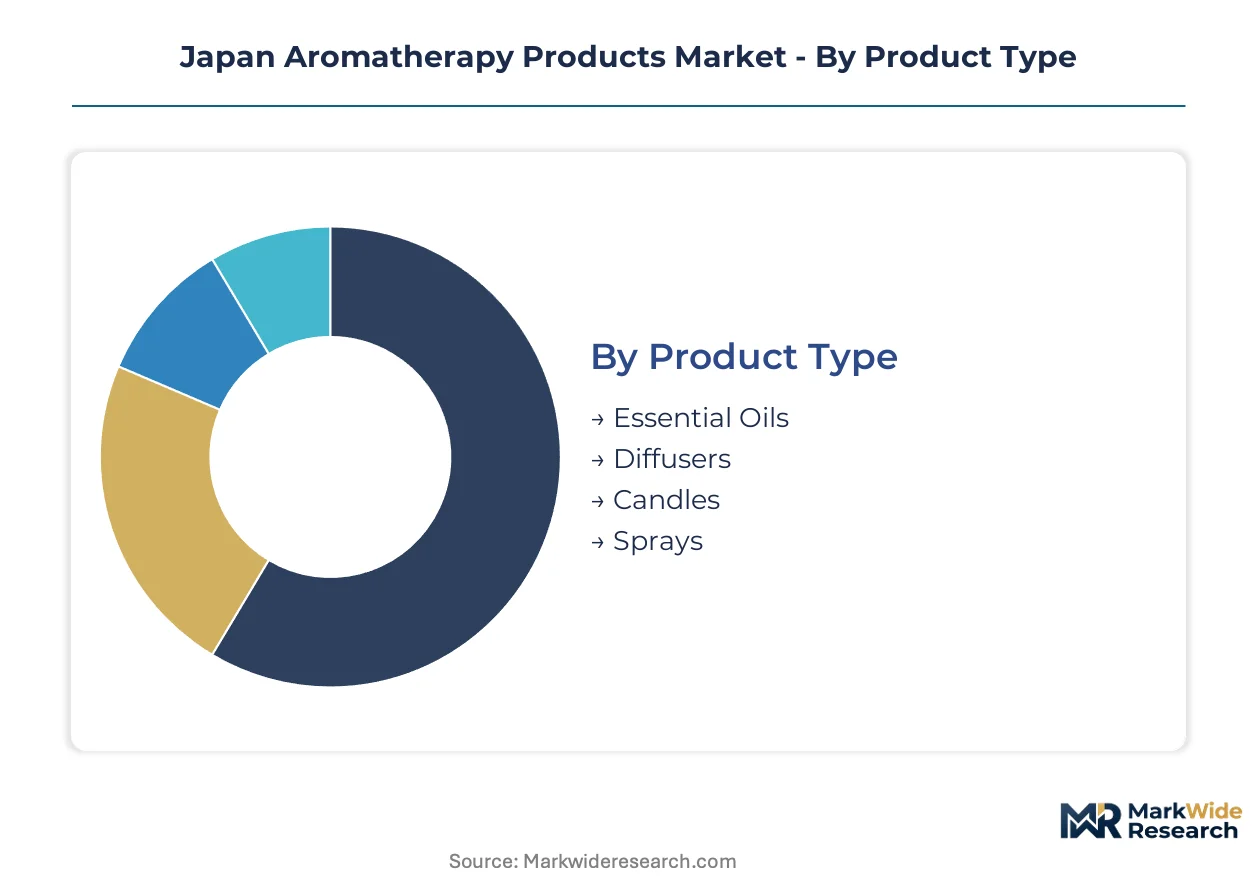
Segmentation in Japan's aromatherapy market reveals how regulatory boundaries and household purchasing patterns concentrate value in specific product formats. Understanding these divisions exposes where PMDA oversight and METI labeling requirements create competitive moats versus commodity pressure.
Product Type:
Substitution pressure from adjacent wellness categories—functional fragrances, air purifiers, sleep tech—varies sharply across product formats, with some segments facing direct displacement while others enjoy protected therapeutic positioning.
- Essential Oils:Steam-distilled or cold-pressed volatile plant extracts with terpene concentrations ranging from therapeutic-grade to ambient scenting. Japanese households in Tokyo's 23 wards drive concentrated demand for single-origin organic certifications that command premium shelf positioning.
- Diffusers:Ultrasonic nebulization and heat-free dispersion devices that preserve molecular integrity of loaded oils. Osaka metropolitan households are adopting app-controlled smart diffusion systems at accelerated rates, compressing replacement cycles for basic ultrasonic alternatives.
- Candles:Paraffin and soy-based vessels with embedded essential oil loads for ambient scenting. Facing displacement from flameless alternatives in fire-conscious Japanese residential settings.
- Sprays:Aerosol and pump-dispensed formulations for immediate air treatment. Competing directly with conventional air fresheners in mass retail channels with limited therapeutic claim differentiation.
Essential oils retain volume leadership; diffusers hold the steepest expansion curve.
End User:
Cost tier stratification separates institutional procurement with compliance documentation requirements from discretionary household purchases driven by influencer discovery and subscription convenience.
- Households:Individual consumers purchasing for residential wellness, stress management, and sleep enhancement applications. Urban density in Tokyo and Osaka corridors supports compact-format adoption with high repeat purchase frequency for oil refills.
- Wellness Centers:Professional service providers requiring certified practitioner oversight and treatment-room diffusion systems. Practitioner supply collapse is constraining this segment's expansion and pushing demand toward home-use alternatives.
- Spas:Hospitality-integrated aromatherapy services with ambient scenting and topical treatment protocols. Facing margin pressure from rising essential oil costs and labor certification requirements.
- Retailers:Department store fragrance counters and lifestyle outlets curating discovery experiences. Losing traffic to direct-to-consumer channels and influencer-curated subscription boxes.
Households dominate absolute volume; wellness centers face the most severe demand compression.
Distribution Channel:
Channel maturity varies from established pharmacy gatekeepers with quasi-drug compliance layers to emerging digital formats that bypass traditional retail infrastructure entirely.
- Online Retail:E-commerce platforms and brand-direct websites with subscription models and influencer-driven discovery. Tokyo-based professional households are consolidating purchases through curated boxes that disintermediate department store counters.
- Supermarkets:Mass-market outlets with limited shelf space for premium therapeutic-grade formulations. Competing primarily on price with conventional air care products.
- Specialty Stores:Dedicated wellness and lifestyle retailers with trained staff and sampling programs. Facing traffic erosion to digital channels with superior convenience.
- Pharmacies:Licensed outlets with quasi-drug claim oversight and practitioner referral networks. PMDA therapeutic claim enforcement creates documentation burdens that slow product turnover.
Online retail is climbing the fastest; pharmacies retain the most stringent compliance overlay.
Form:
Supply concentration in liquid extraction and formulation creates cost advantages for fluid formats while solid and gel alternatives face manufacturing scale constraints.
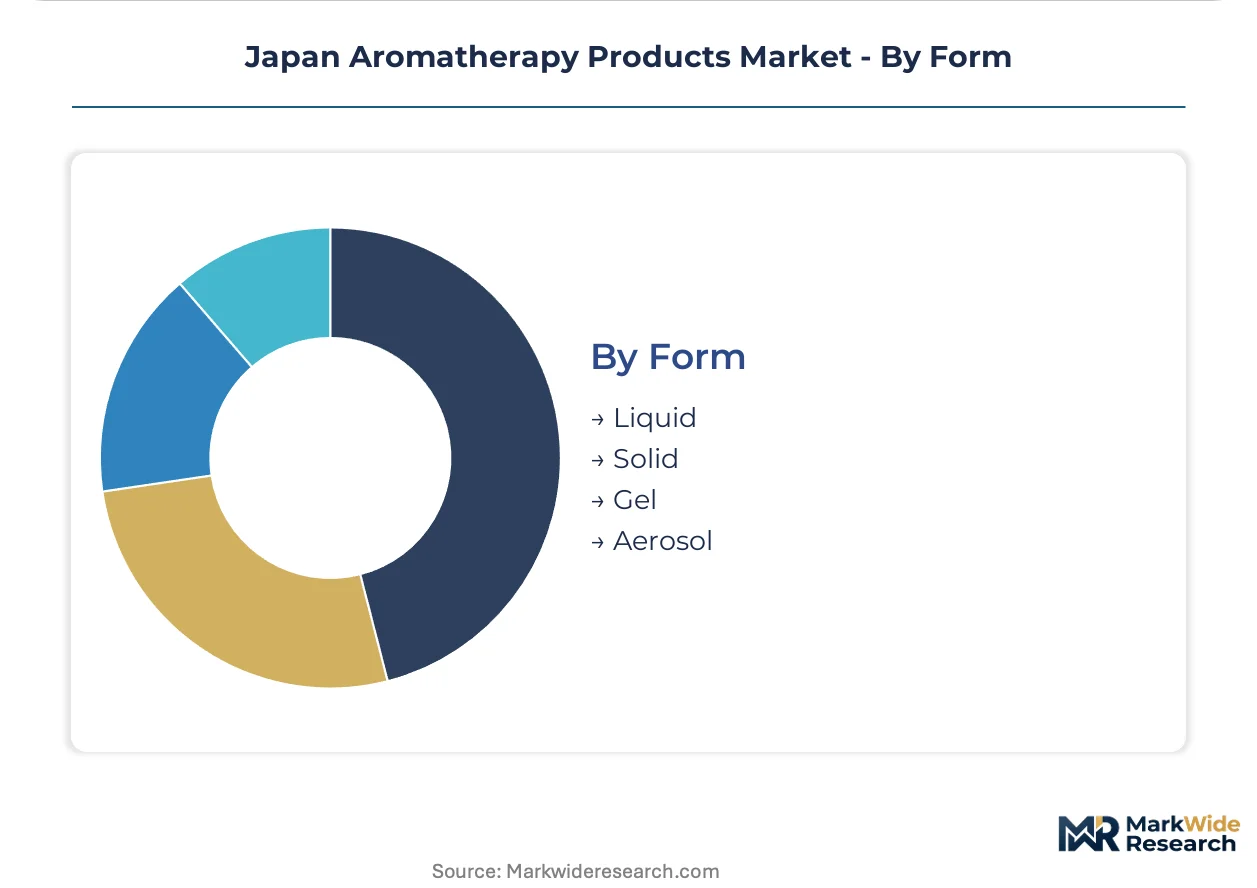
- Liquid:Oils, hydrosols, and alcohol-based solutions in dropper, roller, and spray delivery. Industrial fragrance houses in Japan maintain captive distillation capacity that secures supply security for major brands.
- Solid:Wax-based balms, resin infusions, and portable inhalation sticks. Niche positioning in travel and workplace applications where spill prevention matters.
- Gel:Polymer-matrix slow-release formulations for extended ambient scenting. Limited domestic manufacturing infrastructure elevates import dependency.
- Aerosol:Pressurized spray systems with propellant-dispersed oil microdroplets. Facing environmental regulatory pressure and consumer preference shifts toward pump alternatives.
Liquid forms command volume leadership; solid formats are gaining share fastest in portable applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI's labeling protocols and PMDA oversight anchor Japan's regulatory environment, concentrating aromatherapy demand in metropolitan corridors where wellness retail density supports premium product adoption.
Kanto/Tokyo
Tokyo's 23 wards drive concentrated demand for app-controlled smart diffusion systems and single-origin organic certifications. METI household goods quality standards enforce extensive raw material traceability that elevates documentation burdens for domestic formulators. Shibuya and Shinjuku wellness retail clusters are witnessing accelerated adoption of subscription commerce models that disintermediate traditional department store counters.
Kansai/Osaka
Osaka metropolitan households are adopting ultrasonic nebulization technology at rates exceeding national averages, compressing replacement cycles for basic diffuser alternatives. JIS electrical safety mandates for diffuser components shape manufacturing partnerships and extend product development timelines. Umeda and Namba commercial districts are developing secondary market depth for premium aromatherapy services with underdeveloped practitioner supply constraining professional channel expansion.
Chubu/Nagoya
Nagoya's manufacturing heritage supports industrial fragrance compounding infrastructure that secures supply security for major domestic brands. PMDA quasi-drug claim enforcement creates dual compliance layers that filter market entrants and elevate formulation documentation requirements. The city's automotive industry workforce is driving demand for workplace stress-management applications and portable inhalation formats.
Kyushu
Fukuoka's emerging wellness service sector is attracting direct-to-consumer brands seeking geographic diversification beyond Tokyo-Osaka concentration. METI sustainable sourcing protocols shape product formulation requirements for natural ingredient labeling claims. The region's agricultural base is supporting domestic cultivation of aromatic raw materials that reduce import dependency for regional formulators.
Hokkaido
Sapporo's hospitality-integrated spa sector is experiencing margin pressure from rising essential oil costs and labor certification requirements. PMDA therapeutic versus cosmetic claim scrutiny intensifies enforcement uncertainty for social media marketing practices targeting seasonal tourism demand. The sub-region's cold climate is sustaining demand for indoor air quality management and sleep enhancement applications through extended winter periods.
Japan Aromatherapy Products Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with industrial fragrance houses leveraging captive distillation capacity against direct-to-consumer wellness brands building traceability credentials. The market structure bifurcates between century-old compounding expertise and minimalist lifestyle retail integration, with regulatory compliance capabilities serving as the primary competitive moat. Three archetypes dominate: industrial suppliers with regulatory affairs functions, mass-market lifestyle retailers with design-forward positioning, and organic-certified specialists competing on transparency. Dominant competitive moves include portfolio diversification into smart diffusion technology and backward integration into captive aromatic raw material cultivation.
Within the industrial supplier tier, Shiono Koryo Kaisha, Ltd. exemplifies century-old fragrance compounding heritage, while Ryohin Keikaku Co., Ltd. (MUJI) anchors mass-market diffusion through lifestyle retail network integration. ARTQ ORGANICS occupies a position representing the organic-certified specialist archetype, with traceability credentials that resonate with discerning household purchasers. These three entities collectively illustrate the competitive tension between scale-driven regulatory compliance and niche transparency positioning that defines Japan's aromatherapy sector.
| Leading Market Players |
|---|
| ARTQ ORGANICS |
| Shiono Koryo Kaisha, Ltd. |
| Ryohin Keikaku Co., Ltd. (MUJI) |
| Shizen Ryoho |
| Yuica (Takasho Co., Ltd.) |
| Flavor Life Co., Ltd. |
| Ecology Shimanto |
| Young Living Essential Oils |
| HONO KA |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day aromatic raw material lead times from Southeast Asian cultivation zones compress margin flexibility for Japanese formulators while amplifying pricing power for domestic fragrance houses with captive distillation infrastructure. This temporal tension concentrates value capture among industrial suppliers and forces premium positioning for brands lacking upstream control.
Pricing Analysis
Tokyo-to-Osaka price spreads of 15-20% for identical organic-certified essential oils reflect metropolitan retail density premiums and logistics cost stratification. Three-tier pricing structure across premium therapeutic-grade, standard wellness, and economy ambient-scenting levels segments buyer archetypes by certification tolerance. Cost compression in the economy tier intensifies because supermarket channel buyers prioritize unit economics over traceability credentials. Household purchasers in Osaka demonstrate highest price sensitivity, while Tokyo wellness centers accept premiums for single-origin documentation.
Supply Chain Analysis
Container availability constraints on Southeast Asia-Japan trade lanes elevate inbound logistics costs for imported aromatic feedstocks and compress working capital cycles for small-batch formulators. Domestic supply concentrates in Japan's industrial fragrance corridor with backward integration into Kyushu cultivation zones, though bulk raw material draws from Indonesia, India, and Madagascar. Single-source vulnerability in organic-certified sandalwood and frankincense extracts threatens formulation continuity for premium brands. Distribution runs through pharmacy gatekeepers with quasi-drug compliance layers, direct-to-consumer subscription platforms, and lifestyle retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Practitioner supply collapse fragments professional service channels and creates white-space opportunities for home-use product formats targeting stress-management demand without consultation dependency.
For Market Incumbents: Shield market position by deepening captive aromatic raw material cultivation in Kyushu and Fukuoka agricultural zones to reduce import dependency. Accelerate regulatory affairs investment to navigate PMDA quasi-drug claim evolution and preempt enforcement actions against social media marketing practices. Consolidate manufacturing partnerships with JIS-certified electrical component suppliers to compress smart diffuser development timelines.
For New Entrants and Emerging Players: Differentiate on traceability transparency by building direct-from-grower relationships with Indonesian and Indian aromatic crop cooperatives. Target Osaka metropolitan households with app-controlled diffusion systems at price points below Tokyo premiums. Pursue influencer-curated subscription box partnerships to bypass department store counter gatekeepers and capture discovery-phase loyalty formation.
For Investors and Strategic Acquirers: Long-term, this sits as a wellness-infrastructure play because aging demographics and workplace stress-management demand sustain category relevance through economic cycles. Acquisition targets should emphasize organic-certified specialists with documented supply chain transparency and established METI labeling compliance. Monitor PMDA enforcement intensity against therapeutic claims as the signal for regulatory risk repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aromatic Cultivation | Kyushu lavender and citrus plantations reduce import exposure for Japanese fragrance houses. |
| Smart Diffuser Platform Launch | App-controlled nebulization systems command premium positioning in Tokyo's 23 wards. |
| Subscription Commerce Expansion | Recurring revenue formats bypass pharmacy gatekeepers and capture household loyalty. |
| Organic Certification Investment | METI natural ingredient labeling standards elevate consumer trust in traceable supply chains. |
| Osaka Market Penetration | Secondary metropolitan corridor offers geographic diversification beyond Tokyo saturation. |
Research Methodology
Desk research of METI regulatory filings, PMDA quasi-drug guidance documents, and JIS electrical safety standards preceded structured interviews with fragrance house procurement directors, wellness center operators, and pharmacy category buyers. Primary fieldwork combined with secondary validation against customs trade data, retail audit databases, and industrial production statistics. Bottom-up household penetration modeling and top-down category value estimation were triangulated to constrain variance.
Variance decomposition across product type, end user, distribution channel, and regional metropolitan density dimensions anchored the analytical framework. CAGRs were derived from segment-level growth rate synthesis and cross-referenced against macroeconomic wellness spending elasticity. Forecast inputs incorporated METI labeling protocol adoption curves and PMDA enforcement intensity trajectories without year-specific calibration.
Forecasts assume regulatory continuity in METI household goods quality standards and PMDA quasi-drug oversight regimes; material policy shifts would require re-modeling. Supply chain disruption scenarios and practitioner certification recovery patterns represent specific risk factors that could revise trajectory assumptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Facial Rollers Market
Beauty & Personal Care
US Sustainable Personal Care Market
Beauty & Personal Care
Vanity Mirror Market
Beauty & Personal Care
Nail Lamps Market
Beauty & Personal Care
Hair and Nail Accessories Market
Beauty & Personal Care
Depilatory Product Market
Beauty & Personal Care
US Personal Care Products Market
Beauty & Personal Care
Middle East and Africa Hair Conditioner Market
Beauty & Personal Care
Electric Facial Cleansing Brush Market
Beauty & Personal Care
Over-Night Hair Treatment Products Market
Beauty & Personal Care
Anti-Aging Cosmetics Market
Beauty & Personal Care
Herbal Haircare Products Market
Beauty & Personal Care
South America E-Commerce Skin Care Products Market
Beauty & Personal Care
Asia-Pacific Beauty and Personal Care Products Market
Beauty & Personal Care
Intimate Wash Care Products Market
Beauty & Personal Care
Luxury Bath and Body Products Market