
 Cruelty-Free Makeup Market | 2026-2036
Cruelty-Free Makeup Market Size, Share, and Industry Trends Forecast 2026-2036
Cruelty-Free Makeup Market Analytics
The EU's REACH regulation is repositioning formulation chemistry requirements for brands entering European markets. Fenty Beauty leverages its R&D intensity to reformulate products without animal-derived testing proxies. KVD Beauty anchors its portfolio in vegan certification standards that exceed baseline cruelty-free claims. Tarte Cosmetics specializes in botanical ingredient sourcing that satisfies both Leaping Bunny and PETA verification protocols.
Cruelty-free makeup comprises cosmetic formulations developed without animal testing at any production stage, verified through in-vitro methods like reconstructed human epidermis models and ingredient-level supply chain audits. These products serve consumers seeking ethical alignment between personal care purchases and animal welfare standards. Foundation and lipstick dominate current volume within product type segmentation, while online distribution channels capture the fastest expansion as direct-to-consumer platforms bypass traditional retail gatekeepers. The premium price tier concentrates margin pools, though mid-range positioning attracts the broadest demographic crossover from conventional cosmetics.
FDA guidelines in the United States, China's NMPA cosmetic registration reforms, and the EU's ECHA framework collectively determine market access pathways for cruelty-free claims. Brands must navigate divergent documentation requirements between voluntary certification systems and mandatory regulatory filings. Stakeholders should monitor how shifting testing exemption protocols in Asia-Pacific markets alter the geographic feasibility of zero-animal-testing supply chains.
Market Dynamics
Millennial and Gen Z purchasing power is compressing traditional certification timelines, forcing brands to accelerate Leaping Bunny and PETA verification before product launch rather than post-market. This demographic pressure is restructuring R&D budgets toward in-vitro testing infrastructure and supply chain auditing capabilities.
Growth Catalysts
- REACH enforcement in the European Union:The ECHA framework mandates animal-test-free alternatives for cosmetic safety assessments, compelling formulation reformulation across imported and domestic brands. This regulatory pressure expands addressable market for verified cruelty-free suppliers.
- Reconstructed human epidermis models:Maturation of in-vitro skin sensitization testing reduces dependency on animal proxies while accelerating product development cycles. Cosmetic laboratories in Germany and the Netherlands are scaling these methods.
- China's NMPA cosmetic registration reforms:Updated testing exemptions for general cosmetics eliminate mandatory animal testing requirements, unlocking market access for previously excluded international cruelty-free brands.
Market Restraints
- Botanical ingredient supply concentration:Certified sustainable plant-derived alternatives to animal-tested synthetics concentrate sourcing in specific equatorial growing regions, creating weather and geopolitical exposure.
- Regulatory documentation fragmentation:Divergent filing requirements between voluntary certification systems and mandatory FDA cosmetic registration create compliance cost stacking for multi-market brands.
- Technical validation bottlenecks:In-vitro test method acceptance varies across national regulators, forcing redundant safety studies for identical formulations entering different jurisdictions.
Strategic Opportunities
- Direct-to-consumer platform expansion:Digitally native brands bypass traditional retail gatekeepers, capturing margin compression from eliminated wholesale markups while building certification-transparent customer relationships.
- India's CDSCO cosmetic regulatory harmonization:Emerging alignment with international cruelty-free standards creates first-mover advantage for brands establishing compliant supply chains ahead of formal mandate adoption.
- Convergence of blockchain traceability with certification verification:Immutable ingredient sourcing records enable real-time consumer authentication of cruelty-free claims, differentiating premium positioning.
Industry Challenges
- In-vitro toxicology expertise scarcity:Cosmetic formulators with validated reconstructed tissue model experience command compensation premiums that strain mid-range brand R&D staffing.
- Multi-certification audit fatigue:Simultaneous maintenance of Leaping Bunny, PETA, and regional vegan standards requires dedicated compliance personnel and recurring third-party facility inspections.
- Legacy supplier conversion timelines:Long-term raw material contracts with animal-testing ingredient vendors lock brands into non-compliant supply chains until contract expiration or buyout negotiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cruelty-Free Makeup Market |
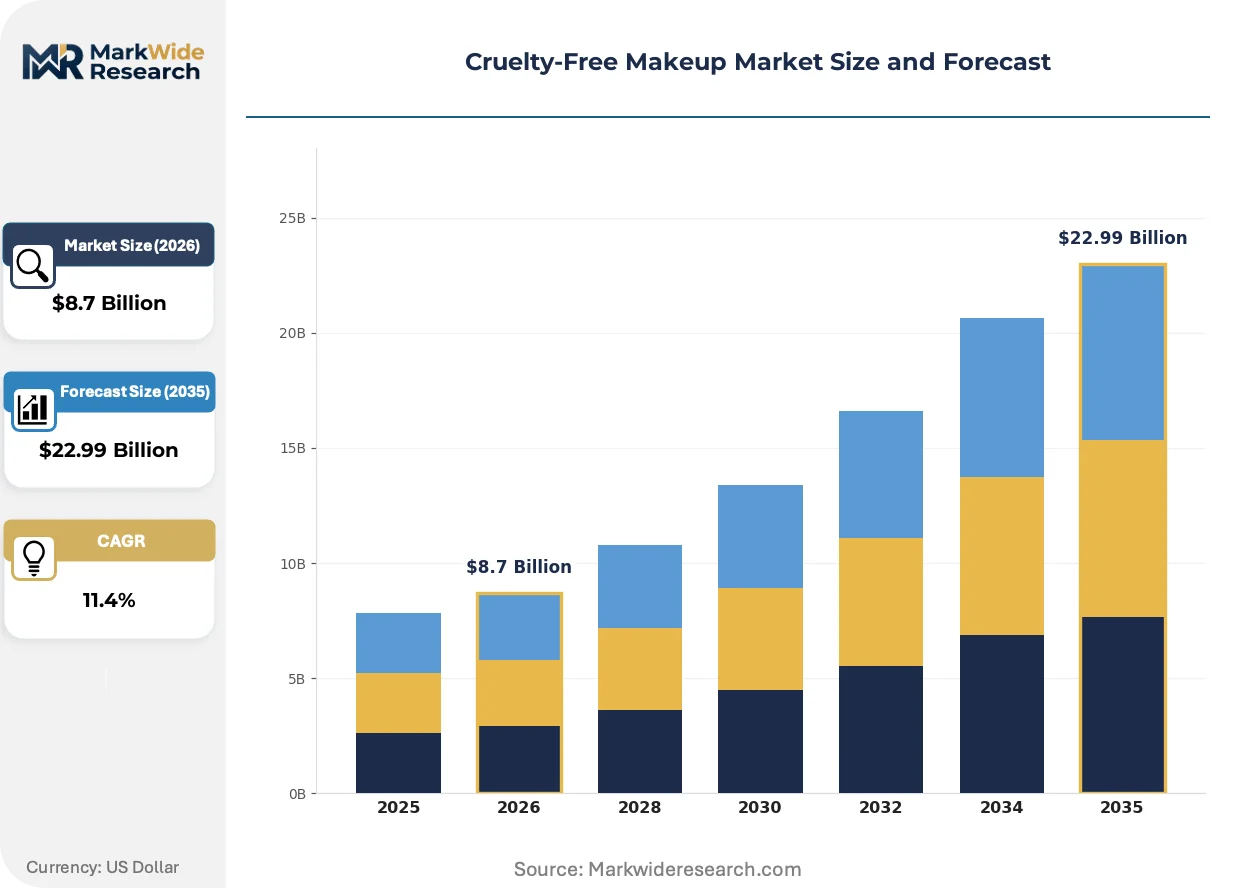
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foundation, Lipstick, Mascara, Eyeshadow End User: Consumers, Salons, Influencers, Retailers Distribution Channel: Online, Specialty Stores, Supermarkets, Pharmacies Price Tier: Premium, Mid-Range, Budget, Luxury |
| Companies Covered | KVD Beauty, Urban Decay, Fenty Beauty, Haus Labs by Lady Gaga, Charlotte Tilbury, Tarte Cosmetics, Too Faced, bareMinerals, e.l.f. Beauty Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cruelty-Free Makeup Market Evolving Landscape
Biotechnology-derived alternatives to animal-tested cosmetic ingredients are restructuring formulation economics, while regulatory harmonization efforts compress geographic market entry barriers. These forces are converging to accelerate product development velocity and reshape competitive differentiation mechanisms.
Organ-on-chip technology is converging with cosmetic safety assessment workflows, enabling dynamic modeling of human skin responses to complex formulations. Premium skincare laboratories in Switzerland and South Korea are adopting these systems to replace static in-vitro screens. The technology is converging with regulatory pre-submission pathways, compressing approval timelines for novel active ingredients.
The EU's ECHA framework is expanding alternative test method validation requirements beyond baseline REACH mandates, forcing ingredient suppliers to maintain parallel safety dossiers. This regulatory pressure elevates compliance costs for small-batch botanical extractors. Color cosmetics and sun care categories face the steepest documentation burdens under the updated guidance.
Certification-driven purchasing now dominates premium beauty procurement, with buyers prioritizing Leaping Bunny verification over legacy brand recognition. Specialty retailers and clean beauty platforms are displacing conventional department store distribution for verified cruelty-free lines. This behavioral shift concentrates most visibly in urban coastal markets across the United States and United Kingdom.
Cruelty-Free Makeup Market Segmentation
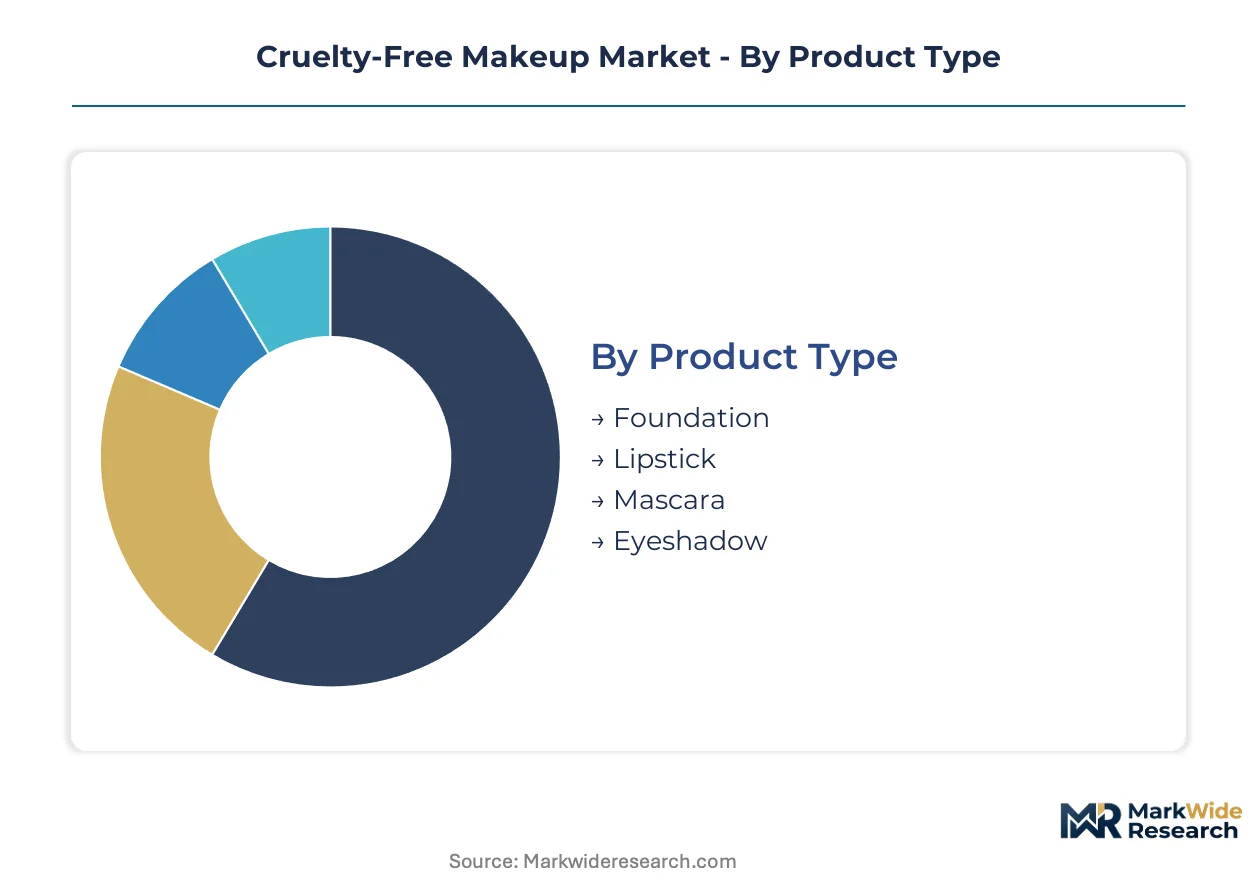
Segmentation in cruelty-free cosmetics reveals how certification requirements reshape product development priorities and channel economics. Distinct buyer profiles—ethical purists versus convenience seekers—drive divergent formulation and distribution strategies across each dimension.
Product Type:
Complexity of safety documentation determines R&D resource allocation across cosmetic categories.
- Foundation:Liquid and powder formulations require extensive in-vitro phototoxicity testing for UV-filter ingredients. Demand clusters among digitally native direct-to-consumer brands in the United States seeking complexion-matching algorithm integration.
- Lipstick:Wax and pigment blends face heightened scrutiny for heavy metal contamination pathways, necessitating supply chain auditing beyond baseline cruelty-free verification. European Union REACH enforcement elevates documentation burdens for colorants.
- Mascara:Ophthalmological safety protocols demand specialized reconstructed cornea models, limiting supplier pools to laboratories with validated ocular toxicology capabilities.
- Eyeshadow:Pressed powder manufacturing concentrates mica sourcing traceability requirements, with blockchain verification emerging as a competitive differentiator.
Volume sits with Foundation; growth tilts toward Eyeshadow as palette customization expands.
End User:
Purchasing authority and certification literacy vary sharply across buyer types, dictating marketing investment and proof-point requirements.
- Consumers:Individual buyers prioritize Leaping Bunny and PETA verification badges at point-of-sale, with Millennial and Gen Z demographics demanding ingredient transparency apps.
- Salons:Professional makeup artists require bulk-format products with batch-level traceability for liability coverage, driving B2B procurement platform development.
- Influencers:Content creators function as de facto quality assurance gatekeepers, with affiliate commission structures rewarding certification depth over brand heritage.
- Retailers:Specialty beauty chains and clean beauty platforms impose vendor qualification standards exceeding regulatory minimums, filtering supplier bases.
Revenue concentrates with Consumers; margin expansion tilts toward Salons as professional-grade lines command pricing premiums.
Distribution Channel:
Channel selection determines certification visibility and customer education depth.
- Online:Direct-to-consumer platforms enable real-time supply chain transparency through QR-linked ingredient sourcing maps, bypassing traditional retail gatekeeper margins.
- Specialty Stores:Sephora and Ulta Beauty allocate dedicated shelf space to verified cruelty-free lines, with trained associates converting certification awareness into purchase decisions.
- Supermarkets:Mass-market retail limits SKU breadth for certified products, compressing entry opportunities to private-label partnerships.
- Pharmacies:CVS and Walgreens integrate cruelty-free filters into digital shelf browsing, though physical placement remains constrained by legacy brand contracts.
Volume concentrates in Specialty Stores; channel expansion tilts most quickly toward Online as platform-native brands scale.
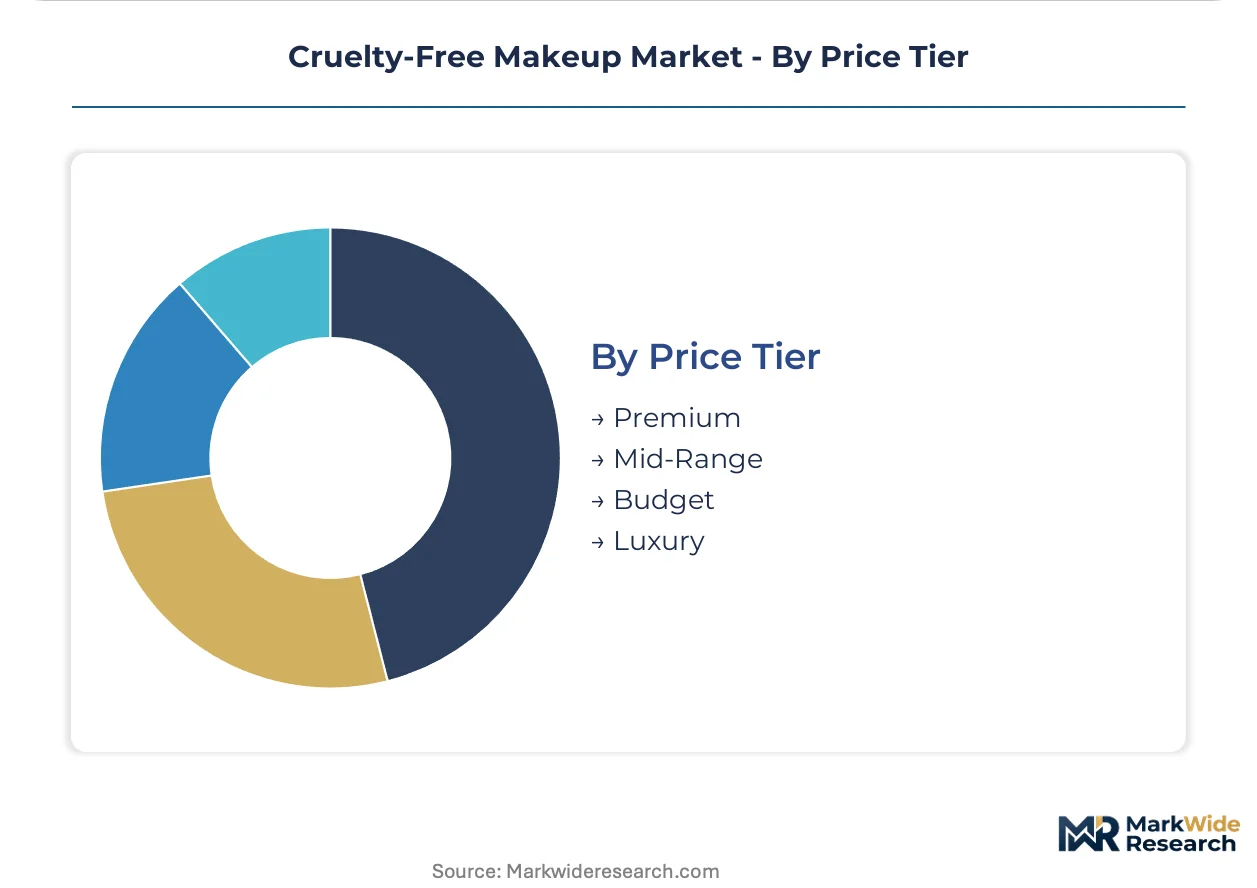
Price Tier:
Certification cost absorption capacity separates viable positioning levels.
- Premium:Mid-to-high price points capture the broadest demographic crossover from conventional cosmetics, with certification transparency justifying modest markups over non-verified alternatives.
- Mid-Range:Mass-premium positioning faces margin compression from simultaneous certification maintenance and competitive pricing pressure.
- Budget:Entry-level pricing limits supplier audit frequency, constraining certification depth to single-standard verification.
- Luxury:Ultra-premium segments absorb multi-certification compliance costs while leveraging exclusivity narratives around biotechnology-derived ingredients.
Margin pools concentrate in Luxury; demographic reach tilts toward Premium as certification normalization erodes price premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in the United Arab Emirates concentrate cruelty-free cosmetics distribution for Middle Eastern markets. Regulatory harmonization efforts in Asia-Pacific are unlocking previously restricted market access for animal-test-free brands.
United States
Millennial and Gen Z purchasing power drives cruelty-free certification adoption across direct-to-consumer platforms. FDA cosmetic registration requirements maintain baseline safety documentation standards without mandating animal testing. Los Angeles and New York City anchor digitally native brand headquarters, with Sephora and Ulta Beauty expanding verified product shelf space.
Germany
REACH enforcement through ECHA mandates alternative test methods for cosmetic safety assessments. Reconstructed human epidermis laboratories in Berlin and Hamburg scale in-vitro validation services for European market entry. Frankfurt serves as a logistics hub for cruelty-free ingredient sourcing across continental supply chains.
China
NMPA cosmetic registration reforms eliminate mandatory animal testing for general cosmetics, enabling international brand market access. Shanghai and Hangzhou concentrate cross-border e-commerce platforms facilitating cruelty-free product importation. Domestic biotechnology firms in Suzhou develop organ-on-chip alternatives for safety assessment workflows.
United Kingdom
Post-Brexit regulatory autonomy preserves EU-equivalent animal testing prohibitions while streamlining certification recognition. London anchors specialty beauty retail chains imposing vendor qualification standards exceeding regulatory minimums. Manchester and Birmingham host formulation laboratories specializing in botanical ingredient verification protocols.
South Korea
MFDS cosmetic safety guidelines increasingly align with OECD alternative test method validation standards. Seoul concentrates premium skincare laboratories adopting organ-on-chip technology for dynamic skin response modeling. Busan-Ulsan industrial clusters manufacture biotechnology-derived ingredient alternatives to animal-tested synthetics.
Cruelty-Free Makeup Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across certification depth and price tier positioning. Market structure tilts toward brand-led differentiation rather than manufacturing consolidation. Three archetypes dominate: legacy prestige houses pivoting toward vegan certification, digitally native direct-to-consumer entrants, and clean beauty platform-native labels. Competitive moves center on supply chain auditing capability acquisition and multi-certification maintenance infrastructure.
Within the prestige pivot archetype, Charlotte Tilbury and Too Faced occupy positions emphasizing heritage brand recognition combined with accelerated Leaping Bunny verification. Among platform-native specialists, e.l.f. Beauty Inc. exemplifies mid-range positioning with certification transparency as a core value proposition. KVD Beauty anchors the vegan certification specialist tier, representing standards that exceed baseline cruelty-free claims through supply chain integration.
| Leading Market Players |
|---|
| KVD Beauty |
| Urban Decay |
| Fenty Beauty |
| Haus Labs by Lady Gaga |
| Charlotte Tilbury |
| Tarte Cosmetics |
| Too Faced |
| bareMinerals |
| e.l.f. Beauty Inc. |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up specialty ingredient suppliers anchor supply-side discipline, compressing procurement timelines for mid-range brands while extracting certification premiums that reshape tiered pricing across cruelty-free cosmetics.
Pricing Analysis
Short lead-time premiums now separate verified cruelty-free formulations from spot-market alternatives, with Leaping Bunny-certified SKUs commanding measurable markups over single-standard competitors. Three-tier pricing structure across luxury, premium, and accessible levels stratifies by certification depth rather than formulation complexity alone. Cost compression in the mid-range tier intensifies because simultaneous PETA and Leaping Bunny maintenance drains margin pools. Individual consumers exhibit highest price sensitivity, while professional salon buyers absorb premiums for batch-level traceability.
Supply Chain Analysis
Dual-sourcing requirements for botanical actives now mandate multi-supplier qualification across India, Madagascar, and Brazil to mitigate weather-driven harvest volatility. Certified sustainable mica, shea butter, and plant-derived emulsifiers draw from equatorial growing regions with concentrated ESG audit infrastructure. Single-source vulnerability elevates risk exposure where blockchain verification infrastructure remains underdeveloped. Distribution runs through direct-to-consumer platforms and specialty retail chains, bypassing mass-market wholesale gatekeepers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from multi-certification audit fatigue will force sub-scale brands toward acquisition or private-label conversion over the projection horizon.
For Market Incumbents: Hedge against supply disruption by securing captive contracts with reconstructed tissue testing laboratories in Germany and the Netherlands. Acquire in-vitro toxicology capabilities ahead of ECHA validation expansion, as technical expertise scarcity threatens R&D staffing at mid-tier competitors.
For New Entrants and Emerging Players: Organ-on-chip safety assessment platforms offer entry wedge into premium skincare segments where legacy brands lag technology adoption. Target professional salon channels with bulk-format certification-transparent lines, leveraging lower customer acquisition costs than saturated direct-to-consumer markets.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-range cruelty-free specialists with existing Leaping Bunny infrastructure in the United States, where regulatory documentation fragmentation squeezes undercapitalized competitors. Monitor NMPA enforcement consistency across Chinese provincial regulators as inflection indicator for Asia-Pacific market access viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Certification Infrastructure Buildout | Simultaneous Leaping Bunny and PETA maintenance captures premium shelf placement at Sephora and Ulta Beauty. |
| Direct-to-Consumer Platform Launch | Bypassing wholesale markups enables real-time ingredient transparency via QR-linked supply chain maps. |
| In-Vitro Testing Laboratory Acquisition | Captive reconstructed epidermis capabilities compress product development cycles ahead of REACH enforcement expansion. |
| Blockchain Traceability Integration | Immutable mica and botanical sourcing records differentiate premium positioning for ethically motivated Millennial buyers. |
| Professional Salon Channel Expansion | Bulk-format procurement with batch-level documentation commands pricing premiums from liability-conscious makeup artists. |
Research Methodology
Trade databases, regulatory filing repositories, and certification body disclosure records formed the secondary backbone, cross-referenced with primary interviews involving cosmetic formulators, supply chain auditors at Leaping Bunny-accredited facilities, specialty retail category buyers, and in-vitro testing laboratory directors. Bottom-up demand modeling triangulated against top-down market sizing validated volume and value estimates across the analysis window.
Bottom-up unit economics aggregated by product type, price tier, distribution channel, and geographic regulatory cluster, while top-down macro validation anchored CAGR derivation to documented certification adoption curves and regulatory harmonization timelines. Modeled inputs incorporated REACH enforcement trajectory, NMPA exemption protocol stability, and reconstructed tissue method validation progress without year-specific milestone assumptions.
Several conditions sit outside the modeled scope, including abrupt ECHA guidance revision, geopolitical disruption to equatorial botanical supply zones, and consumer certification fatigue. Deviation in Chinese provincial NMPA enforcement consistency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Germany Lip Care Products Market
Beauty & Personal Care
Spray Tanning Market
Beauty & Personal Care
Hair Styling Equipment Market
Beauty & Personal Care
Asia Pacific Beauty Fridges Market
Beauty & Personal Care
US Personal Care Contract Manufacturing Market
Beauty & Personal Care
UK Vegan Cosmetics Market
Beauty & Personal Care
Aluminium-Free Deodorants Market
Beauty & Personal Care
Organic Liquid Soaps Market
Beauty & Personal Care
Global Heated Eyelash Curlers Market
Beauty & Personal Care
Global Electric Head and Scalp Massager Market
Beauty & Personal Care
Wrinkle Release Spray Market
Beauty & Personal Care
Beeswax for Cosmetics Market
Beauty & Personal Care
Bath and Body Products Market
Beauty & Personal Care
Plant-Based Skincare Products Market
Beauty & Personal Care
South America Deodorants Market
Beauty & Personal Care
Europe Professional Beauty Services Market