
 United States Male Grooming Products Market | 2026-2036
United States Male Grooming Products Market Size, Share, and Industry Trends Forecast 2026-2036
United States Male Grooming Products Market Intelligence
Buyer concentration among male grooming consumers is decoupling as Gen Z and millennial segments fragment across specialty channels while professional athletes consolidate around premium kit offerings. Procter & Gamble leverages its mass-market scale to dominate shelf presence in supermarkets and pharmacies. Edgewell Personal Care anchors its position through specialized shaving hardware and blade systems. L'Oréal differentiates via premium skincare-infused grooming lines targeting urban professionals.
United States male grooming products encompass topical formulations and mechanical tools designed for hair management, skin conditioning, and facial hair maintenance, typically incorporating emollients, active botanicals, or lubricating polymers to reduce irritation during or after hair removal. These products serve commercial purposes ranging from daily hygiene regimens to professional appearance standards across workplace and social contexts. Beard oil and hair gel segments capture expanding margin pools as consumers prioritize conditioning and styling performance over basic cleansing. Online retail channels sustain the fastest growth trajectory, while supermarkets and pharmacies occupy mature volume positions with established replenishment cycles.
The FDA governs cosmetic safety and labeling requirements for male grooming products, while the FTC monitors advertising claims related to performance benefits and ingredient efficacy. State-level regulations in California, administered through the Department of Public Health, impose additional disclosure mandates on fragranced personal care items. The EPA evaluates environmental impacts of aerosol propellants and volatile organic compounds in spray-format products. Stakeholders must monitor evolving state ingredient bans and federal classification shifts that could reclassify certain grooming formulations as drugs based on therapeutic claims.
Market Dynamics
Gen Z's preference for hybrid beard care and skincare formulations is fragmenting traditional category boundaries, forcing manufacturers to reformulate around multi-functional claims while navigating FDA scrutiny of cosmetic-drug classification thresholds.
Growth Catalysts
- California's Fragrance Disclosure Mandates:The Department of Public Health's expanded reporting requirements for scented personal care items are accelerating ingredient transparency investments among domestic manufacturers.
- Beard Oil Formulation Innovation:Conditioning polymers derived from plant-based emollients are penetrating premium segments as urban male professionals prioritize facial hair health alongside skin conditioning.
- Texas Urban Professional Concentration:Dallas and Houston metropolitan clusters are sustaining above-average demand for kit-based grooming systems targeting workplace appearance standards.
Market Restraints
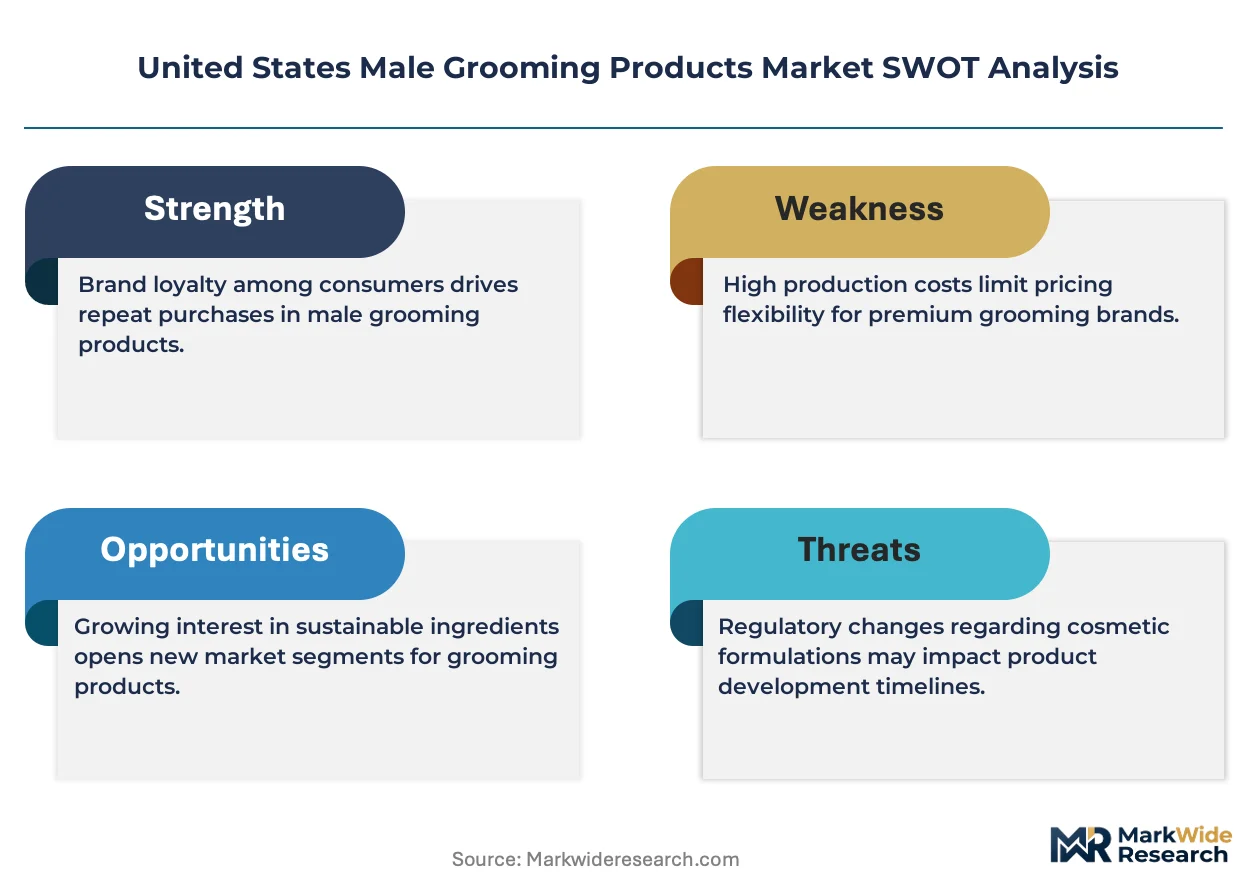
- Aerosol Propellant Cost Volatility:Petroleum-derived hydrocarbon feedstocks for spray-format hair products expose margins to energy market fluctuations.
- FDA Classification Uncertainty:Therapeutic claims around anti-aging or acne prevention risk triggering drug-level compliance costs and extended approval timelines.
- Single-Use Plastic Packaging Substitution:Aluminum and glass alternatives carry 40-60% unit cost premiums that compress mass-market accessibility.
Strategic Opportunities
- Subscription Channel Penetration:Direct-to-consumer replenishment models are capturing recurring revenue from millennial buyers seeking convenience.
- Skincare-Convergence Formulations:Niacinamide and hyaluronic acid integration into post-shave balms is converging with dermatologist-recommended routines.
- State-Level Clean Beauty Incentives:California's Safer Consumer Products program offers regulatory pathways for brands eliminating parabens and phthalates.
Industry Challenges
- Cosmetic Chemist Talent Scarcity:Formulation expertise bridging traditional grooming and active skincare remains concentrated among a limited pool of specialists.
- FTC Claim Substantiation Burden:Clinical testing requirements for performance advertising are extending product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Male Grooming Products Market |
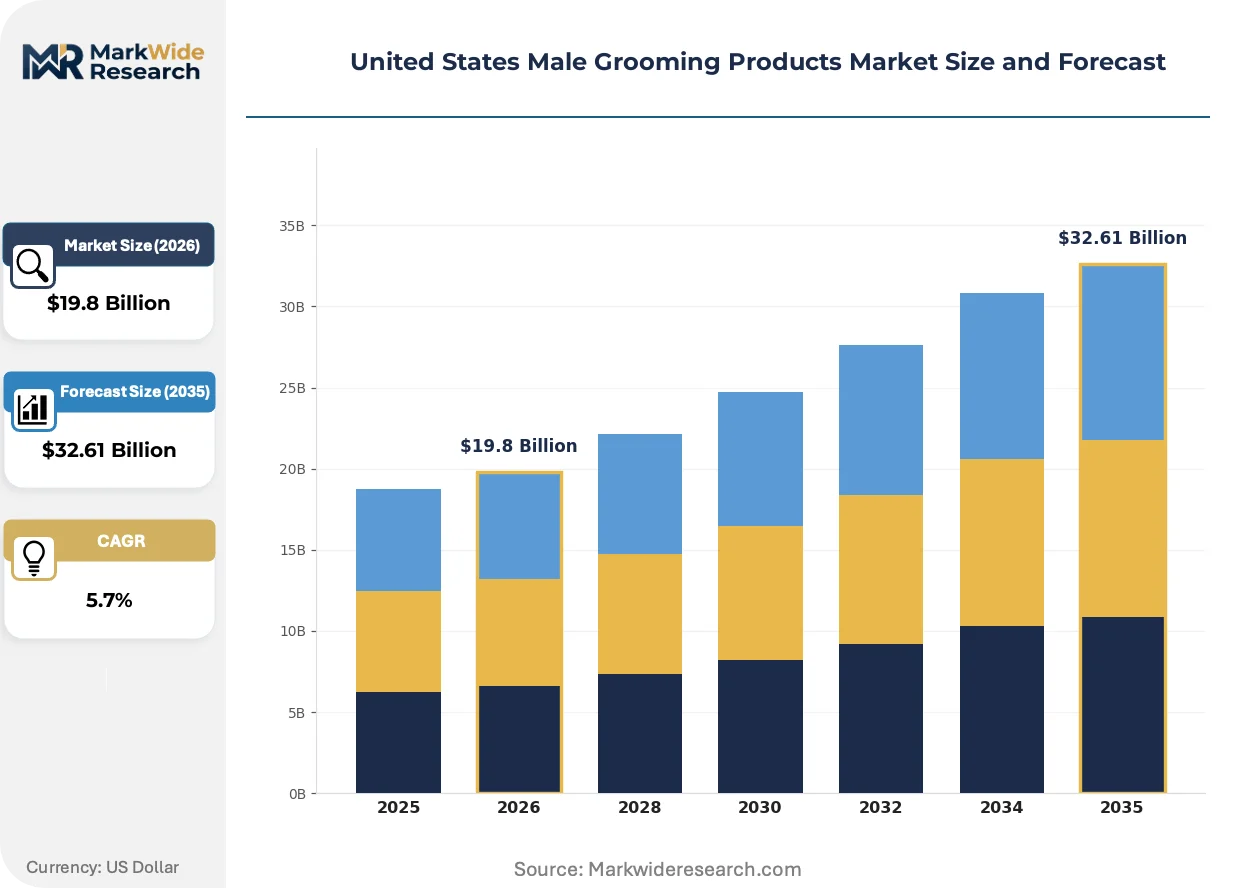
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $32.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shaving Cream, Beard Oil, Hair Gel, Aftershave Packaging Type: Tubes, Jars, Pumps, Kits Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Pharmacies End User: Millennials, Gen Z, Professionals, Athletes |
| Companies Covered | Beiersdorf, Edgewell Personal Care, Procter & Gamble, Johnson & Johnson, Coty, Unilever, Reckitt Benckiser Group, Colgate-Palmolive Company, L'Oréal, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Male Grooming Products Market Strategic Shifts & Innovations
Active botanicals and biome-friendly preservatives are displacing conventional synthetic bases as ingredient transparency becomes a non-negotiable purchase criterion across generational segments.
Microbiome-supporting prebiotic formulations are converging with traditional aftershave applications. Gen Z buyers in metropolitan California and Texas are adopting these products twice as fast as national averages. This convergence is compressing the historical separation between dermatological skincare and mass-market grooming.
The FTC's updated guidance on environmental marketing claims is tightening substantiation standards for "clean" and "natural" product positioning. Manufacturers must now maintain documentary evidence for biodegradability assertions. Premium lines targeting coastal urban professionals are most affected, with several reformulating to remove ambiguous terminology.
Specialty retailers are unbundling replenishment from discovery, pushing subscription platforms to compete on curation rather than convenience alone. Urban male professionals in California and Texas are consolidating purchases through curated kit services. This behavioral shift is most visible among millennials aged 28-38 seeking simplified routines.
United States Male Grooming Products Market Segmentation
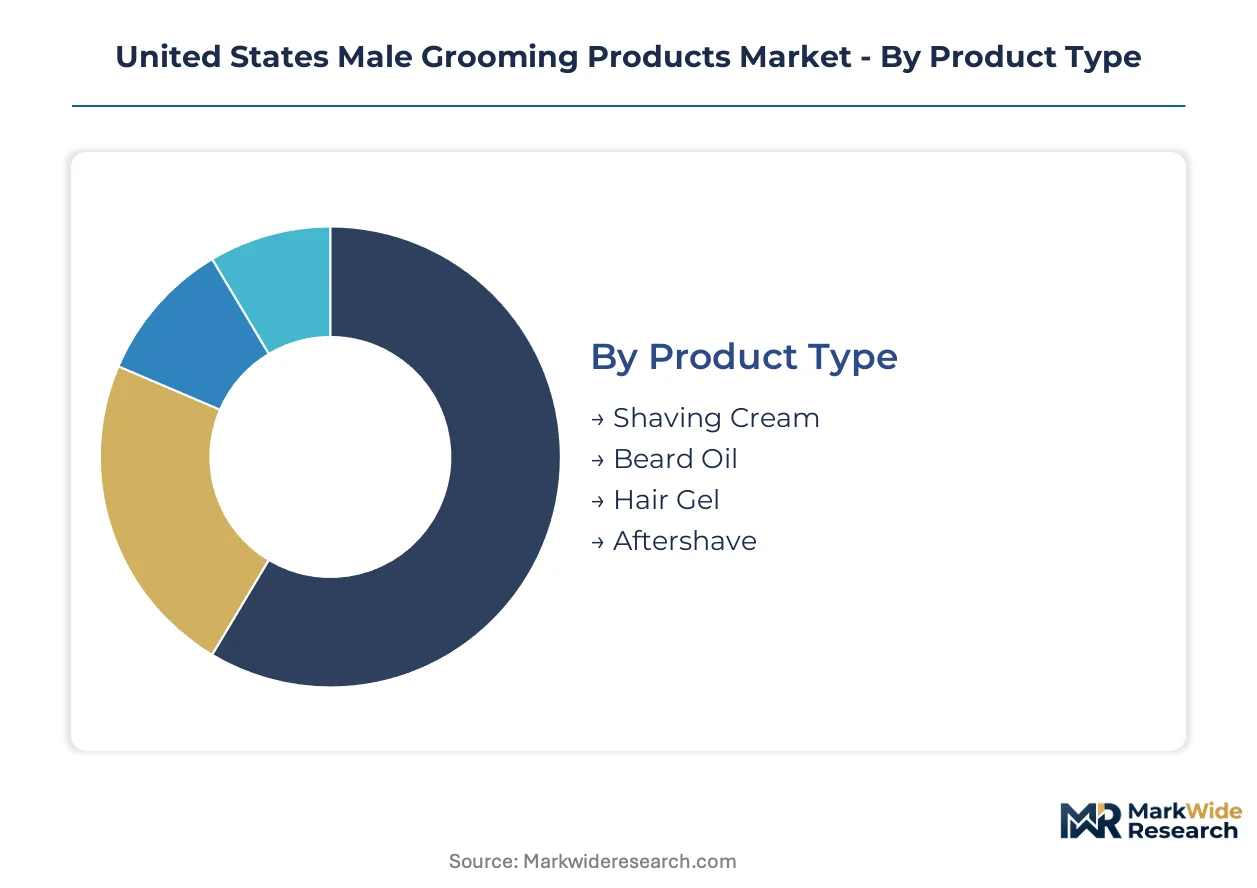
Segmentation in the United States male grooming products market reveals distinct purchasing patterns across generational cohorts and channel preferences. Manufacturers must align formulation complexity and packaging formats with the specific ritual expectations of each buyer type.
Product Type:
Standalone topical formulations dominate daily use routines, while hybrid formats increasingly embed skincare actives for multi-functional appeal.
- Shaving Cream:Lubricating emulsions incorporating glycerin and stearic acid reduce blade friction during hair removal. Demand clusters among professionals in Texas metropolitan areas where workplace grooming standards mandate close-shaven appearance.
- Beard Oil:Plant-derived carrier oils such as jojoba and argan deliver conditioning polymers to facial hair shafts and underlying skin. Urban male professionals in California drive premium positioning as beard maintenance converges with skincare rituals.
- Hair Gel:PVP and carbomer-based styling polymers provide hold and texture definition for short to medium hair lengths.
- Aftershave:Astringent and moisturizing formulations reduce post-shave irritation through witch hazel or aloe vera bases.
Volume placements concentrate in Shaving Cream; the faster expansion belongs to Beard Oil.
Packaging Type:
Format selection tracks price tier and replenishment frequency, with single-use portability commanding premium positioning versus bulk household formats.
- Tubes:Collapsible aluminum or laminated plastic containers protect viscous formulations from oxidation and contamination. Mass-market shaving creams and hair gels rely on this format for shelf efficiency in supermarkets and pharmacies.
- Jars:Wide-mouth glass or polypropylene vessels accommodate scoop-application products such as beard balms and styling pomades. Gen Z buyers in California urban clusters favor this format for aesthetic display and precise portion control.
- Pumps:Metered-dispensing systems reduce product waste and improve hygiene for liquid formulations.
- Kits:Curated multi-product bundles consolidate discovery and replenishment for gift occasions and routine simplification.
Unit economics favor Tubes at mass scale; Kits capture the steepest margin expansion trajectory.
Distribution Channel:
Channel strategy must reconcile discovery-driven trial with the replenishment efficiency that sustains lifetime value.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators enable subscription replenishment and algorithmic personalization. Millennials aged 28-38 consolidate purchases here for convenience and access to niche formulations unavailable in physical retail.
- Supermarkets:High-velocity shelf space in grocery chains anchors mass-market volume for established brands with household recognition.
- Specialty Stores:Curated assortments in men's grooming boutiques and barbershop retail extensions facilitate expert-guided trial.
- Pharmacies:Drugstore chains emphasize therapeutic-positioned products with dermatologist endorsement or sensitive-skin claims.
Supermarkets and pharmacies hold established volume positions; Online Retail is gaining share fastest.
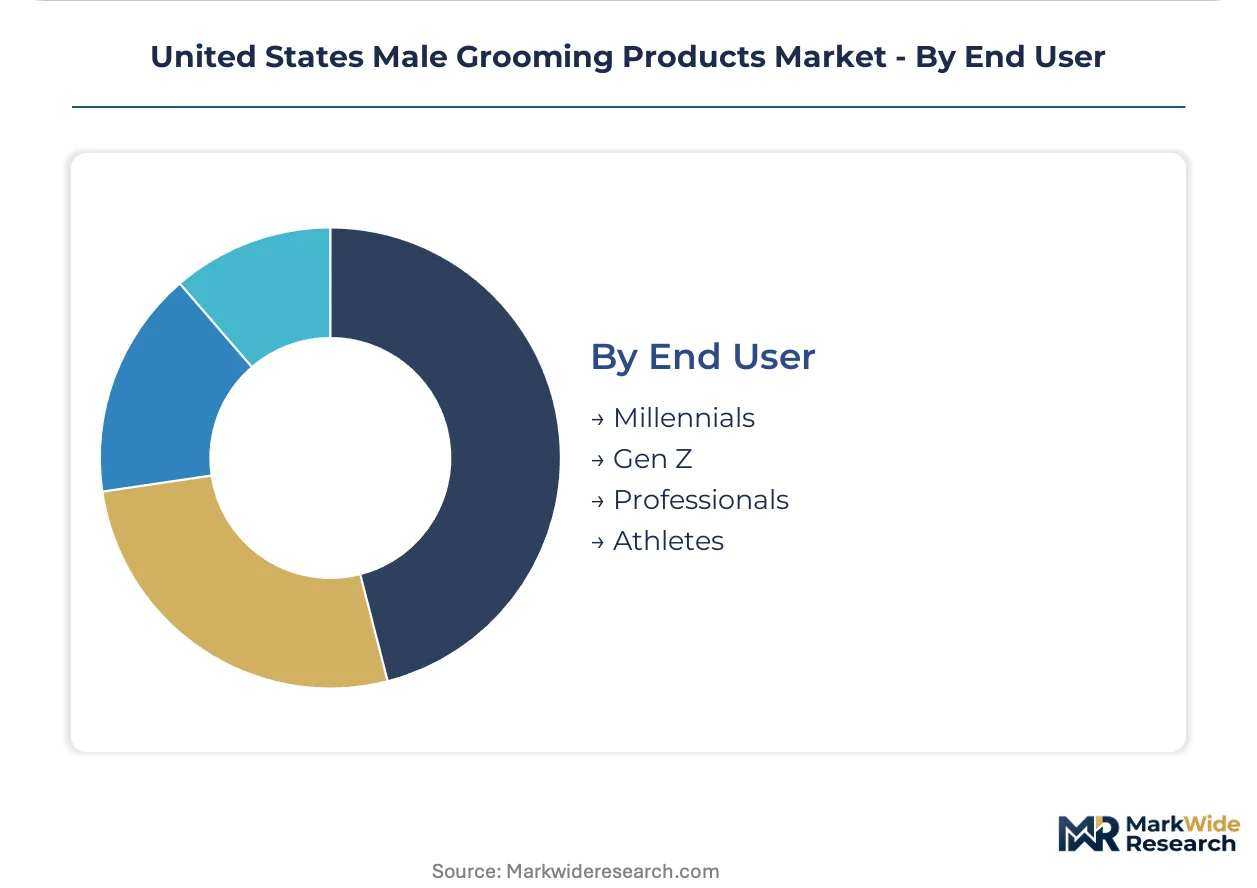
End User:
Generational and occupational segments fragment around ritual complexity, from minimal viable routines to elaborate multi-step systems.
- Millennials:Buyers aged 28-43 balance career-stage appearance investment with family budget constraints, favoring kit-based simplification.
- Gen Z:Younger consumers prioritize ingredient transparency and hybrid functionality, adopting beard care and skincare convergence at double the national average rate in California and Texas.
- Professionals:Workplace appearance standards drive consistent replenishment of shaving and styling products.
- Athletes:Performance-oriented buyers seek sweat-resistant hold and rapid-recovery skin conditioning for active lifestyles.
Millennials and Professionals anchor current volume; Gen Z exhibits the most rapid behavioral shift toward premium hybrid formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban male professionals in California and Texas generate disproportionate demand for premium grooming formulations, while metropolitan clusters in the Northeast and Midwest sustain volume through established replenishment channels.
California
Gen Z consumers in Los Angeles and San Francisco metropolitan areas adopt hybrid beard care and skincare products at double the national average rate. The state's Department of Public Health enforces expanded fragrance disclosure mandates through the Safer Consumer Products program. San Diego's grooming retail corridor attracts direct-to-consumer brands seeking coastal urban visibility.
Texas
Dallas and Houston workplace appearance standards drive consistent demand for kit-based grooming systems among professionals aged 28-43. The Texas Commission on Environmental Quality monitors volatile organic compound emissions from aerosol-format hair products. Austin's emerging grooming boutique cluster serves as a test market for microbiome-friendly prebiotic formulations.
New York Metro
Millennial buyers in Manhattan and Brooklyn consolidate purchases through subscription platforms prioritizing curation over convenience. The New York State Department of Environmental Conservation regulates aerosol propellant formulations under air quality standards. Specialty retailers in SoHo and Williamsburg unbundle discovery from replenishment through expert-guided trial experiences.
Florida
Sweat-resistant styling products capture demand among athletic professionals in Miami and Orlando metropolitan areas. The Florida Department of Agriculture and Consumer Services oversees cosmetic labeling compliance for products distributed through pharmacy chains. Tampa's grooming subscription fulfillment infrastructure supports Southeast regional distribution networks.
Illinois
Mass-market volume concentrates in Chicago's supermarket and pharmacy corridors where established brands anchor household replenishment cycles. The Illinois Environmental Protection Agency evaluates aluminum and glass packaging alternatives to single-use plastics. Suburban Cook County distribution centers serve as Midwest logistics hubs for direct-to-consumer replenishment models.
United States Male Grooming Products Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue skincare-convergence and subscription channel penetration. The market exhibits tiered concentration with mass-market scale players dominating supermarket shelf space while specialty operators capture premium margins through curated assortments. Three archetypes define competitive positioning: diversified consumer goods conglomerates with grooming divisions, specialized personal care companies focused on hardware and blade systems, and premium skincare-infused grooming specialists targeting urban professionals. Dominant competitive moves include portfolio diversification into hybrid formulations and strategic partnerships with subscription platforms to secure recurring revenue.
Within the diversified conglomerate tier, Procter & Gamble and Unilever exemplify mass-market scale operations with extensive supermarket and pharmacy presence. Edgewell Personal Care occupies a specialized position focused on shaving hardware and blade system innovation. L'Oréal represents the premium skincare-convergence archetype through dermatologist-recommended grooming lines targeting metropolitan professionals.
| Leading Market Players |
|---|
| Beiersdorf |
| Edgewell Personal Care |
| Procter & Gamble |
| Johnson & Johnson |
| Coty |
| Unilever |
| Reckitt Benckiser Group |
| Colgate-Palmolive Company |
| L'Oréal |
| Others |
Cost & Logistics Intelligence
Captive production of conditioning polymers and plant-derived emollients anchors both supply security and premium pricing power for manufacturers targeting California and Texas urban professionals. FDA oversight of cosmetic-drug classification thresholds forces reformulation investments that compress mass-market margins while rewarding specialized players with pricing flexibility.
Pricing Analysis
Volume placements concentrate in mass-market tubes and supermarket channels where price sensitivity runs highest among suburban millennial households. Premium-mid-economy pricing differentiation separates dermatologist-endorsed skincare-convergence lines from basic grooming staples. Pricing pressure stems from aluminum and glass packaging alternatives carrying unit cost premiums that squeeze accessibility. Professional athletes and Gen Z urban buyers exhibit the least price sensitivity, prioritizing ingredient transparency and hybrid functionality over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with petroleum-derived hydrocarbon feedstocks for aerosol propellants sourced from concentrated energy markets. Manufacturing draws from domestic compounding facilities in California and Texas alongside contract producers in Mexico and Canada. Tariff exposure on imported botanical actives from India and Morocco threatens margin stability for premium beard oil formulations. Distribution runs through direct-to-consumer subscription platforms, supermarket replenishment cycles, and specialty retailer discovery channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around players with formulation chemistry capabilities and subscription infrastructure, as FDA claim substantiation burdens and extended launch cycles force undercapitalized competitors toward exit.
For Market Incumbents: Hedge against Gen Z fragmentation by acquiring microbiome-friendly formulation specialists in Austin and San Diego test markets. Lock in backward integration of jojoba and argan oil supply through long-term offtake agreements with Moroccan and Indian agricultural cooperatives. Channel control through barbershop retail extensions defends against direct-to-consumer disintermediation. For New Entrants and Emerging Players: Subscription-platform curation offers the lowest barrier to millennial professionals in Dallas and Houston seeking kit-based simplification. Target white-space in sweat-resistant styling products for Florida athletic professionals, where incumbent coverage remains thin. Pursue go-to-market partnerships with California-based clean beauty retailers leveraging state-level Safer Consumer Products regulatory alignment. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified personal care conglomerates seeking skincare-convergence capabilities. Five-to-ten year viability favors brands with established subscription recurring revenue and FDA-compliant claim substantiation documentation. Watch for inflection in state-level paraben and phthalate ban acceleration as signal for clean formulation premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Subscription Launch | Captures recurring revenue from millennial buyers consolidating purchases through curated kit services. |
| Skincare-Convergence Formulation Investment | Addresses Gen Z preference for hybrid beard care and niacinamide-infused post-shave balms. |
| Sustainability Repositioning | Aligns with California fragrance disclosure mandates and EPA volatile organic compound scrutiny. |
| Distribution Channel Expansion | Penetrates specialty retailers in SoHo and Williamsburg unbundling discovery from replenishment. |
| Regulatory Compliance Investment | Preempts FDA drug-level reclassification risk for anti-aging and acne prevention therapeutic claims. |
Research Approach
Multi-period observation of Gen Z purchasing velocity, subscription platform growth rates, and state regulatory filing volumes anchored the trend analysis, supplemented by interviews with cosmetic chemists, brand managers at established personal care conglomerates, category buyers at pharmacy chains, and supply planners at aluminum packaging manufacturers. Secondary validation drew from FDA cosmetic registration databases, EPA volatile organic compound emission reports, Nielsen retail audit data, and customs records of botanical oil imports. Bottom-up demand modeling triangulated against top-down market sizing across generational cohorts.
Segment-weighting applied differential growth assumptions to product type, packaging format, distribution channel, and end-user generational cohort dimensions throughout the forecast period. CAGRs derived from regression analysis of historical velocity trends projected against regulatory event timelines and channel shift trajectories. Forecast inputs incorporated California Safer Consumer Products program expansion scenarios and FTC claim substantiation burden impact on launch cycle durations.
The model holds under stable FDA cosmetic classification boundaries and continued state-level clean beauty incentive programs; deviation in federal drug-level reclassification or accelerated petroleum feedstock cost volatility would shift trajectory. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Organic Shampoo Market
Beauty & Personal Care
Foaming Hand Soaps Market
Beauty & Personal Care
Online Cosmetics Market
Beauty & Personal Care
Makeup Brush and Tool Market
Beauty & Personal Care
Brazil Beauty and Personal Care Products Market
Beauty & Personal Care
Skincare Market
Beauty & Personal Care
Lip Care Market
Beauty & Personal Care
Facial Massager Market
Beauty & Personal Care
Europe Hair and Skincare Market
Beauty & Personal Care
Nail Care Products Market
Beauty & Personal Care
Asia-Pacific Bath and Shower Products Market
Beauty & Personal Care
United States Beauty and Personal Care Products Market
Beauty & Personal Care
Face Makeup Market
Beauty & Personal Care
Beauty Devices Market
Beauty & Personal Care
Global Heated Eyelash Curlers Market
Beauty & Personal Care
Male Grooming Products Market