
 Underarm Antiperspirant and Deodorant Market | 2026-2036
Underarm Antiperspirant and Deodorant Market Size, Share, and Industry Trends Forecast 2026-2036
Underarm Antiperspirant and Deodorant Market Insights
Market Context
The capital-intensity divergence between mass-market and premium personal-care players is unwinding as niche brands scale manufacturing. Procter and Gamble leverages its global distribution infrastructure to maintain shelf dominance across hypermarkets and pharmacies. Beiersdorf AG anchors its position through dermatological credibility and sustained R&D investment in skin-tolerance formulations. Unilever PLC competes via aggressive emerging-market penetration and localized scent portfolios.
Technical and Segment Structure
Underarm antiperspirant and deodorant comprises topical formulations containing aluminum chloride or zirconium complexes that temporarily obstruct eccrine sweat ducts, alongside deodorant variants that mask or neutralize odor through antimicrobial agents or fragrance encapsulation. The stick format dominates volume due to convenience and travel compatibility, while natural-ingredient formulations capture expanding margin pools as consumers reject aluminum compounds. Biodegradable packaging represents the fastest-growing packaging segment, though aerosol cans still sustain volume in Latin American and Southeast Asian markets where spray application remains culturally preferred.
Regulatory Environment
Regulators including the FDA, ECHA under REACH, and Health Canada scrutinize aluminum bioaccumulation claims and aerosol propellant classifications, forcing reformulation investments and label transparency upgrades. The EU Green Deal and CSRD extend pressure into packaging circularity mandates and supply-chain emissions disclosure. Stakeholders must monitor evolving classification thresholds for nanomaterial suspensions in roll-on gels and prepare for state-level ingredient disclosure laws that could fragment compliance requirements across North American distribution networks.
Market Dynamics
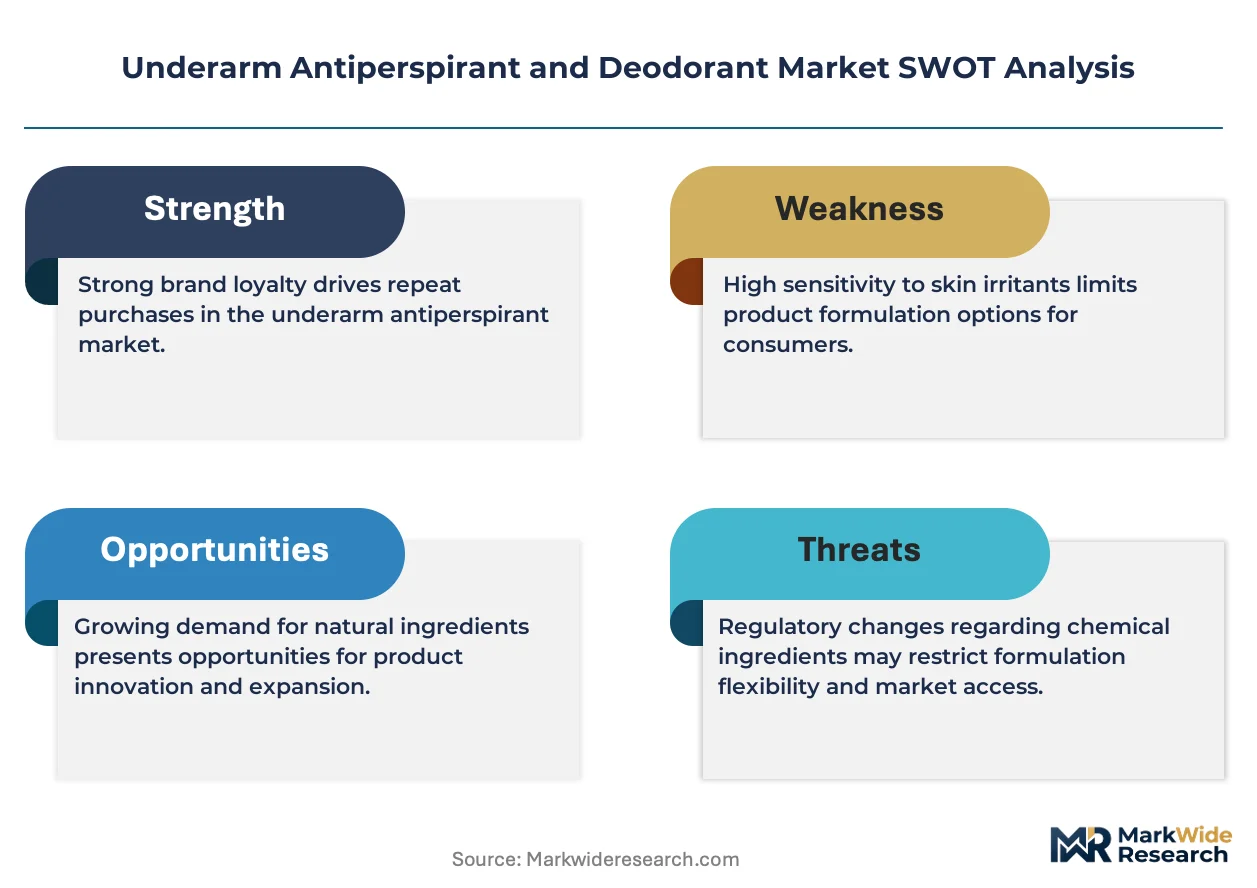
Aluminum-free formulation pipelines are absorbing disproportionate R&D capital as EFSA safety scrutiny and consumer ingredient skepticism converge, forcing incumbents to dual-track legacy and clean-label portfolios without sacrificing margin structure.
Growth Catalysts
- EFSA Ingredient Safety Reviews:European regulatory pressure on aluminum bioaccumulation is accelerating clean-label innovation cycles and opening shelf space for zirconium-based alternatives.
- Male Grooming Routine Expansion:Antiperspirant stick incorporation into daily male personal-care protocols in the United States and Germany is expanding addressable household penetration.
- Biodegradable Packaging Mandates:EU Green Deal circularity requirements are pulling polymer innovation investment toward compostable stick housings and paperboard push-up formats.
Market Restraints
- Aluminum Salt Supply Concentration:Zirconium and aluminum chloride feedstock refining clusters in China create single-source vulnerability for Western formulators.
- Aerosol Propellant Reclassification:ECHA REACH restrictions on volatile organic compound thresholds are forcing Latin American and Southeast Asian manufacturers into costly propellant reformulation.
- Natural Ingredient Cost Volatility:Arrowroot powder, baking soda, and essential oil harvests face climate-driven price swings that compress margin on aluminum-free SKUs.
Strategic Opportunities
- India Tier-2 Urban Expansion:Underpenetrated deodorant adoption in Surat, Indore, and Coimbatore offers whitespace for roll-on and spray format introduction.
- CSRD Supply-Chain Disclosure:EU corporate sustainability reporting mandates create first-mover advantage for brands with verified Scope 3 emissions tracking.
- Smart Packaging Convergence:NFC-enabled sticks connecting to refill subscription apps are unlocking direct-to-consumer retention in premium segments.
Industry Challenges
- Clinical Efficacy Certification Timelines:FDA 510(k) pathways for novel antiperspirant actives extend 18-24 months, delaying aluminum-free claims with sweat-reduction efficacy.
- Fragrance Chemist Talent Scarcity:Formulation expertise at the intersection of natural preservation and microbiome compatibility commands premium compensation and constrains scale-up velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Underarm Antiperspirant and Deodorant Market |
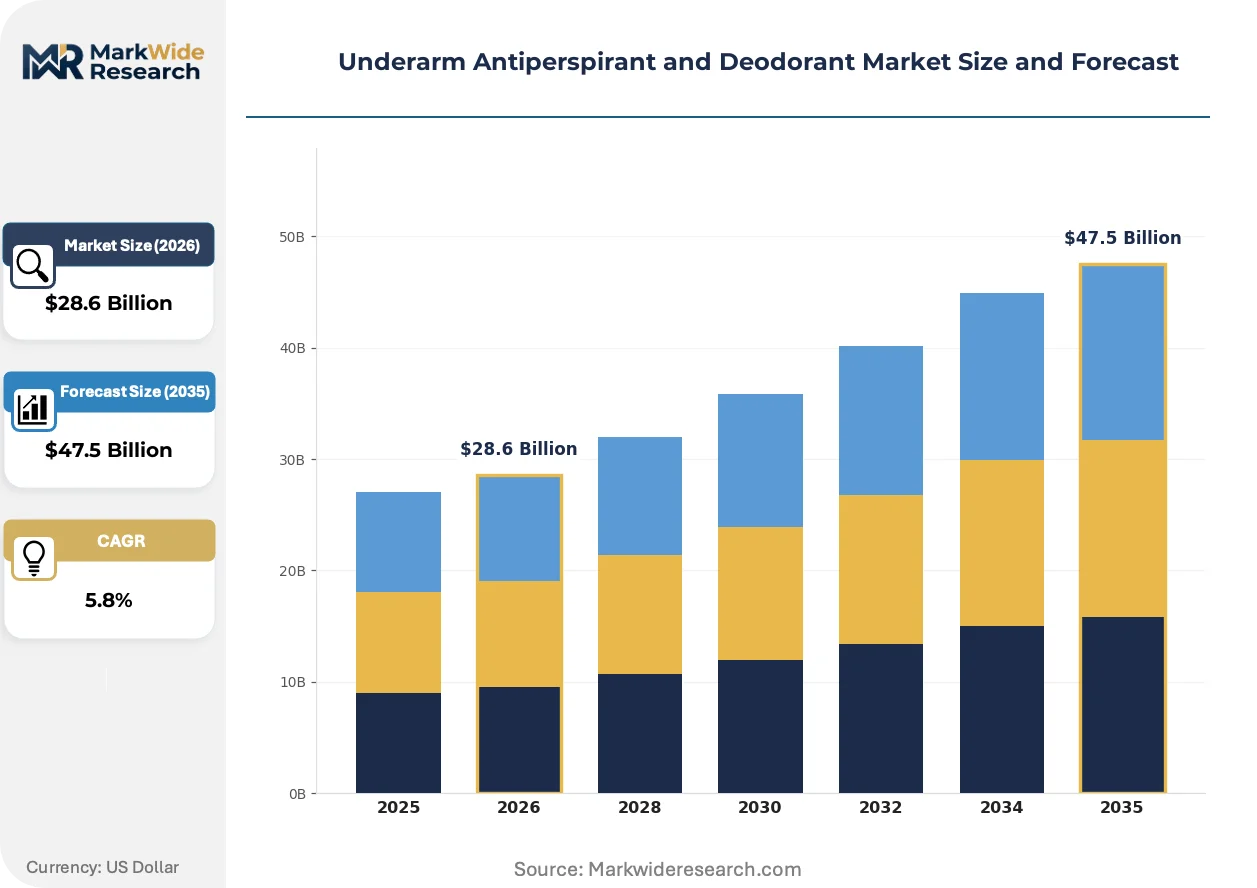
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stick, Roll-On, Spray, Gel Ingredient Type: Aluminum Compounds, Natural Ingredients, Alcohol-Free, Fragrance-Free Packaging Type: Tubes, Jars, Aerosol Cans, Biodegradable Packaging User Type: Men, Women, Unisex, Teens |
| Companies Covered | Henkel AG and Co KGaA, Colgate-Palmolive Company, Unilever PLC, Kao Corporation, Reckitt Benckiser Group PLC, Procter and Gamble, L’Oreal S.A., Church and Dwight Co., Inc, Beiersdorf AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Underarm Antiperspirant and Deodorant Market Trends and Innovations
Formulation science and packaging engineering are diverging from legacy aluminum complexes toward microbiome-conscious actives and zero-waste delivery systems, reshaping competitive investment priorities.
Encapsulated fragrance-release technology is miniaturizing volatile compound delivery into time-released microspheres that extend scent longevity across 12-hour wear cycles. Premium natural brands in Germany and the United States are adopting this at scale to match aluminum-based product performance claims. The technology is miniaturizing the efficacy gap between conventional and clean-label formulations, compressing consumer trade-off tolerance.
REACH authorization requirements for nanomaterial suspensions in roll-on gels are forcing reformulation of particle-dispersion chemistries across EU manufacturing facilities. The industrial consequence is a shift toward macro-emulsion alternatives that sacrifice some cosmetic elegance for compliance certainty. Roll-on segments in France and Italy are absorbing the highest compliance costs as ANSM intensifies post-market surveillance.
Subscription-based refill programs are displacing single-use stick purchases in direct-to-consumer channels, with consumers accepting 10-15% per-unit premiums for packaging-free replenishment. Sephora and Ulta Beauty are carving dedicated shelf space for refillable deodorant systems, accelerating format experimentation. This pattern concentrates in coastal United States metro areas where waste-reduction purchasing correlates with household income thresholds.
Underarm Antiperspirant and Deodorant Market Segmentation
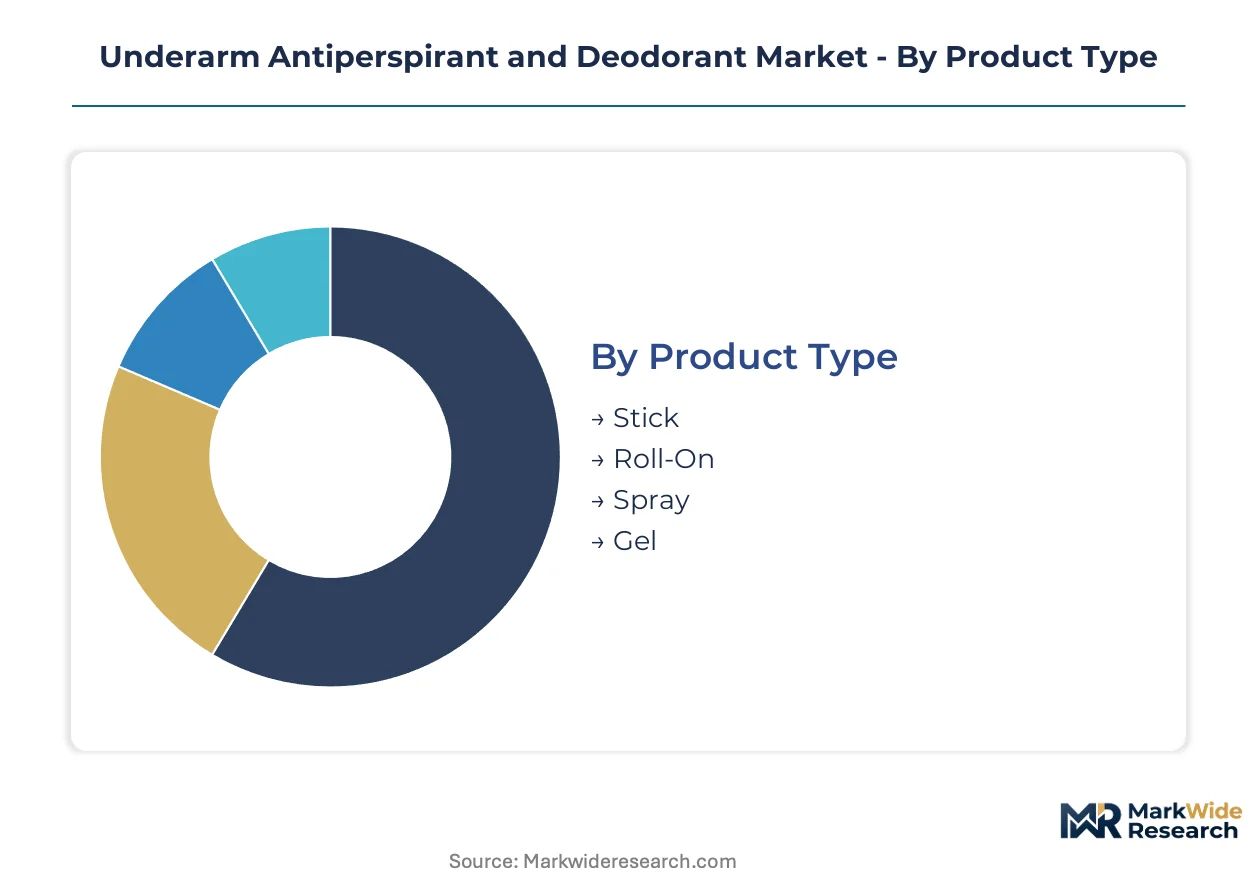
Segmentation in underarm antiperspirant and deodorant reveals divergent growth vectors across formulation chemistry, delivery mechanics, and demographic targeting. Manufacturers must align R&D pipelines and packaging investments with the specific performance expectations and regulatory exposures of each segment cluster.
Product Type:
Stick formats dominate domestic consumption in the United States and Germany, while spray adoption concentrates in export-dependent Latin American and Southeast Asian markets where aerosol application remains culturally embedded.
- Stick:Solid wax-based formulations combining aluminum zirconium complexes with emollient carriers deliver precise application control. Demand concentrates among male grooming routines in the United States, driven by gym-bag portability and TSA travel compliance. The format absorbs disproportionate R&D investment as brands engineer biodegradable paperboard housings to meet EU Green Deal mandates.
- Roll-On:Liquid suspension systems utilizing ball-applicator mechanisms provide even coverage for sensitive skin applications. German and French consumers favor this format for dermatological credibility, though ECHA REACH nanomaterial scrutiny is forcing reformulation of particle-dispersion chemistries into macro-emulsion alternatives.
- Spray:Pressurized aerosol systems dominate Mexican and Brazilian household penetration due to climate-driven refreshment preferences and shared-family usage patterns. ECHA volatile organic compound thresholds are propelling propellant transition costs.
- Gel:Clear-drying silicone and water-based formulations target visible-residue avoidance in professional apparel contexts. Japanese and South Korean markets show concentrated adoption among white-collar demographics.
Stick holds the largest share; momentum sits with spray formats in emerging market expansion.
Ingredient Type:
Cost-tier stratification separates legacy aluminum formulations from premium-positioned natural alternatives, with mid-tier alcohol-free and fragrance-free variants capturing price-sensitive consumers seeking compromise solutions.
- Aluminum Compounds:Aluminum chloride and zirconium complex formulations provide clinically validated sweat-duct occlusion. Mass-market volume concentrates in Walmart and CVS distribution networks across the United States, though EFSA bioaccumulation reviews are eroding consumer confidence and forcing dual-track portfolio management.
- Natural Ingredients:Arrowroot powder, baking soda, and essential oil blends deliver odor neutralization without metal salts. Premium natural-ingredient seekers in coastal United States metro areas and German organic retail channels drive 10-15% per-unit pricing premiums, though climate-driven agricultural volatility compresses margin stability.
- Alcohol-Free:Glycerin and propylene glycol-based formulations target post-shave irritation avoidance and sensitive skin tolerance. Post-procedure dermatology recommendations in France and Switzerland sustain niche positioning.
- Fragrance-Free:Unscented variants serve workplace policy compliance and allergy-prone demographics. Institutional procurement in healthcare and food-service sectors in Canada and Australia generates steady contract volume.
Aluminum compounds retain volume dominance; natural ingredients are climbing the fastest as clean-label skepticism accelerates.
Packaging Type:
Packaging maturity curves diverge sharply, with conventional polymer and metal formats facing displacement pressure from circularity-mandated alternatives in European markets while legacy formats sustain volume in price-sensitive regions.
- Tubes:Flexible laminate and squeeze-tube formats dominate gel and cream delivery systems. Southeast Asian manufacturing clusters in Thailand and Vietnam supply cost-optimized extrusion capacity for mass-market brands.
- Jars:Wide-mouth rigid containers serve cream-based deodorant and baking soda paste formulations. Artisanal and direct-to-consumer brands in Portland and Brooklyn utilize this format for refill-subscription program differentiation.
- Aerosol Cans:Steel and aluminum pressurized containers sustain spray format distribution. Brazilian and Argentine regulatory lag relative to EU VOC restrictions preserves manufacturing continuity, though ECHA alignment pressure is building.
- Biodegradable Packaging:Compostable stick housings, paperboard push-up tubes, and mushroom-derived mycelium containers represent polymer innovation frontiers. EU CSRD supply-chain disclosure requirements advantage early adopters with verified Scope 3 emissions tracking.
Aerosol cans maintain installed-base volume; biodegradable packaging shows steepest expansion trajectory as circularity mandates harden.
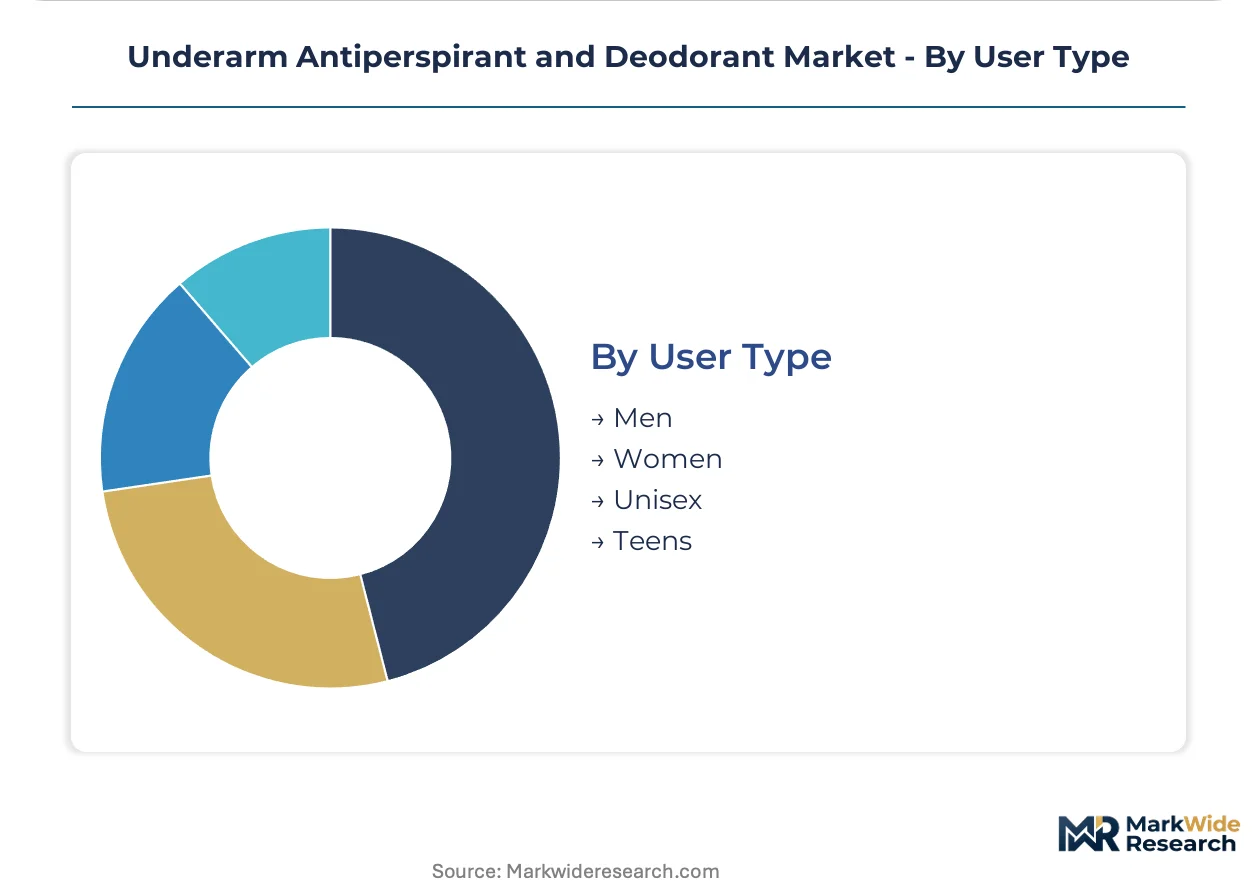
User Type:
Customer-type targeting reflects divergent distribution channel strategies, with gendered marketing sustaining mass-retail presence while unisex and teen positioning unlocks direct-to-consumer and social-commerce pathways.
- Men:Masculine-coded fragrance profiles and higher-strength antiperspirant claims capture gym and workplace placement. Procter and Gamble's Gillette-aligned distribution secures shelf dominance in Target and Walgreens male grooming aisles.
- Women:Skin-conditioning additives and invisible-dry claims dominate Sephora and Ulta Beauty premium positioning. Dermatological endorsement partnerships with Mayo Clinic and Cleveland Clinic sustain credibility premiums.
- Unisex:Neutral fragrance palettes and minimalist branding attract cohabiting household consolidation. Subscription refill programs through Grove Collaborative and Blueland concentrate in high-income coastal demographics.
- Teens:Entry-priced formats with playful scent profiles and social-media-native marketing capture first-brand loyalty. TikTok-driven discovery in the United States and United Kingdom outpaces traditional retail penetration.
Women's segment commands margin concentration; unisex positioning is gaining share fastest as household consolidation trends intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade imbalances in aluminum salt feedstocks and finished formulations are redrawing regional manufacturing footprints. Import-dependent markets face margin compression as Chinese refining clusters dominate zirconium supply chains.
United States
Premium natural-ingredient seekers in coastal metro areas drive aluminum-free SKU expansion. FDA 510(k) certification timelines delay novel active ingredient launches by 18-24 months. Cincinnati and Chicago house Procter and Gamble's distribution infrastructure sustaining mass-market shelf dominance.
Germany
Dermatological credibility anchors Beiersdorf AG's sustained R&D investment in skin-tolerance formulations. EFSA bioaccumulation reviews on aluminum compounds accelerate clean-label innovation cycles. Hamburg and Frankfurt manufacturing clusters absorb disproportionate compliance costs from REACH nanomaterial scrutiny.
China
Domestic demand for spray formats sustains aerosol can production despite ECHA-aligned VOC pressure building. NMPA cosmetic ingredient filings create dual-track regulatory navigation for export-oriented formulators. Zhejiang and Guangdong refining clusters concentrate aluminum chloride and zirconium feedstock supply.
Brazil
Climate-driven refreshment preferences entrench spray application in household penetration patterns. ANVISA regulatory lag relative to EU VOC restrictions preserves propellant manufacturing continuity. São Paulo industrial corridors sustain Latin America's largest aerosol packaging capacity.
India
Underpenetrated deodorant adoption in Surat, Indore, and Coimbatore offers whitespace for roll-on and spray format introduction. BIS cosmetic standards convergence with ASEAN harmonization pressures creates compliance investment requirements. Maharashtra and Gujarat manufacturing zones scale contract formulation for regional brands.
Underarm Antiperspirant and Deodorant Market Competitive Landscape
Concentration sits with diversified consumer goods conglomerates wielding global distribution infrastructure against insurgent clean-label specialists. Three-tier competitive structure separates mass-market volume players, premium dermatological brands, and direct-to-consumer naturals. Strategic moves center on dual-track portfolio management balancing legacy aluminum formulations with aluminum-free pipelines, alongside biodegradable packaging investments responding to EU circularity mandates.
Among diversified consumer goods conglomerates, Procter and Gamble and Unilever PLC exemplify scale-driven archetypes leveraging hypermarket and pharmacy shelf dominance. Beiersdorf AG occupies a dermatological credibility position sustained through R&D investment in skin-tolerance science. Church and Dwight Co., Inc represents the specialist tier with household and personal care diversification across baking soda-derived formulations.
| Leading Market Players |
|---|
| Henkel AG and Co KGaA |
| Colgate-Palmolive Company |
| Unilever PLC |
| Kao Corporation |
| Reckitt Benckiser Group PLC |
| Procter and Gamble |
| L'Oreal S.A. |
| Church and Dwight Co., Inc |
| Beiersdorf AG |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts for aluminum chloride and zirconium feedstock lock in supply access and price visibility for Western formulators navigating Chinese refining concentration. These arrangements tether procurement costs to Shanghai Futures Exchange benchmarks while insulating against spot volatility in agricultural inputs like arrowroot powder.
Pricing Analysis
Mass-market retailers anchor pricing stratification across premium dermatological, standard aluminum-based, and economy private-label tiers. Price differentiation hinges on certification grade for EU REACH compliance and volume scale through Walmart and CVS distribution networks. Cost compression in natural-ingredient SKUs is intensifying because climate-driven agricultural volatility squeezes arrowroot and baking soda margins. Institutional procurement in Canadian healthcare sectors shows least price sensitivity, while teen-entry segments in TikTok-native channels absorb highest elasticity.
Supply Chain Analysis
Port congestion at Ningbo and Shanghai elevates inbound logistics costs for aluminum salt feedstock destined for German and US manufacturing clusters. Zirconium refining concentrates in Zhejiang and Guangdong provinces, while essential oil extraction feeds from Indian and Indonesian agricultural belts. Single-source vulnerability runs through Chinese aluminum chloride clusters. Distribution runs through hypermarket and pharmacy networks for mass-market volume, with direct-to-consumer refill subscriptions carving parallel pathways in coastal US metro areas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based refill platforms are reconfiguring this market toward ecosystem economics, with NFC-enabled sticks and app-integrated replenishment creating interoperability between hardware and digital retention layers.
For Market Incumbents: Shield legacy aluminum formulation margins by accelerating dual-track portfolio management that segments clean-label SKUs into premium channels without cannibalizing mass-market volume. Secure dermatological certification investment for skin-tolerance claims that Beiersdorf AG has anchored in German retail. Channel control through hypermarket shelf dominance remains critical as TikTok-native entrants erode teen-segment loyalty.
For New Entrants and Emerging Players: Differentiate on biodegradable packaging convergence by targeting EU Green Deal circularity mandates with compostable stick housings that incumbent polymer infrastructure cannot pivot toward quickly. White-space concentrates in Indian Tier-2 urban expansion across Surat and Indore, where roll-on format introduction lags deodorant adoption curves. Direct-to-consumer subscription apps offer the most penetrable go-to-market angle for bypassing established retail gatekeepers.
For Investors and Strategic Acquirers: Capital is best deployed toward aluminum-free formulation specialists with verified Scope 3 emissions tracking that satisfies CSRD disclosure requirements ahead of compliance deadlines. Long-term viability favors brands that have secured FDA 510(k) pathways for novel antiperspirant actives, given certification timelines that delay competitive entry. Monitor EFSA aluminum bioaccumulation review outcomes as the inflection signal that could accelerate clean-label substitution rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Packaging Transition | EU Green Deal mandates pull polymer innovation toward compostable stick housings and paperboard formats. |
| Aluminum-Free Formulation Pipeline | EFSA safety scrutiny accelerates R&D investment in zirconium-based alternatives and microbiome-conscious actives. |
| Direct-to-Consumer Refill Launch | NFC-enabled sticks connecting to subscription apps unlock retention premiums in Sephora and Ulta Beauty channels. |
| India Tier-2 Distribution Expansion | Underpenetrated deodorant adoption in Surat and Coimbatore offers whitespace for roll-on format introduction. |
| CSRD Supply-Chain Disclosure Investment | Verified Scope 3 emissions tracking creates first-mover advantage as EU corporate sustainability reporting mandates harden. |
Research Methodology
A standing panel of brand managers at multinational consumer goods conglomerates, category buyers at Target and Walgreens, supply planners for aluminum salt procurement, and channel sales heads in direct-to-consumer platforms provided ongoing calibration across primary fieldwork. Secondary validation drew from Nielsen retail audit data, customs records for zirconium feedstock trade flows, SEC 10-K filings for Procter and Gamble and Unilever PLC, and EFSA ingredient safety review documentation. Bottom-up SKU-level volume builds triangulated against top-down category expenditure models.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled formulation chemistry, delivery mechanics, packaging format, and demographic targeting dimensions alongside regional regulatory cluster exposure. CAGRs were derived from segment-level growth trajectory synthesis. Forecast inputs incorporated ECHA REACH nanomaterial authorization timelines and FDA 510(k) certification pathway durations for novel actives.
The analysis sits within stated boundaries; outcomes outside EFSA aluminum bioaccumulation rulings, BIS-ASEAN harmonization timelines, or NMPA cosmetic ingredient filing trajectories would require recalibration. Forecasts reflect documented assumptions about regulatory enforcement intensity and consumer clean-label substitution elasticity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
North America Beauty Devices Market
Beauty & Personal Care
UK Sustainable Personal Care Market
Beauty & Personal Care
Curling Irons Market
Beauty & Personal Care
Spray Tanning Market
Beauty & Personal Care
Organic Shampoo Market
Beauty & Personal Care
Organic Personal Care Market
Beauty & Personal Care
Asia-Pacific Perms and Relaxants Market
Beauty & Personal Care
Deodorant Roll-Ons Market
Beauty & Personal Care
Europe Male Grooming Products Market
Beauty & Personal Care
Cruelty-Free Makeup Market
Beauty & Personal Care
South Korea Dermocosmetics Market
Beauty & Personal Care
United Kingdom Cosmetics Products Market
Beauty & Personal Care
Europe Hair Styling Products Market
Beauty & Personal Care
Bar Soap Market
Beauty & Personal Care
Handmade False Eyelash Market
Beauty & Personal Care
Saudi Arabia Beauty and Personal Care Market