
 Hand Soap in Retail Market | 2026-2036
Hand Soap in Retail Market Size, Share, and Industry Trends Forecast 2026-2036
Hand Soap in Retail Market Insights
Refill pouch bundling with reusable dispensers is hardening as the dominant packaging configuration in retail hand soap aisles. Procter & Gamble leverages its scale to anchor shelf presence across supermarkets and pharmacies in North America. Unilever differentiates through concentrated formulas that reduce shipping weight and plastic intensity. Kao Corporation specializes in foam-dispenser compatibility, a format that commands premium positioning in Japanese and Southeast Asian retail channels.
Hand soap in retail encompasses surfactant-based cleansing formulations, typically containing anionic or amphoteric agents at concentrations between 10% and 20% active matter, manufactured through continuous saponification or synthetic detergent processes, designed for personal hygiene in domestic and commercial settings. Liquid soap retains the largest volume share across distribution channels, though foam soap is displacing conventional formats in institutional customer segments where per-use cost and water conservation drive procurement decisions. Bar soap occupies a shrinking but defensible margin pool among price-sensitive individual consumers in emerging retail markets, while gel soap competes in premium positioning through viscosity-modified formulations.
The EPA regulates antimicrobial claims under FIFRA in the United States, requiring registration for soaps marketed with pathogen-killing efficacy, while REACH and the EU Green Deal constrain surfactant chemistry and packaging recyclability across European retail. Japan's Ministry of Economy, Trade and Industry (METI) enforces labeling standards that shape how manufacturers disclose ingredient origins and biodegradability on consumer-facing packaging. Stakeholders must monitor evolving chemical restriction schedules and packaging Extended Producer Responsibility frameworks to anticipate reformulation costs and channel access requirements.
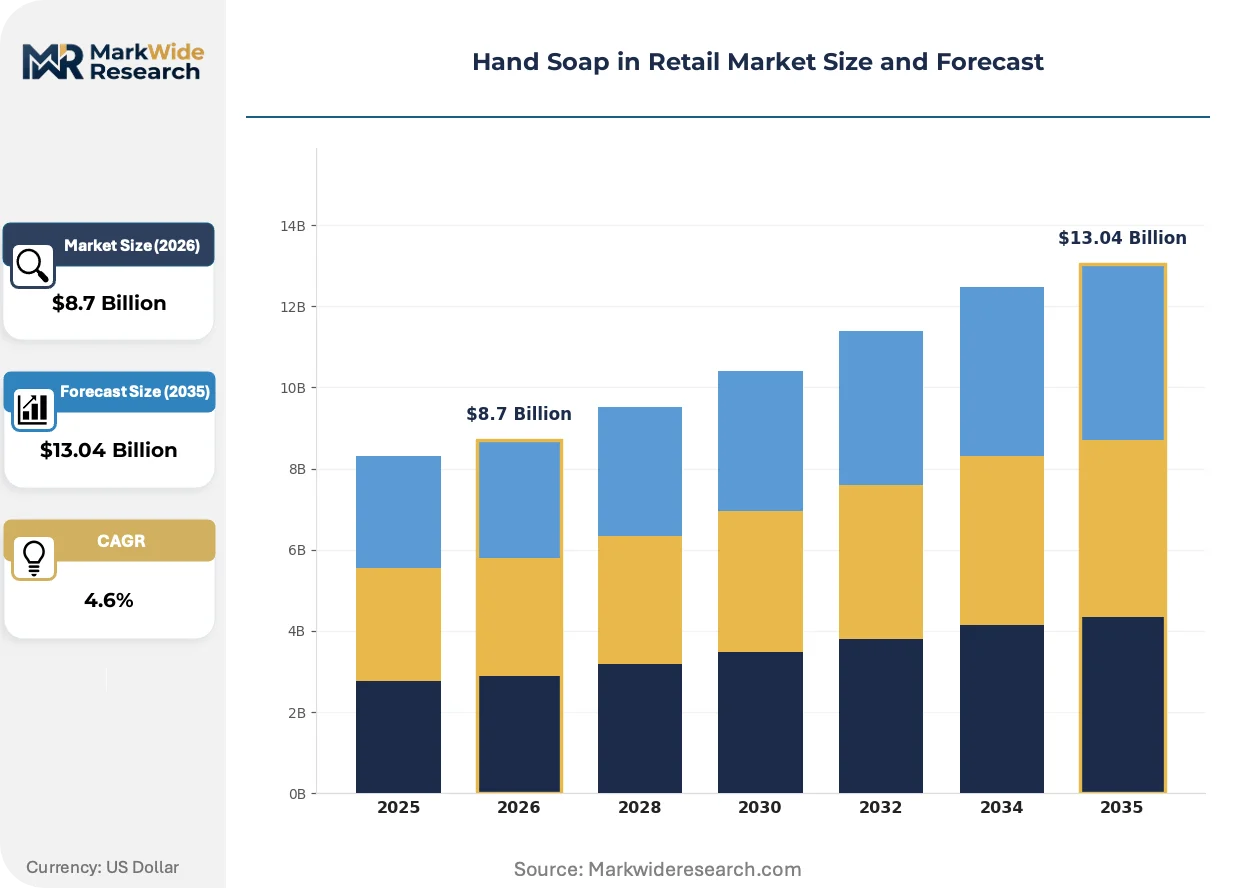
Market Dynamics
Refill pouch bundling with reusable dispensers is compressing conventional bottle formats across retail aisles, while REACH chemical standards and EU Green Deal mandates force surfactant reformulation cycles that reshape manufacturing economics.
Growth Catalysts
- Biodegradable surfactant mandates:The EU Green Deal and REACH standards accelerate manufacturer migration from petrochemical-derived agents to plant-based alternatives, opening premium shelf positioning.
- Foam-dispenser compatibility:Japanese and Southeast Asian households drive per-use cost reduction through water-conserving foam formats that require specialized pump mechanisms.
- Refill economics:Concentrated pouch formulations cut shipping weight and plastic intensity, attracting value-seeking families in Germany and the United States.
Market Restraints
- Palm oil and coconut fatty acid volatility:Feedstock price swings for natural surfactant bases compress margin predictability for formulators committed to biodegradable chemistry.
- Single-use plastic restrictions:France and Italy enforce packaging Extended Producer Responsibility frameworks that impose compliance costs on conventional bottle-dominant portfolios.
- Bar soap persistence:Price-sensitive consumers in emerging retail markets sustain demand for solid formats that bypass dispenser compatibility requirements entirely.
Strategic Opportunities
- Concentrated refill innovation:Ultra-compact dilutable formulas enable direct-to-consumer subscription channels that bypass supermarket slotting fees.
- Antimicrobial claim registration:EPA FIFRA compliance for pathogen-killing efficacy opens institutional procurement segments in healthcare and foodservice.
- Dispenser hardware bundling:Sensor-activated touchless pumps integrate with premium soap cartridges, capturing hygiene-conscious households in Japan.
Industry Challenges
- Biodegradability certification timelines:OECD 301 testing protocols for surfactant environmental fate extend product development cycles by 12-18 months.
- Legacy equipment retooling:Continuous saponification lines require capital-intensive modification to process high-foaming, low-viscosity formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hand Soap in Retail Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Soap, Foam Soap, Gel Soap, Bar Soap Customer Type: Individual Consumers, Families, Businesses, Institutions Distribution Channel: Supermarkets, Pharmacies, Online Retail, Convenience Stores Packaging Type: Bottles, Pouches, Bulk Containers, Dispensers |
| Companies Covered | Procter & Gamble, Unilever, Colgate-Palmolive, Reckitt Benckiser, Henkel, GOJO Industries, Lion Corporation, Kao Corporation, Godrej Consumer Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hand Soap in Retail Market Trends and Innovations
Waterless and solid-concentrate formats are disrupting conventional liquid supply chains, while regulatory chemistry constraints and dispenser hardware integration reshape competitive boundaries across retail channels.
Foam-dispenser pump technology converts liquid soap into aerated microbubbles through specialized mesh mechanisms, reducing per-handwash water consumption by approximately one-third. Japanese households and Southeast Asian foodservice operators adopt these systems fastest, prioritizing conservation metrics in procurement specifications. This format is overtaking conventional liquid pumps in premium retail positioning across Tokyo, Osaka, and Singapore supermarket chains.
The EU Green Deal's packaging recyclability targets and REACH surfactant restriction schedules constrain formulator chemistry choices across European manufacturing. Manufacturers must document biodegradability percentages and recycled content ratios on consumer-facing labels under METI-equivalent disclosure frameworks. German and French brands face the steepest compliance curves as national Extended Producer Responsibility schemes phase in ahead of broader EU harmonization.
Subscription-based refill replenishment bypasses traditional retail slotting fees and builds direct consumer relationships. Direct-to-consumer channels displace supermarket and pharmacy intermediaries for brand-loyal households seeking convenience and price transparency. This pattern concentrates in United States urban markets and Japanese metropolitan corridors where delivery infrastructure density supports predictable restocking intervals.
Hand Soap in Retail Market Segmentation
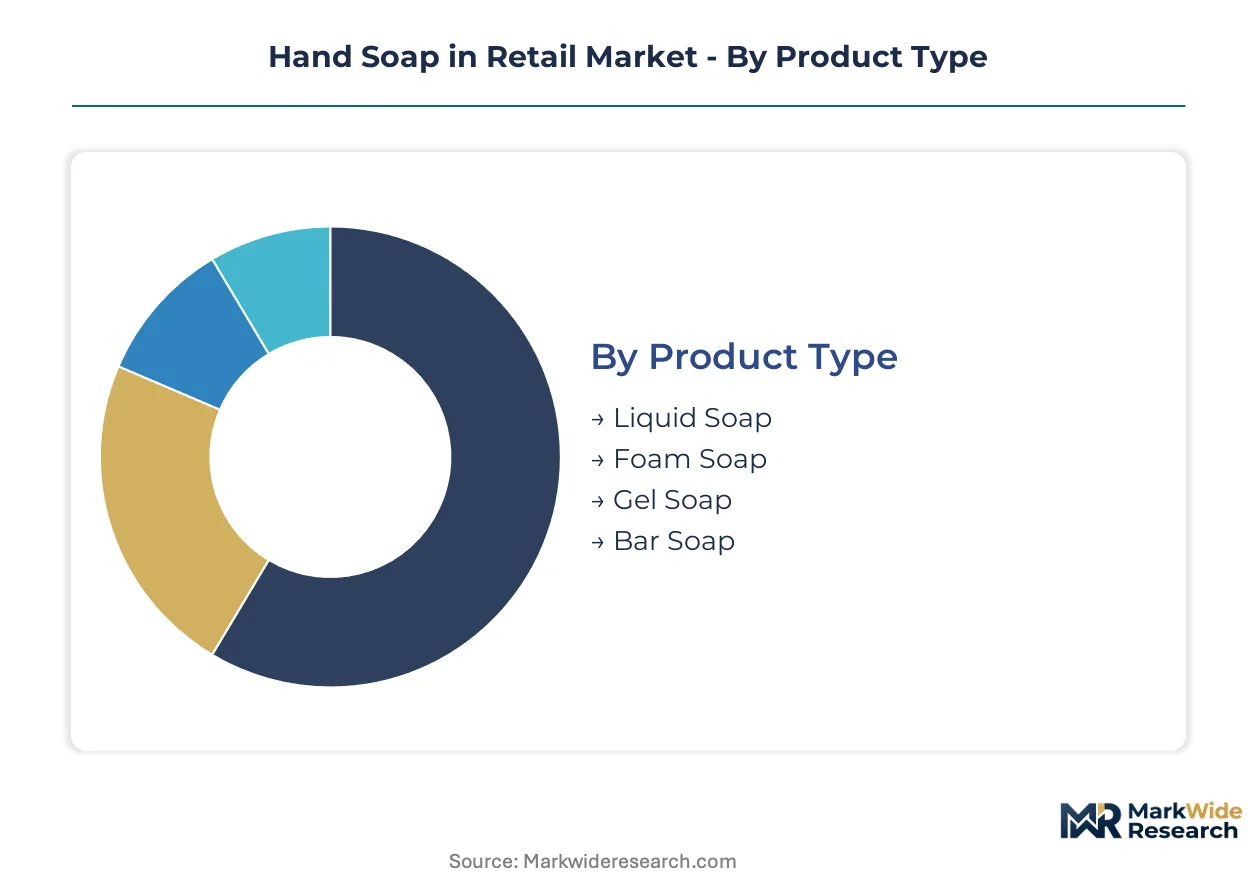
Hand soap retail segmentation reflects divergent supply chain economics across formulation chemistry, packaging engineering, and channel logistics. Manufacturers configure production lines around specific viscosity ranges and dispenser compatibility requirements that lock in customer segments.
Product Type:
Supply concentration clusters around continuous saponification capacity and surfactant blending infrastructure that favors liquid processing over solid bar manufacturing.
- Liquid Soap:Anionic and amphoteric surfactant formulations at 10-20% active matter dominate retail shelf space through pump-dispenser compatibility. United States and German supermarkets allocate prime positioning to refill-compatible variants that reduce per-use plastic intensity.
- Foam Soap:Aerated microbubble delivery through specialized mesh pump mechanisms cuts water consumption by approximately one-third per handwash. Japanese households and Southeast Asian foodservice operators drive procurement specifications that prioritize conservation metrics.
- Gel Soap:Viscosity-modified formulations targeting premium positioning through enhanced skin-conditioning additives.
- Bar Soap:Solid saponified formats sustained by price-sensitive consumers in emerging retail markets who bypass dispenser hardware requirements entirely.
Liquid soap absorbs the bulk of installed capacity; foam soap is expanding most quickly.
Customer Type:
Cost tier differentiation separates high-volume institutional contracts from premium household subscriptions that command margin premiums.
- Families:Multi-user households prioritize value-engineered refill pouches and bulk formats that minimize per-liter expenditure across high-consumption environments.
- Individual Consumers:Single-person households and travelers drive demand for portable, aesthetically packaged formats that emphasize convenience over unit economics.
- Businesses:Commercial restrooms and corporate facilities specify dispenser-compatible cartridges that reduce maintenance frequency and standardize hygiene protocols.
- Institutions:Healthcare and foodservice procurement teams enforce EPA FIFRA-registered antimicrobial claims and water-conservation metrics in bulk purchasing agreements.
Families absorb the bulk of installed capacity; institutions are expanding most quickly.
Distribution Channel:
Volume concentration in supermarket and pharmacy intermediaries is fragmenting as direct-to-consumer subscription channels capture brand-loyal households.
- Supermarkets:Mass-market retailers anchor category visibility through end-cap displays and seasonal promotional cycles that drive trial among undecided shoppers.
- Online Retail:E-commerce platforms enable concentrated refill replenishment and subscription bundling that bypasses slotting fees while building direct manufacturer relationships.
- Pharmacies:Healthcare-adjacent positioning supports dermatologist-recommended and sensitive-skin formulations at premium price points.
- Convenience Stores:Impulse-oriented locations stock travel-size and emergency-replacement formats for immediate consumption needs.
Supermarkets absorb the bulk of installed capacity; online retail is expanding most quickly.
Packaging Type:
Margin structure separates single-use disposable formats from reusable hardware systems that generate recurring cartridge revenue.
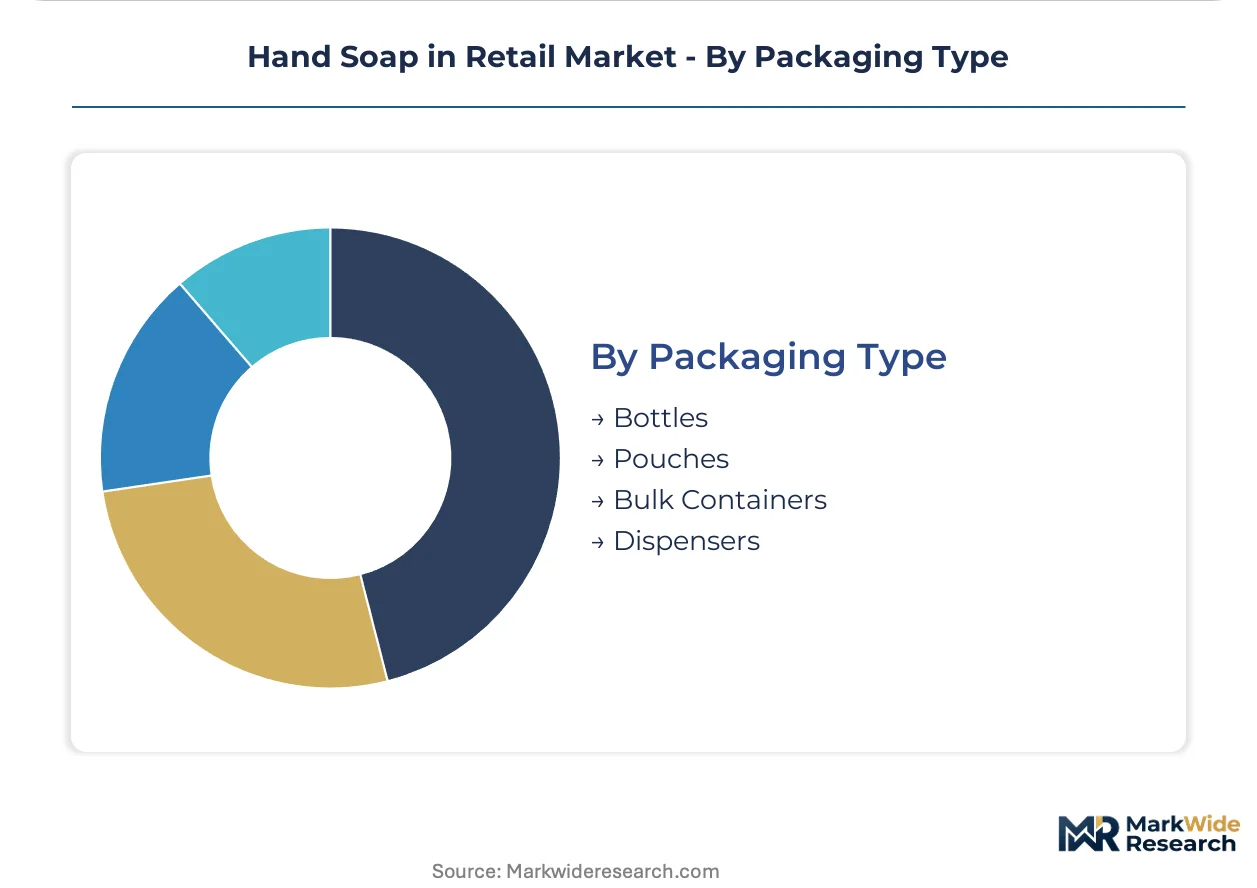
- Pouches:Flexible refill formats cut shipping weight and plastic intensity by 70-80% versus rigid bottles, attracting sustainability-focused families in Germany and the United States.
- Dispensers:Reusable pump hardware— increasingly sensor-activated in Japanese households— locks consumers into proprietary cartridge ecosystems with recurring purchase obligations.
- Bottles:Conventional rigid PET and HDPE containers face regulatory pressure under France and Italy's Extended Producer Responsibility frameworks.
- Bulk Containers:Institutional-grade formats serve healthcare and foodservice procurement with minimal packaging overhead per liter delivered.
Pouches absorb the bulk of installed capacity; dispensers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in Germany and Japan while consumption concentrates in the United States, creating cross-border supply flows that shape regional pricing and formulation standards.
United States
EPA FIFRA registration requirements for antimicrobial claims drive institutional procurement specifications in healthcare and foodservice segments. Families in suburban markets prioritize value-engineered refill pouches that reduce per-liter plastic intensity. Chicago and Dallas retail corridors anchor mass-market distribution networks for dispenser-compatible formats.
Germany
Extended Producer Responsibility frameworks under national packaging laws impose compliance costs on conventional bottle-dominant portfolios. REACH surfactant restrictions accelerate migration toward plant-based biodegradable chemistry. The Rhine-Ruhr industrial belt hosts concentrated continuous saponification capacity serving pan-European retail channels.
Japan
METI labeling standards mandate ingredient origin disclosure and biodegradability percentages on consumer-facing packaging. Foam-dispenser compatibility commands premium positioning in Tokyo and Osaka metropolitan households seeking water conservation metrics. Kansai region manufacturing specializes in high-foaming, low-viscosity formulation infrastructure.
China
SAMR national standards for liquid soap quality and labeling shape domestic retail compliance requirements. Emerging middle-class households in Shanghai and Guangzhou drive demand for aesthetically packaged formats emphasizing convenience over unit economics. Yangtze River Delta production clusters supply surfactant blending capacity for regional brand portfolios.
India
BIS quality certification requirements for personal care products establish baseline formulation standards across retail channels. Price-sensitive consumers in Mumbai and Delhi sustain demand for bar soap formats that bypass dispenser hardware requirements entirely. Gujarat chemical manufacturing corridors provide captive fatty acid feedstock for natural surfactant bases.
Hand Soap in Retail Market Competitive Landscape
The competitive structure tilts toward diversified consumer goods conglomerates with integrated surfactant supply chains and established retail slotting relationships. Scale advantages concentrate in North American and European headquarters with manufacturing footprints spanning multiple regulatory jurisdictions. Three archetypes dominate: multinational CPG holding companies, regional specialty chemical formulators, and institutional hygiene specialists. Competitive moves center on concentrated formula innovation and direct-to-consumer subscription channel development.
Among diversified consumer goods conglomerates, Procter & Gamble, Unilever, and Kao Corporation exemplify scale-driven positioning across mass-market and premium retail tiers. These entities anchor shelf presence through dispenser hardware bundling and refill pouch economics that lock consumers into recurring purchase ecosystems. Their geographic footprints span EPA, REACH, and METI regulatory jurisdictions, enabling standardized formulation platforms with localized packaging adaptations.
| Leading Market Players |
|---|
| Procter & Gamble |
| Unilever |
| Colgate-Palmolive |
| Reckitt Benckiser |
| Henkel |
| GOJO Industries |
| Lion Corporation |
| Kao Corporation |
| Godrej Consumer Products |
| Others |
Pricing and Supply Chain Analysis
Continuous saponification line retooling for high-foaming, low-viscosity formulations simultaneously inflates capital expenditure requirements and consolidates manufacturing scale among entities with multi-regional plant footprints. This technical transition compresses margin predictability for mid-tier formulators while amplifying pricing power for integrated conglomerates with captive surfactant supply.
Pricing Analysis
Margin tightening in standard liquid formats reflects palm oil and coconut fatty acid feedstock volatility that compresses cost predictability for plant-based surfactant commitments. Three-tier pricing structure across premium foam-dispenser systems, standard refill pouches, and economy bar soap separates households by dispenser hardware investment and sustainability preference. Cost-down pressure on conventional rigid bottles accelerates because France and Italy enforce packaging Extended Producer Responsibility frameworks ahead of EU harmonization. Families purchasing bulk refill pouches exhibit highest price sensitivity; Japanese metropolitan households seeking sensor-activated touchless systems show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Malaysian and Indonesian palm oil estates that feed natural surfactant bases for biodegradable formulations. Manufacturing capacity clusters in Germany, Japan, and the United States, drawing from fatty acid feedstocks, specialized pump mechanism components, and recycled PET resin streams. Tariff exposure on Southeast Asian oleochemical imports threatens margin stability for European formulators committed to REACH-compliant chemistry. Distribution runs through supermarket and pharmacy intermediaries, though direct-to-consumer subscription channels fragment traditional slotting-fee structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration race dynamics intensify as manufacturers pursue captive control over surfactant feedstock supply to insulate margins from oleochemical price swings.
For Market Incumbents: Acquire continuous saponification capacity in the Rhine-Ruhr corridor to anchor pan-European supply security against REACH reformulation mandates. Consolidate dispenser hardware engineering capabilities to lock households into proprietary cartridge ecosystems that generate recurring revenue. Bar soap persistence in emerging markets and refill pouch economics in Germany and the United States demand dual-format portfolio defense. For New Entrants and Emerging Players: Direct-to-consumer subscription routes bypass supermarket slotting fees and capture brand-loyal households in United States urban corridors and Japanese metropolitan markets. White-space concentrates in ultra-compact dilutable formulas for institutional healthcare procurement and waterless solid-concentrate formats for Southeast Asian foodservice. Lead with EPA FIFRA antimicrobial claim registration to unlock hospital and foodservice segments. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified consumer goods conglomerates seeking surfactant integration and regional regulatory footprint expansion. Long-term viability favors entities with OECD 301 biodegradability certification infrastructure and multi-jurisdiction manufacturing presence. Watch for inflection in national Extended Producer Responsibility implementation schedules that would accelerate bottle-format obsolescence.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oleochemical Supply | Captive palm oil and coconut fatty acid sourcing insulates margins from feedstock volatility under REACH mandates. |
| Direct-to-Consumer Subscription Launch | Bypasses supermarket slotting fees while building recurring revenue relationships with brand-loyal households. |
| Foam-Dispenser Hardware Bundling | Locks consumers into proprietary cartridge ecosystems with sensor-activated touchless pumps commanding premium positioning. |
| EPA FIFRA Antimicrobial Registration | Opens institutional procurement segments in healthcare and foodservice with pathogen-killing efficacy claims. |
| Sustainability Repositioning | Biodegradable surfactant chemistry and refill pouch formats align with EU Green Deal packaging recyclability targets. |
Research Methodology
Multi-period observation of refill pouch adoption rates, dispenser hardware penetration, and surfactant chemistry migration anchored the trend analysis, supplemented by interviews with brand managers, category buyers at mass-market retailers, supply planners, and technical R&D directors. Secondary validation drew from Nielsen retail audit data, customs records on oleochemical trade flows, SEC 10-K filings of diversified consumer goods conglomerates, and METI disclosure frameworks. Bottom-up segment sizing triangulated against top-down macroeconomic indicators to ensure consistency.
Segment-weighting across product type, customer archetype, distribution channel, and packaging format informed the analytical framework across the projection horizon. CAGRs derived from fitted growth curves applied to baseline volume data, with cross-validation against historical elasticity patterns in United States, German, and Japanese retail channels. Forecast inputs incorporated OECD 301 biodegradability certification timelines and national Extended Producer Responsibility phase-in schedules.
The model holds under stable regulatory enforcement trajectories; deviation in REACH surfactant restriction acceleration or palm oil supply disruption would shift trajectory assumptions. Forecasts reflect documented base conditions with acknowledged sensitivity to feedstock price volatility and packaging law compliance costs. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
United States Beauty and Personal Care Products Market
Beauty & Personal Care
Cosmetic Serum Market
Beauty & Personal Care
Body Glitters Market
Beauty & Personal Care
Dry Shampoo Market
Beauty & Personal Care
Facial Makeup Setting Spray Market
Beauty & Personal Care
Personal Care Ingredients Market
Beauty & Personal Care
Natural Hair Care Product Market
Beauty & Personal Care
South Korea Beauty and Personal Care Products Market
Beauty & Personal Care
Nail Care Market
Beauty & Personal Care
Foaming Hand Soaps Market
Beauty & Personal Care
Philippines Beauty & Personal Care Market
Beauty & Personal Care
Spas and Beauty Salons Market
Beauty & Personal Care
Global Bath Salts Market
Beauty & Personal Care
Shaving and Hair Removal Products Market
Beauty & Personal Care
Global Organic Hair Color Market
Beauty & Personal Care
Organic Liquid Soaps Market