
 Europe Men's Grooming Products Market | 2026-2036
Europe Men's Grooming Products Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Men's Grooming Products Market Insights
Natural surfactant chemistry is shifting formulation economics across men's skincare and haircare lines. Beiersdorf AG anchors its European position through intensive R&D in dermatologically tested formulations. L'Oréal S.A. dominates premium men's skincare through controlled distribution in specialty retail and pharmacy channels. Henkel AG & Co. KGaA leverages its Schwarzkopf manufacturing scale to compete on haircare volume across drugstore and supermarket tiers.
Europe men's grooming products encompass topical preparations designed for male skin and hair physiology, typically incorporating pH-balanced surfactant systems, lipid-replenishing agents, and fragrance compounds at concentrations between 1% and 5% by weight, manufactured through emulsification or aerosol propellant processes for cleansing, conditioning, or scenting applications. Skincare leads value contribution as male facial care routines expand beyond basic cleansing into serums and moisturizers, while online distribution captures the fastest growth trajectory as direct-to-consumer subscription models displace traditional retail foot traffic. Haircare sustains volume dominance through frequent replenishment cycles, though margin pools concentrate in fragrance and premium skincare where brand equity commands pricing power.
REACH restricts certain preservative and fragrance allergen concentrations, compelling reformulation investments across suppliers serving the European Economic Area. ECHA classification rules for skin sensitizers and the EU Green Deal's packaging waste directives are tightening compliance thresholds for imported and domestically produced grooming lines. Stakeholders must monitor regulatory divergence between EU member state enforcement practices and emerging national eco-label schemes that could fragment market access requirements.
Market Dynamics
REACH compliance costs and the EU Green Deal's packaging mandates are forcing simultaneous reformulation and supply chain restructuring across European men's grooming manufacturers. These regulatory pressures now dominate capital allocation decisions more than consumer demand fluctuations.
Growth Catalysts
- Urban professional routines:Male white-collar workers in London, Paris, and Berlin now normalize multi-step facial care regimens previously confined to female skincare. This behavioral shift expands addressable spend per capita.
- REACH Annex XVII restrictions:Preservative bans on methylisothiazolinone and formaldehyde-releasers accelerate clean-label innovation cycles. First movers capture pharmacy shelf space before compliance deadlines.
- Biotechnology-derived surfactants:Rhamnolipid and sophorolipid production scales reduce raw material cost premiums versus petrochemical alternatives. German chemical suppliers lead capacity expansion.
Market Restraints
- Palm oil derivative volatility:Sodium lauryl sulfate and glycerin feedstock costs swing with Malaysian and Indonesian export policy. Margin compression hits mass-market shampoo and body wash lines hardest.
- Fragrance allergen concentration caps:ECHA's 26-allergen labeling threshold forces reformulation of legacy scent profiles. Reformulation R&D consumes 18-24 month development windows.
- Glass and aluminum packaging premiums:EU plastic tax implementation shifts cost structures toward heavier materials. Transportation cost per unit rises disproportionately for online-direct fulfillment.
Strategic Opportunities
- Polish and Romanian pharmacy channels:Underpenetrated Eastern European markets show 40% lower male skincare penetration than Western benchmarks. Local distributors seek exclusive brand partnerships.
- Refill station infrastructure:French retail regulations now mandate in-store packaging reduction targets. Refillable aluminum canister systems qualify for green tax credits.
- AI-driven skin diagnostics:Computer vision tools paired with smartphone cameras enable personalized serum matching. Integration with subscription platforms reduces customer acquisition costs.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulation expertise in natural preservative systems remains concentrated at Beiersdorf, L'Oréal, and Henkel. Mid-tier brands face recruitment bottlenecks.
- Multi-jurisdictional eco-label fragmentation:Nordic Swan, Blue Angel, and emerging French environmental scoring systems create conflicting certification requirements. Compliance teams must track 12+ national schemes.
- Legacy ERP integration with traceability mandates:EU digital product passport requirements demand batch-level ingredient tracking. SAP and Oracle implementations require 14-18 month deployment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Men's Grooming Products Market |
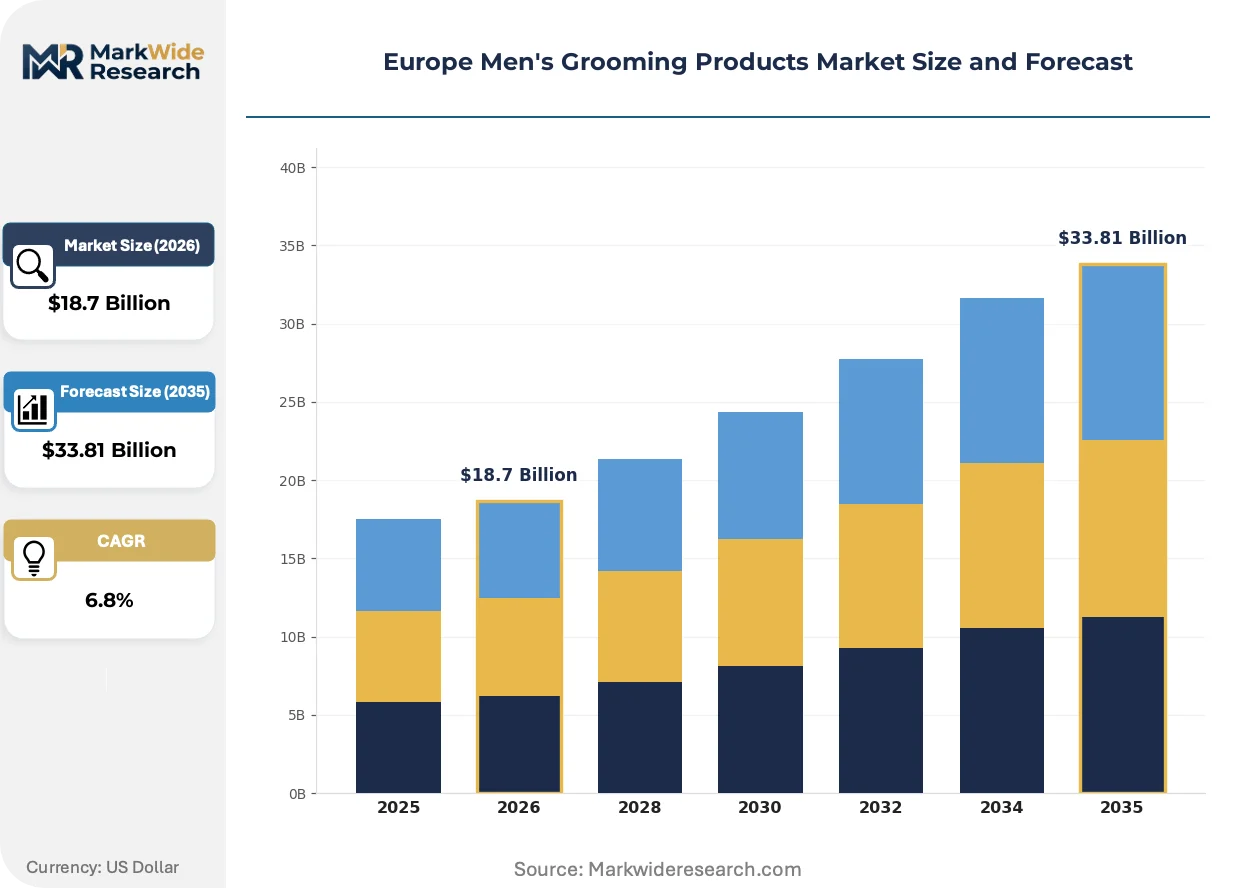
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shaving, Skincare, Haircare, Fragrance Distribution Channel: Online, Supermarkets, Specialty Stores, Drugstores End User: Young Adults, Professionals, Seniors, Athletes Formulation: Cream, Gel, Lotion, Spray |
| Companies Covered | Procter & Gamble Company, Unilever PLC, Beiersdorf AG, L'Oréal S.A., Edgewell Personal Care Company, Henkel AG & Co. KGaA, Coty Inc., Shiseido Company, Colgate-Palmolive Company, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Men's Grooming Products Market Trends and Innovations
Formulation chemistry and distribution infrastructure are undergoing parallel transformation as regulatory pressure and direct-to-consumer adoption reshape competitive requirements. Technology investment now separates margin leaders from volume followers.
Biotechnology-derived emulsifiers are absorbing formulation share from traditional petrochemical surfactants. Rhamnolipid producers in Germany and the Netherlands scale fermentation capacity to serve mid-tier brands seeking clean-label credentials. This transition is absorbing margin pressure from palm oil volatility while enabling premium positioning in pharmacy channels.
REACH authorization requirements for skin sensitizers now cover 4-isopropyl-m-cresol and additional fragrance allergens. Manufacturers must submit full safety dossiers or reformulate within 36-month sunset periods. Small Italian and Spanish contract manufacturers lack toxicology submission resources, consolidating production toward larger integrated players.
Subscription-based replenishment models now capture one-third of online male grooming spend in the United Kingdom. Direct-to-consumer brands bypass Boots and Superdrug shelf fees while capturing recurring revenue data. Urban millennials in Manchester and Birmingham show highest conversion rates for automated reorder algorithms.
Europe Men's Grooming Products Market Segmentation
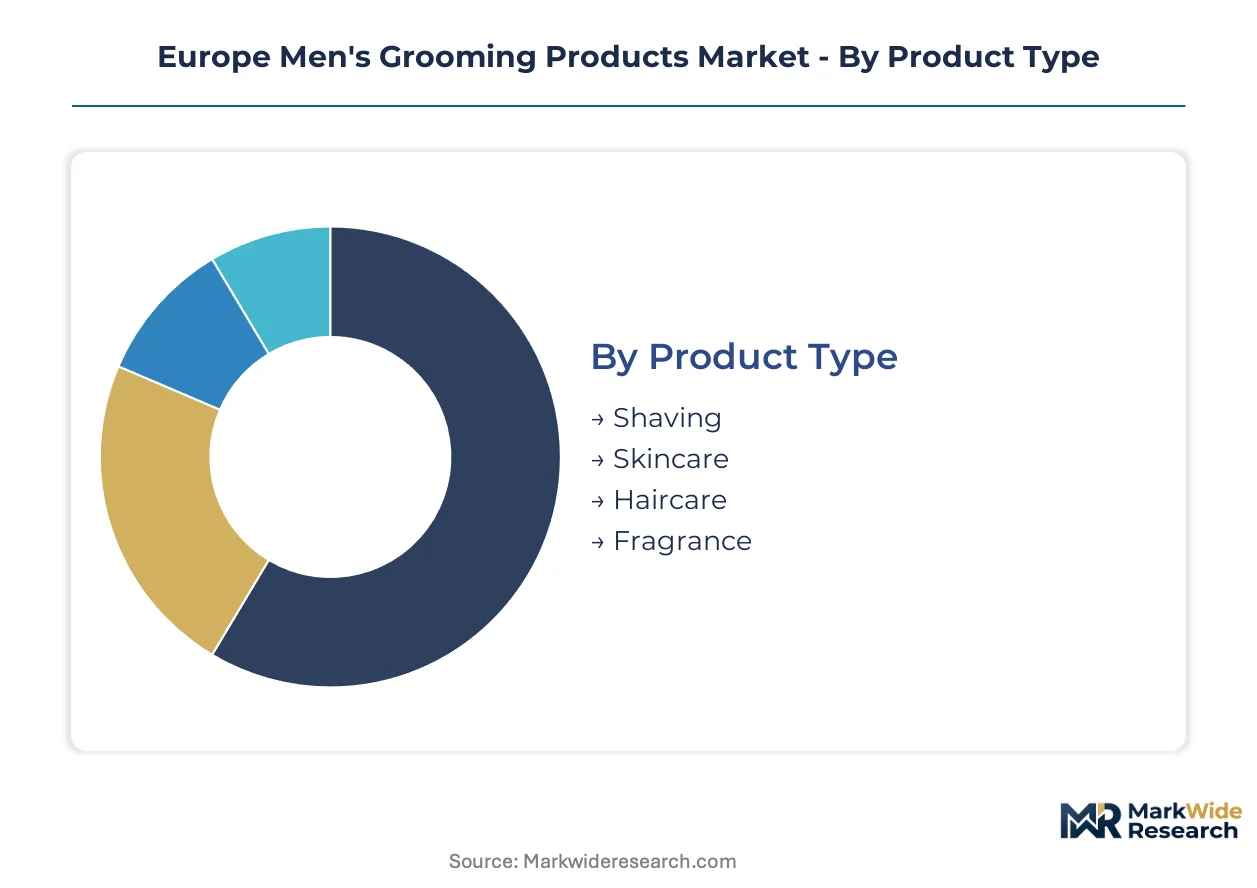
Segmentation in European men's grooming reveals how purchasing decisions fragment across channel preferences, professional identity, and formulation chemistry. Understanding these divides allows suppliers to allocate R&D and distribution investments against the highest-margin pockets.
Product Type:
Professional men in London, Paris, and Berlin select products based on routine complexity and workplace grooming standards rather than price alone.
- Shaving:Traditional foam and gel formulations incorporating glycerin-based lubricants and menthol cooling agents. Demand concentrates among German and British men over 35 who maintain daily wet-shaving rituals despite electric alternatives. REACH restrictions on aerosol propellants are accelerating pump-dispense format transitions.
- Skincare:pH-balanced serums, moisturizers, and eye creams with niacinamide and hyaluronic acid concentrations. French and Italian urban professionals drive adoption as multi-step facial routines normalize in white-collar workplaces. Pharmacy channel placement commands premium shelf positioning.
- Haircare:Shampoo and conditioner systems with sulfate-free surfactant bases for frequent washing cycles.
- Fragrance:Eau de toilette and cologne concentrations at 5-15% aromatic compound loadings for daily wear.
Skincare leads on scale; skincare also leads on momentum as routine complexity deepens.
Distribution Channel:
Channel selection in European men's grooming reflects convenience thresholds, advice requirements, and subscription loyalty patterns.
- Online:Direct-to-consumer platforms and marketplace aggregators with automated replenishment algorithms. Manchester and Birmingham millennials convert fastest to subscription models that bypass traditional retail markups. Data capture enables personalized serum matching and churn reduction.
- Supermarkets:Mass-market shampoo, body wash, and shaving foam in high-velocity packaging formats. German and Dutch shoppers prioritize one-stop convenience for replenishment purchases with minimal decision friction.
- Specialty Stores:Curated fragrance and premium skincare boutiques with trained consultation staff.
- Drugstores:Pharmacy-affiliated retail with dermatological credibility and insurance-adjacent positioning.
Supermarkets lead on scale; online channels are expanding most quickly.
End User:
Life stage and professional identity shape formulation requirements, price sensitivity, and channel loyalty across European male consumers.
- Young Adults:Men aged 18-25 prioritizing acne control, fragrance experimentation, and social signaling through grooming. TikTok and Instagram discovery drives trial of Korean-influenced skincare formats in British and Spanish urban centers.
- Professionals:White-collar workers aged 25-45 investing in anti-fatigue eye creams and subtle workplace-appropriate scents. Polish and Romanian urban markets show 40% lower penetration than Western benchmarks, creating expansion headroom.
- Seniors:Men over 55 seeking scalp care and skin barrier repair formulations.
- Athletes:Active men requiring sweat-resistant, quick-application products for post-training routines.
Professionals lead on scale; young adults gain share fastest through social commerce conversion.
Formulation:
Physical form determines manufacturing process, packaging material requirements, and usage occasion compatibility for European male consumers.
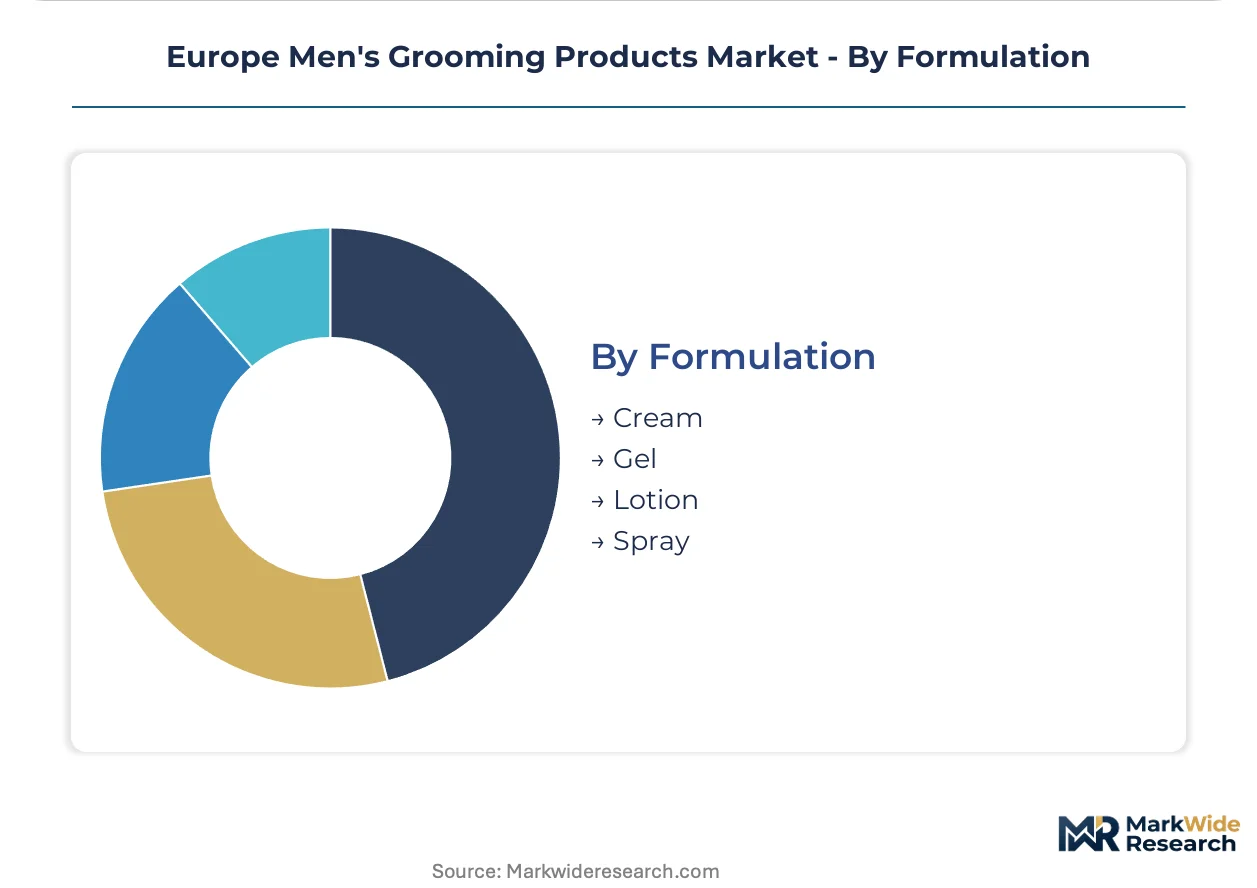
- Cream:Oil-in-water emulsions with 15-25% lipid content for shaving and moisturizing applications. German chemical suppliers lead rhamnolipid-derived emulsifier production that replaces petrochemical alternatives under EU Green Deal pressure.
- Gel:Water-based carbomer-thickened systems for transparent shaving and hair styling. French refill station regulations favor gel formats in aluminum canister systems qualifying for packaging reduction credits.
- Lotion:Lower-viscosity fluid preparations for body and facial application.
- Spray:Aerosol or pump-dispensed fine mists for fragrance and dry shampoo delivery.
Cream formulations lead on scale; gel formats show the steepest expansion trajectory amid packaging regulation shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr chemical corridor anchors European formulation chemistry for men's grooming, with German suppliers scaling rhamnolipid fermentation capacity to serve clean-label demand across the continent.
Germany
Professional men in Berlin and Munich drive pharmacy-channel adoption of multi-step facial regimens. REACH Annex XVII restrictions on methylisothiazolinone accelerate reformulation timelines for domestic manufacturers. The Cologne-Düsseldorf corridor concentrates Beiersdorf AG and Henkel AG manufacturing facilities serving export markets.
France
Parisian white-collar workplaces normalize subtle fragrance and anti-fatigue skincare as professional necessities. The EU Green Deal's packaging waste directives mandate in-store refill station infrastructure under French retail regulations. Lyon-based chemical suppliers expand sophorolipid production for premium emulsifier applications.
United Kingdom
Manchester and Birmingham millennials convert fastest to subscription-based replenishment models bypassing traditional retail markups. ECHA classification rules for skin sensitizers force 18-24 month reformulation windows for legacy scent profiles. London anchors direct-to-consumer brand headquarters capturing recurring revenue data.
Italy
Milanese professionals expand facial care routines into serums and eye creams previously confined to female skincare categories. National enforcement practices for REACH compliance create divergence from German regulatory interpretation. Small contract manufacturers in Emilia-Romagna lack toxicology submission resources, consolidating production toward integrated players.
Poland
Warsaw and Krakow urban markets show 40% lower male skincare penetration than Western European benchmarks, creating expansion headroom for pharmacy-channel entrants. Local distributors seek exclusive brand partnerships to capture rising professional disposable income. Poznan logistics clusters enable efficient distribution into underpenetrated Eastern European markets.
Europe Men's Grooming Products Market Competitive Landscape
Global majors compete with regional champions across formulation chemistry and channel control, creating a tiered structure where scale advantages concentrate in haircare and dermatological skincare. The vendor base separates into integrated chemical-formulation players, pure-brand marketing operations, and contract manufacturing specialists. Three archetypes dominate: multinational CPG conglomerates with captive R&D, mid-tier European brands leveraging pharmacy credibility, and direct-to-consumer disruptors bypassing retail shelf fees. Competitive moves center on biotechnology licensing for surfactant alternatives and vertical integration into refillable packaging systems.
Within the integrated multinational tier, Procter & Gamble Company, Unilever PLC, and Beiersdorf AG occupy positions defined by manufacturing scale and dermatological testing infrastructure. Beiersdorf AG exemplifies the European pharmacy-channel archetype through intensive R&D concentration. Procter & Gamble Company and Unilever PLC represent global volume leaders competing across mass-market supermarket and drugstore tiers. These three entities anchor the competitive structure through control of formulation expertise and distribution relationships.
| Leading Market Players |
|---|
| Procter & Gamble Company |
| Unilever PLC |
| Beiersdorf AG |
| L'Oréal S.A. |
| Edgewell Personal Care Company |
| Henkel AG & Co. KGaA |
| Coty Inc. |
| Shiseido Company |
| Colgate-Palmolive Company |
| Others |
Pricing and Supply Chain Analysis
Urban professional procurement preferences for pharmacy-grade dermatological formulations are forcing manufacturers to absorb REACH compliance costs while maintaining premium positioning, compressing margins in mid-tier supermarket channels disproportionately.
Pricing Analysis
Input-cost pass-through from rhamnolipid and sophorolipid fermentation capacity expansion is reshaping formulation economics. Three-tier pricing structure across premium, standard, and economy levels separates pharmacy-channel dermatological lines from mass-market supermarket tiers and private-label drugstore alternatives. Price differentiation hinges on certification grade (REACH Annex XVII compliance) and volume scale, with subscription models capturing least price-sensitive urban millennials. Cost compression in mass-market haircare is intensifying because palm oil derivative volatility hits sodium lauryl sulfate and glycerin feedstock costs.
Supply Chain Analysis
Cosmetic chemist talent scarcity in the Cologne-Düsseldorf corridor and Lyon chemical clusters is constraining formulation capacity expansion for natural preservative systems. Manufacturing gravity centers on Germany, France, and the United Kingdom, with German suppliers scaling biotechnology-derived emulsifier production. Raw material dependencies rest on Malaysian and Indonesian palm oil derivatives, German fermentation-based surfactants, and French fragrance compound supply. Single-source vulnerability in toxicology submission expertise concentrates production toward integrated players with captive regulatory affairs teams. Distribution runs through pharmacy-affiliated retail, direct-to-consumer subscription platforms, and supermarket mass-market tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH Annex XVII restrictions on methylisothiazolinone and formaldehyde-releasers function as a regulatory compounder, accelerating clean-label innovation cycles that deepen pharmacy-channel penetration and expand addressable spend per professional male consumer.
For Market Incumbents: Acquire toxicology submission expertise and natural preservative formulation capabilities before 36-month REACH sunset periods expire. Consolidate production capacity in the Rhine-Ruhr corridor to exploit scale advantages in rhamnolipid fermentation. Defend against direct-to-consumer subscription disruptors by capturing recurring revenue data through automated replenishment algorithms integrated with AI-driven skin diagnostics. For New Entrants and Emerging Players: Capture underpenetrated Polish and Romanian pharmacy channels where male skincare penetration trails Western benchmarks by substantial margins. Target Warsaw and Krakow urban professionals through exclusive distributor partnerships. Enter via gel-format refillable aluminum canister systems qualifying for French green tax credits, bypassing legacy retail shelf fee structures. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier European brands possessing pharmacy credibility but lacking integrated manufacturing scale. Five-to-ten year viability favors targets with established REACH compliance dossiers and biotechnology licensing relationships. Watch for inflection signals in ECHA classification rule expansions covering additional fragrance allergens, which will trigger consolidation waves among small Italian and Spanish contract manufacturers lacking submission resources.| Strategic Initiative | Industry Significance |
|---|---|
| Biotechnology Licensing Agreement | Rhamnolipid and sophorolipid production partnerships enable clean-label pharmacy positioning against petrochemical competitors. |
| Refill Station Infrastructure Deployment | French retail regulations mandate packaging reduction targets that aluminum canister systems satisfy for green tax credits. |
| Direct-to-Consumer Platform Launch | Subscription models bypass Boots and Superdrug shelf fees while capturing recurring revenue data from Manchester millennials. |
| REACH Compliance Dossier Investment | Pre-submission of skin sensitizer safety data secures pharmacy shelf space before 36-month sunset deadlines eliminate competitors. |
| AI-Driven Skin Diagnostic Integration | Computer vision tools paired with smartphone cameras reduce customer acquisition costs for personalized serum matching platforms. |
Research Methodology
Direct dialogue with brand managers, category buyers at pharmacy and supermarket retailers, formulation chemists at Beiersdorf and Henkel, and regulatory affairs specialists at ECHA anchored qualitative findings. Secondary validation drew from REACH Annex XVII restriction notices, EU Green Deal packaging directives, Nielsen retail audit data, and customs records tracking surfactant feedstock imports. Bottom-up segment sizing triangulated against top-down market value estimates across product type, distribution channel, end user, and formulation chemistry dimensions.
Market size and growth projections across the analysis window reflect econometric modeling of professional male disposable income trajectories, urbanization rates in target cities, and regulatory compliance cost absorption curves. Segmentation dimensions span shaving, skincare, haircare, and fragrance product types; online, supermarket, specialty store, and drugstore channels; young adult, professional, senior, and athlete end users; and cream, gel, lotion, and spray formulations. CAGRs derive from regression analysis of historical premium grooming adoption patterns, with biotechnology surfactant cost curves and refill station infrastructure rollout timelines as key forecast inputs.
REACH enforcement divergence across member states, palm oil export policy volatility in Southeast Asia, and subscription platform churn rate fluctuations are the dominant revision risks to projections. Forecasts reflect assumptions about regulatory timeline adherence and clean-label consumer preference stability. Material deviation in ECHA classification rule expansions or German chemical supplier capacity expansion delays warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Goods
Egypt Microwave Ovens Market
Consumer Goods
Hair Bond Multiplier Market
Consumer Goods
GCC Bath Soap Market
Consumer Goods
Smart Body Scales Market
Consumer Goods
Pet Grooming Services Market
Consumer Goods
Philippines Beauty & Personal Care Market
Consumer Goods
Mexico Pet Food Market
Consumer Goods
Earplug Distributor Market
Consumer Goods
United States Electric Toothbrush Market
Consumer Goods
Pet Grooming Products Market
Consumer Goods
South Korea Luxury Goods Market
Consumer Goods
Middle East and Africa Robotic Vacuum Cleaner Market
Consumer Goods
Athletic Footwear Market
Consumer Goods
Body Shaper Market
Consumer Goods
Baby Sleeping Bag Market
Consumer Goods
Mobile Phone Accessories Market