
 Beauty Products Market | 2026-2036
Beauty Products Market Size, Share, and Industry Trends Forecast 2026-2036
Beauty Products Market Intelligence
Multi-source ingredient procurement is pivoting toward vertically integrated supply chains as brands seek traceability for botanical and biotech-derived actives. L'Oréal S.A. anchors its competitive stance through captive biotechnology labs producing proprietary hyaluronic acid variants. Shiseido Company leverages century-old fermentation expertise to differentiate its premium skincare lines. Unilever sustains mass-market scale through consolidated global manufacturing networks.
Beauty products encompass chemically formulated topical preparations including emulsions, serums, suspensions, and aerosols engineered with defined pH ranges, active concentrations between 0.5% and 15%, and stability thresholds of 24 to 36 months under controlled conditions, serving aesthetic enhancement, skin barrier protection, and personal hygiene functions. Skincare commands the largest margin pool due to repeat-purchase loyalty and clinical-positioned pricing, while hair styling segments compete on salon professional channel control. Online stores represent the fastest-growing distribution channel as direct-to-consumer platforms disintermediate traditional wholesale relationships.
FDA cosmetic labeling requirements and EU REACH chemical restrictions compel reformulation cycles that elevate compliance costs for synthetic preservative-dependent product lines. ECHA substance evaluation processes now classify additional fragrance allergens, forcing disclosure changes across European formulations. Stakeholders must monitor emerging state-level bans on per- and polyfluoroalkyl substances in the United States, as these cascade into reformulation mandates affecting waterproof makeup and long-wear categories.
Market Dynamics
Clean beauty mandates are restructuring R&D allocation across the beauty products sector, forcing accelerated transitions from petroleum-derived emollients toward biotechnology-synthesized alternatives and waterless formulation architectures.
Growth Catalysts
- EU REACH chemical restrictions:Regulatory pressure on synthetic preservatives is accelerating investment in fermentation-derived actives and biodegradable surfactant chemistry.
- Male grooming segment expansion:Shifting social norms around masculine self-care are opening incremental SKU development in skincare and hair styling categories previously oriented toward female demographics.
- Biotechnology platforms:Proprietary hyaluronic acid variants and engineered peptides are enabling clinical-grade positioning at premium price tiers.
Market Restraints
- Botanical supply concentration:Traceability requirements for plant-derived actives concentrate procurement risk in specific cultivation regions vulnerable to climate volatility.
- Reformulation cost cycles:FDA cosmetic labeling requirements and ECHA fragrance allergen classifications impose recurring compliance expenditures on established synthetic-dependent product lines.
- Waterless technical barriers:Anhydrous formulation stability and sensory acceptance limitations constrain rapid category migration despite sustainability tailwinds.
Strategic Opportunities
- Direct-to-consumer channel expansion:Online stores are disintermediating traditional wholesale relationships, enabling margin capture and first-party data accumulation.
- Waterless product architectures:Concentrated solid formats and anhydrous delivery systems address both sustainability positioning and shipping cost reduction.
- State-level PFAS bans in the United States:Anticipatory reformulation for waterproof and long-wear categories creates first-mover advantage in clean performance segments.
Industry Challenges
- Fermentation expertise scarcity:Century-old biotechnology capabilities reside in limited institutional settings, constraining rapid capability replication.
- Supply chain reconfiguration friction:Multi-source ingredient procurement transitions toward vertically integrated models encounter legacy supplier contract complexities and qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beauty Products Market |
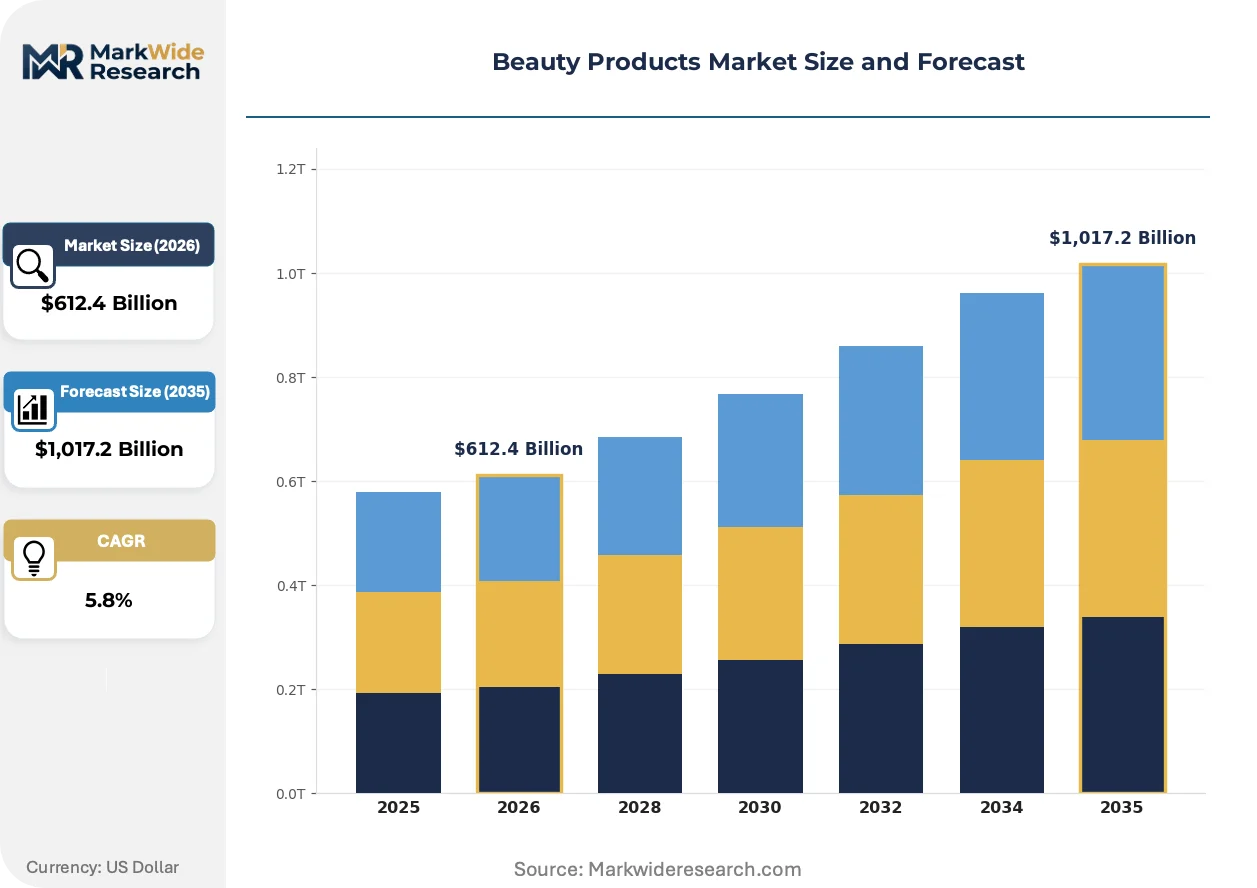
| Market Size in 2026 | $612.4 Billion |
| Market Size in 2035 | $1,017.2 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Hair Care, Makeup, Fragrances, Personal Care Application: Anti-Aging, Sun Protection, Moisturizing, Cleansing, Hair Styling Customer Type: Salon Professionals, Individual Consumers, Retailers, Spas, Dermatologists Distribution Channel: Online Stores, Brand Outlets, Pharmacies, Department Stores, Specialty Retailers |
| Companies Covered | LVMH, Shiseido Company, L'Oréal S.A., Coty Inc., Kao Corporation, Unilever, Procter & Gamble, Beiersdorf, The Estée Lauder Companies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beauty Products Market Strategic Shifts & Innovations
Biotechnology-derived actives and anhydrous formulation science are compressing traditional chemical synthesis pathways, while regulatory chemical restrictions and channel disintermediation simultaneously reshape competitive positioning.
Solid and waterless delivery formats are electrifying conventional emulsion chemistry, replacing aqueous phases with concentrated lipid and powder matrices. Premium skincare brands in South Korea and the United States are accelerating SKU launches in this architecture. The shift is compressing packaging volumes, reducing preservative loads, and enabling concentrated active dosing previously constrained by aqueous solubility limits.
ECHA substance evaluation processes now classify additional fragrance allergens, forcing disclosure changes across European formulations. The industrial consequence is label redesign, supply chain requalification, and consumer communication restructuring. Waterproof makeup and long-wear categories face cascading pressure as the United States advances state-level per- and polyfluoroalkyl substance bans.
Direct-to-consumer platforms are displacing traditional department store and pharmacy wholesale relationships, concentrating buyer relationships through owned digital channels. Subscription replenishment models in skincare are compressing switching cycles and elevating lifetime value metrics. China and South Korea demonstrate the most advanced execution of this channel architecture, with live commerce integration accelerating conversion velocity.
Beauty Products Market Segmentation
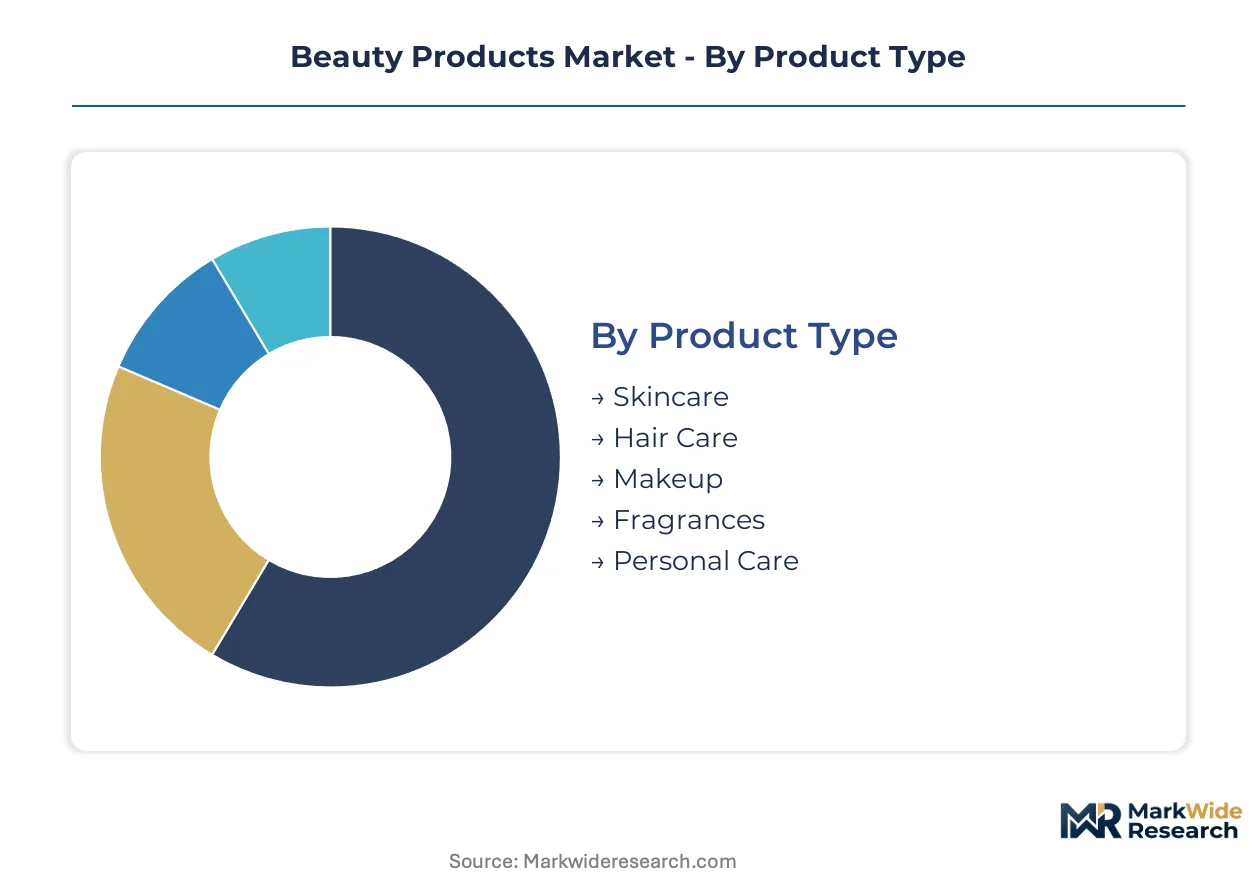
Segmentation in beauty products determines regulatory pathways, margin architecture, and channel strategy. Each dimension carries distinct certification burdens and supply chain requirements that reshape competitive positioning.
Product Type:
EU REACH chemical restrictions and FDA cosmetic labeling requirements impose tiered compliance obligations across formulation categories, with clinical-grade segments facing the heaviest documentation loads.
- Skincare:Emulsions, serums, and suspensions with defined pH ranges and active concentrations between 0.5% and 15% dominate margin pools through repeat-purchase loyalty. Demand concentrates in China, South Korea, and the United States for premium clinical-positioned lines driven by biotechnology-synthesized actives.
- Hair Care:Shampoos, conditioners, and treatments compete on salon professional channel control and fermentation-derived ingredient differentiation. Male grooming expansion is redirecting SKU development toward styling and scalp health formats previously oriented toward female demographics.
- Makeup:Color cosmetics face reformulation pressure from state-level PFAS bans affecting waterproof and long-wear categories.
- Fragrances:ECHA fragrance allergen classifications force disclosure changes and label redesign across European formulations.
- Personal Care:Mass-market hygiene products sustain scale through consolidated global manufacturing networks and biodegradable surfactant transitions.
Skincare sits at the top of the volume ranking, with hair care climbing the fastest.
Application:
Cost tier stratification separates clinical-grade positioning from mass-market accessibility, with premium segments commanding three-to-five-fold price multiples.
- Anti-Aging:Engineered peptides and proprietary hyaluronic acid variants enable premium pricing through biotechnology platforms. South Korean and US brands lead SKU density in this segment.
- Sun Protection:Mineral and chemical UV filters face reformulation cycles from evolving FDA monograph requirements and EU-approved filter lists. Waterless formats are gaining traction for reef-safe positioning.
- Moisturizing:Basic hydration functions compete on ingredient story and packaging sustainability.
- Cleansing:Biodegradable surfactant chemistry is displacing petroleum-derived emollients under clean beauty mandates.
- Hair Styling:Male grooming normalization is expanding addressable demand beyond traditional salon channels.
Moisturizing captures the largest absolute volume, while anti-aging gains share fastest.
Customer Type:
Volume concentration varies sharply across professional versus retail channels, with institutional buyers demanding batch certification and traceability documentation.
- Salon Professionals:Licensed practitioners require backbar sizing, technical training support, and exclusive distribution territories. Channel control in hair styling segments depends on professional education investment.
- Individual Consumers:Direct-to-consumer platforms accumulate first-party data through subscription replenishment models that compress switching cycles.
- Retailers:Mass-market chains negotiate consolidated global manufacturing networks for private label and branded placement.
- Spas:Premium service providers source clinical-grade positioning for treatment-room protocols and retail resale.
- Dermatologists:Medical channel access requires stability thresholds of 24 to 36 months and defined pH range documentation.
Individual consumers sit at the top of the volume ranking, with dermatologists climbing the fastest.
Distribution Channel:
Geographic execution maturity separates advanced live commerce integration from legacy wholesale relationships.
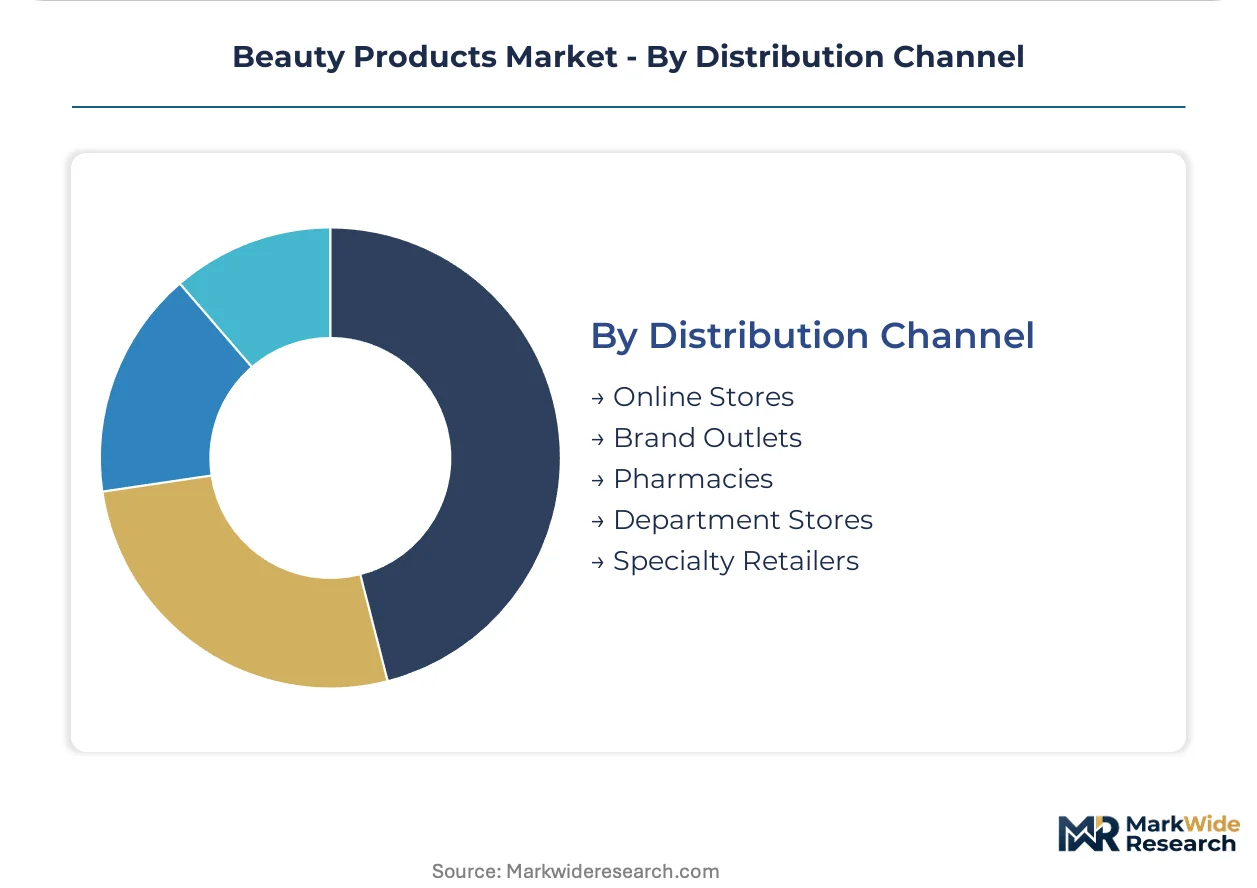
- Online Stores:Direct-to-consumer platforms disintermediate traditional wholesale relationships and enable margin capture. China and South Korea demonstrate the most advanced execution with live commerce integration accelerating conversion velocity.
- Brand Outlets:Owned retail captures full margin and controls experiential positioning for premium skincare lines.
- Pharmacies:Regulated channel access requires FDA cosmetic labeling compliance and pharmacist education for dermocosmetic placement.
- Department Stores:Traditional wholesale relationships face displacement as digital channels concentrate buyer relationships.
- Specialty Retailers:Curated assortments compete on clean beauty curation and ingredient transparency storytelling.
Department stores retain historical volume leadership, with online stores expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting manufacturing investment toward jurisdictions with stable compliance frameworks as EU REACH chemical restrictions and FDA cosmetic labeling requirements widen cost-of-compliance gaps between production locations.
United States
Premium skincare demand concentrates in coastal metropolitan clusters as male grooming normalization expands addressable demographics. FDA cosmetic labeling requirements and emerging state-level PFAS bans in California and New York are forcing reformulation cycles for waterproof makeup and long-wear categories. New York and Los Angeles anchor direct-to-consumer platform development with live commerce integration accelerating conversion velocity.
China
Clinical-grade positioning and K-beauty influenced routines drive premium skincare volume through tier-one cities. NMPA cosmetic registration requirements and dual carbon goals are redirecting R&D spending toward waterless formulation architectures and biodegradable surfactant chemistry. Shanghai and Hangzhou concentrate biotechnology platform investment for proprietary hyaluronic acid variants.
South Korea
Fermentation-derived actives and engineered peptides enable premium pricing through century-old biotechnology capabilities concentrated in Seoul and Busan. MFDS cosmetic safety standards and export-oriented regulatory alignment support cross-border expansion into China and Southeast Asia. The Seoul Capital Area anchors SKU density leadership in anti-aging and waterless product segments.
Germany
Clean beauty mandates and sustainability positioning drive demand for anhydrous delivery systems and concentrated solid formats. ECHA fragrance allergen classifications under REACH are forcing disclosure changes and supply chain requalification across European formulations. Hamburg and Düsseldorf concentrate mass-market manufacturing scale through consolidated global networks.
France
Luxury fragrance and premium skincare heritage supports clinical-grade positioning at three-to-five-fold price multiples. ANSM cosmetic surveillance and EU Green Deal chemical restrictions are accelerating transitions from petroleum-derived emollients toward biotechnology-synthesized alternatives. Paris anchors captive biotechnology lab investment for traceable botanical and biotech-derived actives.
Beauty Products Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue waterless formulation architectures and direct-to-consumer channel control. The market structures around three distinct maturity tiers: multinational conglomerates with consolidated global manufacturing networks, regional specialists with fermentation expertise, and digital-native brands with subscription replenishment models. Strategic moves concentrate on backward integration into captive biotechnology labs and anticipatory reformulation for state-level PFAS bans.
Within the biotechnology-platform tier, L'Oréal S.A. and Shiseido Company exemplify divergent capability accumulation strategies. L'Oréal S.A. anchors proprietary hyaluronic acid variant production through captive laboratory infrastructure. Shiseido Company occupies a position defined by century-old fermentation expertise institutionalized in premium skincare lines. Unilever sits within the mass-market scale vector, sustaining volume leadership through consolidated global manufacturing networks.
| Leading Market Players |
|---|
| LVMH |
| Shiseido Company |
| L'Oréal S.A. |
| Coty Inc. |
| Kao Corporation |
| Unilever |
| Procter & Gamble |
| Beiersdorf |
| The Estée Lauder Companies |
| Others |
Cost & Logistics Intelligence
Direct-to-consumer subscription buyers concentrate purchasing power through replenishment models, compressing switching cycles and anchoring the dominant pricing architecture around lifetime value capture rather than transactional margin extraction.
Pricing Analysis
Distributor margin layers vary sharply between mass-market chains and professional salon channels. Three-tier pricing structure across premium, standard, and economy levels separates clinical-grade biotechnology positioning from basic personal care accessibility. Pricing pressure stems from clean beauty reformulation cycles elevating compliance costs for synthetic-dependent portfolios. Mass-market retailers exhibit highest price sensitivity, while dermatologist-channel buyers prioritize stability documentation over unit economics.
Supply Chain Analysis
Dual-sourcing requirements for botanical actives mandate multi-supplier qualification across cultivation regions vulnerable to climate volatility. Raw material dependencies center on fermentation-derived hyaluronic acid variants, engineered peptides, and biodegradable surfactant chemistry. Geographic supply concentration draws from France, South Korea, and China for biotechnology platforms and active ingredient synthesis. Single-source vulnerability persists in century-old fermentation expertise institutionalized in limited facilities. Distribution runs through consolidated global manufacturing networks for mass-market scale, with direct-to-consumer platforms disintermediating traditional wholesale relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EU REACH chemical restrictions and state-level PFAS bans cascade into recurring reformulation demand across formulation-dependent portfolios.
For Market Incumbents: Hedge synthetic-dependent product line exposure through anticipatory reformulation for ECHA fragrance allergen classifications and United States state-level PFAS bans. Deepen backward integration into captive biotechnology labs producing proprietary hyaluronic acid variants. Channel control through professional salon education investment defends hair styling segment positioning against digital-native entrants.
For New Entrants and Emerging Players: Begin with waterless formulation architectures where technical barriers constrain incumbent rapid migration despite sustainability tailwinds. Male grooming skincare and scalp health formats present the most penetrable white space previously oriented toward female demographics. Live commerce integration in China and South Korea offers the strongest go-to-market angle for subscription replenishment model establishment.
For Investors and Strategic Acquirers: Personal care conglomerates seeking biotechnology capability gaps represent the most active acquirer in this space. Acquisition targets should concentrate on regional specialists with institutionalized fermentation expertise or digital-native brands with proven direct-to-consumer unit economics. Watch anticipatory reformulation completion rates for waterproof and long-wear categories as the signal indicating first-mover advantage capture in clean performance segments.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Biotechnology Lab Investment | Proprietary hyaluronic acid production secures clinical-grade positioning against fermentation expertise scarcity. |
| Waterless Product Architecture Launch | Concentrated solid formats address EU REACH chemical restrictions while reducing shipping cost structures. |
| Direct-to-Consumer Channel Expansion | Owned digital platforms disintermediate department store wholesale relationships and accumulate first-party data. |
| Anticipatory PFAS Reformulation | Early transition from fluorinated compounds in waterproof makeup creates clean performance category leadership. |
| Professional Salon Education Investment | Technical training support secures exclusive distribution territories in hair styling segments. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with brand managers, category buyers at retailers, channel sales heads, and supply planners with secondary validation against Nielsen retail audit data, customs records, SEC filings, and ECHA substance evaluation databases. Bottom-up SKU-level modeling and top-down category sizing triangulated volume and value estimates.
Segment-weighting approaches distributed projections across product type, application, customer type, and distribution channel dimensions throughout the forecast period. CAGRs derived from regression analysis of historical trajectory and regulatory-driven demand inflection points incorporated biotechnology platform adoption curves and clean beauty reformulation cycle timing as industry-specific inputs.
Several conditions sit outside the modeled scope, including black-market cosmetic trade volumes, unregistered direct-sales channel activity, and raw material price shocks beyond historical volatility bands. Deviation in ECHA fragrance allergen classification timing or United States state-level PFAS ban coordination would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
United States Male Grooming Products Market
Beauty & Personal Care
Luxury Beauty Devices Market
Beauty & Personal Care
Cosmetic Palettes Market
Beauty & Personal Care
Mens Intimate Care Products Market
Beauty & Personal Care
Mexico Beauty and Personal Care Market
Beauty & Personal Care
UV Nail Gel Market
Beauty & Personal Care
Hair Removal Spray Market
Beauty & Personal Care
Cosmetology Market
Beauty & Personal Care
Europe Hair Conditioner Market
Beauty & Personal Care
Home Use Anti-Aging Beauty Device Market
Beauty & Personal Care
United States Beauty and Personal Care Products Market
Beauty & Personal Care
Australia Facial Care Market
Beauty & Personal Care
US Color Cosmetics Market
Beauty & Personal Care
Hair Color Spray Market
Beauty & Personal Care
Facial Epilator Market
Beauty & Personal Care
Hair Removal Wax Market