
 Eyelash Serum Market | 2026-2036
Eyelash Serum Market Size, Share, and Industry Trends Forecast 2026-2036
Eyelash Serum Market Analysis
Professional beauty salons is collapsing into medical clinics and at-home personal care as the dominant buyer archetype for eyelash serums. Grande Cosmetics leverages its physician-dispensed heritage to anchor credibility in the prescription-adjacent segment. RevitaLash Cosmetics sustains premium positioning through proprietary peptide complexes that differentiate its formulations from commodity alternatives. Shiseido Company, Limited competes by extending its R&D infrastructure from skincare into lash-specific biotechnologies.
Eyelash serum denotes a topical cosmetic formulation designed to enhance lash length, density, and resilience through active ingredients such as prostaglandin analogs, peptides, or biotin, typically applied along the upper eyelid margin with a fine brush applicator. These products function by extending the anagen growth phase of the hair follicle cycle and conditioning the lash shaft to reduce breakage, serving both aesthetic consumer markets and professional beauty service providers. Growth serums command the largest revenue pool due to their clinical positioning and higher price points, while conditioning serums represent the fastest-expanding category as consumers integrate them into daily skincare rituals. Peptide-based formulations capture disproportionate margin attention from investors because they navigate regulatory scrutiny more cleanly than prostaglandin-containing alternatives.
The FDA oversees eyelash serums containing drug ingredients such as bimatoprost through its ophthalmic drug approval pathway, while the EU Cosmetics Regulation mandates safety assessments that exclude certain prostaglandin analogs from cosmetic formulations. ISO 22716 Good Manufacturing Practices for cosmetics provide the baseline quality framework that manufacturers must satisfy for market access across multiple jurisdictions. Stakeholders must monitor evolving regulatory distinctions between cosmetic and drug classifications, as these boundaries determine which distribution channels remain accessible and which formulation investments retain commercial viability.
Market Dynamics
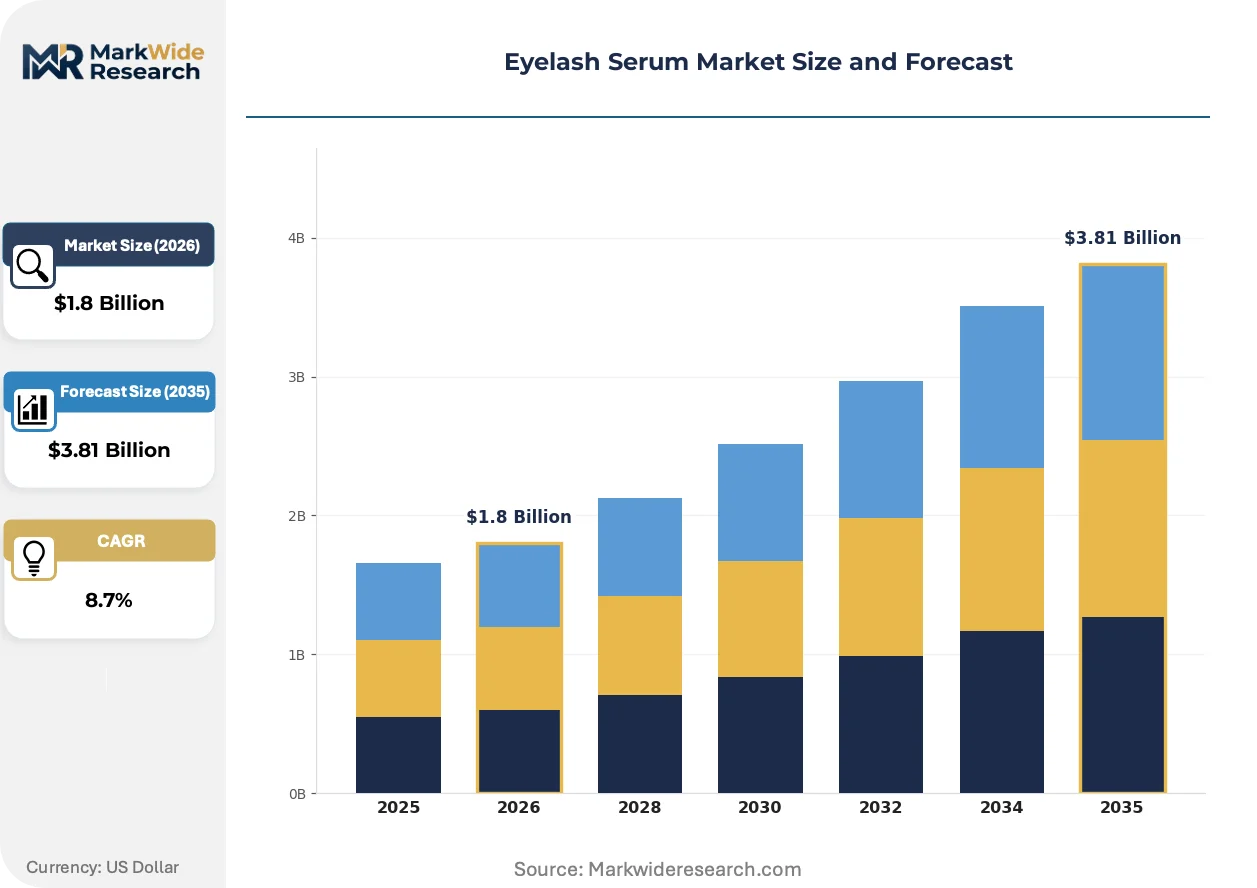
The eyelash serum market is restructuring around the regulatory divergence between cosmetic and drug classification pathways, with peptide-based formulations gaining commercial traction as prostaglandin analogs face heightened safety scrutiny across major jurisdictions.
Growth Catalysts
- EU Cosmetics Regulation safety assessments:The framework's exclusion of certain prostaglandin analogs from cosmetic use is redirecting R&D investment toward peptide and biotin-based alternatives that clear regulatory barriers more efficiently.
- Professional beauty salon service expansion:Lash treatment menus are broadening beyond extensions to include conditioning protocols that integrate retail serum sales into recurring service relationships.
- Direct-to-consumer subscription models:Social media-native brands are capturing recurring revenue through automated replenishment programs that reduce customer acquisition costs and improve lifetime value metrics.
Market Restraints
- FDA ophthalmic drug pathway requirements:Bimatoprost-containing formulations must navigate lengthy approval timelines that delay market entry and inflate development expenditures relative to cosmetic-class competitors.
- Raw material concentration in specialized peptide suppliers:A limited base of contract manufacturers with GMP-certified facilities for bioactive cosmetic ingredients creates supply vulnerability and pricing power asymmetries.
- Mascara and extension substitution:Lower-cost daily cosmetics and semi-permanent lash extension services compete for the same aesthetic expenditure pool, particularly among price-sensitive consumer segments.
Strategic Opportunities
- Underpenetrated male grooming segments:Conditioning serums positioned for brow and lash health in men's personal care represent whitespace with minimal incumbent competition and premium pricing potential.
- Convergence of lash and scalp hair biotechnology:Follicle-stimulating peptide complexes developed for eyelash applications are transferring to eyebrow and hairline products, expanding addressable market scope per R&D dollar.
- Medical clinic channel development:Physician-dispensed positioning adjacent to aesthetic dermatology and ophthalmology practices commands higher price points and insulates against retail price erosion.
Industry Challenges
- Cosmetic-drug classification ambiguity:Regulatory authorities in multiple jurisdictions apply inconsistent standards to prostaglandin-containing formulations, forcing parallel compliance strategies and legal risk exposure.
- Formulation stability expertise scarcity:The specialized knowledge required to maintain peptide bioactivity across shelf-life and temperature variations constrains qualified manufacturing partner availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eyelash Serum Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Growth Serums, Conditioning Serums, Repair Serums, Enhancing Serums Application: Personal Care, Beauty Salons, Retail Outlets, Medical Clinics Ingredient Type: Pantheol, Peptides, Biotin, Natural Extracts Price Tier: Luxury, Premium, Mid-range, Budget |
| Companies Covered | L'Oréal S.A., Grande Cosmetics, RevitaLash Cosmetics, Latisse, Shiseido Company, Limited, JB Cosmetics Group, Pacifica Beauty, Skin Research Laboratories, Neora, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eyelash Serum Market Emerging Trajectories
Formulation science and distribution architecture are diverging simultaneously as regulatory pressure and consumer channel preferences reshape competitive requirements.
Peptide-based active delivery systems are bifurcating the market between clinical-positioned growth serums and daily-use conditioning formats. Professional salons are adopting the former for service-menu integration, while direct-to-consumer brands are scaling the latter through subscription mechanics. This technology split is compressing the middle market for undifferentiated commodity serums and rewarding specialized positioning.
REACH compliance obligations in Europe are forcing reformulation investments that exceed the cost structures of smaller competitors. The regulation's data requirements for novel cosmetic ingredients are consolidating supplier relationships toward established peptide houses with existing safety dossiers. Multinational brands with dedicated regulatory affairs functions are absorbing these costs more efficiently than emerging challengers.
Subscription-based replenishment is displacing episodic retail purchasing in the United States direct-to-consumer segment. Social media acquisition funnels are feeding automated delivery programs that reduce churn through habit formation rather than promotional discounting. This behavioral shift is most visible among millennial and Gen-Z demographics in coastal metropolitan markets where digital-native beauty brands have achieved category penetration.
Eyelash Serum Market Segmentation
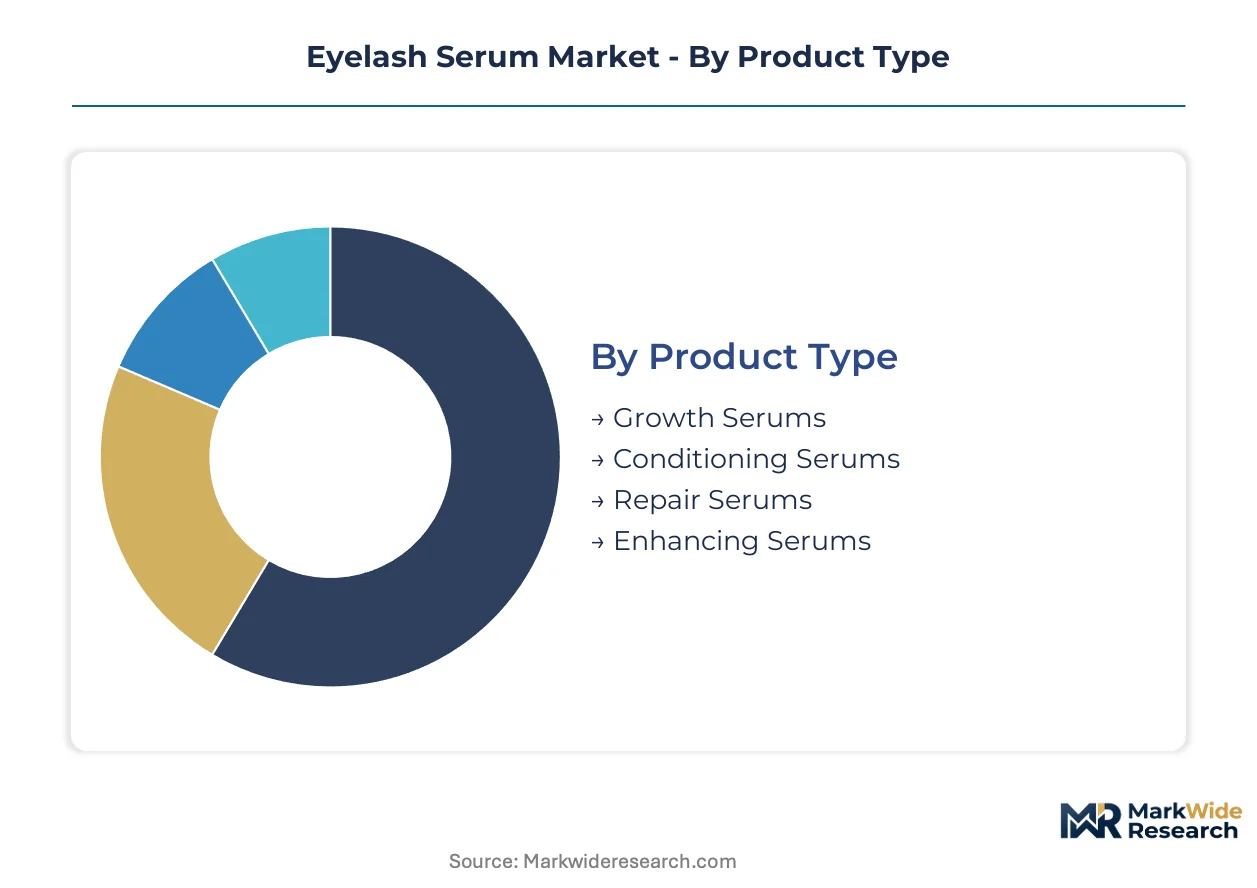
Eyelash serum segmentation reveals how formulation chemistry and channel economics split demand across distinct buyer archetypes. Understanding these divides exposes where pricing power concentrates and which technology platforms scale efficiently.
Product Type:
Growth serums dominate export flows to Asia-Pacific markets, while conditioning formats sell predominantly through domestic direct-to-consumer channels in North America and Europe.
- Growth Serums:These formulations deploy prostaglandin analogs or high-concentration peptide complexes to extend the anagen growth phase of lash follicles. Demand clusters in South Korea and Japan where medical-aesthetic crossover positioning commands premium shelf space in dermatology clinics.
- Conditioning Serums:Daily-use formulations emphasizing biotin and panthenol for shaft resilience and breakage reduction. United States subscription brands have built recurring revenue engines around this segment, integrating it into broader skincare rituals through social media acquisition funnels.
- Repair Serums:Targeted formulations for post-extension damage recovery, typically sold through professional salon channels in Germany and France.
- Enhancing Serums:Cosmetic-tinted hybrids combining conditioning actives with immediate visual density effects, popular in Brazilian and Mexican retail pharmacies.
Growth serums hold the largest share; momentum sits with conditioning serums.
Application:
Channel cost structures range from high-touch professional service integration to automated digital replenishment, with margin profiles inversely related to customer acquisition friction.
- Personal Care:At-home application dominates volume through e-commerce subscriptions and mass retail placement. This channel absorbs the majority of peptide-based formulations that navigate cosmetic classification cleanly without prescription requirements.
- Beauty Salons:Professional service integration enables serum retail attachment to lash extension and lifting procedures. United Kingdom and Australian salon chains have formalized these protocols into standardized treatment menus.
- Retail Outlets:Sephora, Ulta, and equivalent beauty specialists provide discovery-driven purchase environments for prestige brands in urban United States and Canadian markets.
- Medical Clinics:Physician-dispensed positioning adjacent to aesthetic dermatology and ophthalmology practices in Switzerland and the United Arab Emirates commands the highest price points and insulates against retail price erosion.
Personal care channels capture the greatest volume; medical clinics deliver the steepest expansion trajectory.
Ingredient Type:
Raw material sourcing geography and regulatory clearance timelines differentiate these platform technologies.
- Panthenol:Vitamin B5 derivative conditioning the lash shaft through moisture retention and cuticle sealing. Widely approved across jurisdictions with minimal regulatory burden.
- Peptides:Signal molecules stimulating keratin production and follicle metabolism. European peptide houses in Switzerland and the Netherlands dominate supply, with REACH-compliant safety dossiers enabling rapid market access.
- Biotin:Water-soluble B-vitamin supporting keratin infrastructure. Popular in clean-beauty positioned brands targeting ingredient-conscious consumers in California and New York metropolitan markets.
- Natural Extracts:Botanical sourcing from argan, castor, and green tea for positioning in organic-certified segments, concentrated in French and Italian formulation traditions.
Peptide platforms anchor the premium tier; biotin is gaining share fastest among mass-market entrants.
Price Tier:
Pricing stratification reflects certification grade, active concentration, and channel service intensity rather than manufacturing cost alone.
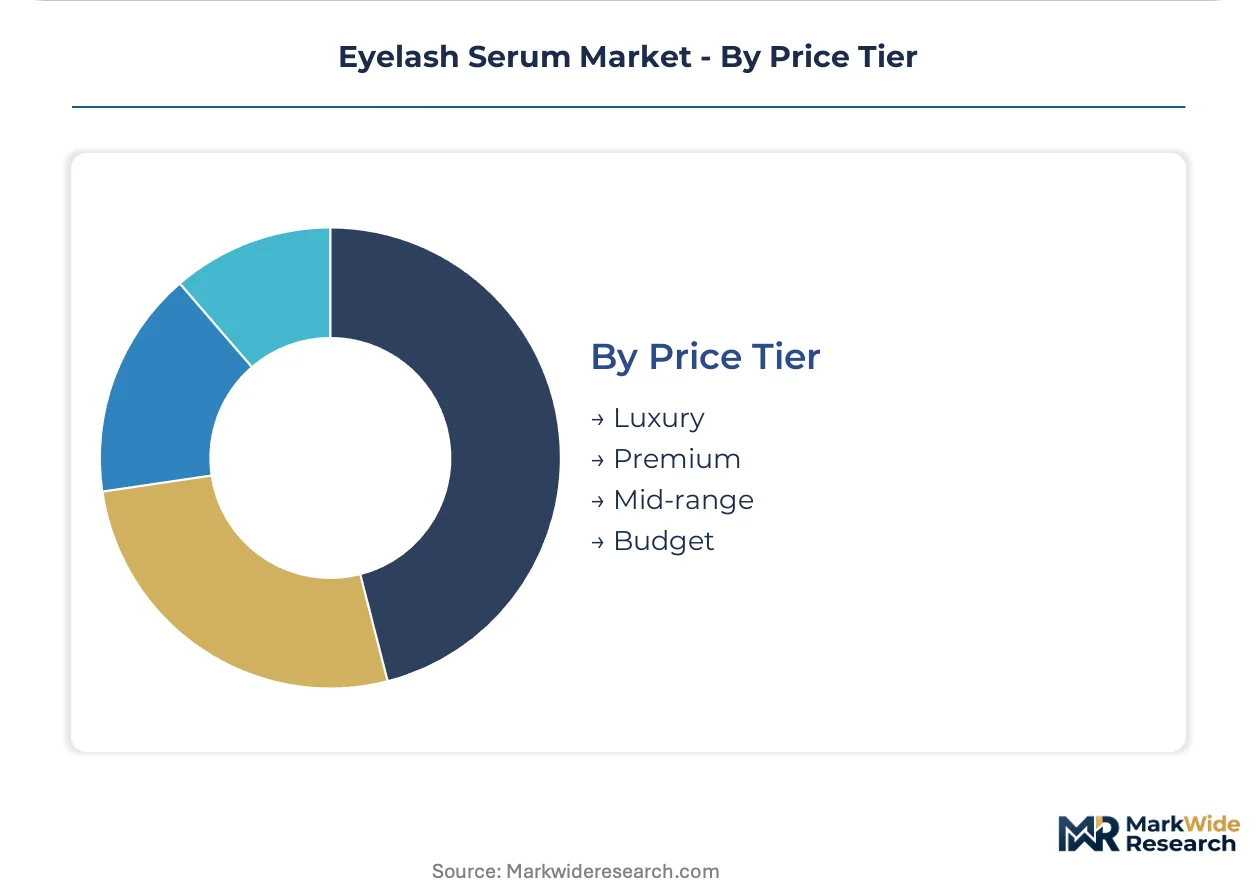
- Luxury:Positioning above $150 per unit with clinical-study substantiation and limited distribution through medical and high-service salon channels in London, Paris, and Dubai.
- Premium:$75-150 range occupying Sephora and equivalent specialty retail, where peptide complexity and packaging innovation justify elevation above mass alternatives.
- Mid-range:$30-75 segment where direct-to-consumer brands compete on subscription economics and influencer marketing efficiency in United States coastal cities.
- Budget:Sub-$30 mass retail placement through drugstore chains in Mexico, Brazil, and Southeast Asian markets, with biotin and panthenol as primary actives.
Premium pricing captures disproportionate margin attention; mid-range subscription models are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation expertise clusters in Switzerland and the Netherlands where peptide houses maintain REACH-compliant safety dossiers. Regulatory divergence between cosmetic and drug classifications fragments manufacturing investment across jurisdictions with divergent approval timelines.
United States
Direct-to-consumer subscription models dominate volume through automated replenishment programs in coastal metropolitan markets. FDA oversight of bimatoprost-containing formulations through ophthalmic drug pathways delays market entry for prescription-adjacent products. Los Angeles and New York anchor influencer-driven acquisition funnels that feed recurring revenue engines for digital-native brands.
South Korea
Medical-aesthetic crossover positioning commands premium shelf space in dermatology clinics across Seoul. MFDS maintains stringent safety assessments for prostaglandin analogs that redirect formulation investment toward peptide alternatives. Gangnam district concentrates flagship clinic networks that integrate retail serum sales into standardized treatment protocols.
Germany
Professional salon channels in Berlin and Munich formalize conditioning protocols into recurring service relationships with attached retail sales. REACH compliance obligations for novel cosmetic ingredients consolidate supplier relationships toward established peptide houses with existing safety dossiers. Bavaria hosts GMP-certified contract manufacturers serving premium European brands.
United Kingdom
Salon chain networks in London and Manchester have standardized lash treatment menus that integrate serum retail into extension and lifting procedures. MHRA alignment with EU Cosmetics Regulation safety frameworks excludes certain prostaglandin analogs from cosmetic formulations. Greater London concentrates prestige brand headquarters leveraging physician-dispensed heritage for credibility positioning.
Japan
Shiseido and domestic competitors extend R&D infrastructure from skincare into lash-specific biotechnologies targeting discerning consumers in Tokyo and Osaka. PMDA maintains distinct cosmetic-drug boundaries that influence formulation investment decisions. Kanto region anchors biotechnology clusters transferring follicle-stimulating peptide complexes from eyelash to scalp hair applications.
Eyelash Serum Market Vendor Landscape
Concentration sits with multinational beauty conglomerates and physician-dispensed specialists competing across distinct regulatory and channel vectors. The market structures into three tiers: prescription-adjacent clinical brands, prestige direct-to-consumer labels, and mass-market retail entrants. Strategic moves center on peptide-based reformulation to navigate prostaglandin restrictions and subscription infrastructure deployment to capture recurring revenue.
Within the physician-dispensed tier, Grande Cosmetics and RevitaLash Cosmetics exemplify credibility positioning adjacent to aesthetic dermatology practices. Shiseido Company, Limited represents multinational R&D leverage extending skincare biotechnology into lash-specific applications. L'Oréal S.A. anchors mass-market scale with distribution infrastructure spanning retail pharmacy and specialty beauty channels across multiple continents.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| Grande Cosmetics |
| RevitaLash Cosmetics |
| Latisse |
| Shiseido Company, Limited |
| JB Cosmetics Group |
| Pacifica Beauty |
| Skin Research Laboratories |
| Neora |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between Swiss peptide houses and premium serum brands lock in both REACH-compliant raw material access and multi-year price visibility that insulates against supply shocks. These contracts concentrate pricing power with established GMP-certified manufacturers while forcing emerging competitors into volatile spot markets for bioactive ingredients.
Pricing Analysis
Volume-discount tiering structures dominate the United States direct-to-consumer segment, where subscription commitments of six to twelve months unlock per-unit reductions against single-purchase pricing. Certification grade and peptide concentration complexity drive price differentiation between medical clinic and mass retail channels. Pricing pressure stems from biotin-based mass entrants undercutting premium peptide positioning in coastal metropolitan markets. Budget-tier buyers in Southeast Asian drugstore chains exhibit highest price sensitivity, while physician-dispensed segments in Dubai and London maintain lowest elasticity.
Supply Chain Analysis
Switzerland and the Netherlands anchor peptide synthesis and safety dossier compilation for REACH-compliant cosmetic actives. South Korea and Japan supply specialized prostaglandin analog alternatives cleared through MFDS and PMDA pathways respectively. Raw material sourcing draws from argan cultivation in Morocco, castor seed processing in India, and biotech fermentation facilities in Germany. Single-source vulnerability concentrates in Swiss contract manufacturers holding exclusive peptide complex patents. Distribution runs through professional salon networks in Germany and the United Kingdom, direct-to-consumer platforms in the United States, and medical clinic channels in South Korea and Switzerland.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Eyelash serum markets face high-growth disruption as regulatory divergence between cosmetic and drug classifications accelerates peptide-based reformulation cycles across major jurisdictions.
For Market Incumbents: Fortify supply chain control through backward integration into GMP-certified peptide manufacturing or exclusive capacity reservations with Swiss and Dutch contract houses. Deepen regulatory affairs capabilities to navigate parallel FDA ophthalmic drug and EU Cosmetics Classification compliance strategies. Defend against direct-to-consumer subscription entrants by locking salon channel exclusivity in Germany and the United Kingdom.
For New Entrants and Emerging Players: REACH dossier fast-tracks through partnerships with established European peptide houses enable rapid market access without multi-year safety study investments. Target male grooming segments in the United States and United Kingdom where conditioning serum positioning for brow and lash health remains underpenetrated. Deploy social media-native acquisition funnels feeding automated replenishment programs to capture recurring revenue against episodic retail competitors.
For Investors and Strategic Acquirers: Physician-dispensed heritage brands with established aesthetic dermatology channel relationships represent the highest-conviction acquisition archetype for long-term viability. Monitor regulatory enforcement intensity around prostaglandin analog classification as the critical inflection signal determining which formulation platforms retain commercial viability. Prioritize targets with demonstrated peptide bioactivity stability expertise across shelf-life and temperature variation requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Peptide-Based Reformulation | REACH-compliant alternatives bypass prostaglandin restrictions while maintaining clinical positioning in European markets. |
| Subscription Infrastructure Deployment | Automated replenishment programs reduce customer acquisition costs for digital-native brands competing against established retail presence. |
| Medical Clinic Channel Expansion | Physician-dispensed positioning in Gangnam and Dubai commands price premiums insulated from mass retail erosion. |
| Regulatory Affairs Capability Buildout | Dedicated compliance functions absorb FDA and EU divergence costs more efficiently than emerging challengers. |
| Male Grooming Line Extension | Brow and lash conditioning serums target whitespace segments with minimal incumbent competition in United States metropolitan markets. |
Methodological Framework
Desk research of regulatory filing databases, customs trade records, and salon industry association publications preceded structured interviews with peptide synthesis technical directors, cosmetic regulatory affairs leads, professional salon chain procurement managers, and direct-to-consumer brand marketing executives. Secondary validation drew from FDA 510(k) submissions, ECHA REACH registrations, MFDS cosmetic safety assessments, and social media advertising spend disclosures. Bottom-up volume estimates across product type, application channel, and ingredient technology platforms were triangulated against top-down market sizing derived from premium brand revenue disclosures and mass retail placement audits.
Variance decomposition across the projection horizon isolates growth contribution by segmentation dimension including serum category, distribution channel economics, active ingredient platform, and regional regulatory cluster. CAGRs were derived from modeled unit volume trajectories and price tier evolution assumptions. Forecast inputs incorporated peptide supplier capacity expansion timelines, salon service menu integration rates, and social media customer acquisition cost trends specific to beauty subscription commerce.
Underlying assumptions cover sustained regulatory divergence between cosmetic and drug classifications, with deviation risk concentrated in harmonized prostaglandin restrictions or accelerated FDA enforcement against unapproved ophthalmic drug claims. Recalibration cycles align with material shifts in EU Cosmetics Regulation guidance, peptide synthesis capacity commissioning, and direct-to-consumer churn rate inflections in coastal United States markets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
US Color Cosmetics Market
Beauty & Personal Care
Brazil Sustainable Personal Care Market
Beauty & Personal Care
Hair Straightener Market
Beauty & Personal Care
Global and North America Organic and Natural Feminine Care Market
Beauty & Personal Care
Europe Shampoo Market
Beauty & Personal Care
Facial Cleansers and Toners Market
Beauty & Personal Care
Germany Beauty Industry Market
Beauty & Personal Care
Bath and Shower Products Market
Beauty & Personal Care
Body Mist Market
Beauty & Personal Care
Sustainable Personal Care Market
Beauty & Personal Care
Global Electric Head and Scalp Massager Market
Beauty & Personal Care
Spray Tanning Market
Beauty & Personal Care
Europe Lip Care Products Market
Beauty & Personal Care
Men's Skincare Products Market
Beauty & Personal Care
Europe Cosmeceuticals Market
Beauty & Personal Care
Asia-Pacific Hair Conditioner Market