
 Asia-Pacific Bath and Shower Products Market | 2026-2036
Asia-Pacific Bath and Shower Products Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Bath and Shower Products Market Outlook
The hospitality sector is recalibrating its amenity procurement standards across Southeast Asian resort and boutique hotel chains, shifting from bulk synthetic formulations to branded individual-use products. Unilever leverages its Hindustan Unilever subsidiary to dominate mass-market body wash penetration across Indian urban centers. Kao Corporation anchors its position through specialized Japanese fermentation-derived ingredient technology in premium shower gel lines. Amorepacific Corporation differentiates via hanbang-inspired medicinal formulations targeting skin-condition-specific segments.
Asia-Pacific bath and shower products encompass surfactant-based cleansing formulations, emollient systems, and fragrance compounds designed for epidermal hygiene and dermatological maintenance, typically manufactured through cold-process saponification or hot-mix emulsification with pH stabilization between 5.5 and 6.5. Shower gels and body washes lead volume due to higher per-capita usage frequency and pump-dispenser convenience, while organic and natural formulation segments capture expanding margin pools as clean-label preferences intensify across metropolitan consumers. Soap bars retain cost-driven dominance in rural distribution channels where unit economics favor solid formats, though e-commerce penetration is eroding this advantage through subscription-based liquid product delivery.
China's SAMR enforces GB standards governing cosmetic ingredient safety and labeling transparency, while India's BIS mandates product quality certification for imported personal care items, collectively elevating compliance costs for synthetic formulation suppliers. Japan's METI promotes sustainable packaging directives that reshape primary container material selection across regional manufacturing bases. Stakeholders must monitor regulatory divergence between national cosmetic frameworks and emerging ASEAN harmonization initiatives to optimize multi-country portfolio allocation.
Market Dynamics
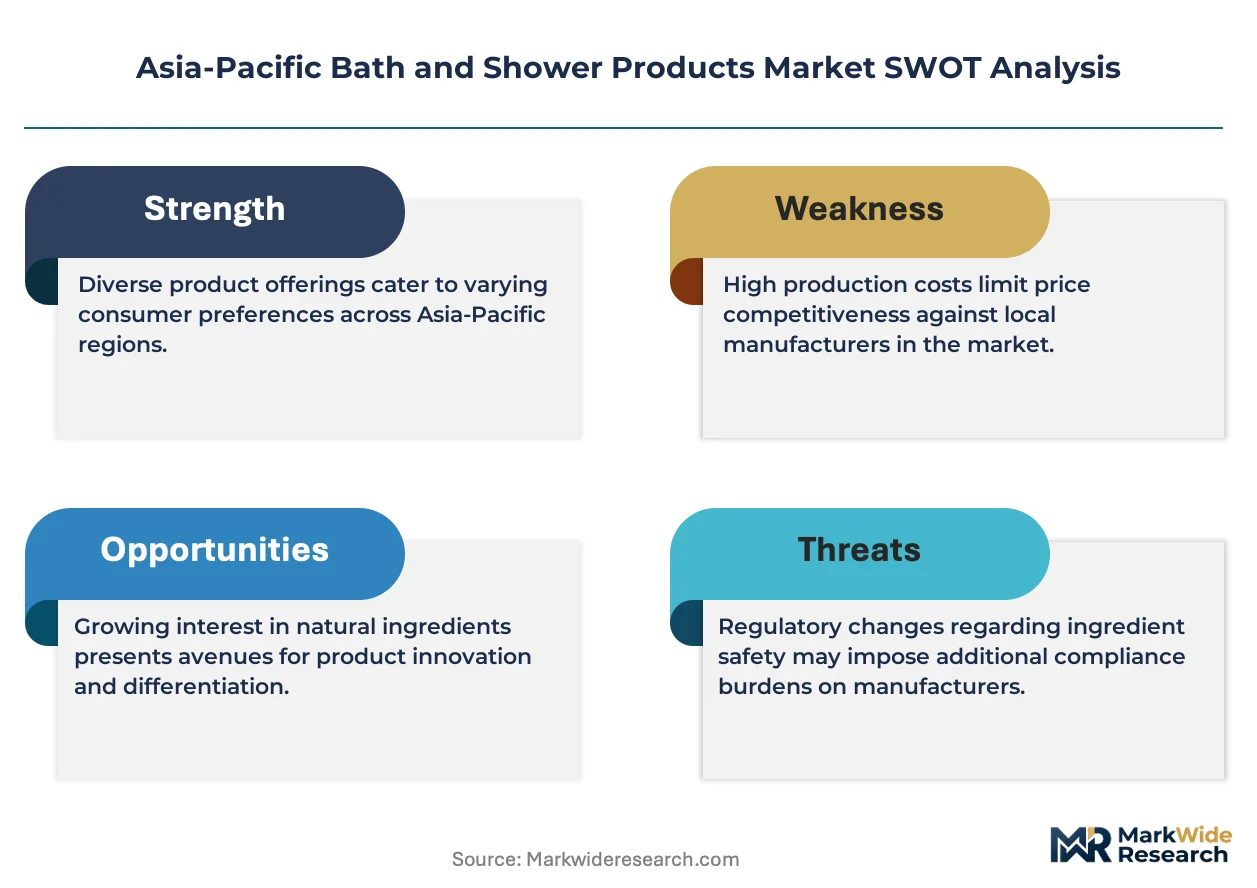
Hospitality procurement standards across Southeast Asian resort chains are forcing formulation upgrades from bulk synthetic amenities to branded individual-use products, compressing margins for commodity suppliers while opening premium positioning for specialized manufacturers.
Growth Catalysts
- GB Standards Compliance:China's SAMR mandates on cosmetic ingredient disclosure are accelerating reformulation investments toward cleaner-label products that command price premiums in tier-one retail channels.
- Modern Retail Penetration:India's tier-two cities are experiencing accelerated body wash adoption as organized retail formats expand shelf space for pump-dispenser liquid products.
- Fermentation Technology:Japanese-derived bio-fermentation processes for surfactant production are reducing petrochemical dependency while improving skin tolerance profiles in sensitive-skin formulations.
Market Restraints
- Palm Oil Price Volatility:Fatty acid feedstock costs fluctuate with Malaysian and Indonesian plantation output, destabilizing saponification economics for mass-market soap bar producers.
- Import Certification Burden:India's BIS quality mandates impose testing timelines and documentation costs that disadvantage smaller foreign suppliers without local manufacturing presence.
- Synthetic Surfactant Substitution:Sulfate-free preference trends threaten sodium lauryl sulfate formulations that dominate low-cost body wash production.
Strategic Opportunities
- Tier-Two India Expansion:Underpenetrated urban centers outside Mumbai and Delhi present first-mover advantage for brands establishing modern trade relationships before shelf saturation.
- Subscription E-Commerce:Direct-to-consumer refill models bypass traditional distributor markups while capturing recurring revenue streams in metropolitan Australia and South Korea.
- ASEAN Harmonization:Emerging regional cosmetic regulatory alignment could streamline multi-country portfolio registration for manufacturers with Thai or Singaporean production bases.
Industry Challenges
- Formulation Chemist Scarcity:Shortage of specialists capable of navigating divergent national cosmetic safety frameworks complicates regional product development teams.
- Packaging Compliance Divergence:Japan's METI sustainable packaging directives conflict with cost-optimized plastic formats required for price-sensitive Indian rural distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Bath and Shower Products Market |
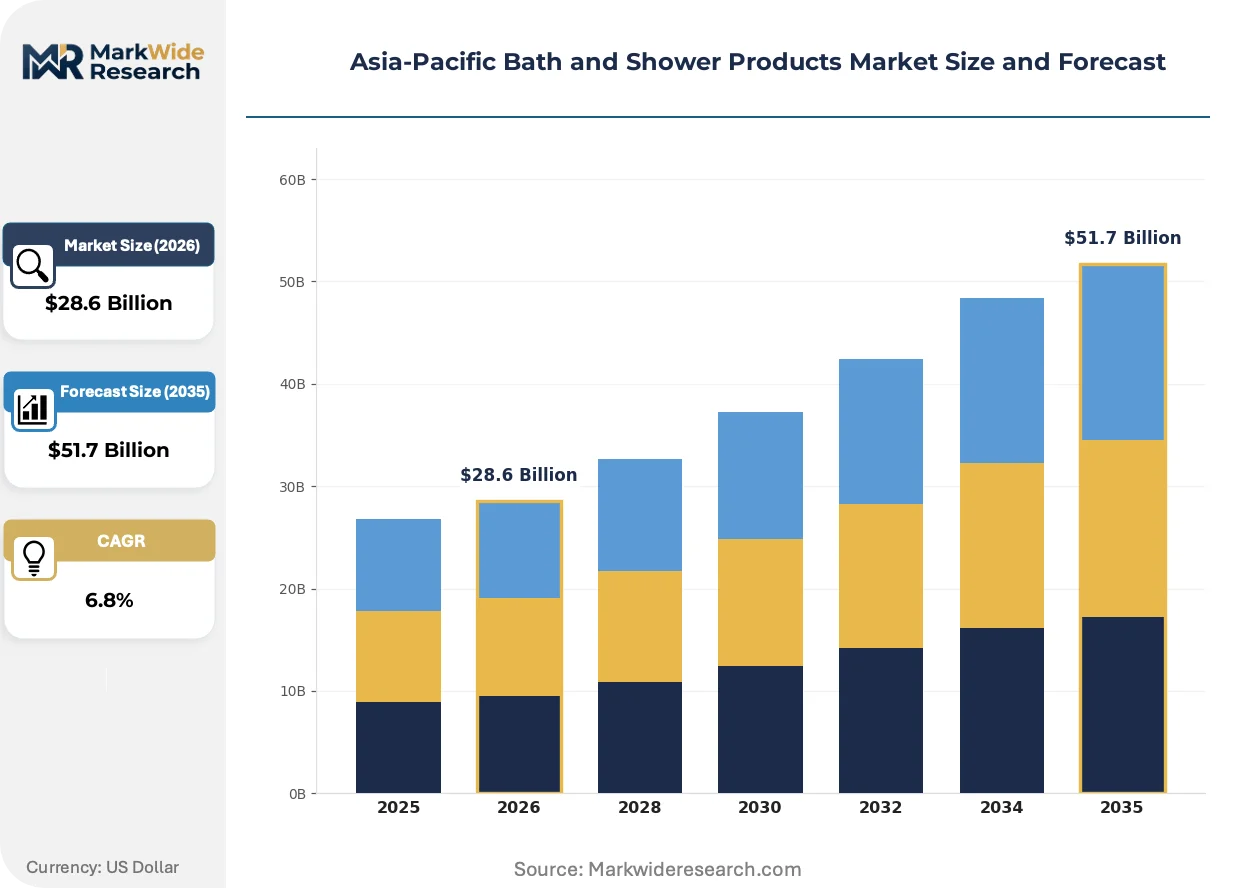
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shower Gels, Bath Salts, Body Washes, Soap Bars Distribution Channel: Supermarkets, E-commerce, Specialty Stores, Pharmacies Customer Type: Residential, Hospitality, Healthcare, Fitness Centers Formulation: Organic, Natural, Synthetic, Medicinal |
| Companies Covered | Unilever, L'Oréal S.A., Procter & Gamble, Johnson & Johnson, Colgate-Palmolive Company, Kao Corporation, Beiersdorf AG, Amorepacific Corporation, LG H&H Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Bath and Shower Products Market Strategic Shifts
Clean-label ingredient transparency and biotechnology-derived surfactants are compressing traditional petrochemical formulation advantages while reshaping procurement relationships between manufacturers and hospitality buyers.
Cold-process fermentation technology for biosurfactant production is unifying mildness performance with environmental biodegradability credentials. Southeast Asian boutique hotel chains are adopting these formulations at accelerated procurement cycles. The technology is unifying premium positioning with mass-market cost structures through scalable bioreactor deployment.
China's GB standards on cosmetic ingredient safety and labeling transparency are mandating full supply chain disclosure for imported personal care items. Foreign manufacturers face reformulation costs or withdrawal from compliant distribution channels. Premium shower gel segments absorb compliance investments through price architecture while economy tiers experience margin compression.
Hospitality buyers are consolidating amenity procurement through centralized sustainability scorecards that prioritize individual-use formats with recyclable packaging. Southeast Asian resort chains are displacing bulk dispensers with branded miniature products. Vietnam and Thailand hospitality markets exhibit the most aggressive transition timelines as international brand standards propagate through management contracts.
Asia-Pacific Bath and Shower Products Market Segmentation
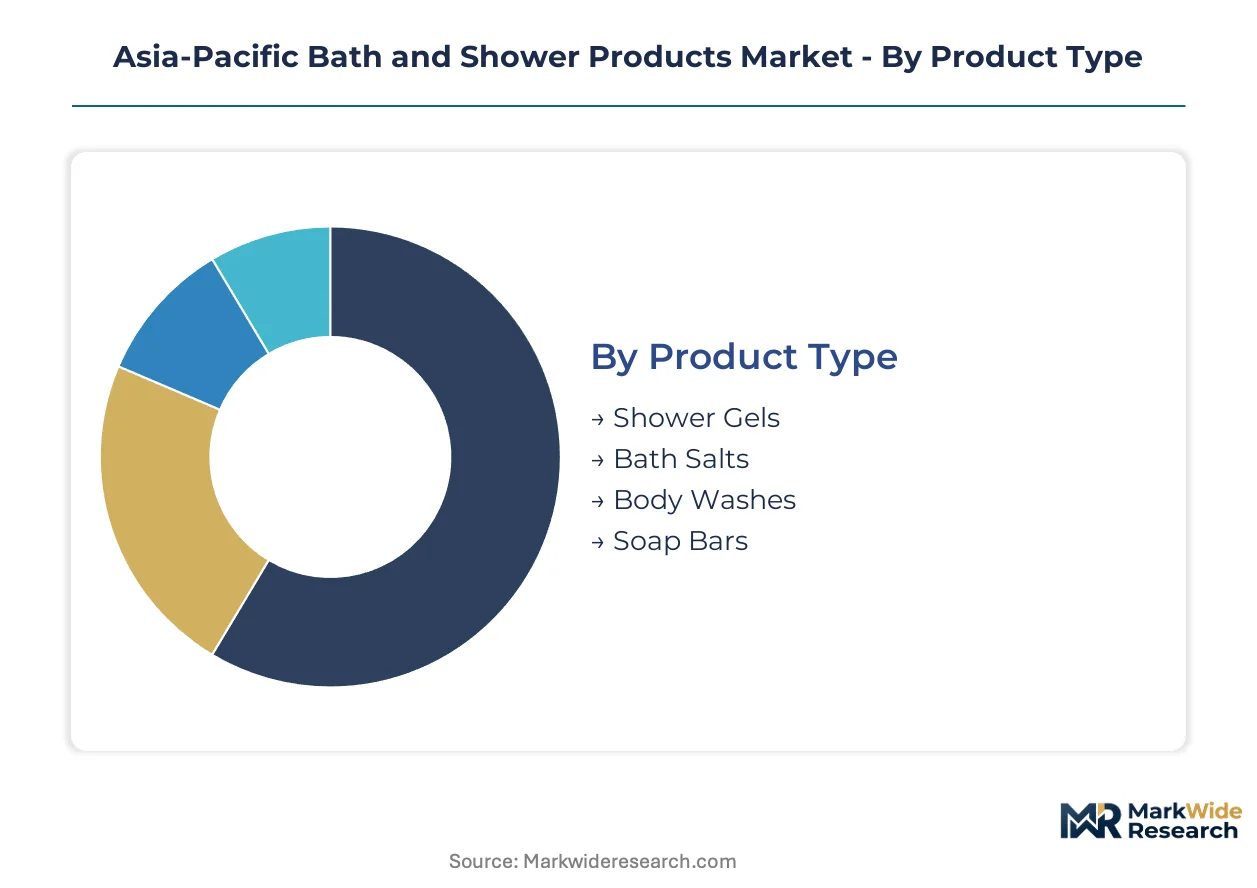
Segmentation in Asia-Pacific bath and shower products reveals divergent compliance burdens and margin structures across formulation types and procurement channels. Understanding these divides enables targeted resource allocation for multi-country portfolios navigating GB standards, BIS certification, and METI packaging directives.
Product Type:
GB standards compliance intensity varies sharply across physical formats, with liquid products facing stricter preservative disclosure requirements than solid bars under China's SAMR mandates.
- Shower Gels:Surfactant-based emulsions with pH stabilization between 5.5 and 6.5, typically incorporating fragrance compounds and emollient systems. Demand concentrates in China's tier-one cities where SAMR ingredient disclosure rules favor transparent supply chains and pump-dispenser convenience drives repeat purchase. GB standards compliance costs compress margins for imported formulations while domestic producers capture price-sensitive volume.
- Body Washes:Thicker viscosity formulations with higher emollient loading than shower gels, designed for dry-skin conditions. India's tier-two cities represent the fastest adoption corridor as modern retail penetration expands shelf space for branded pump formats; BIS quality certification timelines disadvantage smaller foreign suppliers without local manufacturing presence.
- Bath Salts:Mineral-based soaking formulations with epsom salt or Dead Sea mineral compositions, positioned in premium gifting and spa segments.
- Soap Bars:Cold-process saponified or hot-mix formulations retaining cost-driven dominance in rural Indian distribution channels where unit economics favor solid formats and palm oil feedstock volatility destabilizes mass-market production economics.
Leading the category by volume: Body Washes. Growing fastest: Shower Gels.
Distribution Channel:
Channel selection determines margin capture and regulatory exposure, with direct-to-consumer models bypassing India's BIS import certification burdens while modern trade accelerates clean-label product trials.
- Supermarkets:Organized retail formats with centralized procurement and shelf-space fees dominating urban India and Southeast Asian metropolitan centers. These channels absorb compliance investments through premium pricing architectures while economy tiers experience margin compression from listing fee structures.
- E-commerce:Direct-to-consumer and marketplace platforms enabling subscription refill models that bypass traditional distributor markups. Australia's metropolitan consumers and South Korea's digitally native shoppers drive recurring revenue capture through automated replenishment algorithms.
- Specialty Stores:Curated retail environments emphasizing hanbang-inspired or fermentation-derived ingredient stories, concentrated in Japanese and Korean urban shopping districts.
- Pharmacies:Regulated retail channels with pharmacist endorsement requirements, significant for medicinal formulations targeting dermatological conditions in Japan's PMDA-compliant distribution.
Dominant by transaction volume: Supermarkets. Expanding most quickly: E-commerce.
Customer Type:
Procurement sophistication and sustainability scoring intensity separate hospitality and healthcare buyers from residential consumers across the region.
- Residential:Individual consumers purchasing through retail or digital channels, with India's tier-two cities showing accelerated body wash adoption as disposable incomes rise and modern trade formats expand.
- Hospitality:Resort and hotel chains across Vietnam and Thailand implementing centralized sustainability scorecards that displace bulk dispensers with branded individual-use miniature products; international brand standards propagate through management contracts with aggressive transition timelines.
- Healthcare:Hospitals and clinics requiring hypoallergenic and pH-balanced formulations for patient hygiene protocols, particularly in Japan's regulated institutional procurement.
- Fitness Centers:Gym and wellness facility chains with high-frequency usage patterns favoring large-format pump dispensers and bulk procurement economics.
Largest absolute demand: Residential. Procurement standards tightening fastest: Hospitality.
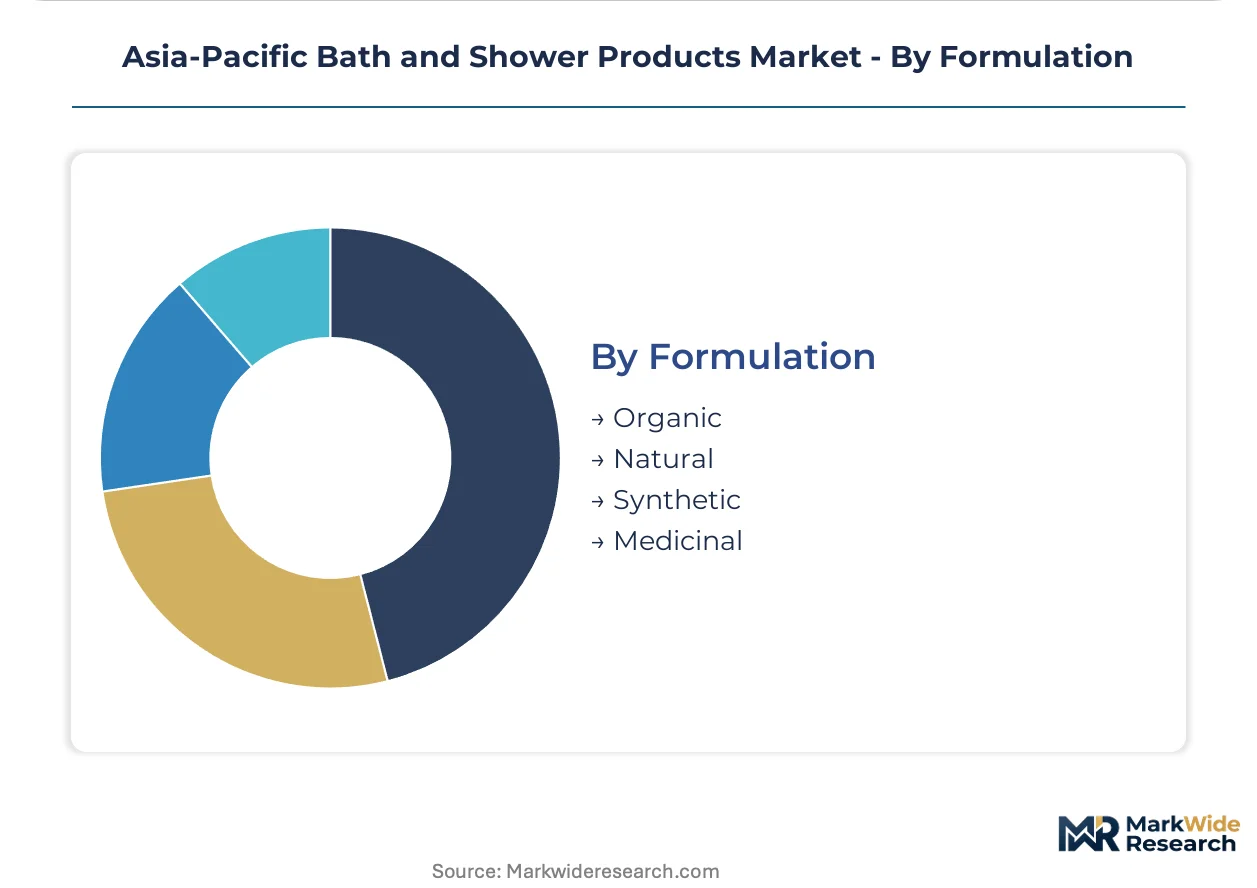
Formulation:
Ingredient origin determines regulatory pathway complexity and price architecture, with organic and natural segments absorbing compliance investments through premium positioning.
- Organic:Certified formulations meeting international organic standards with full supply chain traceability, commanding price premiums in tier-one Chinese retail channels where GB standards on ingredient disclosure accelerate reformulation investments.
- Natural:Plant-derived surfactants and botanical extracts without synthetic petrochemical inputs, capturing expanding margin pools as clean-label preferences intensify across metropolitan Australia and South Korean consumers.
- Synthetic:Petrochemical-derived surfactant systems including sodium lauryl sulfate formulations dominating low-cost body wash production; sulfate-free preference trends threaten volume retention in premium urban segments.
- Medicinal:Hanbang-inspired or dermatologically active formulations targeting skin-condition-specific segments, with Amorepacific Corporation's heritage positioning exemplifying differentiation through traditional Korean medicine integration.
Highest volume share: Synthetic. Steepest expansion trajectory: Natural.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Thailand's Eastern Economic Corridor concentrate contract manufacturing capacity serving hospitality procurement networks across Southeast Asia. These zones attract multinational formulators seeking tariff-advantaged export platforms into Vietnam, Indonesia, and Philippine resort markets.
China
Shanghai and Guangzhou retail corridors absorb premium shower gel volumes as SAMR's GB standards on ingredient disclosure accelerate reformulation investments. Domestic producers leverage compliant supply chains to capture price-sensitive volume while foreign brands absorb compliance costs through tier-one price architecture. Yangtze River Delta manufacturing clusters specialize in fermentation-derived surfactant production for sensitive-skin formulations.
India
Mumbai and Delhi modern trade formats anchor body wash adoption, while tier-two cities including Pune, Ahmedabad, and Hyderabad represent underpenetrated expansion corridors. BIS quality certification timelines disadvantage smaller foreign suppliers lacking local manufacturing presence. Gujarat's chemical manufacturing belt supplies fatty acid feedstocks to domestic saponification facilities serving rural soap bar demand.
Japan
Tokyo-Osaka metropolitan consumers drive premium positioning for bio-fermentation technologies in shower gel formulations. METI's sustainable packaging directives reshape primary container material selection across regional manufacturing bases. Kansai industrial clusters specialize in bioreactor-derived biosurfactant production unifying mildness performance with biodegradability credentials.
South Korea
Seoul's digitally native shoppers anchor subscription e-commerce models for refill-based body wash delivery bypassing traditional distributor markups. MFDS cosmetic safety frameworks align with hanbang-inspired medicinal formulation trends targeting skin-condition-specific segments. Busan-Ulsan chemical complexes supply fermentation-derived ingredient inputs to domestic premium brands.
Australia
Sydney and Melbourne metropolitan markets concentrate clean-label preference intensity for natural and organic formulation segments. TGA-influenced retail environments emphasize dermatological endorsement requirements for sensitive-skin product positioning. Subscription-based direct-to-consumer channels capture recurring revenue streams through automated replenishment algorithms in these urban centers.
Asia-Pacific Bath and Shower Products Market Competitive Environment
Top-tier vendors anchor mass-market penetration through subsidiary networks and established retail relationships, while mid-tier specialists occupy fermentation-technology and hanbang-formulation niches. The competitive structure stratifies across three archetypes: multinational conglomerates with regional subsidiary operations, Japanese and Korean technology-driven specialists, and emerging domestic champions in India and Southeast Asia. Consolidation pressure intensifies through hospitality procurement centralization and compliance cost escalation under divergent national regulatory frameworks.
Within the multinational conglomerate tier, Unilever and Procter & Gamble exemplify scale-driven market presence through mass-market body wash and shower gel distribution across urban retail networks. Kao Corporation occupies a specialist position representing Japanese fermentation-technology differentiation in premium surfactant systems. Amorepacific Corporation anchors the hanbang-inspired medicinal formulation archetype, exemplifying heritage-based positioning targeting skin-condition-specific consumer segments in Korean and broader Asian markets.
| Leading Market Players |
|---|
| Unilever |
| L'Oréal S.A. |
| Procter & Gamble |
| Johnson & Johnson |
| Colgate-Palmolive Company |
| Kao Corporation |
| Beiersdorf AG |
| Amorepacific Corporation |
| LG H&H Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Palm oil fatty acid feedstock costs originating from Malaysian and Indonesian plantation belts cascade through three distinct pricing tiers downstream, with premium shower gel formulations absorbing volatility through branded positioning while mass-market soap bars transmit cost swings directly to price-sensitive rural Indian consumers.
Pricing Analysis
Short lead-time premiums command price architecture in Southeast Asian hospitality procurement, where resort chains facing compressed amenity replacement cycles pay marked-up rates for rapid-turnaround fermentation-derived formulations. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade under China's SAMR GB standards and volume scale commitments, with BIS-certified imports capturing margin premiums while uncertified bulk suppliers compete on spot economics. Pricing pressure stems from sulfate-free substitution trends threatening sodium lauryl sulfate formulations that anchor low-cost body wash production. Hospitality buyers exhibit least price sensitivity due to sustainability scorecard mandates, while rural Indian residential segments resist pump-dispenser premiums in favor of solid-format unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Malaysian and Indonesian palm oil estates supplying fatty acid feedstocks to regional saponification facilities, creating exposure to El Niño-driven output disruptions and plantation labor availability constraints. Manufacturing concentrates in China's Yangtze River Delta fermentation clusters, India's Gujarat chemical belt, and Thailand's Eastern Economic Corridor contract manufacturing zones. Raw material dependencies encompass palm-derived fatty acids, petrochemical surfactant precursors, and Japanese-imported fermentation culture strains. Tariff exposure threatens Thai-based exporters serving Vietnamese and Philippine hospitality networks under divergent ASEAN harmonization timelines. Distribution runs through organized modern trade formats in tier-one Indian cities and direct-to-consumer subscription platforms in Australian and South Korean metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where China's SAMR GB standards on cosmetic ingredient disclosure erect barrier-to-entry moats favoring domestic producers with transparent supply chains and capitalized foreign brands capable of absorbing reformulation investments.
For Market Incumbents: Lock in hospitality procurement relationships through centralized sustainability scorecards that preempt competitor entry via international brand management contract propagation across Vietnam and Thailand resort chains. Deepen backward integration into fermentation-derived surfactant production through Kansai bioreactor capacity expansion, insulating margin structures from petrochemical feedstock volatility while capturing clean-label premium positioning. Counter sulfate-free substitution threats by accelerating biosurfactant R&D pipelines before emerging Korean hanbang specialists capture dermatological endorsement channels. For New Entrants and Emerging Players: Capture tier-two Indian urban centers including Pune, Ahmedabad, and Hyderabad before shelf saturation eliminates first-mover positioning in modern trade body wash categories. Exploit BIS certification timeline disadvantages facing smaller foreign suppliers by establishing local manufacturing presence or partnership structures that bypass import documentation burdens. Lead with subscription e-commerce direct-to-consumer models in Australian metropolitan markets, leveraging automated replenishment algorithms to bypass traditional distributor markup structures and capture recurring revenue streams. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier fermentation-technology specialists in Japan's Kansai industrial corridor facing temporary margin compression from METI sustainable packaging compliance investments. Long-term viability over the extended projection horizon hinges on regulatory divergence arbitrage capabilities across SAMR, BIS, and emerging ASEAN harmonization frameworks. Acquisition target archetype: Japanese or Korean biosurfactant producers with scalable bioreactor infrastructure and established hospitality supply relationships. Signal to monitor: accelerated ASEAN cosmetic regulatory alignment announcements that would streamline multi-country portfolio registration economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biosurfactant Production | Kansai bioreactor deployment unifies mildness performance with METI-compliant biodegradability credentials for hospitality buyers. |
| Direct-to-Consumer Subscription Launch | Automated replenishment algorithms in Sydney and Melbourne bypass traditional distributor markups while capturing recurring revenue. |
| Premium Tier Introduction | Hanbang-inspired medicinal formulations targeting skin-condition-specific segments command price premiums under MFDS frameworks. |
| Distribution Channel Expansion | Modern trade relationships in Pune and Hyderabad establish positioning before tier-two Indian shelf saturation eliminates entry. |
| Sustainability Repositioning | Individual-use miniature formats with recyclable packaging satisfy Southeast Asian resort chain centralized sustainability scorecards. |
Study Parameters
Document review covered customs and trade flow databases, SAMR regulatory filings, and hospitality procurement contract disclosures, complemented by interviews with brand managers at multinational consumer goods subsidiaries, category buyers at Indian modern retail chains, fermentation technology R&D directors in Japanese chemical complexes, and procurement leads at Southeast Asian resort management companies. Secondary validation drew from BIS certification records, METI sustainable packaging directive documentation, and ASEAN harmonization initiative progress reports. Bottom-up volume estimates triangulated against top-down category spending analyses across the analysis window.
Cross-referencing historical adoption curves with expert panel input on regulatory timeline probabilities shaped the analytical framework across product type, distribution channel, customer segment, and formulation origin dimensions. CAGRs were derived through segmented growth rate aggregation with convergence testing against macroeconomic indicators and demographic penetration benchmarks. Industry-specific forecast inputs encompassed palm oil futures curve trajectories, tier-two Indian modern retail format expansion schedules, and hospitality management contract renewal cycles.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ASEAN regulatory harmonization acceleration, El Niño-driven plantation output disruptions, and sulfate-free formulation preference shifts. Forecasts reflect documented assumptions regarding SAMR enforcement intensity, BIS certification processing timelines, and METI packaging directive implementation schedules. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Leave-In Conditioner Market
Beauty & Personal Care
Russia Beauty and Personal Care Market
Beauty & Personal Care
Cosmetic Palettes Market
Beauty & Personal Care
Men's Personal Care Market
Beauty & Personal Care
Stretch Mark Removal Products Market
Beauty & Personal Care
Face Oil Market
Beauty & Personal Care
Soap Market
Beauty & Personal Care
Eyelash Serum Market
Beauty & Personal Care
Beauty Salon Market
Beauty & Personal Care
South America Hair Styling Products Market
Beauty & Personal Care
North America Setting Spray Market
Beauty & Personal Care
United States Bath Soap Market
Beauty & Personal Care
Cosmetic Wax Market
Beauty & Personal Care
Facial Make-Up Market
Beauty & Personal Care
Global Organic Personal Care and Cosmetic Products Market
Beauty & Personal Care
Body Mist Market