
 Facial Care Products Market | 2026-2036
Facial Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Facial Care Products Market Analysis
Dermatological formulation expertise is collapsing across Western Europe, forcing brands to recruit from Asian cosmetic science programs. L'Oréal S.A. leverages captive R&D centers in Singapore to offset this talent drain. The Procter & Gamble Company anchors North American mass-market facial care through pharmacy channel dominance. Shiseido Company Limited navigates premium positioning by controlling ingredient sourcing from Japanese biotech suppliers.
Facial care products encompass topically applied formulations designed to cleanse, hydrate, protect, or treat facial skin, typically containing active concentrations between 0.5% and 5% for over-the-counter retinoids or alpha-hydroxy acids, and manufactured through emulsion-based processes requiring precise pH stabilization between 4.5 and 6.5 to maintain barrier compatibility. Moisturizers occupy the largest revenue pool within product type segmentation due to daily-use frequency and repeat purchase velocity, while cleansers compete on unit volume through mass-market penetration. Anti-aging applications command premium pricing within the application dimension, though brightening segments accelerate fastest in Asia-Pacific markets where pigmentation concerns drive clinical-grade ingredient demand.
The EU Green Deal and REACH frameworks restrict paraben and microplastic additive use, compelling reformulation investments that raise compliance costs for exporters accessing European consumers. The FDA maintains monograph oversight on acne treatment claims, limiting active ingredient marketing for salicylic acid and benzoyl peroxide concentrations above specified thresholds. China's NMPA requires animal-testing alternatives for imported cosmetics, reshaping market access protocols for Western brands. Stakeholders must monitor evolving patchwork regulations across multiple jurisdictions to anticipate formulation mandates before they disrupt supply continuity.
Market Dynamics
EU Green Deal mandates and REACH chemical restrictions are forcing wholesale reformulation of facial care pipelines, collapsing legacy preservative systems and microplastic-dependent textures while accelerating biotech-derived active sourcing from Asian suppliers.
Growth Catalysts
- Clean Beauty Mandates:EU Green Deal and REACH frameworks are eliminating paraben and microplastic additives, creating first-mover advantages for brands with compliant formulations already in market.
- Male Grooming Normalization:Dissolving stigma around men's skincare routines is unlocking incremental daily-use volume in previously underpenetrated demographic segments across developed markets.
- K-Beauty Export Engine:South Korea's multi-step regimen culture sustains premium facial care consumption while generating formulation IP that Western brands license for global distribution.
Market Restraints
- Input Cost Volatility:Plant-derived alternatives to synthetic emulsifiers and preservatives face agricultural supply fluctuations that destabilize unit economics for mass-market SKUs.
- Talent Concentration Risk:Dermatological formulation expertise is collapsing across Western Europe, forcing reliance on Singapore and South Korean cosmetic science programs for skilled R&D recruitment.
- Regulatory Fragmentation:China's NMPA animal-testing alternatives requirement, EU REACH substance restrictions, and FDA acne monograph thresholds create incompatible compliance matrices for global product architectures.
Strategic Opportunities
- Biotech Ingredient Convergence:Fermentation-derived ceramides and postbiotic complexes from Japanese suppliers enable clinical-grade efficacy claims without traditional synthetic actives.
- Pharmacy Channel Expansion:Dermocosmetic positioning through pharmacy and clinic channels captures consumers seeking prescription-adjacent solutions without dermatologist visit friction.
- Personalization Infrastructure:AI-driven skin diagnostic tools paired with modular base formulations allow mass-customization at scale, compressing the traditional trial-and-repeat purchase cycle.
Industry Challenges
- Formulation Talent Scarcity:pH stabilization expertise for emulsion-based processes requiring 4.5-6.5 barrier compatibility is concentrating among aging specialists with limited knowledge transfer pipelines.
- Certification Timeline Compression:EU notified body backlogs for novel cosmetic ingredient safety assessments extend go-to-market timelines by 18-24 months versus historical benchmarks.
- Supply Chain Reconfiguration Costs:Eliminating China-dependent raw material flows for brands targeting EU Green Deal compliance requires qualifying alternative suppliers across Southeast Asian biotech clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Facial Care Products Market |
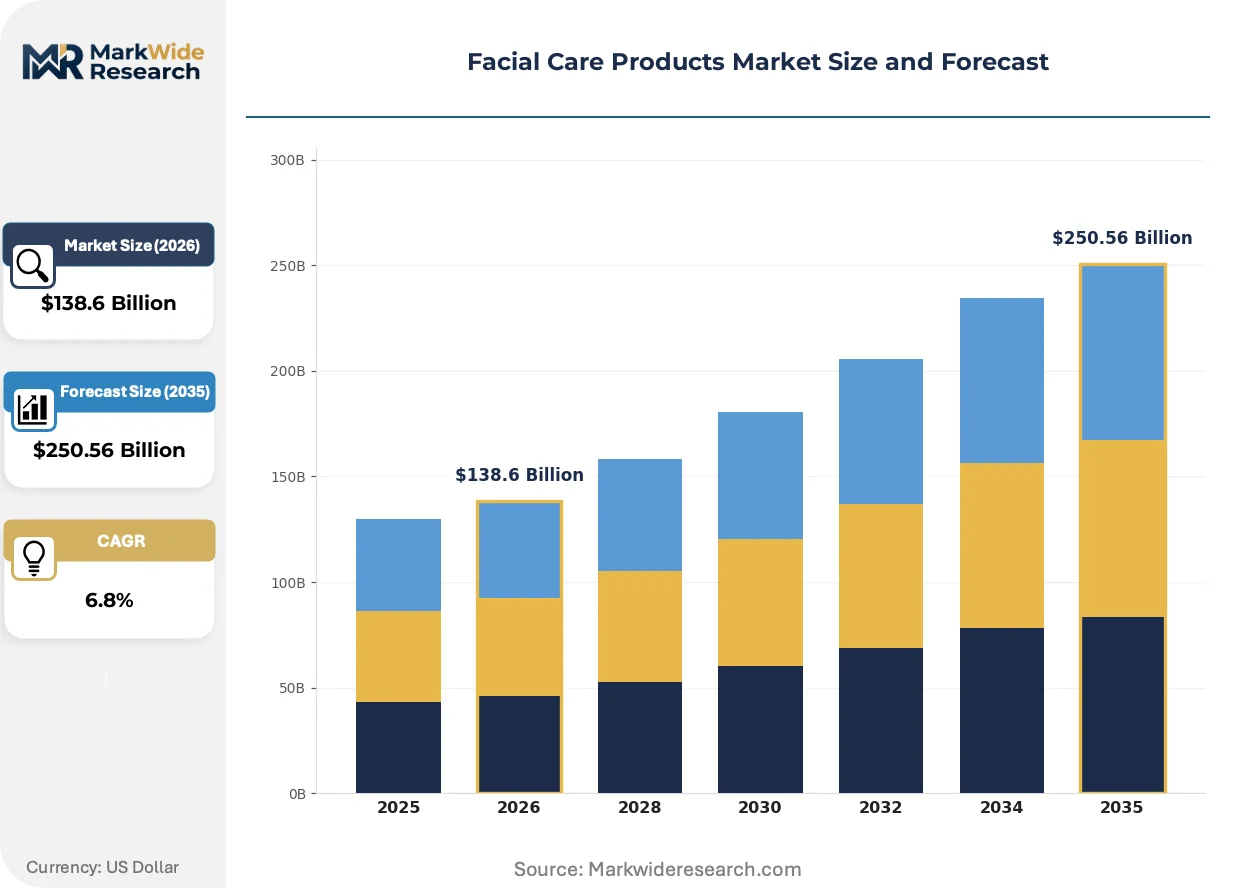
| Market Size in 2026 | $138.6 Billion |
| Market Size in 2035 | $250.56 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Moisturizers, Cleansers, Exfoliators, Masks Application: Anti-Aging, Hydration, Brightening, Acne Treatment End User: Women, Men, Teens, Professionals Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Pharmacies |
| Companies Covered | L'Oréal S.A., The Procter & Gamble Company, Unilever PLC, The Estée Lauder Companies Inc., Beiersdorf AG, Shiseido Company Limited, Johnson & Johnson Services, Inc., Coty Inc., Oriflame Cosmetics AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Facial Care Products Market Emerging Trajectories
Active delivery systems and biomanufacturing platforms are compressing the traditional R&D-to-shelf timeline while regulatory chemistry restrictions force ingredient architecture reinvention.
Encapsulation technology using lipid nanoparticles and microsponge matrices is miniaturizing active ingredient payloads for controlled release at target skin depths. Prestige and clinical brands are adopting these systems to stabilize retinoid and vitamin C potency through shelf life. The technology is miniaturizing formulation minimum effective concentrations, allowing efficacy claims at lower active percentages that reduce irritation incidence and expand addressable skin sensitivity segments.
REACH authorization requirements and EU Green Deal substance restriction roadmaps are phasing out per- and polyfluoroalkyl substances (PFAS) used in long-wear cosmetic films. Industrial consequence includes forced abandonment of waterproof mascara and sunscreen architectures dependent on fluorinated compounds. Color cosmetics and sun care categories face compressed reformulation windows with limited qualified replacement chemistries, driving partnership urgency with specialty silicone and plant-derived polymer suppliers.
Subscription and auto-replenishment models are displacing traditional retail discovery and repurchase patterns for core daily-use categories. Direct-to-consumer platforms and pharmacy loyalty programs capture moisturizer and cleanser replenishment with predictable cadence, reducing promotional dependency. South Korea and Japan demonstrate the model's maturity through integrated beauty app ecosystems that link diagnostic data to personalized product curation with seamless reordering functionality.
Facial Care Products Market Segmentation
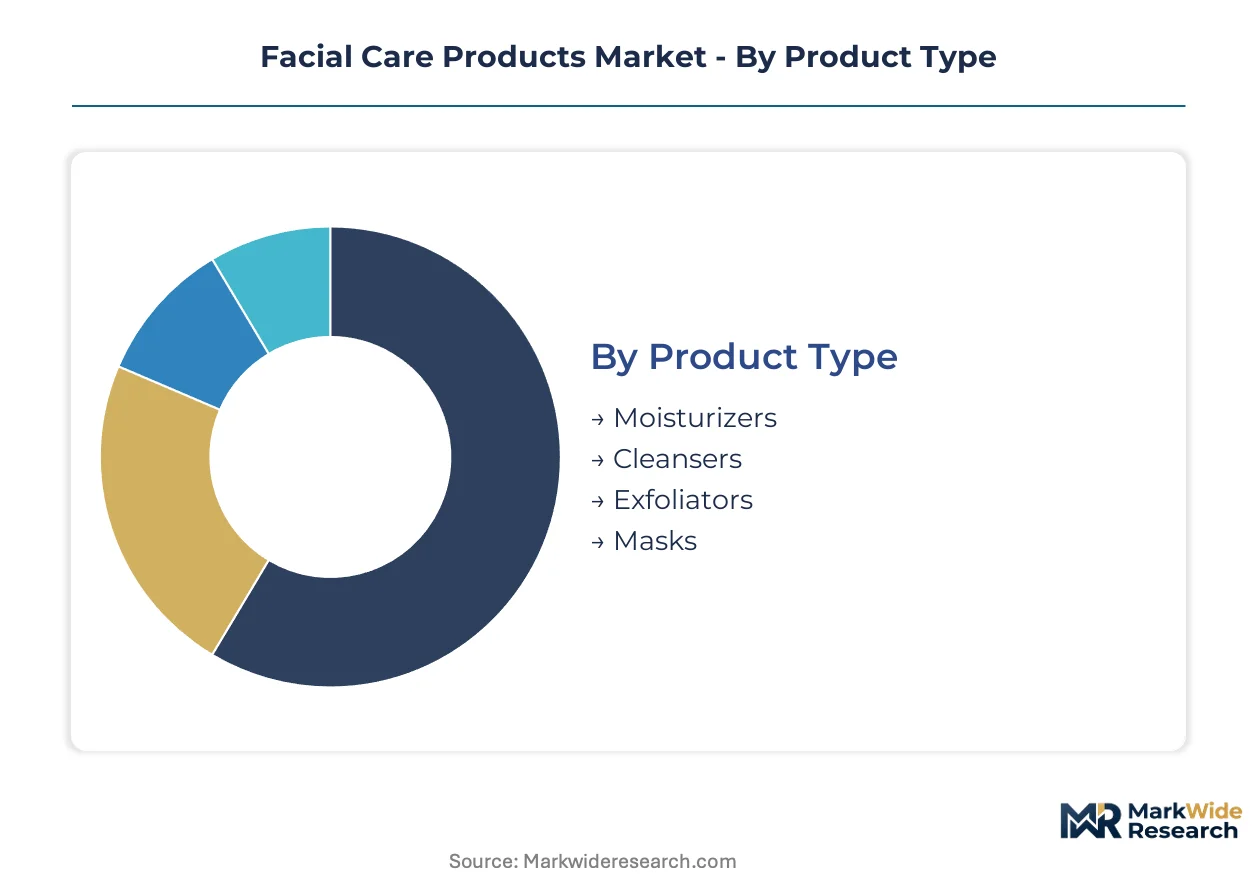
Facial care segmentation reveals divergent growth mechanics across daily-use staples and treatment-grade solutions. Product architecture, channel access, and demographic targeting each create distinct margin profiles and formulation requirements.
Product Type:
Moisturizers and cleansers dominate domestic consumption patterns across developed markets, while masks and exfoliators concentrate in export-led K-beauty distribution channels.
- Moisturizers:Emulsion-based formulations with ceramide and hyaluronic acid concentrations between 0.5% and 2% stabilize barrier function for daily application. Demand concentrates in North American pharmacy channels where consumers seek prescription-adjacent hydration solutions without dermatologist visit friction.
- Cleansers:Surfactant systems including amino acid-based and micellar technologies require precise pH buffering between 5.0 and 6.0 to maintain acid mantle integrity. South Korean consumers drive volume through multi-step regimen adoption, creating export demand that Western brands license for global distribution.
- Exfoliators:Alpha-hydroxy acid and enzyme-based formulations accelerate cell turnover with active concentrations capped by FDA monograph thresholds for over-the-counter distribution.
- Masks:Sheet mask hydrogels and clay-based treatments deliver concentrated active payloads through occlusive delivery mechanisms, with manufacturing concentrated in Taiwanese and South Korean contract facilities.
Moisturizers hold the largest share; momentum sits with masks as K-beauty export licensing accelerates.
Application:
Premium pricing power clusters around anti-aging and brightening claims, while hydration and acne treatment segments compete on volume through mass-market penetration strategies.
- Anti-Aging:Retinoid and peptide complexes command price premiums through clinical-grade efficacy positioning, with encapsulation technology stabilizing active potency across shelf life. Japanese biotech suppliers dominate ceramide and postbiotic sourcing for prestige formulations targeting professional demographics in urban centers.
- Brightening:Niacinamide and arbutin formulations address pigmentation concerns prevalent in Asia-Pacific consumer bases, with China's NMPA registration requirements reshaping ingredient sourcing protocols for imported products.
- Hydration:Hyaluronic acid and glycerin-based solutions compete on repeat purchase velocity through supermarket and online retail channels.
- Acne Treatment:Salicylic acid and benzoyl peroxide concentrations face FDA monograph restrictions that limit marketing claims and channel placement options.
Anti-aging commands the highest margins; brightening gains share fastest as pigmentation-focused demand expands beyond traditional Asia-Pacific boundaries.
End User:
Women's segments sustain volume foundations, while men's and professional categories unlock incremental pricing power through specialized positioning.
- Women:Multi-step regimen adherence drives category breadth across all product types, with subscription auto-replenishment models capturing predictable repurchase cadence.
- Men:Dissolving stigma around skincare routines unlocks daily-use volume in previously underpenetrated demographics, with pharmacy channel expansion capturing consumers seeking simplified positioning.
- Teens:Acne-focused solutions compete on accessibility through mass retail and social commerce discovery mechanisms.
- Professionals:Clinical-grade ingredient concentrations and diagnostic-linked personalization justify premium pricing for time-constrained urban consumers.
Women's segments anchor volume; men's categories are climbing the fastest as grooming normalization penetrates developed markets.
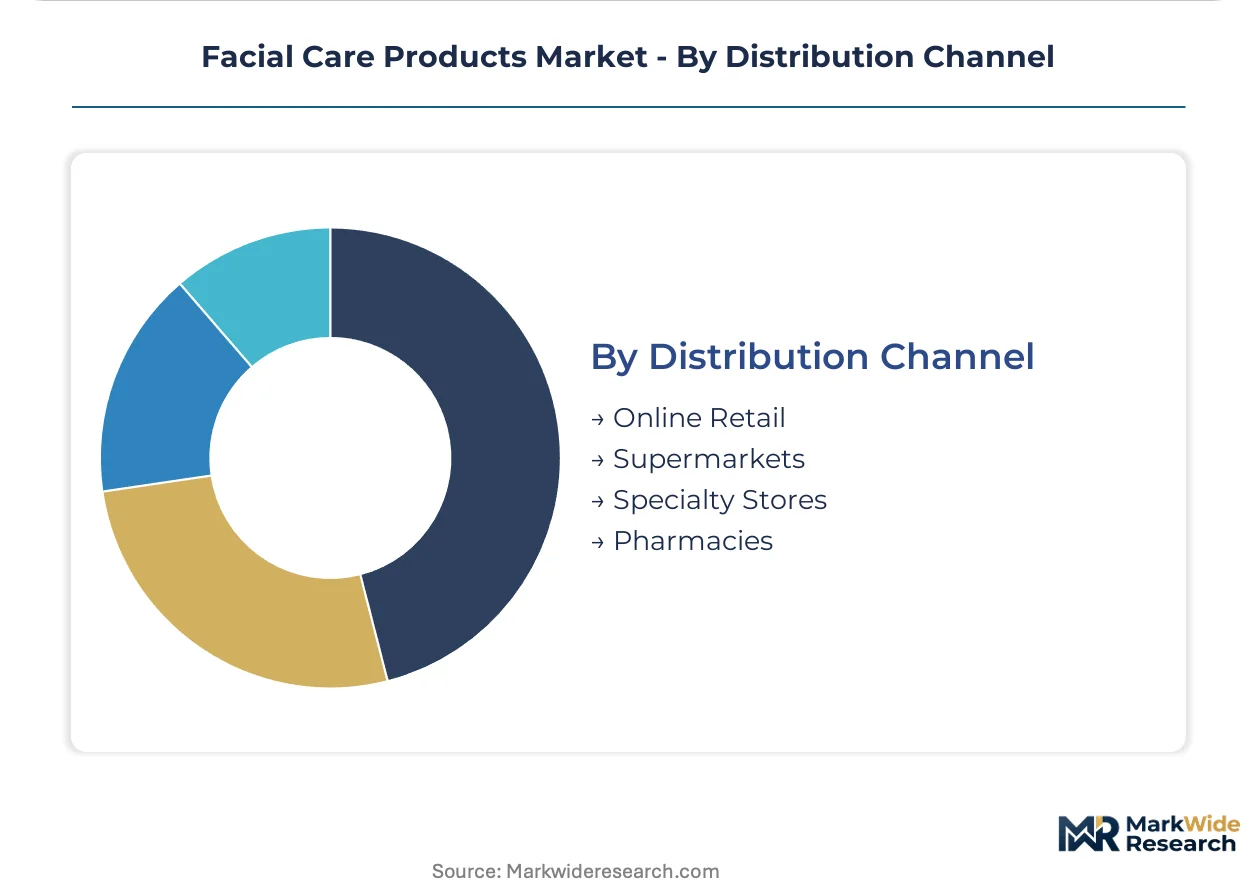
Distribution Channel:
Channel selection determines regulatory compliance burden and consumer education requirements, with pharmacy positioning demanding stricter documentation than mass retail alternatives.
- Online Retail:Direct-to-consumer platforms enable AI-driven skin diagnostic integration with modular product curation, compressing traditional trial-and-repeat purchase cycles.
- Supermarkets:Mass-market moisturizers and cleansers compete on shelf placement and promotional velocity, with unit economics sensitive to agricultural input cost fluctuations affecting plant-derived emulsifiers.
- Specialty Stores:Prestige brand discovery and experiential sampling justify higher price points through service-intensive environments.
- Pharmacies:Dermocosmetic positioning captures consumers seeking prescription-adjacent efficacy, with EU Green Deal compliance requirements elevating qualification barriers for shelf access.
Pharmacies capture the highest value per transaction; online retail is expanding most quickly as subscription infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA monograph oversight on acne treatment claims anchors the United States as the reference market for over-the-counter active concentration thresholds. EU REACH substance restrictions and the Green Deal framework are forcing reformulation across European export destinations. China's NMPA animal-testing alternatives requirement reshapes market access protocols for Western brands.
United States
Pharmacy channel dominance drives dermocosmetic positioning for daily-use moisturizers and cleansers. FDA acne monograph thresholds cap salicylic acid and benzoyl peroxide marketing claims, limiting active ingredient concentrations for mass-market distribution. Greater Boston and New Jersey host contract manufacturing clusters specializing in pH-stabilized emulsion processes for barrier-compatible formulations.
South Korea
Multi-step regimen culture sustains premium facial care consumption through sheet mask and essence product innovation. MFDS cosmetic safety standards require pre-market notification for novel biotech-derived actives, compressing go-to-market timelines for fermentation-based ingredient platforms. Seoul Capital Area contract manufacturers supply hydrogel and biocellulose mask substrates for global K-beauty licensing deals.
Germany
Clean beauty mandates under EU REACH and the Green Deal are eliminating paraben and microplastic additives from legacy formulations. ECHA authorization requirements for novel cosmetic substances extend safety assessment timelines by 18-24 months versus historical benchmarks. North Rhine-Westphalia specialty chemical suppliers are qualifying plant-derived emulsifiers to replace synthetic alternatives in mass-market SKUs.
Japan
Prestige positioning relies on controlled ingredient sourcing from domestic biotech suppliers for ceramide and postbiotic complexes. PMDA quasi-drug classification for brightening and anti-aging claims demands clinical documentation that elevates compliance costs for imported competitors. Osaka-Kobe industrial clusters concentrate fermentation-derived active manufacturing for supply to regional formulation specialists.
China
Pigmentation-focused demand for niacinamide and arbutin formulations accelerates brightening segment growth beyond traditional Asia-Pacific boundaries. NMPA registration requirements for imported cosmetics mandate animal-testing alternatives, forcing Western brands to restructure market access protocols. Yangtze River Delta biotech clusters are scaling fermentation platforms for domestic ceramide and hyaluronic acid production.
Facial Care Products Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in facial care, with scale advantages concentrating in captive R&D and controlled ingredient sourcing. The upper tier commands pharmacy channel access and dermocosmetic positioning through clinical-grade efficacy claims. Three archetypes dominate: multinational conglomerates with captive biotech supply, regional specialists leveraging local fermentation expertise, and direct-to-consumer platforms with AI-driven personalization infrastructure. Competitive moves center on biotech ingredient licensing partnerships and pharmacy channel expansion to capture prescription-adjacent demand.
Within the integrated multinational tier, L'Oréal S.A. and The Procter & Gamble Company exemplify divergent geographic anchoring strategies. L'Oréal leverages Singapore-based R&D centers to offset Western European formulation talent scarcity, while P&G anchors North American mass-market volume through pharmacy distribution dominance. Shiseido Company Limited occupies a position bridging premium Japanese biotech sourcing with regional Asian market access. These three entities represent distinct responses to regulatory fragmentation: EU Green Deal compliance, FDA monograph navigation, and NMPA animal-testing alternatives adaptation.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| The Procter & Gamble Company |
| Unilever PLC |
| The Estée Lauder Companies Inc. |
| Beiersdorf AG |
| Shiseido Company Limited |
| Johnson & Johnson Services, Inc. |
| Coty Inc. |
| Oriflame Cosmetics AG |
| Others |
Supply Flow & Price Mechanics
EU REACH substance restrictions and Green Deal compliance timelines simultaneously gate supplier qualification and stratify price tiers across the facial care market. Brands qualifying alternative chemistries for European market access command premium positioning, while mass-market SKUs face margin compression from agricultural input volatility affecting plant-derived emulsifiers.
Pricing Analysis
Geographic price spreads widen between pharmacy-positioned dermocosmetics and supermarket mass-market tiers, with three-tier pricing structure across premium, standard, and economy levels separating clinical-grade ceramide formulations from basic glycerin-based hydrators. Price differentiation hinges on certification grade—EU Green Deal compliance and FDA monograph adherence—and brand premium anchored in biotech sourcing narratives. Cost compression in standard tiers intensifies because agricultural supply fluctuations destabilize plant-derived preservative economics. Mass-market consumers exhibit highest price sensitivity, while professional segments accept premium positioning for diagnostic-linked personalization.
Supply Chain Analysis
Just-in-time inventory strategies dominate fermentation-derived active sourcing from Japanese and South Korean biotech suppliers, though strategic stockpiling of hydrogel mask substrates from Taiwanese contract manufacturers buffers against seasonal demand spikes. Supply concentrates in South Korea for multi-step regimen products, Japan for ceramide and postbiotic complexes, and Germany for REACH-compliant emulsifier alternatives. Raw material dependencies include biocellulose substrates, fermentation-derived ceramides, and plant-derived surfactants. Single-source vulnerability runs through Seoul Capital Area hydrogel manufacturing. Distribution runs through pharmacy channels for dermocosmetic tiers and direct-to-consumer platforms for subscription replenishment models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
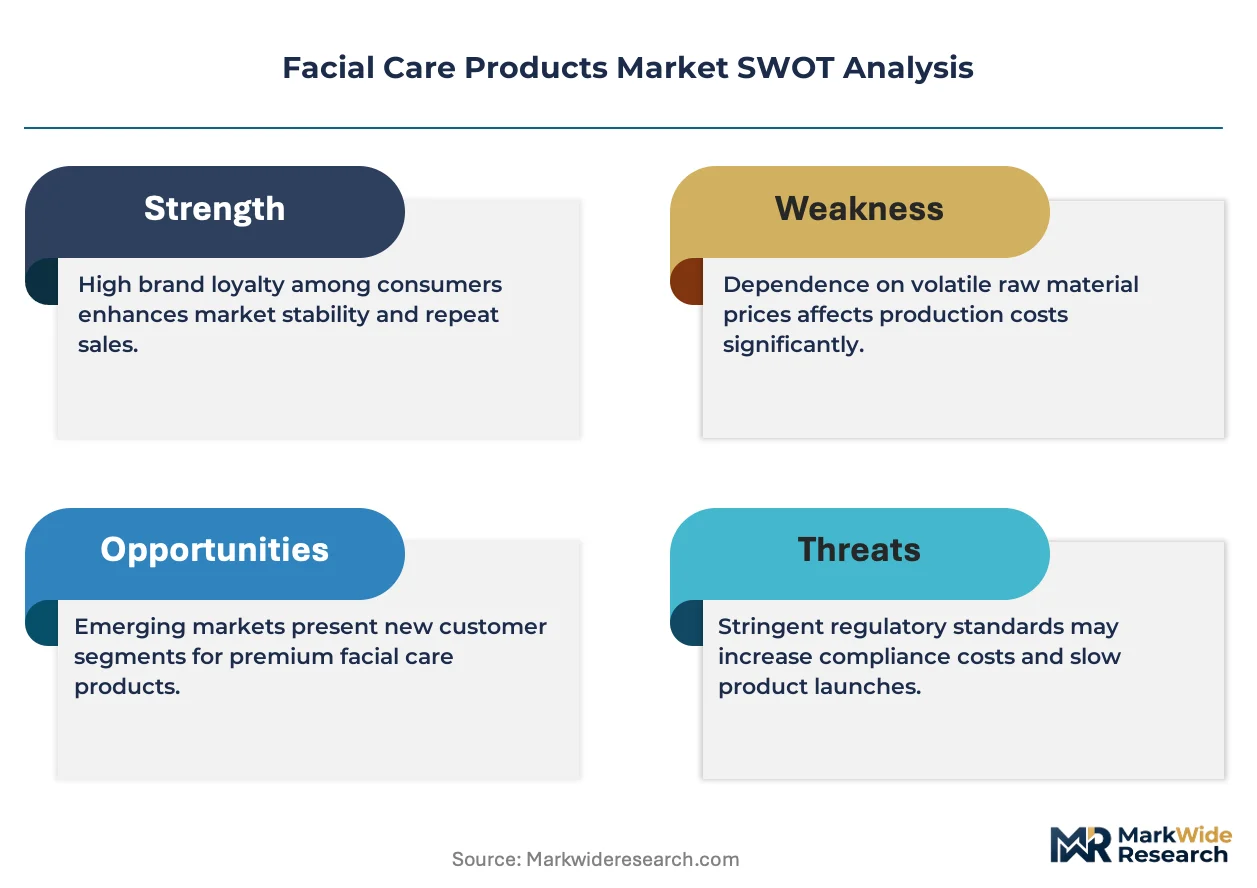
Regulatory entrenchment creates durable defensive moats in facial care, as EU Green Deal compliance and FDA monograph navigation demand specialized formulation expertise that resists rapid competitive replication.
For Market Incumbents: Fortify captive R&D positioning by deepening backward integration into fermentation-derived active production and securing exclusive pharmacy channel access before clean beauty mandates tighten shelf qualification. Threats from direct-to-consumer platforms with AI diagnostic tools demand preemptive personalization infrastructure investment. Capacity addition in Singapore and South Korea offsets Western European talent scarcity. For New Entrants and Emerging Players: Anchor in men's grooming segments where stigma dissolution outpaces incumbent product development cycles, and pharmacy channel expansion in North America where prescription-adjacent positioning remains underexploited. White space concentrates in simplified regimen formats for male demographics and subscription-auto-replenishment models with diagnostic integration. Go-to-market angle should leverage modular base formulations paired with skin diagnostic apps. For Investors and Strategic Acquirers: EU Green Deal substance restriction roadmaps reshape the acquisition landscape by elevating valuation premiums for brands with compliant formulations already in market. Long-term viability favors entities with biotech ingredient licensing pipelines and pharmacy channel relationships. Acquisition target archetype: regional specialists with captive fermentation expertise and established NMPA animal-testing alternatives protocols. Signal to watch is ECHA authorization backlog resolution timelines for novel cosmetic substances.| Strategic Initiative | Industry Significance |
|---|---|
| Biotech Ingredient Licensing | Fermentation-derived ceramide partnerships with Japanese suppliers enable clinical-grade efficacy claims without synthetic actives. |
| Pharmacy Channel Expansion | Dermocosmetic positioning through CVS and Walgreens captures prescription-adjacent demand without dermatologist friction. |
| AI-Driven Personalization Launch | Skin diagnostic tools paired with modular formulations compress trial-and-repeat purchase cycles for subscription retention. |
| Clean Beauty Reformulation | EU Green Deal compliance investments raise qualification barriers that eliminate non-compliant competitors from European shelves. |
| K-Beauty Export Licensing | Multi-step regimen IP from South Korean contract manufacturers generates royalty streams across Western mass-market distribution. |
Methodological Framework
Desk research of regulatory filings, customs trade databases, and retail audit data preceded structured interviews with cosmetic formulation chemists, pharmacy category buyers, biotech supplier account managers, and direct-to-consumer platform operators. Secondary validation drew from ECHA substance restriction updates, FDA monograph guidance documents, MFDS cosmetic safety standards, and NMPA registration protocols. Bottom-up demand modeling triangulated against top-down market sizing across product type, application, end user, and distribution channel dimensions.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects within each segmentation layer. The analytical framework models moisturizers, cleansers, exfoliators, and masks by anti-aging, brightening, hydration, and acne treatment applications, further split by women, men, teens, and professional end users. CAGRs derive from regression against macroeconomic indicators and demographic penetration curves. Industry-specific inputs include K-beauty export licensing velocity and pharmacy channel expansion rates.
Underlying assumptions cover regulatory timeline adherence, agricultural input cost stability, and male grooming normalization trajectories, with deviation risk concentrated in ECHA authorization backlogs and China NMPA protocol shifts. Forecasts reflect these conditions without contingency for abrupt tariff reconfigurations or biotech supply disruptions. Revision becomes warranted when clean beauty compliance cost thresholds cross mass-market margin sustainability limits.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Anti-Aging Cosmetics Market
Beauty & Personal Care
Curling Irons Market
Beauty & Personal Care
Luxury Hair Care Market
Beauty & Personal Care
Personal Care Shower and Bath Market
Beauty & Personal Care
Slimming Cream Market
Beauty & Personal Care
Lip and Cheek Tint Market
Beauty & Personal Care
Deodorant Roll-Ons Market
Beauty & Personal Care
Spain Sustainable Personal Care Market
Beauty & Personal Care
Brazil Beauty and Personal Care Products Market
Beauty & Personal Care
Global Cosmetic Products Market
Beauty & Personal Care
Nail Polish Remover Market
Beauty & Personal Care
Hairstyling Products Market
Beauty & Personal Care
Portable Atomizer Market
Beauty & Personal Care
Germany Beauty Industry Market
Beauty & Personal Care
North America Cosmetics Market
Beauty & Personal Care
Spas and Beauty Salons Market