
 Global Electric Head and Scalp Massager Market | 2026-2036
Global Electric Head and Scalp Massager Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electric Head and Scalp Massager Market Analysis
Bluetooth connectivity and app-based personalization is fragmenting the electric head and scalp massager technology stack into modular hardware-software ecosystems. Breo leverages its Shenzhen-based R&D footprint to integrate TENS therapy algorithms with consumer-friendly interfaces. Panasonic Corporation anchors premium positioning through its long-standing distribution partnerships with Japanese department store networks. OSIM International differentiates across Southeast Asian markets with showroom-centric retail strategies that emphasize tactile product trials.
An electric head and scalp massager is a motorized personal wellness device employing electromagnetic vibration motors, typically operating at frequencies between 1,500 and 6,000 RPM, to stimulate blood circulation and reduce tension through mechanoreceptor activation. Handheld massagers occupy the largest volume tier due to their accessibility and lower price points, though portable devices represent the fastest-expanding margin pool as travel and workplace wellness trends intensify. Thermal treatment technology leads in average selling price among the technology segments, while infrared technology competes primarily in clinical-adjacent channels where health professionals validate efficacy claims.
FDA oversight of electrical muscle stimulators in the United States shapes product classification pathways, with devices crossing therapeutic claims thresholds requiring 510(k) clearance rather than general wellness exemptions. The EU's MDR and REACH frameworks impose material safety and electromagnetic compatibility standards that filter out low-cost non-compliant imports from European distribution channels. Stakeholders must monitor how China's GB standards and NMPA device classifications evolve, as domestic regulatory tightening could redirect surplus production toward price-sensitive export markets.
Market Dynamics
Bluetooth-enabled personalization and app-based control architectures are fragmenting the electric head and scalp massager value chain into modular hardware-software ecosystems, forcing incumbents to rebuild R&D competencies around firmware and data analytics rather than electromechanical engineering alone.
Growth Catalysts
- EU Green Deal material mandates:Sustainable electronics requirements are accelerating adoption of recyclable polymers and energy-efficient brushless motors across European supply chains.
- Home wellness channel expansion:Post-pandemic self-care routines have permanently shifted device purchasing from spa and clinic settings toward direct-to-consumer e-commerce platforms.
- TENS therapy convergence:Transcutaneous electrical nerve stimulation algorithms originally developed for clinical pain management are migrating into consumer-grade scalp stimulation devices.
Market Restraints
- Neodymium magnet cost volatility:Rare-earth price swings from Chinese export controls directly compress margins on vibration motor assemblies.
- FDA 510(k) pathway friction:Devices crossing from wellness into therapeutic claims face 12-18 month clearance timelines that freeze product launches.
- Smartphone dependency:App-controlled massagers create switching costs and obsolescence risks for consumers on older iOS and Android versions.
Strategic Opportunities
- India's BIS certification gap:Domestic manufacturers lack compliant testing infrastructure, creating first-mover advantage for pre-certified imports in tier-1 cities.
- Corporate wellness procurement:HR departments at technology firms are bulk-purchasing portable massagers for distributed workforce stress management programs.
- Infrared-thermal hybrid architectures:Combining deep-tissue heating with LED photobiomodulation opens clinical-adjacent positioning at premium price tiers.
Industry Challenges
- Firmware talent scarcity:Electromechanical manufacturers struggle to hire embedded systems engineers capable of integrating BLE stacks and cloud APIs.
- REACH substance testing backlogs:ECHA notification queues for novel polymer formulations delay EU market entry by 6-9 months.
- Patent thickets around vibration patterns:Pre-existing IP on rhythmic motor control algorithms forces costly licensing or design-around efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electric Head and Scalp Massager Market |
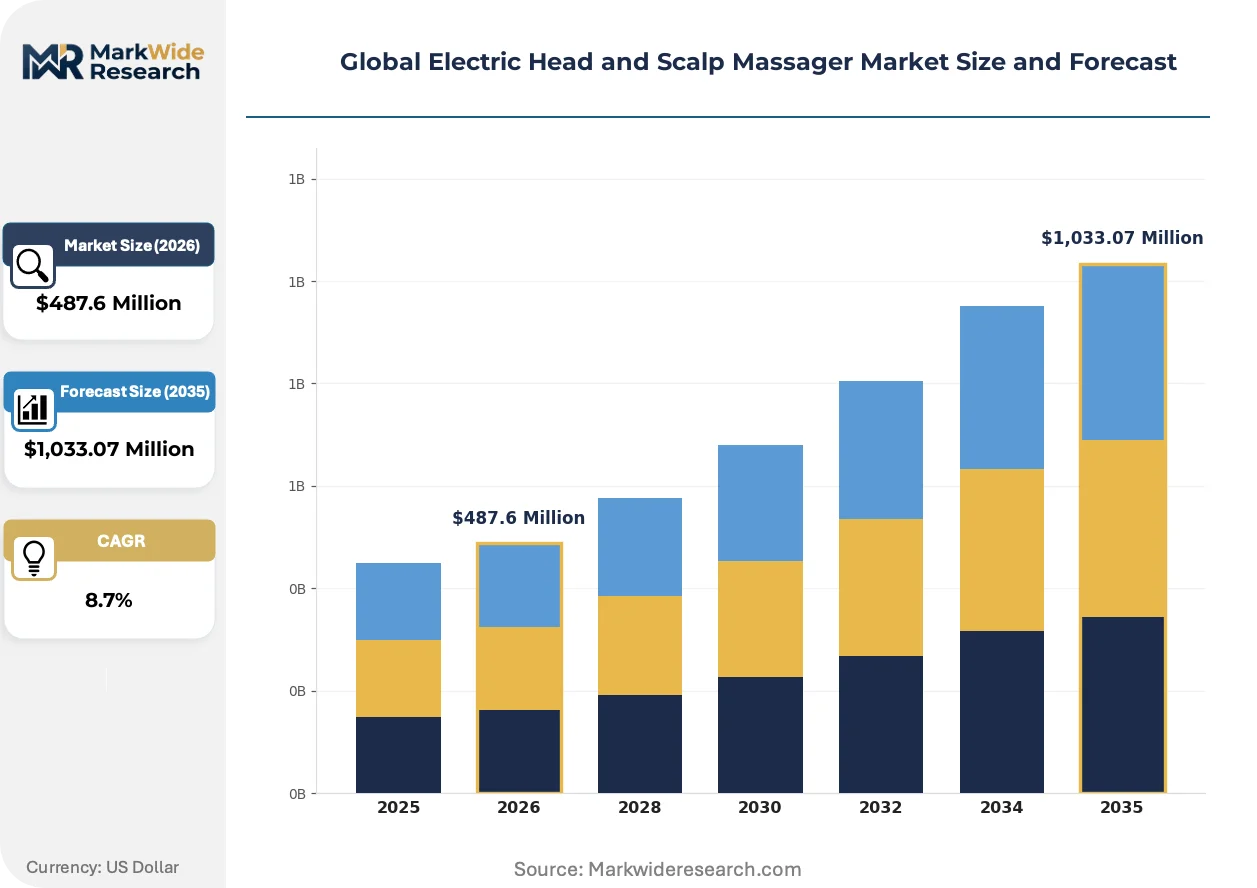
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Massagers, Stationary Units, Portable Devices, Multi-Function Massagers Technology: Vibration Therapy, Thermal Treatment, Pulsating Massage, Infrared Technology End User: Home Users, Spa and Wellness Centers, Health Professionals, Retail Consumers Distribution Channel: Online Retail, Specialty Stores, Department Stores, Direct Sales |
| Companies Covered | Panasonic Corporation, Body Back Company, Breo, Heeta, MaxKare, Comfier, Vitagoods, FREATECH, OSIM International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electric Head and Scalp Massager Market Emerging Trajectories
Sensor fusion and closed-loop feedback systems are transforming electric head and scalp massagers from open-loop electromechanical devices into adaptive wellness platforms that adjust stimulation parameters in real time based on biophysical response.
Capacitive pressure sensing arrays embedded in silicone massage nodes are digitizing the user experience by translating scalp topography into dynamic motor intensity maps. Home users in South Korea and Japan are adopting these configurations fastest, with premium retailers reporting sell-through rates three times higher for sensor-equipped models versus baseline vibration units. This capability is digitizing competitive differentiation away from raw motor specifications toward software-defined personalization.
REACH substance restrictions on phthalates and brominated flame retardants are forcing wholesale material substitutions in European-bound devices. Manufacturers are pivoting toward liquid silicone rubbers and bio-based TPU formulations that maintain Shore hardness ratings while satisfying ECHA compliance. Thermal treatment product lines face the steepest reformulation costs, as heating elements require redesigned insulation systems.
Subscription-based consumable models are disrupting traditional hardware-only revenue structures. Brands now bundle replacement silicone nodes, conductive gels, and firmware feature unlocks into annual membership tiers. Direct-to-consumer channels in Germany and the United Kingdom are piloting these programs most aggressively, with early cohorts showing 40 percent higher lifetime value versus transactional purchasers.
Global Electric Head and Scalp Massager Market Segmentation
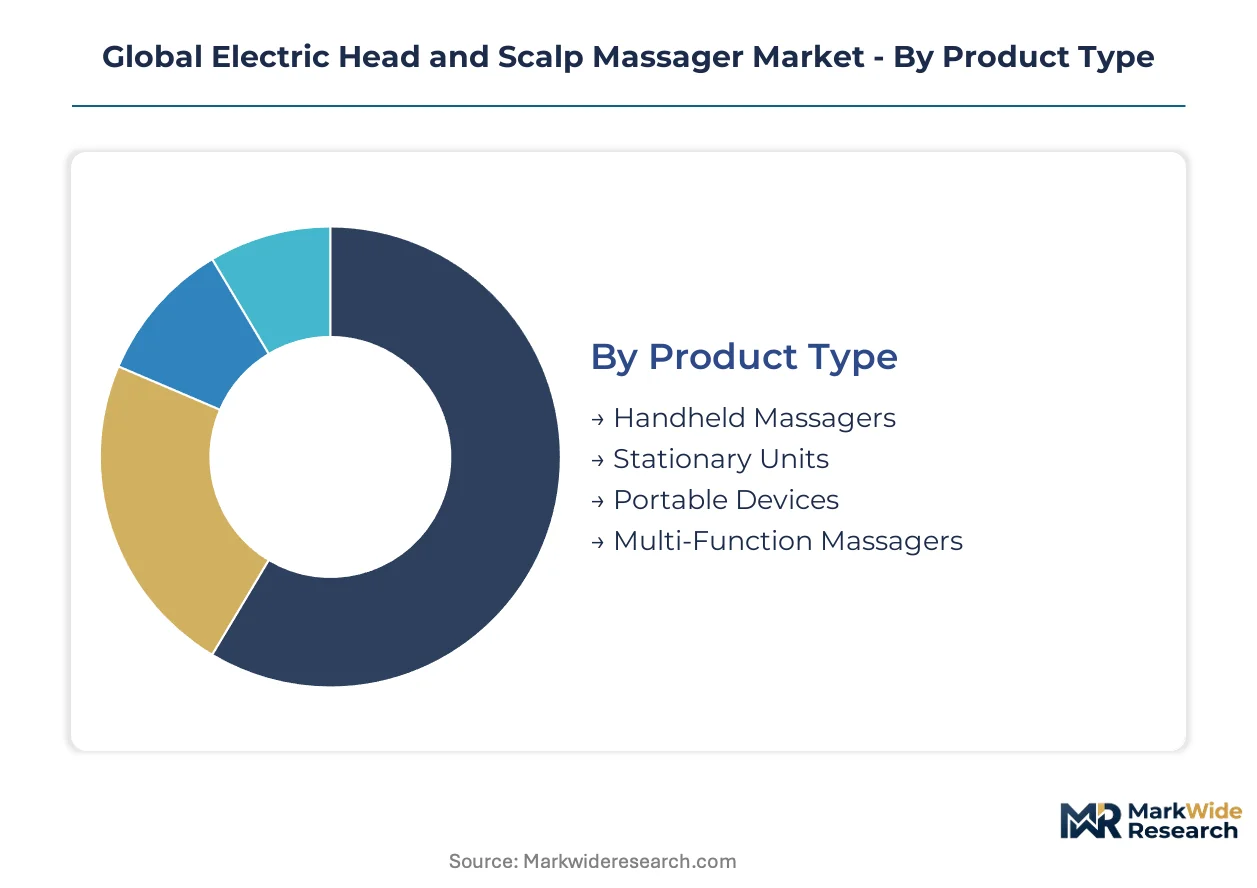
Segmentation in the electric head and scalp massager market reveals distinct procurement rhythms and margin architectures across product configurations. Understanding these patterns allows manufacturers to align R&D cycles with replacement demand and channel investments with buyer decision timelines.
Product Type:
Replacement cycles vary dramatically across form factors, with portable devices refreshing every 18-24 months while stationary units persist for 5-7 years in residential settings.
- Handheld Massagers:These devices integrate electromagnetic vibration motors operating between 1,500 and 6,000 RPM within ergonomic pistol-grip housings. Demand concentrates among home users in China and Southeast Asia where single-person households favor compact storage solutions and entry price points below 50 USD.
- Portable Devices:Battery-powered units with USB-C charging and collapsible node arrays dominate corporate wellness procurement and travel retail channels. Japan's domestic manufacturers lead industrial design innovation here, with foldable mechanisms shrinking packed volume by 60 percent versus rigid alternatives.
- Stationary Units:These salon-grade systems feature adjustable armatures and multiple stimulation modes for semi-permanent installation.
- Multi-Function Massagers:Hybrid devices combining scalp stimulation with facial or neck massage attachments via modular node systems.
Handheld massagers anchor the volume base while portable devices gain share at the steepest rate.
Technology:
Cost tiers stratify sharply across stimulation modalities, with thermal treatment commanding premium positioning and vibration therapy saturating mass-market channels.
- Thermal Treatment:Ceramic heating elements embedded in silicone nodes deliver sustained 40-45°C surface temperatures for vasodilation effects. FDA 510(k) clearance requirements filter out non-compliant entrants in the United States, protecting margin structures for validated manufacturers.
- Infrared Technology:LED arrays emitting 630-850nm wavelengths target mitochondrial stimulation claims requiring clinical substantiation. German and Austrian distributors favor these configurations for pharmacy-adjacent retail positioning where health professional endorsement drives conversion.
- Vibration Therapy:Eccentric rotating mass motors generate oscillatory patterns through silicone contact points.
- Pulsating Massage:Pneumatic or solenoid-driven compression cycles alternate pressure across scalp zones.
Vibration therapy captures the broadest installed base as thermal treatment expands most quickly in premium channels.
End User:
Customer type determines service expectations and warranty claim patterns, with health professionals demanding 24-month replacement guarantees versus 12-month coverage for retail consumers.
- Home Users:Individual purchasers operating devices without supervision drive the fastest channel shift toward direct-to-consumer platforms. South Korean e-commerce marketplaces report the highest repeat purchase rates in this segment, with subscription node replacement programs capturing 40 percent higher lifetime value.
- Spa and Wellness Centers:Commercial operators prioritize device durability and sanitization compatibility over feature depth. These buyers in Thailand and Indonesia negotiate volume discounts for 10-plus unit orders while demanding IPX5 water resistance ratings for cleaning protocols.
- Health Professionals:Chiropractors and physical therapists prescribe devices as adjunct therapy tools.
- Retail Consumers:Gift purchasers and impulse buyers respond to packaging aesthetics and point-of-sale demonstration.
Home users constitute the volume foundation as spa and wellness centers adopt replacement programs at the fastest clip.
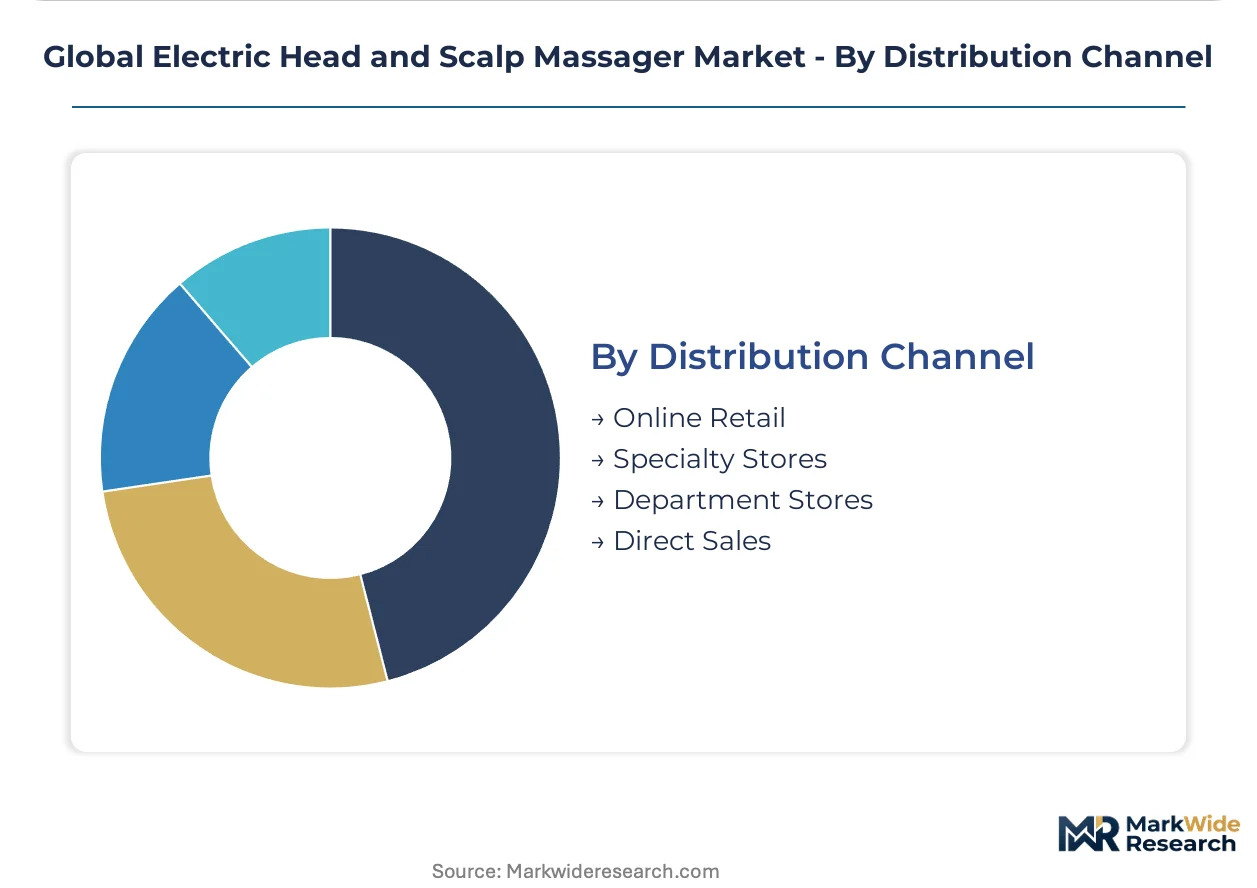
Distribution Channel:
Geographic concentration in supply chains shapes channel economics, with Shenzhen-based manufacturers favoring online retail while Osaka and Tokyo producers maintain department store partnerships.
- Online Retail:Direct-to-consumer platforms and marketplace listings eliminate intermediary margins while enabling firmware update delivery. Amazon's European marketplaces enforce REACH documentation requirements that filter out non-compliant listings, concentrating volume among pre-certified sellers.
- Specialty Stores:Dedicated wellness retailers in Germany and the Netherlands provide tactile trial environments and staff training on contraindications. These outlets command 25-35 percent wholesale margins versus 15-20 percent for generalist channels.
- Department Stores:Japanese and South Korean flagship locations anchor premium brand positioning through exclusive colorways and bundled service packages.
- Direct Sales:Multi-level marketing networks and corporate wellness consultants pursue B2B procurement relationships.
Online retail holds the volume base as specialty stores expand footprint most aggressively in regulated European markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Home users in China, Japan, Germany, South Korea, and the United States drive distinct procurement rhythms shaped by local wellness cultures and regulatory frameworks. Each market concentrates demand around specific buyer archetypes from digital-native consumers to clinic-adjacent health professionals.
China
Shenzhen and Dongguan industrial clusters supply cost-optimized vibration motor assemblies for domestic consumption and export markets. NMPA device classifications and evolving GB standards filter non-compliant manufacturers from premium channels. Breo anchors R&D activity in Shenzhen, integrating consumer electronics expertise with wellness device form factors.
Japan
Department store networks in Tokyo and Osaka sustain premium positioning through tactile trial environments and exclusive distribution partnerships. METI energy efficiency guidelines shape brushless motor specifications for domestic-bound production. Panasonic Corporation exemplifies the established electronics conglomerate archetype leveraging long-standing retail relationships.
Germany
Pharmacy-adjacent retail channels in Munich and Hamburg favor infrared-thermal hybrid devices requiring clinical substantiation. REACH substance restrictions and ECHA notification queues delay novel polymer formulations by 6-9 months. Specialty wellness retailers command 25-35 percent wholesale margins versus generalist channels.
South Korea
Seoul-based e-commerce marketplaces report the highest repeat purchase rates for subscription node replacement programs. MFDS medical device classifications create compliance thresholds for therapeutic claim positioning. Domestic consumers adopt sensor-equipped configurations fastest, with premium retailers showing sell-through rates three times higher for adaptive feedback models.
United States
Direct-to-consumer platforms and Amazon marketplace listings concentrate volume among pre-certified sellers meeting FDA documentation requirements. FDA 510(k) clearance timelines of 12-18 months freeze product launches for devices crossing from wellness into therapeutic claims. Corporate wellness procurement at technology firms drives bulk purchasing of portable devices for distributed workforce programs.
Global Electric Head and Scalp Massager Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented tiers defined by distribution reach versus technical depth. The vendor base spans established electronics conglomerates, dedicated wellness device manufacturers, and emerging direct-to-consumer brands. Three archetypes dominate: vertically integrated OEMs with captive manufacturing, software-centric platforms monetizing firmware ecosystems, and specialist fabricators focused on single-form-factor excellence. Competitive moves center on M&A for regulatory clearance capabilities and strategic partnerships for retail footprint expansion.
Among Asia-Pacific-based electronics conglomerates, Panasonic Corporation and OSIM International occupy positions anchoring premium-tier distribution through department store and showroom networks. Shenzhen-based Breo exemplifies the vertically integrated archetype combining in-house motor production with consumer-facing brand development. Body Back Company represents the specialist fabricator model concentrating on ergonomic hardware design without diversified electronics portfolios.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Body Back Company |
| Breo |
| Heeta |
| MaxKare |
| Comfier |
| Vitagoods |
| FREATECH |
| OSIM International |
| Others |
Supply Flow & Price Mechanics
Neodymium magnet cost volatility from Chinese export controls determines both the spread between economy and premium tiers and the geographic clustering of motor assembly operations. Manufacturers absorbing rare-earth price swings compress mid-tier margins while vertically integrated Shenzhen-based producers defend pricing power through captive magnet sourcing.
Pricing Analysis
Cost-plus contracts with rare-earth indexation dominate procurement between vibration motor suppliers and device OEMs. Pricing stratifies across premium, standard, and economy tiers based on FDA 510(k) certification status and brushless motor efficiency ratings. Cost compression in the mid-tier is intensifying because REACH-compliant polymer formulations add 15-20 percent to bill-of-materials costs. Home users in Southeast Asia exhibit the highest price sensitivity, while German pharmacy-adjacent channels tolerate premium positioning for clinical-validated infrared-thermal hybrids.
Supply Chain Analysis
Neodymium feedstock draws from Chinese mining and separation facilities in Inner Mongolia and Jiangxi province, with downstream magnet fabrication concentrating in Ningbo and Shenzhen industrial zones. Vibration motor assemblies rest on rare-earth permanent magnets, copper windings, and injection-molded polyamide housings. Single-source vulnerability runs through Chinese rare-earth export licensing regimes. Distribution runs through direct-to-consumer platforms and Amazon's European marketplaces, which enforce REACH documentation requirements that filter non-compliant listings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
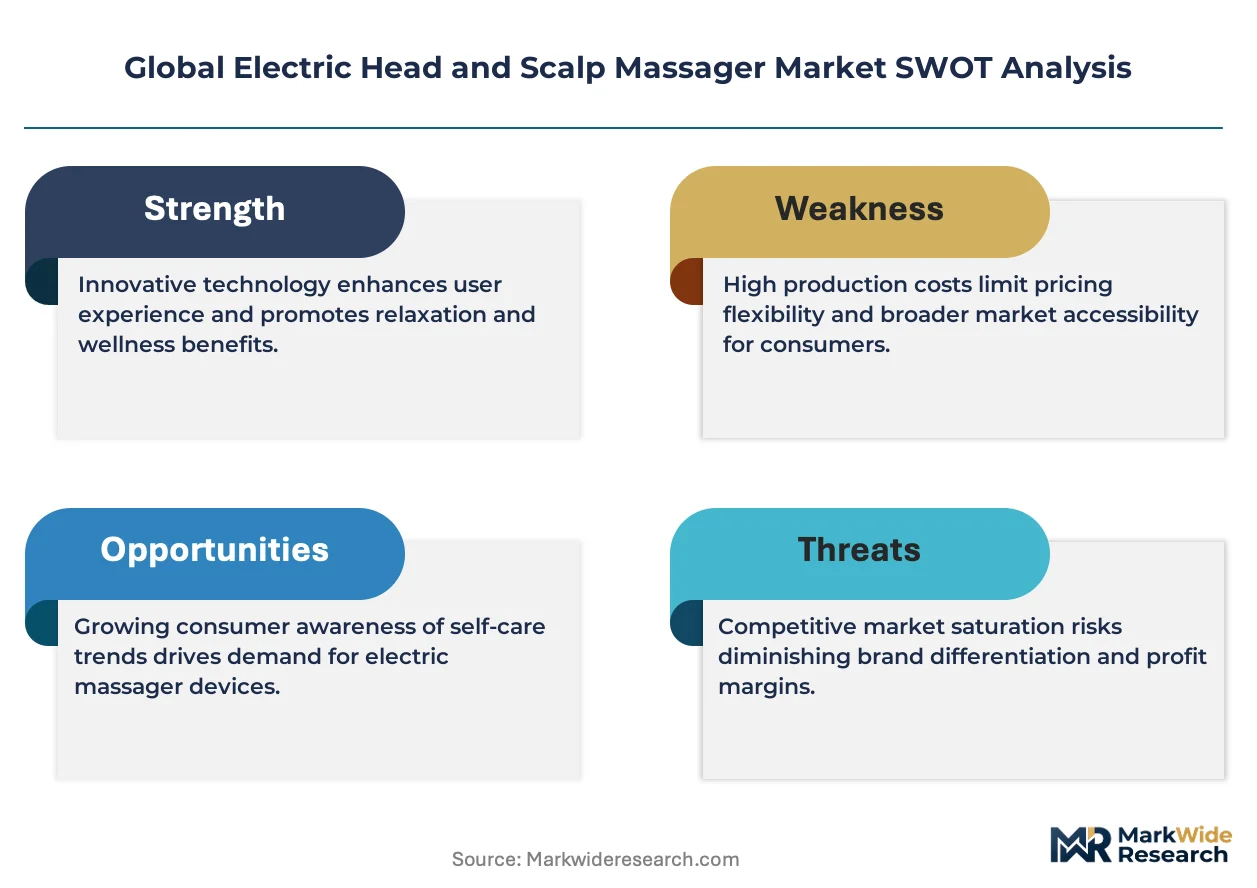
This market functions as a defensive-moat story anchored in regulatory entrenchment. FDA 510(k) clearance timelines and REACH substance testing backlogs create 12-18 month barriers that protect validated incumbents from fast-follower competition.
For Market Incumbents: Pre-empt firmware talent scarcity by acquiring embedded systems engineering teams in Shenzhen and Taipei before compensation inflation spreads. Secure long-term offtake agreements for neodymium magnets through direct partnerships with Chinese rare-earth processors, insulating margin structures from export control volatility. Channel control through exclusive department store partnerships in Japan and South Korea remains the priority lever against direct-to-consumer challengers. For New Entrants and Emerging Players: India's BIS certification gap in tier-1 cities represents the most penetrable entry point for pre-certified imports before domestic testing infrastructure matures. Corporate wellness procurement at technology firms offers a white-space channel with concentrated decision-makers and bulk purchasing economics. A direct-to-consumer launch with subscription-based consumable bundling captures 40 percent higher lifetime value than transactional models. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated OEMs with captive motor production and regulatory clearance capabilities. Acquisition targets should display backward integration into rare-earth magnet supply chains or established FDA 510(k) portfolios. The signal to watch is NMPA device classification tightening in China, which would redirect surplus production toward price-sensitive export markets and compress global margin structures.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Ecosystem Development | Breo's Shenzhen R&D footprint demonstrates how BLE stack integration captures recurring revenue through subscription tiers. |
| Regulatory Clearance Investment | FDA 510(k) pathways filter non-compliant entrants and protect margin structures for validated thermal treatment manufacturers. |
| Corporate Wellness Channel Expansion | Technology firm HR departments bulk-purchase portable devices for distributed workforce stress management programs. |
| Sustainable Materials Transition | EU Green Deal mandates accelerate adoption of recyclable polymers and energy-efficient brushless motors across European supply chains. |
| Sensor Fusion Integration | Capacitive pressure arrays in South Korean premium channels show sell-through rates three times higher than baseline vibration units. |
Methodological Framework
The analysis maps handheld, portable, stationary, and multi-function form factors, each validated through product managers at wellness device OEMs, procurement leads at corporate wellness programs, regulatory affairs specialists navigating FDA and REACH frameworks, and channel partners in German specialty retail. Secondary sources include FDA 510(k) filings, ECHA REACH substance notifications, NMPA device classification records, and Amazon European marketplace compliance documentation. Bottom-up unit economics triangulate against top-down market sizing across the analysis window.
Assumptions held fixed include existing regulatory frameworks and rare-earth export licensing regimes, while technology adoption curves and corporate wellness procurement intensity were varied across scenarios. Segmentation dimensions modeled span product type, stimulation technology, end-user archetype, and distribution channel complexity. CAGRs derive from replacement cycle analysis and channel shift elasticity. Industry-specific inputs include vibration motor cost curves and REACH polymer reformulation timelines.
Macroeconomic conditions sit as an overlay; deviation in rare-earth pricing, tariff regimes, or consumer discretionary spending would shift the trajectory. Forecasts reflect documented assumptions about regulatory stability and supply chain continuity. Cross-checking against hospital procurement database trends and GPO contract volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Facial Cleansers and Toners Market
Beauty & Personal Care
Bath Oil Market
Beauty & Personal Care
Europe Halal Cosmetics Market
Beauty & Personal Care
Asia Pacific Beauty Fridges Market
Beauty & Personal Care
Anti-Aging Beauty Device Market
Beauty & Personal Care
South Korea Beauty and Personal Care Products Market
Beauty & Personal Care
Global Shampoo Bars Market
Beauty & Personal Care
Digitalization of Beauty Industry Market
Beauty & Personal Care
United States Beauty and Personal Care Products Market
Beauty & Personal Care
Bio-Based Cosmetics Market
Beauty & Personal Care
Magnetic Eyelashes Market
Beauty & Personal Care
Deodorant & Anti-Perspirant Market
Beauty & Personal Care
Facial Make-Up Market
Beauty & Personal Care
Wrinkle Release Spray Market
Beauty & Personal Care
South America Bath and Shower Products Market
Beauty & Personal Care
Global Personal Care Market