
 Cosmetics and Personal Care Stores Market | 2026-2036
Cosmetics and Personal Care Stores Market Size, Share, and Industry Trends Forecast 2026-2036
Cosmetics and Personal Care Stores Market Analysis
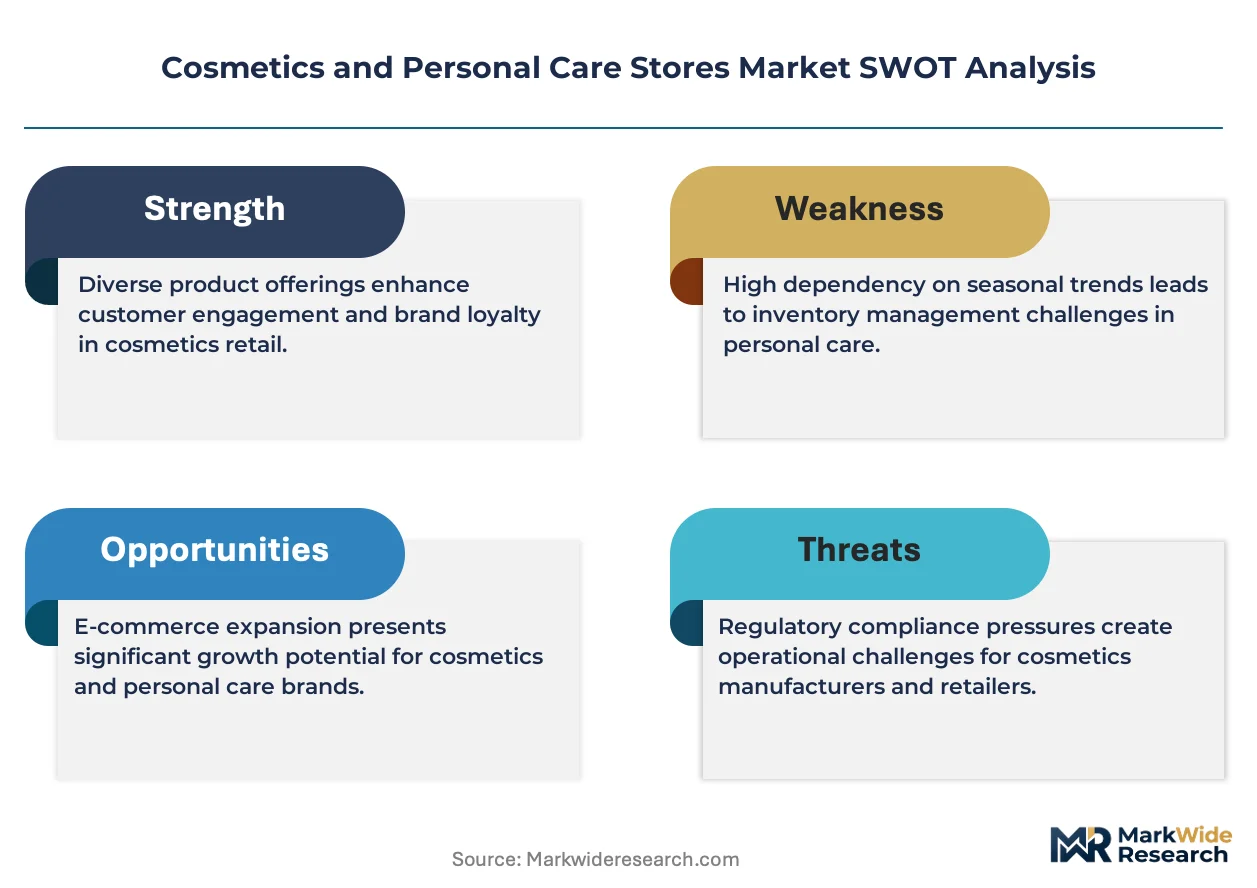
EU REACH compliance is broadening the cost-of-entry calculus for new market participants, forcing reformulation investments before shelf placement. Sephora USA Inc leverages its North American store network to sustain premium brand access. DM Drogerie Markt GmbH anchors Central European mass-market penetration through private-label strength. Douglas GmbH competes on fragrance exclusivity across Continental Europe.
Cosmetics and personal care stores are specialized retail establishments carrying topical formulations with defined pH ranges, preservative systems, and dermatological testing protocols, serving consumers seeking curated beauty and hygiene solutions. Skincare commands the largest margin pool as consumers prioritize barrier-function science over color cosmetics. Haircare occupies a mature volume position with replenishment-driven purchasing. Specialty shops within the distribution channel dimension capture the highest basket values through consultation-based selling.
FDA oversees cosmetic safety labeling in the United States, while EMA-aligned frameworks govern dermatological claims across Europe, and China's NMPA mandates animal-testing alternatives for imported products. These regulatory layers shape inventory composition, supplier qualification timelines, and cross-border e-commerce feasibility. Stakeholders must monitor evolving ingredient blacklists and green-claim substantiation rules to preserve market access.
Market Dynamics
Experiential retail formats in China's tier-one cities are compressing traditional transaction-based selling into consultation-driven discovery environments, forcing inventory and staffing models to pivot toward service intensity over product velocity.
Growth Catalysts
- EU Cosmetics Regulation disclosure mandates:Ingredient transparency requirements are accelerating reformulation investments that premiumize shelf positioning and justify margin expansion through certified clean-label claims.
- Young urban professionals in Asia-Pacific:Digital-first discovery behaviors through social commerce platforms are collapsing traditional advertising funnels and shortening path-to-purchase cycles for skincare categories.
- Animal-testing alternatives under China's NMPA:Regulatory acceptance of non-animal safety assessments is unlocking cross-border e-commerce feasibility for European heritage brands previously blocked from direct market entry.
Market Restraints
- EU REACH compliance cost structure:Broadened chemical safety documentation requirements are elevating cost-of-entry for new market participants before any revenue-generating shelf placement occurs.
- Preservative system concentration:Supply of compliant broad-spectrum preservation technologies remains concentrated among specialty chemical suppliers in Germany and Switzerland, creating input vulnerability.
- Fragrance allergen technical limitations:Current dermatological testing protocols cannot reliably predict individual sensitization responses, constraining claim substantiation for hypoallergenic positioning.
Strategic Opportunities
- Experiential retail in China's tier-one cities:Flagship formats combining skin diagnostics with personalized formulation are capturing basket values multiples above standard retail through consultation-based selling.
- Barrier-function science convergence:Microbiome research intersecting with ceramide delivery systems is creating white-space positioning between dermatological and cosmetic classifications.
- India's PLI scheme for manufacturing:Production-linked incentives for domestic formulation facilities are enabling regional supply hub strategies for South Asian market penetration.
Industry Challenges
- Formulation chemist talent scarcity:Specialized expertise in preservative-free stability engineering commands premium compensation and extends recruitment timelines for NMPA-bound product pipelines.
- Green-claim substantiation timelines:Certification bodies lack standardized methodologies for carbon-footprint labeling, delaying product launches and complicating marketing calendars.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cosmetics and Personal Care Stores Market |
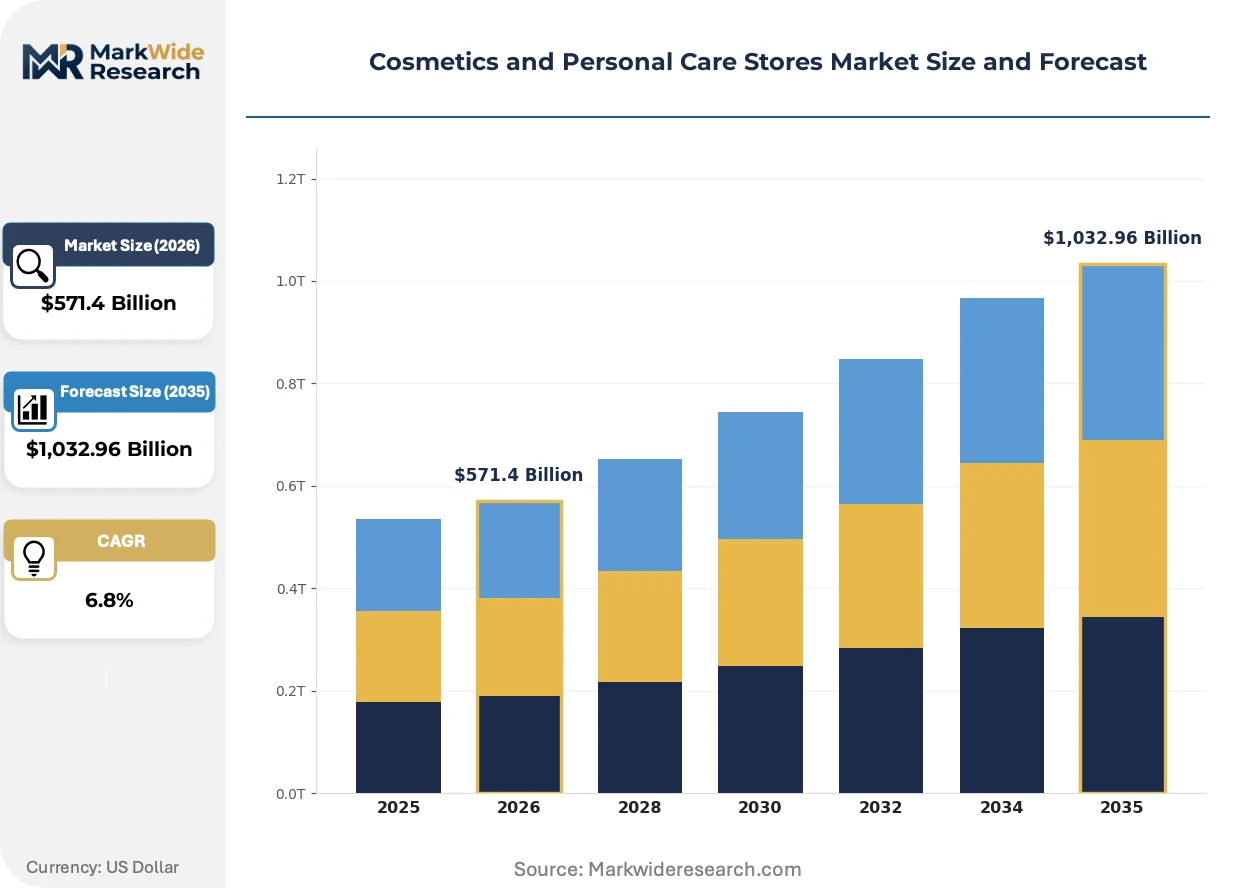
| Market Size in 2026 | $571.4 Billion |
| Market Size in 2035 | $1,032.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Makeup, Skincare, Haircare, Fragrances Customer Type: Individuals, Salons, Retail Chains, E-commerce Distribution Channel: Online, Department Stores, Specialty Shops, Drugstores Brand Positioning: Luxury, Mass, Niche, Eco-friendly |
| Companies Covered | A S Watson Group, Superdrug Stores plc, Ulta Beauty Inc, Rossmann GmbH, DM Drogerie Markt GmbH, Sephora USA Inc, Boots UK Limited, Marionnaud Parfumeries, Douglas GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cosmetics and Personal Care Stores Market Emerging Trajectories
Artificial intelligence is penetrating the discovery layer of beauty retail, compressing the gap between consumer biometric data and personalized product matching while reshaping inventory allocation logic.
Skin analysis hardware integrating spectroscopy with machine learning is automating the consultation workflow previously dependent on trained beauty advisors. Department store beauty halls in Seoul and Tokyo are deploying these systems at scale, reducing staff-to-customer ratios while maintaining conversion rates through algorithmic matching precision.
REACH authorization requirements for microplastic-containing rinse-off cosmetics are forcing reformulation roadmaps across European manufacturing facilities. The restriction timeline is compressing supplier qualification windows and elevating natural polymer sourcing costs, with haircare categories facing the steepest compliance burden due to conditioning agent dependencies.
Subscription-based replenishment models are displacing episodic retail purchasing for core skincare routines. Direct-to-consumer channels in the United States and United Kingdom are capturing recurring revenue streams through algorithmic refill timing, while traditional retailers respond with loyalty-program tiering that mimics subscription convenience without ownership transfer.
Cosmetics and Personal Care Stores Market Segmentation
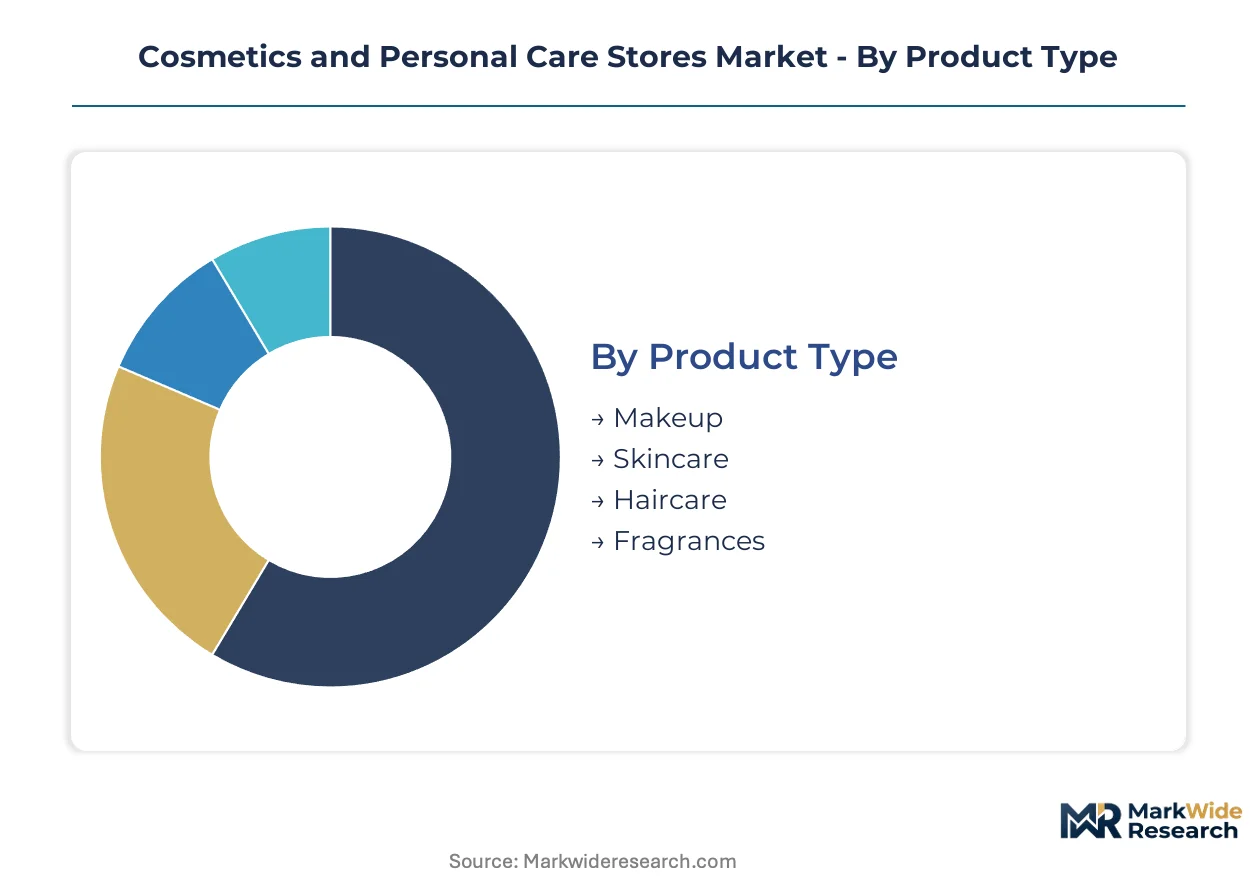
Cosmetics and personal care stores segment across formulation science, procurement behavior, and retail format. These axes determine margin architecture, inventory velocity, and regulatory exposure for channel participants.
Product Type:
Formulation complexity and dermatological testing intensity define the technical hierarchy across topical categories.
- Skincare:Barrier-function formulations with defined pH ranges and ceramide delivery systems command the largest margin pool. Demand concentrates in China's tier-one cities where experiential retail formats drive consultation-based purchasing for personalized regimens.
- Haircare:Replenishment-driven categories with mature volume positioning face steep compliance burdens from REACH microplastic restrictions on conditioning agents. Procurement patterns favor natural polymer sourcing from German and Swiss specialty chemical suppliers.
- Makeup:Color cosmetics with preservative system requirements serve episodic purchase occasions through digital-first discovery channels.
- Fragrances:Exclusivity-driven positioning across Continental Europe relies on allergen disclosure mandates that constrain hypoallergenic claim substantiation.
Mature deployment sits with Haircare. Newer deployment is concentrated in Skincare.
Customer Type:
Procurement scale and decision-making authority reshape service intensity and pricing architecture.
- Individuals:Direct consumers seeking curated beauty solutions drive basket value through personalized consultation. Digital-first discovery behaviors among young urban professionals in Asia-Pacific compress path-to-purchase cycles for premium formulations.
- Retail Chains:Multi-door operators with centralized procurement negotiate exclusive distribution rights and volume-tiered terms. Sephora USA Inc leverages its North American store network to sustain premium brand access through controlled shelf placement.
- E-commerce:Algorithmic matching platforms capture recurring revenue through subscription-based replenishment models displacing episodic retail purchasing.
- Salons:Professional service providers with licensed aesthetician requirements source bulk formulations with institutional pricing.
Volume concentration favors Retail Chains. Margin expansion is climbing the fastest with Individuals.
Distribution Channel:
Physical versus digital format determines inventory allocation logic and staff-to-customer ratios.
- Specialty Shops:Consultation-driven environments with skin diagnostic hardware capture basket values multiples above standard retail. DM Drogerie Markt GmbH anchors Central European mass-market penetration through private-label strength in this format.
- Online:Direct-to-consumer channels with algorithmic refill timing capture recurring revenue streams through loyalty-program tiering that mimics subscription convenience.
- Department Stores:Beauty halls in Seoul and Tokyo deploy spectroscopy-integrated machine learning systems to reduce staff ratios while maintaining conversion precision.
- Drugstores:Mass-market accessibility points with high-velocity replenishment cycles serve barrier-function basics and hygiene essentials.
Established infrastructure sits with Department Stores. Investment flows are concentrating in Specialty Shops.
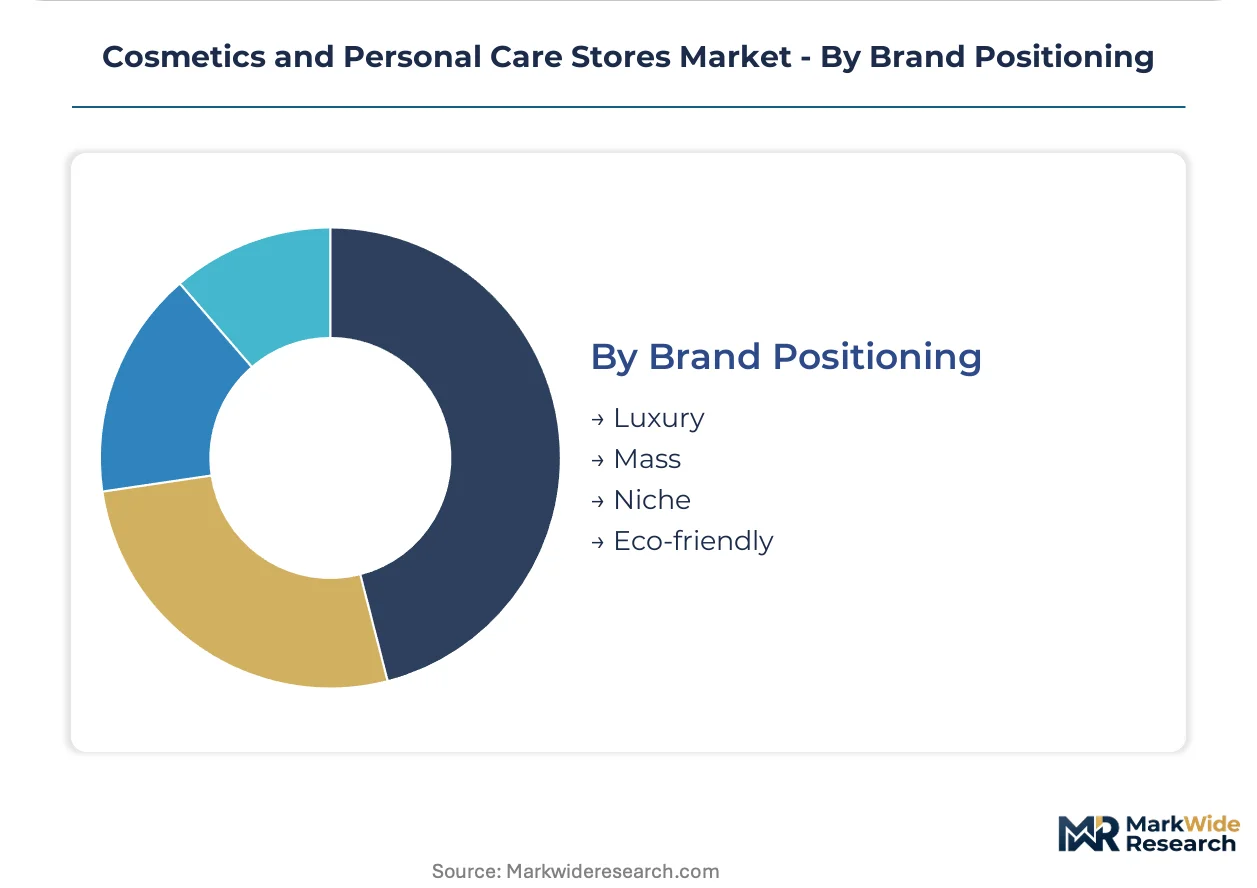
Brand Positioning:
Certification requirements and claim substantiation protocols segment the competitive landscape.
- Luxury:Heritage European brands with fragrance exclusivity positioning leverage NMPA animal-testing alternatives to unlock direct China market entry previously blocked by regulatory barriers.
- Eco-friendly:Clean-label claims with carbon-footprint certification face delayed launches due to non-standardized green-claim substantiation methodologies from third-party bodies.
- Mass:Volume-tiered pricing with private-label strength serves replenishment-driven categories through drugstore and hypermarket placement.
- Niche:Microbiome research intersecting with dermatological classifications creates white-space positioning between cosmetic and pharmaceutical regulatory frameworks.
Regulatory compliance investment sits with Luxury. Reformulation urgency is expanding most quickly with Eco-friendly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Hainan Free Trade Port tax-incentive zone is accelerating duty-free cosmetics retail concentration, while India's Production Linked Incentive scheme for manufacturing reshapes regional supply hub strategies across South Asia.
China
Young urban professionals in Shanghai and Beijing drive digital-first discovery through social commerce platforms, collapsing traditional advertising funnels for skincare categories. NMPA mandates on animal-testing alternatives unlock direct market entry for European heritage brands previously blocked from cross-border e-commerce. Experiential retail formats in tier-one cities deploy skin diagnostic hardware to capture basket values multiples above standard retail.
United States
Subscription-based replenishment models displace episodic retail purchasing for core skincare routines through algorithmic refill timing. FDA oversight of cosmetic safety labeling shapes inventory composition and supplier qualification timelines. Specialty retailers leverage North American store networks to sustain premium brand access through controlled shelf placement.
Germany
REACH authorization requirements for microplastic-containing rinse-off cosmetics force reformulation roadmaps across manufacturing facilities. ECHA-aligned frameworks govern dermatological claims and ingredient disclosure mandates. Central European mass-market penetration anchors through private-label strength in drugstore formats.
France
Fragrance exclusivity positioning relies on allergen disclosure mandates that constrain hypoallergenic claim substantiation. ANSM regulates cosmetic product safety alongside EU Cosmetics Regulation compliance. Heritage brand concentration in Parisian beauty halls sustains premium positioning through consultation-driven discovery environments.
India
Production-linked incentives for domestic formulation facilities enable regional supply hub strategies for South Asian market penetration. CDSCO regulates cosmetic imports with evolving ingredient blacklist monitoring. Maharashtra and Gujarat industrial corridors concentrate contract manufacturing capacity for barrier-function science convergence products.
Cosmetics and Personal Care Stores Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base spans mass-market drugstore operators, premium specialty retailers, and digital-native direct-to-consumer platforms. Three strategic archetypes dominate: private-label mass-market anchors, experiential premium flagships, and algorithmic subscription services. Competitive moves concentrate on exclusive distribution rights negotiation and cross-border e-commerce platform development.
Among European heritage retailers, Douglas GmbH and Marionnaud Parfumeries exemplify fragrance exclusivity positioning across Continental Europe. DM Drogerie Markt GmbH represents private-label strength anchoring Central European mass-market penetration. Sephora USA Inc occupies a position leveraging North American store density for premium brand access.
| Leading Market Players |
|---|
| A S Watson Group |
| Superdrug Stores plc |
| Ulta Beauty Inc |
| Rossmann GmbH |
| DM Drogerie Markt GmbH |
| Sephora USA Inc |
| Boots UK Limited |
| Marionnaud Parfumeries |
| Douglas GmbH |
| Others |
Supply Flow & Price Mechanics
Young urban professionals in Asia-Pacific concentrate purchasing power for premium skincare, anchoring a subscription-replenishment pricing model that rewards recurring commitment with algorithmic refill discounts over episodic retail purchasing.
Pricing Analysis
Short lead-time premiums attach to experiential retail formats in China's tier-one cities, where same-day skin diagnostic consultations command full margin while standard shelf inventory moves at contracted wholesale rates. Three-tier pricing structure across premium consultation-based, standard retail, and economy drugstore levels differentiates by service intensity and personalization depth. Cost compression in mass-market haircare intensifies as REACH microplastic restrictions force natural polymer sourcing from German and Swiss specialty suppliers. Individual direct consumers show highest price sensitivity for replenishment basics, while salon professional buyers absorb premium pricing for bulk institutional formulations.
Supply Chain Analysis
Formulation chemist scarcity in Maharashtra and Gujarat industrial corridors constrains production scaling for NMPA-bound product pipelines destined for China market entry. Manufacturing concentrates in Germany, Switzerland, and India, with preservative system inputs drawing from specialty chemical suppliers in the Rhine-Ruhr and Basel regions. Broad-spectrum preservation technologies, ceramide delivery systems, and natural polymer alternatives for conditioning agents constitute critical input dependencies. Single-source vulnerability sits with compliant broad-spectrum preservation technologies concentrated among German and Swiss suppliers. Distribution runs through specialty shop flagships in Shanghai and Beijing, North American subscription platforms, and Central European drugstore networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Machine learning-integrated skin diagnostic hardware is displacing trained beauty advisor workflows, compressing the technology transition window for retailers dependent on consultation-based selling.
For Market Incumbents: Cement exclusive distribution rights for heritage European fragrance brands before NMPA animal-testing alternatives fully normalize direct China entry for competitors. Deepen backward integration into preservative-free stability engineering capabilities to offset formulation chemist talent scarcity. Prioritize certification investment for carbon-footprint labeling ahead of standardized green-claim substantiation methodologies. For New Entrants and Emerging Players: India's tier-two cities present an underserved buyer archetype with production-linked incentive-enabled local manufacturing cost advantages and minimal incumbent specialty shop penetration. Target barrier-function science convergence products occupying white-space between dermatological and cosmetic regulatory classifications. Pursue direct-to-consumer algorithmic matching platforms with subscription-based replenishment timing as the primary go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors vertically integrated mid-cap specialists with captive preservative system sourcing and NMPA-compliant testing infrastructure. Long-term viability centers on acquisition targets controlling microbiome research pipelines and ceramide delivery system IP. Watch for ECHA microplastic restriction enforcement acceleration as the inflection indicator for natural polymer input cost restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Experiential Retail Flagship Expansion | Skin diagnostic hardware deployment in Shanghai and Beijing captures basket value multiples above standard retail. |
| Preservative-Free Stability R&D Investment | Specialized formulation expertise commands premium compensation and extends recruitment timelines for NMPA pipelines. |
| Direct-to-Consumer Subscription Launch | Algorithmic refill timing in the United States and United Kingdom displaces episodic retail purchasing for core routines. |
| Carbon-Footprint Certification Program | Clean-label claims face delayed launches due to non-standardized green-claim substantiation from third-party bodies. |
| Regional Manufacturing Hub Establishment | India's PLI scheme for domestic formulation facilities enables South Asian supply hub strategies with CDSCO compliance. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across brand managers, category buyers at specialty retailers, channel sales heads, and supply planners. EMA submissions, NMPA registration databases, FDA cosmetic safety filings, and EU Cosmetics Regulation disclosure logs provided segmentation validation. Bottom-up SKU-level modeling and top-down category spend analysis enabled triangulation across the analysis window.
Data-stream reconciliation integrated shipment volumes, retail audit data, and e-commerce transaction patterns across product type, customer archetype, distribution format, and brand positioning dimensions. CAGRs derived from regression-based trend extrapolation with regulatory timeline adjustments. Forecast inputs included NMPA animal-testing alternative adoption curves, REACH microplastic restriction phase-in schedules, and PLI scheme capacity buildout trajectories.
Revisions become necessary when ECHA enforcement timelines accelerate, NMPA registration backlogs extend, or green-claim certification methodologies standardize ahead of projected adoption. Forecasts reflect documented assumptions on regulatory compliance cost pass-through rates and consumer willingness-to-pay for consultation-based service premiums. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Luxury Hair Care Market
Beauty & Personal Care
Makeup Brushes Market
Beauty & Personal Care
Beauty Tools Market
Beauty & Personal Care
Oil Control Shampoo Market
Beauty & Personal Care
India Herbal Shampoo Market
Beauty & Personal Care
DIY Eyelash Extension Market
Beauty & Personal Care
At-Home Beauty Devices Market
Beauty & Personal Care
Hair Wig Market
Beauty & Personal Care
Online Cosmetics Market
Beauty & Personal Care
North America Cosmetics Market
Beauty & Personal Care
Color Cosmetics Market
Beauty & Personal Care
United Kingdom Dermocosmetics Market
Beauty & Personal Care
Lip and Cheek Tint Market
Beauty & Personal Care
North America Lip Care Products Market
Beauty & Personal Care
Elastomer Gel in Personal Care Market
Beauty & Personal Care
Facial Rollers Market