
 Beard Oil Market | 2026-2036
Beard Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Beard Oil Market Analysis
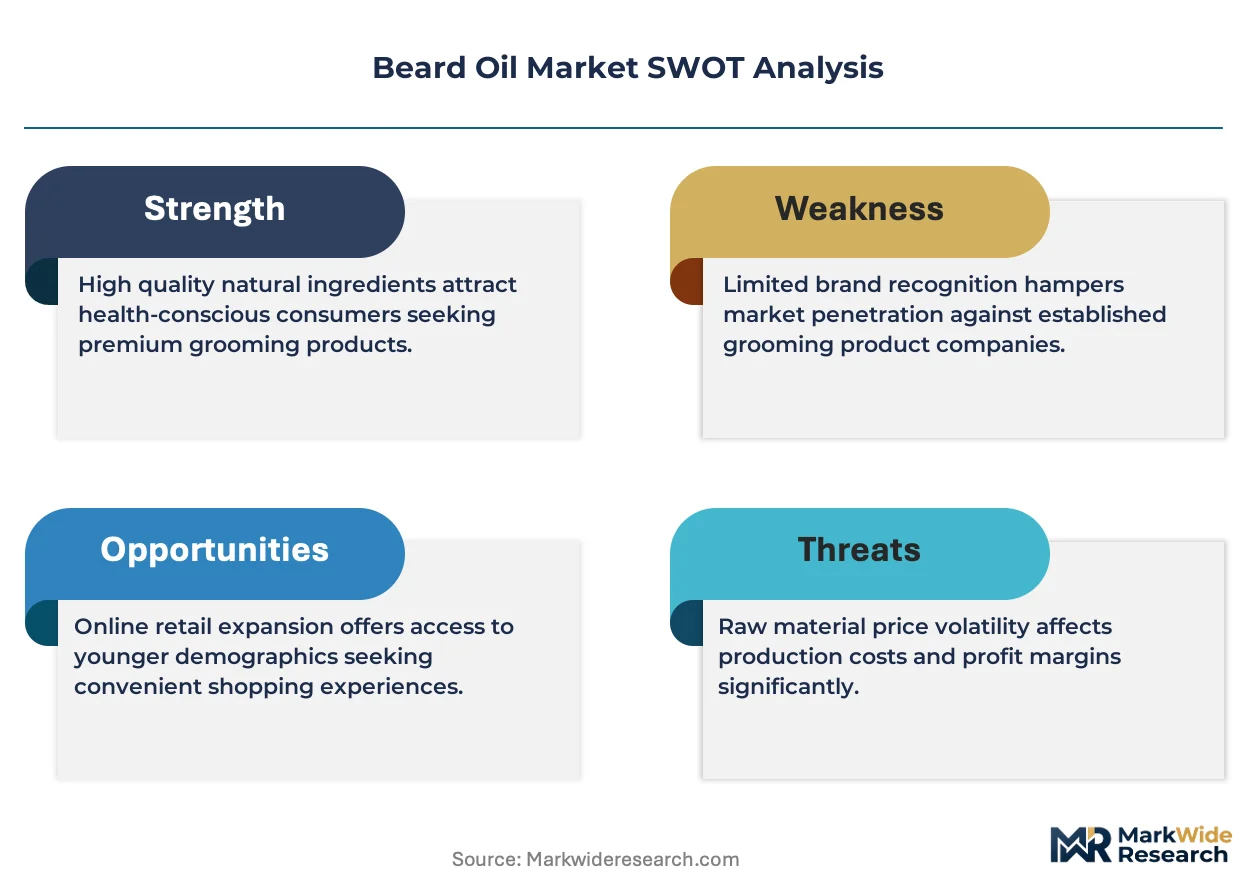
The price-performance gap between premium artisan beard oils and mass-market commodity alternatives is hardening. Honest Amish leverages its heritage positioning and all-natural ingredient claims to sustain pricing power in the premium tier. BeardBrand competes through content-driven community building and specialized grooming education that extends customer lifetime value beyond single-product transactions.
Beard oil is a leave-on cosmetic formulation comprising carrier oils such as jojoba or argan combined with essential oil blends, designed to condition facial hair and moisturize underlying skin while reducing itch and flaking. Manufacturing typically involves cold-pressing or refined extraction followed by blending at controlled temperatures to preserve volatile aromatic compounds. Hydrating oil dominates volume as the entry-point category, while growth oil commands the fastest expansion due to functional positioning around beard density concerns. Natural oils anchor margin pools as consumers scrutinize ingredient transparency, though fragrance oils retain share in styling-oriented SKUs where scent differentiation drives impulse purchase.
FDA cosmetic labeling requirements and EU REACH substance restrictions shape permissible ingredient palettes and international market access protocols for cross-border brands. The country's national cosmetic regulator in emerging Asian markets increasingly mandates local safety assessments that delay entry for smaller artisan producers. Stakeholders must monitor evolving clean-beauty certification schemes and decide whether to absorb reformulation costs or cede positioning to compliance-first competitors.
Market Dynamics
Clean-label ingredient mandates from FDA cosmetic regulations and EU REACH compliance are forcing wholesale reformulation across the beard oil supply chain, compressing margins for artisan producers while creating compliance moats for scaled manufacturers.
Growth Catalysts
- EU REACH substance transparency:Mandatory ingredient disclosure protocols elevate consumer trust in premium natural formulations, accelerating migration from synthetic fragrance oils to cold-pressed carrier bases.
- Barbershop channel concentration:Professional grooming establishments in the United States and United Kingdom drive trial through in-chair application, converting service encounters into recurring direct-to-consumer subscriptions.
- Jojoba oil cultivation expansion:Domesticated argan and jojoba plantations in Israel and Australia reduce raw material lead times for North American formulators, stabilizing input availability for growth oil SKUs.
Market Restraints
- Argan kernel supply concentration:Moroccan cooperative structures control eighty percent of cosmetic-grade argan oil exports, exposing formulators to harvest volatility from Saharan drought cycles.
- Essential oil oxidation chemistry:Thermal degradation of volatile terpenes during international shipping limits shelf-life claims, constraining export market penetration for small-batch producers.
- Beard balm substitution:Multi-function styling products incorporating shea butter and beeswax capture price-sensitive consumers seeking hold-plus-conditioning in single-application routines.
Strategic Opportunities
- India male grooming liberalization:Urban millennial consumers in Mumbai and Bangalore embrace facial hair aesthetics previously restricted by corporate dress codes, opening white-space demand for hydrating oil entry SKUs.
- Biotechnology-derived squalane:Sugar-cane fermentation processes from Brazilian suppliers offer vegan alternatives to shark-liver and olive-derived emollients, capturing clean-beauty certification premiums.
- Social commerce livestreaming:TikTok Shop and Instagram Checkout integration enables real-time ingredient storytelling, collapsing discovery-to-purchase funnels for Gen Z first-time buyers.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulation expertise bridging aromatherapy traditions and stability testing protocols commands premium compensation, squeezing mid-tier brand R&D budgets.
- Organic certification timeline compression:USDA NOP and ECOCERT audit cycles extend eighteen to twenty-four months, delaying product launches for challenger brands against incumbent clean-label portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beard Oil Market |
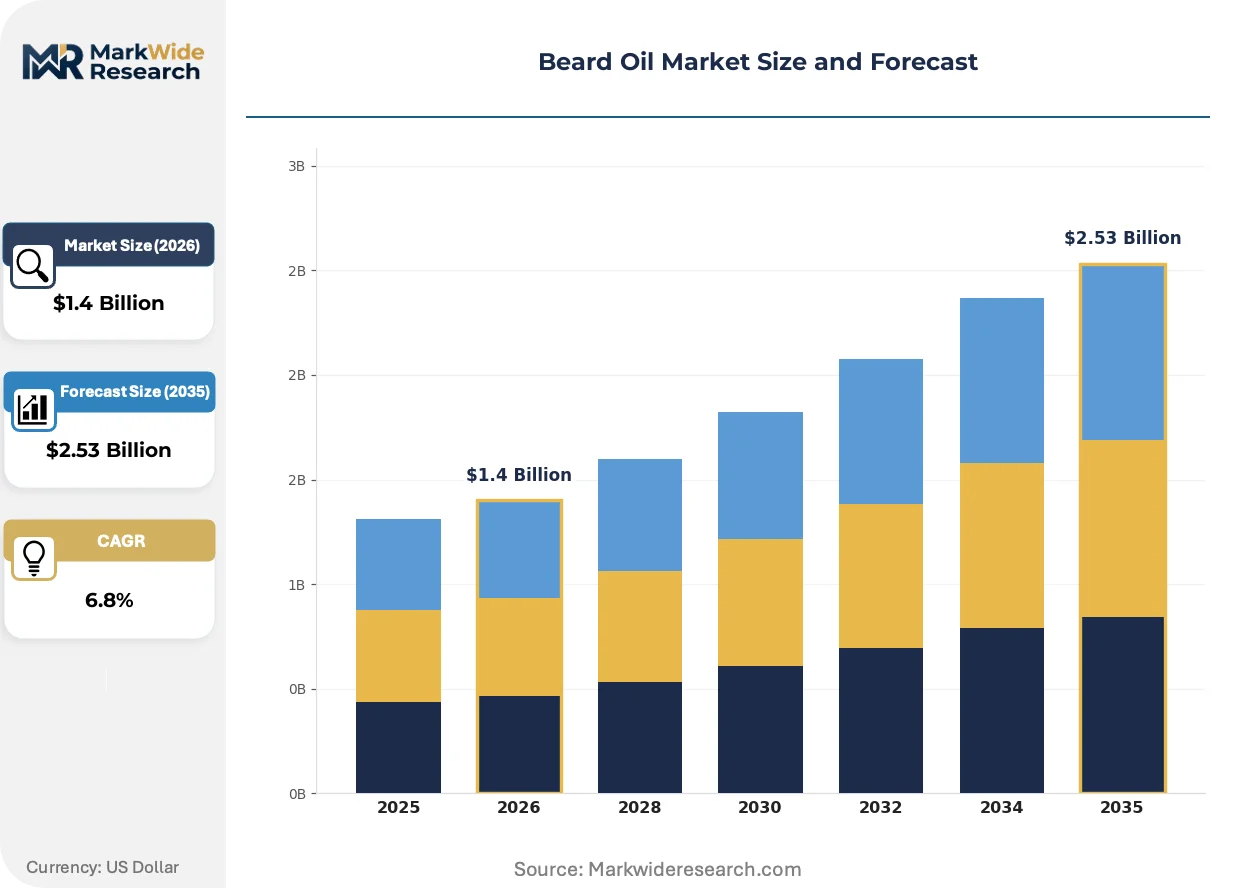
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrating Oil, Styling Oil, Lightweight Oil, Growth Oil Ingredient Type: Natural Oils, Essential Oils, Carrier Oils, Fragrance Oils Packaging Type: Dropper Bottle, Spray Bottle, Jar, Tube Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Salons |
| Companies Covered | Honest Amish, Beard Octane, Black Rebel Beard, Bearded Bastard, Luxurious Bastard, BeardBrand, Artius Man, Dr. Nick's, Live Bearded, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beard Oil Market Emerging Trajectories
Formulation transparency and biotechnology-derived ingredients are restructuring competitive advantage in beard oil manufacturing, displacing heritage storytelling with verifiable supply chain documentation.
Biotechnology is decentralizing raw material sourcing for carrier oil production. Precision fermentation platforms from synthetic biology suppliers now generate squalane and hemisqualane molecules identical to botanical extractions. Indie brands in Portland and Austin adopt these inputs to bypass agricultural commodity markets. The technology is decentralizing supply chain power from Mediterranean and North African cultivation regions toward controlled bioreactor facilities.
EU REACH microplastic restrictions are eliminating synthetic glitter and certain film-forming polymers from styling-oriented beard oils. The regulation forces reformulation of shimmer and texturizing SKUs ahead of enforcement deadlines. Fragrance oil-dependent brands in Germany face compressed innovation cycles to identify compliant aesthetic modifiers.
Subscription bundling now dominates customer acquisition economics for direct-to-consumer beard oil brands. Quarterly replenishment boxes combining hydrating oil, wash, and comb reduce per-order logistics costs while lifting twelve-month retention metrics. This pattern concentrates in United Kingdom urban markets where grooming subscription penetration exceeds continental European averages.
Beard Oil Market Segmentation
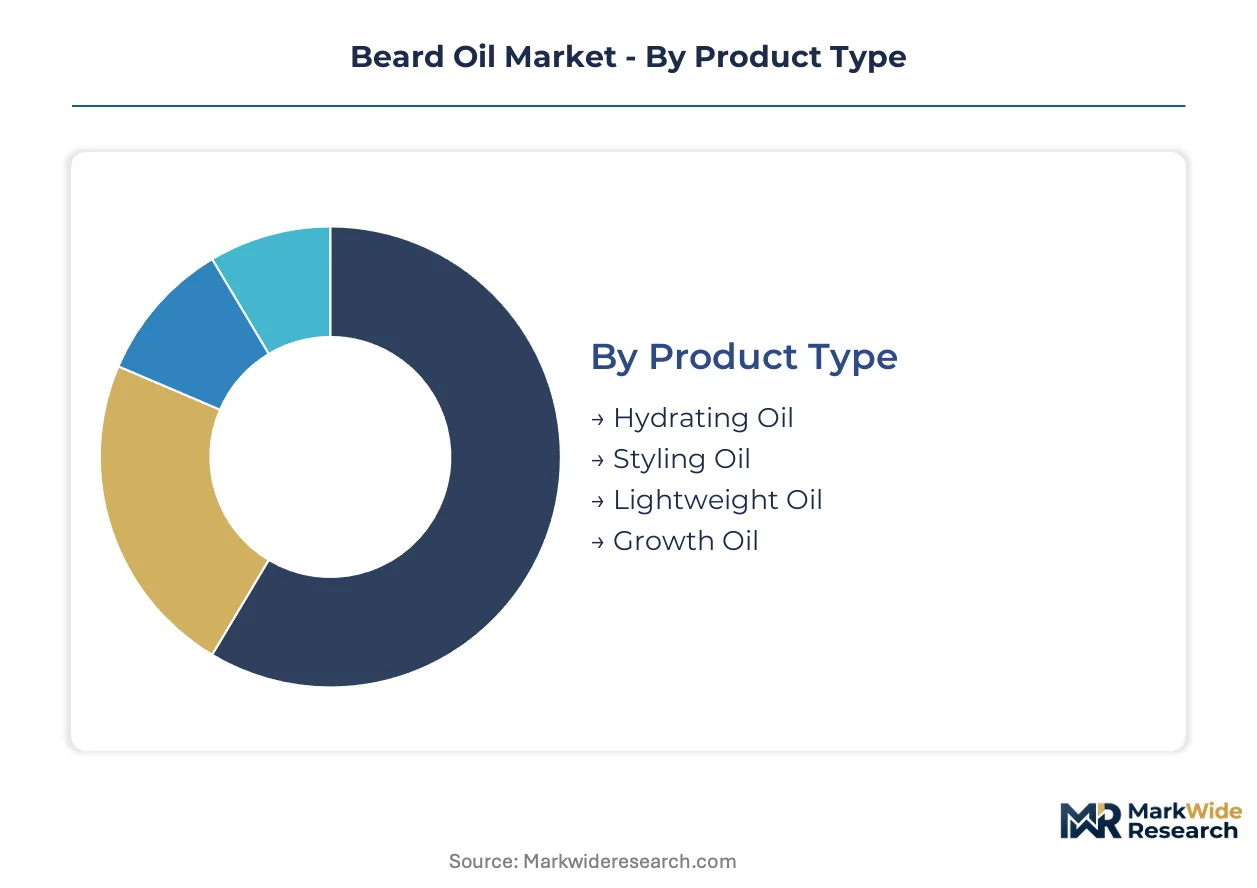
Beard oil manufacturers compete across four distinct segmentation axes that determine pricing power, shelf positioning, and customer acquisition economics. Product formulation and ingredient sourcing anchor margin structures, while packaging format and channel strategy shape trial conversion and repeat purchase rates.
Product Type:
The customization-to-standardization spectrum spans from highly specialized functional SKUs to universal daily-use formulations, with consumer beard length and grooming sophistication driving selection.
- Hydrating Oil:Jojoba and argan carrier bases dominate formulations designed for daily moisture replenishment and itch reduction. Demand concentrates among first-time beard growers in the United States and United Kingdom, where barbershop education drives trial through in-chair application demonstrations.
- Growth Oil:Functional positioning around density and patch-fill concerns commands premium pricing through biotin, caffeine, and peptide additives. Urban millennial consumers in Germany and India fuel expansion as facial hair aesthetics gain workplace acceptance.
- Styling Oil:Medium-hold formulations with beeswax micro-doses target shaped beard maintenance.
- Lightweight Oil:Fast-absorbing squalane and hemisqualane bases suit humid climates and short stubble.
Leading the category by volume: Hydrating Oil. Growing fastest: Growth Oil.
Ingredient Type:
Cost tier stratification separates cold-pressed botanical extractions from compounded synthetic alternatives, with certification status determining shelf placement in premium retail.
- Natural Oils:USDA NOP and ECOCERT-certified cold-pressed jojoba, argan, and hemp seed oils anchor clean-beauty positioning. North American and European consumers absorb 40-60% price premiums for verified supply chain documentation.
- Carrier Oils:Refined grape seed and sweet almond bases provide formulation flexibility for mid-tier brands balancing cost and performance. Volume demand from private-label manufacturers in the United States stabilizes input contracts.
- Essential Oils:Terpene-rich aromatic blends from sandalwood, cedarwood, and tea tree deliver scent differentiation.
- Fragrance Oils:Synthetic aromatic compounds retain share in styling SKUs where EU REACH microplastic restrictions force reformulation timelines.
Highest margin capture: Natural Oils. Steepest expansion trajectory: Carrier Oils.
Packaging Type:
Application ritual and portability requirements segment formats across home vanity use and travel-oriented replenishment.
- Dropper Bottle:Glass amber bottles with calibrated pipettes dominate premium positioning, preserving volatile terpenes from oxidation. Subscription box bundling in the United Kingdom favors this format for controlled dispensing and perceived pharmacy-grade precision.
- Spray Bottle:Fine-mist atomizers suit lightweight oil formulations and body-beard dual-use applications. German consumers prefer this format for even coverage on dense growth.
- Jar:Wide-mouth containers accommodate balm-oil hybrid textures and finger-application rituals.
- Tube:Squeeze formats target gym bag and air travel compliance under TSA liquid restrictions.
Standard for premium tier: Dropper Bottle. Gaining share in functional segments: Spray Bottle.
Distribution Channel:
Customer type and purchase occasion separate discovery-driven trial from replenishment-driven loyalty, with channel mix determining brand positioning investment.
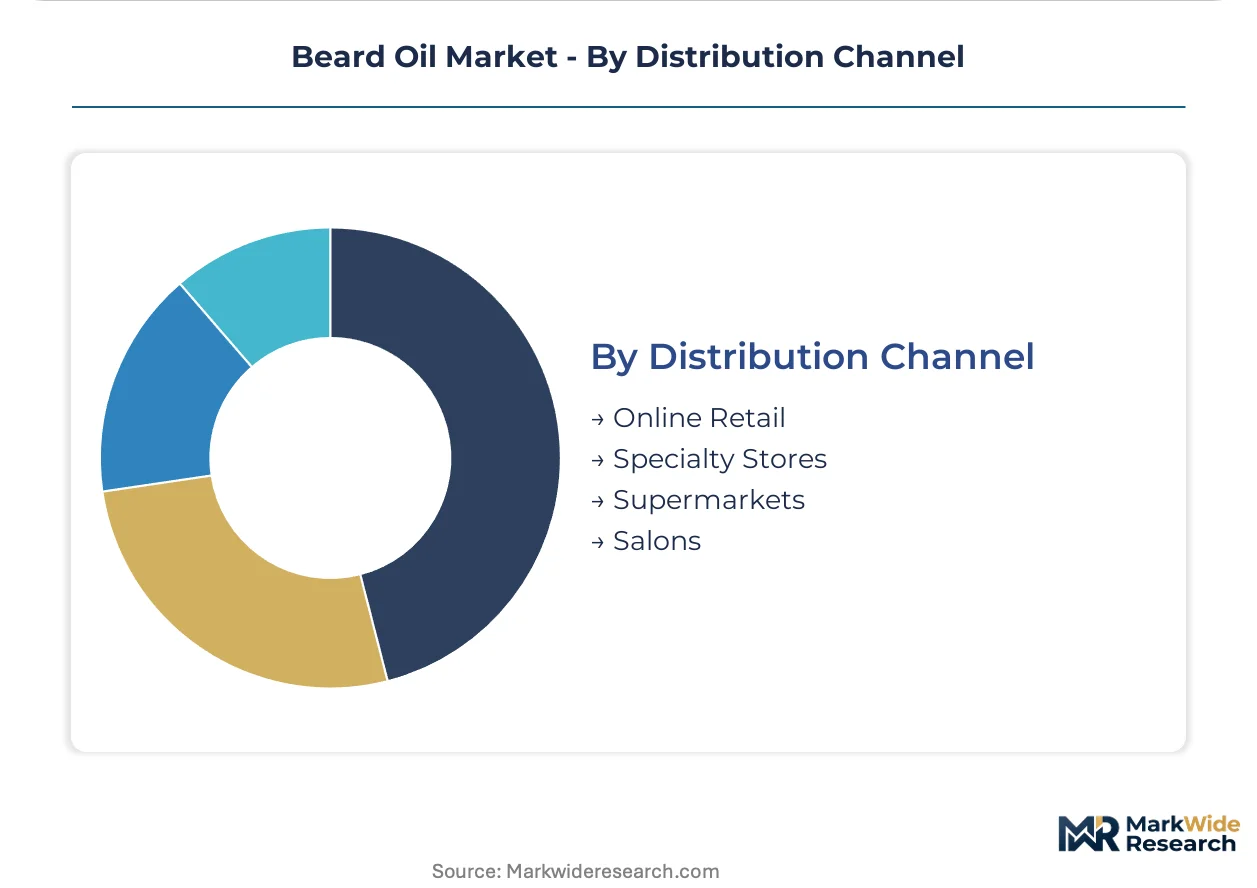
- Online Retail:Direct-to-consumer subscriptions and TikTok Shop integration collapse discovery-to-purchase funnels. Gen Z first-time buyers in the United States and India convert through livestream ingredient storytelling and influencer seeding programs.
- Specialty Stores:Grooming boutiques and apothecary formats provide tactile sampling and staff consultation. UK urban markets sustain this channel through experiential retail investment.
- Supermarkets:Mass-market placement drives price-sensitive volume through bundled value packs.
- Salons:Barbershop channel concentration in the United States converts service encounters into product attachment.
Highest retention economics: Online Retail. Strongest trial conversion: Salons.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brooklyn's barbershop corridor anchors artisan beard oil formulation activity, with clustered grooming boutiques driving premium product development and direct-to-consumer subscription economics.
United States
Barbershop channel concentration in Austin and Brooklyn converts service encounters into recurring product attachments. FDA cosmetic labeling requirements mandate full ingredient disclosure, compressing margins for small-batch producers. Portland's indie brand cluster adopts biotechnology-derived squalane to bypass agricultural commodity markets.
United Kingdom
London's grooming subscription penetration exceeds continental European averages through quarterly replenishment bundling. EU REACH substance transparency protocols accelerate migration from synthetic fragrance oils to cold-pressed carrier bases. Manchester's apothecary retail formats sustain tactile sampling and staff consultation channels.
Germany
Urban millennial workplace acceptance of facial hair aesthetics fuels growth oil demand in Berlin and Hamburg. EU REACH microplastic restrictions eliminate synthetic glitter from styling-oriented SKUs, forcing compressed reformulation timelines. Bavaria's precision manufacturing base supplies calibrated dropper bottle packaging to premium brands.
India
Mumbai and Bangalore's corporate dress code liberalization opens white-space demand for hydrating oil entry SKUs. The country's national cosmetic regulator mandates local safety assessments that delay artisan producer entry. Hyderabad's contract manufacturing cluster scales natural oil formulation for domestic and export markets.
Australia
Domesticated jojoba plantations in Queensland reduce raw material lead times for North American formulators. TGA cosmetic ingredient standards align with EU REACH protocols, easing export compliance burdens. Sydney's direct-to-consumer brands leverage social commerce livestreaming for Gen Z acquisition.
Beard Oil Market Vendor Landscape
Premium-margin players sit above commodity-margin players across ingredient transparency and certification documentation. The vendor base clusters around heritage storytelling, content-driven community building, and biotechnology sourcing respectively. Three archetypes dominate: artisan formulators leveraging all-natural claims, digital-native brands collapsing discovery-to-purchase funnels, and scaled manufacturers absorbing organic certification timelines. Competitive moves concentrate on strategic partnerships with barbershop channels and portfolio diversification into subscription bundling.
Within the heritage-positioned tier, Honest Amish and BeardBrand exemplify divergent margin defense strategies. Honest Amish anchors premium pricing through all-natural ingredient claims and traditional formulation narratives. BeardBrand occupies a position defined by content-driven community building and specialized grooming education that extends customer lifetime value. At the digital-native end, Beard Octane represents the direct-to-consumer acquisition model integrating TikTok Shop and Instagram Checkout for real-time ingredient storytelling.
| Leading Market Players |
|---|
| Honest Amish |
| Beard Octane |
| Black Rebel Beard |
| Bearded Bastard |
| Luxurious Bastard |
| BeardBrand |
| Artius Man |
| Dr. Nick's |
| Live Bearded |
| Others |
Supply Flow & Price Mechanics
EU REACH substance transparency mandates gate qualified supply access and premium-tier pricing power, forcing artisan producers to absorb eighteen-to-twenty-four month organic certification timelines while scaled manufacturers capture compliance moats.
Pricing Analysis
Outcome-based pricing tied to beard density improvement anchors growth oil premiums, while hydrating oil competes on subscription retention economics. Three-tier pricing structure across premium, standard, and economy levels separates USDA NOP-certified natural formulations from refined carrier bases and synthetic fragrance alternatives. Cost compression in the mid-tier is intensifying because private-label manufacturers absorb volume contracts. Mass-market buyers through supermarket channels exhibit highest price sensitivity; barbershop-channel subscribers demonstrate lowest sensitivity due to service-attachment loyalty.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore manage hub-and-spoke patterns for EU and Asia-Pacific fulfillment. Raw material supply concentrates in Morocco for argan kernel, Israel and Australia for jojoba cultivation, and Brazil for biotechnology-derived squalane. Formulation depends on cold-pressed carrier oils and volatile terpene stability. Single-source vulnerability from Moroccan cooperative structures controlling cosmetic-grade argan exports exposes harvest volatility. Distribution runs through direct-to-consumer subscription platforms and barbershop professional channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU REACH and FDA cosmetic labeling requirements create barrier-to-entry moats favoring scaled manufacturers with dedicated regulatory affairs capacity.
For Market Incumbents: Lock in barbershop channel exclusivity through professional education programs and in-chair application protocols. Acquire biotechnology squalane supply agreements to bypass Moroccan argan volatility. Certification investment in USDA NOP and ECOCERT documentation defends against clean-beauty challenger brands. For New Entrants and Emerging Players: TikTok Shop livestreaming collapses discovery-to-purchase funnels for Gen Z first-time buyers in India and the United States. Target hydrating oil entry SKUs in Mumbai and Bangalore where corporate dress code liberalization opens white-space demand. Social commerce integration enables real-time ingredient storytelling without legacy retail slotting fees. For Investors and Strategic Acquirers: Eighteen-to-twenty-four month organic certification backlog is the leading indicator that compliant manufacturing capacity will command scarcity premiums. Mid-tier brands with established barbershop distribution and subscription retention metrics represent viable acquisition targets. Watch for EU REACH microplastic enforcement deadlines as inflection signals for reformulation-driven consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Squalane Supply | Brazilian fermentation partnerships bypass Moroccan argan kernel concentration and Saharan drought exposure. |
| Barbershop Channel Expansion | Professional grooming establishments in Austin and Brooklyn convert service encounters into recurring subscription attachments. |
| Clean-Beauty Certification Investment | USDA NOP and ECOCERT documentation unlocks 40-60% price premiums in North American and European retail. |
| Social Commerce Platform Integration | TikTok Shop and Instagram Checkout enable real-time ingredient storytelling for Gen Z acquisition. |
| Subscription Bundling Architecture | Quarterly replenishment boxes combining oil, wash, and comb reduce logistics costs and lift retention metrics. |
Methodological Framework
Multi-period observation of formulation transparency mandates, barbershop channel penetration, and biotechnology adoption rates anchored the trend analysis, supplemented by interviews with cosmetic chemists, brand founders, apothecary retail buyers, and contract manufacturing operators. Secondary validation drew from FDA cosmetic labeling guidance, EU REACH substance restriction databases, customs import records for jojoba and argan oil, and Nielsen retail audit data for grooming subscription services. Bottom-up SKU-level volume estimates triangulated against top-down market sizing from personal care industry associations.
Input-output matrices modeled relationships between carrier oil sourcing costs, certification timeline delays, and channel-specific pricing power across the projection horizon. Segmentation dimensions included product type (hydrating, growth, styling, lightweight), ingredient sourcing tier (natural certified, refined carrier, synthetic fragrance), packaging format, and distribution channel. CAGRs derived from regression analysis of historical subscription retention curves and barbershop service-to-product conversion rates. Biotechnology adoption curves and EU regulatory enforcement timelines served as industry-specific forecast inputs.
The model holds under stable Moroccan argan harvest conditions and sustained barbershop channel growth; deviation in Saharan drought cycles or social commerce platform policy shifts would revise volume trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Cosmetic Serum Market
Beauty & Personal Care
Pre-Shave Care Market
Beauty & Personal Care
US Sustainable Personal Care Market
Beauty & Personal Care
Pore Strips Market
Beauty & Personal Care
Premium Cosmetics Market
Beauty & Personal Care
Hair Removal Epilator Market
Beauty & Personal Care
Global Bath Bomb Market
Beauty & Personal Care
Face Makeup Market
Beauty & Personal Care
Europe Male Grooming Products Market
Beauty & Personal Care
Hair Conditioner Market
Beauty & Personal Care
Global Electric Head and Scalp Massager Market
Beauty & Personal Care
Body Balm Market
Beauty & Personal Care
GCC Male Grooming Products Market
Beauty & Personal Care
Over-Night Hair Treatment Products Market
Beauty & Personal Care
Luxury Hair Care Market
Beauty & Personal Care
Global Beauty and Personal Care Products Market