
 Middle East and Africa Hair Styling Products Market | 2026-2036
Middle East and Africa Hair Styling Products Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Hair Styling Products Market Foresight
CE marking under the EU Cosmetics Regulation is redrawing competitive access for brands exporting into North African markets. L'Oréal S.A. leverages its R&D footprint to sustain premium positioning across Gulf retail channels. Unilever Plc anchors mass-market penetration through deep supermarket distribution in South Africa and Kenya. Procter & Gamble Co differentiates via technology leadership in humidity-resistant polymer formulations suited to coastal climates.
Middle East and Africa hair styling products encompass leave-in and rinse-off preparations—typically containing film-forming polymers, emollients, and propellants—engineered to shape, hold, or texturize hair across diverse curl patterns and environmental conditions. The primary commercial purpose centers on enabling consumer self-styling and professional finishing services in high-humidity and high-heat climates. Hairspray and gel together occupy the dominant volume positions, though organic formulations within the water-based category represent the fastest-expanding margin pool as clean-label preferences migrate from Europe into urban African and Gulf markets. Professional stylists and salons command disproportionate influence on brand trial, making this end-user segment the critical gateway for premium pricing architecture.
South Africa's National Regulator for Compulsory Specifications enforces mandatory labeling and safety testing for all cosmetic imports, while Saudi Arabia's SFDA mandates halal certification and ingredient disclosure that filter which formulations enter Gulf retail. These dual compliance frameworks elevate barriers for smaller exporters and favor scaled manufacturers with dedicated regulatory affairs teams. Stakeholders must monitor how Nigeria's proposed adoption of ECOWAS harmonized standards will reshape cross-border trade routes and local production incentives.
Market Dynamics
Professional salon chains across Gulf cities are consolidating procurement power, forcing manufacturers to reconfigure volume pricing and technical service support around formal grooming culture rather than traditional retail distribution.
Growth Catalysts
- Halal certification mandates:Saudi Arabia's SFDA requires ingredient disclosure and halal verification, filtering out non-compliant imports and creating protected market space for certified domestic and regional producers.
- Water-based formulations:Young consumers in Nigeria's Lagos-Abuja corridor are pivoting toward organic water-based gels and sprays, expanding the premium margin pool as clean-label preferences migrate from European markets.
- Humidity-resistant polymers:Coastal climates from Durban to Mombasa are driving adoption of advanced film-forming polymers that maintain hold integrity under extreme heat and moisture conditions.
Market Restraints
- Propellant cost volatility:Aerosol hairspray formulations depend on hydrocarbon propellant supplies concentrated in Gulf petrochemical complexes, exposing margin structures to feedstock price swings.
- Import compliance fragmentation:South Africa's National Regulator for Compulsory Specifications imposes mandatory safety testing and labeling protocols that elevate fixed costs for smaller exporters without dedicated regulatory affairs teams.
- Silicone substitution pressure:Natural oil emollients from Moroccan argan and Ethiopian shea are displacing synthetic silicones in premium positioning, compressing formulation flexibility for conventional polymer suppliers.
Strategic Opportunities
- Ethiopian manufacturing zones:Underpenetrated East African production capacity offers tariff-advantaged export positioning into COMESA markets with growing urban middle-class demand.
- ECOWAS harmonization:Nigeria's proposed adoption of regional standards will streamline cross-border trade routes and reduce redundant certification burdens for formulations entering West African markets.
- Salon-direct digital platforms:Professional stylist networks in Dubai and Riyadh are migrating procurement onto specialized B2B platforms, bypassing traditional distributor markups and enabling direct technical relationship building.
Industry Challenges
- Formulation chemist scarcity:Gulf markets lack sufficient trained cosmetic chemists capable of adapting global polymer technologies to local climate conditions and halal compliance requirements.
- Multi-jurisdiction labeling:Divergent Arabic-French-English packaging mandates across Maghreb and Mashreq markets force SKU proliferation and inventory complexity without unified regional standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Hair Styling Products Market |
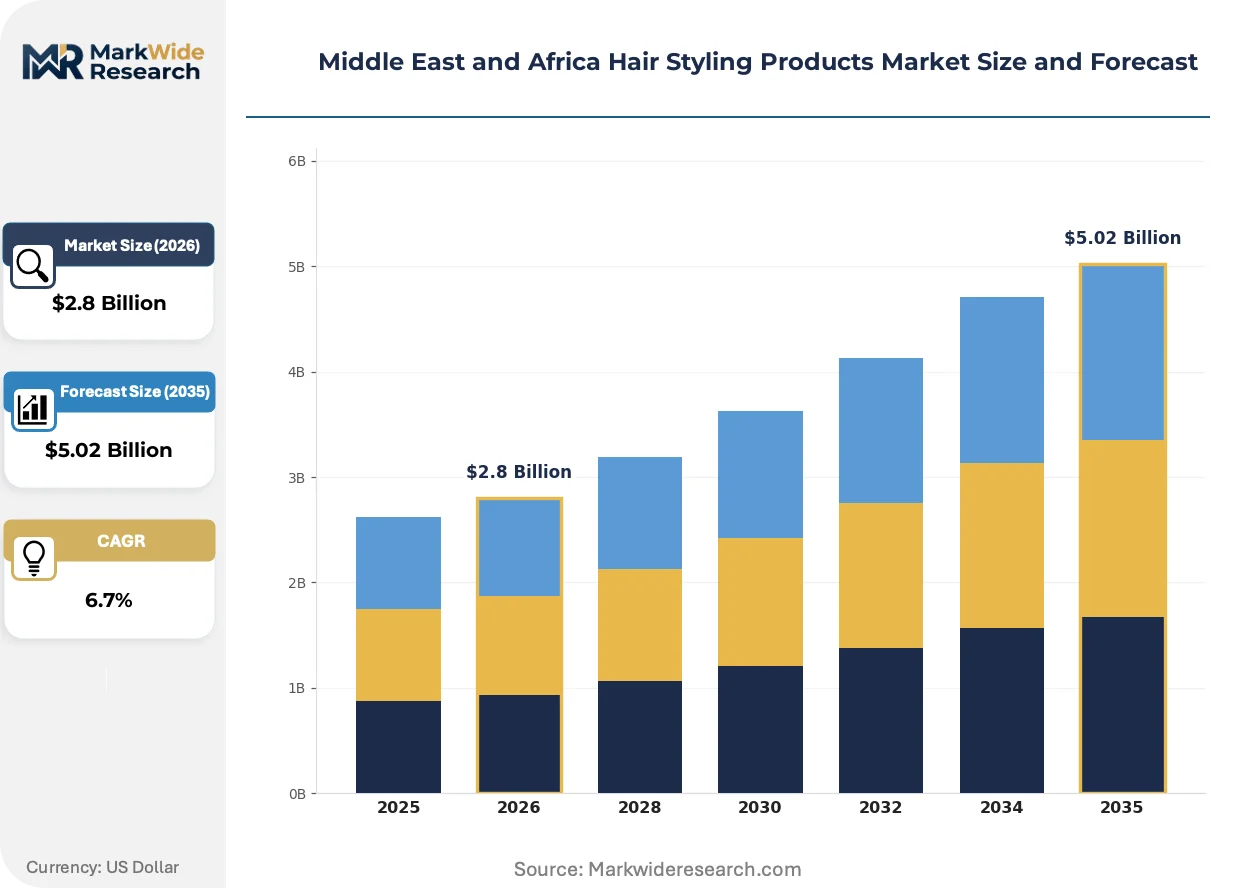
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hairspray, Mousse, Gel, Pomade End User: Men, Women, Salons, Professional Stylists Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales Formulation: Organic, Chemical-based, Water-based, Cream |
| Companies Covered | L'Oréal S.A., Unilever Plc, Procter & Gamble Co, Marico Ltd, Twincare International, Sano Bruno's Enterprises Ltd, Kao Corporation, Henkel AG & Co. KGaA, Amka Products (Pty) Ltd, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Hair Styling Products Market Shifts & Advancements
Climate-adaptive chemistry and regulatory transparency are converging to reshape competitive positioning across Middle East and Africa hair styling, with technology miniaturization and clean-label migration as dominant vectors.
Biodegradable film-forming polymers derived from corn starch and cellulose are replacing conventional petrochemical resins in premium leave-in conditioners and styling creams. Professional salons in Jeddah and Casablanca are piloting these materials for clients with sensitive scalps and environmental preferences. The technology is miniaturizing batch production economics, enabling regional contract manufacturers to compete with multinational scale on customized small-run formulations.
South Africa's updated cosmetics labeling requirements under the National Regulator for Compulsory Specifications now mandate full ingredient disclosure in all eleven official languages. This policy is forcing reformulation of legacy imports and accelerating local production investments by brands seeking to avoid translation compliance costs. Mass-market supermarket chains in Johannesburg and Cape Town are responding by prioritizing domestically manufactured SKUs with simplified supply chains.
Salon chains across Gulf cities are consolidating vendor relationships and demanding outcome-based technical service rather than product-only transactions. Independent distributors in traditional souk retail channels are losing share to direct manufacturer partnerships with consolidated professional buyer networks. This pattern is most visible in Dubai's Jumeirah salon corridor and Riyadh's Tahlia Street district, where procurement centralization is compressing traditional wholesale margins.
Middle East and Africa Hair Styling Products Market Segmentation
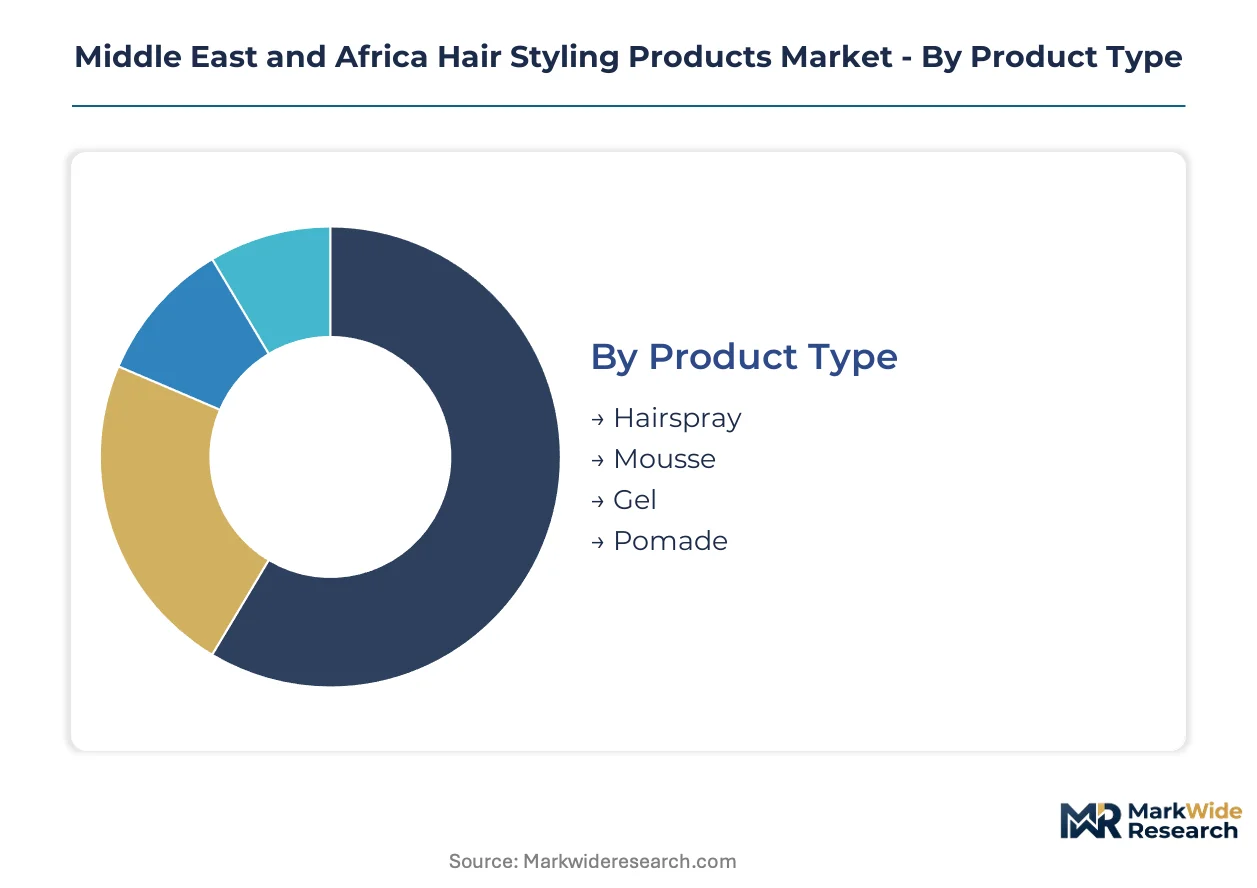
Segmentation in Middle East and Africa hair styling products reveals how channel strategy and formulation chemistry intersect with climate adaptation and regulatory compliance across diverse consumer bases.
Product Type:
Hairspray and gel dominate supermarket and specialty store shelves across Gulf retail corridors, while mousse and pomade concentrate in salon-direct and online channels serving professional stylists.
- Hairspray:Aerosol and pump-dispensed formulations rely on hydrocarbon propellants and film-forming polymers engineered for humidity resistance. Demand clusters in Saudi Arabia and UAE retail chains where consumers prioritize long-lasting hold under extreme heat conditions.
- Gel:Water-based and alcohol-based variants span mass-market tubes to premium salon jars with specialized polymers for curl definition. Nigeria's Lagos-Abuja corridor drives fastest volume expansion as young male consumers adopt daily styling routines.
- Mousse:Lightweight foam preparations containing conditioning agents and flexible-hold polymers target volume enhancement. Professional stylists in Dubai and Casablanca favor mousse for blow-dry finishing services.
- Pomade:Oil-based and water-soluble wax formulations deliver high-shine sculpting hold. Barbershops across Johannesburg and Nairobi represent the core procurement channel for this segment.
Hairspray dominates installed base across mass retail. Gel is where expansion concentrates as water-based organic variants gain share.
End User:
Volume concentration varies sharply by price tier—salons and professional stylists anchor premium positioning while individual consumers drive mass-market throughput.
- Men:Male grooming culture deepening across Gulf cities has normalized daily hair styling, with water-based gels and matte pomades as preferred formats. Young professionals in Riyadh and Jeddah represent the fastest-expanding demographic cohort.
- Women:Female consumers span heat-protectant sprays for thermal styling to humidity-resistant hold products for natural curl patterns. Demand concentrates in Nigeria's urban centers and South Africa's metropolitan retail corridors.
- Salons:Formal salon chains across Dubai's Jumeirah district and Riyadh's Tahlia Street consolidate procurement power, demanding technical service support alongside product supply. This segment commands disproportionate influence on brand trial and premium pricing architecture.
- Professional Stylists:Independent stylists and mobile service providers source through specialized B2B platforms and direct manufacturer relationships, bypassing traditional wholesale distribution.
Individual consumers anchor volume throughput. Salon and professional stylist channels are climbing the fastest as formal grooming culture deepens.
Distribution Channel:
Channel mix reflects infrastructure maturity—supermarket penetration correlates with modern retail development while online and direct sales expand where logistics networks enable last-mile delivery.
- Online Retail:E-commerce platforms capture growing share among urban millennials seeking convenience and product reviews. Jumia and regional marketplace operators serve Nigeria, Kenya, and Morocco with expanding hair care assortments.
- Supermarkets:Mass-market chains in South Africa, UAE, and Saudi Arabia stock standardized SKUs with simplified labeling compliant with local regulator mandates. Shoprite, Carrefour, and Lulu Hypermarket represent dominant retail gatekeepers.
- Specialty Stores:Beauty-focused retailers and pharmacy chains curate premium and professional-grade formulations. This channel concentrates in Gulf cities where consumers seek imported European and North American brands.
- Direct Sales:Manufacturer relationships with salon chains and professional networks bypass distributor markups. Direct technical relationship building enables customized formulation support and volume pricing negotiation.
Supermarkets dominate installed base. Online retail is where expansion concentrates as logistics infrastructure matures across urban Africa.
Formulation:
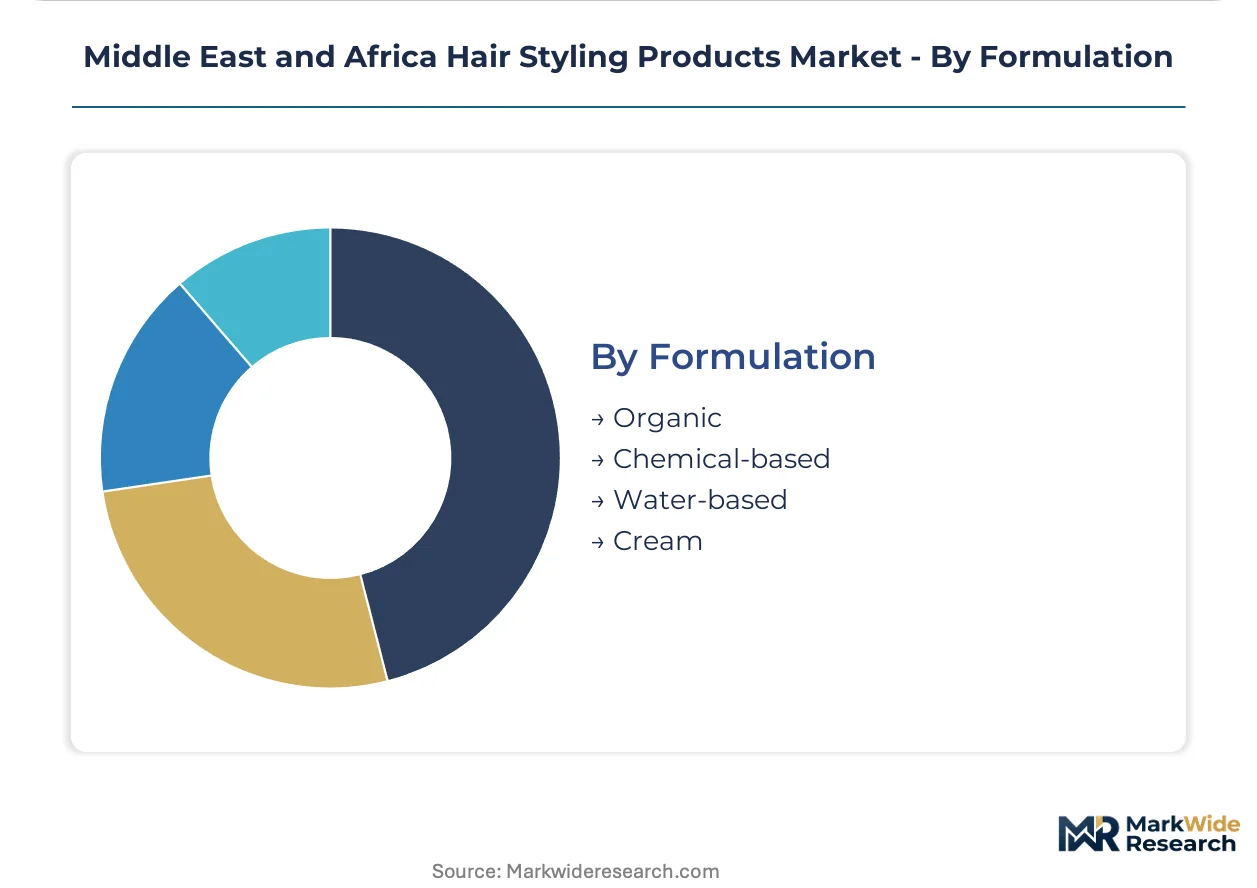
Formulation chemistry determines regulatory compliance burden and margin structure—organic and water-based variants face halal certification requirements while chemical-based formats navigate safety testing protocols.
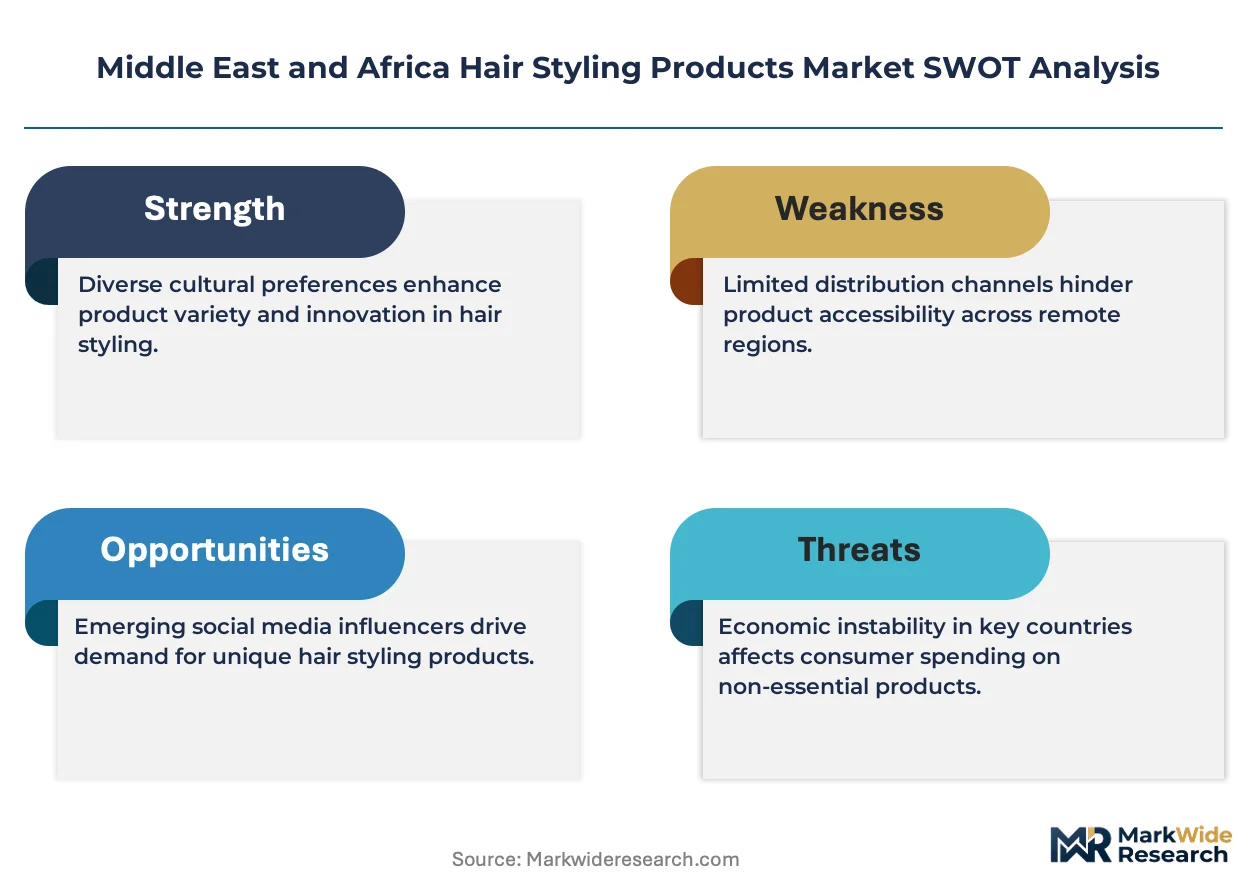
- Organic:Plant-derived film-formers and natural oil emollients from Moroccan argan and Ethiopian shea command premium positioning. Saudi Arabia's SFDA halal certification mandates filter which organic formulations enter Gulf retail.
- Chemical-based:Synthetic polymers and silicone emollients deliver cost-efficient performance in mass-market hairsprays and gels. South Africa's National Regulator for Compulsory Specifications imposes mandatory safety testing that elevates compliance costs for imports.
- Water-based:Low-VOC formulations using water as primary solvent address environmental and regulatory pressures. Young consumers in Nigeria's urban corridor drive fastest adoption as clean-label preferences migrate from European markets.
- Cream:Emulsion-based preparations combining conditioning and styling functions target consumers with textured and curl-patterned hair. Demand concentrates in South Africa and across East African markets with diverse hair types.
Chemical-based formulations dominate installed base. Organic and water-based variants are gaining share fastest as clean-label preferences and halal compliance reshape procurement criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's SFDA halal certification mandates and South Africa's National Regulator for Compulsory Specifications labeling requirements are reshaping import compliance costs across the Middle East and Africa hair styling products landscape.
Saudi Arabia
Gulf cities drive formal grooming culture expansion among young male professionals. SFDA mandates halal certification and full ingredient disclosure for all cosmetic imports. Riyadh's Tahlia Street salon corridor consolidates procurement power through direct manufacturer partnerships.
South Africa
Johannesburg and Cape Town anchor mass-market distribution through supermarket chains. The National Regulator for Compulsory Specifications enforces eleven-language labeling and mandatory safety testing. Domestic production investments accelerate as brands seek to avoid translation compliance costs.
Nigeria
Lagos-Abuja urban corridor concentrates demand for water-based and organic formulations among young consumers. Proposed ECOWAS harmonized standards will streamline cross-border trade routes. Local manufacturing incentives strengthen as regional integration advances.
UAE
Dubai's Jumeirah salon district exemplifies professional channel consolidation with outcome-based technical service demands. MOHAP cosmetic regulations align with Gulf Cooperation Council standards. E-commerce platforms capture growing millennial share through specialized B2B procurement migration.
Morocco
Casablanca and Rabat pilot biodegradable polymer formulations leveraging indigenous argan oil emollient supplies. CE marking requirements under EU Cosmetics Regulation filter competitive access for European exports. Regional contract manufacturers compete on customized small-run production economics.
Middle East and Africa Hair Styling Products Market Competitive Landscape
Player mix skews toward multinational consumer goods conglomerates with dedicated regulatory affairs capabilities and regional specialty manufacturers with halal certification expertise. Market structure concentrates around three to four scaled manufacturers controlling premium distribution channels, with fragmented local producers occupying mass-market tiers. Strategic archetypes include Gulf-compliant formulators, salon-direct technical service providers, and natural ingredient specialists. Dominant competitive moves center on halal certification acquisition and direct salon chain partnership establishment.
Within the multinational tier, L'Oréal S.A., Unilever Plc, and Procter & Gamble Co exemplify divergent positioning strategies. L'Oréal S.A. occupies a position emphasizing premium R&D investment across Gulf retail channels. Unilever Plc anchors mass-market penetration through deep supermarket distribution networks in South Africa and Kenya. Procter & Gamble Co represents technology leadership in humidity-resistant polymer formulations suited to coastal climates from Durban to Mombasa.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| Unilever Plc |
| Procter & Gamble Co |
| Marico Ltd |
| Twincare International |
| Sano Bruno's Enterprises Ltd |
| Kao Corporation |
| Henkel AG & Co. KGaA |
| Amka Products (Pty) Ltd |
| Others |
Supply & Pricing Matrix
Long-term capacity reservation agreements between Gulf petrochemical complexes and aerosol propellant buyers lock in feedstock access while anchoring price visibility against hydrocarbon volatility swings. These contractual structures concentrate procurement power among scaled manufacturers with dedicated regulatory affairs teams, compressing margin flexibility for smaller importers navigating South Africa's eleven-language labeling mandates and Saudi Arabia's halal certification requirements.
Pricing Analysis
Certification level creates the primary spread between premium organic formulations and mass-market chemical-based alternatives. Three-tier pricing structure across premium halal-certified, standard import-grade, and economy domestic-manufactured tiers reflects compliance burden differentials. Pricing pressure intensifies in the standard tier as Nigerian consumers pivot toward water-based organic variants, while salon-direct channels show least price sensitivity due to outcome-based technical service bundling.
Supply Chain Analysis
Strategic stockpile preferences dominate raw material procurement given propellant feedstock volatility and seasonal demand surges around Gulf religious observances. Manufacturing concentrates in Saudi Arabia, South Africa, and Ethiopia, with film-forming polymers and natural oil emollients as critical inputs. Single-source vulnerability runs through Gulf petrochemical complexes for hydrocarbon propellants. Distribution runs through supermarket chains in South Africa and UAE, with direct salon partnerships gaining share in Gulf cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formal grooming culture expansion across Gulf cities signals cyclical recovery as young male professionals normalize daily styling routines and consolidate procurement through salon chains.
For Market Incumbents: Shield premium positioning by deepening backward integration into Moroccan argan and Ethiopian shea supply chains against natural oil emollient substitution pressure. Accelerate halal certification renewal cycles ahead of SFDA mandate tightening. Defend salon-direct relationships through embedded technical service teams in Dubai's Jumeirah corridor and Riyadh's Tahlia Street district.
For New Entrants and Emerging Players: Anchor in Ethiopia's underpenetrated manufacturing zones to capture COMESA tariff advantages and regional middle-class demand expansion. Target Nigeria's Lagos-Abuja urban corridor with water-based organic formulations as clean-label preferences accelerate. Deploy specialized B2B platforms to bypass traditional distributor markups and build direct stylist relationships.
For Investors and Strategic Acquirers: Capital is best deployed toward Gulf-compliant formulators with established SFDA relationships and scalable halal certification infrastructure. Long-term viability hinges on regulatory moat depth rather than volume scale alone. Watch ECOWAS harmonization implementation in Nigeria as inflection signal for West African production incentive restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Acceleration | SFDA compliance creates protected market access for certified domestic and regional producers. |
| Backward Integration into Natural Oils | Moroccan argan and Ethiopian shea sourcing secures premium formulation differentiation against silicone displacement. |
| Salon-Direct Digital Platform Launch | B2B procurement migration in Dubai and Riyadh bypasses traditional distributor margin compression. |
| Ethiopian Manufacturing Footprint Expansion | COMESA tariff advantages enable competitive export positioning into East African urban markets. |
| Biodegradable Polymer R&D Investment | Corn starch and cellulose film-formers address sensitive scalp preferences in Jeddah and Casablanca salons. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with cosmetic chemists, regulatory affairs directors at multinational formulators, salon chain procurement heads, and specialty retail category buyers; and secondary validation against SFDA halal certification registries, South Africa's National Regulator for Compulsory Specifications filings, customs trade records, and supermarket chain SKU audit databases. Bottom-up volume modeling triangulated with top-down value estimates across product type, end user, distribution channel, and formulation chemistry dimensions.
Across the analysis window, the forecasting framework projected value expansion by segmenting demand across hairspray, gel, mousse, and pomade categories intersecting with professional stylist, salon chain, and individual consumer end users. CAGRs derived from historical trajectory analysis adjusted for regulatory compliance cost step-changes and channel migration patterns. Humidity-resistant polymer adoption curves and halal certification penetration rates served as industry-specific demand drivers.
Decision-makers should treat outputs as directional under assumptions of sustained Gulf petrochemical feedstock availability and incremental ECOWAS harmonization progress; material deviation would warrant model refresh. Revision becomes warranted when propellant cost volatility crosses threshold levels triggering formulation substitution or when Nigeria's regulatory adoption timeline accelerates beyond baseline assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Electric Facial Cleansing Brush Market
Beauty & Personal Care
Global Massage Oil Market
Beauty & Personal Care
Mexico Beauty and Personal Care Market
Beauty & Personal Care
Kids Shampoo Market
Beauty & Personal Care
Organic Shampoo Market
Beauty & Personal Care
Leave-In Conditioner Market
Beauty & Personal Care
Sun Protection Spray Market
Beauty & Personal Care
Colombia Cosmetics Products Market
Beauty & Personal Care
Coffee Beauty Products Market
Beauty & Personal Care
UV Nail Gel Lamp Market
Beauty & Personal Care
Premium Cosmetics Market
Beauty & Personal Care
Male Grooming Products Market
Beauty & Personal Care
Beard Straightener Market
Beauty & Personal Care
Personal Care Contract Manufacturing Market
Beauty & Personal Care
LAMEA Hair Removal Wax Market
Beauty & Personal Care
Over-Night Hair Treatment Products Market