
 Halal Cosmetic Products Market | 2026-2036
Halal Cosmetic Products Market Size, Share, and Industry Trends Forecast 2026-2036
Halal Cosmetic Products Market Outlook
Young Muslim professionals and Gen Z consumers is bifurcating demand away from traditional family-oriented purchasing toward individual brand exploration. Wardah Cosmetics dominates Indonesia's mass-market halal beauty shelf with deep pharmacy and supermarket penetration. INIKA Organic anchors premium positioning through vegan-certified color cosmetics that command specialty store placement. Martha Tilaar Group leverages backward integration into botanical sourcing to sustain margin control across its multi-brand portfolio.
Halal cosmetic products exclude alcohol, pork derivatives, and blood-based ingredients while substituting plant-derived emulsifiers and synthetic alternatives vetted by religious authorities. Manufacturing requires dedicated production lines or validated cleaning protocols to prevent cross-contamination with non-halal substances, with finished goods certified by bodies such as JAKIM, MUI, or halal accreditation agencies in Europe. Skincare commands the largest revenue pool as Muslim consumers prioritize wudu-friendly formulations that permit water permeability during ablution. Makeup competes through color cosmetics innovation, particularly breathable foundations and halal-certified lip products. Online channels represent the fastest-growing distribution vector, driven by influencer-led education and subscription box models that reduce trial barriers for emerging brands.
JAKIM in Malaysia, BPJPH in Indonesia, and EMA's evolving cosmetic ingredient safety framework collectively determine market access thresholds and reformulation obligations for multinational entrants. REACH compliance in Europe and FDA cosmetic labeling rules in the United States create additional compliance layers that halal-certified producers must navigate to serve cross-border demand. Stakeholders must monitor certification reciprocity negotiations between Southeast Asian halal bodies and Gulf standardization organizations, as mutual recognition agreements will reshape competitive geography for export-oriented manufacturers.
Market Dynamics
Certification fragmentation between JAKIM, BPJPH, and Gulf standardization bodies is forcing multinational halal cosmetic manufacturers to maintain parallel compliance tracks, elevating operational complexity while regional mutual recognition negotiations remain stalled.
Growth Catalysts
- Gen Z Muslim consumer autonomy:Young Muslim professionals in Southeast Asia are decoupling purchasing decisions from family units, accelerating individual brand trial and premium product adoption in color cosmetics.
- BPJPH regulatory expansion:Indonesia's 2024 mandatory halal certification deadlines for cosmetics are compelling reformulation investments across the supply chain, converting informal producers into certified market participants.
- Wudu-compatible formulation science:Water-permeable skincare emulsions are deepening category penetration among practicing Muslim women who prioritize ablution-friendly daily routines.
Market Restraints
- Botanical input cost volatility:Backward-integrated producers face margin pressure from weather-driven fluctuations in palm-derived emulsifiers and exotic plant extracts sourced from Indonesian archipelago suppliers.
- Certification timeline friction:JAKIM's 6-12 month approval cycles for new manufacturing facilities create launch delays that disadvantage entrants against established Malaysian producers with validated production lines.
- Synthetic alcohol substitution limits:Technical constraints in replacing ethanol-based preservatives in color cosmetics without compromising shelf stability restrict formulation freedom in lip products and liquid foundations.
Strategic Opportunities
- Subscription box distribution models:Influencer-curated halal beauty boxes are collapsing trial barriers for emerging Indonesian brands, converting online discovery into recurring revenue streams.
- EU-Gulf certification reciprocity:Pending mutual recognition agreements between European halal accreditation agencies and Saudi SFDA standards would unlock streamlined export pathways for Southeast Asian manufacturers.
- Vegan-halal convergence:Plant-based certification overlap is creating premium positioning whitespace in specialty retail channels across Malaysia's urban centers.
Industry Challenges
- Cross-contamination protocol validation:Dedicated production line requirements demand capital-intensive facility segregation that strains mid-tier manufacturers serving both halal and conventional cosmetic clients.
- Ingredient traceability system integration:Blockchain and batch-tracking technologies require technical talent scarce in Indonesian supply chain hubs, delaying compliance with tightening JAKIM documentation mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Halal Cosmetic Products Market |
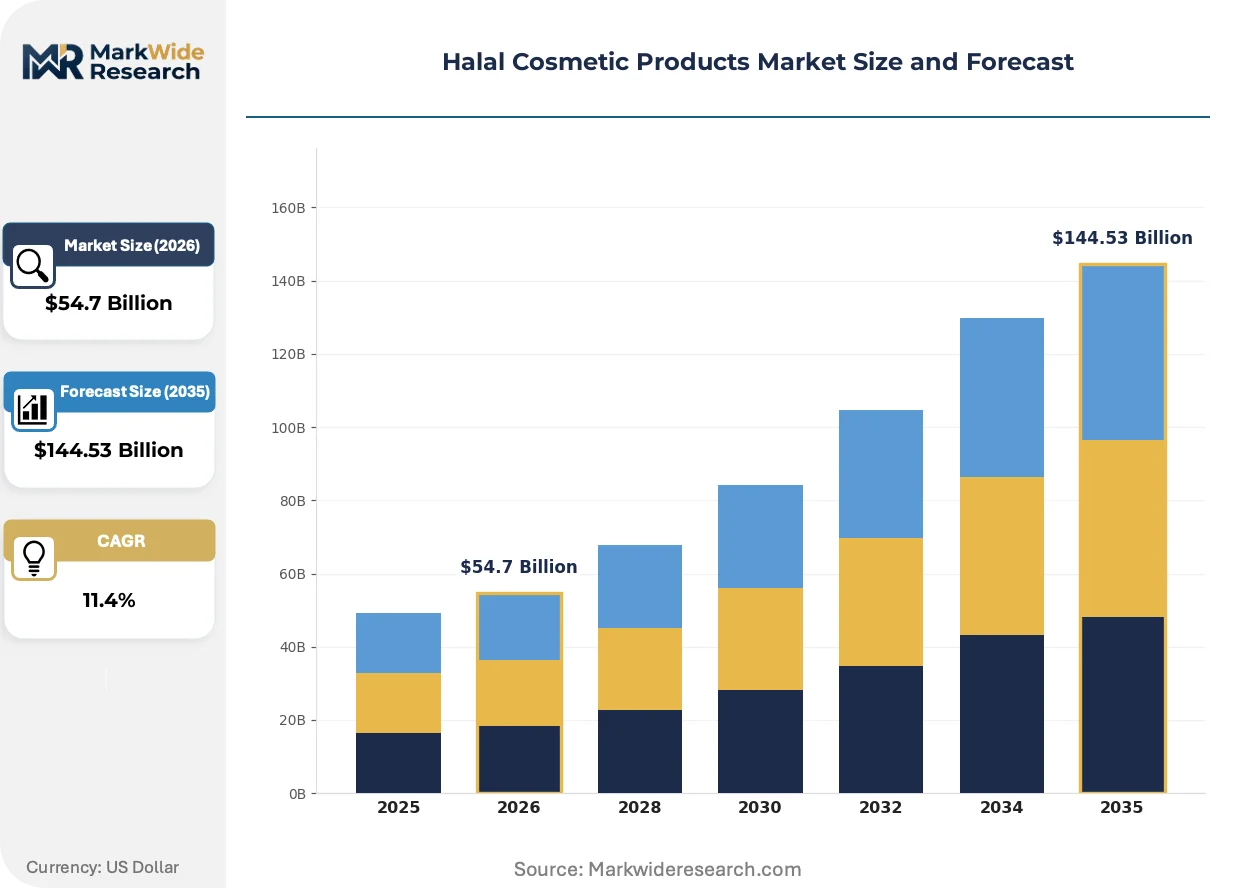
| Market Size in 2026 | $54.7 Billion |
| Market Size in 2035 | $144.53 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Haircare, Makeup, Fragrance Ingredient Type: Natural, Organic, Synthetic, Vegan Distribution Channel: Online, Supermarkets, Specialty Stores, Pharmacies End User: Women, Men, Children, Professionals |
| Companies Covered | Amara Halal Cosmetics, INIKA Organic, Ivy Beauty Corporation, Clara International Beauty Group, Iba Cosmetics, Martha Tilaar Group, Sampure Minerals, PHB Ethical Beauty, Wardah Cosmetics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Halal Cosmetic Products Market Strategic Shifts
Biotechnology-derived alternatives to animal-sourced cosmetic ingredients are compressing the traditional halal certification burden while opening formulation pathways previously blocked by religious compliance constraints.
Enzymatic biocatalysis is decomposing the conventional reliance on chemically synthesized emulsifiers in halal skincare production. Premium Indonesian brands are adopting plant-cell-culture-derived squalane and fermented hyaluronic acid at accelerating rates. This biotechnology shift is decomposing cost barriers that historically confined advanced hydration science to conventional cosmetic lines.
EMA's evolving cosmetic ingredient safety framework is tightening documentation requirements for novel preservatives seeking halal-compliant status in European export markets. The regulation is forcing Southeast Asian manufacturers to front-load toxicology testing investments before market entry. Color cosmetics with extended shelf-life claims face the steepest compliance reconfiguration as EMA scrutiny intensifies on phenoxyethanol alternatives.
Social commerce live-streaming is collapsing traditional pharmacy and supermarket gatekeeper control over halal beauty discovery in Indonesian secondary cities. Young Muslim consumers are bypassing established retail channels for direct-to-brand engagement through TikTok Shop and Instagram checkout. This channel disintermediation is most visible in Jakarta and Surabaya, where influencer-led education drives real-time purchase conversion without physical product handling.
Halal Cosmetic Products Market Segmentation
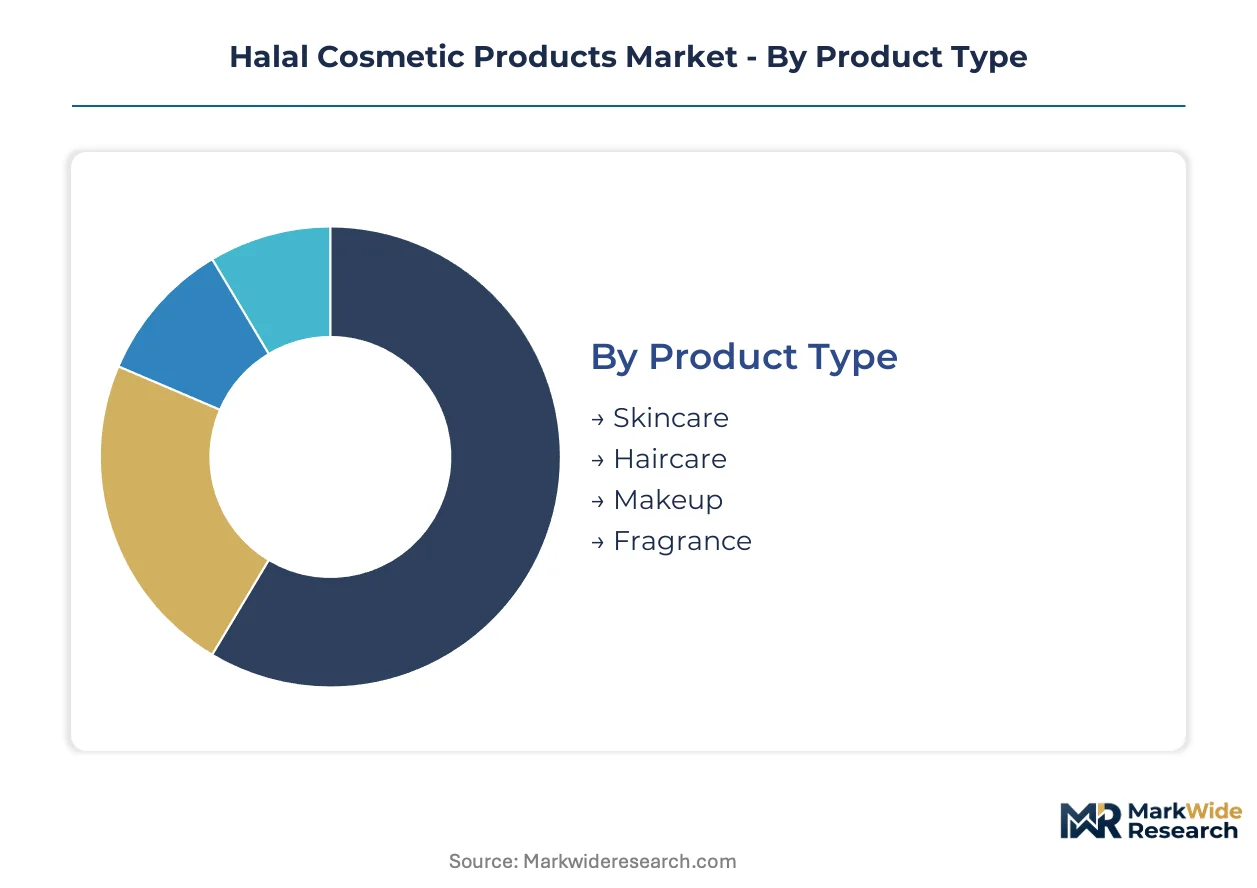
Halal cosmetic segmentation reveals where substitution pressures from conventional beauty products threaten incumbent positioning, and where certification creates defensible market pockets. Distinct demand profiles across product categories, ingredient preferences, and channel behaviors require tailored formulation and distribution strategies.
Product Type:
Skincare faces the strongest substitution threat from conventional hydrating lines, while wudu-compatible formulations create stickiness among practicing Muslim consumers.
- Skincare:Water-permeable emulsions permit ablution without product removal, anchoring daily-use loyalty among observant Muslim women. Demand concentrates in Indonesia's urban centers where pharmacy chains stock dedicated halal moisturizing shelves, though conventional K-beauty imports erode share among less-practicing segments.
- Makeup:Breathable foundations and alcohol-free lip formulations command premium positioning through specialty retail. Indonesian professionals drive color cosmetics trial, with Jakarta's influencer economy accelerating shade-range expansion beyond traditional beige-centric offerings.
- Haircare:Silicone-free conditioners and alcohol-free styling sprays address scalp sensitivity concerns. Malaysian salon channels push professional-grade halal hair treatment adoption.
- Fragrance:Alcohol-free perfume oils and water-based mists substitute for conventional eau de parfum. Gulf export markets favor concentrated attar-style formulations.
Skincare retains volume leadership; Makeup holds the steepest expansion curve.
Ingredient Type:
Cost tier stratification separates mass-market synthetic formulations from premium-positioned botanical and certified-vegan alternatives.
- Natural:Plant-derived emulsifiers and cold-pressed oils dominate mid-tier halal skincare, with Indonesian producers sourcing palm-based ingredients through backward-integrated supply chains. JAKIM traceability mandates are elevating documentation costs for natural claim substantiation.
- Synthetic:Laboratory-engineered preservatives and emollients enable shelf-stable mass production at price points accessible to Southeast Asia's emerging middle class. BPJPH certification timelines compress margin windows for reformulated synthetic lines.
- Organic:Certified organic botanical extracts command specialty store placement in Malaysia's urban centers. Supply concentration among Indonesian archipelago growers creates input cost volatility.
- Vegan:Plant-cell-culture-derived actives and fermented ingredients target premium positioning where halal and vegan certifications overlap. Biotechnology adoption is accelerating among Indonesian premium brands seeking differentiation from conventional halal competitors.
Natural formulations dominate unit economics; Vegan certification is climbing the fastest as a positioning lever.
Distribution Channel:
Geography of customer acquisition is shifting from physical gatekeepers to digital-native discovery platforms.
- Online:TikTok Shop and Instagram checkout collapse trial barriers for emerging Indonesian brands, with influencer-curated subscription boxes converting discovery into recurring revenue. Secondary cities bypass traditional retail infrastructure entirely through social commerce live-streaming.
- Specialty Stores:Premium halal beauty boutiques in Kuala Lumpur and Jakarta offer product education and shade-matching services unavailable in mass retail. Vegan-halal convergence products concentrate in this channel.
- Supermarkets:Wardah Cosmetics anchors Indonesia's mass-market shelf presence through deep penetration of Indomaret and Alfamart chains. Price competition with conventional beauty imports constrains margin expansion.
- Pharmacies:Dermatologist-recommended halal skincare lines leverage professional credibility in Malaysia's Guardian and Watsons networks. Wudu-compatible claims receive clinical validation support in this channel.
Supermarkets retain volume leadership; Online channels are gaining share fastest through demographic tailwinds.
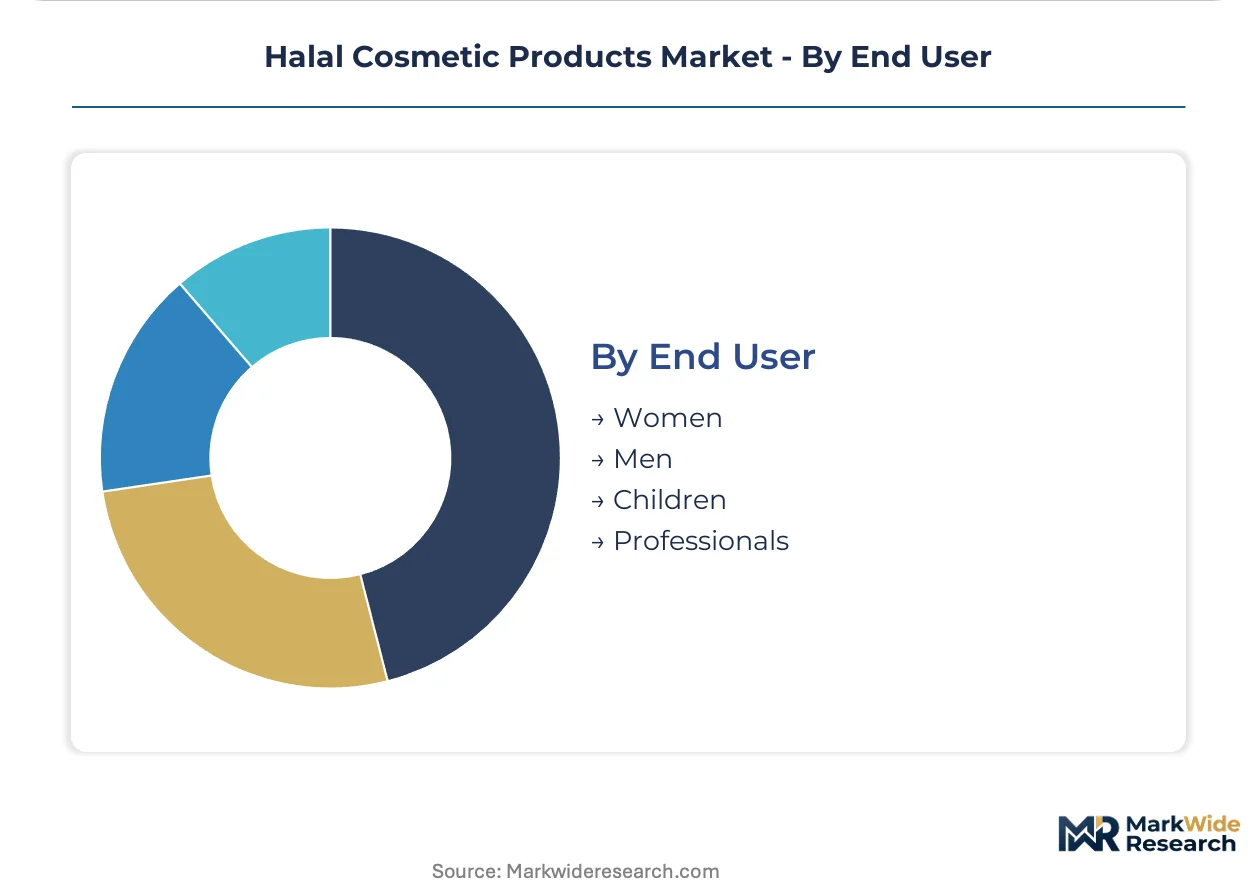
End User:
Customer type maturity varies sharply, with professional segments exhibiting brand exploration behavior distinct from family-unit purchasing traditions.
- Women:Practicing Muslim women across Southeast Asia drive core demand for wudu-compatible daily routines, with generational divergence between tradition-bound family purchasers and autonomous Gen Z brand explorers.
- Professionals:Young Muslim white-collar workers in Jakarta and Surabaya decouple cosmetic decisions from household purchasing, accelerating premium color cosmetics adoption and individual brand trial.
- Men:Halal grooming lines remain underdeveloped relative to women's categories, though beard care and alcohol-free toners show nascent demand concentration in Malaysian urban markets.
- Children:Sensitive-skin formulations with simplified ingredient lists address parental safety concerns. Pharmacy channels dominate this low-volume, high-trust segment.
Women retain volume leadership; Professionals are expanding most quickly as autonomous purchasing behavior normalizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Tanjung Priok in Jakarta anchors Southeast Asia's halal cosmetic trade flows, connecting Indonesian manufacturing clusters to Gulf export markets through dedicated cold-chain logistics corridors.
Indonesia
Jakarta and Surabaya drive domestic demand concentration as young professionals decouple purchasing from family units. BPJPH's 2024 mandatory halal certification deadlines compel reformulation investments across the supply chain. The Jababeka Industrial Estate outside Jakarta hosts concentrated contract manufacturing capacity serving both local brands and multinational entrants.
Malaysia
Kuala Lumpur's urban consumer base prioritizes premium positioning where vegan and halal certifications overlap. JAKIM maintains the region's most stringent traceability mandates, with 6-12 month approval cycles for new manufacturing facilities. The Shah Alam industrial corridor retains validated production lines that disadvantage new entrants against established domestic producers.
Saudi Arabia
Riyadh and Jeddah concentrate Gulf demand for alcohol-free fragrance oils and concentrated attar-style formulations. SFDA standards negotiation with Southeast Asian halal bodies remains stalled, forcing parallel compliance tracks. The King Abdullah Economic City logistics hub channels Indonesian and Malaysian imports into domestic distribution networks.
United Arab Emirates
Dubai's retail infrastructure serves as the regional gateway for halal beauty brands seeking Gulf market entry. MOHAP cosmetic safety frameworks add compliance layers beyond halal certification requirements. The Jebel Ali Free Zone concentrates re-export warehousing for products destined for broader Middle Eastern and North African markets.
United Kingdom
London's Muslim consumer base drives niche demand for premium halal-certified color cosmetics through specialty retail channels. REACH compliance creates additional reformulation obligations for Southeast Asian manufacturers seeking European market access. The East Midlands logistics cluster handles bulk import distribution for brands penetrating the broader UK market.
Halal Cosmetic Products Market Competitive Environment
Concentration sits with established Southeast Asian producers possessing backward-integrated supply chains and validated halal certification infrastructure. The market structure fragments across three tiers: mass-market pharmacy and supermarket brands, premium specialty retail positioning, and emerging direct-to-consumer digital natives. Two strategic archetypes dominate competitive positioning—botanical sourcing integrators controlling input costs, and influencer-marketed digital brands collapsing traditional retail gatekeepers. Capacity expansion and certification reciprocity partnerships constitute the dominant competitive moves as manufacturers prepare for Gulf market standardization.
Among Indonesia-based producers, Wardah Cosmetics and Martha Tilaar Group exemplify contrasting archetypes within the same geography. Wardah occupies the mass-market penetration position through deep pharmacy and supermarket channel presence. Martha Tilaar represents the botanical integration model with captive sourcing from Indonesian archipelago suppliers. INIKA Organic anchors the premium-tier vector as an Australian-originated specialist in vegan-certified color cosmetics, demonstrating how halal-vegan convergence creates defensible positioning in specialty retail channels. These three sit within distinct competitive spaces rather than direct confrontation, with Wardah defending volume leadership, Martha Tilaar sustaining margin control, and INIKA commanding price premiums through certification overlap.
| Leading Market Players |
|---|
| Amara Halal Cosmetics |
| INIKA Organic |
| Ivy Beauty Corporation |
| Clara International Beauty Group |
| Iba Cosmetics |
| Martha Tilaar Group |
| Sampure Minerals |
| PHB Ethical Beauty |
| Wardah Cosmetics |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Indonesian botanical suppliers and halal-certified manufacturers lock in both palm-derived emulsifier access and input cost visibility across multi-year production cycles. These arrangements insulate backward-integrated producers like Martha Tilaar Group from weather-driven price spikes while compressing margin flexibility for spot-market-dependent competitors serving mass retail channels.
Pricing Analysis
Volume-discount tiering structures separate mass-market pharmacy brands from premium specialty retail positioning. Three-tier pricing stratifies across vegan-halal convergence products, standard JAKIM-certified lines, and economy synthetic formulations. Price differentiation hinges on certification grade and botanical sourcing depth. Pricing pressure stems from BPJPH compliance investments converting informal producers into certified competitors. Mass-market supermarket buyers exhibit highest price sensitivity; premium specialty consumers show lowest elasticity.
Supply Chain Analysis
Inventory lead times for Indonesian archipelago-sourced exotic plant extracts stretch manufacturing planning horizons and elevate working capital requirements. Supply concentrates in Indonesia, Malaysia, and select Australian botanical growers. Raw material dependencies center on palm-derived emulsifiers, cold-pressed oils, and plant-cell-culture actives. Single-source vulnerability from concentrated Indonesian archipelago sourcing creates disruption exposure. Distribution runs through pharmacy and supermarket chains for mass brands, with direct-to-consumer social commerce gaining fastest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward autonomous Gen Z professionals decoupling from family-unit purchasing, fragmenting traditional channel gatekeeper control and compressing brand loyalty cycles among emerging demographic cohorts.
For Market Incumbents: Compound certification infrastructure advantages by accelerating JAKIM and BPJPH reciprocity negotiations before Gulf standardization solidifies. Deepen backward integration into Indonesian botanical sourcing to defend margin position against reformulation cost spikes from mandatory halal deadlines. Prioritize wudu-compatible formulation R&D as Korean beauty imports threaten skincare substitution. For New Entrants and Emerging Players: Differentiate on vegan-halal convergence certification to access premium specialty retail whitespace in Kuala Lumpur and Jakarta. Target underpenetrated male grooming segments where alcohol-free toners and beard care show nascent demand concentration. Deploy influencer-curated subscription boxes as primary go-to-market vehicle collapsing traditional retail trial barriers. For Investors and Strategic Acquirers: Botanical-integrated mid-tier manufacturers with validated JAKIM production lines represent the most defensible acquisition profile as certification timelines disadvantage greenfield entrants. Long-term viability centers on Gulf market access through pending SFDA reciprocity agreements. Watch for mutual recognition breakthroughs between Southeast Asian halal bodies and Saudi standardization organizations as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Reciprocity Partnership | Unlocks streamlined Gulf export pathways for JAKIM-validated Indonesian manufacturers. |
| Backward Integration into Botanical Sourcing | Captive supply chains insulate margin control from weather-driven input volatility. |
| Direct-to-Consumer Social Commerce Launch | TikTok Shop and Instagram checkout collapse pharmacy gatekeeper control over discovery. |
| Vegan-Halal Convergence Product Line | Dual certification creates premium positioning whitespace in Malaysia's urban specialty retail. |
| Wudu-Compatible Formulation R&D Investment | Water-permeable emulsions deepen daily-use loyalty among practicing Muslim women. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, with halal brand managers, JAKIM certification officers, pharmacy chain category buyers, and Indonesian contract manufacturing executives providing operational perspective. Secondary validation drew from BPJPH regulatory filings, JAKIM halal registry databases, Indonesian customs export records, and Southeast Asian retail audit data. Bottom-up demand modeling and top-down supply capacity assessments were triangulated to anchor projections.
Across the analysis window, the forecasting framework modeled product type segmentation, ingredient preference tiers, distribution channel evolution, and end-user demographic divergence. CAGRs were derived from segment-level growth trajectory analysis incorporating certification penetration curves and channel shift dynamics. Wudu-compatible formulation adoption rates and social commerce penetration velocity served as key demand-side inputs.
Forecasts assume regulatory continuity in JAKIM, BPJPH, and EMA cosmetic frameworks; material policy shifts in halal certification reciprocity or ingredient safety documentation would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
United Arab Emirates Cosmetic Products Market
Cosmetics & Skincare
Global Cosmetic Shea Butter Market
Cosmetics & Skincare
Asia-Pacific Cosmetics Market
Cosmetics & Skincare
Italy Lip Care Products Market
Cosmetics & Skincare
Herbal Soap Market
Cosmetics & Skincare
Lipstick Market
Cosmetics & Skincare
Probiotic Skin Care Cosmetic Product Market
Cosmetics & Skincare
North America Bath Soap Market
Cosmetics & Skincare
Organic Soaps Market
Cosmetics & Skincare
J-Beauty Products Market
Cosmetics & Skincare
Israel Cosmetics Products Market
Cosmetics & Skincare
Skin Care Products Market
Cosmetics & Skincare
Bath Soap Market
Cosmetics & Skincare
Reusable Makeup Remover Pad Market
Cosmetics & Skincare
Retinol Eye Cream Market
Cosmetics & Skincare
Japan Organic Cosmetics Market