
 Lactose-Free Cheese Market | 2026-2036
Lactose-Free Cheese Market Size, Share, and Industry Trends Forecast 2026-2036
Lactose-Free Cheese Market Foresight
Retail private-label development is rewriting margin distribution across the lactose-free cheese value chain. Arla Foods amba leverages its European dairy infrastructure to sustain cost advantages in enzymatic processing. Miyoko's Creamery differentiates through cultured cashew and oat-based formulations that command premium positioning in specialty channels.
Lactose-free cheese denotes dairy or plant-based cheese products containing negligible lactose, typically achieved through enzymatic conversion of lactose into glucose and galactose or through non-dairy fermentation processes, with protein content and melt functionality serving as critical quality parameters for foodservice applications. Slices and shreds lead volume due to their compatibility with quick-service restaurant operations and home meal preparation, while cream cheese represents the fastest-growing product type as bagel chains and bakery applications expand allergen-friendly menus. Vacuum packs capture disproportionate margin pools by extending shelf life and reducing cold-chain spoilage in export channels.
FDA labeling requirements for lactose content claims and the USDA organic certification framework shape product formulation standards and market access conditions in the United States, while EFSA thresholds for lactose-free claims govern European export eligibility. The EU Green Deal's agricultural sustainability targets are pressuring dairy processors to document enzymatic treatment energy intensity and wastewater profiles. Stakeholders must monitor evolving enzyme supplier consolidation and plant-based ingredient cost curves to calibrate portfolio balance between dairy-derived and fermentation-derived alternatives.
Market Dynamics
Enzymatic lactose hydrolysis technology is compressing production costs while plant-based fermentation methods are fragmenting supplier tiers, forcing traditional dairy processors to defend margin pools through backward integration into enzyme supply chains.
Growth Catalysts
- Bagel chain expansion:Specialty bakery applications are absorbing cream cheese volumes at accelerated rates as allergen-friendly menu mandates spread across quick-service formats.
- USDA organic certification:Premium positioning through dual lactose-free and organic claims is unlocking shelf space in conventional retail channels previously closed to specialty dairy.
- Vacuum packaging technology:Extended shelf-life formats are reducing cold-chain spoilage losses in export corridors, particularly for enzymatically treated hard cheese varieties.
Market Restraints
- Enzyme supplier concentration:Three European biotechnology firms control the majority of commercial lactase supply, exposing processors to input cost volatility during fermentation batch shortages.
- Protein functionality gaps:Plant-based formulations fail to replicate casein melt elasticity in high-heat foodservice applications, limiting penetration in pizza and grilled sandwich segments.
- FDA labeling friction:Disputes over "lactose-free" versus "low-lactose" threshold definitions create compliance uncertainty for cross-border shipments between the United States and Canada.
Strategic Opportunities
- Foodservice distribution bypass:Direct-to-restaurant enzyme-treated bulk formats are circumventing traditional dairy distributor markups in metropolitan clusters.
- EU Green Deal alignment:Documented energy intensity reductions in enzymatic processing are qualifying processors for agricultural sustainability incentives under the EU Green Deal agricultural targets.
- Aged cheese white space:Extended curing protocols that naturally degrade residual lactose remain underexploited in cheddar and gouda categories, offering clean-label alternatives to enzymatic intervention.
Industry Challenges
- Fermentation science talent scarcity:Cross-disciplinary expertise spanning dairy microbiology and plant protein chemistry commands premium compensation, constraining R&D throughput at mid-scale processors.
- Dual certification timelines:Simultaneous pursuit of kosher, halal, and organic credentials extends product launch windows by 8-14 months, compressing first-mover advantage windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lactose-Free Cheese Market |
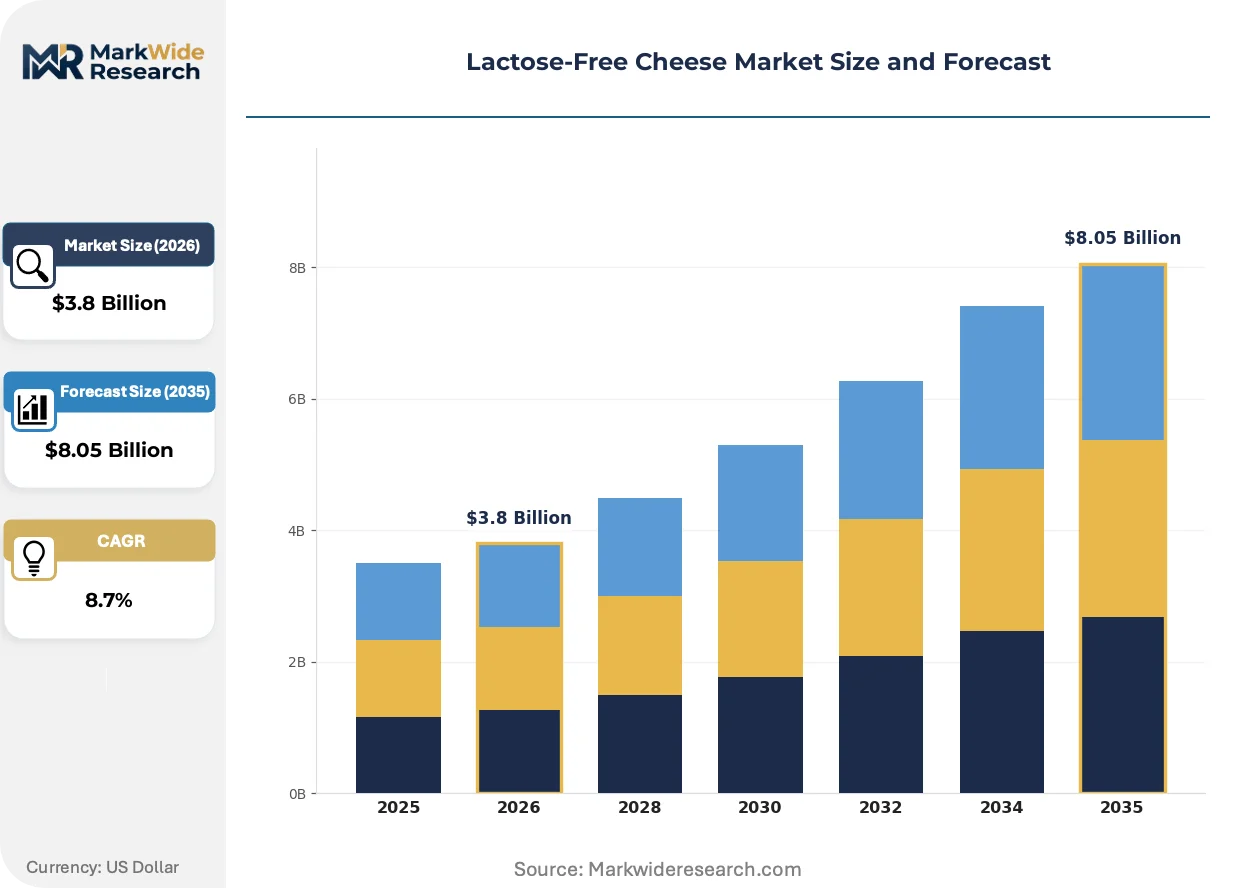
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Slices, Shreds, Blocks, Cream Cheese Packaging Type: Tubs, Sachets, Pouches, Vacuum Packs Sales Channel: Supermarkets, Health Stores, Online Retail, Specialty Stores End User: Households, Restaurants, Cafes, Food Manufacturers |
| Companies Covered | Arla Foods amba, Daiya Foods, Miyoko's Creamery, Violife, Kite Hill, Follow Your Heart, Treeline Cheese, Alpro, Prairie Farms Dairy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lactose-Free Cheese Market Shifts & Advancements
Production technology is bifurcating between precision enzymatic systems and novel fermentation platforms, while regulatory frameworks on both sides of the Atlantic are hardening around residual lactose thresholds and sustainability documentation requirements.
Precision fermentation using engineered microbial strains is migrating from pharmaceutical applications into dairy protein synthesis. Specialty cheese manufacturers in the Netherlands and Denmark are piloting these platforms at commercial scale. The technology is compressing the cost gap between animal-derived and fermentation-derived casein, threatening to displace traditional enzymatic hydrolysis in premium segments within the forecast window.
EFSA threshold harmonization for lactose-free claims is tightening residual sugar limits across European export markets. Processors must now validate sub-0.01% lactose content through third-party laboratory certification to maintain market access. Hard cheese categories with naturally low residual sugars are capturing disproportionate investment as enzymatic treatment costs rise under stricter verification protocols.
Quick-service restaurant procurement is consolidating supplier bases around dual-capability vendors offering both dairy-derived and plant-based formats. Chains with allergen-friendly menu mandates are demanding single-source accountability for cross-contamination protocols. This consolidation is most visible in United States coastal metropolitan markets where labor regulations accelerate kitchen simplification pressures.
Lactose-Free Cheese Market Segmentation
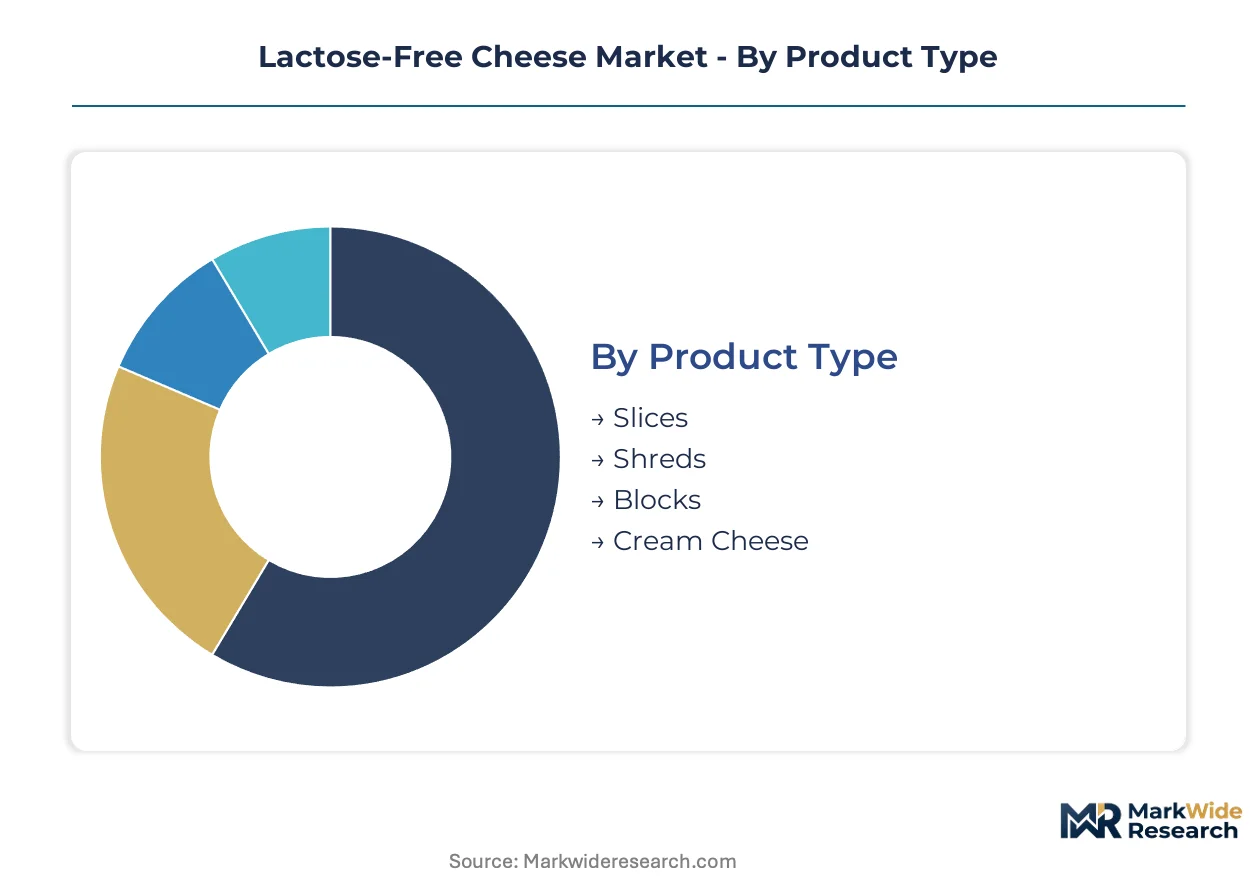
Segmentation in the lactose-free cheese market reveals distinct velocity profiles across product formats and channel structures. Understanding turnover differentials between convenience-oriented and specialty formats enables targeted inventory and margin strategies.
Product Type:
Cycle times vary dramatically across formats, with quick-service compatibility driving rapid inventory turns versus aged varieties that tie up working capital.
- Slices:Thin-cut formats engineered for melt consistency in sandwich applications dominate quick-service procurement. United States bagel chains and deli operators absorb volumes through direct distribution agreements that bypass traditional dairy wholesalers.
- Cream Cheese:Cultured spreads with stabilized fat matrices command premium positioning in bakery and breakfast channels. United States coastal metropolitan markets show steepest expansion as allergen-friendly menu mandates spread through regional chain networks.
- Shreds:Pre-grated mozzarella and cheddar blends optimized for pizza topping coverage.
- Blocks:Unprocessed wheels requiring end-user cutting equipment, concentrated in specialty retail and foodservice bulk purchasing.
Slices anchor the volume base while cream cheese gains share at the steepest rate.
Packaging Type:
Cost tiers separate commodity formats from engineered barrier solutions that protect enzymatic integrity through extended distribution.
- Vacuum Packs:Multi-layer barrier films with oxygen scavenging layers extend shelf life from 45 to 120 days for hard cheese varieties. Export corridors from Denmark and the Netherlands rely on this format to reduce cold-chain spoilage losses during transatlantic shipment.
- Tubs:Polypropylene containers with modified atmosphere sealing dominate cream cheese and spreadable formats. United States retail chains specify tamper-evident closures that add unit cost but reduce shrinkage in self-service dairy cases.
- Sachets:Single-serve portions for foodservice condiment dispensers and airline catering.
- Pouches:Flexible stand-up bags with resealable zippers for shredded cheese retail formats.
Vacuum packs dominate export value while tubs capture the highest unit volumes in domestic retail.
Sales Channel:
Customer type stratification shows household purchasers favoring convenience formats while institutional buyers prioritize bulk consistency and certification documentation.
- Supermarkets:Conventional grocery chains with dedicated dairy alternative sections now stock lactose-free cheese alongside conventional dairy. United States retailers with private-label programs are rewriting margin distribution by sourcing directly from enzymatic processors.
- Online Retail:Direct-to-consumer platforms with cold-chain logistics capabilities serve households in underserviced postal codes. Subscription models for specialty formats are climbing fastest in United States suburban markets with limited health store penetration.
- Health Stores:Natural product retailers with certified organic requirements and non-GMO verification protocols.
- Specialty Stores:European-style cheese shops with aged variety focus and staff-assisted purchasing.
Supermarkets anchor volume while online retail expands most quickly through subscription mechanics.
End User:
Application concentration varies by heat stress requirements, with food manufacturers demanding casein functionality that plant-based alternatives fail to replicate.
- Restaurants:Full-service and quick-service operators with allergen-friendly menu mandates specify dual dairy-derived and plant-based supply for kitchen simplification. United States coastal metropolitan procurement offices are consolidating supplier bases around single-source accountability for cross-contamination protocols.
- Food Manufacturers:Frozen pizza and prepared meal producers require enzymatically treated hard cheese with validated sub-0.01% lactose content for EFSA-compliant export eligibility. Protein melt elasticity specifications limit plant-based penetration in this segment.
- Households:Home meal preparation with convenience-oriented slice and shred formats.
- Cafes:Coffee-shop chains with pastry and breakfast sandwich programs.
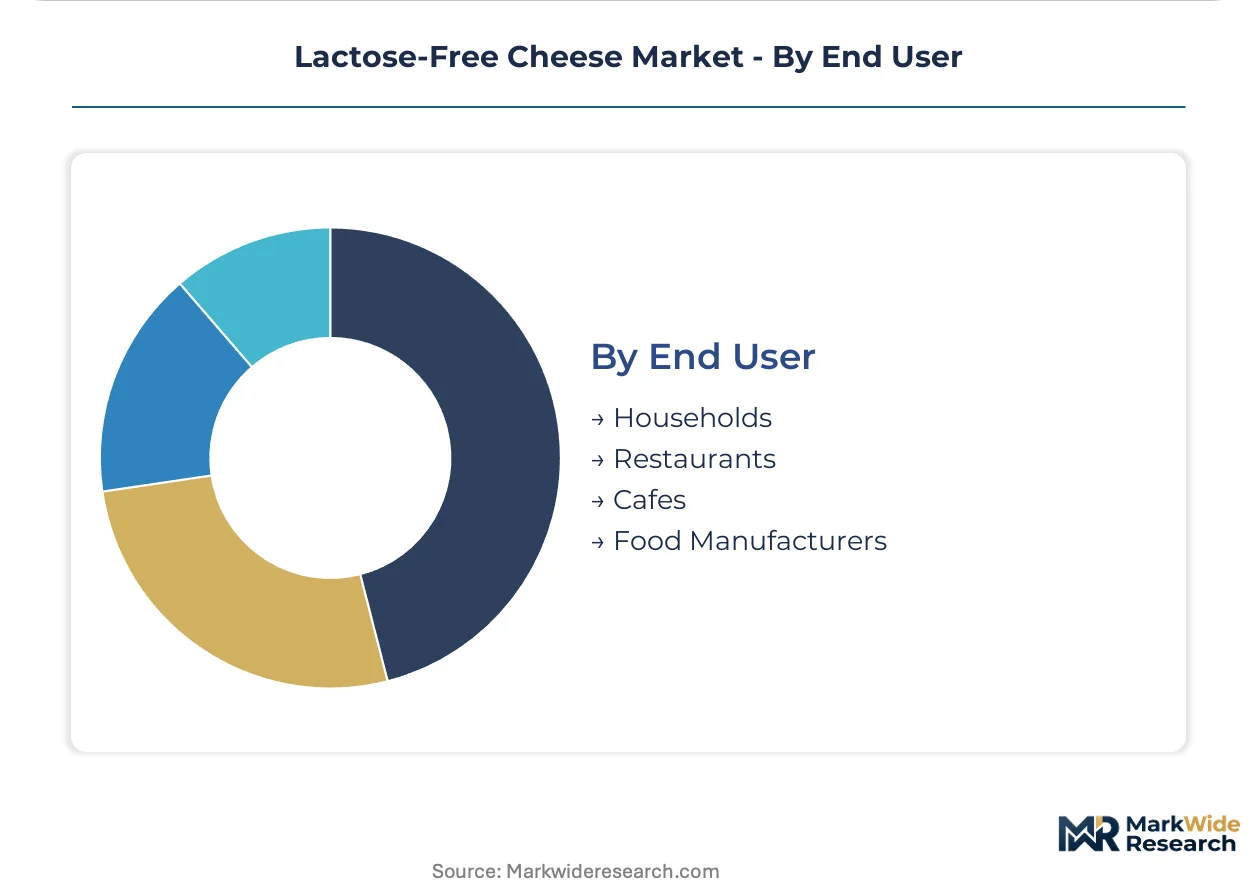
Restaurants anchor current volume while food manufacturers show steepest expansion trajectory through prepared meal channel growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Households in the United States absorb lactose-free cheese at price premiums that European buyers reject, while export corridors from Denmark and the Netherlands compete on shelf-life engineering rather than brand recognition.
United States
Bagel chains and quick-service deli operators specify dual-format supply contracts that simplify kitchen operations. FDA labeling requirements for lactose content claims create compliance friction with Canadian cross-border shipments. The New York metropolitan corridor concentrates procurement offices that consolidate supplier bases around single-source accountability protocols.
Germany
Conventional grocery chains with private-label programs rewrite margin distribution by sourcing directly from enzymatic processors. The EU Green Deal's agricultural sustainability targets pressure dairy processors to document treatment energy intensity. The Bavarian dairy belt hosts enzymatic treatment facilities that serve export markets through Rotterdam port logistics.
Denmark
Precision fermentation pilots using engineered microbial strains compress cost gaps between animal-derived and fermentation-derived casein. EFSA threshold harmonization for lactose-free claims tightens residual sugar limits across European export markets. Copenhagen-area biotechnology clusters attract talent spanning dairy microbiology and plant protein chemistry.
Netherlands
Vacuum packaging technology with multi-layer barrier films extends shelf life for hard cheese varieties bound for transatlantic shipment. EFSA verification protocols for sub-0.01% lactose content raise enzymatic treatment costs. The Gouda-Rotterdam industrial corridor specializes in aged curing protocols that naturally degrade residual lactose.
United Kingdom
Natural product retailers with certified organic requirements and non-GMO verification protocols capture premium positioning through dual lactose-free and organic claims. Post-Brexit regulatory divergence from EFSA thresholds creates certification complexity for exporters. London and Southeast England concentrate specialty retail channels with staff-assisted purchasing formats.
Lactose-Free Cheese Market Competitive Landscape
Capability concentration sits with biotechnology specialists mastering enzymatic hydrolysis; scale advantage sits with diversified dairy processors leveraging existing cold-chain infrastructure. The vendor base separates into three tiers: European dairy cooperatives with backward integration into enzyme supply chains, plant-based fermentation startups commanding premium positioning in specialty channels, and private-label contract manufacturers serving retail consolidation. Dominant competitive moves include direct-to-restaurant distribution bypass in metropolitan clusters and simultaneous pursuit of kosher, halal, and organic credentials that extend product launch windows.
Among European dairy cooperatives, Arla Foods amba anchors the scale-driven tier with infrastructure spanning enzymatic processing and retail private-label development. Miyoko's Creamery and Violife occupy positions within the plant-based fermentation segment, exemplifying cultured cashew and oat-based formulations that command premium shelf space in United States coastal metropolitan markets. These three names illustrate the structural bifurcation between dairy-derived enzymatic processing and novel fermentation platforms reshaping competitive positioning.
| Leading Market Players |
|---|
| Arla Foods amba |
| Daiya Foods |
| Miyoko's Creamery |
| Violife |
| Kite Hill |
| Follow Your Heart |
| Treeline Cheese |
| Alpro |
| Prairie Farms Dairy |
| Others |
Supply & Pricing Matrix
The Bavarian dairy belt's enzymatic processing capacity concentration translates directly into downstream pricing leverage for hard cheese exports. FDA and EFSA certification tiers stratify contract structures, with vacuum-packed formats commanding sustained premiums against commodity tub packaging.
Pricing Analysis
Long-term offtake agreements dominate institutional procurement, locking in volume commitments from United States bagel chains and European retail private-label programs. Price differentiation rests on dual lactose-free and organic certification premiums versus standard enzymatic treatment tiers. Cost compression in plant-based alternatives is intensifying because precision fermentation pilots erode casein cost advantages. Quick-service restaurant procurement offices show highest price sensitivity, while specialty retailers with staff-assisted purchasing absorb premium positioning.
Supply Chain Analysis
Upstream feedstock flows from Danish and Dutch dairy cooperatives with backward integration into lactase enzyme supply chains. Raw material dependencies center on fermentation-derived microbial strains, multi-layer barrier films for vacuum packaging, and organic-certified milk solids. Single-source vulnerability concentrates in three European biotechnology firms controlling commercial lactase supply. Distribution runs through Rotterdam port logistics for transatlantic export corridors and direct-to-restaurant metropolitan bypass channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated quick-service restaurant procurement offices that demand single-source accountability for cross-contamination protocols. United States coastal metropolitan markets exemplify this consolidation, compressing supplier margins through volume concentration.
For Market Incumbents: Entrench defensive positions through captive enzyme supply arrangements and accelerated kosher-halal-organic triple certification timelines. Precision fermentation startups threaten premium segment displacement; counter by locking in aged cheese curing protocols that naturally degrade residual lactose without enzymatic intervention costs.
For New Entrants and Emerging Players: Build out white-space presence in aged cheddar and gouda categories where extended curing protocols meet clean-label demand. The most penetrable segment sits in United States suburban markets with limited health store penetration, served through subscription-based direct-to-consumer cold-chain platforms.
For Investors and Strategic Acquirers: Long-term, this sits as a sustainability-documentation play because EU Green Deal agricultural incentives reward processors with verified energy intensity reductions in enzymatic treatment. Target acquisition archetypes include mid-scale processors with documented wastewater profiles and existing organic certification infrastructure. Watch for enzyme supplier consolidation announcements as inflection indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Enzyme Supply | Captive lactase production insulates Arla Foods amba from fermentation batch shortage volatility. |
| Precision Fermentation Scale-Up | Engineered microbial strain platforms threaten to displace traditional enzymatic hydrolysis in premium segments. |
| Triple Certification Investment | Simultaneous kosher, halal, and organic credentials unlock previously closed conventional retail shelf space. |
| Direct-to-Restaurant Distribution | Metropolitan bulk format bypass circumvents traditional dairy distributor markups in United States coastal clusters. |
| Vacuum Packaging Technology Expansion | Multi-layer barrier films with oxygen scavenging layers reduce cold-chain spoilage in transatlantic export corridors. |
Research Methodology
A standing panel of enzymatic processing plant managers, quick-service restaurant procurement directors, retail category buyers, and specialty cheese shop operators provided ongoing calibration. Primary interviews combined with secondary validation from FDA labeling guidance documents, EFSA threshold determinations, EU Green Deal agricultural sustainability reports, and customs trade data for dairy alternative exports. Bottom-up volume modeling and top-down value triangulation anchored the analytical framework.
Scenario-bracketing across enzymatic cost compression trajectories and precision fermentation adoption curves bounded the projection horizon. Segmentation dimensions modeled include product format, packaging barrier technology tier, sales channel structure, and end-user heat-stress requirements. CAGRs derived from fitted growth curves applied to validated baseline volumes. Industry-specific inputs incorporated enzyme supplier concentration indices and EFSA verification protocol cost escalations.
Stress conditions across lactase input price volatility, transatlantic shipping rate fluctuations, and plant-based protein functionality breakthroughs were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory threshold stability and sustainability incentive continuity. Cross-checking against Nielsen retail audit data for United States dairy alternative shelf velocity is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Europe Chocolate Milk Market
Dairy Products
Condensed Whey Market
Dairy Products
Oman Dairy Products and Juice Market
Dairy Products
Cheese Crumbles Market
Dairy Products
Fat-Rich Dairy Products Market
Dairy Products
Cheese Shreds Market
Dairy Products
Asia-Pacific Casein and Caseinates Market
Dairy Products
Sweet Whey Market
Dairy Products
Paneer Market
Dairy Products
Global Yogurt Market
Dairy Products
Recombined Milk Products Market
Dairy Products
Textured Butter Market
Dairy Products
North America Cheese Market
Dairy Products
Hydrolyzed Casein Market
Dairy Products
Asia-Pacific Dairy Market
Dairy Products
Dairy Based Dressings Market