
 UHT Milk Market | 2026-2036
UHT Milk Market Size, Share, and Industry Trends Forecast 2026-2036
UHT Milk Market Intelligence
Market Context
European dairy cooperatives is rebalancing processing capacity toward longer-life formats as energy costs pressure fresh milk margins. Arla Foods leverages its Scandinavian farmer-owned structure to secure raw milk supply for UHT conversion. Nestlé anchors its position through pediatric and fortified UHT lines in tropical markets. Lactalis dominates Southern European private-label production with integrated packaging operations.
Technical Definition and Segment Structure
UHT milk is liquid dairy product heat-treated at temperatures exceeding 135 degrees Celsius for 1-3 seconds, then aseptically packaged to achieve ambient shelf stability for 6-12 months without refrigeration. Whole milk and semi-skimmed milk variants lead volume due to caloric preference in developing markets, while skimmed milk concentrates margin pools in health-positioned channels. Tetra Packs and cartons command packaging share because aseptic laminate technology blocks light and oxygen ingress, though pouches are gaining traction in price-sensitive African and South Asian retail environments.
Regulatory Frame and Outlook
The EU EFSA and ECHA govern migration limits for packaging adhesives and chemical residues in UHT contact materials, while the FDA and USDA set Grade A pasteurized milk ordinances that UHT imports must satisfy for US market access. India's FSSAI enforces microbial and additive standards that foreign suppliers navigate through joint ventures with domestic dairies like Yili Group and China Mengniu Dairy. Stakeholders must monitor how carbon border adjustments and single-use packaging bans in the EU Green Deal reshape aseptic carton material sourcing and recycling economics.
Market Dynamics
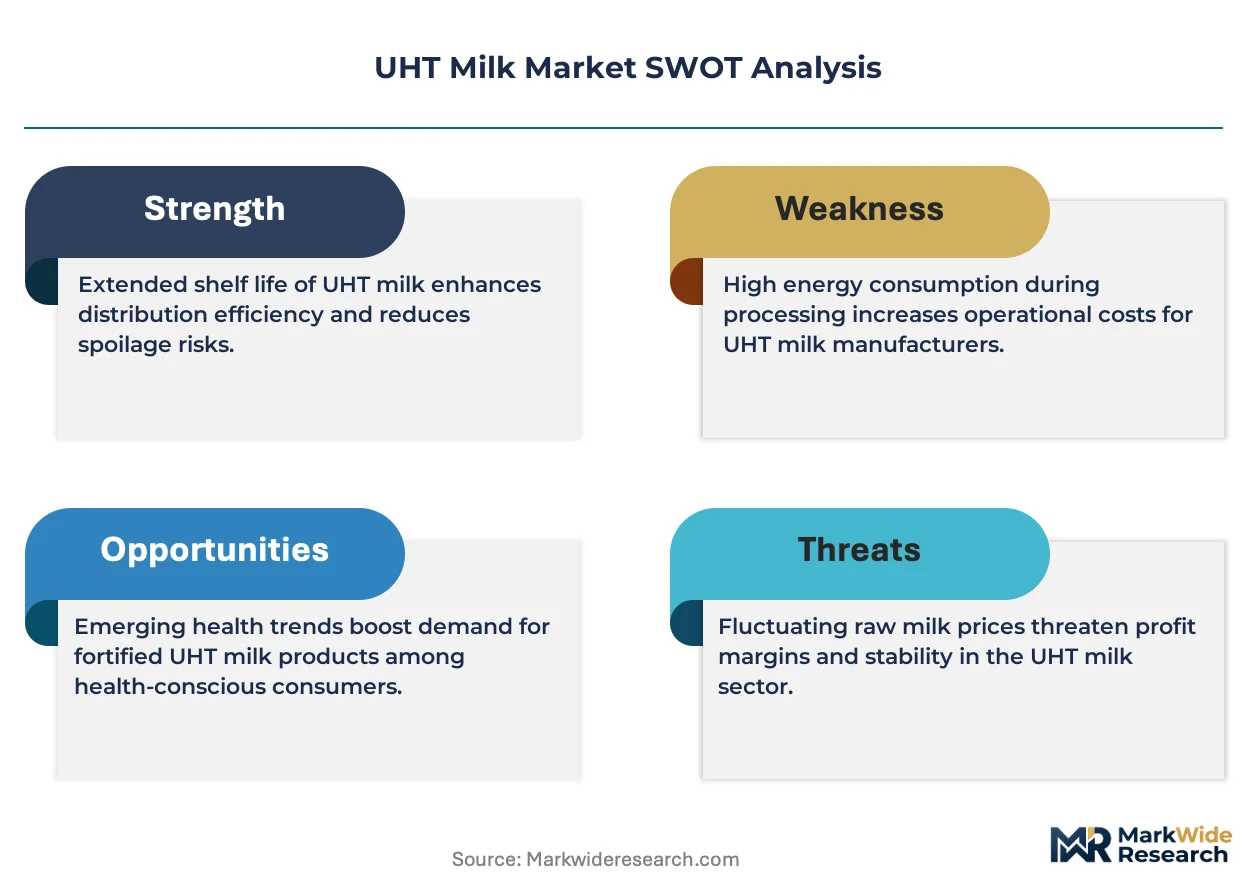
EU F-Gas Regulation phase-down mandates are forcing dairy processors to abandon hydrofluorocarbon-based refrigeration in favor of ammonia and CO2 systems, compressing operating margins while extending asset replacement cycles across European UHT facilities.
Growth Catalysts
- Rural Cold Chain Gaps:India's inadequate refrigerated distribution infrastructure makes ambient-stable UHT formats essential for protein access in villages beyond the milk-shed radius.
- REACH Packaging Compliance:Stricter migration limits for adhesives and laminates in aseptic cartons are accelerating material science investment that improves shelf-life extension.
- Energy Cost Divergence:Natural gas price volatility in Europe is tilting processing economics toward longer-life formats that reduce per-unit pasteurization frequency.
Market Restraints
- Tetra Pak Supply Concentration:Aseptic carton equipment and laminate supply remains captive to a narrow supplier base, creating single-source vulnerability for mid-scale processors.
- Raw Milk Input Volatility:Feed cost inflation and weather-driven yield swings in New Zealand and Argentina transmit directly to UHT conversion margins without short-term hedge mechanisms.
- Fresh Milk Substitution:Cold chain improvements in urban China and Brazil enable pasteurized milk to reclaim share among premium-positioned consumers.
Strategic Opportunities
- Fortified Pediatric Positioning:Vitamin D and iron-enriched UHT lines targeting stunting reduction programs in Nigeria and Indonesia open institutional procurement channels.
- Pouch Format Penetration:Flexible aseptic pouches at lower per-unit packaging cost are capturing price-sensitive African retail segments previously unserved by carton economics.
- EU Green Deal Tailwinds:Carbon border adjustment mechanisms and single-use packaging bans create first-mover advantage for processors with certified recyclable laminate supply chains.
Industry Challenges
- Aseptic Engineering Talent Scarcity:Specialized technicians capable of maintaining 135-degree Celsius sterilization lines and sterile zone integrity remain concentrated in Northern European dairy clusters.
- Legacy System Integration:Retrofitting existing pasteurization plants for UHT conversion requires simultaneous overhaul of filling, sealing, and packaging lines without production halt.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UHT Milk Market |
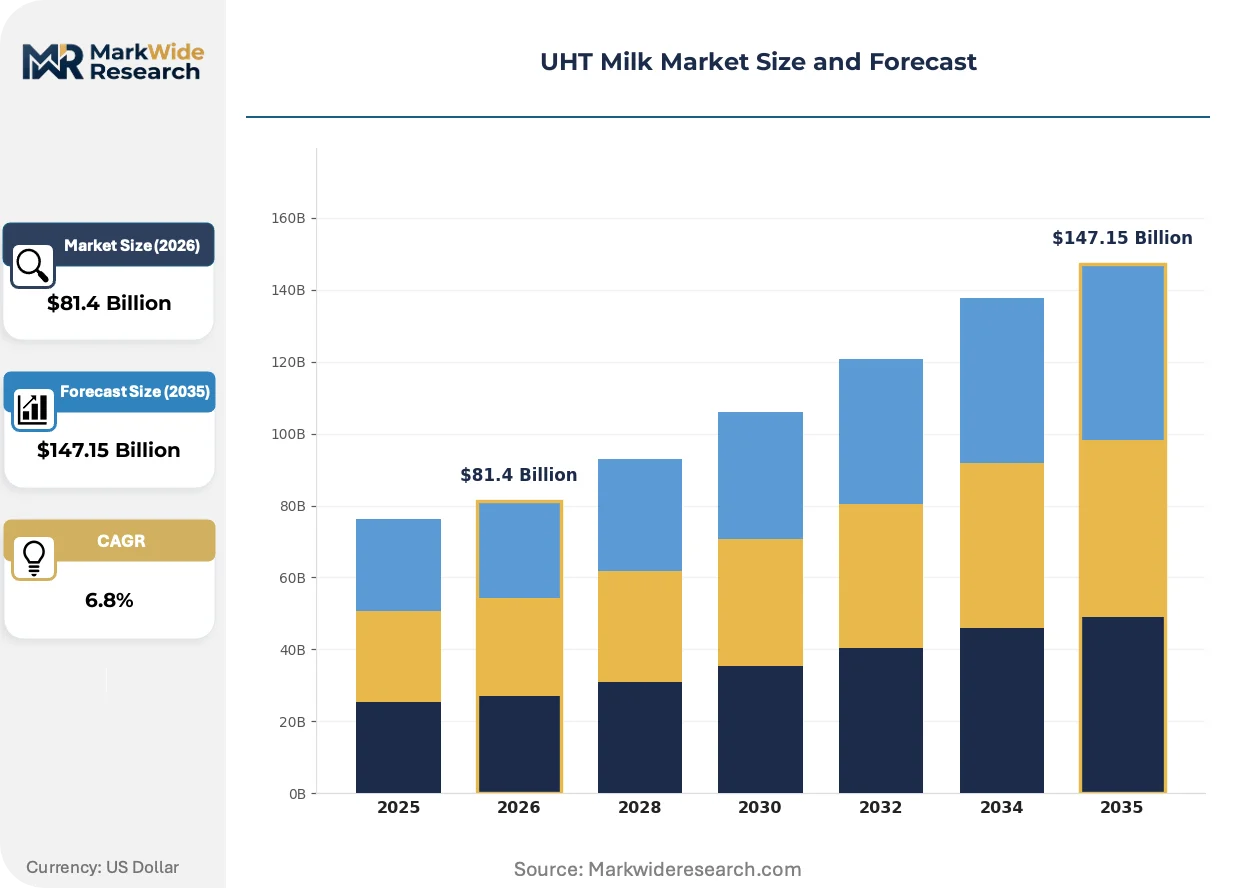
| Market Size in 2026 | $81.4 Billion |
| Market Size in 2035 | $147.15 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Milk, Skimmed Milk, Semi-Skimmed Milk, Flavored Milk Packaging Type: Cartons, Bottles, Pouches, Tetra Packs End User: Retail Consumers, Food Service, Schools, Hospitals Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Wholesale |
| Companies Covered | Arla Foods, Royal FrieslandCampina, Nestlé, Parmalat, Yili Group, Lactalis, Danone, China Mengniu Dairy, Fonterra Co-operative Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UHT Milk Market Strategic Shifts & Innovations
Direct heating technologies and plant-based fortification are compressing processing energy intensity while expanding addressable consumer segments beyond traditional dairy drinkers.
Steam injection and direct UHT systems are overtaking indirect plate heat exchangers in new European installations. Arla Foods and FrieslandCampina are prioritizing these configurations for their 20-30% thermal efficiency advantage. The shift is overtaking conventional equipment vendors and consolidating procurement around integrated sterilization-filling suppliers.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are compelling laminate reformulation across aseptic packaging. ECHA enforcement timelines are compressing supplier qualification windows to 18 months. Dairy cooperatives in Denmark and the Netherlands are responding with captive recycling partnerships to secure post-consumer carton fiber streams.
Subscription-based replenishment models for fortified UHT are displacing traditional wholesale distribution in Southeast Asian e-commerce channels. Shopee and Lazada logistics networks enable direct-to-household delivery that bypasses wet-market intermediaries. This pattern concentrates in Indonesian urban corridors where refrigerator penetration remains below 35%.
UHT Milk Market Segmentation
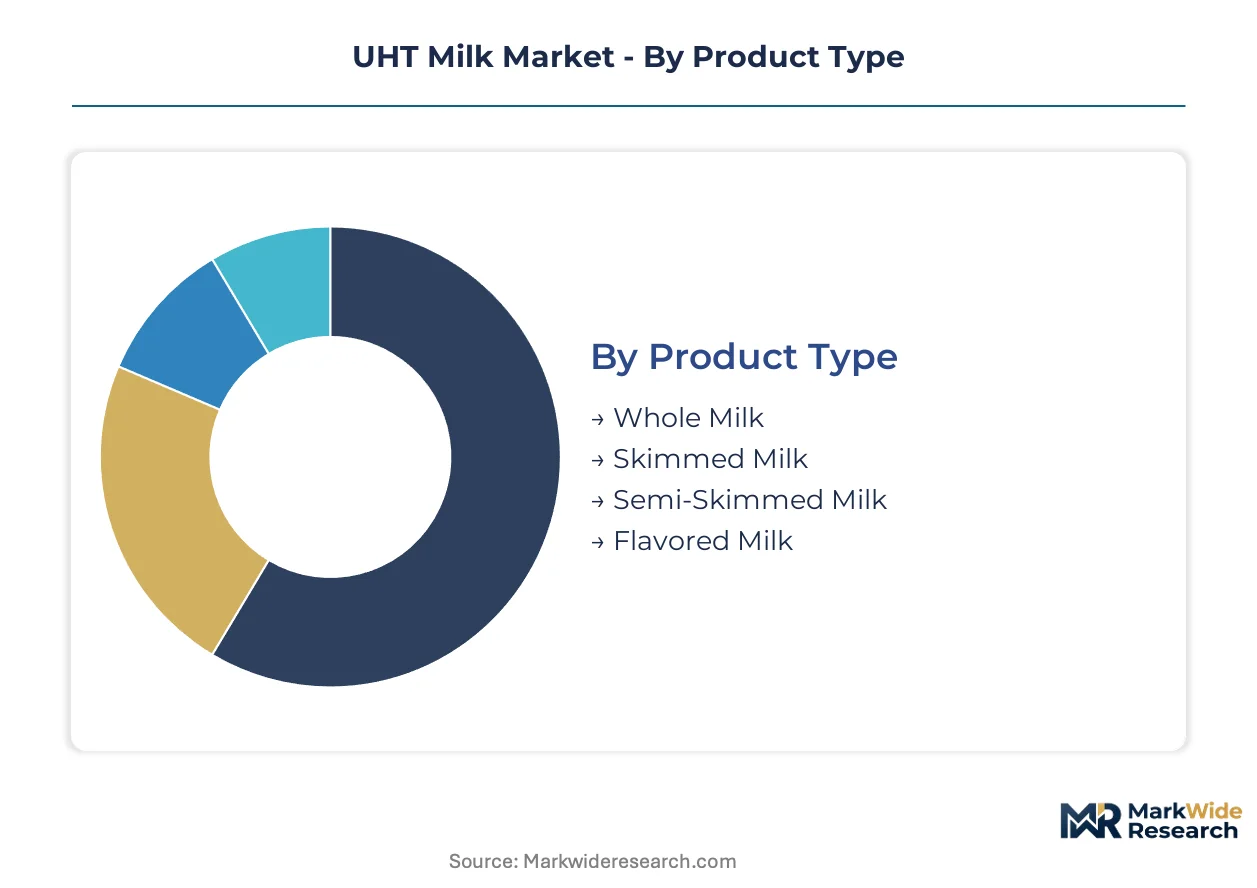
UHT milk segmentation tracks divergent buyer priorities across caloric preference, shelf-life economics, and institutional procurement channels. Processors must align product formats with cold chain maturity and packaging recyclability mandates in each target geography.
Product Type:
Caloric density and health positioning drive consumer selection between full-fat and reduced-fat variants across tropical and temperate markets.
- Whole Milk:Standardized at 3.5% fat content minimum, this variant delivers caloric completeness prized in protein-deficient rural diets. Demand concentrates in India's northern states and Nigeria's Sahel belt where ambient storage replaces refrigeration. Rural cold chain gaps make this the default protein vehicle.
- Semi-Skimmed Milk:Fat content ranging 1.5-1.8% balances taste retention with moderate caloric reduction. Urban Brazilian and Mexican households favor this middle tier as refrigerated pasteurized milk penetrates premium segments. The format captures volume in markets transitioning from whole milk dependency.
- Skimmed Milk:Near-zero fat formulation targets cardiovascular-conscious consumers in EU health-positioned channels.
- Flavored Milk:Cocoa and strawberry variants expand pediatric consumption in Indonesian and Vietnamese school feeding programs.
Volume sits with Whole Milk; growth tilts toward Semi-Skimmed Milk.
Packaging Type:
Material science investment and per-unit cost structures determine competitive viability across ambient distribution networks.
- Tetra Packs:Aseptic laminate technology combining aluminum foil, polyethylene, and paperboard blocks light and oxygen ingress for 6-12 month shelf stability. European dairy cooperatives anchor procurement around this format to satisfy EU Green Deal recyclability timelines. The supplier base remains concentrated in Lund and Modena engineering clusters.
- Cartons:Gable-top and brick configurations without aluminum layers reduce material cost for shorter-life applications. Kenyan and Tanzanian processors favor these for 90-day distribution cycles where retail turnover is predictable.
- Pouches:Flexible aseptic films at 40% lower per-unit cost than cartons are capturing Nigerian and Bangladeshi price-sensitive retail segments.
- Bottles:HDPE and PET formats serve premium-positioned fresh-taste segments in urban Chinese convenience channels.
Procurement concentrates with Tetra Packs; expansion accelerates fastest in Pouches.
End User:
Institutional tender specifications and household refrigerator penetration create divergent quality and fortification requirements.
- Retail Consumers:Individual and family-sized formats dominate volume, with purchase decisions driven by price per liter and brand recognition in ambient retail environments. Indian kirana stores and Brazilian neighborhood markets account for the majority of global offtake.
- Schools:National nutrition programs in Indonesia and the Philippines mandate iron and vitamin D fortification, creating dedicated procurement channels with microbiological specifications exceeding standard retail grades.
- Food Service:Hotels and restaurants in Dubai and Singapore source UHT for espresso preparation and dessert manufacturing where fresh milk logistics are unreliable.
- Hospitals:Enteral feeding and therapeutic nutrition applications require extended shelf-life guarantees in climate-vulnerable geographies.
Revenue weight rests with Retail Consumers; institutional expansion climbs fastest in Schools.
Distribution Channel:
Logistics infrastructure maturity and digital payment penetration reshape channel economics across emerging economies.
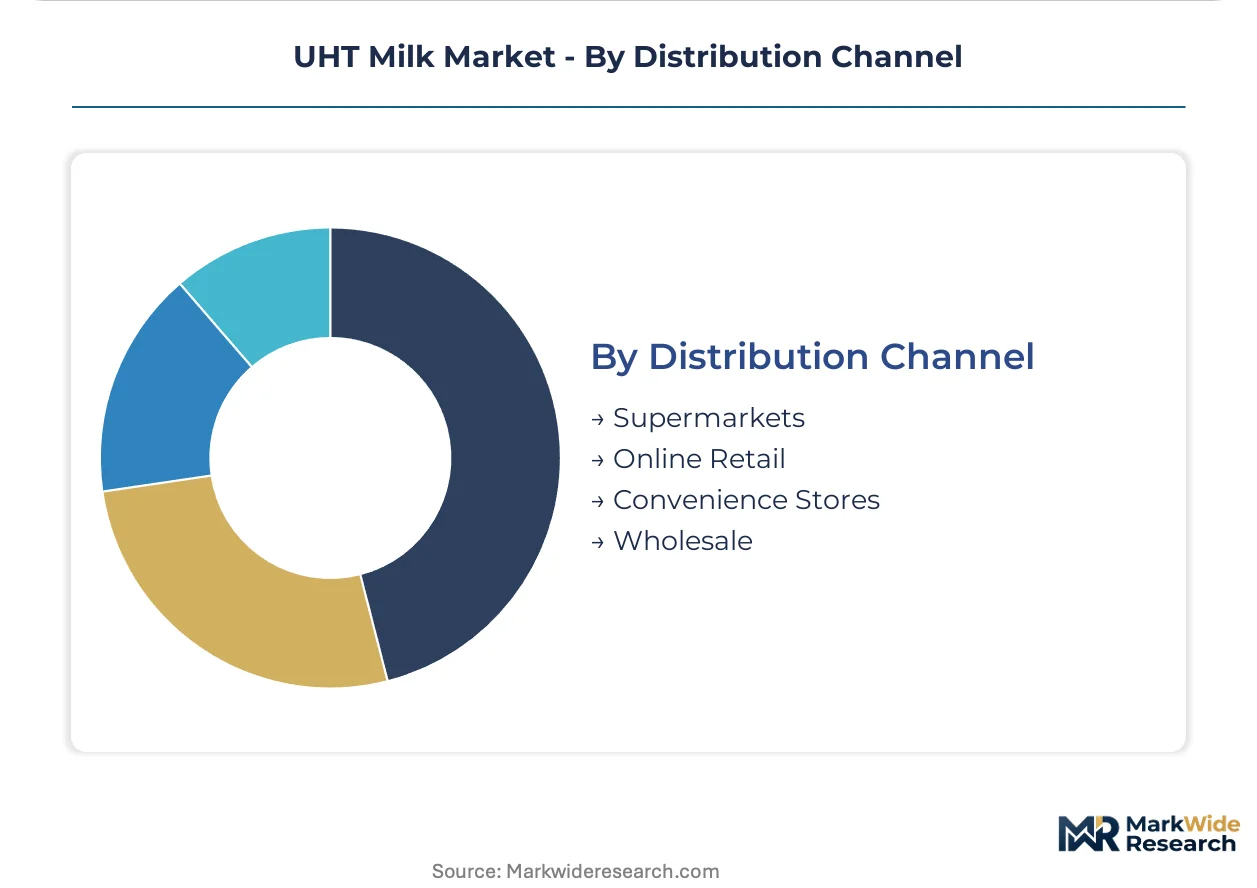
- Supermarkets:Organized retail in São Paulo, Jakarta, and Mexico City provides temperature-controlled environments that extend UHT shelf-life realization. Carrefour and Cencosud chains negotiate direct supply agreements bypassing wholesale intermediaries.
- Convenience Stores:24-hour urban formats in Bangkok and Manila capture impulse and top-up purchases where refrigerator space constraints favor ambient stability.
- Online Retail:Shopee and Lazada subscription models in Indonesian urban corridors enable direct-to-household delivery bypassing wet-market intermediaries.
- Wholesale:Bulk formats for rural stockists and small retailers remain essential in African markets with dispersed population density.
Transaction volume flows through Supermarkets; digital adoption expands most quickly in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New Zealand's pasture-based dairy farming supplies the protein concentrate that processors convert into shelf-stable formats for tropical distribution networks.
India
Rural cold chain deficits in Uttar Pradesh and Bihar drive whole-milk UHT consumption as the default protein source beyond the 150-kilometer milk-shed radius. The FSSAI enforces microbial standards that foreign suppliers navigate through joint ventures with domestic dairies. Processing clusters concentrate in Maharashtra's Pune-Nashik corridor where cooperatives retrofit pasteurization lines for UHT conversion.
Germany
Energy cost volatility tilts Bavarian and North Rhine-Westphalian cooperatives toward longer-life formats that reduce per-unit thermal processing frequency. The EU F-Gas Regulation mandates ammonia-based refrigeration retrofits that compress operating margins. Stuttgart engineering clusters supply direct-steam injection sterilization equipment with 20-30% thermal efficiency gains over plate exchangers.
Brazil
Urban cold chain improvements in São Paulo enable pasteurized milk to reclaim premium segments, while semi-skimmed UHT captures volume in transitioning households. ANVISA governs dairy additive standards that fortified lines must satisfy for school feeding program eligibility. Minas Gerais dairy clusters anchor private-label production for southeast retail chains.
Nigeria
Pouch-format UHT at 40% lower packaging cost than cartons penetrates price-sensitive retail segments in Lagos and Kano where refrigerator penetration remains below 15%. The country's national food safety regulator enforces microbial specifications that imported powder-reconstituted products must meet. Northern distribution corridors rely on ambient-stable formats for Sahel belt protein access.
Indonesia
Subscription-based replenishment models displace wet-market intermediaries in Jakarta and Surabaya where urban refrigerator penetration stays below 35%. Iron and vitamin D fortification mandates for school nutrition programs create dedicated procurement channels. East Java processing clusters supply pediatric-positioned lines for institutional tender.
UHT Milk Market Key Industry Players
Global majors compete with regional champions across packaging technology and raw milk procurement networks. The structure tilts toward consolidation at the equipment-laminate interface while fragmenting across dairy cooperative federations. Three archetypes dominate: Scandinavian farmer-owned cooperatives with captive milk supply, Swiss-French dairy conglomerates with integrated packaging operations, and Chinese state-affiliated processors with domestic distribution scale. Competitive moves concentrate on sterile-zone engineering partnerships and pouch-format capacity expansion.
Among European cooperative structures, Arla Foods and Royal FrieslandCampina exemplify the farmer-owned model that secures raw milk access for UHT conversion. Nestlé occupies a position representing the nutrition conglomerate archetype with fortified pediatric lines in tropical markets. Within private-label manufacturing, Lactalis exemplifies integrated packaging control across Southern European production.
| Leading Market Players |
|---|
| Arla Foods |
| Royal FrieslandCampina |
| Nestlé |
| Parmalat |
| Yili Group |
| Lactalis |
| Danone |
| China Mengniu Dairy |
| Fonterra Co-operative Group |
| Others |
Cost & Logistics Intelligence
Rural cold chain deficits in India and Nigeria force processors to absorb higher packaging costs for ambient-stable formats, compressing margins unless offset by volume scale or fortified premium positioning. This demand-side pressure tilts procurement toward pouch formats and integrated laminate supply to preserve pricing flexibility.
Pricing Analysis
Equipment warranty and sterile-zone maintenance bundling separate premium processor tiers from commodity competitors. Three-tier pricing structure across premium, standard, and economy levels tracks fortification intensity and packaging recyclability certification. Price differentiation hinges on EU Green Deal compliance status and volume commitment scale. Pricing pressure stems from feed cost volatility transmitting directly to raw milk inputs. Institutional buyers in school nutrition programs exhibit lowest price sensitivity; rural retail segments in Bangladesh and Nigeria show highest.
Supply Chain Analysis
Regional distribution centers in Maharashtra's Pune-Nashik corridor and East Java clusters anchor hub-and-spoke patterns for tropical market penetration. Supply concentrates in New Zealand for protein concentrate, Germany for direct-steam injection equipment, and China for aseptic laminate films. Raw material dependencies include aluminum foil, polyethylene, and post-consumer paperboard fiber. Single-source vulnerability at the Tetra Pak equipment-laminate interface creates structural risk. Distribution runs through wholesale intermediaries in African markets and direct retail in Southeast Asian e-commerce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play where REACH Annex XVII compliance timelines and F-Gas Regulation retrofit costs force sub-scale processors toward exit or acquisition.
For Market Incumbents: Deepen captive recycling partnerships to secure post-consumer carton fiber streams ahead of EU Green Deal mandates. Expand pouch-format capacity in Nigerian and Bangladeshi processing clusters where price-sensitive retail segments remain underserved. Threat substitution from fresh milk reclamation in urban Brazil and China demands defensive positioning through fortified pediatric lines. For New Entrants and Emerging Players: Subscription-based replenishment routes through Shopee and Lazada logistics networks offer the most penetrable channel in Indonesian urban corridors where refrigerator penetration stays below 35%. Target institutional procurement for iron and vitamin D fortified lines in Nigerian and Indonesian school feeding programs. White-space exists in flexible aseptic pouch production for African retail segments previously unserved by carton economics. For Investors and Strategic Acquirers: The window for entry favors processors with certified recyclable laminate supply chains and direct-steam injection equipment installations. Long-term viability over the mid-decade horizon rests on sterile-zone engineering talent concentration and ammonia-based refrigeration retrofit completion. Watch carbon border adjustment mechanism implementation timing as inflection indicator for EU market access competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Pouch Format Capacity Expansion | Captures price-sensitive African retail segments at 40% lower packaging cost than cartons. |
| Direct-Steam Injection Retrofit | Arla Foods and FrieslandCampina prioritize 20-30% thermal efficiency gains over plate exchangers. |
| Captive Recycling Partnership | Danish and Dutch cooperatives secure post-consumer carton fiber streams for EU Green Deal compliance. |
| Fortified Pediatric Line Launch | Vitamin D and iron-enriched UHT opens institutional procurement channels in Nigeria and Indonesia. |
| Subscription Model Integration | Shopee and Lazada logistics enable direct-to-household delivery bypassing wet-market intermediaries. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with dairy cooperative procurement directors, aseptic packaging engineers, FSSAI compliance officers, and school feeding program administrators validated demand-side assumptions. Bottom-up volume modeling triangulated against top-down macroeconomic indicators from EFSA migration limit documentation and ECHA enforcement timelines.
Reconciliation of production volume data, import-export flows, and retail audit channels informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, packaging format, end-user category, and distribution channel. CAGRs derived from trend extrapolation anchored in historical energy cost divergence patterns and cold chain infrastructure development trajectories. Forecast inputs incorporated EU F-Gas Regulation phase-down mandates and REACH Annex XVII substance restrictions.
The model holds under steady regulatory enforcement and feed cost normalization; deviation in carbon border adjustment implementation or aluminum foil supply disruption would shift trajectory. Forecasts reflect documented assumptions about sterile-zone engineering talent availability and laminate supplier qualification windows. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
US Cheese Market
Dairy Products
Africa Yogurt Market
Dairy Products
Europe Cow Milk Minerals Market
Dairy Products
Europe Cheese Market
Dairy Products
A2 Protein Milk Market
Dairy Products
Recombined Milk Market
Dairy Products
GCC Camel Dairy Market
Dairy Products
Organic Milk Market
Dairy Products
Green Tea Butter Market
Dairy Products
Middle East and Africa Whey Protein Market
Dairy Products
Sour Cream Market
Dairy Products
Dairy Foods Market
Dairy Products
North America A2 Milk Market
Dairy Products
United Arab Emirates Dairy Market
Dairy Products
GCC Casein Market
Dairy Products
Gruyere Market