
 Green Tea Butter Market | 2026-2036
Green Tea Butter Market Size, Share, and Industry Trends Forecast 2026-2036
Green Tea Butter Market Foresight
Specialty ingredient distribution is narrowing as consolidated procurement desks at multinational formulators reduce vendor lists. Unilever leverages its captive sourcing network across tropical tea-growing belts to secure consistent butter volumes. Givaudan differentiates through biotechnology-derived concentrate streams that standardize catechin retention. Taiyo International anchors Japanese supply through direct plantation partnerships in Shizuoka and Kagoshima prefectures.
Green tea butter is a lipid-rich extract obtained from Camellia sinensis seed oil through controlled hydrogenation or fractionation, yielding a semi-solid butter with melting points between 32°C and 37°C that functions as an emollient, antioxidant carrier, and occlusive agent in topical formulations. Organic product type commands the widest margin pool as certified supply chains justify price premiums over conventional unflavored grades. Cosmetics application leads volume absorption, though nutraceuticals represents the fastest-expanding addressable segment as soft-gel encapsulation of polyphenol-lipid complexes gains traction among supplement marketers.
Japan's Ministry of Economy, Trade and Industry (METI) enforces cosmetic ingredient disclosure standards that elevate traceability requirements for botanical derivatives. The EU REACH regulation and EFSA novel food assessments jointly determine whether green tea butter qualifies for food-grade and dermal-grade classifications across member states. Stakeholders must monitor how divergent purity benchmarks between Asian cosmetic regulators and European chemical agencies reshape cross-border formulation strategies and certification investments.
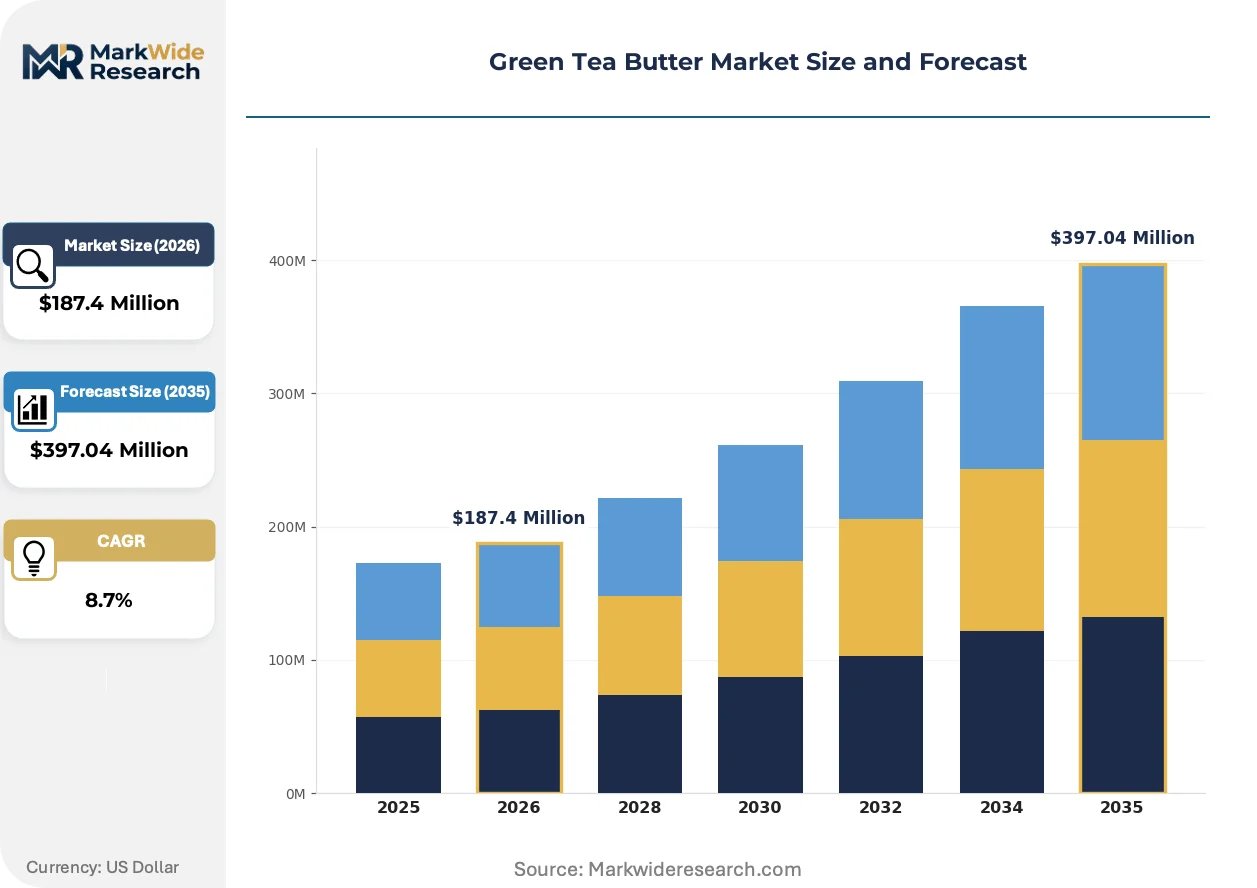
Market Dynamics
Consolidated procurement desks at multinational cosmetics formulators are compressing vendor lists and demanding certified organic feedstock traceability, reshaping competitive access for green tea butter suppliers.
Growth Catalysts
- EU REACH Purity Thresholds:Tightened botanical extract standards under ECHA oversight push formulators toward certified organic grades, creating premium tier demand.
- K-Beauty Emollient Specification:South Korean cosmetics manufacturers specify green tea butter for stability in skincare lines, anchoring volume absorption in East Asian beauty markets.
- Soft-Gel Encapsulation Technology:Polyphenol-lipid complex delivery systems for nutraceuticals expand addressable segments beyond topical applications.
Market Restraints
- Camellia Seed Oil Price Volatility:Input costs fluctuate with tea harvest yields in Shizuoka and Kagoshima prefectures, compressing processor margins.
- Plantation Concentration Risk:Premium organic feedstock depends on limited certified acreage in Japan's southern islands, creating supply bottleneck exposure.
- Shea Butter Substitution:Lower-cost lipid alternatives with comparable emollient properties displace green tea butter in mass-market cosmetic formulations.
Strategic Opportunities
- Indian Nutraceutical Penetration:Ayurveda-inspired supplement marketers in Maharashtra and Karnataka represent underdeveloped demand for catechin-rich lipid complexes.
- Japan METI Traceability Incentives:Cosmetic ingredient disclosure standards reward blockchain-verified supply chains, opening premium positioning for compliant suppliers.
- Biotechnology-Derived Concentrates:Fermentation-based catechin standardization converges with lipid fractionation, enabling consistent active retention without plantation dependency.
Industry Challenges
- Organic Certification Timeline:JAS and EU organic accreditation cycles extend 18-24 months, delaying market entry for new plantation partnerships.
- Legacy Emulsion System Compatibility:Formulation chemists face integration friction when substituting green tea butter for petroleum-derived occlusives in existing product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Tea Butter Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unflavored, Flavored, Organic, Herbal Application: Cosmetics, Food & Beverage, Nutraceuticals, Personal Care Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Health Food Shops Packaging Type: Tubs, Sachets, Jars, Pouches |
| Companies Covered | Unilever, ADM, Givaudan, International Flavors & Fragrances, Kemin Industries, Synthite Industries, Firmenich, Finlay Tea Solutions, Taiyo International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Tea Butter Market Shifts & Advancements
Biotechnology and digital traceability systems are compressing traditional plantation-dependent supply models while regulatory disclosure mandates reshape procurement specifications across cosmetics and nutraceuticals.
Controlled hydrogenation protocols for Camellia sinensis seed oil is virtualizing the consistency of batch-to-batch catechin retention. Japanese nutraceutical encapsulators adopt these standardized concentrates to reduce quality variance in soft-gel production. The technology is virtualizing the role of geographic terroir as a quality differentiator, compressing premium pricing power for single-origin suppliers.
EFSA novel food assessments under EU jurisdiction now determine dual-use classification for lipid extracts crossing between dermal and ingestible applications. This regulatory friction forces suppliers to maintain parallel certification streams for cosmetics-grade and food-grade designations. Small-scale processors in Kagoshima face disproportionate compliance burdens relative to integrated multinationals with captive regulatory affairs capacity.
Direct plantation partnerships are displacing spot-market procurement for certified organic feedstock. South Korean formulators now require blockchain-verified origin documentation from Shizuoka growers, bypassing traditional trading houses. This channel disintermediation concentrates purchasing power with vertically integrated cosmetics conglomerates while marginalizing independent butter processors lacking upstream acreage control.
Green Tea Butter Market Segmentation
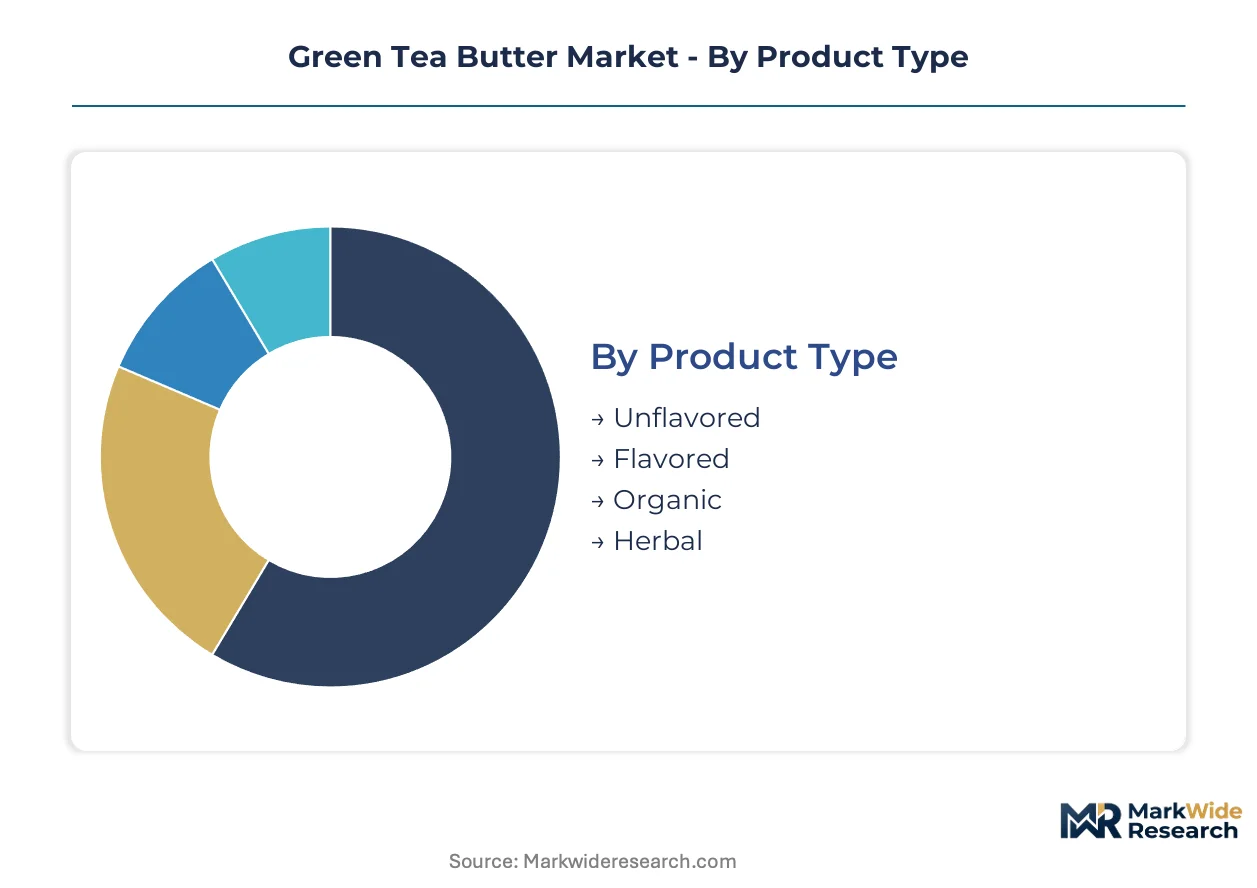
Segmentation in green tea butter markets reveals how procurement specifications diverge between premium cosmetic formulators and mass-market food processors. Technical requirements around catechin retention, melting point consistency, and organic certification create distinct commercial tiers that reshape supplier competitive access.
Product Type:
After-sales technical support intensity varies sharply across product grades, with organic certification demanding ongoing audit documentation and traceability system maintenance that conventional grades do not require.
- Organic:Certified supply chains under JAS or EU organic standards command sustained price premiums through documented plantation provenance. South Korean K-beauty formulators in Seoul and Busan now mandate organic grades for emollient stability in premium skincare lines, compressing vendor lists to accredited suppliers.
- Unflavored:Standard lipid fractions with 32-37°C melting points serve as base emollients where catechin content remains secondary to occlusive performance. Mass-market cosmetic manufacturers in Osaka and Nagoya specify this grade for cost-sensitive body butter formulations.
- Flavored:Infused variants with botanical extracts target niche aromatherapy applications.
- Herbal:Compound formulations blending Camellia sinensis with additional botanical actives.
By volume, unflavored leads. By growth pace, organic is ahead.
Application:
Cost tier differentiation separates premium dermal formulations from commodity food-grade applications, with certification investments determining margin capture.
- Cosmetics:Emollient and antioxidant carrier functions in topical formulations demand batch-to-batch catechin consistency. Japanese cosmetics manufacturers under METI disclosure standards now require blockchain-verified origin documentation from Shizuoka prefecture growers.
- Nutraceuticals:Soft-gel encapsulation of polyphenol-lipid complexes expands addressable segments beyond dermal applications. Maharashtra and Karnataka supplement marketers in India represent underdeveloped demand for standardized concentrates.
- Food & Beverage:EFSA novel food assessments determine dual-use classification for lipid extracts crossing between ingestible and cosmetic applications.
- Personal Care:Mass-market body care applications compete with shea butter substitution pressure.
Cosmetics absorbs the most volume. Nutraceuticals climbs the fastest.
Distribution Channel:
Customer type concentration shapes channel strategy, with consolidated procurement desks at multinational formulators displacing traditional trading house relationships.
- Specialty Stores:Curated retail environments in Tokyo's Ginza and Seoul's Gangnam districts sustain premium positioning for single-origin and small-batch green tea butter products. Direct consumer relationships here justify higher margin capture for certified organic grades.
- Online Retail:E-commerce platforms enable traceability documentation display and subscription replenishment models. South Korean and Japanese direct-to-consumer brands leverage digital channels to bypass traditional distribution markups.
- Supermarkets:Mass-market retail placement competes on price with conventional lipid alternatives.
- Health Food Shops:Natural products retail channels emphasize organic certification visibility.
Specialty stores dominate premium volume. Online retail gains share fastest.
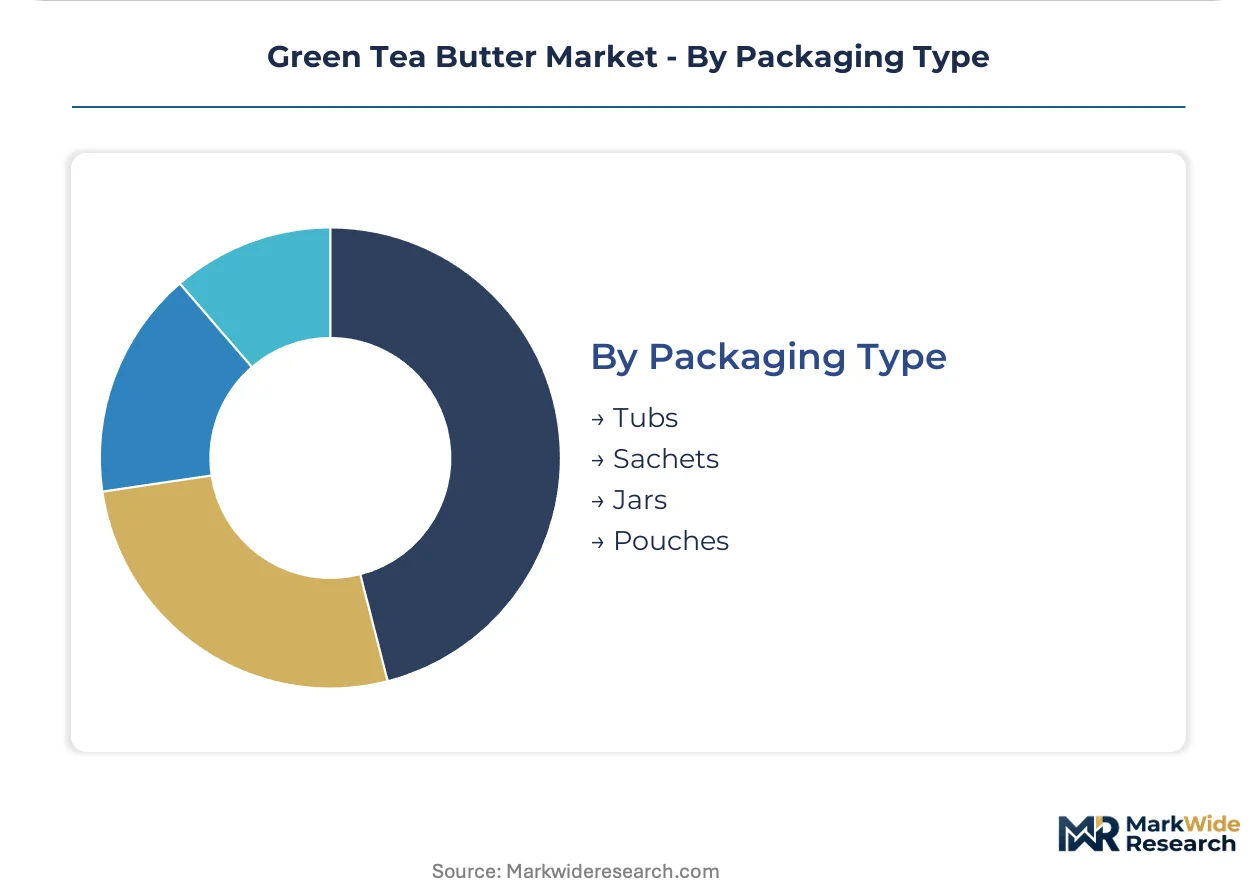
Packaging Type:
Supply concentration in Japanese processing infrastructure favors formats compatible with existing filling equipment and export logistics.
- Jars:Premium cosmetic positioning requires amber glass or high-barrier polymer containers that protect catechin stability from oxidation. Osaka-based formulators specify jar formats for prestige skincare lines targeting domestic and export markets.
- Tubs:Bulk institutional formats serve manufacturing-scale cosmetic and food processors. Kagoshima butter processors supply tub formats to Unilever's captive sourcing network across tropical tea-growing belts.
- Sachets:Single-use sampling formats support trial conversion in direct-to-consumer channels.
- Pouches:Flexible packaging reduces shipping cube for export logistics.
Tubs lead by procurement volume. Jars sustain the steepest expansion trajectory in premium tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese suppliers command price premiums through certified organic traceability, while Indian processors compete on volume for unflavored commodity grades. This asymmetry concentrates margin capture in East Asian plantation partnerships while compressing returns in South Asian toll-processing arrangements.
Japan
Shizuoka and Kagoshima prefectures anchor premium feedstock supply through direct plantation partnerships with cosmetics formulators. METI cosmetic ingredient disclosure standards enforce blockchain-verified origin documentation, elevating compliance costs for small-scale processors. Tokyo-based K-beauty distributors now bypass traditional trading houses to source certified organic butter directly from Kyushu growers.
South Korea
Seoul and Busan formulators specify green tea butter for emollient stability in premium skincare lines, driving volume absorption in the K-beauty export sector. MFDS cosmetic safety assessments align with EU REACH purity benchmarks, creating dual-certification pressure for imported feedstock. Gangnam district specialty retailers sustain premium positioning through curated single-origin product placement.
India
Maharashtra and Karnataka supplement marketers represent underdeveloped demand for catechin-rich lipid complexes in Ayurveda-inspired nutraceuticals. FSSAI novel food assessments determine ingestible-grade classification for lipid extracts crossing from cosmetic to supplement applications. Mumbai-based soft-gel encapsulators adopt standardized concentrates to reduce batch-to-batch quality variance.
United States
California and New York cosmetic formulators source certified organic grades for clean-label skincare positioning in premium retail channels. FDA cosmetic labeling requirements and EPA botanical extract standards create parallel compliance tracks for dermal-grade versus food-grade designations. Los Angeles-based direct-to-consumer brands leverage digital traceability documentation to justify subscription replenishment pricing.
Germany
Bavaria and North Rhine-Westphalia processing hubs distribute green tea butter across EU cosmetics manufacturers under ECHA REACH oversight. EFSA novel food assessments determine dual-use classification for lipid extracts, forcing suppliers to maintain separate certification streams. Düsseldorf-based procurement desks at multinational formulators compress vendor lists to accredited organic suppliers with captive regulatory affairs capacity.
Green Tea Butter Market Competitive Landscape
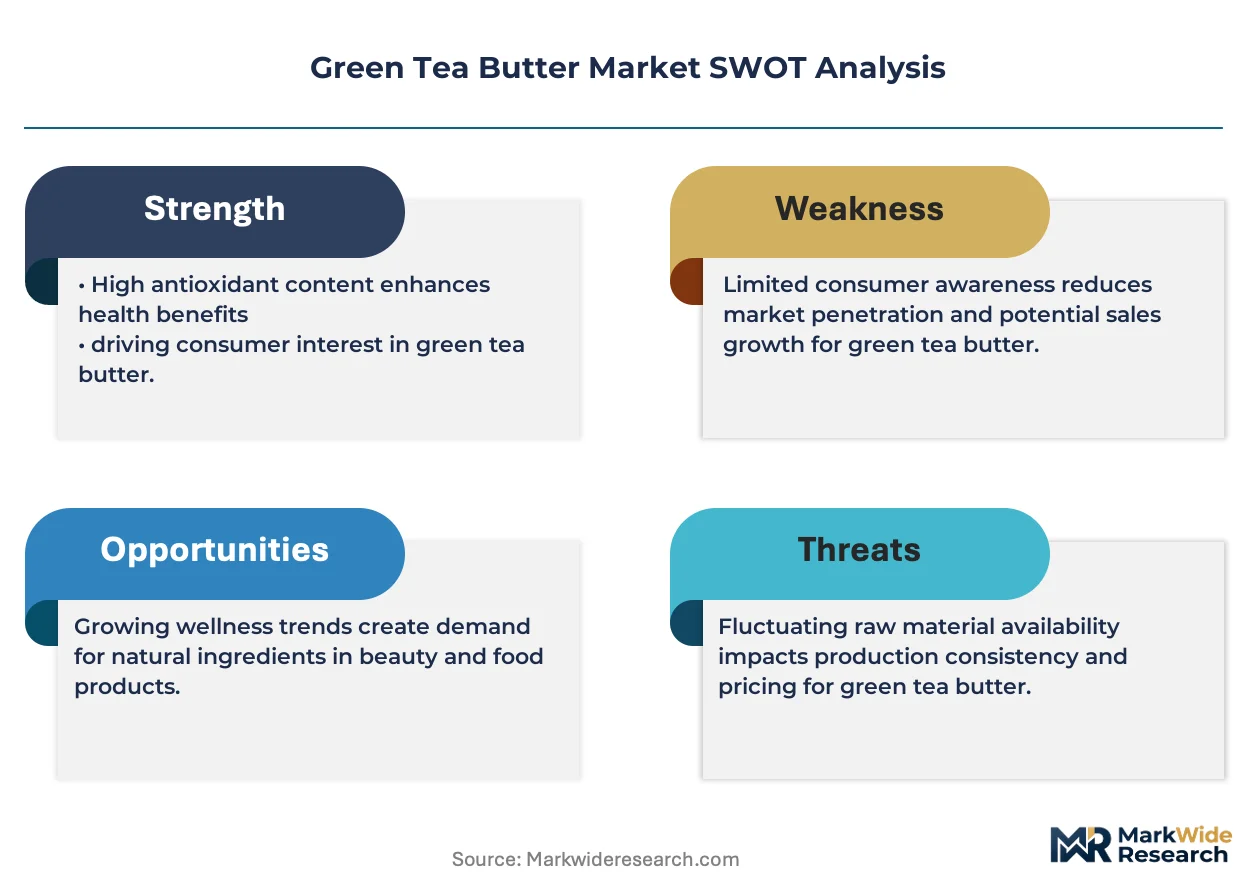
Platform integrators command the system tier; component specialists sit upstream in feedstock and fractionation. The vendor base compresses around consolidated procurement desks at multinational cosmetics conglomerates that demand certified organic traceability. Three archetypes dominate: vertically integrated plantation-to-butter processors, biotechnology-derived concentrate specialists, and toll-processing intermediaries lacking upstream acreage control. Competitive moves center on direct plantation partnerships displacing spot-market procurement, and fermentation-based catechin standardization reducing geographic terroir dependency.
Among the integrated platform tier, Unilever anchors volume absorption through captive sourcing networks across tropical tea-growing belts. Givaudan occupies a position within biotechnology-derived concentrate streams that standardize active retention without plantation dependency. Taiyo International exemplifies the plantation-partnership archetype through direct acreage control in Shizuoka and Kagoshima prefectures.
| Leading Market Players |
|---|
| Unilever |
| ADM |
| Givaudan |
| International Flavors & Fragrances |
| Kemin Industries |
| Synthite Industries |
| Firmenich |
| Finlay Tea Solutions |
| Taiyo International |
| Others |
Supply & Pricing Matrix
Shizuoka prefecture's certified organic acreage constraints translate directly into premium pricing power for plantation-adjacent processors, while Kagoshima toll operators absorb margin compression from volatile Camellia seed oil spot markets.
Pricing Analysis
Configured-to-order pricing for blockchain-verified organic grades commands spreads exceeding standard unflavored quotations by certification and traceability investments. Three-tier pricing structure across premium, standard, and economy levels stratifies by JAS organic accreditation, catechin retention consistency, and volume commitment scale. Cost compression in commodity unflavored tiers is intensifying because shea butter substitution pressures mass-market cosmetic formulators. Mass-market personal care manufacturers exhibit highest price sensitivity, while Seoul-based K-beauty formulators demonstrate lowest sensitivity due to emollient stability requirements.
Supply Chain Analysis
Tariff exposure between Japan and South Korea dominates cross-border feedstock movements despite geographic proximity. Primary supply concentrates in Japan, India, and Germany, drawing from Camellia sinensis seed oil, hydrogenation catalysts, and encapsulation-grade gelatin inputs. Single-source vulnerability pervades Shizuoka organic certification pipelines where 18-24 month JAS accreditation cycles create bottleneck exposure. Distribution runs through vertically integrated cosmetics conglomerates with captive procurement desks, displacing traditional trading house intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs competitive outcomes as blockchain-verified traceability systems enable direct plantation-to-formulator disintermediation, collapsing traditional trading margins into ecosystem orchestration fees.
For Market Incumbents: Insulate premium positioning through backward integration into Kagoshima organic acreage, securing JAS certification pipelines ahead of METI disclosure standard expansions. Deepen captive sourcing networks across tropical tea-growing belts to offset Camellia seed oil price volatility. Prioritize biotechnology-derived concentrate R&D to reduce geographic terroir dependency and standardize catechin retention without plantation concentration risk.
For New Entrants and Emerging Players: Build out Maharashtra and Karnataka nutraceutical penetration for Ayurveda-inspired soft-gel encapsulators seeking standardized polyphenol-lipid complexes. Target underdeveloped Indian supplement marketers with fermentation-based catechin concentrates that bypass 18-24 month organic certification timelines. Pursue white-label toll-processing arrangements with Mumbai-based encapsulators lacking upstream feedstock control.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors biotechnology-derived concentrate specialists with fermentation-based standardization capabilities over plantation-dependent processors. Long-term viability rests on acquiring platforms with dual-use certification streams spanning EFSA novel food and ECHA REACH dermal classifications. Monitor EFSA assessment velocity as inflection indicator for dual-use lipid extract commercialization timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Acreage | JAS certification pipelines in Shizuoka secure premium tier access for compliant processors. |
| Biotechnology-Derived Concentrate Development | Fermentation-based catechin standardization reduces dependency on geographic terroir quality variance. |
| Blockchain-Verified Traceability Implementation | METI disclosure standards reward compliant suppliers with direct formulator procurement relationships. |
| Dual-Use Certification Stream Maintenance | Parallel EFSA novel food and ECHA REACH designations enable cross-segment revenue capture. |
| Indian Nutraceutical Channel Expansion | Maharashtra and Karnataka supplement marketers represent underdeveloped demand for lipid complexes. |
Research Methodology
A standing panel of cosmetics formulators, nutraceutical encapsulators, plantation operations managers, and regulatory affairs specialists provided ongoing calibration across primary fieldwork and secondary validation. Input combined structured interviews with procurement leads at multinational conglomerates, technical directors at Japanese butter processors, and compliance officers navigating EFSA novel food assessments. Secondary sources encompassed ECHA REACH filings, FSSAI novel food registrations, METI cosmetic ingredient disclosure guidance, and customs trade data for Camellia-derived lipid fractions. Bottom-up volume triangulation against top-down value estimates anchored segmentation-specific projections.
Scenario-bracketing around organic certification timeline delays, shea butter substitution elasticity, and biotechnology concentrate adoption curves bounded projection uncertainty across the modeling period. Segmentation dimensions spanned product grade tier, application end-use, distribution channel concentration, and regional regulatory cluster. CAGRs derived from weighted average of historical trajectory analysis and technology diffusion modeling, incorporating catechin retention standardization progress and soft-gel encapsulation capacity expansion as industry-specific inputs.
Practitioners should monitor EFSA novel food assessment backlogs, JAS organic accreditation queue lengths, and shea butter price spreads for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Blue Cheese Market
Dairy Products
Butter and Margarine Market
Dairy Products
Recombined Milk Market
Dairy Products
United Kingdom Casein and Caseinates Market
Dairy Products
Sheep Milk Market
Dairy Products
Saudi Arabia Dairy Products Market
Dairy Products
Low-Fat Sour Cream Market
Dairy Products
Global Lipolyzed Butter Fat Market
Dairy Products
Filled Cheese Market
Dairy Products
GCC UHT Milk Market
Dairy Products
Non-GMO Yogurt Market
Dairy Products
Clotted Cream Market
Dairy Products
Low Fat Yogurt Calories Market
Dairy Products
Organic Cheese Powder Market
Dairy Products
Kuwait Dairy Products Market
Dairy Products
North America Fluid Milk Market