
 Savory Dairy Products Market | 2026-2036
Savory Dairy Products Market Size, Share, and Industry Trends Forecast 2026-2036
Savory Dairy Products Market Analytics
Food manufacturers is reorganizing procurement priorities toward savory dairy inputs for prepared meals and industrial formulations. Nestlé leverages its global dairy supply network to secure consistent ingredient flows for savory applications. Danone sustains competitive pressure through specialized fermented savory dairy lines. Arla Foods anchors its position in European savory cheese portfolios with controlled cooperative sourcing.
Savory dairy products encompass cultured, aged, or processed dairy formulations engineered for umami-forward flavor profiles, typically containing 15-35% milk fat and active bacterial cultures for shelf-stable or refrigerated distribution. These products serve commercial food production and retail meal preparation where salt-tolerant cultures and controlled proteolysis develop characteristic depth. Cheddar cheese and cream cheese command the largest volume positions, while feta cheese captures expanding interest in Mediterranean-inspired product development. The meal kits application segment shows the fastest structural momentum as subscription food services standardize savory dairy components for recipe consistency.
FDA standards of identity and EFSA dairy labeling requirements shape permissible ingredient declarations and nutritional claims across export markets. The EU Green Deal agricultural targets and F-Gas Regulation cold-chain mandates influence processing energy costs and sustainable packaging transitions for refrigerated savory dairy distribution. Stakeholders must monitor evolving regulatory thresholds for sodium reduction and clean-label fermentation disclosures to preserve market access and brand positioning.
Market Dynamics
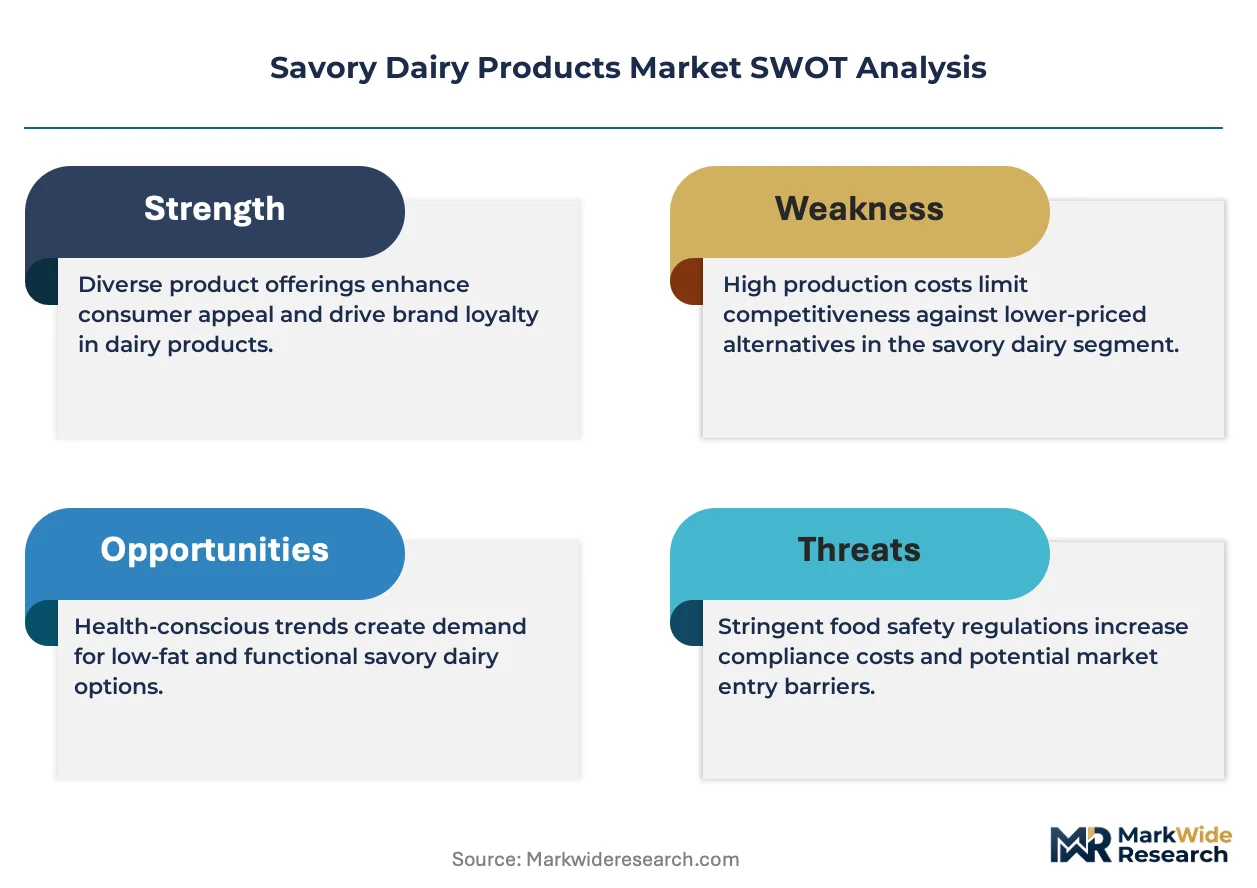
Clean-label fermentation protocols are restructuring savory dairy procurement as EFSA and FDA disclosure mandates force reformulation of bacterial culture declarations and sodium reduction targets.
Growth Catalysts
- Meal kit standardization:Subscription food services are locking in savory dairy specifications for recipe consistency across refrigerated supply chains.
- EFSA clean-label guidance:Permissible ingredient declarations now favor fermented savory dairy with transparent bacterial culture sourcing.
- Controlled proteolysis:Salt-tolerant culture development is extending shelf-stable distribution windows for umami-forward formulations.
Market Restraints
- Milk fat input volatility:Butterfat price swings between 15-35% formulation bands compress margin predictability for aged cheese producers.
- Refrigerated logistics concentration:Cold-chain capacity bottlenecks in Germany and Japan limit export scalability for cream cheese portfolios.
- F-Gas Regulation compliance costs:EU cold-chain energy mandates are elevating processing overhead for refrigerated savory dairy distribution.
Strategic Opportunities
- Mediterranean product development:Feta cheese applications remain underdeveloped in US retail compared to cheddar saturation.
- EU Green Deal agricultural targets:Sustainable packaging transitions offer first-mover positioning for cooperative dairy networks.
- Fermentation disclosure technology:Blockchain-tracked bacterial culture provenance is creating premium tier separation in clean-label segments.
Industry Challenges
- Sodium reduction formulation expertise:Salt-tolerant culture engineering requires specialized dairy microbiology talent pools that remain thin.
- Legacy ERP integration:Batch-level traceability systems for FDA identity standards clash with decades-old manufacturing software architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Savory Dairy Products Market |
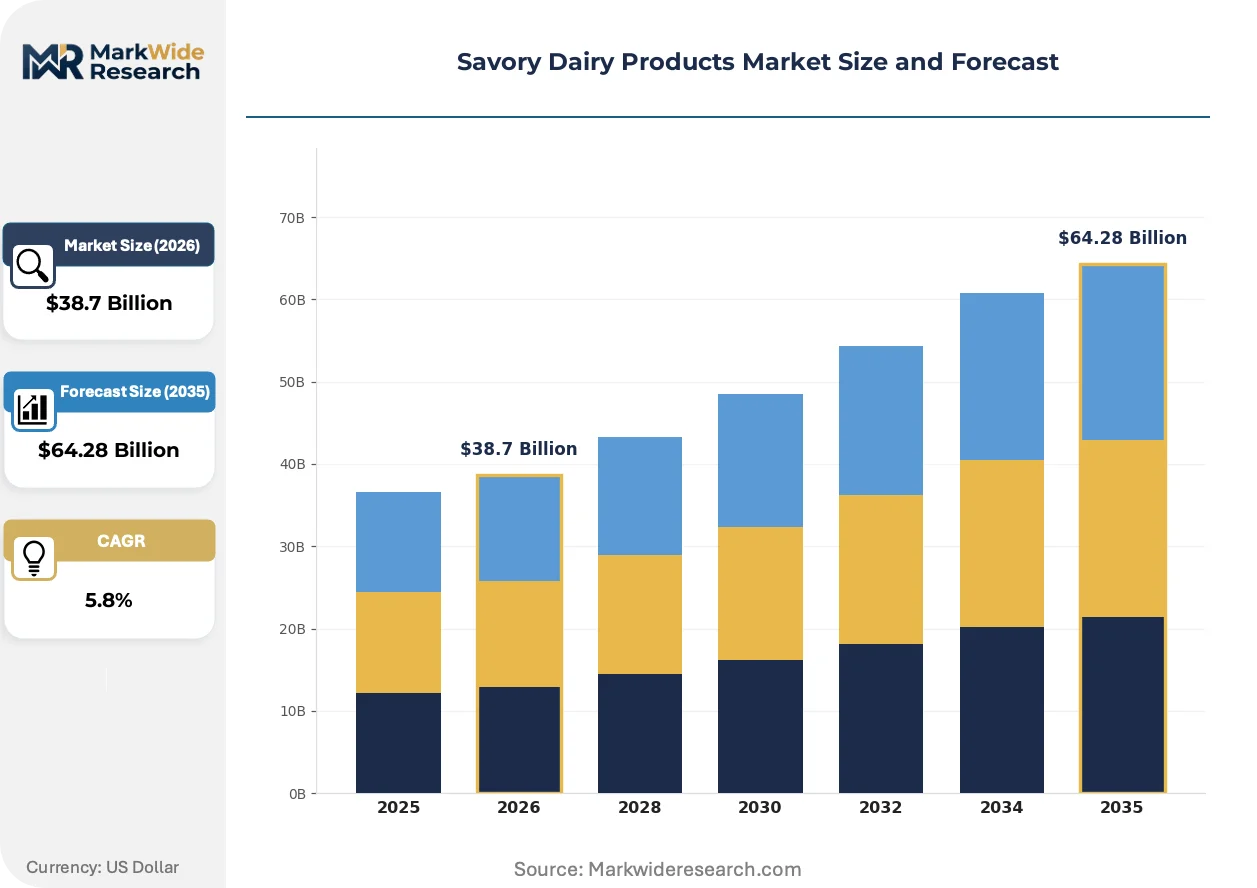
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cream Cheese, Cottage Cheese, Cheddar Cheese, Feta Cheese Application: Snacks, Cooking, Meal Kits, Spreads Packaging Type: Glass Jars, Plastic Containers, Vacuum Packs, Tetra Packs End User: Restaurants, Households, Catering Services, Food Manufacturers |
| Companies Covered | Nestlé, Danone, Arla Foods, Lactalis, Fonterra, Saputo, FrieslandCampina, Dairy Farmers of America, Kraft Heinz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Savory Dairy Products Market Evolving Landscape
Active bacterial culture transparency and fermentation process disclosure are becoming competitive differentiators as regulatory scrutiny intensifies across export markets.
Precision fermentation for dairy protein analogs is supplanting traditional animal-derived milk fat in select savory applications. Industrial food manufacturers in Germany are piloting these formulations for prepared meal lines. The technology is supplanting conventional aged cheese inputs in cost-sensitive contract manufacturing.
EFSA's evolving dairy labeling requirements are mandating granular bacterial strain disclosure on savory fermented products. This policy friction is forcing reformulation of long-established cheddar and cream cheese brands. Manufacturers serving European export markets are accelerating clean-label fermentation investments to preserve shelf access.
Direct procurement relationships between meal kit operators and dairy cooperatives are compressing traditional ingredient distributor roles. Subscription services in the United States are negotiating captive supply agreements for standardized savory components. This channel restructuring is most visible in premium meal kit segments where recipe consistency commands price premiums.
Savory Dairy Products Market Segmentation
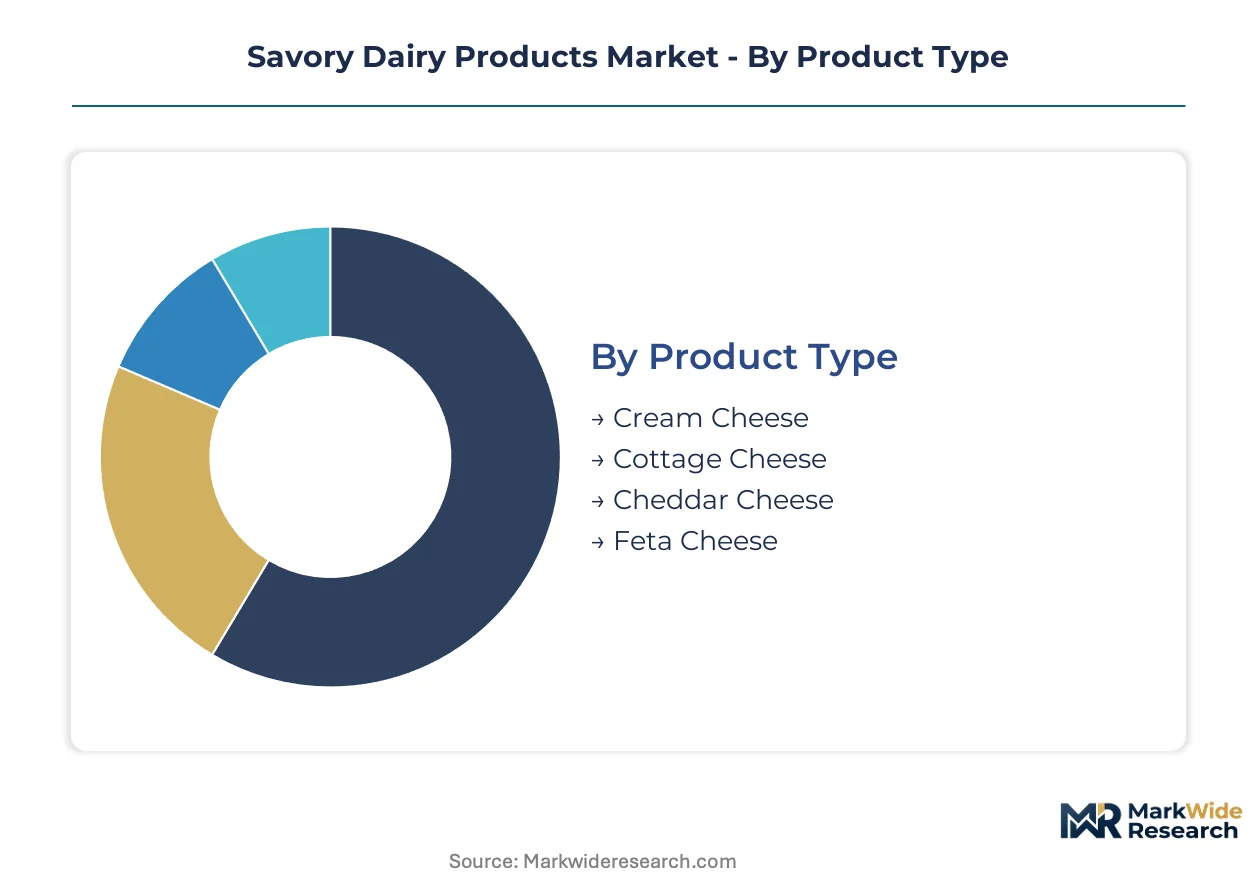
Savory dairy procurement flows through distinct channel configurations that reshape margin capture and formulation requirements. Understanding segment-specific distribution patterns enables suppliers to align production capacity with where volume concentrates versus where premiums materialize.
Product Type:
Cream cheese and cheddar anchor refrigerated retail distribution through supermarkets and club stores, while feta and cottage cheese concentrate in foodservice and specialty import channels with shorter payment cycles.
- Cream Cheese:High-moisture fresh cheese with 33-55% milk fat content formulated for spreadability and cold-chain stability. Demand clusters in US meal kit subscription services where standardized 8-ounce blocks support recipe consistency across refrigerated logistics networks.
- Cheddar Cheese:Aged cultured cheese with controlled proteolysis developing umami depth through 3-24 month maturation cycles. Volume concentrates in German food manufacturing where shredded and diced formats feed industrial ready-meal production lines requiring melt-point precision.
- Cottage Cheese:Fresh curd product with 4% milk fat and active cultures delivering high-protein positioning. Japanese convenience retailers stock single-serve cups for breakfast protein applications.
- Feta Cheese:Brined white cheese with crumbly texture and 6% salt content enabling ambient-stable distribution. Mediterranean restaurant chains in the United States source bulk formats for salad and grain bowl applications.
Cheddar dominates installed base across retail and foodservice. Feta is where expansion concentrates as Mediterranean flavor profiles penetrate US coastal markets.
Application:
Cost tier stratification separates commodity bulk sales from premium positioned formats, with meal kits commanding formulation premiums while cooking applications drive volume throughput.
- Meal Kits:Pre-portioned savory dairy components in recipe-calibrated quantities requiring batch-level traceability and consistent melt behavior. Subscription operators in the United States negotiate captive supply agreements for cheddar and cream cheese with locked-in fat content specifications.
- Cooking:Industrial-scale shredded, diced, and sauce-based formats for ready-meal and soup manufacturing. German contract food manufacturers source aged cheddar through cooperative dairy networks for cost-sensitive prepared meal lines.
- Snacks:Portion-controlled cheese sticks, crisps, and dip formats for convenience retail. Japanese vending machine operators stock ambient-stable processed cheese products.
- Spreads:Flavored cream cheese and processed cheese formats for bread and cracker pairing. US supermarket delis stock private-label options alongside branded portfolios.
Cooking applications dominate installed base. Meal kits represent the steepest expansion trajectory as subscription services standardize savory dairy specifications.
Packaging Type:
Volume scale separates high-throughput formats from premium positioning, with vacuum packs and Tetra Packs enabling extended distribution reach versus glass and rigid plastic's retail premium capture.
- Vacuum Packs:Modified atmosphere packaging with oxygen barrier films extending refrigerated shelf life to 90-180 days for block cheese formats. German dairy cooperatives deploy this format for export cheddar shipments to Japan where cold-chain bottlenecks demand extended stability windows.
- Plastic Containers:Injection-molded tubs and cups for fresh cheese with resealable lids supporting multi-use occasions. US retailers stock cream cheese and cottage cheese in this format across mass and club channels.
- Glass Jars:Premium-positioned containers for artisanal and imported feta varieties. Specialty grocers in the United States source Greek and Bulgarian feta in this format for Mediterranean ingredient aisles.
- Tetra Packs:Aseptic carton technology enabling ambient-stable liquid cheese sauces and processed cheese. Food manufacturers in Germany pilot this format for prepared meal sauce components.
Plastic containers dominate installed base. Vacuum packs are where expansion concentrates as export logistics demand extended shelf stability.
End User:
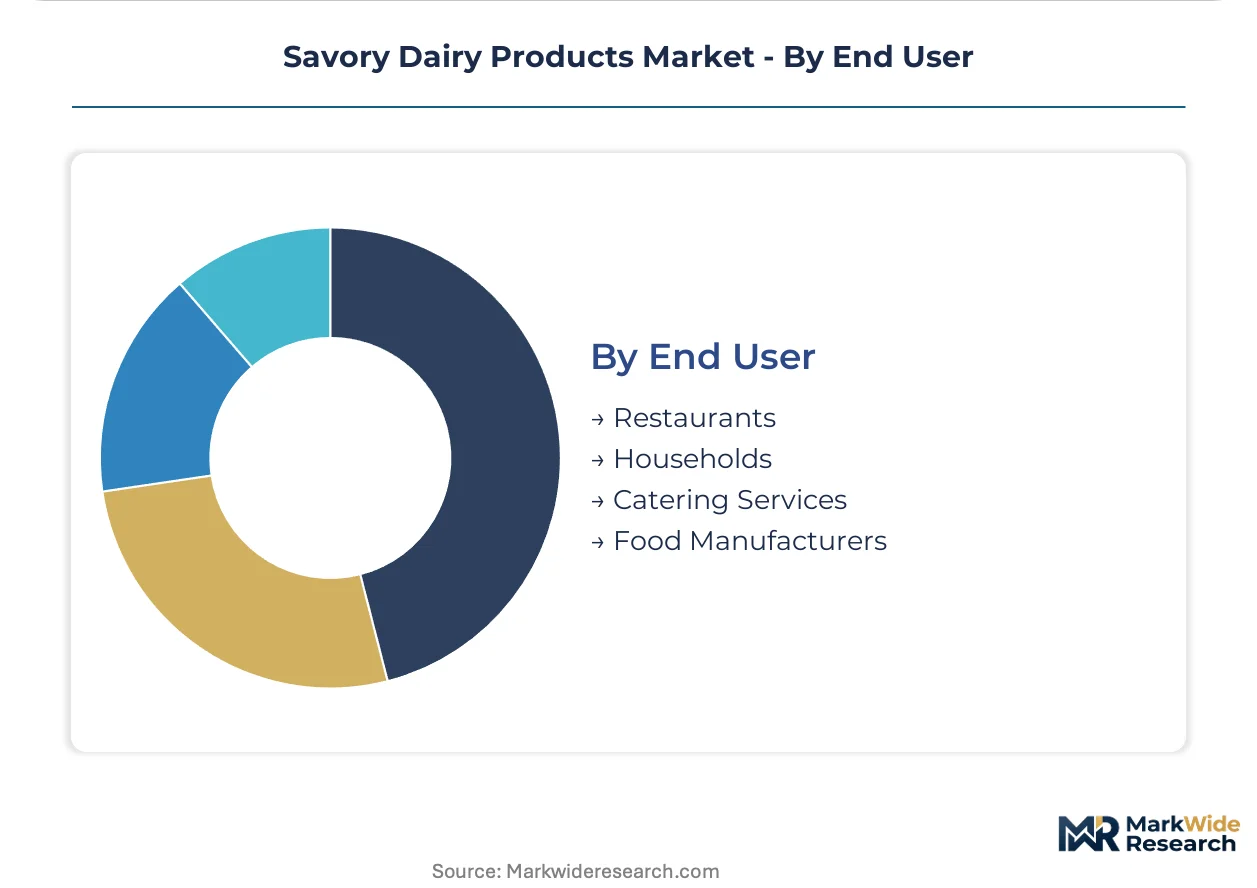
Customer type stratification separates price-sensitive bulk procurement from premium formulation requirements, with food manufacturers driving standardization while restaurants demand flexibility.
- Food Manufacturers:Industrial buyers sourcing shredded, diced, and sauce formats with precise melt-point and moisture specifications for ready-meal and soup production. German contract manufacturers lock in annual cheddar volumes through cooperative supply agreements.
- Restaurants:Foodservice operators purchasing bulk blocks and pre-portioned formats with variable cut specifications. US fast-casual chains source crumbled feta for Mediterranean menu items through broadline distributors.
- Households:Retail consumers selecting branded and private-label formats through supermarket and e-commerce channels. Japanese households purchase single-serve cream cheese for breakfast applications.
- Catering Services:Event and institutional foodservice requiring bulk formats with flexible delivery scheduling. US corporate catering operators source cream cheese spreads for breakfast buffets.
Food manufacturers dominate installed base. Restaurants are where expansion concentrates as fast-casual Mediterranean concepts multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Meal kit operators and industrial food manufacturers concentrate procurement in three distinct buyer archetypes: subscription services demanding batch-level traceability, contract manufacturers seeking locked-in fat specifications, and fast-casual chains sourcing Mediterranean flavor components.
United States
Subscription meal kit services standardize cheddar and cream cheese specifications across refrigerated logistics networks. FDA standards of identity govern permissible ingredient declarations for clean-label reformulations. New York and California coastal markets drive feta cheese adoption for Mediterranean grain bowl applications.
Germany
Industrial ready-meal manufacturers source shredded and diced cheddar through cooperative dairy networks for melt-point precision. EU Green Deal agricultural targets and F-Gas Regulation cold-chain mandates elevate sustainable packaging compliance costs. Bavarian and North Rhine-Westphalia dairy cooperatives anchor export cheddar shipments to Asian markets.
Japan
Convenience retailers stock single-serve cream cheese cups for breakfast protein positioning. METI energy efficiency standards shape refrigerated distribution infrastructure investments. Tokyo and Osaka metropolitan areas concentrate demand for ambient-stable processed cheese in vending machine channels.
France
Specialty cheese exporters leverage Protected Designation of Origin frameworks for premium feta and aged cheese positioning. EFSA dairy labeling requirements mandate granular bacterial strain disclosure on fermented products. The Auvergne-Rhône-Alpes region hosts artisanal producers supplying Mediterranean restaurant chains in export markets.
India
Urban foodservice operators expand paneer and processed cheese procurement for fast-casual Indian and fusion menu development. FSSAI food safety regulations govern dairy processing standards and labeling requirements. Maharashtra and Gujarat dairy cooperatives scale production capacity to serve domestic quick-service restaurant expansion.
Savory Dairy Products Market Competitive Landscape
Player mix skews toward cooperative-owned dairy networks and multinational packaged food conglomerates with integrated ingredient supply chains. Tier concentration separates scale-driven commodity producers from premium-positioned specialty cheese specialists. Two strategic archetypes dominate: cooperative structures leveraging farmer-owned sourcing control, and diversified food manufacturers backward integrating into captive dairy ingredient networks. Competitive moves center on direct procurement relationships with meal kit operators and fermentation disclosure technology investments for clean-label premium positioning.
Within the cooperative archetype, Arla Foods and Fonterra exemplify farmer-owned structures that anchor European and Oceania savory dairy supply. Among diversified multinationals, Nestlé occupies a position representing integrated global dairy networks serving industrial formulation demand. These three companies represent the spectrum from regional cooperative concentration to multinational ingredient platform scale.
| Leading Market Players |
|---|
| Nestlé |
| Danone |
| Arla Foods |
| Lactalis |
| Fonterra |
| Saputo |
| FrieslandCampina |
| Dairy Farmers of America |
| Kraft Heinz |
| Others |
Value Network & Pricing Analysis
Precision fermentation for dairy protein analogs is displacing conventional milk fat inputs in German prepared meal manufacturing, simultaneously shifting procurement geography toward biotechnology hubs and compressing pricing premiums for traditional aged cheddar suppliers serving cost-sensitive contract manufacturers.
Pricing Analysis
Butterfat-indexed cost-plus contracts with quarterly adjustments dominate procurement between German dairy cooperatives and industrial ready-meal manufacturers. Three-tier pricing structure across premium clean-label fermentation, standard cooperative-sourced, and economy-grade processed cheese tiers separates buyers by EFSA disclosure compliance and bacterial culture transparency. Pricing pressure stems from precision fermentation pilots offering protein analogs at lower input volatility than milk fat. Contract manufacturers exhibit highest price sensitivity; meal kit operators absorb premiums for locked-in fat specifications.
Supply Chain Analysis
Sixty-to-ninety-day inventory cycles for aged cheddar reflect maturation timelines that constrain just-in-time responsiveness. Supply concentrates in Germany, the United States, and France for cultured cheese production, with New Zealand and Australia anchoring bulk milk powder inputs for processed variants. Raw material flows draw from butterfat spot markets, salt-tolerant culture suppliers, and sustainable packaging feedstocks. Single-source vulnerability sits with specialized dairy microbiology talent pools for sodium reduction formulation. Distribution runs through cooperative-owned networks direct to food manufacturers, bypassing traditional ingredient distributors in meal kit channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense against precision fermentation protein analogs that threaten to commoditize traditional umami-forward formulations in cost-sensitive industrial applications.
For Market Incumbents: Consolidate captive supply relationships with meal kit operators through locked-in fat specification contracts that precision fermentation cannot yet match for melt-point precision. Deepen backward integration into salt-tolerant culture engineering to defend formulation expertise scarcity against biotechnology entrants.
For New Entrants and Emerging Players: Lead with blockchain-tracked bacterial culture provenance to capture premium clean-label segments where EFSA disclosure mandates create first-mover separation. Target US coastal Mediterranean restaurant chains for bulk feta supply, exploiting underdeveloped distribution relative to cheddar saturation.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision fermentation platforms seeking downstream offtake agreements to validate protein analog economics. Five-to-ten-year viability hinges on fermentation cost parity with traditional dairy inputs. Watch for captive supply agreement announcements between meal kit operators and biotechnology firms as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Fermentation Investment | EFSA bacterial strain disclosure mandates force reformulation of established cheddar and cream cheese brands. |
| Meal Kit Captive Supply Agreement | Subscription services lock in standardized savory dairy components for recipe consistency across refrigerated logistics. |
| Precision Fermentation Pilot Scale-Up | German contract manufacturers test protein analogs for cost-sensitive prepared meal lines. |
| Sustainable Packaging Transition | EU Green Deal targets and F-Gas Regulation elevate compliance costs for refrigerated distribution. |
| Mediterranean Product Line Extension | US coastal markets drive feta adoption for grain bowl applications beyond saturated cheddar portfolios. |
Research Methodology
A spread of perspectives from dairy cooperative procurement directors, food manufacturer R&D leads, meal kit supply chain managers, and EFSA regulatory affairs specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through FDA standards of identity documentation, EU Green Deal agricultural target disclosures, F-Gas Regulation compliance filings, and customs trade data for dairy ingredient flows. Bottom-up volume modeling triangulated against top-down value estimates derived from cooperative network production disclosures.
Segmentation dimensions modeled span product type, application, packaging format, and end-user category across the projection horizon. Cheddar cheese maturation cycles, meal kit subscription growth trajectories, and cold-chain infrastructure investments in Germany and Japan fed analytical frameworks. CAGRs were synthesized from installed base expansion rates and substitution elasticity assumptions for precision fermentation alternatives.
Underlying assumptions cover sustained EFSA disclosure stringency, stable butterfat price corridors, and precision fermentation cost reduction curves, with deviation risk concentrated in regulatory acceleration or biotechnology breakthrough timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Organic Milk Market
Dairy Products
North America Dairy Desserts Market
Dairy Products
Milk Protein Concentrate Market
Dairy Products
Solidified Yogurt Market
Dairy Products
North America Flavored Milk Market
Dairy Products
Sour Cream Market
Dairy Products
Malted Milk Powder Market
Dairy Products
Europe Casein and Caseinates Market
Dairy Products
US and Europe Nuts and Seeds Cheese Market
Dairy Products
Cheese Color Market
Dairy Products
Fermented Dairy Ingredients Market
Dairy Products
Cultured Whey Products Market
Dairy Products
United Kingdom Casein and Caseinates Market
Dairy Products
Evaporated Filled Milk Market
Dairy Products
Butter Concentrate Market
Dairy Products
Global Dairy Market