
 Asia-Pacific Casein and Caseinates Market | 2026-2036
Asia-Pacific Casein and Caseinates Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Casein and Caseinates Market Outlook
Multi-source procurement among dairy ingredient buyers is shifting toward vertically integrated suppliers with captive milk streams. Fonterra Co-operative Group Limited anchors New Zealand's casein export pipeline through cooperative-owned processing infrastructure. Gansu Hua'an Biotechnology Group leverages regional whey streams to sustain cost-competitive caseinate production in northwest China. Royal FrieslandCampina N.V. differentiates through European-origin quality protocols applied to its Southeast Asian blending operations.
Casein and caseinates denote protein fractions precipitated from skim milk via acid or rennet treatment, then dried into functional powders with emulsifying, gelling, and nutritional binding properties. Acid casein retains superior adhesive qualities for wood glue and paper coating, while micellar casein preserves native protein structure for slow-release amino acid delivery in nutritional supplements. Sodium caseinate leads food-grade applications for its solubility and fat-emulsification performance, whereas calcium caseinate gains share in pharmaceutical sector tablet formulations where mineral fortification intersects with controlled protein release. Powder form dominates bulk industrial offtake, though liquid caseinate concentrates penetrate ready-to-drink nutritional supplement channels requiring reduced reconstitution steps.
FSSAI standards in India govern maximum moisture and ash content in edible casein, while China's GB standards and NMPA oversight mandate heavy metal thresholds and production facility licensing for domestic and imported products. Japan's Ministry of Health, Labour and Welfare applies positive-list screening to novel caseinate applications in functional foods, creating compliance bottlenecks for entrants. Stakeholders must monitor evolving protein-labeling regulations and traceability mandates across Australia, South Korea, and ASEAN harmonization frameworks to preempt market access disruptions.
Market Dynamics
Cooperative-owned processing infrastructure across New Zealand and India's western dairy belt is consolidating milk sourcing power, compressing spot-market availability and forcing ingredient buyers into long-term offtake commitments with vertically integrated suppliers.
Growth Catalysts
- Sports nutrition fortification:Southeast Asian protein powder manufacturers are expanding sodium caseinate procurement for ready-to-mix formulations targeting gym-goers and amateur athletes.
- FSSAI edible casein standards:India's tightened moisture and ash content thresholds are professionalizing domestic production quality, enabling export-grade output from cooperatives in Maharashtra and Gujarat.
- Rennet casein adhesive demand:Wood glue and paper coating applications in Australia's manufacturing sector are pulling acid casein volumes away from purely nutritional uses.
Market Restraints
- Skim milk powder price volatility:Feedstock costs for casein precipitation fluctuate with global dairy commodity cycles, squeezing processor margins during El Niño-driven supply contractions.
- NMPA facility licensing bottlenecks:China's food additive production permits require multi-year approval timelines, freezing capacity expansion for domestic caseinate manufacturers.
- Plant protein substitution:Pea and rice protein isolates are capturing share in mass-market sports nutrition, pressuring caseinate pricing in economy-tier formulations.
Strategic Opportunities
- Vietnam dairy processing gap:Underdeveloped domestic caseinate production creates import dependency that regional suppliers from Thailand and New Zealand can capture through dedicated distribution partnerships.
- Pharmaceutical tablet binding:Calcium caseinate's mineral fortification properties align with Japan's aging-population supplement demand for controlled-release protein delivery.
- ASEAN harmonization frameworks:Emerging mutual recognition agreements for dairy ingredient standards will reduce redundant testing costs for cross-border trade within Southeast Asia.
Industry Challenges
- Spray-drying energy intensity:Caseinate powder production requires substantial thermal input, exposing processors to carbon pricing mechanisms under South Korea's emissions trading scheme.
- Traceability system integration:Blockchain-enabled milk provenance tracking demands IT infrastructure upgrades that smaller Indian cooperatives struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Casein and Caseinates Market |
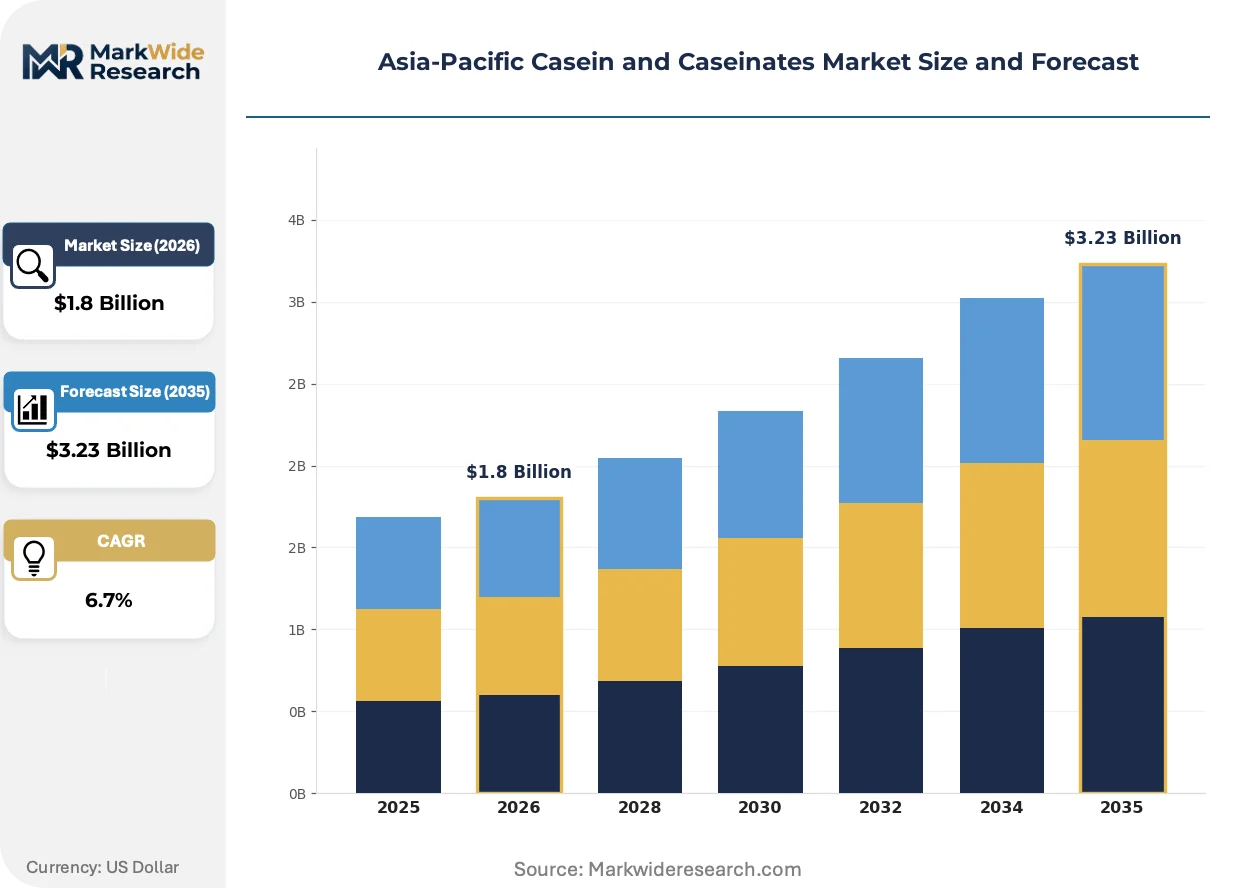
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Casein, Sodium Caseinate, Calcium Caseinate, Micellar Casein End User: Food Industry, Pharmaceutical Sector, Dairy Products, Nutritional Supplements Form: Powder, Liquid, Granular, Tablet Distribution Channel: Online Retail, Supermarkets, Direct Sales, Wholesale |
| Companies Covered | Arla Foods amba, Fonterra Co-operative Group Limited, Gansu Hua'an Biotechnology Group, Lacto Japan Co., Ltd., Royal FrieslandCampina N.V., Nestlé S.A., Saputo, Groupe Lactalis, AMCO Proteins, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Casein and Caseinates Market Strategic Shifts
Micellar casein preservation technology and clean-label protein positioning are reconfiguring how ingredient buyers evaluate supplier partnerships across the Asia-Pacific dairy derivatives landscape.
Membrane filtration advances in micellar casein extraction are unifying protein integrity with industrial scalability. Australian sports nutrition contract manufacturers are adopting ceramic microfiltration systems at pace, enabling native protein structure preservation for slow-release amino acid delivery. This unifying capability is compressing the quality gap between commodity acid casein and premium nutritional grades.
China's NMPA tightening of food additive labeling rules is forcing reformulation investments among imported caseinate distributors. Domestic brands must now declare protein source origins on packaging, triggering supply chain audits and documentation overhauls. Japanese functional food entrants face the steepest compliance burden as positive-list screening delays novel application approvals.
Direct procurement from cooperative processors is displacing traditional trader intermediaries in India's western dairy belt. Large-scale bakery and confectionery manufacturers in Mumbai and Pune are establishing captive supply relationships with Maharashtra-based spray-drying facilities. This channel compression is most visible in export-oriented operations seeking FSSAI-certified traceability for European and Middle Eastern buyers.
Asia-Pacific Casein and Caseinates Market Segmentation
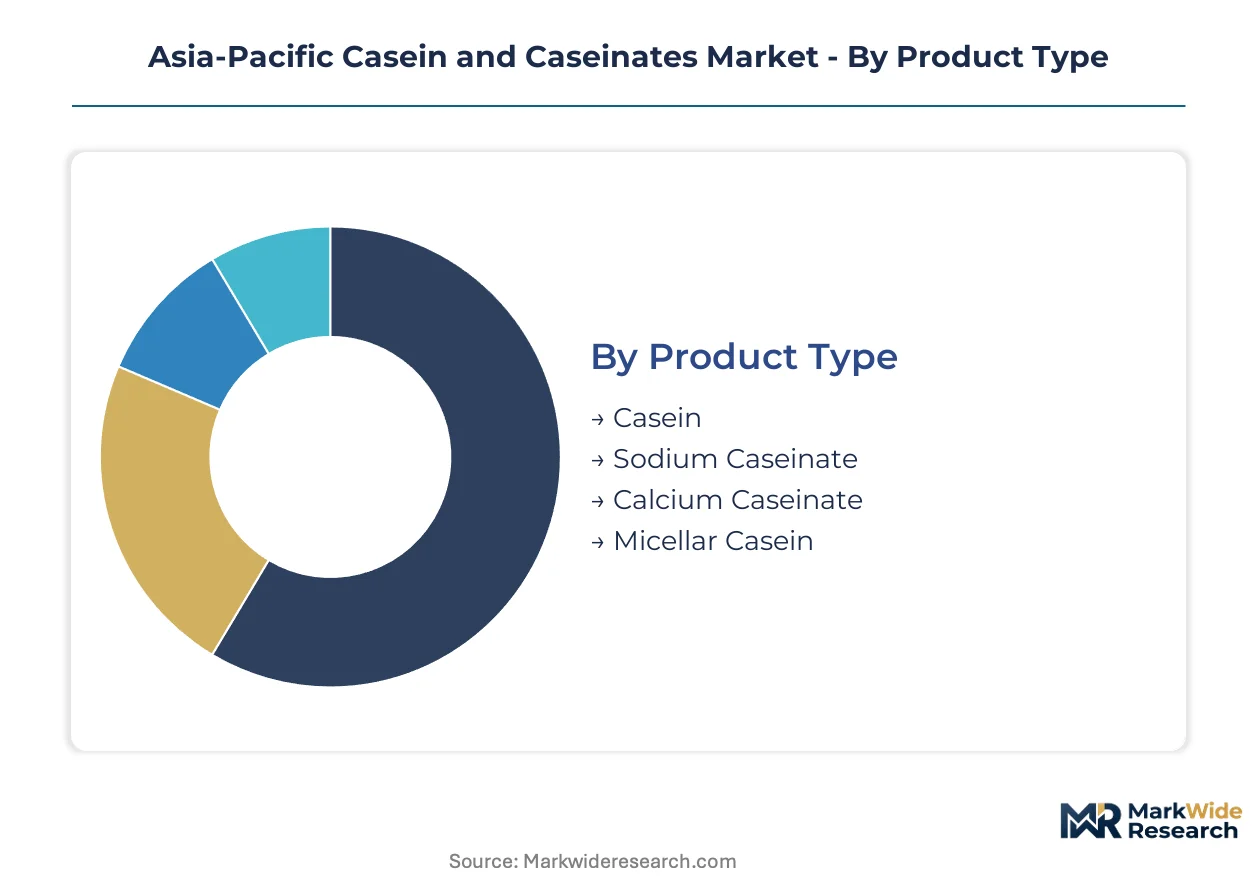
Casein and caseinate procurement decisions across Asia-Pacific hinge on solubility profiles, mineral fortification requirements, and downstream processing compatibility. Buyers segment suppliers by functional performance rather than commodity pricing alone.
Product Type:
Formulators prioritize emulsification stability and protein bioavailability when selecting casein variants for specific applications.
- Casein:Acid-precipitated protein retains superior adhesive properties for industrial binders in Australia's wood glue sector. Rennet casein variants command premium positioning in Japanese functional foods where texture integrity drives repeat purchase behavior.
- Sodium Caseinate:Highly soluble salt form dominates Southeast Asian sports nutrition manufacturing for ready-to-mix protein fortification. Thai and Vietnamese contract manufacturers specify sodium caseinate for its fat-emulsification performance in instant beverage applications.
- Calcium Caseinate:Mineral-fortified variant aligns with Japan's aging-population supplement demand for controlled-release protein delivery in tablet formulations.
- Micellar Casein:Native protein structure preservation enables slow-release amino acid profiles favored by Australian premium sports nutrition brands targeting overnight recovery positioning.
Sodium caseinate leads on scale across food-grade applications; micellar casein gains momentum fastest in premium nutritional segments.
End User:
Regulatory compliance intensity varies sharply across buyer categories, with pharmaceutical and nutritional applications facing the strictest documentation burdens.
- Food Industry:Bakery and confectionery manufacturers in Mumbai and Pune source FSSAI-certified spray-dried caseinate for export-grade emulsification. India's western dairy belt cooperatives scale output specifically for European and Middle Eastern food industry buyers demanding traceability documentation.
- Pharmaceutical Sector:Tablet binding applications in Japan require calcium caseinate meeting PMDA positive-list standards for novel excipient approvals. Mineral fortification intersects with controlled protein release specifications in geriatric supplement formulations.
- Dairy Products:Processed cheese manufacturers across New Zealand leverage acid casein for melt-stretch functionality in pizza cheese analogs.
- Nutritional Supplements:Southeast Asian gym culture expansion drives sodium caseinate procurement for amateur athlete protein powders.
Food industry procurement dominates absolute volume; pharmaceutical sector applications climb fastest on margin expansion.
Form:
Reconstitution labor and storage economics determine powder versus liquid selection in downstream manufacturing workflows.
- Powder:Spray-dried caseinate dominates bulk industrial offtake across Asia-Pacific due to extended shelf stability and reduced shipping costs. Indian cooperatives in Maharashtra and Gujarat specialize in export-grade powder production for international ingredient distributors.
- Liquid:Concentrates penetrate ready-to-drink nutritional supplement channels in Australia and New Zealand where manufacturers seek reduced reconstitution steps.
- Granular:Intermediate flowability suits intermediate processing stages in Southeast Asian blending operations.
- Tablet:Direct-compression grades serve Japanese pharmaceutical manufacturers requiring precise disintegration profiles.
Powder commands the installed manufacturing base; liquid concentrates expand most quickly in beverage-ready applications.
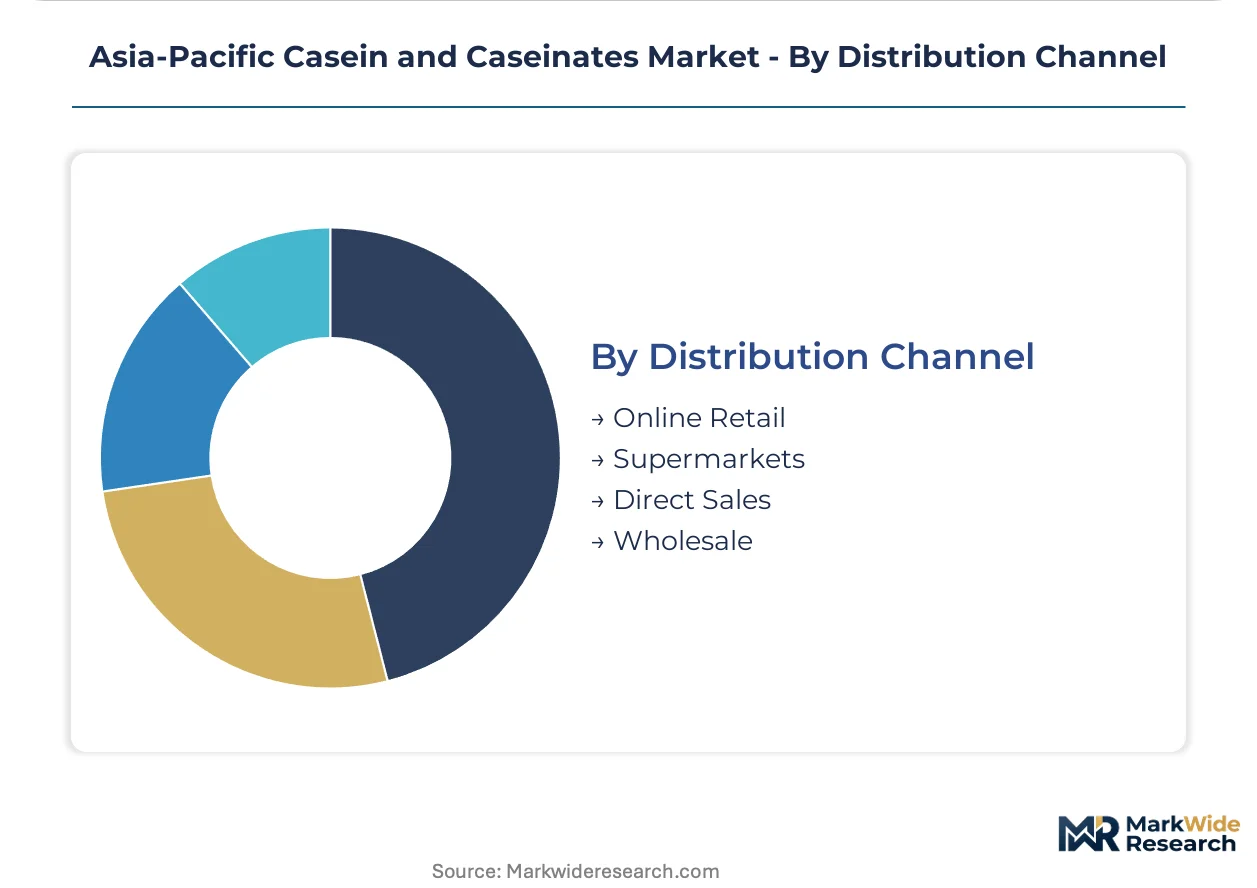
Distribution Channel:
Traceability requirements and volume scale dictate whether buyers source through trader intermediaries or direct cooperative relationships.
- Online Retail:Specialty ingredient platforms serve small-batch nutritional supplement startups in South Korea and Australia seeking sample quantities without minimum order constraints.
- Supermarkets:Consumer-packaged caseinate products reach amateur athletes through mass retail in Thailand's urban centers.
- Direct Sales:Large-scale bakery and confectionery manufacturers in India's western dairy belt bypass traders to establish captive supply relationships with Maharashtra-based spray-drying facilities.
- Wholesale:Regional ingredient distributors aggregate volumes for Southeast Asian processors lacking cold-chain infrastructure for liquid concentrate handling.
Direct sales anchor volume throughput for established manufacturers; online retail channels gain share fastest among emerging brand entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography across Asia-Pacific as processors migrate toward jurisdictions with streamlined food additive licensing and lower energy costs for spray-drying operations.
China
NMPA facility licensing bottlenecks are freezing domestic capacity expansion while imported caseinate distributors absorb reformulation costs from tightened food additive labeling rules. Gansu Hua'an Biotechnology Group leverages regional whey streams in northwest China to sustain cost-competitive production despite regulatory headwinds. The NMPA's multi-year approval timelines for production permits are pushing some processors toward contract manufacturing arrangements in neighboring markets.
India
FSSAI edible casein standards are professionalizing domestic production quality and enabling export-grade output from cooperatives in Maharashtra and Gujarat. The western dairy belt is consolidating spray-dried caseinate capacity specifically for European and Middle Eastern buyers demanding traceability documentation. Mumbai and Pune-based bakery manufacturers are establishing direct procurement relationships with Maharashtra spray-drying facilities to bypass trader intermediaries.
Japan
PMDA positive-list screening creates compliance bottlenecks for novel caseinate applications in functional foods and pharmaceutical tablet formulations. Calcium caseinate demand is climbing among geriatric supplement manufacturers seeking controlled-release protein delivery with mineral fortification. The Ministry of Health, Labour and Welfare's regulatory intensity is compressing market access for entrants lacking established documentation protocols.
Australia
Acid casein adhesive demand from wood glue and paper coating applications is pulling volumes away from purely nutritional uses. Sports nutrition contract manufacturers are adopting ceramic microfiltration systems for micellar casein extraction to preserve native protein structures. Carbon pricing mechanisms under the national emissions trading scheme are exposing spray-drying operations to energy cost volatility.
Vietnam
Underdeveloped domestic caseinate production is creating import dependency that regional suppliers from Thailand and New Zealand are capturing through dedicated distribution partnerships. Wholesale ingredient distributors are aggregating volumes for processors lacking cold-chain infrastructure for liquid concentrate handling. Urban mass retail channels in Ho Chi Minh City and Hanoi are reaching amateur athletes with consumer-packaged caseinate products.
Asia-Pacific Casein and Caseinates Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue pharmaceutical-grade certification and clean-label positioning to escape commodity pricing pressure. The supplier base stratifies between cooperative-owned processing infrastructure with captive milk streams and independent processors dependent on spot-market skim milk powder. Three archetypes dominate: vertically integrated dairy cooperatives, regional biotechnology specialists leveraging whey byproduct streams, and European-origin multinationals applying quality protocols to Southeast Asian blending operations. Competitive moves center on backward integration into milk sourcing and geographic expansion through dedicated distribution partnerships in underdeveloped markets.
Among cooperative-structured producers, Fonterra Co-operative Group Limited and Royal FrieslandCampina N.V. exemplify the vertically integrated archetype with processing infrastructure anchored in New Zealand and European-origin quality systems. Gansu Hua'an Biotechnology Group represents the regional specialist model, occupying a position within China's northwest dairy processing corridor where whey stream access sustains cost positioning. These three entities collectively illustrate how scale, geographic origin, and feedstock integration define competitive positioning in Asia-Pacific casein and caseinate supply.
| Leading Market Players |
|---|
| Arla Foods amba |
| Fonterra Co-operative Group Limited |
| Gansu Hua'an Biotechnology Group |
| Lacto Japan Co., Ltd. |
| Royal FrieslandCampina N.V. |
| Nestlé S.A. |
| Saputo |
| Groupe Lactalis |
| AMCO Proteins |
| Others |
Value Chain & Pricing Dynamics
Spray-drying energy intensity in caseinate powder production simultaneously elevates thermal cost exposure and consolidates processing capacity toward cooperative-owned facilities with captive energy sourcing. This technological shift compresses margin structures for independent processors while amplifying pricing power among vertically integrated suppliers in New Zealand and India's western dairy belt.
Pricing Analysis
Distributor margins in Southeast Asian ingredient channels absorb documentation costs from NMPA labeling rule compliance. Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial-grade casein separates premium micellar casein for Australian sports nutrition from commodity acid casein for wood glue applications. Cost compression in economy-tier sodium caseinate intensifies because pea protein isolates capture mass-market sports nutrition share. Small-batch nutritional supplement startups in South Korea exhibit highest price sensitivity; Japanese pharmaceutical manufacturers show lowest sensitivity due to PMDA certification requirements.
Supply Chain Analysis
Single-source vulnerability sits with New Zealand cooperative processors controlling Fonterra's export pipeline infrastructure. Geographic supply concentration clusters in New Zealand, India, and China where regional whey stream access feeds into caseinate production. Raw material dependencies center on skim milk powder, regional whey availability, and spray-drying energy inputs. Tariff exposure from ASEAN harmonization delays creates inventory positioning risks for cross-border trade. Distribution runs through wholesale ingredient aggregators for Southeast Asian processors lacking direct cooperative relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
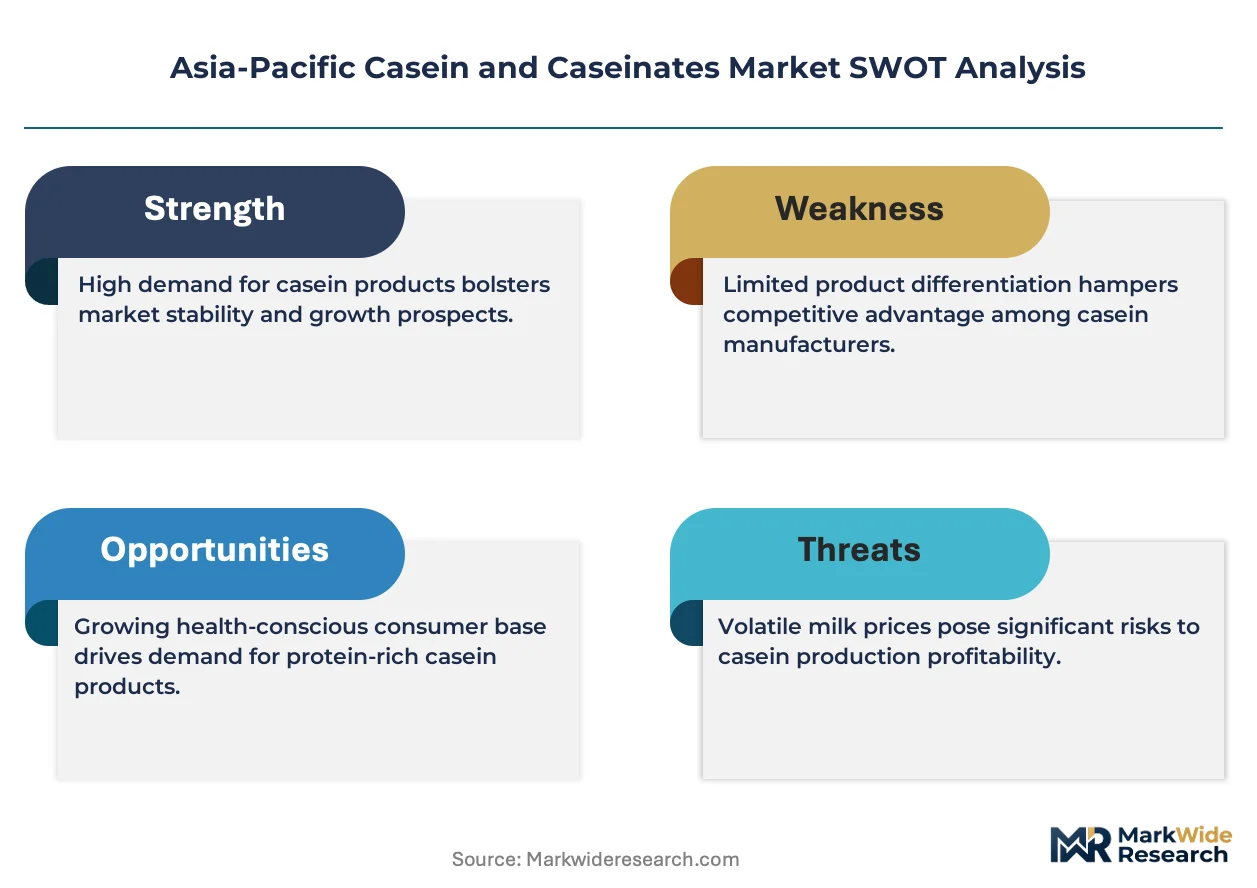
This market functions as a geographic-arbitrage play where NMPA facility licensing bottlenecks in China push processing investment toward India's FSSAI-professionalized western dairy belt with streamlined certification pathways.
For Market Incumbents: Cement backward integration into captive milk sourcing across Maharashtra and Gujarat cooperatives to lock in FSSAI-certified traceability documentation for European export demand. Expand spray-drying capacity in energy-cost-advantaged geographies before South Korea's emissions trading scheme carbon pricing intensifies. Plant protein substitution in economy-tier sports nutrition represents the core threat requiring premium-grade micellar casein differentiation investment. For New Entrants and Emerging Players: Enter via Vietnam's underdeveloped domestic caseinate production gap through dedicated distribution partnerships with Thai and New Zealand regional suppliers. Target pharmaceutical-grade calcium caseinate for Japan's aging-population tablet binding applications where PMDA positive-list screening delays create incumbent vulnerability. Pursue clean-label positioning and ceramic microfiltration technology adoption as the primary go-to-market angle against commodity acid casein incumbents. For Investors and Strategic Acquirers: Valuations sit cheapest among independent processors dependent on spot-market skim milk powder without cooperative milk sourcing integration. Long-term viability across the projection horizon favors acquisition targets with established FSSAI or NMPA facility licensing and export-grade spray-drying infrastructure. Monitor ASEAN mutual recognition agreement implementation progress as the signal to watch for cross-border trade cost reduction inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Milk Sourcing | Maharashtra cooperatives secure FSSAI-certified traceability for European export demand. |
| Ceramic Microfiltration Technology Adoption | Australian contract manufacturers preserve native protein structures for premium sports nutrition positioning. |
| Pharmaceutical-Grade Certification Investment | Calcium caseinate producers access Japan's PMDA-controlled geriatric supplement tablet formulations. |
| Dedicated Distribution Partnership Expansion | Thai and New Zealand suppliers capture Vietnam's import-dependent caseinate demand gap. |
| Clean-Label Protein Positioning | Micellar casein extraction enables slow-release amino acid marketing against plant protein substitutes. |
Study Parameters
Bottom-up nutritional supplement and pharmaceutical procurement modeling reconciled against top-down dairy cooperative production capacity tracking forms the analytical core. Primary interviews with spray-drying facility managers, FSSAI compliance officers at Maharashtra cooperatives, sports nutrition contract manufacturing procurement leads, and NMPA regulatory affairs specialists combined with secondary validation from customs trade data, FSSAI edible casein standard filings, NMPA food additive licensing records, and ASEAN harmonization framework documentation.
Input-output matrices map casein variant production volumes through end-use application demand across food industry, pharmaceutical sector, dairy products, and nutritional supplements segments. Segmentation dimensions include product type tier, end-user regulatory intensity, powder versus liquid form factor, and direct sales versus wholesale channel configuration. CAGRs derive from trajectory fitting against historical dairy commodity cycles and regulatory implementation timelines. Forecast inputs incorporate El Niño-driven skim milk powder supply contraction patterns and carbon pricing mechanism exposure under South Korea's emissions trading scheme.
Inputs from cooperative processing facility disclosures and regulatory filing databases were available through the study window; gaps in real-time spot-market skim milk powder transaction data introduce uncertainty bands around margin compression scenarios. Forecasts reflect documented assumptions about ASEAN mutual recognition timeline progression and NMPA licensing approval velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
A2 Protein Milk Market
Dairy Products
Sweetened Condensed Milk Market
Dairy Products
Global Lipolyzed Butter Fat Market
Dairy Products
Reduced Fat Dairy Market
Dairy Products
Asia-Pacific Dairy Market
Dairy Products
Yogurt and Probiotic Drink Market
Dairy Products
Qatar Dairy Products Market
Dairy Products
GCC Cheese Market
Dairy Products
Cheese Crumbles Market
Dairy Products
A2 Fresh Milk Market
Dairy Products
United States Milk Protein Market
Dairy Products
Organic Milk Powder Market
Dairy Products
White Cheese Market
Dairy Products
Argentina Whey Protein Market
Dairy Products
Probiotic Yogurt Market
Dairy Products
Camel Dairy Market