
 Dry Mix Base for Frozen Desserts Market | 2026-2036
Dry Mix Base for Frozen Desserts Market Size, Share, and Industry Trends Forecast 2026-2036
Dry Mix Base for Frozen Desserts Market Foresight
Recurring formulation support services is repositioning how manufacturers monetize dry mix bases beyond one-time ingredient sales. Itaberco leverages its technical consultation programs to lock in foodservice accounts with customized stabilizer blends. All American Foods sustains large-scale production through backward integration into dairy protein sourcing. Kent Precision Foods Group dominates the private-label channel for regional grocery chains.
A dry mix base for frozen desserts comprises spray-dried dairy solids, emulsifiers, stabilizers, and flavor precursors that reconstitute with water or milk to produce consistent frozen dessert matrices with target overrun values of 80-100%. The formulation serves commercial producers seeking batch-to-batch uniformity without liquid cold-chain dependency. Ice cream mix formulations command the largest volume share due to their ubiquity across foodservice and retail channels, while non-dairy formulation types are expanding fastest as oat and coconut protein stabilizer systems mature. Gelato base segments carry premium positioning in artisan applications where lower overrun targets and higher fat concentrations justify specialized ingredient sourcing.
The FDA governs dairy identity standards and allergen labeling under FALCPA, directly constraining how non-dairy formulation types are positioned relative to traditional ice cream mixes. The USDA Organic seal and third-party gluten-free certifications create tiered market access thresholds that filter which producers can supply specific retail banners. Stakeholders must monitor evolving plant-based identity standards and clean-label stabilizer approvals to preserve formulation flexibility.
Market Dynamics
Pre-formulated dry mix bases are consolidating production control across quick-service restaurants and artisan ice cream shops, shifting value capture from ingredient suppliers toward integrated formulation services that lock in recurring revenue streams.
Growth Catalysts
- Plant-Based Dairy Alternatives:FDA labeling updates for non-dairy identity standards are forcing reformulation investments that favor suppliers with regulatory navigation capabilities.
- Spray-Dried Protein Systems:Oat and coconut protein stabilizer technologies are maturing, enabling clean-label frozen desserts without cold-chain dependency.
- Southeast Manufacturing Corridors:Concentrated foodservice expansion across the United States is generating batch-to-batch uniformity demand from regional production hubs.
Market Restraints
- Dairy Protein Input Volatility:Backward-integrated suppliers control pricing power, squeezing margins for non-integrated dry mix base producers.
- Allergen Labeling Friction:FALCPA compliance complexity raises formulation costs and extends product development timelines.
- Liquid Mix Substitution:Fresh dairy processors in the Midwest retain cost advantages for high-volume foodservice accounts with reliable cold-chain infrastructure.
Strategic Opportunities
- Private-Label Regional Grocery:Captive supply relationships with supermarket banners enable margin expansion through exclusive stabilizer blends.
- USDA Organic Certification Tier:Premium positioning through third-party validation opens shelf access at natural retail banners with stricter entry thresholds.
- Artisan Gelato Channel:Lower overrun targets and specialized fat concentrations justify technical consultation fees from boutique producers.
Industry Challenges
- Clean-Label Stabilizer Approval Timelines:Novel hydrocolloid petitions face extended FDA review cycles, delaying product launches.
- Emulsifier System Integration:Legacy batch equipment requires retrofitting to handle next-generation protein stabilizer hydration rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dry Mix Base for Frozen Desserts Market |
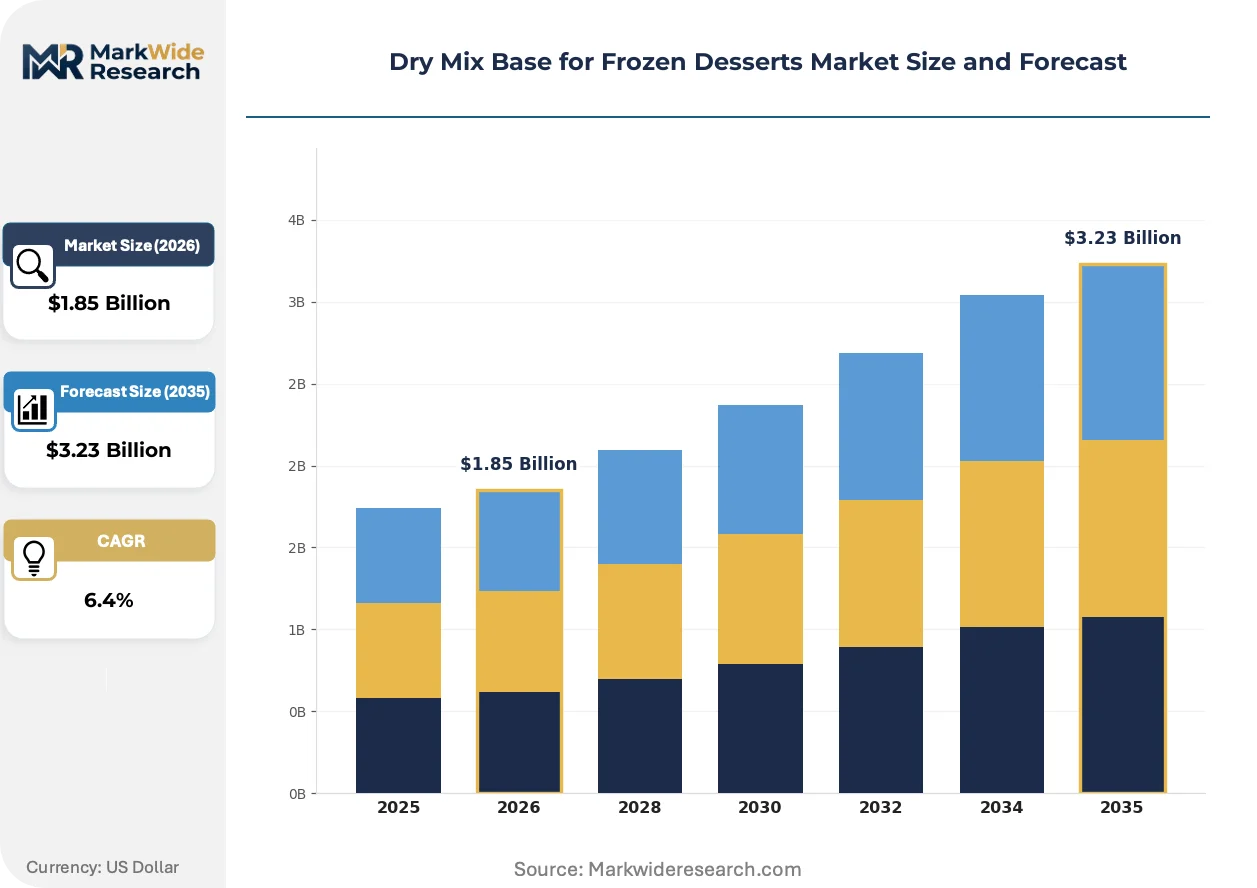
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ice Cream Mix, Sorbet Base, Frozen Yogurt Mix, Gelato Base Flavor Profile: Vanilla, Chocolate, Strawberry, Mango Formulation Type: Organic, Gluten-Free, Non-Dairy, Sugar-Free Application: Food Service, Retail, Home Use, Commercial |
| Companies Covered | Itaberco, All American Foods, Nanci's Frozen Yogurt, The Langlois, Alpha Freezz, Kent Precision Foods Group, AussieBlends, Mr Dewie's Cashew Creamery, Nimje Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dry Mix Base for Frozen Desserts Market Shifts & Advancements
Formulation science is pivoting toward modular stabilizer architectures that let producers customize overrun and mouthfeel without reformulating from scratch. Technical service bundling now separates competitive winners from commodity suppliers.
Spray-dried oat protein isolate systems are expanding into mainstream ice cream formulations previously dominated by dairy solids. Quick-service chains with standardized menu boards are adopting these bases to simplify supplier management and reduce allergen cross-contamination risk. The technology is expanding into mid-tier retail private labels where cost parity with conventional dairy mixes has recently been achieved.
REACH-compliant emulsifier sourcing requirements are reshaping supplier qualification protocols for European-bound exports. Manufacturers must now document full supply chain substance volumes and toxicity profiles. Gelato base segments face the steepest compliance burden due to their reliance on specialty lipids with complex additive packages.
Foodservice procurement teams are consolidating vendor lists around suppliers offering integrated technical consultation. Regional dairy cooperatives that once sold commodity powders now compete against specialized dry mix houses with in-house application labs. The United States exhibits the most pronounced concentration, with Southeast manufacturing corridors leading the shift toward single-source formulation partnerships.
Dry Mix Base for Frozen Desserts Market Segmentation
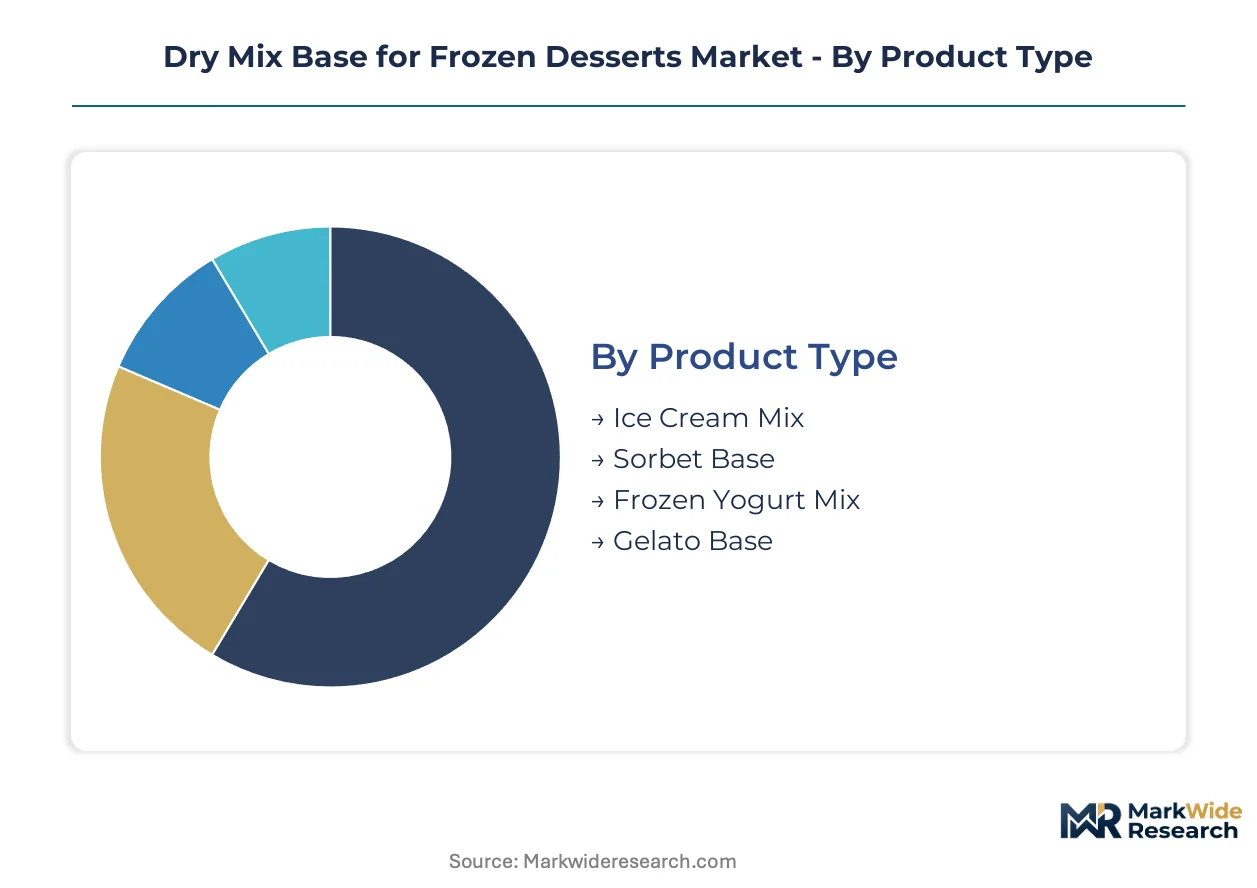
Dry mix base segmentation determines equipment compatibility, reconstitution protocols, and distribution channel eligibility. Manufacturers configure production lines around specific segment requirements rather than producing universal formulations.
Product Type:
Standalone dry mix bases dominate commercial procurement, while embedded stabilizer systems serve co-manufacturing relationships requiring ingredient transparency.
- Ice Cream Mix:Spray-dried dairy solids with 10-16% butterfat content and emulsifier systems calibrated for 80-100% overrun targets. Quick-service chains in the United States Southeast manufacturing corridors specify this base for batch-to-batch uniformity across multi-unit operations.
- Gelato Base:Higher fat concentrations (16-20%) with specialized stabilizer architectures designed for lower overrun (20-35%) and denser mouthfeel. Artisan producers in the United States Midwest pay technical consultation fees for customized formulations that justify premium positioning.
- Sorbet Base:Fruit-sugar-stabilizer matrices without dairy solids, requiring precise hydrocolloid hydration control.
- Frozen Yogurt Mix:Acidified dairy protein systems with live culture compatibility and tartness modulation.
Ice cream mix leads volumes today; gelato base is gaining share fastest.
Flavor Profile:
Flavor segmentation aligns with manufacturing run economics and clean-label certification tiers rather than consumer preference mapping alone.
- Vanilla:Bourbon and Tahitian extract variants with natural flavor precursor stability challenges. United States retail private-label programs specify this profile for base formulation standardization.
- Chocolate:Cocoa butter compatibility requirements and alkalization processing variables. Foodservice accounts in the United States Southeast prioritize this profile for menu consistency.
- Strawberry:Freeze-dried fruit powder integration with pH stability concerns.
- Mango:Tropical flavor precursor sourcing with seasonal availability constraints.
Vanilla anchors production volumes; chocolate commands the highest formulation service fees.
Formulation Type:
Certification-driven segments filter market access through regulatory compliance thresholds and third-party validation requirements.
- Non-Dairy:Oat and coconut protein stabilizer systems replacing dairy solids with clean-label positioning. FDA labeling updates for plant-based identity standards are forcing reformulation investments that favor suppliers with regulatory navigation capabilities in the United States.
- Organic:USDA Organic seal requirements constraining emulsifier and stabilizer sourcing to National List substances. United States natural retail banners use this certification as a shelf-access threshold.
- Gluten-Free:Third-party certification protocols with cross-contamination prevention documentation.
- Sugar-Free:Polyol and high-intensity sweetener systems with freezing point depression calculations.
Non-dairy formulations are climbing the fastest; organic maintains the tightest supply qualifications.
Application:
Application segmentation reflects cold-chain infrastructure availability and batch size economics rather than end-product differentiation.
- Food Service:High-volume reconstitution protocols with equipment calibration support requirements. United States quick-service restaurants specify this segment for supplier consolidation and allergen risk reduction.
- Commercial:Mid-scale production with technical service bundling and customized stabilizer blend development.
- Retail:Consumer-facing packaging with extended shelf-life requirements and reconstitution instruction clarity.
- Home Use:Small-format packaging with simplified hydration ratios and minimal equipment assumptions.
Food service drives current procurement volumes; commercial applications show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States diverge sharply in dry mix base adoption patterns, with German producers prioritizing REACH-compliant emulsifier sourcing while American manufacturers chase Southeast corridor foodservice expansion. This bifurcation shapes distinct regulatory compliance burdens and supply chain configurations across both markets.
United States
Quick-service restaurants across Florida and Georgia manufacturing corridors drive batch-to-batch uniformity demand for ice cream mix formulations. FDA labeling updates for plant-based dairy alternatives force reformulation investments among suppliers serving natural retail banners. Charlotte and Atlanta anchor regional production hubs where single-source formulation partnerships concentrate procurement decisions.
Germany
Artisan gelato producers in Bavaria and Baden-Württemberg pay premium technical consultation fees for specialized fat concentration formulations. ECHA REACH compliance documentation requirements reshape supplier qualification protocols for European-bound exports. Munich-based dry mix houses compete against regional dairy cooperatives through integrated application laboratory services.
Italy
Traditional gelato craftsmanship in Emilia-Romagna and Lombardy sustains demand for lower overrun base formulations with dense mouthfeel specifications. EU Green Deal sustainability reporting obligations filter emulsifier sourcing toward bio-based alternatives. Bologna and Milan host formulation development centers serving boutique producers across the Mediterranean export corridor.
France
Luxury frozen dessert houses in Île-de-France specify premium gelato bases with specialized stabilizer architectures for premium positioning. ANSM oversight of food additive safety assessments extends approval timelines for novel hydrocolloid petitions. Parisian co-manufacturing clusters demand embedded stabilizer systems with full ingredient transparency documentation.
Japan
Convenience store chains in Tokyo and Osaka metropolitan areas standardize on spray-dried protein systems for soft-serve consistency across franchise networks. METI technical standards for food manufacturing equipment calibration influence reconstitution protocol specifications. Nagoya industrial zones concentrate dairy protein processing capacity serving domestic dry mix base producers.
Dry Mix Base for Frozen Desserts Market Competitive Landscape
Top-tier vendors anchor private-label and foodservice channels, while mid-scale specialists compete through technical consultation bundling and customized stabilizer development. The vendor base stratifies across three tiers: multinational ingredient houses with backward-integrated dairy protein sourcing, regional dry mix specialists with captive application laboratories, and commodity powder traders lacking formulation services. Two dominant competitive moves define current positioning: geographic expansion into Southeast United States manufacturing corridors, and portfolio diversification toward oat and coconut protein stabilizer systems.
Within the technical consultation tier, Itaberco and Kent Precision Foods Group exemplify suppliers locking in recurring revenue through customized stabilizer blend programs. All American Foods occupies a position among backward-integrated producers controlling dairy protein input costs through upstream supply chain ownership. These three companies represent distinct archetypes—formulation service bundlers, private-label channel dominators, and integrated commodity processors—each pursuing margin defense through different capability configurations.
| Leading Market Players |
|---|
| Itaberco |
| All American Foods |
| Nanci's Frozen Yogurt |
| The Langlois |
| Alpha Freezz |
| Kent Precision Foods Group |
| AussieBlends |
| Mr Dewie's Cashew Creamery |
| Nimje Industries |
| Others |
Supply & Pricing Matrix
Dairy protein spot indices cascading through Southeast United States manufacturing corridors stratify dry mix base procurement into contract-linked and spot-market tiers, with backward-integrated suppliers commanding premium positioning over commodity powder traders lacking captive dairy sourcing.
Pricing Analysis
Capacity additions in the United States Southeast are reshaping price floors for ice cream mix formulations as regional production hubs achieve economies of scale. Three-tier pricing structure across premium, standard, and economy levels separates USDA Organic certified bases with National List emulsifier sourcing from conventional dairy solids and unbranded commodity powders. Pricing pressure stems from liquid mix substitution in Midwest foodservice accounts with reliable cold-chain infrastructure. Quick-service restaurant chains exhibit highest price sensitivity due to standardized menu cost targets, while artisan gelato shops accept formulation service premiums for customized fat concentration blends.
Supply Chain Analysis
Freight cost volatility between Midwest dairy processing zones and Southeast manufacturing corridors incentivizes regional production hub development near Charlotte and Atlanta. Supply concentrates in the United States, Germany, and Italy for specialized gelato base formulations with REACH-compliant emulsifier documentation. Raw material dependencies center on spray-dried dairy solids, oat protein isolates, and coconut-derived stabilizer systems. Single-source vulnerability risks emerge from concentrated hydrocolloid suppliers facing extended FDA petition review cycles. Distribution runs through foodservice redistribution centers and private-label co-manufacturing clusters serving regional grocery banners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards margin expansion through technical consultation bundling that captures recurring revenue streams beyond commodity ingredient sales, with oat protein stabilizer maturation enabling clean-label premium tier migration.
For Market Incumbents: Acquire application laboratory capabilities to lock in foodservice accounts with customized stabilizer blend development. Defend against liquid mix substitution in Midwest corridors by embedding equipment calibration support into long-term supply contracts. Prioritize backward integration into dairy protein sourcing to insulate margins from input volatility squeezing non-integrated competitors. For New Entrants and Emerging Players: Direct-to-foodservice digital procurement platforms offer lowest barrier entry for oat protein-based non-dairy formulations with simplified allergen documentation. Target artisan gelato channels in Bavaria and Emilia-Romagna where technical consultation fees justify premium positioning. Lead with FDA regulatory navigation capabilities as differentiated value proposition against commodity suppliers. For Investors and Strategic Acquirers: Asymmetric upside sits with regional dry mix specialists possessing captive application labs and Southeast United States manufacturing footprint. Five-to-ten year viability hinges on plant-based identity standard clarity and clean-label stabilizer approval velocity. Monitor ECHA REACH compliance documentation requirements as signal for European export qualification barriers favoring integrated suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dairy Protein Sourcing | Captive supply of spray-dried solids insulates margin from commodity volatility squeezing non-integrated producers. |
| Application Laboratory Service Bundling | Technical consultation programs lock in recurring revenue from foodservice accounts seeking batch-to-batch uniformity. |
| Oat Protein Stabilizer System Development | Clean-label positioning opens premium tier access as FDA plant-based identity standards reshape formulation requirements. |
| Private-Label Regional Grocery Partnerships | Exclusive stabilizer blends with supermarket banners generate margin expansion through captive supply relationships. |
| REACH Compliance Documentation Investment | Full supply chain substance volume tracking enables European export access for gelato base segments with complex additive packages. |
Research Methodology
Direct dialogue with dry mix base formulation scientists, quick-service restaurant procurement directors, artisan gelato shop owners, and regional dairy cooperative supply chain managers grounded qualitative insights in operational reality. Secondary validation drew from FDA labeling guidance documents, USDA Organic certification databases, ECHA REACH substance volume registrations, and foodservice distribution trade records. Bottom-up demand modeling across application segments triangulated against top-down value chain analysis.
Bottom-up volume estimates by product type, formulation certification tier, and regional manufacturing corridor integrated with top-down value capture analysis across ingredient supplier, co-manufacturer, and retail banner levels. CAGRs were derived from segment-level growth trajectory assessment incorporating oat protein stabilizer technology maturation, Southeast United States foodservice expansion patterns, and FDA regulatory timeline assumptions. Forecast inputs included spray-dried protein system adoption curves and clean-label hydrocolloid petition approval velocity.
The model assumes a particular technology adoption path for oat and coconut protein stabilizer systems; alternative pathways involving novel fermentation-derived proteins would alter the outlook for non-dairy formulation growth. Forecasts reflect assumptions about FDA plant-based identity standard finalization and ECHA REACH documentation burden evolution. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
North America Frozen Desserts Market
Processed and Frozen Foods
Turkey Cold Storage Market
Processed and Frozen Foods
Low-Fat Low-Cholesterol Foods Market
Processed and Frozen Foods
Frozen Smoked Salmon Market
Processed and Frozen Foods
GCC Frozen Fruits and Vegetables Market
Processed and Frozen Foods
Europe Frozen Finger Chips Market
Processed and Frozen Foods
Europe Frozen Food Market
Processed and Frozen Foods
Freeze-Dried Food Market
Processed and Frozen Foods
Latin America Frozen Finger Chips Market
Processed and Frozen Foods
Ice Cream and Frozen Dessert Market
Processed and Frozen Foods
Asia-Pacific Frozen Yogurt Market
Processed and Frozen Foods
Cold Storage Market
Processed and Frozen Foods
Commercial Walk in Freezer Market
Processed and Frozen Foods
French Fries Market
Processed and Frozen Foods
Chilled Processed Food Market
Processed and Frozen Foods
North America Frozen Finger Chips Market