
 Sheep Milk Market | 2026-2036
Sheep Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Sheep Milk Market Analysis
Buyer concentration among dairy processors is shifting as specialty cheese makers and nutraceutical formulators fragment procurement across smaller, quality-focused suppliers. Spring Sheep Milk Co. leverages its New Zealand base to sustain year-round volume for export channels. Bellwether Farms anchors premium positioning in the United States through farmstead production models. Alimenta competes on Mediterranean sourcing depth for European industrial buyers.
Sheep milk is the lacteal secretion derived from domesticated ovines, containing approximately 7.4% fat and 5.5% protein with higher medium-chain fatty acid content than bovine alternatives, serving primarily as a raw input for cheese aging, infant formula bases, and functional food formulations. Cheese commands the dominant value share among product types due to aging premiums and protected designation origin structures in Southern Europe. Powdered form exhibits the fastest trajectory as nutraceutical manufacturers seek shelf-stable protein concentrates for sports nutrition and medical food applications.
EFSA hygiene collection standards, FDA dairy plant inspections, and New Zealand's Ministry for Primary Industries export certification collectively determine batch eligibility for cross-border trade. These frameworks elevate capital requirements for cold-chain infrastructure and pathogen testing protocols. Stakeholders must monitor evolving protein content thresholds in import jurisdictions to align procurement specifications with emerging compliance floors.
Market Dynamics
Artisan cheese aging protocols and EFSA hygiene mandates are restructuring procurement relationships between Mediterranean processors and New Zealand suppliers, forcing capital deployment into cold-chain verification systems.
Growth Catalysts
- EFSA Collection Standards:EU hygiene mandates under EFSA are upgrading pathogen testing infrastructure across French and Italian collection cooperatives, expanding batch eligibility for export-grade cheese production.
- Medical Food Formulation:Nutraceutical manufacturers are integrating sheep milk protein concentrates into hypoallergenic infant formula bases, creating new volume anchors beyond traditional cheese channels.
- Waikato Supply Cluster:New Zealand's Waikato region is consolidating fluid milk collection through coordinated farm networks, reducing seasonality gaps that previously constrained year-round export contracts.
Market Restraints
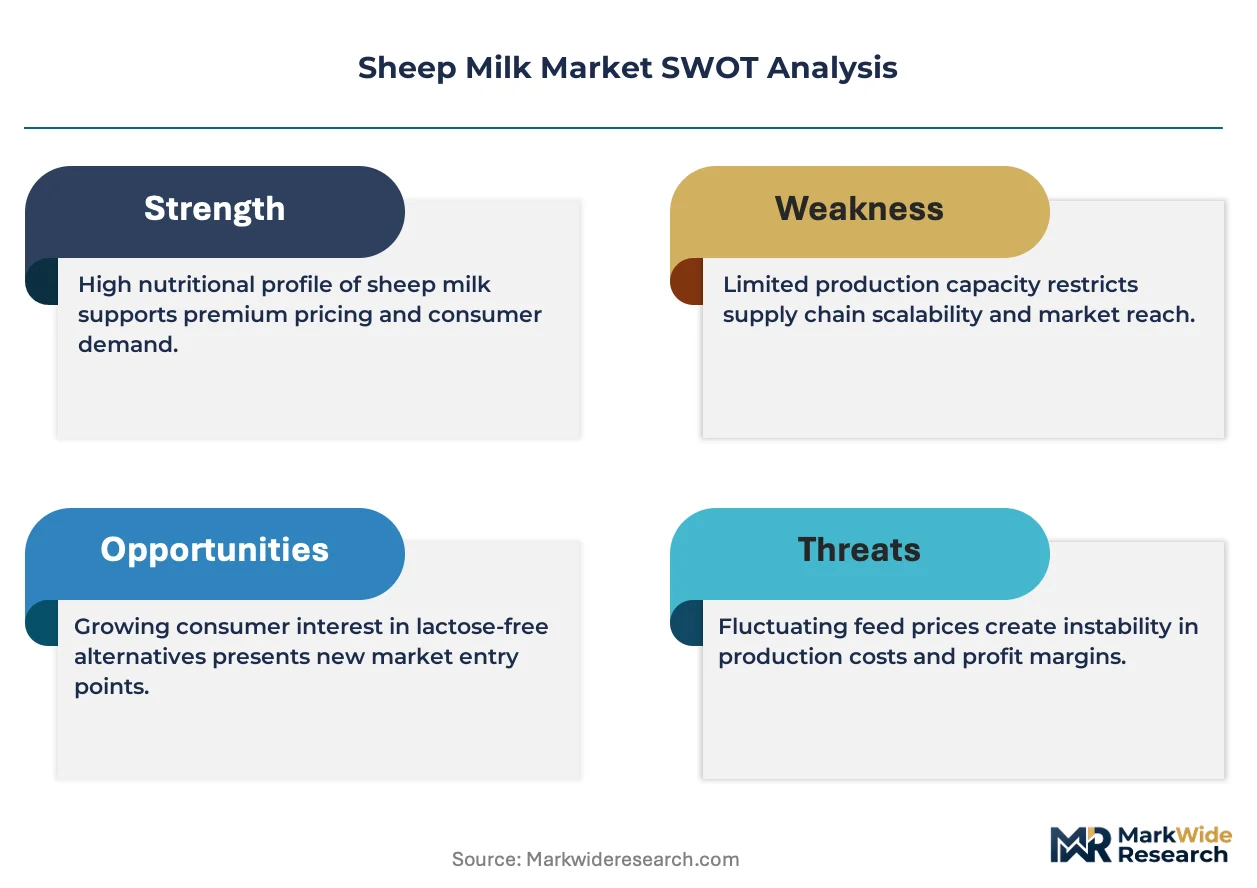
- Feed Cost Volatility:Pasture-based systems in Mediterranean basins face input cost swings from drought-induced hay shortages, compressing margin structures for smallholder suppliers.
- Single-Region Concentration:Fluid milk supply concentrates in New Zealand's North Island, exposing contract manufacturers to climate disruption risks and freight cost spikes.
- Bovine Substitution:A2 beta-casein cow milk variants are capturing shelf space in premium retail channels, displacing sheep milk positioning in lactose-intolerance segments.
Strategic Opportunities
- Chinese Nutraceutical Import Window:NMPA registration pathways for sheep milk-derived medical foods remain underpenetrated, offering first-mover positioning for compliant powder exporters.
- Sports Nutrition Convergence:Collagen peptide fortification combined with sheep whey isolates is opening formulation partnerships with functional beverage brands seeking differentiation from plant-based competitors.
- USDA Organic Certification:USDA organic standards for dairy livestock are creating premium tier separation, enabling margin capture from farmstead producers with verified pasture access.
Industry Challenges
- Veterinary Skill Scarcity:Ovine mastitis diagnostics and somatic cell count management require specialized dairy veterinarians, with training pipelines lagging flock expansion rates in emerging supply regions.
- Cold-Chain Capex Burden:Bulk tank cooling systems and rapid chilling protocols demand capital outlays exceeding smallholder balance sheet capacity, constraining collection network density.
- PDO Documentation Complexity:Protected designation origin certification for Pecorino and Roquefort varieties involves multi-year aging verification and terroir documentation, delaying market entry for new processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sheep Milk Market |
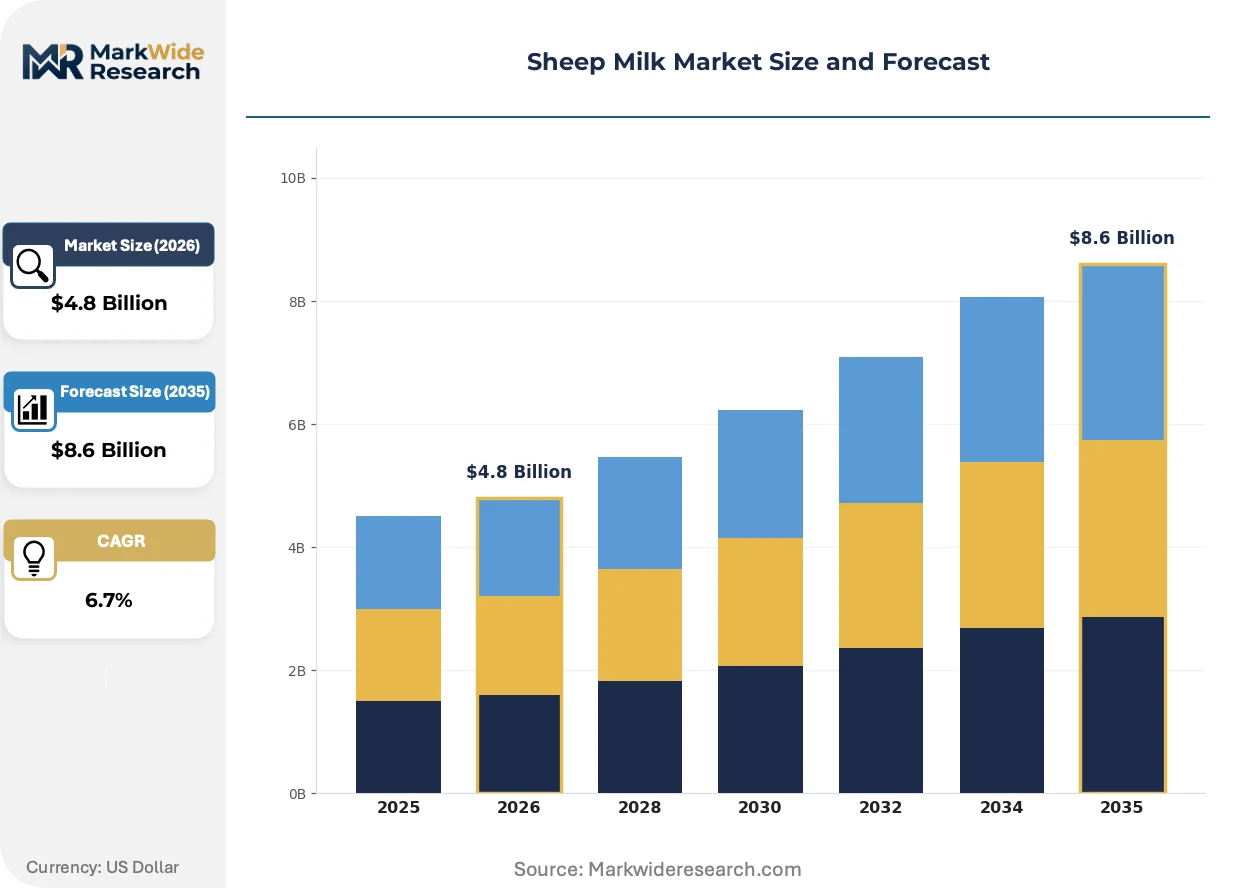
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cheese, Yogurt, Powder, Whole Milk End User: Food Industry, Nutraceuticals, Dairy Processors, Retail Consumers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales Form: Liquid, Powdered, Frozen, Processed |
| Companies Covered | New Zealand Sheep Milk Company, Sheep Milk Company Ltd, Spring Sheep Milk Co., Maui Milk Ltd, Haverton Hill Creamery, Bellwether Farms, Origin Earth, Velvet Cloud, Alimenta, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sheep Milk Market Emerging Trajectories
Robotic milking systems and blockchain traceability layers are compressing labor dependencies while elevating batch verification standards across export-oriented supply chains.
Robotic milking parlors equipped with optical teat detection and automated cluster removal are automating fluid collection in New Zealand and Australian operations. Mid-scale processors with 500-plus ewe equivalents are adopting these systems to reduce labor costs and capture continuous milking data. This automation is compressing the labor cost differential between sheep and bovine operations, enabling smaller flock sizes to achieve commercial viability.
EFSA's updated dairy hygiene collection guidelines are mandating temperature logging at 15-minute intervals during transport and imposing stricter somatic cell count thresholds for fluid milk entering cheese aging programs. French and Italian cooperatives are retrofitting tanker fleets with IoT sensors to maintain compliance. Powder manufacturing segments face the steepest adaptation costs, as spray-drying facilities must revalidate pathogen elimination protocols under the revised standards.
Direct contracting between farmstead producers and specialty cheese retailers is displacing traditional cooperative pooling arrangements in premium channels. E-commerce platforms and restaurant supply aggregators are capturing margin that previously accrued to regional distributors. This channel reconfiguration is most visible in the United States, where Bellwether Farms and similar operations are building captive customer relationships through farmers market networks and chef-direct programs.
Sheep Milk Market Segmentation
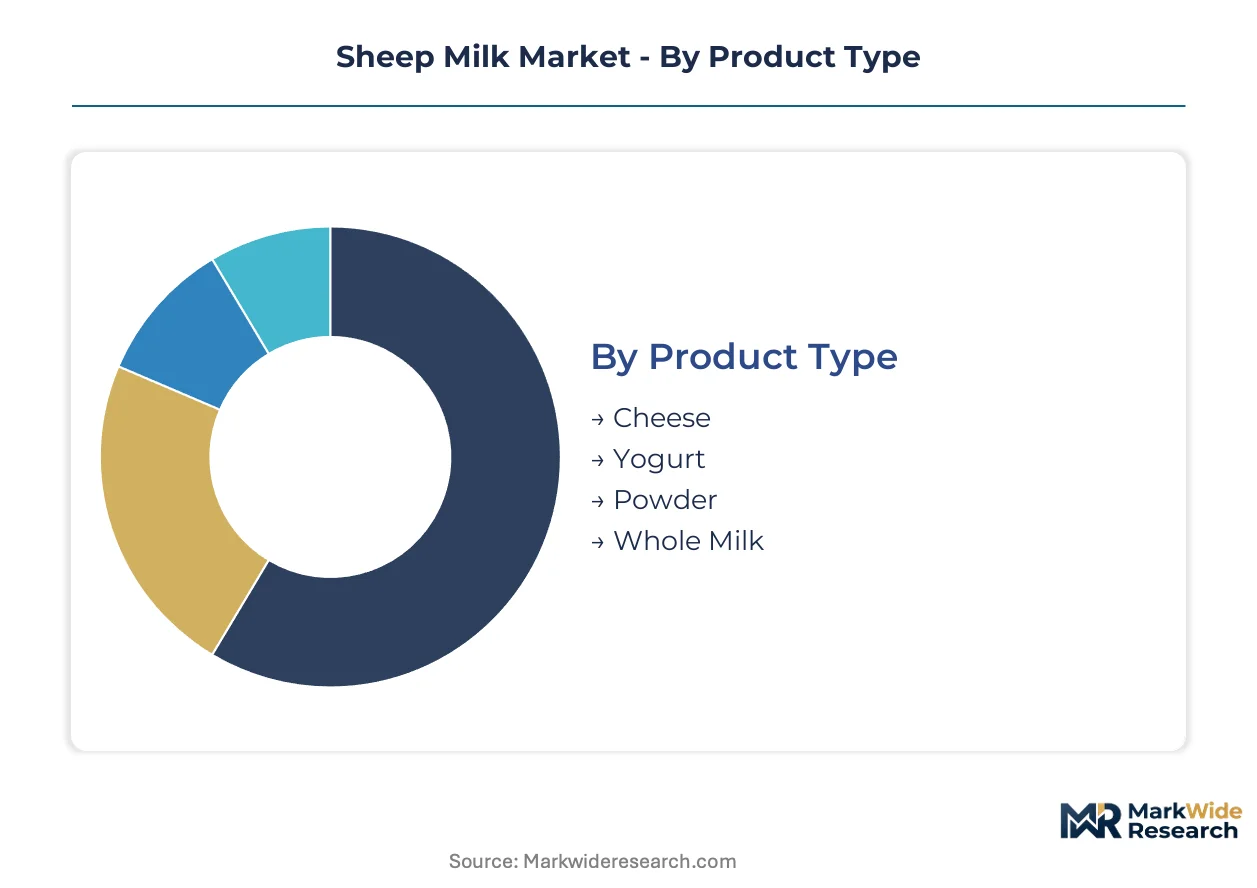
Sheep milk segmentation reflects divergent margin structures across artisan aging protocols and industrial powder processing. Each category channels capital toward distinct infrastructure requirements, from PDO-compliant curing cellars to spray-drying facilities with pathogen elimination validation.
Product Type:
Standardization versus customization tension runs deepest here, with protected designation origin frameworks locking in terroir-specific production methods while powder manufacturing pursues commoditized scale.
- Cheese:Aging protocols for Pecorino and Roquefort varieties require 90-day minimum curing periods in humidity-controlled cellars, locking working capital into inventory. French and Italian cooperatives concentrate procurement relationships here, with EFSA hygiene mandates now mandating temperature logging at 15-minute intervals during milk collection to maintain batch eligibility.
- Powder:Spray-dried protein concentrates achieve shelf stability through 180°C atomization, enabling year-round export contracts from New Zealand's Waikato region. Nutraceutical formulators in medical food and sports nutrition segments drive demand concentration, though revalidation costs for pathogen elimination protocols under revised EFSA standards compress margins for smaller processors.
- Yogurt:Fermented products with live culture counts above 10^6 CFU/g serve Mediterranean retail channels and probiotic-positioned health segments.
- Whole Milk:Fluid sales concentrate in farm-direct and specialty retail with minimal processing overhead but constrained radius economics.
Most installed capacity flows through cheese. Expansion is steepest in powder.
End User:
Cost tier stratification separates commodity dairy processors from premium nutraceutical formulators willing to absorb organic certification premiums.
- Food Industry:Ingredient buyers for bakery, confectionery, and prepared foods seek standardized fat and protein specifications for recipe consistency. Mediterranean industrial clusters concentrate demand, with procurement specifications tightening around somatic cell count thresholds.
- Nutraceuticals:Medical food and sports nutrition manufacturers require hypoallergenic protein isolates with documented amino acid profiles. NMPA registration pathways in China remain underpenetrated, offering first-mover positioning for compliant exporters.
- Dairy Processors:Specialty cheese makers and yogurt manufacturers fragment procurement across smaller quality-focused suppliers.
- Retail Consumers:Direct purchasers through farmers markets and e-commerce platforms absorb highest per-unit premiums for farmstead positioning.
Volume concentrates with dairy processors. Margin expansion is strongest in nutraceuticals.
Distribution Channel:
Geography of demand shapes channel viability, with cold-chain density determining reach for fluid products versus ambient stability enabling e-commerce penetration for powders.
- Specialty Stores:Curated cheese mongers and gourmet retailers command aging premiums through controlled humidity display cases and staff expertise in PDO provenance storytelling.
- Direct Sales:Farmstead producers bypass cooperative pooling through chef-direct programs and subscription models, capturing margin that previously accrued to regional distributors.
- Supermarkets:Mass retail placement requires scale economies and consistent supply that favor New Zealand exporters over seasonal Mediterranean production.
- Online Retail:Powder products achieve widest reach through ambient shipping, while fluid and fresh cheese segments face last-mile refrigeration constraints.
Revenue concentration sits with specialty stores. Digital penetration is climbing fastest in online retail.
Form:
Supply chain configuration separates perishable liquid requiring continuous cold-chain from shelf-stable alternatives that decouple production from consumption timing.
- Liquid:Raw fluid milk demands bulk tank cooling below 4°C within two hours of milking and rapid chilling protocols that exceed smallholder capital capacity, constraining collection network density in emerging supply regions.
- Powdered:Dehydrated concentrates enable inventory positioning ahead of contract manufacturing windows, with collagen peptide fortification creating formulation partnerships in functional beverages.
- Frozen:Blast-frozen curd or milk extends transport radius for industrial buyers with thawing and processing capabilities.
- Processed:UHT or extended shelf-life treatments bridge fresh and ambient categories for retail channels lacking refrigeration infrastructure.
Processing infrastructure dominates liquid. Value-added conversion is expanding most quickly in powdered.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized dairy veterinarians and ovine husbandry technicians concentrate in New Zealand's North Island and France's Massif Central, anchoring fluid milk collection networks that supply export-grade processors.
New Zealand
Waikato region farm networks consolidate fluid milk supply for year-round export contracts to Asian nutraceutical manufacturers. New Zealand's Ministry for Primary Industries enforces export certification protocols that determine batch eligibility for cross-border trade. Spring Sheep Milk Co. and Maui Milk Ltd anchor supply expansion through coordinated collection infrastructure.
France
Roquefort and Basque Country cooperatives drive procurement for PDO-compliant cheese aging programs. EFSA hygiene mandates under EU regulation reshape collection protocols with 15-minute temperature logging requirements. Massif Central shepherds maintain flock density that supports artisan processor demand.
Italy
Pecorino Romano and Sardinian producers fragment procurement across quality-focused suppliers for Mediterranean retail channels. EFSA dairy hygiene collection guidelines impose stricter somatic cell count thresholds for fluid milk entering aging programs. Emilia-Romagna and Tuscany clusters retrofit tanker fleets with IoT sensors for compliance.
United States
Farmstead producers in California and Wisconsin build captive customer relationships through chef-direct programs and farmers market networks. FDA dairy plant inspections elevate capital requirements for cold-chain infrastructure and pathogen testing protocols. Bellwether Farms anchors premium positioning through verified pasture access models.
China
Nutraceutical formulators in Shanghai and Guangzhou seek shelf-stable protein concentrates for medical food applications. NMPA registration pathways for sheep milk-derived medical foods remain underpenetrated, offering positioning for compliant powder exporters. Yangtze River Delta logistics hubs enable ambient distribution of dehydrated concentrates.
Sheep Milk Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market strata. The vendor base fragments across quality-focused suppliers and scale-driven exporters with divergent capital deployment priorities. Three archetypes dominate: farmstead producers with verified pasture access, regional cooperatives with PDO certification depth, and export-oriented processors with spray-drying capacity. Competitive moves concentrate on geographic expansion into underpenetrated nutraceutical channels and backward integration into captive flock supply.
Within the export-processor tier, Spring Sheep Milk Co. and Maui Milk Ltd represent New Zealand-based volume anchors, while Bellwether Farms occupies a position exemplifying the farmstead-premium archetype in North American channels. Alimenta sits within the Mediterranean sourcing cluster serving European industrial buyers. These entities illustrate the geographic bifurcation between Southern Hemisphere scale operations and Northern Hemisphere terroir-positioned specialists.
| Leading Market Players |
|---|
| New Zealand Sheep Milk Company |
| Sheep Milk Company Ltd |
| Spring Sheep Milk Co. |
| Maui Milk Ltd |
| Haverton Hill Creamery |
| Bellwether Farms |
| Origin Earth |
| Velvet Cloud |
| Alimenta |
| Others |
Supply Flow & Price Mechanics
USDA organic certification for dairy livestock gates both qualified supply and premium-tier pricing access, as farmstead producers with verified pasture access capture margin separation while conventional operators face cost compression from feed input volatility.
Pricing Analysis
Unbundled collection services and bundled processor-of-take contracts split procurement relationships across the market. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with PDO-compliant aged cheese commanding the highest tier. Price erosion runs through standard fluid milk channels as New Zealand exporters scale spray-dried powder output. Nutraceutical formulators show least price sensitivity due to hypoallergenic protein premiums, while industrial bakery buyers absorb cost compression most acutely.
Supply Chain Analysis
Refrigerated freight costs from New Zealand's North Island to Asian nutraceutical hubs anchor logistics expenditure for export-grade powder. Supply concentrates in New Zealand, France, and Italy, with fluid milk drawing from pasture-based systems in Waikato and Massif Central. Raw material dependencies center on hay and grain feed inputs, plus packaging materials for shelf-stable concentrates. Single-region concentration in New Zealand exposes contract manufacturers to climate disruption risks. Distribution runs through coordinated farm networks for fluid milk and ambient e-commerce channels for dehydrated products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder, with EFSA hygiene collection standards upgrading pathogen testing infrastructure and expanding batch eligibility for export-grade cheese production.
For Market Incumbents: Extend backward integration into captive flock supply to secure volume anchors against A2 beta-casein cow milk substitution in lactose-intolerance segments. Incumbent processors should retrofit tanker fleets with IoT temperature sensors to maintain EFSA compliance for PDO aging programs, while consolidating procurement relationships with Massif Central and Basque Country cooperatives to defend terroir-positioned margins. For New Entrants and Emerging Players: E-commerce subscription models for farmstead cheese offer the most penetrable white-space route, bypassing cooperative pooling arrangements that dominate traditional distribution. New entrants should target direct-to-chef programs in United States metropolitan markets, leveraging USDA organic certification to capture premium tier separation from commodity fluid milk channels. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale processors with 500-plus ewe equivalents and robotic milking infrastructure already deployed. The five-to-ten year viability window favors acquisition targets with spray-drying capacity and NMPA registration progress for Chinese nutraceutical entry. Watch for NMPA approval signals as the inflection indicator for powder export margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Robotic Milking Deployment | Spring Sheep Milk Co. compression of labor costs enables commercial viability at smaller flock scales. |
| EFSA Compliance Retrofit | French and Italian cooperatives' IoT sensor installation maintains batch eligibility for Roquefort and Pecorino aging. |
| NMPA Registration Pursuit | Compliant powder exporters gain first-mover positioning in China's underpenetrated medical food channel. |
| Direct-to-Consumer Launch | Bellwether Farms' chef-direct programs capture margin previously accruing to regional distributors. |
| Backward Integration into Flock Supply | Captive ewe herds reduce seasonality gaps and secure year-round export contract fulfillment. |
Methodological Framework
Multiple input streams — processor procurement directors, dairy cooperative managers, nutraceutical formulators, and veterinary specialists — were reconciled against trade flow databases and EFSA regulatory filings. Primary interviews with sheep dairy operations in Waikato, Massif Central, and Sardinia were cross-validated with New Zealand Ministry for Primary Industries export certification records and USDA organic livestock standards documentation. Bottom-up volume modeling across cheese, powder, yogurt, and fluid segments was triangulated with top-down value aggregation from customs and specialty retail audit sources.
Data-stream reconciliation anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-user industry, distribution channel, and geographic production cluster. CAGRs were derived from trend extrapolation of historical volume flows and elasticity-adjusted price trajectories. Forecast inputs incorporated EFSA hygiene mandate implementation timelines and NMPA registration pathway progression for Chinese market entry.
The model assumes a particular technology adoption path; alternative pathways for robotic milking and blockchain traceability would alter the outlook for labor cost structures and batch verification standards. Forecasts reflect documented assumptions around pasture yield stability and regulatory enforcement intensity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Butter and Margarine Market
Dairy Products
Probiotic Cheese Market
Dairy Products
Lactose Free Butter Market
Dairy Products
Lactose Free Dairy Products Market
Dairy Products
Qatar Dairy Products Market
Dairy Products
Africa Dairy Protein Market
Dairy Products
China Lactose-Free Dairy Market
Dairy Products
Sweet Whey Market
Dairy Products
Russia Whey Protein Market
Dairy Products
Dry Buttermilk Market
Dairy Products
Low Cholesterol Cheese Market
Dairy Products
Dairy Carton Market
Dairy Products
South America Dairy Protein Market
Dairy Products
Reduced Fat Dairy Market
Dairy Products
Milk Protein Concentrate Market
Dairy Products
Processed Cheese Market