
 China Dairy Market | 2026-2036
China Dairy Market Size, Share, and Industry Trends Forecast 2026-2036
China Dairy Market Insights
Plant-based oat and almond formulations are shifting traditional dairy economics as cost-sensitive consumers experiment with alternatives. Inner Mongolia Yili Industrial Group leverages its integrated pasture-to-retail network to sustain price competitiveness in fluid milk. China Mengniu Dairy Company anchors its growth through R&D intensity in probiotic strains and functional yogurt. Bright Dairy & Food dominates the Yangtze River Delta through cold-chain precision and regional brand strength.
China dairy encompasses fluid milk, fermented products, and solid derivatives produced through pasteurization, ultra-high-temperature processing, or enzymatic coagulation, with fat content ranging from skim to full-cream grades and protein levels typically between 3.0% and 3.6% for standard cow's milk, serving nutritional intake and food manufacturing requirements. Yogurt captures expanding margin pools as functional and probiotic variants attract health-conscious buyers across supermarket and online retail channels. Cheese remains nascent in household penetration but accelerates through baking and food production applications, particularly in coastal urban centers. Milk sustains volume leadership through institutional demand and daily consumption habits.
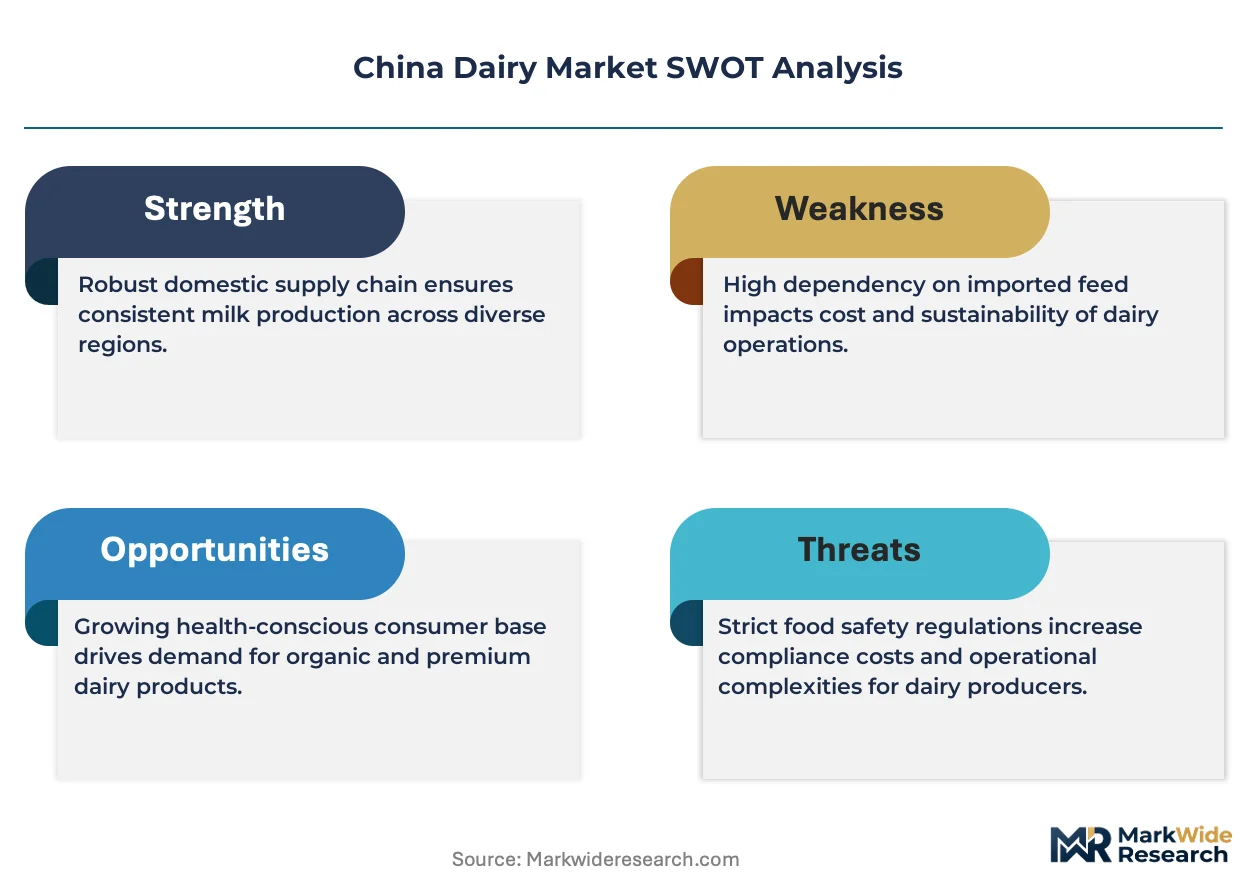
SAMR enforces GB standards for dairy safety and labeling, while the National Health Commission issues dietary guidelines that elevate recommended dairy intake levels among Chinese consumers. The Ministry of Agriculture and Rural Affairs supervises raw milk quality benchmarks through farm-level inspection protocols. Stakeholders must monitor evolving GB standard revisions and cold-chain infrastructure investments as determinants of regional market access and premium product positioning.
Market Dynamics
China's dairy sector is restructuring around cold-chain infrastructure expansion and protein-diet policy mandates from the National Health Commission, compressing regional supply disparities while elevating quality premiums in coastal urban clusters.
Growth Catalysts
- National Health Commission dietary guidelines:Elevated per-capita dairy intake recommendations are pulling fluid milk and yogurt into daily consumption routines across tier-one and tier-two urban households.
- Cold-chain logistics upgrades:Refrigerated transport networks are extending fresh milk shelf reach from 72 hours to 168 hours, unlocking supermarket penetration in Jiangsu and Zhejiang provinces.
- Functional yogurt R&D intensity:Probiotic strain development is creating margin expansion in health-positioned SKUs targeting digestive wellness segments.
Market Restraints
- Feed cost volatility:Alfalfa and soybean meal price swings compress raw milk production margins for pasture-dependent operators in Inner Mongolia.
- GB standards compliance friction:SAMR labeling and safety revisions impose reformulation costs and timeline uncertainty for product line extensions.
- Plant-based substitution acceleration:Oat and almond formulations are capturing trial among cost-sensitive urban consumers in Shanghai and Beijing convenience channels.
Strategic Opportunities
- Cheese household penetration:Baking and foodservice applications in Guangdong and Fujian coastal cities represent untapped volume expansion beyond institutional buyers.
- Dual carbon policy alignment:MEE emissions benchmarks favor operators investing in methane capture and renewable energy at processing facilities.
- E-commerce fresh delivery integration:Community group buying platforms are rewiring last-mile distribution for temperature-sensitive SKUs in Chengdu and Wuhan.
Industry Challenges
- Probiotic strain IP licensing complexity:Foreign microbiome patents create royalty burdens and supply exclusivity constraints for domestic functional yogurt development.
- Cold-chain capex intensity:Refrigerated warehousing and fleet requirements demand sustained capital deployment for regional market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Dairy Market |
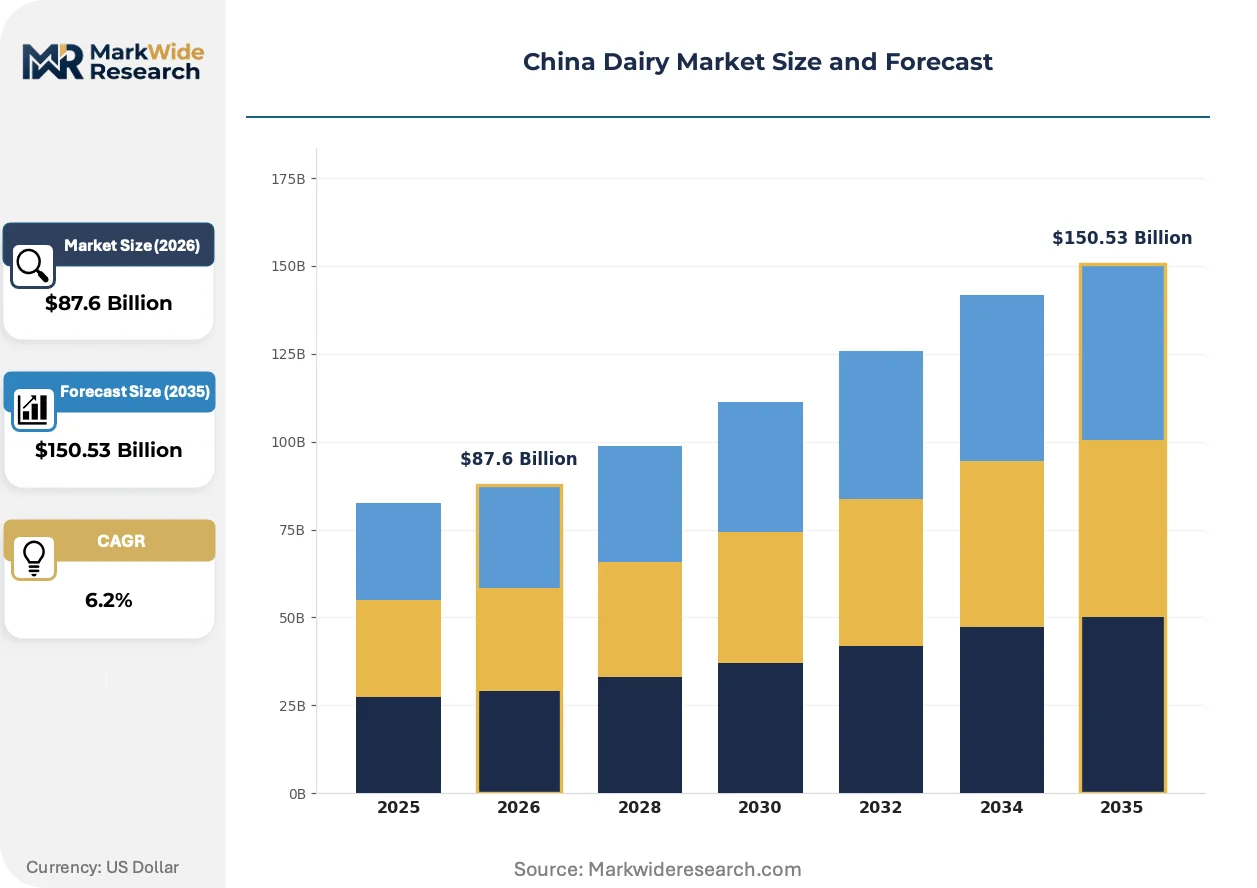
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $150.53 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk, Yogurt, Cheese, Butter Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Wholesale Customer Type: Households, Restaurants, Cafes, Institutions Application: Direct Consumption, Cooking, Baking, Food Production |
| Companies Covered | Inner Mongolia Yili Industrial Group, China Mengniu Dairy Company, Bright Dairy & Food, Junlebao Dairy Group, China Modern Dairy Holdings, Youran Dairy, Nestlé, Danone, Fonterra, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Dairy Market Trends and Innovations
China dairy is rewiring around precision fermentation, regulatory transparency mandates, and channel fragmentation that separates premium freshness positioning from mass-market volume plays.
Aseptic filling and ESL processing technologies are rewriting freshness economics for fluid milk. Supermarket buyers in Beijing and Shanghai are adopting seven-day shelf-life SKUs at pace, compressing the advantage of hyperlocal dairy cooperatives and enabling national brands to contest regional strongholds.
SAMR's evolving GB standards for dairy labeling and safety are tightening formulation disclosure requirements. Processing operators face reformulation audits and packaging redesign costs, with probiotic yogurt lines experiencing the steepest compliance velocity as strain-specific health claims face substantiation thresholds.
Community group buying platforms are fragmenting traditional supermarket dominance in fresh dairy distribution. Meituan and Pinduoduo aggregators are capturing weekly purchase rituals in Wuhan and Chengdu, displacing brick-and-mortar foot traffic while demanding 48-hour farm-to-door fulfillment capabilities from upstream suppliers.
China Dairy Market Segmentation
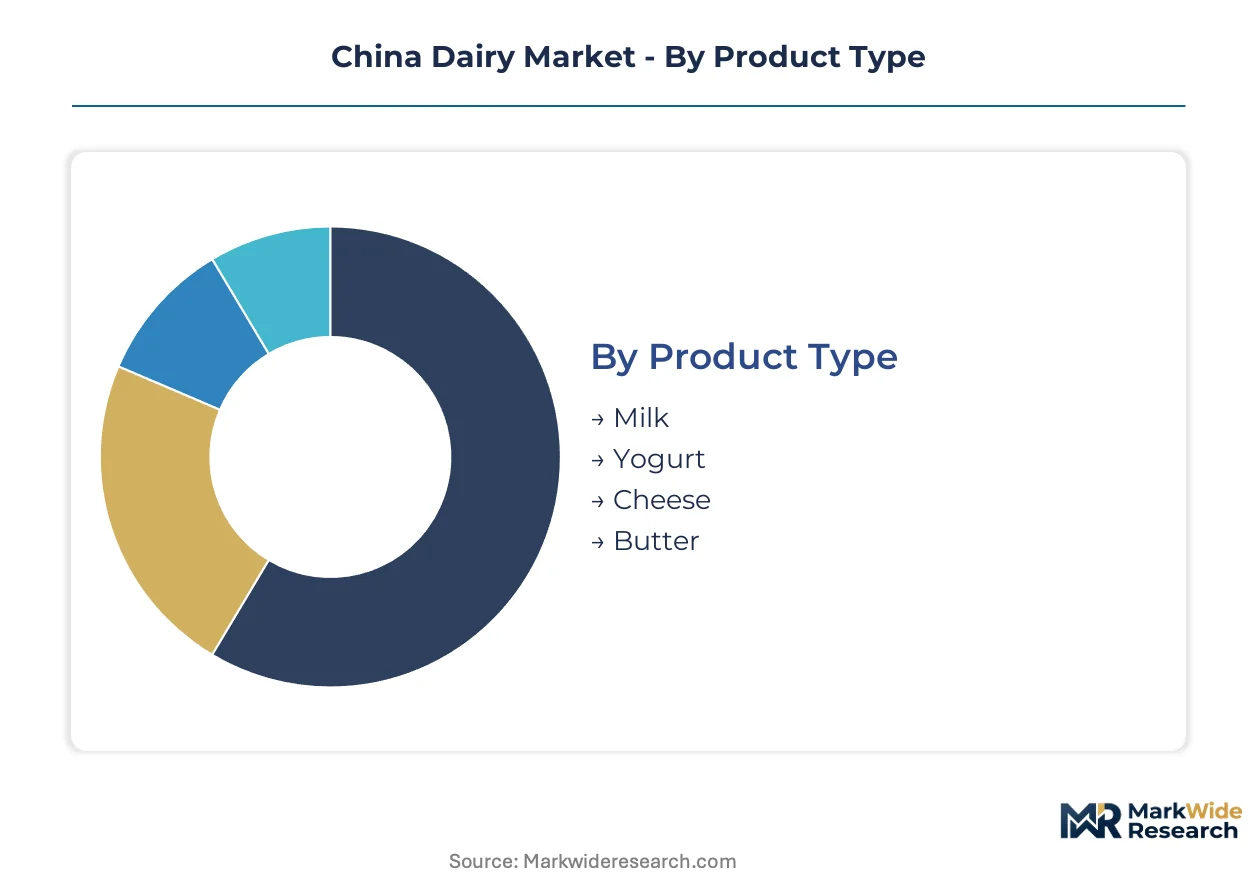
Dairy segmentation in China tracks divergent capital requirements across processing technologies and channel infrastructures. Product categories demand distinct cold-chain investments while distribution channels separate premium freshness plays from volume-driven wholesale routes.
Product Type:
Fluid milk commands the heaviest upfront capital through refrigerated processing lines and ESL packaging infrastructure, while cheese aging facilities require extended depreciation timelines.
- Milk:Ultra-high-temperature and pasteurized variants dominate volume through institutional procurement and daily household routines. Fluid milk absorbs the majority of cold-chain capex in Inner Mongolia and Heilongjiang processing clusters as operators extend shelf reach into Jiangsu and Zhejiang provinces.
- Yogurt:Fermented products with probiotic strain differentiation carry premium positioning through functional health claims and shorter shelf cycles. Demand concentrates in Shanghai and Beijing supermarket channels where SAMR substantiation requirements for strain-specific claims filter out smaller competitors.
- Cheese:Natural and processed varieties serve baking applications and food manufacturing with limited household penetration outside coastal tier-one cities.
- Butter:Cream-derived spreads and industrial fats support bakery and confectionery production with concentrated demand in Guangdong foodservice clusters.
Milk absorbs the bulk of installed capacity; yogurt is expanding most quickly.
Distribution Channel:
Channel selection determines working capital intensity through inventory turnover speeds and temperature control obligations across the fulfillment chain.
- Supermarkets:Multi-format retail chains dominate fresh dairy velocity through dedicated refrigerated sections and private-label partnerships. Supermarket buyers in Beijing and Shanghai are compressing supplier margins through seven-day shelf-life specifications that favor national brands with integrated cold-chain networks.
- Convenience Stores:24-hour urban outlets capture impulse yogurt and single-serve milk purchases with rapid inventory cycles. Convenience channel penetration in Chengdu and Wuhan is climbing the fastest as operators deploy compact refrigeration units in high-footfall locations.
- Online Retail:E-commerce platforms and community group buying aggregators demand 48-hour farm-to-door fulfillment capabilities with temperature logging.
- Wholesale:Institutional and foodservice bulk distribution operates on extended payment terms with lower per-unit handling costs.
Supermarkets retain the deepest refrigerated infrastructure deployment; online retail is gaining share fastest through last-mile integration.
Customer Type:
Customer segmentation separates stable institutional contracts from volatile household trial behavior and premium foodservice specifications.
- Households:Urban families in tier-one and tier-two cities drive yogurt and fresh milk consumption through health-positioned daily routines. Household demand in Shanghai and Beijing concentrates in premium probiotic and organic SKUs with loyalty program stickiness.
- Restaurants:Foodservice operators source bulk butter and cheese for menu applications with specification consistency requirements.
- Cafes:Coffee chain networks demand standardized milk fat content and foaming performance for beverage preparation.
- Institutions:Schools and corporate catering contracts provide volume anchors with rigid safety compliance and long procurement cycles.
Households generate the steepest margin expansion; institutions provide the most predictable offtake volumes.
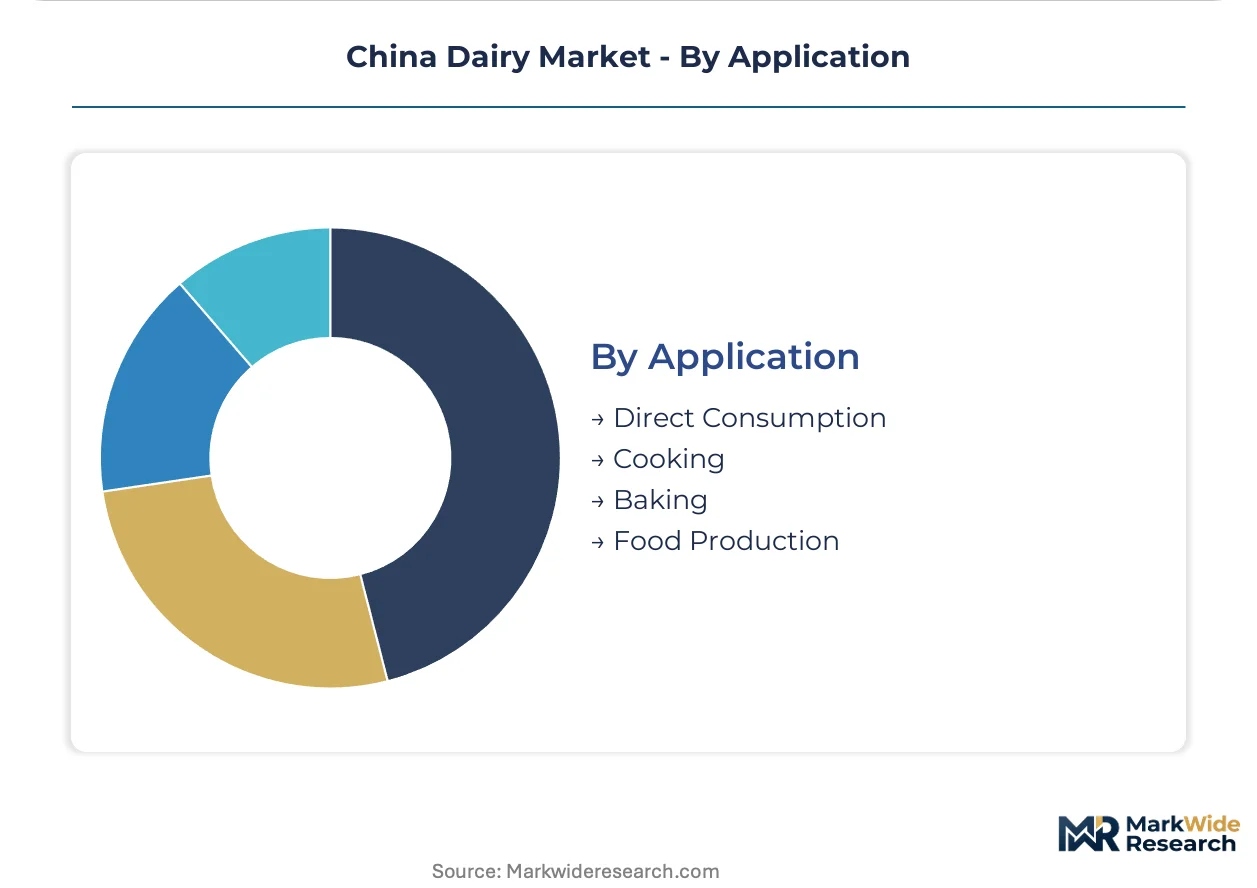
Application:
Application segmentation maps processing complexity from raw consumption to ingredient integration across food manufacturing value chains.
- Direct Consumption:Ready-to-drink milk and spoonable yogurt serve immediate nutritional intake with minimal preparation requirements. Direct consumption in Beijing and Shanghai households is tilting toward functional variants with protein fortification and digestive wellness positioning.
- Cooking:Cream, evaporated milk, and cooking butter integrate into regional cuisine preparation with heat stability specifications.
- Baking:Cheese, butter, and specialized milk powders supply commercial and home baking with precise fat and moisture parameters.
- Food Production:Industrial dairy ingredients including whey proteins and milk solids support processed food and infant formula manufacturing with bulk supply agreements.
Direct consumption commands the highest per-unit pricing; food production is scaling fastest through ingredient outsourcing trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta Economic Zone concentrates premium dairy demand through Shanghai's cold-chain infrastructure and Jiangsu province's processing capacity. Beijing-Tianjin-Hebei anchors northern consumption with institutional procurement networks. Policy incentives under the National Health Commission's dietary guidelines and dual carbon targets from MEE are redistributing investment toward western provinces.
Shanghai-Jiangsu-Zhejiang Cluster
Shanghai households drive probiotic yogurt premiums through supermarket loyalty programs and community group buying platforms. SAMR enforces GB standards for strain-specific health claims that filter smaller competitors from functional SKU development. Bright Dairy leverages cold-chain precision across Suzhou and Hangzhou to sustain seven-day shelf-life specifications for fresh milk.
Beijing-Tianjin-Hebei Corridor
Beijing's institutional catering contracts for schools and corporate campuses provide volume anchors with rigid safety compliance timelines. The National Health Commission's elevated dairy intake recommendations pull fluid milk into daily consumption routines across tier-one urban households. Mengniu anchors processing capacity in Hohhot with R&D intensity targeting probiotic strain differentiation for northern markets.
Guangdong-Fujian Coastal Belt
Guangzhou and Shenzhen foodservice operators accelerate cheese adoption through baking applications and café menu integration. MEE emissions benchmarks favor operators investing in methane capture at processing facilities. Dairy cooperatives in Foshan expand ESL processing lines to contest seven-day fresh milk specifications against national brands.
Sichuan-Chongqing Western Hub
Chengdu's community group buying platforms rewire last-mile distribution for temperature-sensitive SKUs with 48-hour farm-to-door fulfillment. Cold-chain logistics upgrades extend fresh milk shelf reach from 72 hours to 168 hours, unlocking supermarket penetration in secondary cities. Local processors deploy compact refrigeration units in high-footfall convenience locations across Chongqing's urban core.
Inner Mongolia-Heilongjiang Production Base
Pasture-dependent operators in Hohhot and Harbin face feed cost volatility from alfalfa and soybean meal price swings compressing raw milk margins. The Ministry of Agriculture and Rural Affairs supervises farm-level inspection protocols for raw milk quality benchmarks. Yili sustains price competitiveness through integrated pasture-to-retail network control across the northern grassland belt.
China Dairy Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with national integrated players commanding fluid milk volume while regional cooperatives defend fresh proximity advantages. The vendor base organizes around three archetypes: pasture-integrated giants with cold-chain networks, regional dairy cooperatives with hyperlocal freshness positioning, and multinational ingredient suppliers targeting food manufacturing. Consolidation pressure is accelerating through M&A activity among mid-tier processors and strategic partnerships for probiotic strain licensing.
Among domestic listed entities, Inner Mongolia Yili Industrial Group and China Mengniu Dairy Company occupy positions as scale-driven national operators with integrated upstream control, while Bright Dairy exemplifies regional fortress strategies through Yangtze River Delta density. Junlebao Dairy Group and Youran Dairy represent mid-tier specialists expanding through functional yogurt R&D and organic pasture certifications respectively. Nestlé, Danone, and Fonterra anchor the multinational tier through ingredient supply agreements and premium brand licensing rather than direct processing dominance.
| Leading Market Players |
|---|
| Inner Mongolia Yili Industrial Group |
| China Mengniu Dairy Company |
| Bright Dairy & Food |
| Junlebao Dairy Group |
| China Modern Dairy Holdings |
| Youran Dairy |
| Nestlé |
| Danone |
| Fonterra |
| Others |
Pricing and Supply Chain Analysis
ESL processing technology adoption simultaneously compresses per-unit production costs and consolidates shelf-life competitiveness among national brands with integrated cold-chain networks. This technological shift rewards operators who deploy aseptic filling lines across Inner Mongolia and Heilongjiang processing clusters, squeezing regional cooperatives that lack capital for 168-hour freshness specifications.
Pricing Analysis
Volume leadership in fluid milk trades against margin expansion in probiotic yogurt as the defining pricing split. Three-tier pricing structure across premium organic, standard pasteurized, and economy UHT levels stratifies the market, with SAMR strain-specific claim substantiation acting as the primary price differentiation driver alongside cold-chain precision. Cost compression in economy UHT tiers is intensifying because of plant-based oat milk substitution in Shanghai and Beijing convenience channels. Households in tier-one cities demonstrate lowest price sensitivity for functional yogurt SKUs, while institutional buyers in school catering contracts exhibit highest sensitivity through rigid procurement specifications.
Supply Chain Analysis
Dual-sourcing mandates from supermarket buyers in Beijing and Shanghai require fluid milk suppliers to qualify multiple pasture-integrated operators across Inner Mongolia and Heilongjiang. Raw milk procurement draws from alfalfa-dependent northern grasslands, probiotic strain IP licensed from European and Japanese microbiome specialists, and ESL packaging materials from domestic polymer suppliers. Single-source vulnerability concentrates in foreign-held probiotic patents that create royalty burdens for domestic functional yogurt development. Distribution runs through refrigerated fleet networks into supermarket DCs, with community group buying platforms fragmenting last-mile control in Chengdu and Wuhan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GB standards compliance functions as a cost-of-compliance moat where SAMR labeling revisions filter smaller competitors from probiotic strain development, entrenching capital-rich incumbents who absorb reformulation audit costs.
For Market Incumbents: Acquire cold-chain logistics assets in Jiangsu and Zhejiang to extend seven-day fresh milk shelf reach against regional cooperative proximity advantages. Anchor backward integration into methane capture infrastructure at Hohhot processing facilities to align with MEE dual carbon benchmarks. Defend against plant-based substitution by accelerating R&D intensity in protein-fortified functional yogurt strains with exclusive domestic licensing. For New Entrants and Emerging Players: Launch via community group buying platforms in Chengdu and Wuhan with 48-hour farm-to-door fulfillment capabilities targeting temperature-sensitive SKUs. Target cheese household penetration in Guangdong and Fujian coastal cities where baking applications remain underdeveloped against institutional foodservice concentration. Penetrate through organic pasture certification positioning that commands premium pricing from health-conscious tier-one households. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to national integrated operators seeking regional cold-chain density or functional yogurt R&D capabilities. Long-term viability favors pasture-integrated processors with captive raw milk supply and SAMR compliance infrastructure over asset-light brand licensors. Monitor MEE emissions benchmark enforcement as the signal to watch for regulatory-driven consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Network Expansion | Extends 168-hour fresh milk shelf reach into Jiangsu and Zhejiang supermarket channels. |
| Probiotic Strain Licensing Agreement | Secures exclusive domestic rights to foreign microbiome IP for functional yogurt differentiation. |
| Methane Capture Infrastructure Investment | Aligns Hohhot processing facilities with MEE dual carbon policy emissions benchmarks. |
| Community Group Buying Platform Integration | Captures weekly purchase rituals in Chengdu and Wuhan through 48-hour fulfillment. |
| Organic Pasture Certification Program | Commands premium pricing from health-positioned households in Shanghai and Beijing. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with dairy processing executives, cold-chain logistics operators, supermarket category buyers, and SAMR regulatory affairs specialists. Ministry of Agriculture farm-level inspection protocols, GB standards revision drafts, National Health Commission dietary guideline publications, and customs import records for probiotic strains provided validation layers. Bottom-up capacity assessments across Inner Mongolia and Heilongjiang processing clusters triangulated against top-down consumption estimates from tier-one urban household panels.
Data-stream reconciliation across production volume registrations, retail audit velocity, and channel inventory turns generated consistent trajectory outputs across the analysis window. Segmentation modeling tracked product type, distribution channel, customer archetype, and application with regional regulatory cluster overlays. CAGRs derived from historical elasticity patterns applied to projected cold-chain infrastructure deployment and protein-diet policy penetration curves, with feed cost volatility and plant-based substitution rates as sensitivity inputs.
Feed cost volatility, SAMR standards revision timing, and cold-chain capex execution are the dominant revision risks to modeled outputs. Deviation in GB strain-claim substantiation thresholds would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Europe Yogurt Market
Dairy Products
GCC Casein Market
Dairy Products
North America Anhydrous Milk Fat Market
Dairy Products
Argentina Whey Protein Market
Dairy Products
Halloumi Cheese Market
Dairy Products
Dry Whole Milk Powder Market
Dairy Products
Canada Dairy Market
Dairy Products
Asia-Pacific Casein and Caseinates Market
Dairy Products
Fat-Rich Dairy Products Market
Dairy Products
Global Milk Powder Market
Dairy Products
North America Cheese Market
Dairy Products
Butter Powder Market
Dairy Products
Condensed Whey Market
Dairy Products
Low Fat Butter Market
Dairy Products
North America Dairy Desserts Market
Dairy Products
Cheese Crumbles Market