
 Cheese Packaging Market | 2026-2036
Cheese Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Cheese Packaging Market Analysis
Modular portion packs and resealable multi-serve configurations is hardening as the default choice architecture for retail cheese buyers. Amcor leverages its global film extrusion network to supply high-barrier lidding for vacuum-sealed cheddar formats. Winpak anchors North American dairy accounts with integrated forming and sealing equipment tied to film supply contracts. Stora Enso competes through fiber-based tray alternatives that target plastic-reduction commitments by European retailers.
Cheese packaging encompasses barrier films, rigid containers, and fiber-based enclosures engineered to control moisture transmission, oxygen ingress, and light exposure across temperature-variable supply chains, typically specified at water vapor transmission rates below 5 g/m²/day for extended shelf-life applications. Flexible pouches now dominate mozzarella and shredded cheese distribution due to format efficiency and logistics cube optimization. Vacuum packs command margin pools in aged and specialty segments where oxygen exclusion preserves flavor profiles over months-long aging cycles. Cardboard and molded fiber trays are gaining structural share in premium wrapped blocks as German and French retailers enforce plastic-reduction targets.
The FDA governs food-contact substance notifications for cheese packaging sold into US retail channels, while the EU Green Deal and REACH constrain additive chemistries and recyclability claims across European markets. EFSA migration limits for mineral oils and photoinitiators directly shape laminate specifications for wrapped block formats exported from Italy and the Netherlands. Stakeholders must monitor how evolving extended producer responsibility schemes in France and Germany redefine cost allocation between converters and dairy brand owners.
Market Dynamics
EU Green Deal mandates on recyclability and the F-Gas Regulation's phase-down of high-GWP blowing agents are forcing converters to re-engineer multilayer barrier structures while maintaining oxygen and moisture protection for aged cheese formats.
Growth Catalysts
- Artisanal dairy clustering:German regional cheese producers are expanding vacuum-sealed premium formats for export, driving demand for high-barrier lidding films with extended shelf-life specifications.
- REACH-compliant additive reformulation:ECHA restrictions on mineral oil saturated hydrocarbons in food contact materials are accelerating migration-safe laminate development for wrapped block cheese across Benelux and Italian export channels.
- Food service portion control:European restaurant chains and catering operators are adopting single-serve cheese sachets, expanding flexible pouch volumes for mozzarella and processed cheese segments.
Market Restraints
- Ethylene-vinyl alcohol resin cost volatility:EVOH supply concentration in Asian petrochemical corridors exposes European converters to feedstock price swings that compress margin on oxygen-barrier films.
- Multilayer film recyclability dead-end:Current polyethylene-polyamide-EVOH laminates lack economically viable mechanical recycling pathways, creating stranded asset risk as France and Germany advance extended producer responsibility fee structures.
- Aluminum foil substitution ceiling:Fiber-based and metallized polymer alternatives fail to match foil's complete light-blocking performance for long-aged hard cheeses, limiting format migration in premium segments.
Strategic Opportunities
- Mono-material polyolefin barrier films:CEFLEX design guidelines and EU Green Deal circular economy targets are creating first-mover advantage for converters developing recyclable PE or PP structures with comparable WVTR performance to legacy laminates.
- Active packaging integration:Oxygen scavenger and moisture-regulating inserts are converging with modified atmosphere packaging for fresh mozzarella, opening premium pricing in Italian and French retail channels.
- Deposit-return scheme alignment:Germany's DRS expansion to include rigid dairy containers creates volume opportunity for rPET tray producers serving domestic cheese brands with closed-loop packaging commitments.
Industry Challenges
- Migration testing timeline compression:EFSA's evolving guidance on photoinitiator and mineral oil aromatic hydrocarbon limits requires accelerated laboratory validation cycles that strain converter R&D bandwidth.
- Legacy thermoforming asset retrofit:Converters with installed base of polystyrene and PVC forming lines face capital-intensive reconfiguration to process PP or PET alternatives compliant with retailer plastic-reduction pledges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cheese Packaging Market |
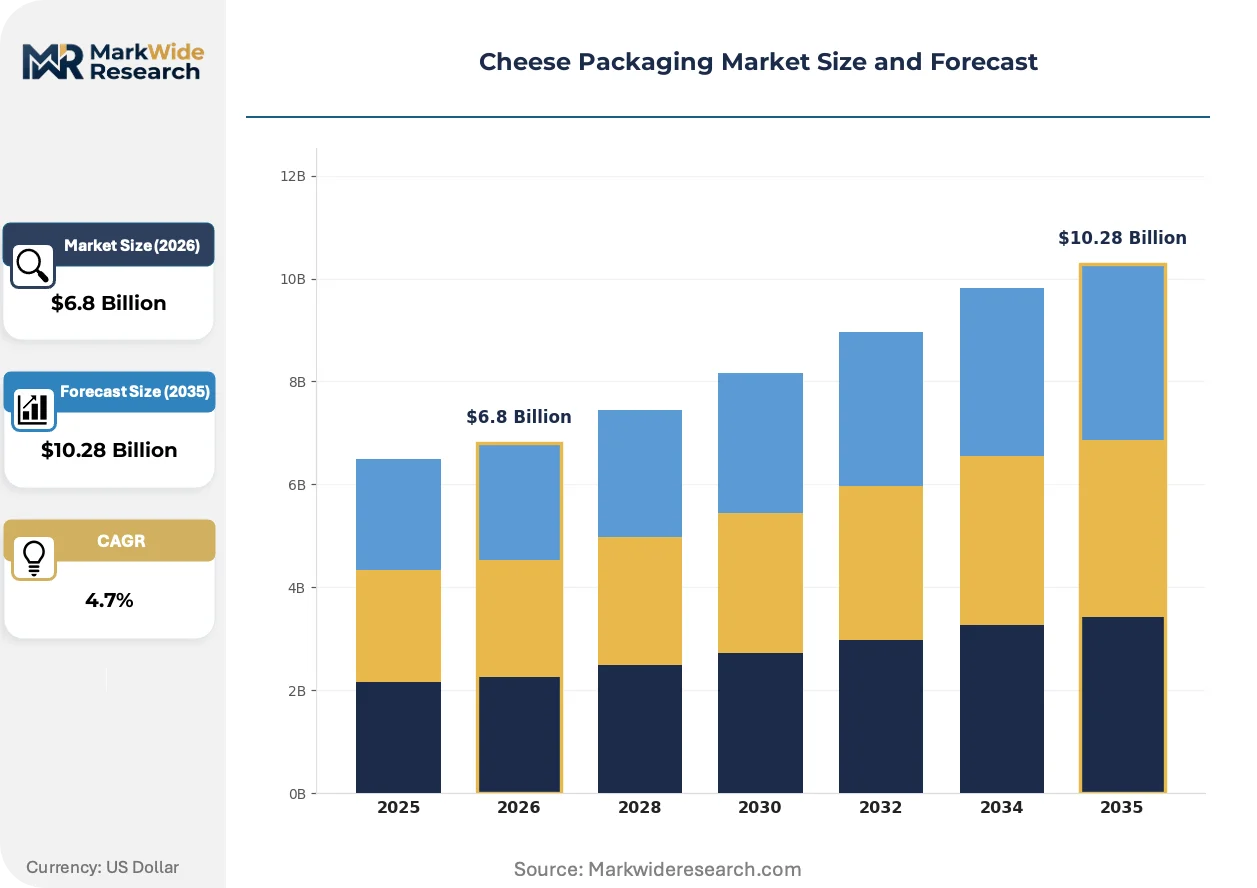
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Flexible Pouches, Vacuum Packs, Containers, Wrapped Blocks Material: Plastic, Cardboard, Glass, Aluminum End User: Retailers, Food Service, Direct Consumers, Food Manufacturers Application: Cheddar, Mozzarella, Gouda, Feta |
| Companies Covered | Amcor, Greatview, Tetra Laval, International Paper, Stora Enso, SIG Combibloc, PFM, Winpak, Elopak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cheese Packaging Market Emerging Trajectories
Packaging format evolution is compressing traditional category boundaries as fiber-based alternatives gain structural legitimacy and digital printing enables batch-level customization for regional cheese brands.
High-barrier mono-material polyethylene films are integrating oxygen scavenger technologies to replace multilayer EVOH laminates in cheddar and gouda vacuum packs. Dutch and German dairy cooperatives are piloting these structures for private-label retail lines. The technology is integrating circular economy compliance into shelf-life performance specifications, allowing converters to meet retailer recyclability targets without sacrificing aging protection.
The EU F-Gas Regulation's hydrofluorocarbon phase-down is compelling tray producers to adopt carbon dioxide or hydrocarbon blowing agents in expanded polystyrene and polypropylene alternatives. This industrial transition elevates capital costs for foam rigid container manufacturing. Aged cheese exporters from Italy and the Netherlands face compressed timelines to validate alternative insulation performance for temperature-controlled distribution.
Food service procurement is consolidating cheese packaging specifications across multi-site restaurant operators, displacing fragmented distributor-led purchasing with direct converter contracts tied to sustainability scorecards. This concentration demands volume flexibility and carbon footprint transparency that smaller regional converters struggle to match. The shift is most visible in French and British contract catering channels where ESG reporting requirements now penetrate supply chain selection criteria.
Cheese Packaging Market Segmentation
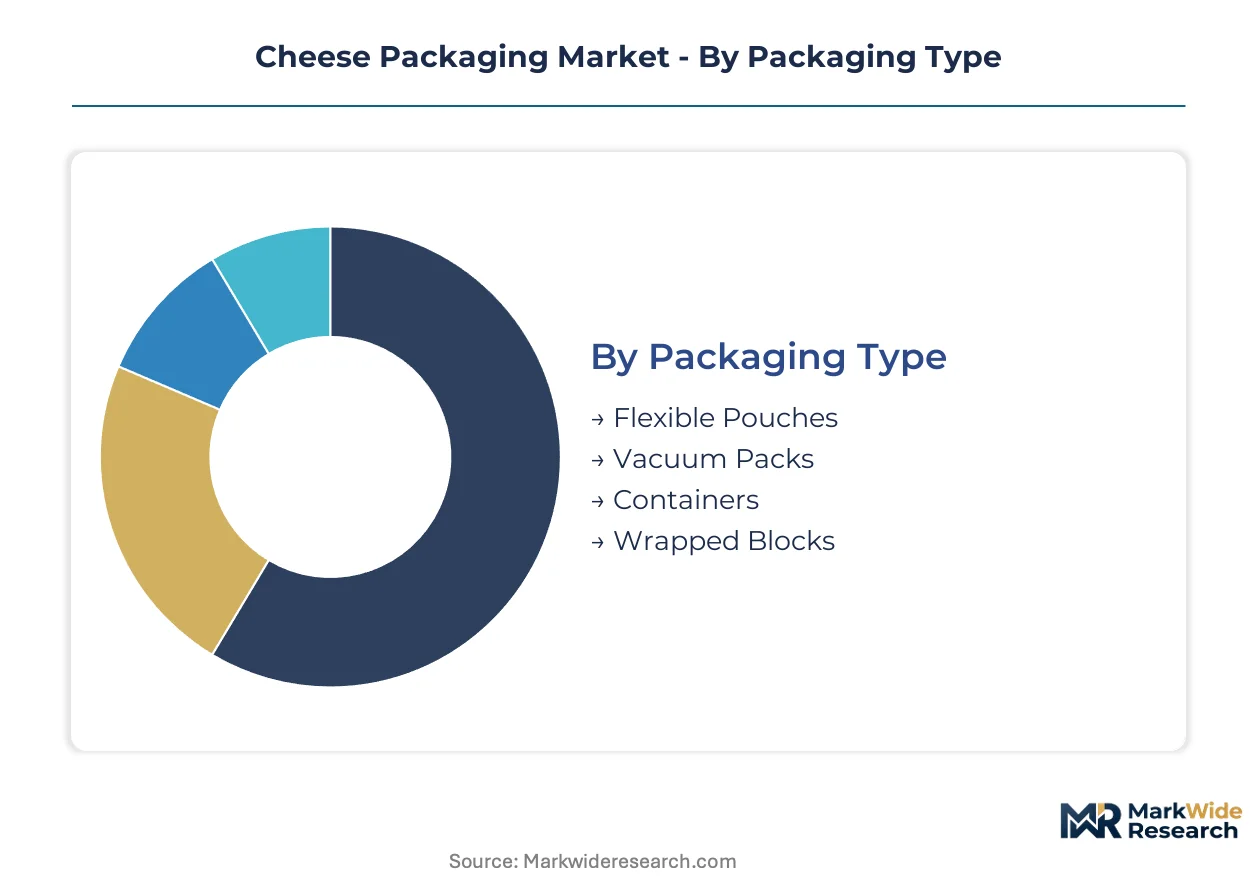
Cheese packaging segmentation reflects divergent technical requirements across shelf-life specifications, distribution temperature profiles, and retail format economics. Each dimension shapes converter investment priorities and barrier film formulation strategies differently.
Packaging Type:
Supply concentration in high-barrier film extrusion tilts competitive advantage toward formats demanding oxygen exclusion and moisture control.
- Flexible Pouches:Multi-layer polyethylene or polyamide laminates with metallized or coextruded barrier layers dominate mozzarella and shredded cheese distribution. German and Dutch dairy cooperatives specify these formats for private-label retail lines where logistics cube efficiency outweighs premium presentation requirements.
- Vacuum Packs:Thermoformed trays paired with lidding films achieve sub-5 g/m²/day water vapor transmission rates essential for aged cheddar and gouda aging cycles. Italian and French specialty cheese exporters concentrate demand here as oxygen exclusion preserves flavor profiles across months-long distribution.
- Containers:Rigid polypropylene or rPET tubs with resealable closures serve fresh cheese segments requiring repeated access without compromising seal integrity.
- Wrapped Blocks:Wax-coated or laminate-wrapped formats persist in artisanal and premium positioning where traditional presentation supports brand differentiation.
Vacuum packs absorb the bulk of installed capacity; flexible pouches are expanding most quickly.
Material:
Cost tier differentiation separates commodity feedstock applications from engineered barrier specifications demanded by extended shelf-life formats.
- Plastic:Polyethylene, polypropylene, and EVOH coextrusions constitute the functional core of oxygen and moisture barrier systems. REACH-compliant additive reformulation is accelerating migration-safe laminate development across Benelux and Italian export channels constrained by EFSA limits.
- Cardboard:Fiber-based tray alternatives target plastic-reduction commitments by German and French retailers, though moisture resistance limitations restrict deployment to shorter shelf-life or secondary packaging roles.
- Glass:Premium positioning in direct-to-consumer and gift segments leverages inert contact surfaces and reuse potential, though weight and fragility constrain distribution scale.
- Aluminum:Foil laminates deliver complete light blocking for long-aged hard cheeses where alternative metallized polymers fail to match performance specifications.
Plastic commands the dominant share of tonnage; cardboard is climbing the fastest amid regulatory pressure.
End User:
Customer type determines order scale, specification complexity, and sustainability reporting requirements that filter converter eligibility.
- Retailers:Supermarket chains and discount operators specify private-label formats with recyclability targets and ESG scorecard compliance, consolidating volume through direct converter contracts.
- Food Service:European restaurant chains and catering operators are adopting single-serve cheese sachets, expanding flexible pouch volumes for mozzarella and processed cheese segments.
- Direct Consumers:Subscription and farm-gate channels favor premium wrapped blocks and reusable glass formats with batch-level customization enabled by digital printing.
- Food Manufacturers:Industrial cheese processors specify bulk formats with forming and sealing equipment integration, locking in film supply contracts tied to volume flexibility requirements.
Retailers absorb the bulk of installed capacity; food service is gaining share fastest.
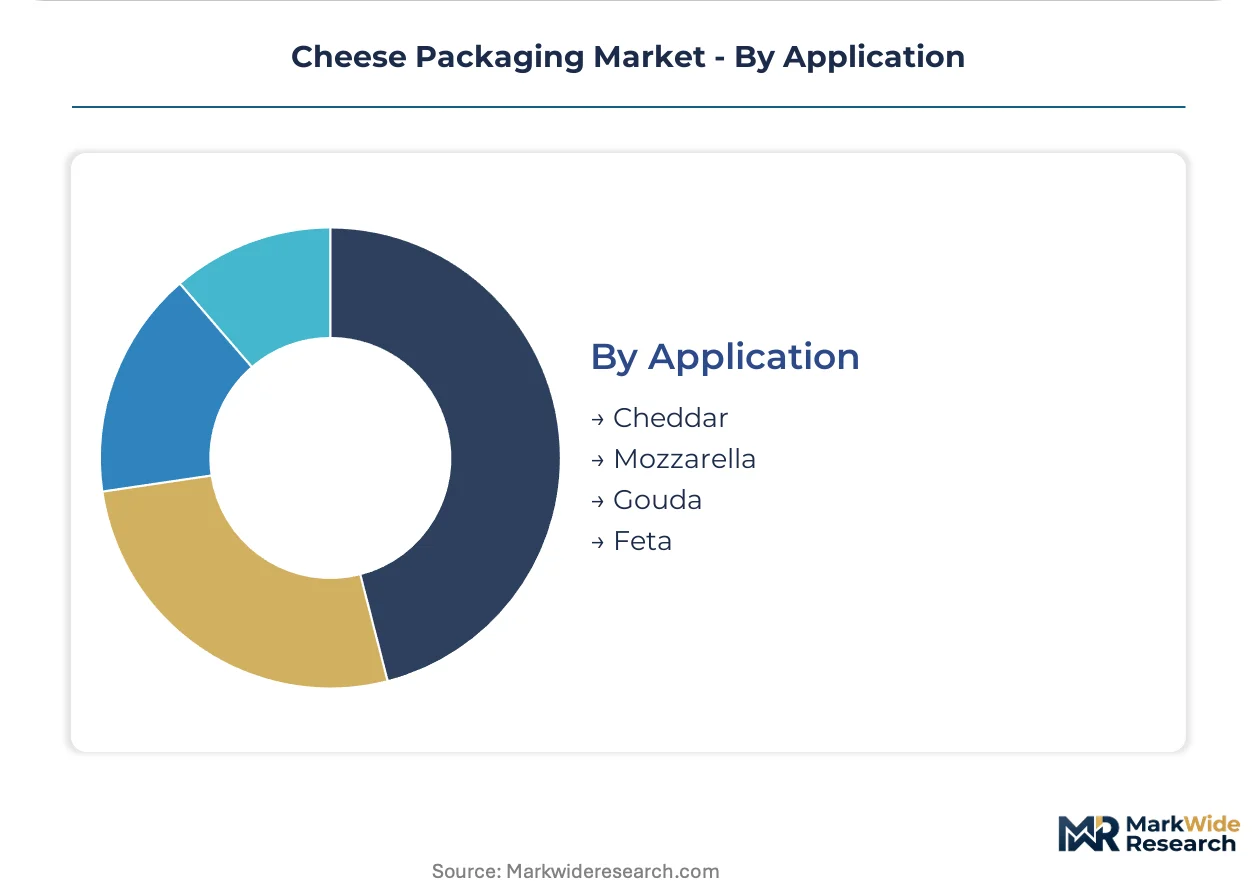
Application:
Volume concentration in commodity cheese varieties shapes converter production scheduling and barrier specification standardization.
- Cheddar:Vacuum-sealed block and shred formats dominate export specifications from UK and Irish producers, with high-barrier lidding films engineered for extended distribution cycles.
- Mozzarella:Modified atmosphere and active packaging integration with oxygen scavenger inserts is opening premium pricing in Italian and French retail channels for fresh varieties.
- Gouda:Dutch cooperative exports specify vacuum packs with aging-optimized barrier performance, though mono-material polyolefin alternatives are piloting for circular economy compliance.
- Feta:Brine-resistant pouch specifications for Greek and Bulgarian exporters require specialized sealant layers preventing salt-induced delamination.
Cheddar absorbs the bulk of installed capacity; mozzarella is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production clusters concentrate in Northern Europe and North America while consumption growth accelerates in Asia-Pacific food service channels. Germany and the Netherlands export barrier films and aged cheese formats to global retail networks. The United States anchors flexible pouch demand through mozzarella and shredded cheese distribution.
Germany
Artisanal dairy cooperatives in Bavaria and Baden-Württemberg drive vacuum-sealed premium format adoption for export markets. The EU Green Deal and F-Gas Regulation compel converters toward lower-carbon barrier films and hydrocarbon blowing agents. Stuttgart-based packaging clusters pilot mono-material polyolefin structures for retailer plastic-reduction compliance.
United States
Food service operators and retail chains specify flexible pouches for mozzarella and processed cheese segments with sustainability scorecard requirements. FDA food-contact substance notifications govern laminate specifications for domestic and export channels. Wisconsin and California dairy processors anchor high-barrier film demand through integrated forming equipment contracts.
Netherlands
Dairy cooperatives specify vacuum packs with aging-optimized barrier performance for gouda export specifications across European and Asian markets. REACH-compliant additive reformulation accelerates migration-safe laminate development constrained by EFSA mineral oil limits. Rotterdam-Antwerp corridor converters develop recyclable PE structures under CEFLEX design guidelines.
Italy
Specialty cheese exporters concentrate demand for oxygen-excluding vacuum formats preserving flavor profiles across months-long distribution cycles. EFSA migration limits for photoinitiators and mineral oil aromatic hydrocarbons directly shape wrapped block laminate specifications. Emilia-Romagna and Lombardy clusters integrate active packaging with oxygen scavenger inserts for fresh mozzarella retail channels.
France
Restaurant chains and contract catering operators consolidate procurement around single-serve cheese sachets with ESG reporting requirements penetrating supply chain selection. Extended producer responsibility schemes redefine cost allocation between converters and dairy brand owners. Paris-region retailers enforce plastic-reduction targets accelerating fiber-based tray adoption for premium wrapped blocks.
Cheese Packaging Market Vendor Landscape
The competitive structure tilts toward integrated film extrusion specialists with global dairy account relationships. Tiered positioning separates multinational converters with captive equipment supply from regional specialists serving artisanal clusters. Three archetypes dominate: barrier film extruders with lidding expertise, fiber-based alternative developers targeting retailer sustainability mandates, and integrated forming-sealing equipment suppliers. Capacity expansion and strategic partnerships constitute the dominant competitive moves as converters re-engineer multilayer structures for recyclability compliance.
Within the integrated equipment tier, Winpak anchors North American dairy accounts with forming and sealing equipment tied to film supply relationships. Amcor leverages global film extrusion networks to supply high-barrier lidding specifications. Stora Enso occupies a position exemplifying the fiber-based alternative archetype targeting European retailer plastic-reduction commitments through tray and enclosure formats.
| Leading Market Players |
|---|
| Amcor |
| Greatview |
| Tetra Laval |
| International Paper |
| Stora Enso |
| SIG Combibloc |
| PFM |
| Winpak |
| Elopak |
| Others |
Supply Flow & Price Mechanics
Captive film extrusion networks anchor both supply security and pricing power for converters serving extended shelf-life cheese formats, with backward integration into EVOH coextrusion insulating margin from Asian petrochemical feedstock volatility while locking in volume commitments from German and Dutch dairy cooperatives.
Pricing Analysis
Margin tightening in high-barrier lidding reflects EVOH resin cost volatility concentrated in Asian petrochemical corridors. Three-tier pricing structure across premium vacuum-sealed formats, standard flexible pouches, and economy shredded cheese bags separates converters by barrier specification complexity. Pricing pressure intensifies in standard tiers as mono-material polyolefin alternatives displace legacy laminates. Food service buyers exhibit highest price sensitivity due to consolidated procurement scorecards, while aged cheese exporters prioritize performance over cost.
Supply Chain Analysis
Return flows of post-industrial film scrap and expired inventory concentrate in mechanical recycling streams feeding back into lower-grade applications. Raw material dependencies center on polyethylene and polyamide resins from Germany, the Netherlands, and Belgium, with EVOH barrier layers sourced from Japanese and South Korean petrochemical producers. Single-source vulnerability in metallized film coating capacity creates chokepoint exposure for oxygen-barrier specifications. Distribution runs through converter-direct contracts with dairy processors, bypassing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation and extended producer responsibility schemes erect compliance moats that favor capitalized incumbents with laboratory validation bandwidth and asset retrofit capacity, while stranding smaller regional converters unable to absorb migration-testing timeline compression.
For Market Incumbents: Anchor barrier film margins through captive EVOH coextrusion capacity in the Rotterdam-Antwerp corridor, insulating against Asian feedstock volatility. Accelerate mono-material polyolefin R&D to preempt recyclability mandates from French and German retailers. Defend position by locking multi-year equipment-integrated contracts with Wisconsin and California dairy processors before alternative blowing agent technologies mature.
For New Entrants and Emerging Players: Artisanal dairy clusters in Bavaria and Baden-Württemberg present underserved white-space demand for batch-customized premium formats enabled by digital printing. Fiber-based tray alternatives for Paris-region retailers offer penetrable entry with lower capital intensity than film extrusion. Pursue direct converter relationships with subscription and farm-gate channels prioritizing sustainability storytelling over volume scale.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated packaging conglomerates seeking barrier film expertise and dairy account relationships. Long-term viability hinges on circular economy compliance rather than shelf-life performance alone. Target converters with validated mono-material structures under CEFLEX guidelines. Monitor EFSA guidance evolution on photoinitiator limits as inflection signal for laboratory capacity valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Barrier Film Development | CEFLEX-aligned structures unlock French and German retailer compliance without sacrificing oxygen protection for aged gouda. |
| Active Packaging Integration | Oxygen scavenger inserts for Italian fresh mozzarella command premium positioning in Paris and Milan retail channels. |
| Equipment-Integrated Contract Expansion | Forming-sealing equipment ties with film supply lock in volume commitments from Wisconsin dairy processors. |
| Hydrocarbon Blowing Agent Transition | F-Gas Regulation compliance for expanded polystyrene alternatives protects Italian and Dutch export container specifications. |
| Fiber-Based Tray Scale-Up | Stora Enso-type alternatives capture German retailer plastic-reduction mandates for premium wrapped block positioning. |
Methodological Framework
Independent corroboration across converter technical directors, dairy cooperative procurement leads, and retail sustainability officers underwrites the qualitative findings, with secondary validation drawing from EFSA migration limit documentation, EU Green Deal regulatory filings, and CEFLEX design guideline publications, combining bottom-up production capacity assessments with top-down demand modeling across packaging type and material segmentation.
Rate-of-change decomposition separates volume growth from value expansion across the projection horizon, with CAGRs derived from trend extrapolation of artisanal dairy clustering, food service portion control adoption, and regulatory compliance cost pass-through. Segmentation dimensions modeled include packaging format, barrier specification tier, end-user channel, and cheese variety application, with forecast inputs incorporating EVOH resin price trajectory assumptions and retailer plastic-reduction target timelines.
Revisions become necessary when EFSA guidance on mineral oil aromatic hydrocarbon limits tightens beyond current modeling assumptions, when Germany's deposit-return scheme expansion accelerates beyond rigid containers into flexible formats, or when Asian petrochemical supply disruptions extend EVOH lead times. Practitioners should monitor regulatory pre-announcements from ECHA and retailer sustainability scorecard updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Organic Milk Protein Market
Dairy Products
Reduced Lactose Whey Market
Dairy Products
North America A2 Milk Market
Dairy Products
Sour Milk Drinks Market
Dairy Products
United Kingdom Milk Protein Market
Dairy Products
Asia-Pacific Dairy Market
Dairy Products
Emmental Cheese Market
Dairy Products
Cheese Concentrate Market
Dairy Products
Citrus Yogurt Market
Dairy Products
Reconstituted Milk Market
Dairy Products
Sheep Milk Cheese Market
Dairy Products
Europe Milk Protein Market
Dairy Products
Natural Cheese Market
Dairy Products
United States Milk Protein Market
Dairy Products
Argentina Whey Protein Market
Dairy Products
United Kingdom Casein and Caseinates Market