
 Dry Mixes Market | 2026-2036
Dry Mixes Market Size, Share, and Industry Trends Forecast 2026-2036
Dry Mixes Market Analysis
Asset-light contract manufacturing and third-party blending arrangements are fragmenting competitive control across the dry mixes landscape. Kerry Group leverages its flavor science infrastructure to dominate premium sauce mix formulations for food service chains. Cargill sustains upstream control over critical hydrocolloid and texturizer supply streams that underpin industrial-scale production. McCormick & Company anchors North American retail shelf presence through decades of brand equity in spice-forward dry blends.
Dry mixes are pre-formulated, shelf-stable powder or granule compositions requiring only the addition of water, milk, or oil to produce finished food or beverage products, with moisture content typically below 5% to ensure microbial stability and extended storage life. Industrial buyers deploy these formulations to reduce labor costs, standardize flavor profiles, and compress batch-to-batch variance in high-volume kitchens. Pancake and beverage mixes command the largest volume positions, while sauce and soup mixes capture disproportionate margin pools in food service channels where labor substitution value runs highest. Sachet and pouch packaging formats are expanding fastest among urban households and cafe operators seeking portion control and reduced preparation time.
FDA food facility registration and GRAS self-determination requirements shape ingredient approval pathways for US-targeted dry mix exporters, while EFSA evaluations of food additives and enzymes directly influence reformulation cycles across European markets. India's FSSAI licensing mandates and BIS packaging standards create compliance thresholds that favor organized manufacturers with dedicated quality laboratories over informal blenders. Stakeholders must monitor how divergent clean-label definitions across FDA, EFSA, and FSSAI jurisdictions force portfolio duplication or regional SKU customization.
Market Dynamics
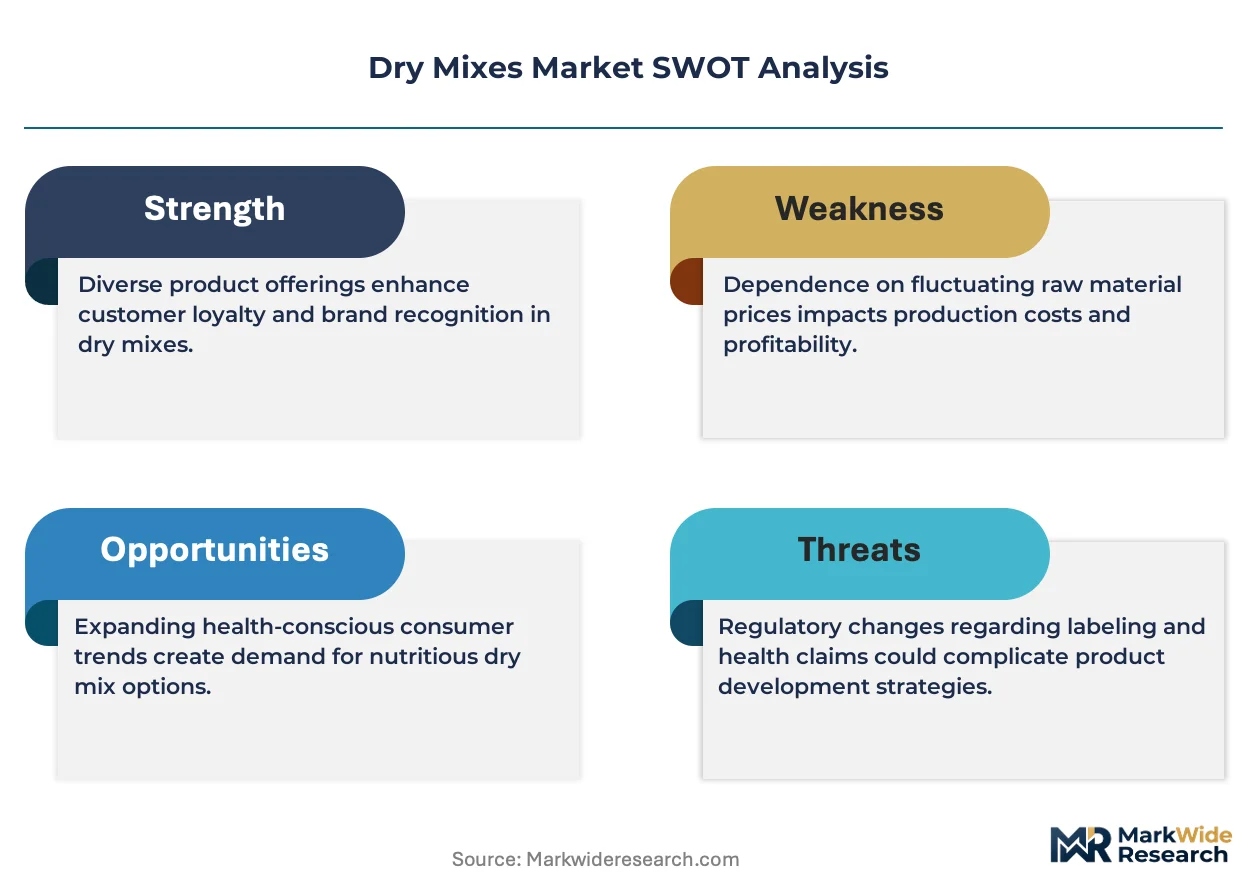
Clean-label reformulations are compressing ingredient decks across the dry mixes landscape, forcing manufacturers to rebuild formulations around shorter, pronounceable component lists while maintaining functional performance in hydration and texture.
Growth Catalysts
- EFSA Additive Evaluations:European safety assessments are accelerating removal of artificial stabilizers from soup and sauce bases, opening procurement contracts for natural hydrocolloid alternatives in food processing facilities.
- Urban Household Concentration:India's working populations in Mumbai, Bangalore, and Delhi are adopting single-serve sachets for daily meal preparation, concentrating demand in premium convenience formats.
- Spray-Drying Infrastructure:Contract manufacturers in Vietnam and Thailand are expanding encapsulated flavor production capacity to serve regional instant beverage mix brands.
Market Restraints
- Hydrocolloid Supply Concentration:Guar gum and xanthan gum supply chains concentrate in India and China, exposing formulators to monsoon-driven harvest volatility and export duty fluctuations.
- Moisture Barrier Material Costs:Multi-layer laminate films required for sub-5% moisture retention are tethered to petrochemical feedstock pricing, compressing margin on value-tier SKUs.
- Clean-Label Technical Ceiling:Natural antioxidants lack the oxidative stability of synthetic alternatives, limiting shelf-life extension in ambient-distribution pancake and cake mixes.
Strategic Opportunities
- FSSAI Licensing Thresholds:India's mandatory quality laboratory requirements are culling informal blenders, creating acquisition targets for organized manufacturers seeking rapid distribution expansion.
- Cafe Channel Direct Supply:Independent coffee chains in Jakarta, Manila, and Ho Chi Minh City are bypassing traditional distributors to source custom beverage mix formulations directly from blenders.
- Enzyme-Assisted Hydration:Convergence of amylase engineering and cold-water soluble starches is enabling ambient-temperature beverage preparation without heating infrastructure.
Industry Challenges
- Flavor Chemist Scarcity:Formulation of clean-label taste systems requires specialists trained in natural extract synergy, a skill set concentrated in European and North American flavor houses.
- Legacy Equipment Retrofit Costs:Shift from bulk drum filling to precision sachet dosing demands capital expenditure on vertical form-fill-seal lines with nitrogen-flush capability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dry Mixes Market |
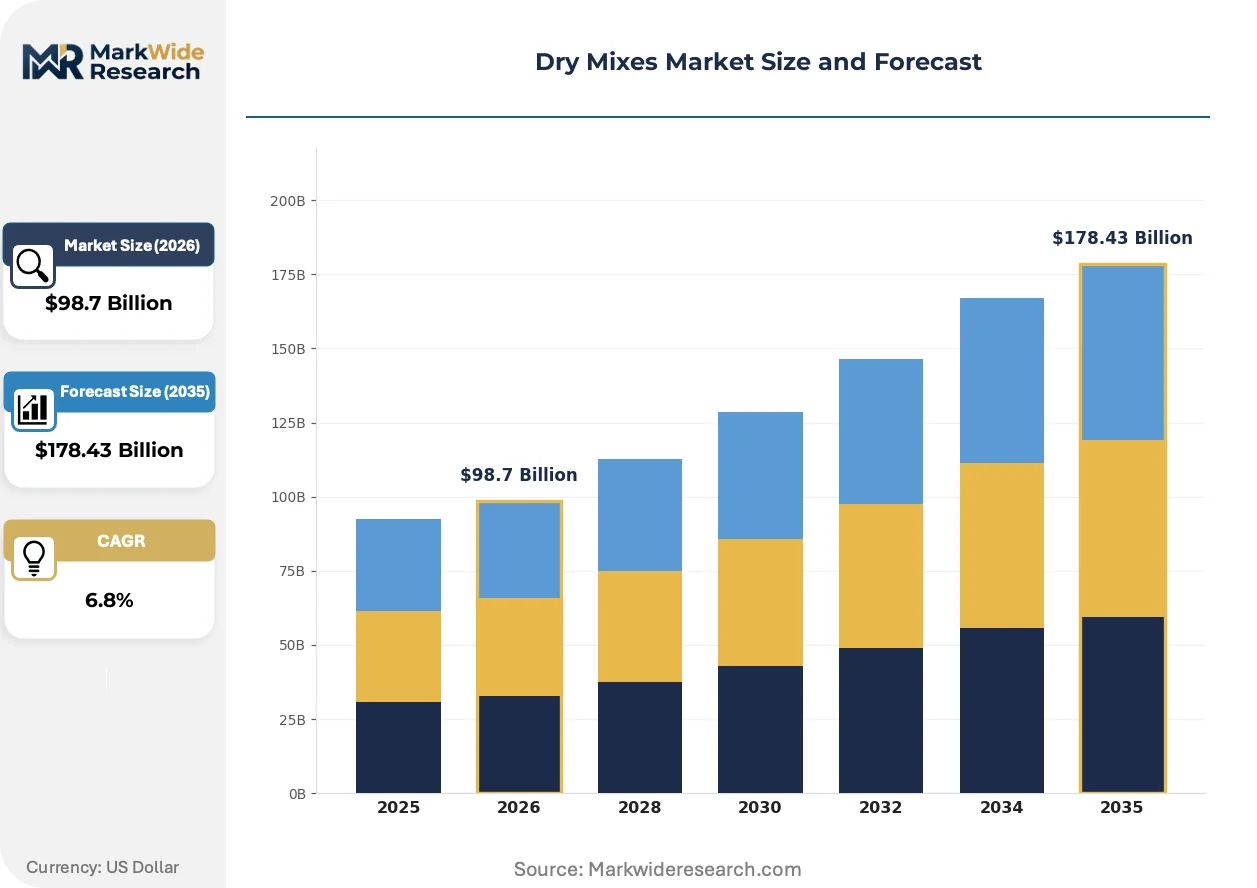
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $178.43 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pancake Mix, Soup Mix, Beverage Mix, Sauce Mix Application: Food Service, Retail, Catering, Industrial End User: Restaurants, Households, Cafes, Food Processing Packaging Type: Bulk Bags, Sachets, Pouches, Jars |
| Companies Covered | Unilever, Kraft Heinz, Cargill, Kerry Group, Archer Daniels Midland, BASF, General Mills, McCormick & Company, Nestle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dry Mixes Market Emerging Trajectories
Spray-drying and encapsulation technologies are converging with precision fermentation to reshape how functional ingredients enter dry mix matrices. Formulators now balance process efficiency against label simplicity.
Encapsulated lipid systems are hybridizing with plant-protein carriers to deliver stable fat-soluble vitamins in fortified beverage powders. Sports nutrition brands in Germany and Australia are adopting these hybrid matrices at pilot scale. The technology is compressing traditional emulsifier loads while extending nutrient bioavailability claims.
REACH restrictions on microplastics in consumer products are forcing reformulation of anti-caking agents in European-targeted seasoning blends. Industrial buyers must validate replacement silicate and cellulose alternatives through accelerated stability testing. Sauce mix exporters to the Netherlands and Sweden face the most compressed compliance timelines.
Food service operators are unbundling soup and sauce preparation from kitchen labor, purchasing pre-portioned dry bases that require only hot water activation. This operational shift displaces scratch-cooking stations in contract catering kitchens across Singapore and Dubai. Hotel chains are piloting the model in buffet and room-service applications.
Dry Mixes Market Segmentation
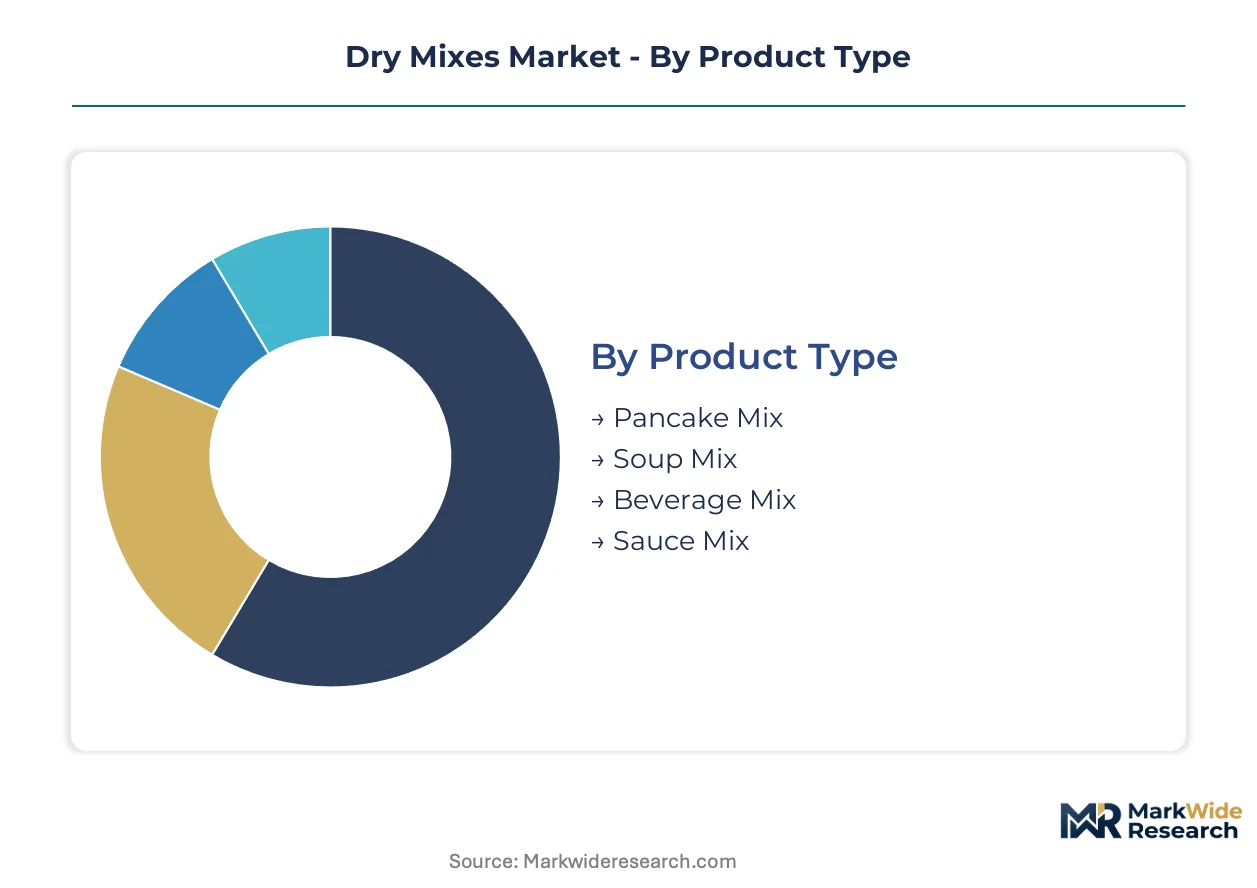
Dry mixes manufacturers must align production cadences with divergent consumption velocities across product categories. Pancake mixes rotate inventory slowly while sachet formats turn weekly in urban convenience channels.
Product Type:
Pancake mixes sit in pantry rotation cycles measured in months, whereas beverage sachets clear shelves in days across Southeast Asian transit hubs.
- Pancake Mix:Wheat-flour based formulations with leavening systems and dried dairy components, typically packaged in multi-serve formats. North American retail channels concentrate procurement here, constrained by clean-label reformulations that eliminate aluminum phosphate leavening agents.
- Beverage Mix:Spray-dried coffee, cocoa, and malted drink powders with encapsulated lipid systems for flavor stability. Mumbai and Jakarta households drive sachet-format demand, accelerated by single-serve consumption rituals in working-class apartments.
- Soup Mix:Dehydrated vegetable and protein particulates with hydrocolloid thickeners. European food service chains specify these for labor reduction in contract catering.
- Sauce Mix:Starch-thickened powder bases requiring hot water activation. Premium formulations incorporate Kerry Group flavor science for restaurant chain consistency.
Pancake mix anchors the volume base while beverage mix gains share at the steepest rate.
Application:
Cost tier differentiation separates capital-intensive industrial buyers from margin-sensitive retail operators.
- Food Service:High-volume procurement of sauce and soup bases by hotel chains and contract caterers in Singapore and Dubai. Labor substitution value justifies premium pricing for consistent hydration performance.
- Retail:Supermarket and hypermarket distribution of pancake and beverage mixes. India's urban households concentrate here, with FSSAI licensing thresholds culling informal suppliers.
- Catering:Event and institutional feeding operations requiring bulk-format dry bases. Shelf-life stability drives specification above flavor complexity.
- Industrial:Food processing facilities purchasing intermediate dry blends for further manufacturing. Southeast Asian instant noodle producers represent concentrated demand.
Food service commands the margin premium while retail absorbs the largest absolute volume.
End User:
Customer type determines packaging format preference and price elasticity thresholds.
- Restaurants:Full-service and quick-service operators sourcing sauce and soup bases for kitchen labor reduction. Chains in Jakarta and Manila negotiate direct supply arrangements with blenders.
- Households:Urban working populations in India's major cities favor single-serve sachets for daily meal preparation with minimal cooking infrastructure.
- Cafes:Independent coffee chains in Ho Chi Minh City and Manila bypass distributors for custom beverage formulations. Portion control and brand differentiation drive specification.
- Food Processing:Industrial buyers deploying dry mixes to standardize flavor profiles and compress batch-to-batch variance in high-volume production.
Households anchor the volume base while cafes expand most quickly through direct supply relationships.
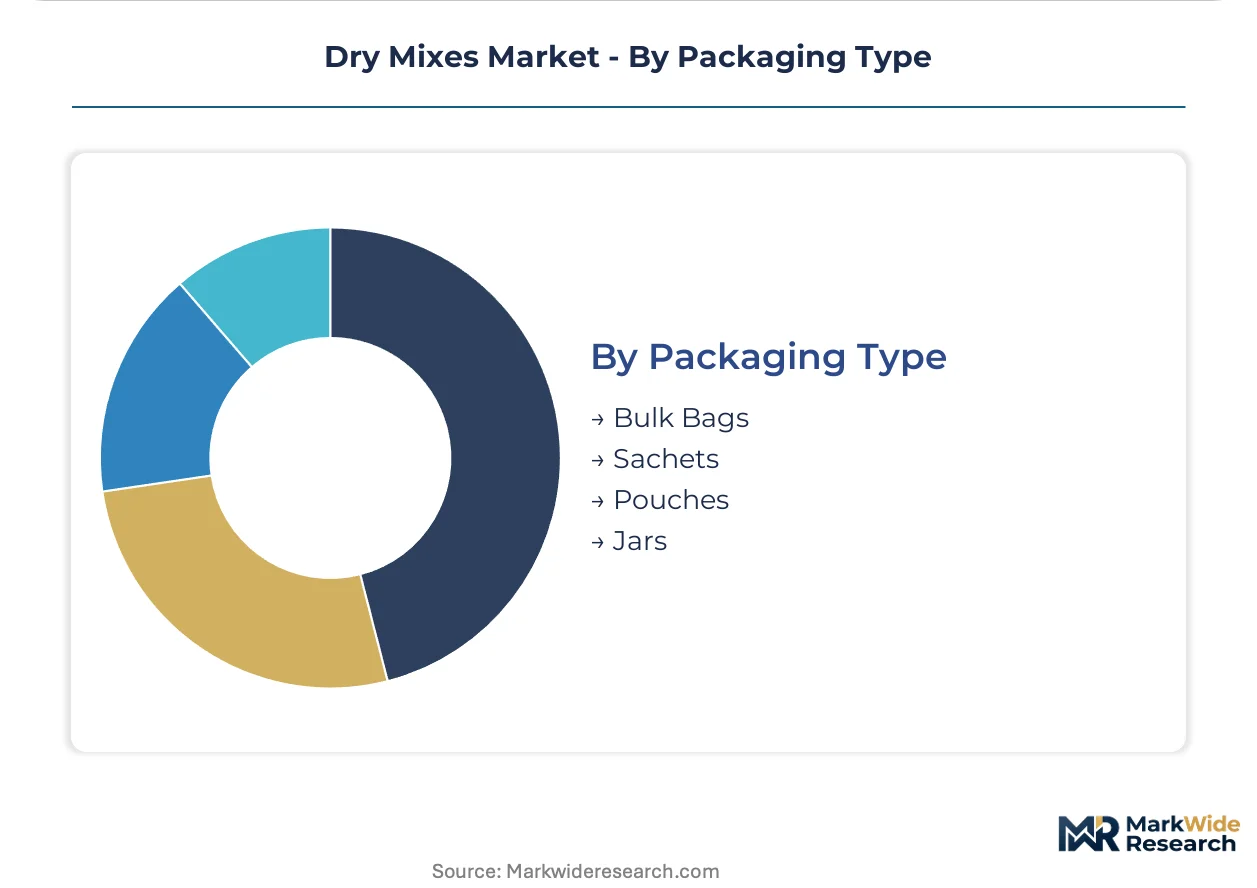
Packaging Type:
Supply concentration in laminate film production shapes format accessibility across price tiers.
- Bulk Bags:Industrial-scale packaging for food processing and catering procurement. Moisture retention below 5% demands multi-layer construction tethered to petrochemical feedstock pricing.
- Sachets:Single-serve portions dominating urban household and cafe channels. Nitrogen-flush vertical form-fill-seal lines require capital investment that favors organized manufacturers.
- Pouches:Intermediate formats for retail pancake and beverage mixes. Zipper reclosure features add material cost for pantry storage convenience.
- Jars:Rigid packaging for premium sauce and seasoning blends. Glass and PET containers concentrate in North American retail shelf presence.
Bulk bags anchor the volume base while sachets climb the fastest through urban convenience adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dry mixes trade flows reveal import dependency in premium formulations against export strength in commodity hydrocolloids. India and China anchor raw material supply chains while Western markets concentrate formulation value addition.
United States
Food service chains drive procurement of sauce and soup bases for kitchen labor reduction. FDA food facility registration and GRAS self-determination requirements shape ingredient approval pathways for domestic blenders. Chicago and Dallas metropolitan areas concentrate contract manufacturing capacity for pancake and beverage mix production.
Germany
Sports nutrition brands pilot encapsulated lipid systems in fortified beverage powders at commercial scale. EFSA evaluations of food additives and enzymes directly influence reformulation cycles across German processing facilities. The Rhine-Ruhr industrial corridor hosts spray-drying infrastructure serving Central European instant mix demand.
India
Urban working populations in Mumbai, Bangalore, and Delhi favor single-serve sachets for daily meal preparation. FSSAI licensing mandates and BIS packaging standards create compliance thresholds favoring organized manufacturers with dedicated quality laboratories. Gujarat and Maharashtra states concentrate guar gum processing capacity underpinning global hydrocolloid supply.
Vietnam
Contract manufacturers expand encapsulated flavor production capacity to serve regional instant beverage mix brands. The country's national food safety authority enforces licensing requirements for export-oriented blending facilities. Ho Chi Minh City anchors direct supply relationships with independent cafe chains across Southeast Asia.
United Arab Emirates
Hotel chains and contract caterers in Dubai pilot pre-portioned dry bases displacing scratch-cooking stations. MOHAP licensing requirements govern food manufacturing facility approvals in the emirates. Dubai's logistics infrastructure positions the city as re-export hub for dry mixes entering African and South Asian markets.
Dry Mixes Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream controlling critical inputs. The dry mixes landscape fragments across asset-light contract manufacturers and integrated multinationals with captive flavor science infrastructure. Three archetypes dominate: hydrocolloid suppliers with upstream agricultural control, flavor houses leveraging encapsulation technology, and retail brand owners with distribution density. Competitive moves concentrate on backward integration into hydrocolloid sourcing and direct supply relationships bypassing traditional distribution.
Within the integrated multinational tier, Kerry Group and McCormick & Company exemplify divergent positioning strategies. Kerry Group leverages European flavor science infrastructure to dominate premium sauce mix formulations for food service chains. McCormick & Company anchors North American retail shelf presence through decades of brand equity in spice-forward dry blends. Cargill sustains upstream control over critical hydrocolloid and texturizer supply streams that underpin industrial-scale production across multiple downstream formulators.
| Leading Market Players |
|---|
| Unilever |
| Kraft Heinz |
| Cargill |
| Kerry Group |
| Archer Daniels Midland |
| BASF |
| General Mills |
| McCormick & Company |
| Nestle |
| Others |
Supply Flow & Price Mechanics
Gujarat's guar gum processing clusters concentrate global hydrocolloid supply, translating monsoon-driven harvest volatility directly into price premiums for downstream sauce and soup mix formulators. Contract manufacturers in Vietnam and Thailand absorb feedstock fluctuations through extended payment terms, while European food service buyers face compressed margins from REACH-compliant packaging material substitutions.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with differentiation driven by hydrocolloid grade and FSSAI certification tier. Price erosion runs through the value-tier sachet segment as informal blenders undercut organized manufacturers on nitrogen-flush packaging costs. Food processing facilities in Southeast Asia exhibit lowest price sensitivity, absorbing premiums for consistent hydration performance, while India's urban households concentrate demand in economy-tier single-serve formats.
Supply Chain Analysis
Extended payment terms from Indian guar gum processors to Vietnamese contract manufacturers stabilize working capital across the upstream tier. Supply concentrates in India, China, and Thailand for critical hydrocolloid, encapsulated flavor, and laminate film inputs. Single-source vulnerability in xanthan gum fermentation capacity exposes formulators to export duty fluctuations. Distribution runs through regional blending hubs in Ho Chi Minh City and Jakarta before final-mile delivery to cafe chains and hotel operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward organized manufacturers as FSSAI licensing mandates cull informal blenders, consolidating procurement leverage among India's urban household segment and Southeast Asian food service chains.
For Market Incumbents: Harden supply security through backward integration into Gujarat guar gum sourcing or captive spray-drying capacity in Vietnam. Kerry Group and McCormick & Company demonstrate divergent defensive postures—flavor science infrastructure versus retail shelf density—against emerging contract manufacturers with asset-light blending models. EFSA additive evaluations threaten formulation obsolescence; prioritize clean-label R&D spend over margin defense in European-targeted portfolios. For New Entrants and Emerging Players: Build out direct supply relationships with independent cafe chains in Jakarta, Manila, and Ho Chi Minh City, bypassing traditional distributor markups. India's FSSAI licensing thresholds create white-space acquisition targets among quality-laboratory-equipped regional blenders. Position on enzyme-assisted hydration technology for ambient-temperature beverage preparation, targeting sports nutrition brands in Germany and Australia with pilot-scale encapsulated lipid systems. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors flavor houses with encapsulation infrastructure over commodity hydrocolloid traders. Long-term viability hinges on convergence of precision fermentation with spray-drying capacity across the projection horizon. Target acquisition archetype: regional contract manufacturers with FSSAI licensing and nitrogen-flush sachet lines. Monitor EFSA clean-label enforcement timelines as inflection indicator for natural hydrocolloid demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydrocolloid Sourcing | Captive guar gum supply from Gujarat insulates margin from monsoon-driven price spikes. |
| Clean-Label Reformulation Investment | EFSA additive evaluations force removal of artificial stabilizers from European-targeted soup bases. |
| Direct Supply Channel Expansion | Bypassing distributors to Jakarta cafe chains captures margin premium from portion-control demand. |
| Spray-Drying Capacity Addition | Vietnamese encapsulated flavor infrastructure serves regional instant beverage mix brands. |
| FSSAI Licensing Acquisition | Quality laboratory mandates cull informal blenders, creating consolidated distribution access. |
Methodological Framework
Desk research of FSSAI licensing databases, EFSA additive evaluation records, and Indian customs hydrocolloid trade data preceded structured interviews with food processing procurement leads, contract manufacturing operations heads, cafe chain supply managers, and flavor house R&D directors. Primary fieldwork across Mumbai, Ho Chi Minh City, and Jakarta validated secondary findings on sachet adoption patterns and direct supply relationship formation. Bottom-up demand modeling from urban household consumption velocity triangulated against top-down value chain analysis.
Assumptions held fixed across the projection horizon include EFSA enforcement timelines for artificial stabilizer removal and FSSAI laboratory licensing compliance thresholds. Segmentation dimensions modeled encompass product type, application channel, end-user archetype, and packaging format, with regional regulatory clusters treated as scenario variables. CAGRs derive from fitted growth curves against historical consumption data, with spray-drying capacity expansion rates and encapsulated flavor technology adoption curves as industry-specific inputs.
Sensitivities concentrate around monsoon severity affecting Gujarat guar gum harvests, REACH microplastic restriction enforcement in the Netherlands and Sweden, and cafe channel consolidation in Southeast Asia. Forecasts reflect documented assumptions; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Wheat Gluten Market
Ingredients
Australia Sodium Reduction Ingredients Market
Ingredients
Mastic Gum Market
Ingredients
Corn Steep Liquor Market
Ingredients
South America Clean Ingredients Market
Ingredients
Glucosylglycerol Market
Ingredients
North America Gluten Free Flour Market
Ingredients
Europe Gelatin Market
Ingredients
Edible Halal Gelatin Market
Ingredients
Feed Ingredients Market
Ingredients
Zero-Calorie Oil Market
Ingredients
South America Vegetable Oil Market
Ingredients
Multi-Grain Premixes Market
Ingredients
Food Grade L-Arabinose Market
Ingredients
South America Fruit and Vegetable Ingredients Market
Ingredients
Farnesene Market