
 Mozzarella Cheese Market | 2026-2036
Mozzarella Cheese Market Size, Share, and Industry Trends Forecast 2026-2036
Mozzarella Cheese Market Intelligence
Plant-based casein alternatives is rebalancing cost structures in mozzarella formulation as dairy processors hedge against milk price volatility. Grande Cheese Company leverages captive milk supply across Wisconsin to sustain margin stability. BelGioioso Cheese specializes in traditional Italian-style fresh mozzarella, occupying premium retail slots in Northeastern United States. Leprino Foods dominates pizza cheese blends through manufacturing scale that supplies national quick-service chains.
Mozzarella is a pasta filata cheese produced by stretching curd in hot water, yielding elastic texture and superior meltability with moisture content ranging from 45% to 60%. Its primary commercial purpose centers on pizza topping applications where stretch, browning, and oil release determine functional performance. Low-moisture mozzarella commands the largest volume share due to extended shelf life and standardized shredding behavior for food service operators. Fresh mozzarella generates premium pricing in retail and specialty restaurant channels where provenance labeling and buffalo milk sourcing differentiate positioning. Distribution through wholesale channels concentrates margin pools with broadline distributors serving multi-unit restaurant chains.
FDA standards of identity govern mozzarella composition and labeling in the United States, while EFSA dairy hygiene protocols shape export qualification for European processors. USDA organic certification and EU PDO designations create tiered market access that filters supplier participation by compliance capability. Stakeholders must monitor evolving methane reduction mandates from EPA and MEE as these determine feedstock costs and processing facility permitting timelines.
Market Dynamics
Clean-label reformulation pressure from quick-service restaurants is compressing ingredient lists while the EU F-Gas Regulation forces cold-chain infrastructure overhaul across European distribution networks.
Growth Catalysts
- EU F-Gas Regulation:Mandates refrigerant phase-down that accelerates cold-chain modernization, extending shelf life for fresh mozzarella and opening new retail channels previously blocked by spoilage risk.
- Quick-service restaurant clean-label mandates:Operators are stripping artificial additives from cheese specifications, pulling demand toward minimally processed mozzarella with traceable milk sourcing.
- Plant-based casein alternatives:Dairy processors are hedging input cost exposure by reformulating with precision-fermented proteins that replicate stretch and melt functionality.
Market Restraints
- Milk price volatility:Feed cost inflation and weather-driven supply swings in Wisconsin and Lombardy compress processor margins unpredictably.
- Fresh mozzarella shelf-life ceiling:High-moisture formulations remain chemically constrained to 7-14 day windows regardless of packaging innovation.
- Buffalo milk supply concentration:Campania province in Italy dominates global buffalo mozzarella output, creating single-point vulnerability for premium positioning.
Strategic Opportunities
- USDA organic certification pipeline:Accelerated conversion of conventional dairy herds to organic is creating supply scarcity that commands 40-60% price premiums in retail.
- Direct-to-foodservice platforms:Digital procurement portals are bypassing broadline distributors, letting regional cheesemakers capture margin pools previously held by Sysco and US Foods.
- Pizza automation compatibility:Robotic topping systems require standardized shred geometry and moisture consistency that only automated production lines can guarantee.
Industry Challenges
- Pasta filata operator skill scarcity:Traditional hot-water stretching demands years of apprenticeship; mechanization erodes texture quality in fresh formats.
- PDO certification timeline:EU protected designation applications require 18-24 month documentation cycles that delay market entry for new regional entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mozzarella Cheese Market |
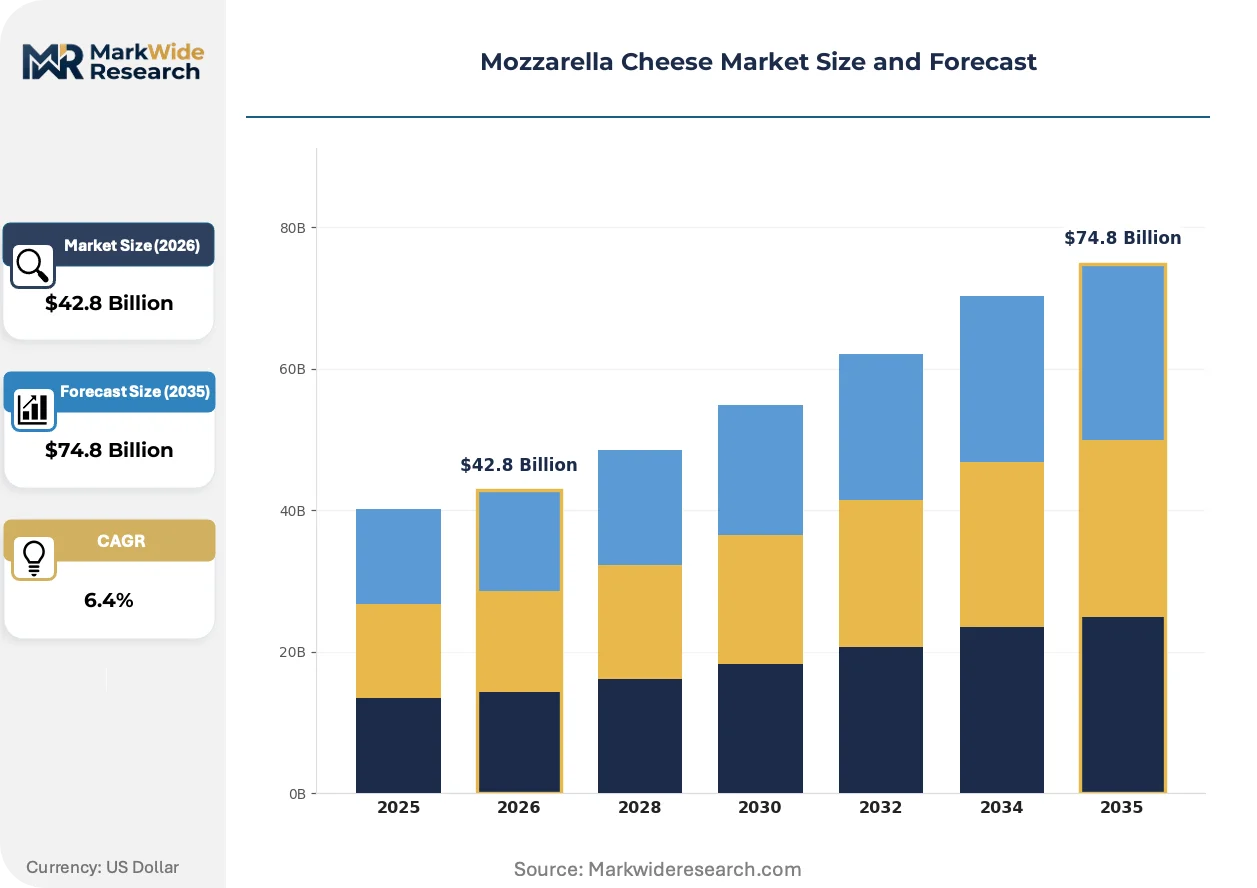
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $74.8 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Mozzarella, Low-Moisture Mozzarella, Smoked Mozzarella, Mozzarella Sticks End User: Restaurants, Cafes, Retail, Food Service Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesale Packaging Type: Block, Shredded, Slice, Bulk |
| Companies Covered | Grande Cheese Company, BelGioioso Cheese, Leprino Foods, Land O'Lakes, Lactalis American Group, Arla Foods, Galbani Cheese, Foremost Farms USA, Saputo Cheese USA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mozzarella Cheese Market Strategic Shifts & Innovations
Stretch-curve engineering and fermentation precision are replacing commodity production logic, while regulatory pressure on refrigerants and methane emissions reconfigures facility investment priorities.
Precision fermentation of dairy proteins is absorbing R&D investment from major ingredient suppliers. Pizza chains with automated kitchen lines are piloting these proteins in blend ratios with conventional milk to standardize functional performance. The technology is absorbing uncertainty around future milk supply contracts by creating ingredient independence.
The EU F-Gas Regulation is banning hydrofluorocarbon refrigerants in commercial cold storage by 2030. Italian and French processors are retrofitting facilities with CO2 cascade systems or magnetic refrigeration to maintain export qualification. Fresh mozzarella with 45-60 day extended shelf life is becoming technically feasible, reshaping retail distribution radius.
Foodservice procurement through consolidated buying groups is compressing supplier rosters. Multi-unit pizza chains are mandating single-source cheese specifications with locked-in shred dimensions and oil-release curves. This consolidation is most visible in the US Northeast, where independent pizzerias are losing access to artisanal fresh mozzarella as distributors rationalize SKUs toward high-volume national accounts.
Mozzarella Cheese Market Segmentation
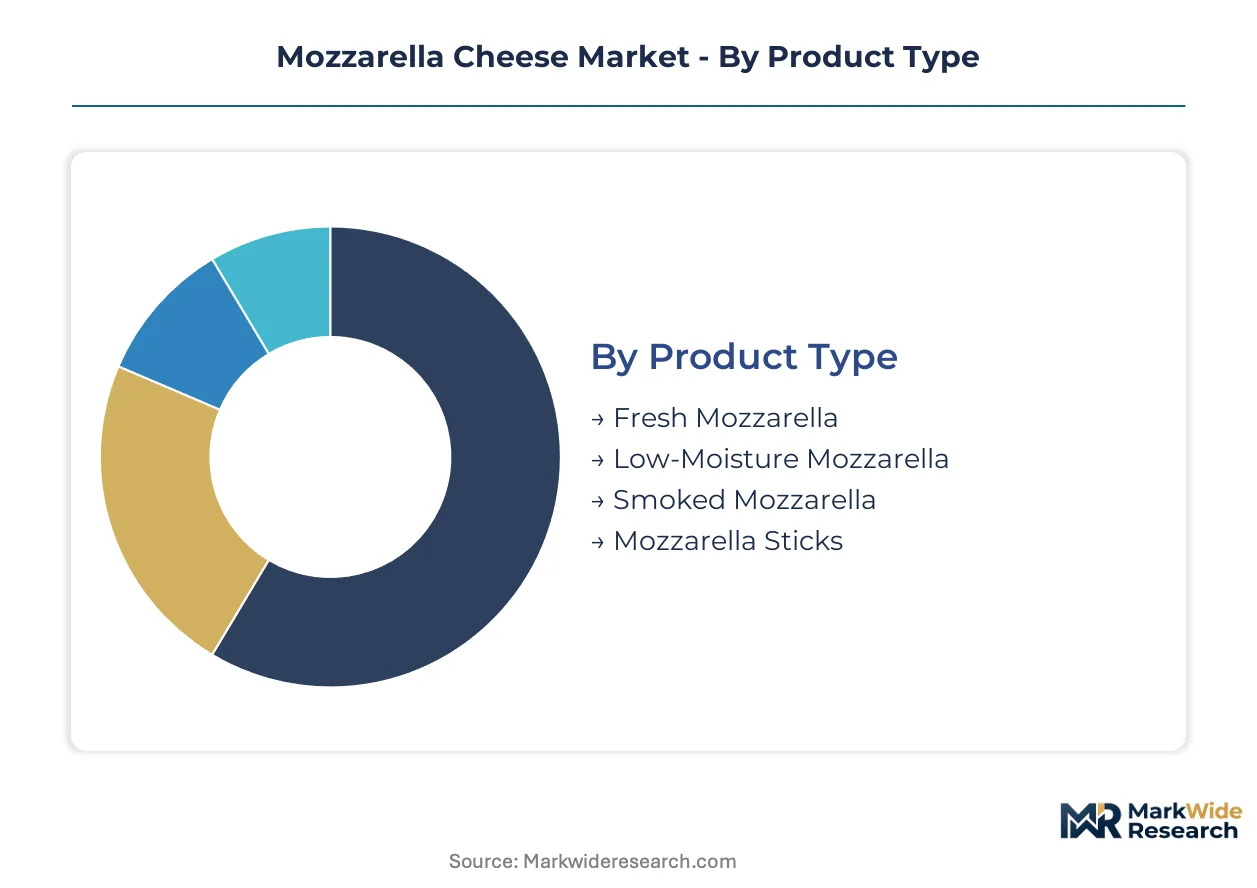
Mozzarella's functional diversity creates distinct value pools across moisture specifications, end-use applications, and distribution formats. Each segment commands different margin structures and faces unique regulatory and operational constraints.
Product Type:
Moisture content and aging protocol separate buyers by shelf-life requirements and melt-performance specifications.
- Fresh Mozzarella:High-moisture pasta filata with 45-60% water content delivers elastic texture and clean dairy flavor. Premium positioning in Italian restaurants and specialty retail in Italy and the United States depends on buffalo milk provenance and PDO certification.
- Low-Moisture Mozzarella:Reduced to 45-52% moisture through controlled aging, this format achieves 30-60 day shelf stability. Pizza chains in the United States specify this grade for automated shredding systems and consistent browning performance.
- Smoked Mozzarella:Cold-smoked variants target charcuterie boards and gourmet sandwich applications with distinct flavor differentiation.
- Mozzarella Sticks:Batter-coated frozen formats concentrate in quick-service appetizer menus and school foodservice programs.
Low-moisture mozzarella leads volumes today; fresh mozzarella is gaining share fastest in premium retail channels.
End User:
Volume scale and procurement sophistication create four distinct buyer archetypes with incompatible service requirements.
- Restaurants:Full-service operators demand custom shred dimensions and locked-in oil-release specifications for pizza applications. Menu clean-label mandates from quick-service chains in the United States are pulling specification authority away from distributors toward corporate procurement teams.
- Food Service:Institutional buyers prioritize case-cost efficiency and extended frozen shelf life over artisanal attributes. Sysco and US Foods consolidation is compressing supplier rosters toward national-scale processors.
- Cafes:Limited-menu operators favor pre-portioned formats that reduce labor and waste in high-turnover breakfast sandwich applications.
- Retail:Grocery channels split between private-label commodity blocks and premium fresh mozzarella with Italian PDO labeling.
Food service leads volumes today; restaurants are climbing the fastest as automation drives standardization.
Distribution Channel:
Cold-chain infrastructure investment and buyer consolidation are reconfiguring route-to-market economics.
- Wholesale:Broadline distributors serving multi-unit chains capture the largest margin pools through consolidated procurement and private-label development.
- Supermarkets:Retail consolidation in the United States and Italy is shifting shelf space toward store-brand mozzarella with direct processor relationships.
- Specialty Stores:Independent cheese shops and Italian delis maintain artisanal fresh mozzarella with Campania province provenance at 40-60% price premiums.
- Online:Direct-to-consumer platforms and restaurant procurement portals are bypassing traditional distribution layers for regional cheesemakers.
Wholesale leads volumes today; online channels show steepest expansion trajectory as digital procurement penetrates foodservice.
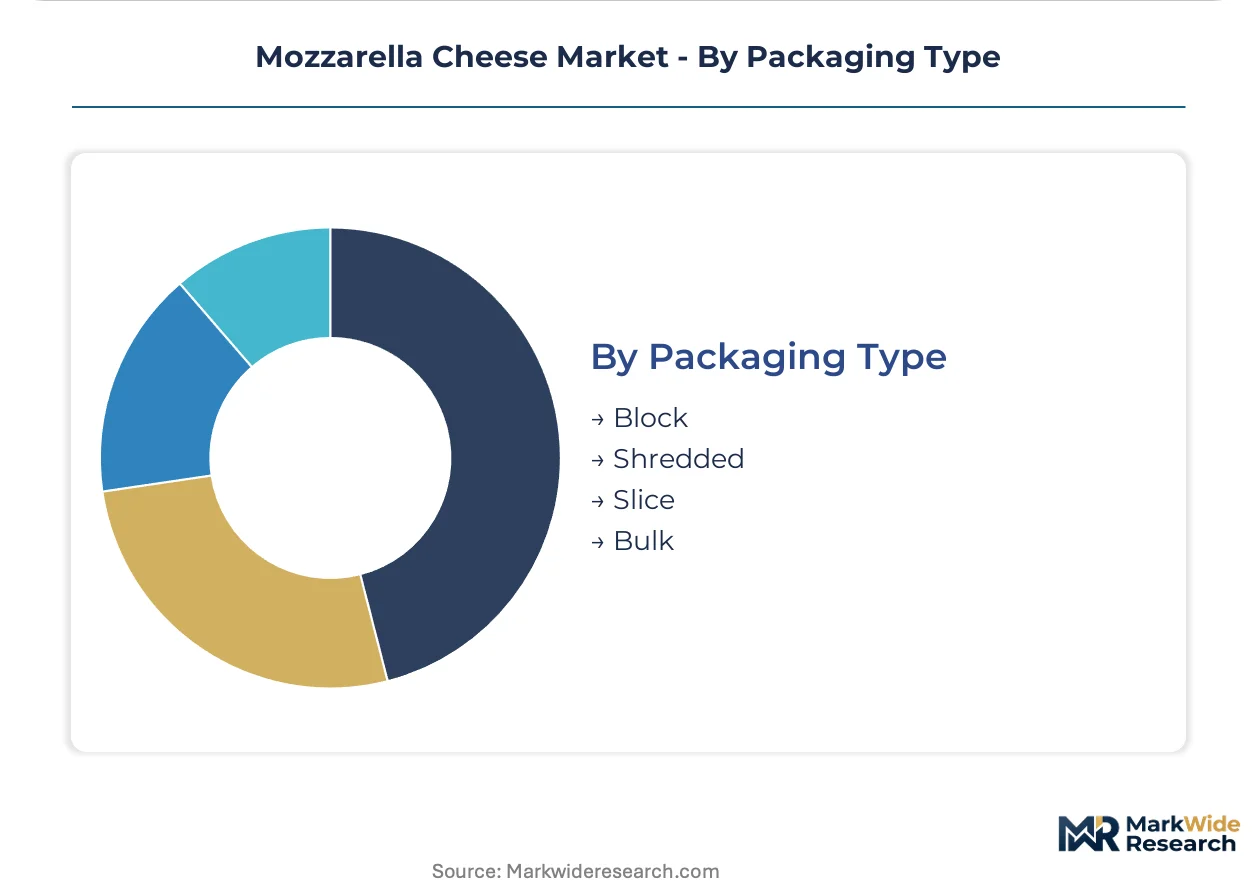
Packaging Type:
Format selection reflects automation compatibility, portion control needs, and shelf-life extension priorities.
- Shredded:Pre-cut formats with anti-caking agents dominate pizza automation lines requiring precise weight deposition and standardized melt curves.
- Block:Unprocessed formats allow on-site cutting flexibility for operators with variable menu mixes and lower throughput.
- Slice:Deli-thin portions target sandwich assembly and school nutrition programs with labor-minimization requirements.
- Bulk:Foodservice sacks and totes serve high-volume operators with in-house shredding equipment and frozen storage capacity.
Shredded leads volumes today; bulk formats are expanding most quickly in automated production environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wisconsin's Fox River Valley anchors mozzarella production capacity through captive milk supply networks and automated pasta filata lines serving national pizza chains.
United States
Quick-service restaurant procurement consolidation drives demand for standardized low-moisture mozzarella with locked-in shred specifications. FDA standards of identity govern composition and labeling requirements for interstate commerce. Wisconsin and California dairy cooperatives operate the largest automated production facilities supplying Sysco and US Foods distribution networks.
Italy
Fresh mozzarella consumption concentrates in Campania province where buffalo milk sourcing commands premium retail positioning. EFSA dairy hygiene protocols shape export qualification for European processors seeking US market access. Lombardy's industrial dairies balance traditional pasta filata methods with mechanized stretching lines for foodservice volume.
Germany
EU F-Gas Regulation mandates refrigerant phase-down accelerating cold-chain infrastructure modernization across Bavarian distribution hubs. REACH compliance requirements filter supplier participation in private-label retail programs. Munich-based processors retrofit facilities with CO2 cascade systems to maintain fresh mozzarella shelf-life extension for export markets.
France
PDO certification timelines create 18-24 month documentation cycles that delay market entry for new regional mozzarella entrants. ANSM food safety inspections govern production facility permitting for fresh cheese operations. Normandy dairy cooperatives leverage organic herd conversion programs to capture USDA certification premiums in transatlantic trade.
Netherlands
Rotterdam port logistics concentrate mozzarella import volumes for redistribution across North European foodservice channels. Dutch dairy processors specialize in mozzarella stick frozen formats for quick-service appetizer menus. Randstad region cold-storage operators invest in magnetic refrigeration systems ahead of 2030 HFC bans.
Mozzarella Cheese Market Key Industry Players
Global majors compete with regional champions across milk supply security and automation scale. The vendor base stratifies into three tiers: integrated dairy cooperatives with captive herd supply, specialty Italian-style producers with PDO positioning, and private-label manufacturers serving broadline distributors. Consolidation pressure from foodservice procurement rationalization favors scale-driven operators with standardized shred geometry capabilities. Strategic moves center on backward integration into milk supply and facility automation for robotic pizza line compatibility.
Within the integrated dairy tier, Grande Cheese Company and Leprino Foods exemplify scale-driven positioning through Wisconsin-based milk supply control and national quick-service chain relationships. BelGioioso Cheese occupies the specialty fresh mozzarella segment with Italian-style production methods. These three entities represent divergent competitive archetypes: captive supply integration, manufacturing scale dominance, and premium provenance differentiation.
| Leading Market Players |
|---|
| Grande Cheese Company |
| BelGioioso Cheese |
| Leprino Foods |
| Land O'Lakes |
| Lactalis American Group |
| Arla Foods |
| Galbani Cheese |
| Foremost Farms USA |
| Saputo Cheese USA |
| Others |
Cost & Logistics Intelligence
Precision-fermented protein adoption is compressing input cost volatility while simultaneously redrawing supplier power maps away from traditional dairy cooperatives. This technological inflection forces processors to rebalance milk supply contracts against bioengineered alternatives, reshaping both margin structures and upstream sourcing concentration.
Pricing Analysis
Input-cost pass-through from milk price swings dominates mozzarella pricing, with Wisconsin and Lombardy feed markets transmitting volatility directly to processor margins. Three-tier pricing structure across premium PDO-certified fresh, standard low-moisture block, and economy private-label shredded segments captures quality and certification differentiation. Cost compression in commodity tiers is intensifying because foodservice procurement consolidation demands locked-in volume contracts. Institutional buyers through Sysco and US Foods exhibit highest price sensitivity, while specialty retailers sourcing Campania buffalo mozzarella show lowest elasticity.
Supply Chain Analysis
EU PDO certification and USDA organic qualification gate market access, filtering supplier participation by compliance capability and documentation timelines. Production concentrates in Italy, the United States, and Germany, with raw milk, precision-fermented proteins, and packaging materials as critical inputs. Single-source vulnerability in Campania buffalo milk supply creates concentration risk for premium positioning. Distribution runs through broadline distributors serving multi-unit chains, with direct-to-foodservice platforms emerging as bypass channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mozzarella market reads as a late-cycle quality story where quick-service clean-label mandates pull demand toward traceable, minimally processed formats with provenance documentation.
For Market Incumbents: Acquire captive milk supply networks in Wisconsin or Lombardy to hedge against precision-fermented protein displacement and input cost volatility. Deepen automation investment for robotic pizza line compatibility, as foodservice procurement consolidation threatens artisanal suppliers without standardized shred geometry capabilities. For New Entrants and Emerging Players: Precision-fermented dairy proteins offer technology-first wedge into commodity mozzarella tiers where milk price volatility erodes incumbent margins. Target USDA organic certification pipeline gaps in retail channels where supply scarcity commands sustained premiums, deploying direct-to-foodservice digital procurement platforms as go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among regional cheesemakers with organic certification pipeline and underutilized pasta filata capacity. Five-to-ten year viability hinges on backward integration into milk supply and automation scale. The signal to watch is quick-service restaurant specification shifts toward blended precision-fermented and conventional mozzarella formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Milk Supply | Captive herd control insulates Grande Cheese and Leprino Foods from Lombardy feed cost volatility. |
| Precision Fermentation Partnership | Bioengineered protein blends reduce input cost exposure for processors hedging milk price swings. |
| USDA Organic Certification Pipeline | Accelerated herd conversion captures 40-60% retail premiums through supply-constrained organic mozzarella tiers. |
| Robotic Pizza Line Compatibility Investment | Standardized shred geometry and moisture consistency qualify suppliers for automated quick-service procurement. |
| Direct-to-Foodservice Platform Launch | Digital procurement portals bypass Sysco and US Foods margin capture for regional cheesemakers. |
Research Approach
Multiple input streams — processor production data, distributor procurement records, and retail audit panels — were reconciled across primary interviews with dairy cooperative executives, quick-service restaurant procurement directors, foodservice distribution category managers, and specialty retail buyers, validated against USDA dairy reports, FDA standards filings, EU F-Gas regulatory texts, and trade customs databases, with bottom-up facility capacity modeling and top-down consumption estimation triangulating volume figures.
Data-stream reconciliation across moisture specifications, end-use applications, distribution formats, and regional regulatory clusters anchored the analytical framework over the projection horizon. CAGRs derived from segment-level growth trajectory blending, incorporating milk supply contract structures, cold-chain infrastructure investment cycles, and precision-fermentation technology penetration curves as mozzarella-specific forecast inputs.
The model holds under stable feed cost and regulatory compliance environments; deviation in EU methane reduction mandates or EPA permitting timelines would shift capacity expansion trajectories. A model refresh is warranted upon material change in quick-service restaurant clean-label specification timelines or precision-fermented protein cost parity achievement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Skim Milk Powder Market
Dairy Products
United Kingdom Milk Protein Market
Dairy Products
Dry Whole Milk Powder Market
Dairy Products
Disposable Curd Cups Market
Dairy Products
Halal Cheese Market
Dairy Products
Mexico Lactose-Free Dairy Market
Dairy Products
Milk Mineral Market
Dairy Products
Europe Drinkable Yogurt Market
Dairy Products
Organic Dairy Market
Dairy Products
Global Quark and Fromage Frais Market
Dairy Products
Milk Protein Concentrate Market
Dairy Products
Low Cholesterol Cheese Market
Dairy Products
India Milk Protein Market
Dairy Products
Organic Cheese Powder Market
Dairy Products
Dairy Carton Market
Dairy Products
United States Milk Protein Market