
 Antibody Pair Kits Market | 2026-2036
Antibody Pair Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Antibody Pair Kits Market Outlook
Academic institutions are rotating toward higher-throughput screening workflows, displacing smaller research groups as the dominant volume buyers of antibody pair kits. Thermo Fisher Scientific leverages its channel breadth to sustain dominant positions in pre-packaged kit distribution across North American research corridors. Abcam differentiates through recombinant antibody specialization, while Bio-Rad Laboratories anchors its competitive stance with deep manufacturing scale in immunoassay components.
Antibody pair kits consist of matched capture and detection antibodies designed for sandwich immunoassay formats, typically supplied at defined concentration ratios with validated cross-reactivity profiles and species specificity guarantees. These reagent systems serve the primary industrial purpose of enabling quantitative protein detection in complex biological matrices without requiring end-user antibody screening. Monoclonal antibody pairs command premium positioning due to their batch-to-batch consistency and defined epitope specificity, while recombinant formats represent the fastest-expanding segment as synthetic biology workflows displace hybridoma-dependent production. ELISA applications consume the largest absolute volume of pair kits, though flow cytometry multiplexing is generating disproportionate margin growth as instrument complexity rises.
The FDA governs diagnostic-grade antibody pair kits through its bioanalytical method validation guidance, while the EMA's ICH Q2(R1) implementation shapes European demand for documented specificity data. ISO 13485 certification requirements for in-vitro diagnostic suppliers are forcing upstream reagent vendors to adopt quality management systems that mirror medical device standards. Stakeholders must monitor how evolving regulatory divergence between the FDA and EMA affects kit registration pathways and determine whether to pursue dual-compliant product architectures or region-specific formulations.
Market Dynamics
Biologics pipeline expansion by pharmaceutical developers is concentrating procurement power among assay developers who demand pre-validated reagent systems, compressing supplier margins while elevating performance requirements.
Growth Catalysts
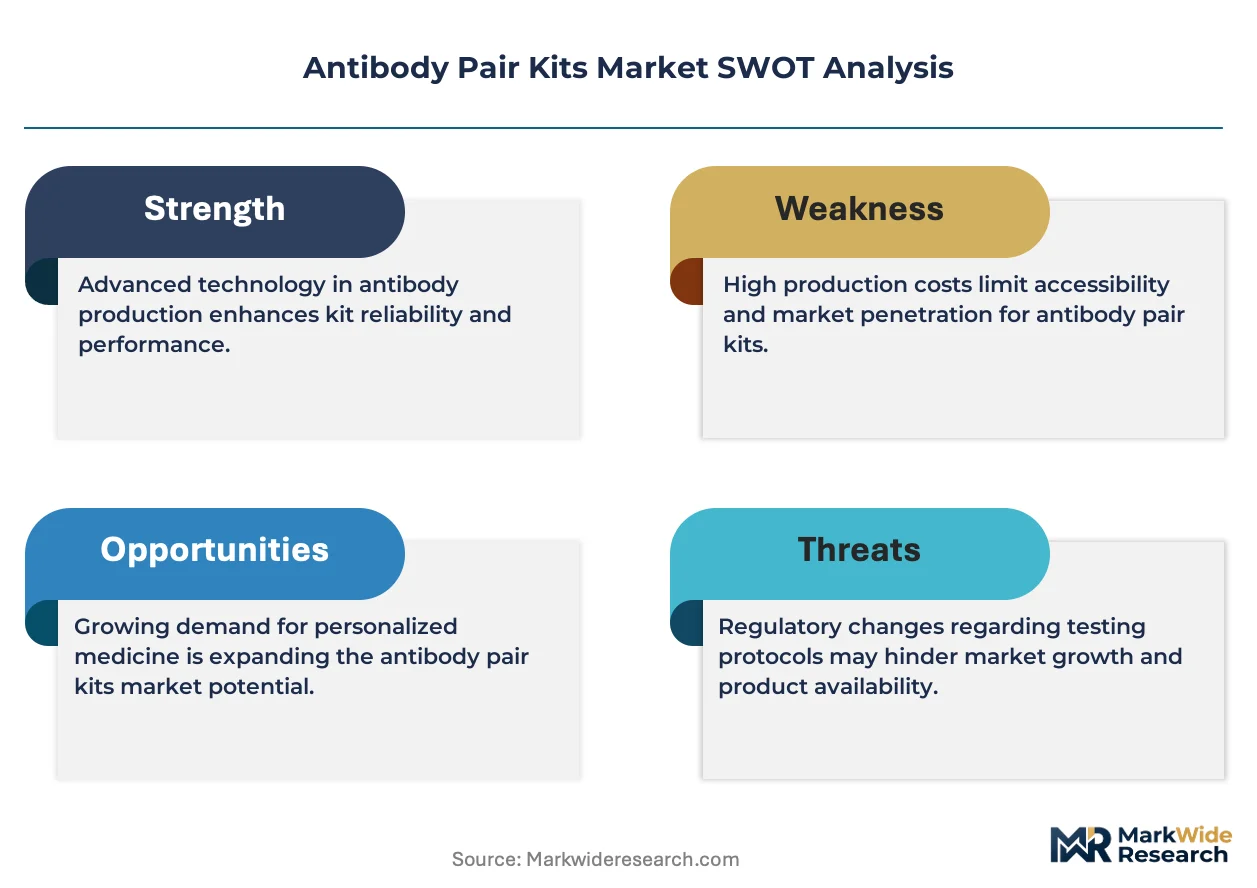
- FDA Bioanalytical Method Validation Guidance:Elevated performance standards for kit specificity and reproducibility are compelling diagnostic manufacturers to upgrade reagent sourcing, expanding the addressable market for documented antibody pairs.
- Flow Cytometry Multiplexing:Instrument complexity gains in cytometry platforms are driving demand for matched antibody sets optimized for multi-parameter panels in oncology and immunology workflows.
- Boston-San Diego Biotech Corridors:Concentrated R&D expenditure in these clusters sustains premium reagent consumption volumes unmatched by dispersed academic purchasing.
Market Restraints
- Hybridoma Production Dependency:Traditional monoclonal antibody generation relies on mammalian cell culture systems vulnerable to batch variability and extended lead times, constraining supply responsiveness.
- Recombinant Input Cost Volatility:Synthetic biology workflows require plasmid construction, transient transfection, and protein A purification steps with fluctuating consumables pricing.
- ISO 13485 Certification Burden:In-vitro diagnostic suppliers must implement quality management systems mirroring medical device standards, raising fixed compliance costs for reagent vendors.
Strategic Opportunities
- India CDMO Expansion:Contract development and manufacturing organizations in Hyderabad and Bengaluru are building biologics capabilities that require validated reagent supply chains for assay development.
- Single-Cell Proteomics Convergence:Integration of mass cytometry with spatial transcriptomics is creating demand for antibody pairs compatible with metal-isotope and fluorescent barcoding schemes.
- EMA ICH Q2(R1) Harmonization:Documented specificity requirements under European guidelines are opening pathways for vendors with validated cross-reactivity profiles to capture diagnostic-grade contracts.
Industry Challenges
- Hybridoma-to-Recombinant Transition:Technical workforce gaps in molecular cloning and display library screening are slowing production migration away from traditional cell line methods.
- Dual Jurisdiction Registration Complexity:Divergent FDA and EMA validation pathways force vendors to maintain parallel documentation systems or sacrifice market access in one region.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antibody Pair Kits Market |
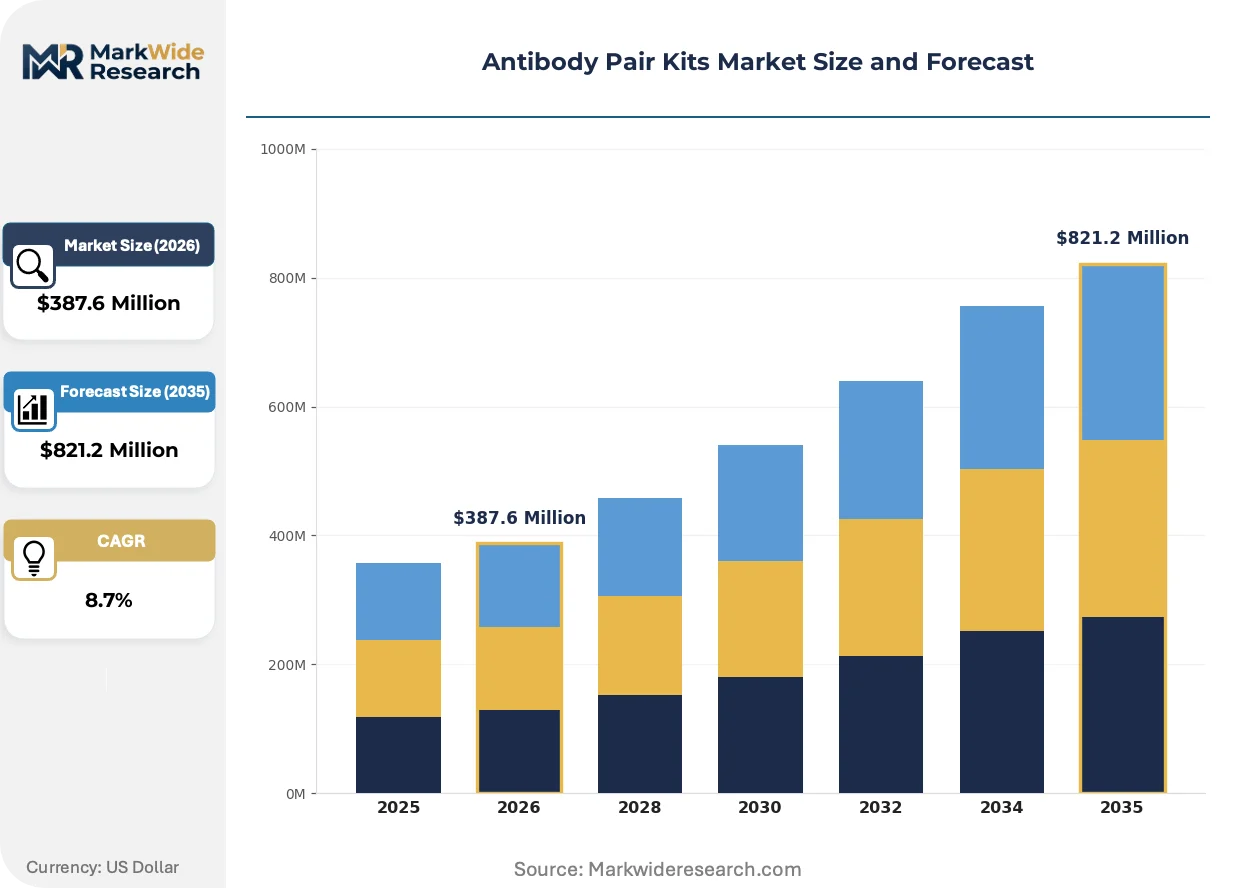
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal, Polyclonal, Recombinant, Hybridoma Application: Immunoassays, Western Blotting, Flow Cytometry, ELISA End User: Research Laboratories, Academic Institutions, Pharmaceuticals, Biotech Companies Packaging Type: Pre-packaged Kits, Custom Kits, Bulk Packages, Single Use |
| Companies Covered | Thermo Fisher Scientific, Abcam, Bio-Rad Laboratories, Abnova Corporation, Novus Biologicals, Creative Diagnostics, GeneTex, Merck KGaA, PerkinElmer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antibody Pair Kits Market Strategic Shifts
Recombinant antibody engineering is fragmenting established production paradigms while regulatory documentation requirements harden across jurisdictions. These forces are compressing supplier differentiation and elevating buyer power.
Recombinant monoclonal antibody formats produced through phage display and yeast surface display systems are displacing hybridoma-dependent methods. Contract research organizations and large pharmaceutical assay developers are adopting these synthetic biology workflows at accelerating pace. The technology is fragmenting supplier bases by enabling de novo epitope discovery without immunization, compressing traditional reagent vendors' technical moats.
EMA implementation of ICH Q2(R1) guidelines for analytical method validation is tightening specificity documentation requirements for diagnostic-grade reagents. European in-vitro diagnostic manufacturers must now submit cross-reactivity profiles and stability data that exceed prior self-certification norms. Kit vendors serving Germany, France, and the Netherlands are restructuring quality assurance functions to meet these evidentiary burdens.
Academic purchasing concentration is displacing fragmented small-lab procurement with centralized core facility buying. University shared resource centers in the United States and United Kingdom are consolidating antibody pair kit selection under dedicated reagent procurement officers. This behavioral shift is most visible in Boston, London, and Singapore where institutional volume contracts are squeezing list pricing and demanding extended validation support.
Antibody Pair Kits Market Segmentation
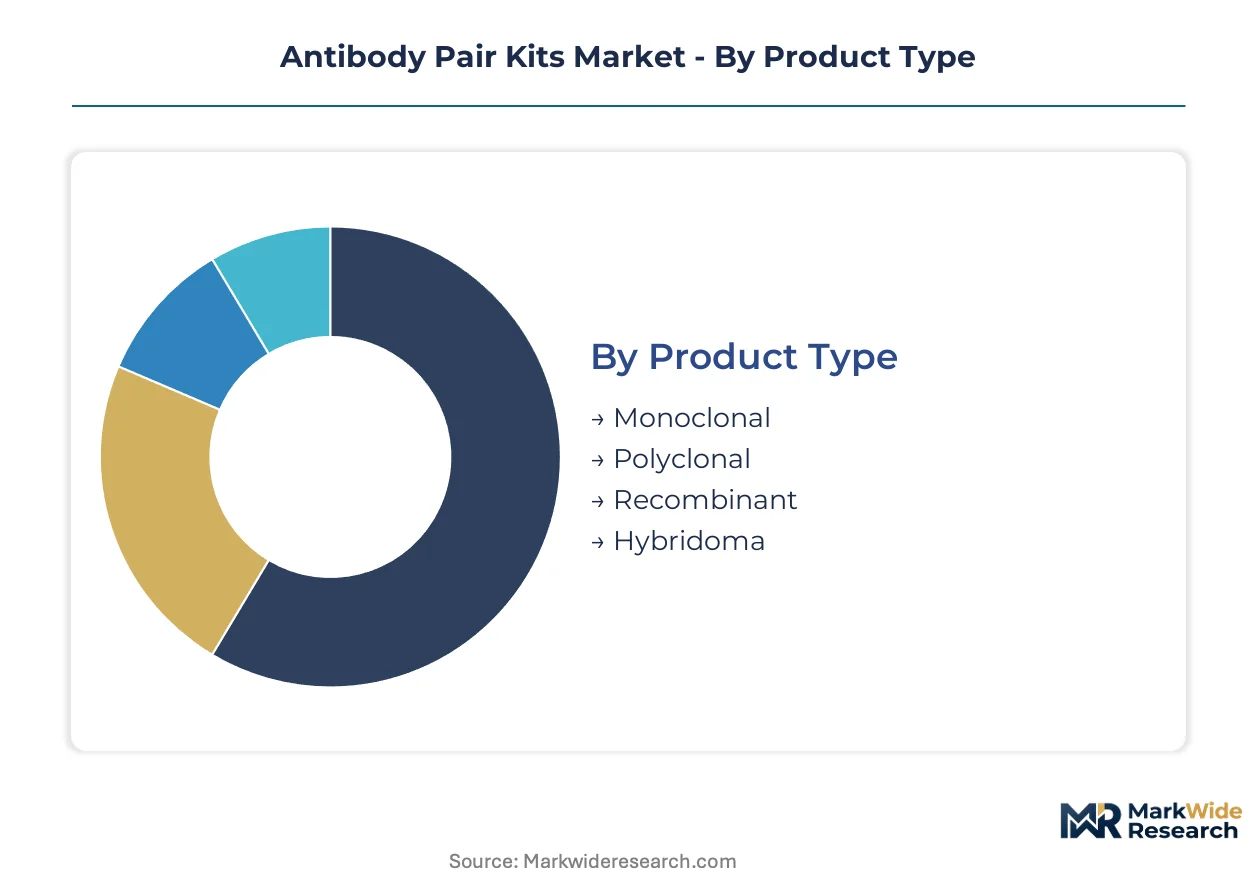
Antibody pair kit segmentation reveals divergent supply chain configurations across product architectures, with recombinant formats reshaping procurement patterns while traditional hybridoma systems retain entrenched positions in regulated diagnostics. Understanding these segment boundaries enables suppliers to align production capacity with the specific validation documentation and lead-time requirements of distinct buyer clusters.
Product Type:
Domestic production concentrates in monoclonal and hybridoma segments where established mammalian cell culture infrastructure supports FDA-regulated supply chains, while recombinant formats increasingly draw on distributed synthetic biology capacity spanning contract manufacturing networks.
- Monoclonal:Defined epitope specificity through single B-cell clone derivation delivers batch-to-batch consistency critical for diagnostic assay validation. Pharmaceutical assay developers in Boston and San Diego biotech corridors consume premium volumes for biologics pipeline support, though hybridoma production dependency constrains supply responsiveness during demand surges.
- Recombinant:Phage display and yeast surface display systems enable de novo epitope discovery without immunization, fragmenting traditional supplier technical moats. Synthetic biology workflows are displacing hybridoma-dependent production fastest in academic core facilities and CRO assay development groups seeking compressed lead times.
- Polyclonal:Multi-epitope recognition profiles serve research applications where cross-reactivity tolerance permits broader antigen detection.
- Hybridoma:Established cell line archives anchor regulated diagnostic supply with documented stability histories meeting FDA bioanalytical validation requirements.
Monoclonal antibody pairs command the established base. The steepest expansion runs through recombinant formats.
Application:
Cost tier stratification separates high-throughput screening workflows demanding disposable standardization from specialized multiplexing applications commanding performance premiums.
- ELISA:Enzyme-linked immunosorbent assay formats consume the largest absolute kit volume, with sandwich configurations requiring matched capture-detection pairs at defined concentration ratios. Pharmaceutical quality control laboratories in United States manufacturing hubs drive repetitive procurement of pre-validated reagent systems for biologics release testing.
- Flow Cytometry:Multi-parameter panel optimization demands antibody pairs compatible with fluorescent and metal-isotope barcoding schemes. Oncology and immunology research workflows generate disproportionate margin growth as instrument complexity rises and reagent qualification burdens intensify.
- Immunoassays:Broad diagnostic platform category encompassing chemiluminescence and electrochemiluminescence detection with species-specific matrix validation requirements.
- Western Blotting:Semi-quantitative protein detection applications favor polyclonal detection antibodies for enhanced signal amplification in complex lysate analysis.
ELISA maintains volume leadership across installed assay infrastructure. Flow cytometry multiplexing climbs the fastest on per-unit value expansion.
End User:
Customer type determines procurement scale and validation documentation intensity, with pharmaceutical buyers demanding ISO 13485-traceable supply chains while academic purchasing consolidates under institutional volume contracts.
- Pharmaceuticals:Bioanalytical method validation under FDA guidance elevates performance standards for kit specificity and reproducibility, compelling documented cross-reactivity profiles and stability data. Biologics pipeline expansion concentrates procurement power among assay developers who demand pre-validated reagent systems.
- Academic Institutions:Shared resource centers in Boston, London, and Singapore are consolidating antibody pair kit selection under dedicated reagent procurement officers, displacing fragmented small-lab purchasing with centralized core facility buying that squeezes list pricing.
- Biotech Companies:Early-stage developers prioritize recombinant formats for rapid assay prototyping without hybridoma lead time constraints.
- Research Laboratories:Smaller independent groups retain fragmented procurement patterns with higher per-unit costs and limited validation support demands.
Pharmaceutical end users anchor premium pricing through regulatory-grade documentation requirements. Academic institutional purchasing is gaining share fastest through procurement consolidation.
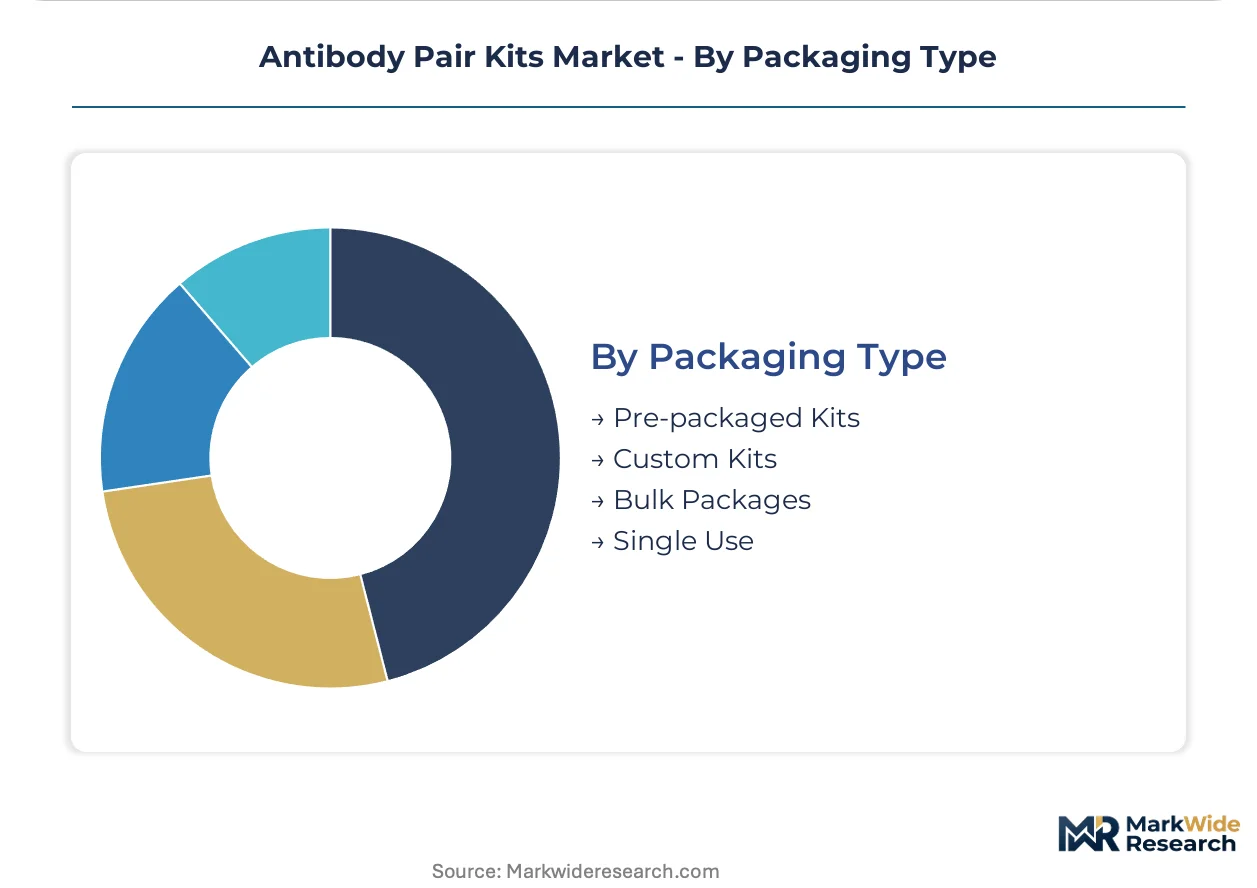
Packaging Type:
Volume scale separates single-use convenience formats from bulk configurations serving high-throughput screening operations with dedicated reagent preparation infrastructure.
- Pre-packaged Kits:Defined concentration ratios with validated cross-reactivity profiles eliminate end-user antibody screening, serving assay developers requiring immediate deployment without reagent optimization. Thermo Fisher Scientific channel breadth sustains dominant distribution positions across North American research corridors for this format.
- Custom Kits:Tailored antibody pair selection with application-specific buffer formulations and conjugation schemes serves specialized multiplexing workflows in spatial transcriptomics and single-cell proteomics convergence applications.
- Bulk Packages:Decant configurations support pharmaceutical manufacturing scale quality control with lot-to-lot consistency guarantees and extended stability documentation.
- Single Use:Disposable aliquots reduce contamination risk in distributed academic laboratory environments without cold chain infrastructure investment.
Pre-packaged kits command the established base. Custom kit configurations expand most quickly as spatial omics applications proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Boston's biotech logistics infrastructure underwrites Massachusetts' role as a primary reagent import gateway, while San Diego's cross-border manufacturing corridors channel antibody pair kit volumes into California's life sciences clusters.
United States
FDA bioanalytical method validation guidance drives diagnostic manufacturers toward documented antibody pairs with cross-reactivity profiles. The agency's evolving performance standards compress supplier margins while elevating reagent sourcing requirements. Boston and San Diego biotech corridors sustain premium consumption volumes through concentrated R&D expenditure and biologics pipeline expansion.
Germany
EMA ICH Q2(R1) implementation tightens specificity documentation requirements for European in-vitro diagnostic manufacturers. The country's national pharmaceutical regulator mandates stability data submissions that exceed prior self-certification norms. Munich and Heidelberg life sciences clusters are restructuring quality assurance functions to meet evidentiary burdens for diagnostic-grade contracts.
United Kingdom
Academic institutional purchasing is consolidating antibody pair kit selection under dedicated reagent procurement officers at shared resource centers. The Medicines and Healthcare products Regulatory Agency shapes demand through post-Brexit alignment with international validation standards. London university core facilities are displacing fragmented small-lab purchasing with centralized volume contracts that squeeze list pricing.
India
Contract development and manufacturing organizations in Hyderabad and Bengaluru are building biologics capabilities requiring validated reagent supply chains for assay development. The Central Drugs Standard Control Organization governs diagnostic import standards with increasing documentation intensity. Karnataka's pharmaceutical manufacturing belt is attracting antibody pair kit distributors seeking to anchor regional supply networks.
Singapore
Institutional volume contracts at university shared resource centers are concentrating procurement power among dedicated reagent officers. The national pharmaceutical regulator enforces ISO 13485-aligned quality management expectations for imported diagnostic components. The city-state's biomedical research hub is generating disproportionate demand for multiplexing-compatible antibody pairs in spatial transcriptomics workflows.
Antibody Pair Kits Market Competitive Environment
Concentration sits with diversified life sciences conglomerates and specialized antibody developers. Thermo Fisher Scientific leverages channel breadth to sustain dominant positions in pre-packaged kit distribution across North American research corridors. Abcam differentiates through recombinant antibody specialization. Bio-Rad Laboratories anchors its stance with manufacturing scale in immunoassay components. Strategic moves center on synthetic biology workflow adoption and quality management system upgrades to ISO 13485 standards.
Among diversified reagent conglomerates, Thermo Fisher Scientific occupies a position exemplifying channel-driven market presence. Abcam and Bio-Rad Laboratories represent contrasting specialization archetypes—recombinant engineering depth versus manufacturing scale breadth. Merck KGaA and PerkinElmer sit within the analytical instrumentation tier, where reagent supply integrates with platform ecosystem strategies. Novus Biologicals, GeneTex, and Creative Diagnostics exemplify the antibody-focused developer segment where technical moats fragment under synthetic biology displacement.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Abcam |
| Bio-Rad Laboratories |
| Abnova Corporation |
| Novus Biologicals |
| Creative Diagnostics |
| GeneTex |
| Merck KGaA |
| PerkinElmer |
| Others |
Value Chain & Pricing Dynamics
ISO 13485 certification gates both supplier qualification and price differentiation in diagnostic-grade antibody pair kits, compressing margins for uncertified vendors while enabling premium positioning for quality-system-compliant manufacturers serving FDA-regulated pharmaceutical assay developers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale. Premium tiers command positioning through FDA bioanalytical validation documentation and ISO 13485-traceable supply chains, while standard tiers serve academic core facilities with consolidated procurement contracts. Pricing pressure stems from hybridoma-to-recombinant production transitions as synthetic biology workflows compress technical moats. Academic institutional buyers exhibit highest price sensitivity through centralized volume negotiations, whereas pharmaceutical quality control laboratories demonstrate lowest sensitivity due to regulatory compliance requirements.
Supply Chain Analysis
Strategic stockpiling of hybridoma cell line archives anchors supply security for regulated diagnostic manufacturers, while just-in-time recombinant production serves academic and CRO assay development groups seeking compressed lead times. Production concentrates in the United States, Germany, and China, with mammalian cell culture infrastructure in Massachusetts and California feeding FDA-regulated supply chains. Critical inputs encompass fetal bovine serum, protein A purification resins, and plasmid construction consumables. Single-source vulnerability in hybridoma cell line archives poses structural risk. Distribution runs through life sciences distributors and direct pharmaceutical procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical workforce gaps in molecular cloning and display library screening constrain production migration, creating scarcity premiums for vendors with recombinant engineering capabilities and documented cross-reactivity profiles.
For Market Incumbents: Secure hybridoma cell line archives through exclusive licensing agreements and accelerate ISO 13485 quality management system upgrades to defend against recombinant-format entrants. Channel control in Boston and San Diego biotech corridors remains critical as procurement consolidation elevates buyer power. Capacity addition in synthetic biology workflows addresses the technical workforce gap threatening traditional production methods. For New Entrants and Emerging Players: Custom kit configuration services represent an under-served layer where incumbents prioritize standardized pre-packaged formats. Spatial transcriptomics and single-cell proteomics applications in Singapore and London academic clusters offer the most penetrable entry points. A go-to-market angle emphasizing compressed recombinant lead times without hybridoma dependency targets biotech companies and CRO assay development groups. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified life sciences conglomerates with under-optimized antibody reagent divisions lacking dedicated recombinant engineering focus. Long-term viability hinges on synthetic biology workflow adoption rates and regulatory documentation intensity across jurisdictions. The signal to watch is EMA-FDA validation pathway divergence forcing parallel compliance investments.| Strategic Initiative | Industry Significance |
|---|---|
| Recombinant Engineering Transition | Phage display and yeast surface display adoption fragments established hybridoma technical moats among incumbent suppliers. |
| ISO 13485 Quality System Upgrade | Diagnostic-grade certification opens FDA-regulated pharmaceutical procurement channels with documented stability data requirements. |
| Academic Core Facility Partnership | Institutional volume contracts in Boston, London, and Singapore concentrate procurement power and squeeze list pricing. |
| Spatial Omics Application Development | Metal-isotope and fluorescent barcoding compatibility captures flow cytometry multiplexing margin expansion in oncology workflows. |
| India CDMO Supply Chain Anchoring | Hyderabad and Bengaluru biologics manufacturing growth creates validated reagent demand for regional distribution networks. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with assay development scientists, regulatory affairs specialists, reagent procurement officers, and core facility directors; and secondary validation through FDA bioanalytical method validation guidance documents, EMA ICH Q2(R1) implementation records, ISO 13485 certification databases, and pharmaceutical quality control laboratory procurement disclosures. Bottom-up triangulation across product type, application, end user, and packaging type segmentation converged with top-down market sizing.
Across the analysis window, the forecasting framework modeled recombinant versus hybridoma production format adoption curves, ELISA versus flow cytometry application growth differentials, and pharmaceutical versus academic end user procurement concentration patterns. CAGRs derived from segment-level volume and value buildups incorporating synthetic biology workflow penetration rates and regulatory documentation intensity indices.
Underlying assumptions cover stable FDA-EMA regulatory divergence, recombinant input cost volatility within historical bands, and hybridoma cell line archive accessibility, with deviation risk concentrated in sudden ISO 13485 certification requirement expansions or synthetic biology workforce supply shocks. Revision becomes warranted when recombinant production cost curves cross hybridoma parity thresholds or regulatory harmonization eliminates dual-jurisdiction documentation burdens.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Immunocytokines Market
Biopharmaceuticals
Asia-Pacific Biologics Market
Biopharmaceuticals
Human Immunodeficiency Virus (HIV) Drugs Market
Biopharmaceuticals
North America Insulin Pens Market
Biopharmaceuticals
Global Levofloxacin Market
Biopharmaceuticals
Global Biopharmaceuticals Contract Manufacturing Market
Biopharmaceuticals
Biological Drugs Market
Biopharmaceuticals
Global Kinase Inhibitors Market
Biopharmaceuticals
Brazil Generic Drug Market
Biopharmaceuticals
Progesterone Market
Biopharmaceuticals
PCSK9 Inhibitors Market
Biopharmaceuticals
Lupus Nephritis Market
Biopharmaceuticals
India Insulin Drug and Delivery Device Market
Biopharmaceuticals
Antibody Discovery Market
Biopharmaceuticals
Theranostics Market
Biopharmaceuticals
North America Diabetes Drugs Market