
 AI in Genomics Market | 2026-2036
AI in Genomics Market Size, Share, and Industry Trends Forecast 2026-2036
AI in Genomics Market Analysis
EU AI Act compliance is consolidating the cost-of-entry calculus for genomic AI platforms seeking European market access. NVIDIA Corporation leverages its GPU-accelerated computing architecture to dominate training workloads for large-scale genomic models. Illumina, Inc. anchors its position through proprietary sequencing instrumentation that generates the foundational data streams powering downstream AI analytics. Deep Genomics specializes in predictive splicing models that differentiate its therapeutic discovery pipeline from generalist platform providers.
AI in genomics denotes the application of computational learning systems to interpret nucleotide sequence data, variant calling, and gene expression patterns from next-generation sequencing outputs with throughput exceeding terabytes per experiment. These systems automate pattern recognition across population-scale biobanks to identify disease-associated loci and predict therapeutic response for individual patients. Machine Learning applications currently lead clinical translation, while Natural Language Processing tools for biomedical literature mining represent the fastest-expanding capability segment as unstructured genomic knowledge accumulates. Drug Discovery commands the largest application-specific investment pool, though Biomarker Identification is deepening its margin profile through companion diagnostic co-development agreements with oncology pipelines.
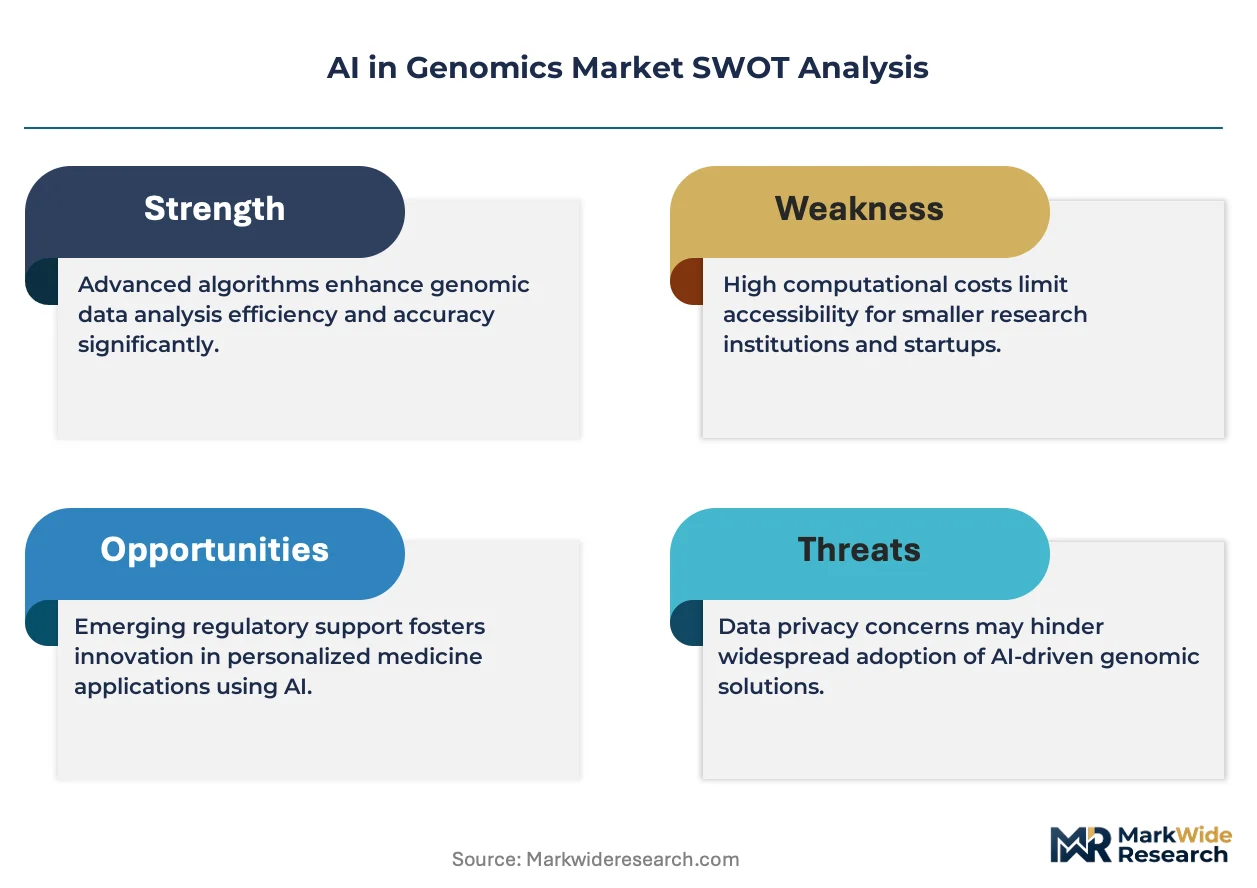
FDA oversight of AI-enabled medical devices and the EU AI Act's risk classification framework for clinical decision support are tightening validation requirements for genomic algorithms deployed in diagnostic settings. ISO 13485 quality management standards and HIPAA privacy safeguards in the United States further constrain how patient genomic data flows into model training pipelines. Stakeholders must monitor evolving regulatory divergence between jurisdictions to determine whether centralized or region-specific algorithm validation strategies minimize compliance drag on product rollout timelines.
Market Dynamics
Foundation model architectures are compressing genomic interpretation timelines from months to days, forcing pharmaceutical pipelines to restructure compound progression workflows around AI-native validation checkpoints rather than traditional wet-lab gating.
Growth Catalysts
- EU AI Act risk-classification pathways:The regulation's tiered compliance framework for clinical decision-support algorithms creates predictable certification roadmaps that de-risk European market entry for genomic diagnostic platforms.
- GPU-accelerated training infrastructure:Specialized silicon for transformer-based nucleotide sequence modeling has dropped per-experiment compute costs, enabling mid-size biotech firms to deploy population-scale variant analysis previously restricted to national sequencing consortia.
- Companion diagnostic co-development mandates:Oncology therapeutic pipelines increasingly require biomarker-qualified patient stratification, pulling AI-driven genomic profiling into front-end clinical trial design.
Market Restraints
- High-performance compute input concentration:Training workloads depend on NVIDIA's CUDA ecosystem and TSMC's advanced node fabrication, creating single-supplier vulnerability for genomic model development.
- HIPAA-GDPR data friction:Cross-border patient genomic data flows face irreconcilable consent and anonymization standards between US and European jurisdictions, fragmenting training dataset scale.
- Wet-lab validation bottlenecks:AI-predicted therapeutic targets still require CRISPR-based experimental confirmation, and core facility capacity constraints limit throughput for hypothesis testing.
Strategic Opportunities
- Underpenetrated rare disease verticals:Orphan indication pipelines in Saudi Arabia and UAE lack established biomarker frameworks, creating first-mover positioning for AI-native genomic diagnostic entrants.
- Federated learning architectures:Differential privacy protocols enable multi-institutional model training without raw data centralization, unlocking siloed hospital biobanks previously inaccessible for algorithm development.
- Japan PMDA regulatory sandbox:The pilot program for AI-enabled medical devices accelerates conditional approval timelines for genomic classifiers, compressing revenue realization cycles versus FDA 510(k) pathways.
Industry Challenges
- Computational biology talent scarcity:The intersection of deep learning architecture expertise and molecular genetics domain knowledge remains thin, inflating compensation premiums for hybrid profile hires.
- ISO 13485 quality system capex:Diagnostic algorithm deployments require medical device-grade documentation infrastructure that AI-native startups lack, forcing expensive consultancy engagements or acquisition by established manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI in Genomics Market |
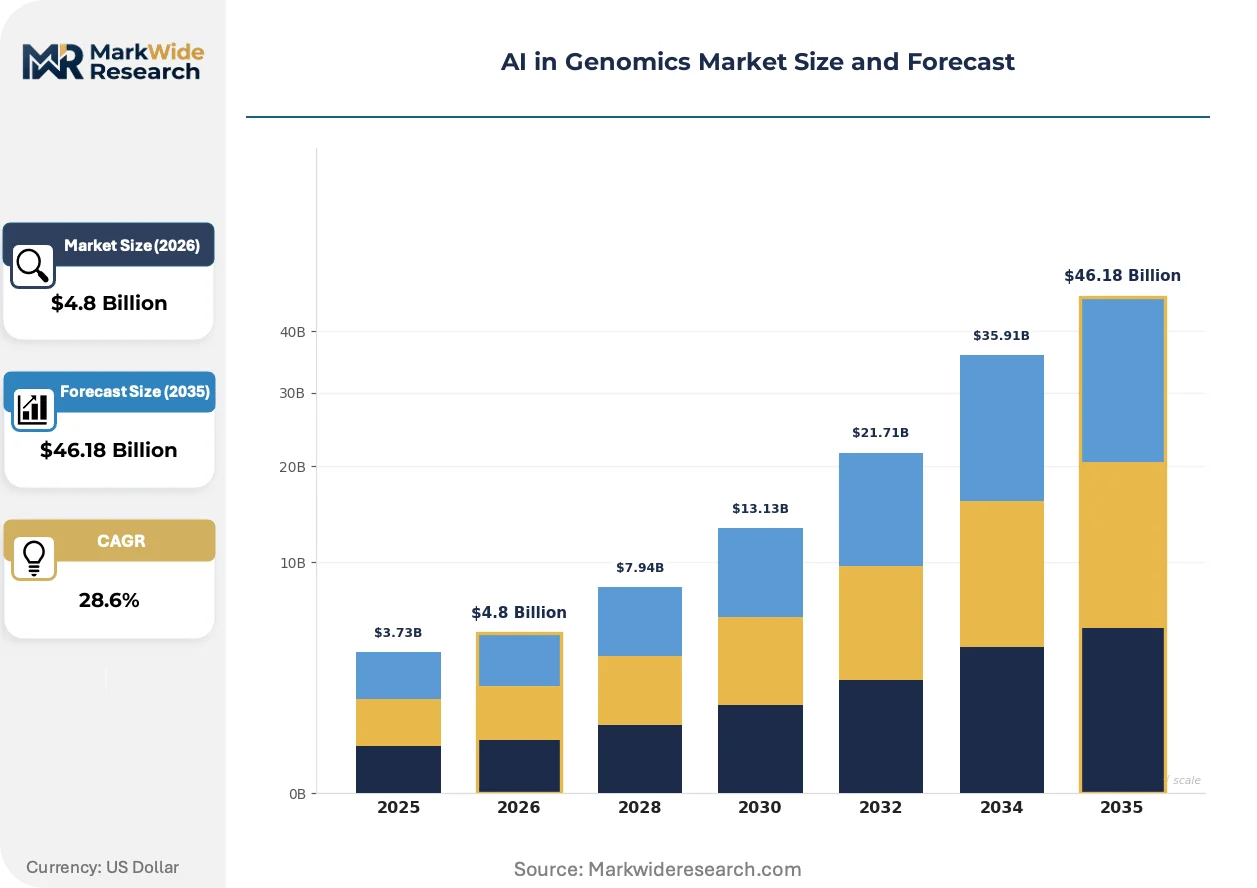
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $46.18 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Genome Sequencing, Genomic Data Analytics, Genomic Testing, Personalized Medicine Technology: Machine Learning, Natural Language Processing, Data Mining, Neural Networks Application: Drug Discovery, Disease Prediction, Gene Editing, Biomarker Identification End User: Pharmaceutical Companies, Research Institutions, Healthcare Providers, Diagnostic Laboratories |
| Companies Covered | NVIDIA Corporation, Microsoft Corporation, IBM, Illumina, Inc., SOPHiA GENETICS, Deep Genomics, Fabric Genomics, Intel Corporation, Tempus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI in Genomics Market Emerging Trajectories
Transformer architectures trained on nucleotide sequences are displacing convolutional and recurrent neural networks as the dominant genomic modeling paradigm, compressing feature engineering requirements while expanding interpretable attention mechanisms for variant pathogenicity scoring.
Multimodal foundation models integrating genomic, transcriptomic, and proteomic data streams are electrifying therapeutic target identification workflows. Large pharmaceutical manufacturers are deploying these systems across early discovery portfolios, collapsing the timeline between sequence submission and druggable site prediction from weeks to hours. The structural consequence is a reallocation of chemistry resources toward synthesis and away from target triage.
The EU AI Act's risk-based classification for clinical decision-support software is tightening validation documentation requirements for genomic diagnostic algorithms. High-risk category placement triggers conformity assessment procedures that extend commercialization timelines by twelve to eighteen months. European hospital procurement committees are responding by prioritizing vendors with pre-established notified body relationships and MDR technical file portfolios.
Biopharma R&D procurement is fragmenting from centralized IT vendor relationships toward direct engagement with specialized genomic AI boutiques. Contract research organizations that previously intermediated computational biology services are losing share to platform-native providers offering API-accessible variant interpretation. This disintermediation is most visible in Boston and San Francisco biotech clusters, where venture-backed startups maintain direct vendor relationships with Deep Genomics and similar specialized developers.
AI in Genomics Market Segmentation
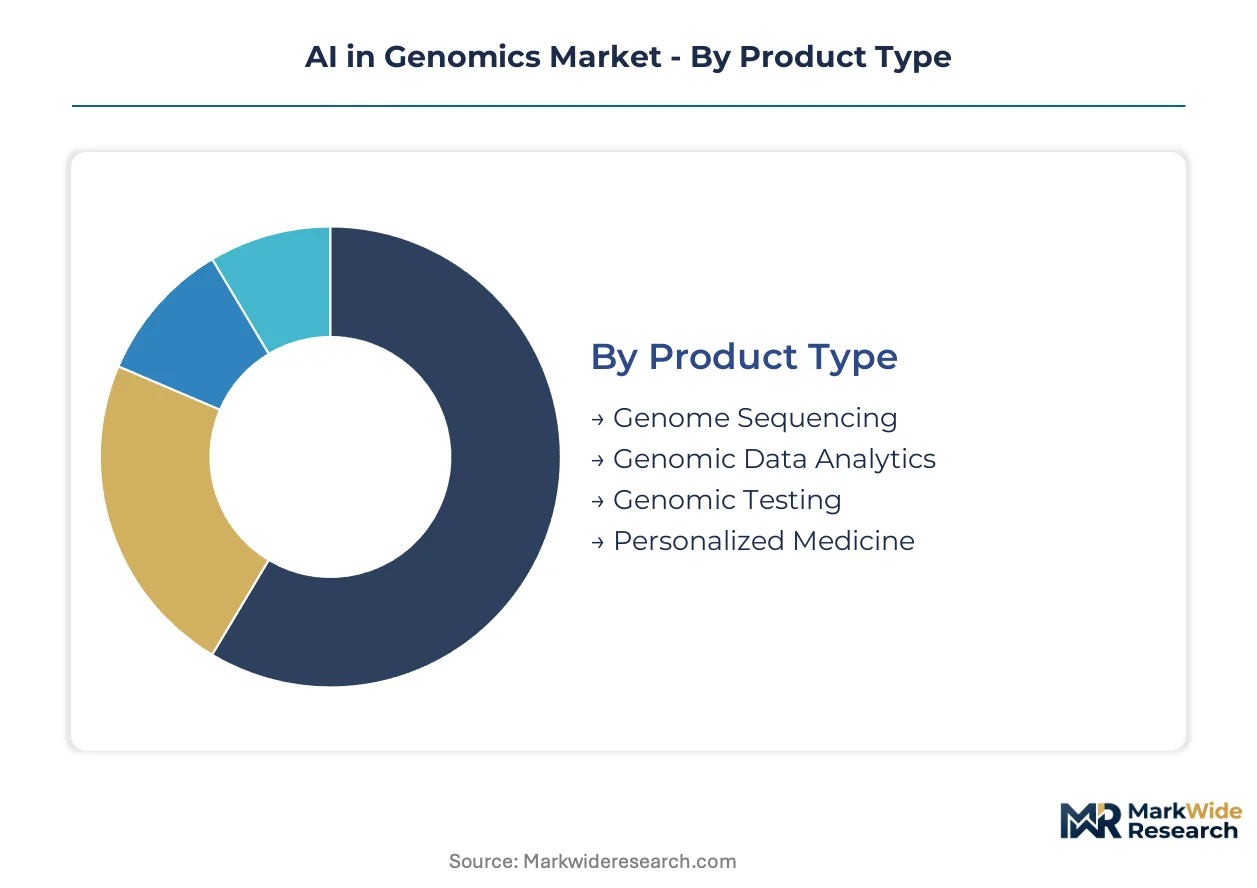
AI in genomics segments diverge sharply in regulatory burden and commercial maturity. Pharmaceutical procurement patterns now favor segments with pre-cleared FDA 510(k) or EU MDR pathways, compressing sales cycles for compliant categories while delaying revenue for novel modalities.
Product Type:
Certification requirements stratify sharply: genome sequencing hardware faces FDA Class II device pathways and EU MDR conformity assessment, while software-only analytics modules navigate lighter 510(k) de novo routes or self-certification under EU AI Act lower-risk tiers.
- Genome Sequencing:Instrumentation generating raw nucleotide reads requires ISO 13485 quality systems and FDA premarket notification. Demand concentrates in NIH-funded US research institutions and German university hospitals upgrading from second-generation platforms.
- Genomic Data Analytics:Cloud-based variant interpretation platforms face lighter 510(k) burdens for research-use-only deployments but trigger FDA Class II scrutiny when marketed for diagnostic reporting. German and French hospital procurement committees prioritize vendors with notified body technical files already assembled.
- Genomic Testing:Laboratory-developed test frameworks in the US and IVDR transition compliance in Europe create divergent go-to-market economics.
- Personalized Medicine:Companion diagnostic co-development agreements with oncology pipelines drive adoption through FDA breakthrough device pathways.
Leading the category by volume: Genomic Data Analytics. Growing fastest: Personalized Medicine.
Technology:
Compute infrastructure costs and talent scarcity create tiered entry barriers across methodological approaches, with transformer architectures demanding NVIDIA GPU clusters that only well-capitalized pharmaceutical deployers can sustain.
- Machine Learning:Supervised classification algorithms for variant pathogenicity scoring dominate clinical translation, with random forest and gradient boosting ensembles deployed across US academic medical centers for hereditary cancer screening workflows.
- Natural Language Processing:Biomedical literature mining for gene-disease association extraction expands fastest as unstructured genomic knowledge accumulates in PubMed and proprietary biopharma document repositories.
- Data Mining:Association rule learning across population biobanks identifies polygenic risk scores without mechanistic interpretation.
- Neural Networks:Deep architectures for splice site prediction and regulatory element annotation require specialized training data curation that constrains deployment to well-resourced discovery groups.
Machine Learning commands installed base leadership. Natural Language Processing climbs fastest as pharmaceutical knowledge management budgets expand.
Application:
Revenue concentration aligns with biopharma R&D budget allocation, with therapeutic pipeline stages determining whether AI investment flows toward target identification, patient stratification, or mechanistic validation.
- Drug Discovery:Target deconvolution and lead optimization workflows absorb the largest investment pool, with Sanofi and Roche deploying foundation models across early discovery portfolios to compress timelines between sequence submission and druggable site prediction.
- Biomarker Identification:Companion diagnostic co-development agreements deepen margin profiles through royalty structures tied to therapeutic approvals, particularly in lung and colorectal oncology indications.
- Disease Prediction:Polygenic risk scoring for common conditions faces reimbursement uncertainty in US commercial insurance markets.
- Gene Editing:CRISPR guide RNA design algorithms require experimental validation that limits pure software revenue models.
Drug Discovery dominates current spending. Biomarker Identification gains share fastest through diagnostic-therapeutic bundling.
End User:
Procurement authority and data access privileges determine segment attractiveness, with pharmaceutical companies offering largest contract values but research institutions providing training data essential for algorithm development.
- Pharmaceutical Companies:Multinational manufacturers including Bristol Myers Squibb and AstraZeneca direct AI procurement toward target identification and patient stratification platforms, with annual contracts exceeding mid-size biotech total R&D budgets.
- Research Institutions:Broad Institute and European Molecular Biology Laboratory provide population-scale biobank access that enables model training, though indirect revenue through sponsored research agreements constrains commercial margins.
- Healthcare Providers:US academic medical centers pilot clinical decision support integration but face HIPAA compliance overhead for genomic data flows.
- Diagnostic Laboratories:Quest Diagnostics and Eurofins scale variant interpretation through automated pipelines, squeezing margins for boutique AI vendors.
Pharmaceutical Companies anchor revenue concentration. Research Institutions expand fastest through biobank partnership monetization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical procurement of AI-driven genomic platforms concentrates in the United States, where NIH-funded research institutions and venture-backed biotech clusters generate the densest deployment environment worldwide.
United States
FDA breakthrough device pathways accelerate companion diagnostic approvals for oncology pipelines, while HIPAA compliance frameworks constrain how patient genomic data flows into model training. The Greater Boston and San Francisco Bay Area biotech clusters host the highest density of AI-native genomic startups deploying foundation models for target identification.
Germany
University hospitals in Heidelberg and Berlin upgrade sequencing infrastructure to feed downstream AI analytics platforms. EU MDR conformity assessment requirements and the EU AI Act's risk classification framework extend commercialization timelines for diagnostic algorithms, favoring vendors with pre-established notified body relationships.
United Kingdom
The NHS Genomic Medicine Service generates population-scale datasets that enable training of polygenic risk models for common conditions. MHRA recognition of FDA approvals streamlines dual-market entry for US-based platform providers, concentrating algorithm development partnerships in London and Cambridge.
China
NMPA regulatory pathways for AI-enabled medical devices are tightening validation documentation for genomic diagnostic software. The Beijing-Tianjin-Hebei corridor anchors national sequencing capacity expansion, with BGI Genomics and related entities feeding training data into domestic foundation model development.
Japan
PMDA's regulatory sandbox for AI-enabled medical devices compresses conditional approval timelines for genomic classifiers versus standard 510(k) pathways. The Kanto region's academic medical centers pilot clinical decision support integration, though reimbursement uncertainty for predictive genomic testing limits commercial scale.
AI in Genomics Market Vendor Landscape
United States technology conglomerates anchor one tier through GPU-accelerated computing infrastructure and cloud-based analytics platforms; specialized genomic AI boutiques hold differentiated positions in therapeutic discovery workflows. Market structure tilts toward consolidation at the infrastructure layer while fragmenting across application-specific software modules. Three archetypes dominate: silicon providers supplying training compute, sequencing instrumentation manufacturers controlling data generation, and predictive biology specialists building proprietary target pipelines. Competitive moves center on strategic partnerships between hardware and software layers, plus portfolio diversification into multimodal foundation models integrating genomic, transcriptomic, and proteomic streams.
Within the specialized therapeutic discovery tier, Deep Genomics exemplifies the predictive splicing model approach that differentiates from generalist platform providers. NVIDIA Corporation anchors the infrastructure layer through GPU-accelerated computing architecture that dominates training workloads for large-scale genomic models. Illumina, Inc. occupies a position as the sequencing instrumentation incumbent whose proprietary data generation feeds downstream analytics ecosystems.
| Leading Market Players |
|---|
| NVIDIA Corporation |
| Microsoft Corporation |
| IBM |
| Illumina, Inc. |
| SOPHiA GENETICS |
| Deep Genomics |
| Fabric Genomics |
| Intel Corporation |
| Tempus |
| Others |
Supply Flow & Price Mechanics
Captive GPU infrastructure integration anchors both supply security and pricing power for genomic AI platform providers, with NVIDIA's CUDA ecosystem concentration forcing buyers into long-term compute commitments that lock in cost structures regardless of algorithm commoditization pressures downstream. This vertical control over training silicon cascades through SaaS pricing tiers, where foundation model access bundles hardware amortization into per-seat subscriptions that mid-size biotech firms cannot replicate through cloud spot markets alone.
Pricing Analysis
Volume concentrates in research-use-only SaaS tiers while margins accrue to diagnostic-grade algorithm licenses carrying FDA 510(k) clearance and EU MDR technical file documentation. Price differentiation separates ISO 13485-certified clinical decision support modules from exploratory analytics platforms lacking notified body validation. Cost compression in the mid-market tier intensifies as Illumina's sequencing instrumentation bundling squeezes standalone software vendors. Academic medical centers exhibit highest price sensitivity due to fixed NIH grant funding, while pharmaceutical discovery groups absorb premium pricing for multimodal foundation model access.
Supply Chain Analysis
Regional distribution centers for sequencing reagents cluster in the United States, Germany, and Singapore, with hub-and-spoke patterns radiating from Thermo Fisher's centralized manufacturing nodes to hospital core facilities. Raw material dependencies span fluorophore chemistries from Japanese specialty chemical suppliers, flow cell substrates from Taiwanese precision glass manufacturers, and CRISPR guide RNA synthesis capacity anchored in South Korea. Single-source vulnerability concentrates in TSMC's advanced node fabrication for training GPUs, where geopolitical export restrictions threaten model development continuity. Distribution runs through direct vendor relationships for pharmaceutical deployers and group purchasing organization contracts for hospital laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over training data biobanks and compute infrastructure determines sustainable margin capture, with upstream data access emerging as the decisive lever separating platform survivors from algorithm commoditization casualties.
For Market Incumbents: Deploy biobank exclusivity agreements as the primary defensive mechanism, locking multi-institutional data partnerships that starve emerging competitors of training scale. Pursue backward integration into sequencing instrumentation to capture data generation economics currently flowing to Illumina. Counter the threat from federated learning consortia by embedding proprietary variant ontologies that resist interoperability standardization. For New Entrants and Emerging Players: Rare disease diagnostic laboratories in Saudi Arabia and the UAE represent the most penetrable buyer archetype, lacking established biomarker frameworks and regulatory precedent that favor incumbents elsewhere. Target orphan indication pipelines through API-first variant interpretation modules that bypass lengthy hospital procurement cycles. Accelerate market entry via Japan's PMDA regulatory sandbox, where conditional approval timelines compress revenue realization versus FDA pathways. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by pharmaceutical manufacturers seeking captive AI capabilities for pipeline acceleration, with IPO viability contingent on demonstrated therapeutic milestone partnerships. Long-term viability favors platforms with proprietary target pipelines rather than generalist analytics tools facing margin erosion. Watch for inflection in companion diagnostic co-development agreement velocity as the signal distinguishing sustainable revenue models from service commoditization.| Strategic Initiative | Industry Significance |
|---|---|
| Biobank Data Partnership | Secures training data scale that federated learning competitors cannot replicate without HIPAA-GDPR friction. |
| EU MDR Technical File Assembly | Accelerates German and French hospital procurement cycles by twelve to eighteen months versus de novo certification. |
| Companion Diagnostic Co-Development | Deepens margin profile through royalty structures tied to FDA breakthrough device oncology approvals. |
| GPU Infrastructure Backward Integration | Reduces NVIDIA CUDA ecosystem dependency that currently concentrates training cost vulnerability. |
| Japan PMDA Sandbox Entry | Compresses conditional approval timelines for genomic classifiers versus standard FDA 510(k) pathways. |
Methodological Framework
Multi-period observation of regulatory submission timelines, biopharma R&D procurement patterns, and sequencing infrastructure deployment rates anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads at genomic diagnostic firms, hospital procurement managers, and payer access specialists. Secondary validation drew from FDA 510(k) filings, EMA MDR technical file databases, ClinicalTrials.gov genomic biomarker entries, and NIH grant award records. Bottom-up segment sizing triangulated against top-down pharmaceutical IT budget allocations across the analysis window.
Input-output matrix framing linked training compute cost curves, biobank data licensing terms, and regulatory approval probability weights to segment-specific revenue realization models. Segmentation dimensions spanned product type, technology methodology, application workflow, and end-user procurement authority, with regional regulatory cluster variations captured separately. CAGRs were derived from fitted growth curves calibrated to historical deployment velocity in comparable clinical decision support categories. Industry-specific forecast inputs included CRISPR validation throughput constraints and EU AI Act risk classification transition schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolitical export controls on advanced semiconductors and divergent FDA-EU MDR regulatory harmonization progress. Outputs reflect documented assumptions around biopharma R&D budget stability and cloud compute pricing trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Genotyping Market
Genomics
Prenatal Genetic Testing Market
Genomics
Antisense Oligonucleotides Market
Genomics
Targeted DNA RNA Sequencing Market
Genomics
Genome Sequencing Market
Genomics
Oligonucleotide Pool Market
Genomics
Next Generation Sequencing Market
Genomics
Genetic Leukemia Detection Testing Market
Genomics
NGS Automation Market
Genomics
Pre-Pregnancy Genetic Testing Market
Genomics
Retail Genomics Market
Genomics
Global Microbiome Sequencing Services Market
Genomics
Global Artificial Intelligence in Genomics Market
Genomics
Hereditary Testing Market
Genomics
Global Lab Automation in Genomics Market
Genomics
North America Whole Exome Sequencing Market