
 Membrane Protein Characterization Service Market | 2026-2036
Membrane Protein Characterization Service Market Size, Share, and Industry Trends Forecast 2026-2036
Membrane Protein Characterization Service Market Outlook
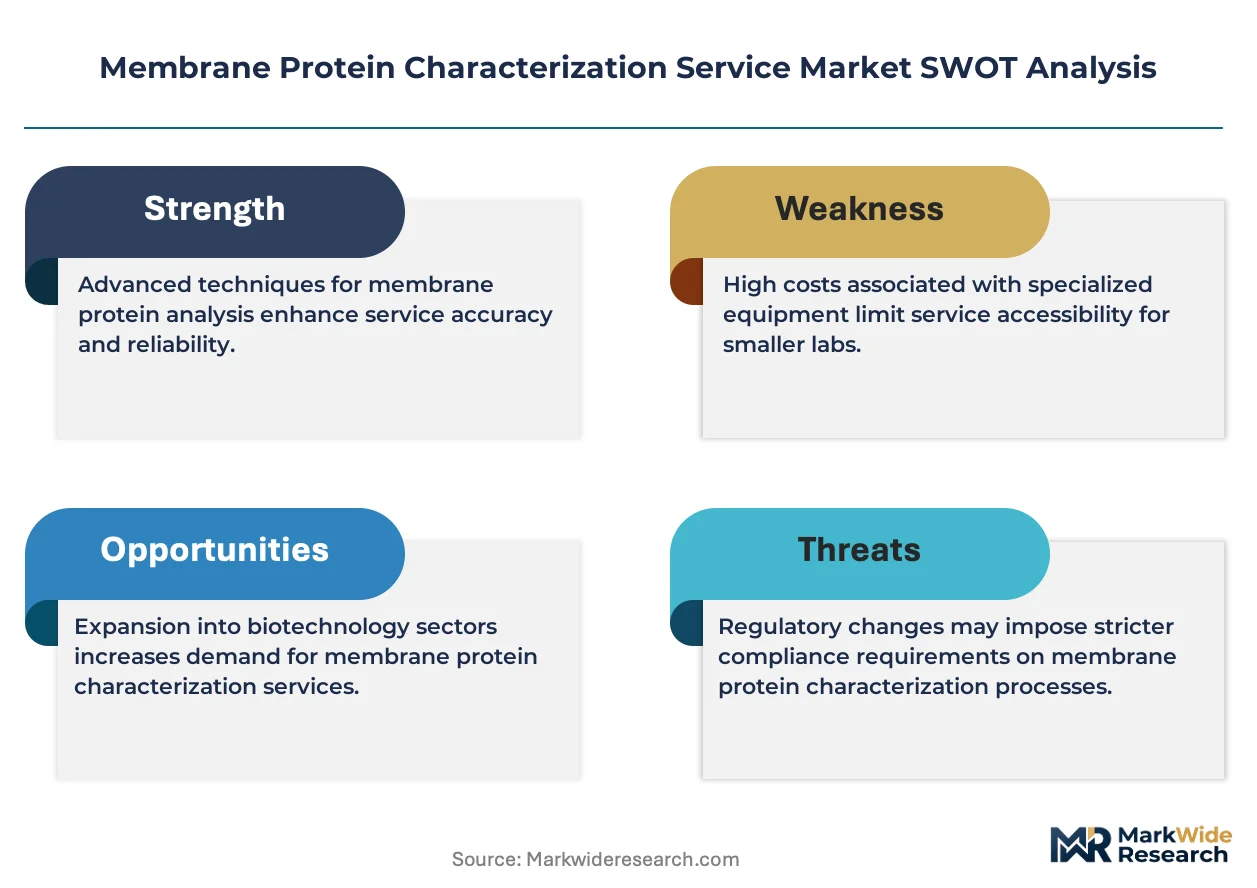
Custom assay development and data analytics bundling is repositioning how membrane protein characterization services are monetized, shifting vendors from transactional project fees toward recurring research partnerships. Thermo Fisher Scientific leverages its integrated mass spectrometry and cryo-EM workflow portfolio to anchor large pharmaceutical accounts. Charles River Laboratories differentiates through its captive biology expertise and GLP-compliant structural biology infrastructure. Sartorius AG competes with bioreactor-linked expression systems that streamline upstream membrane protein production for downstream characterization.
Membrane protein characterization services encompass analytical workflows that determine the three-dimensional architecture, ligand-binding kinetics, thermal stability, and functional activity of integral and peripheral membrane proteins, typically requiring detergent solubilization or lipid nanodisc reconstitution prior to biophysical interrogation. These services enable structure-based drug design against historically intractable targets such as G-protein coupled receptors and ion channels. Cryo-electron microscopy commands premium pricing as the dominant modality for near-atomic resolution of conformationally flexible targets, while mass spectrometry sustains broader adoption for high-throughput screening and post-translational modification mapping. Functional assays attract growing investment from biotechnology firms seeking pharmacological validation prior to lead optimization.
FDA guidance on quality attributes for complex biologics and EMA reflection papers on structure-activity relationships shape validation requirements for contract characterization providers. ISO 17025 accreditation and OECD principles of Good Laboratory Practice govern cross-border data acceptance for regulatory submissions. Stakeholders must monitor how AI-driven structure prediction tools alter the economics of experimental determination versus computational inference in target validation pipelines.
Market Dynamics
The transition from cryo-electron microscopy to AI-augmented structure prediction pipelines is compressing project timelines and redefining value capture for contract research organizations serving biopharma discovery programs.
Growth Catalysts
- Antibody-Drug Conjugate Pipelines:Pharmaceutical manufacturers in the United States and Germany are expanding ADC development against membrane-bound tumor antigens, requiring extensive target validation and epitope mapping services.
- ISO 17025 Accreditation Mandates:Regulatory submissions for complex biologics now demand certified analytical methods, pushing sponsors toward qualified contract characterization providers with established quality management systems.
- GPCR Structural Biology:Cryo-EM resolution breakthroughs for conformationally dynamic receptors are unlocking previously intractable targets for structure-based drug design across neuroscience and metabolic disease portfolios.
Market Restraints
- Helium Supply Volatility:Cryo-EM operations depend on liquid helium for superconducting magnets, with price shocks and allocation constraints disrupting service scheduling for European and Japanese facilities.
- Specialized Talent Scarcity:The intersection of membrane biochemistry, biophysics, and computational structural biology creates a shallow labor pool, inflating personnel costs for service providers in Boston and Basel clusters.
- AI Structure Prediction Substitution:AlphaFold-derived models are displacing experimental determination for certain target classes, eroding demand for routine X-ray crystallography and NMR spectroscopy services.
Strategic Opportunities
- India Biopharma Manufacturing:Contract development and manufacturing organizations in Hyderabad and Bangalore are building captive structural biology capabilities, creating demand for technology transfer and training partnerships.
- Functional Assay Integration:Bioreactor-linked expression systems combined with real-time pharmacology readouts enable end-to-end membrane protein production and characterization workflows for cell therapy developers.
- Japan Regenerative Medicine:PMDA accelerated pathways for induced pluripotent stem cell therapies are expanding demand for membrane protein target validation in immunogenicity assessment protocols.
Industry Challenges
- Cryo-EM Facility Capital Intensity:Microscope acquisition, maintenance, and cryogen infrastructure demand $10-15 million upfront investment, constraining mid-tier service provider expansion.
- Cross-Platform Data Harmonization:Integrating cryo-EM density maps, hydrogen-deuterium exchange mass spectrometry, and molecular dynamics simulations requires interoperable file formats and metadata standards that remain immature.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Membrane Protein Characterization Service Market |
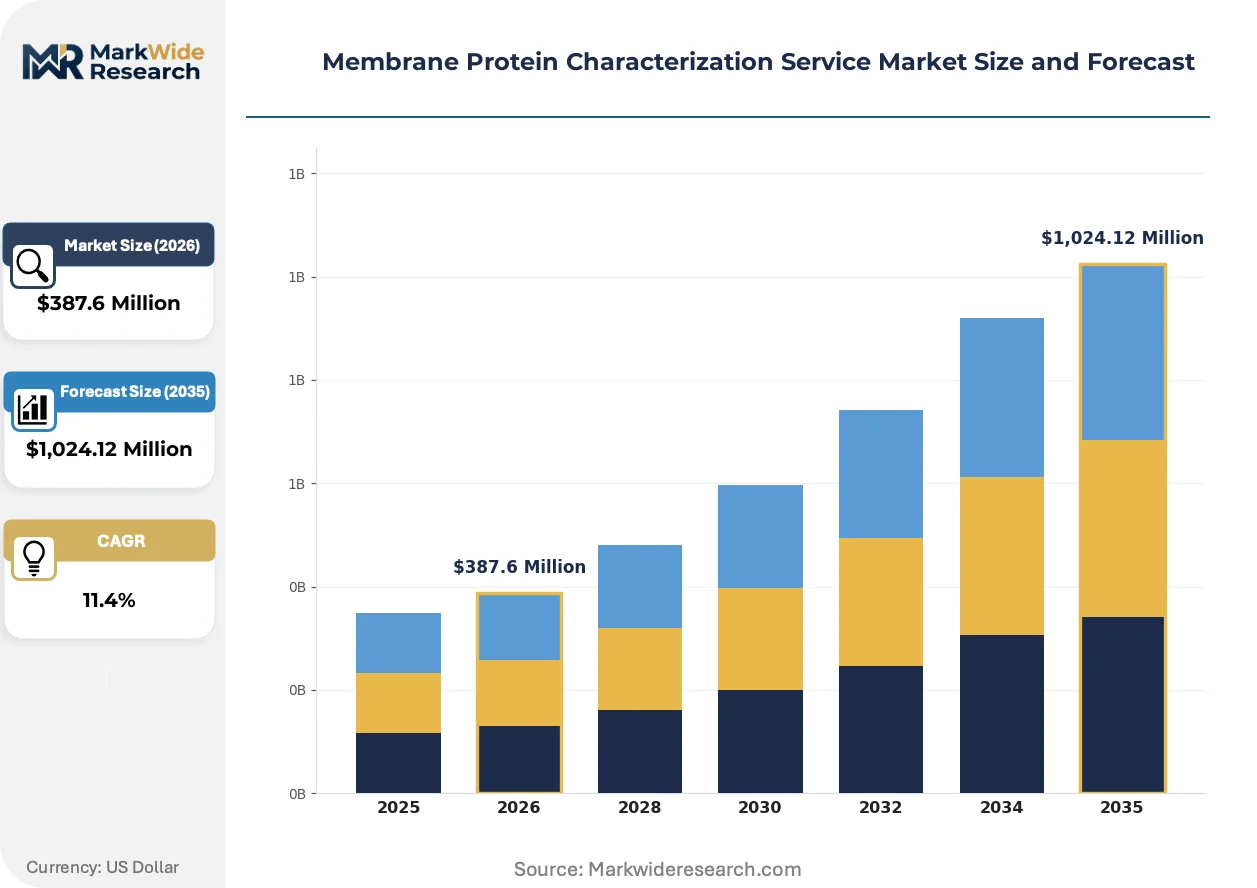
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Conformational Analysis, Binding Studies, Stability Testing, Functional Assays Technology: Mass Spectrometry, NMR Spectroscopy, Cryo-EM, X-ray Crystallography End User: Pharmaceutical Companies, Academic Institutions, Research Organizations, Biotechnology Firms Delivery Mode: On-site Services, Remote Analysis, Consultation Services, Online Reporting |
| Companies Covered | Bruker Corporation, Sartorius AG, Thermo Fisher Scientific Inc., Parker Hannifin Corp., Merck and Co. Inc., Agilent Technologies Inc., Charles River Laboratories Inc., Pentair Plc, Waters Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Membrane Protein Characterization Service Market Strategic Shifts
Service providers are repositioning around integrated workflows that bundle expression, purification, and multi-modal characterization, compressing sponsor decision cycles and anchoring long-term research partnerships.
Cloud-based cryo-EM data processing pipelines are decentralizing computational infrastructure requirements for membrane protein structure determination. Mid-sized biotechnology firms without captive high-performance computing clusters are adopting these platforms to accelerate model building and refinement. The shift is compressing barriers to entry for structural biology programs and redistributing value toward data interpretation and biological insight generation.
EMA reflection papers on quality attributes for complex biologics are tightening documentation requirements for higher-order structure characterization. Contract providers must now demonstrate method robustness across multiple operators and instrument platforms to support regulatory submissions. European sponsors are responding by consolidating procurement with accredited laboratories possessing established validation packages.
Biopharma purchasing departments are unbundling project-based contracts into modular statement-of-work arrangements with milestone-based payments. Large pharmaceutical accounts in New Jersey and Massachusetts are piloting preferred provider agreements that lock in capacity allocation and standardized data deliverables. The model is displacing transactional fee-for-service relationships in North American antibody discovery programs.
Membrane Protein Characterization Service Market Segmentation
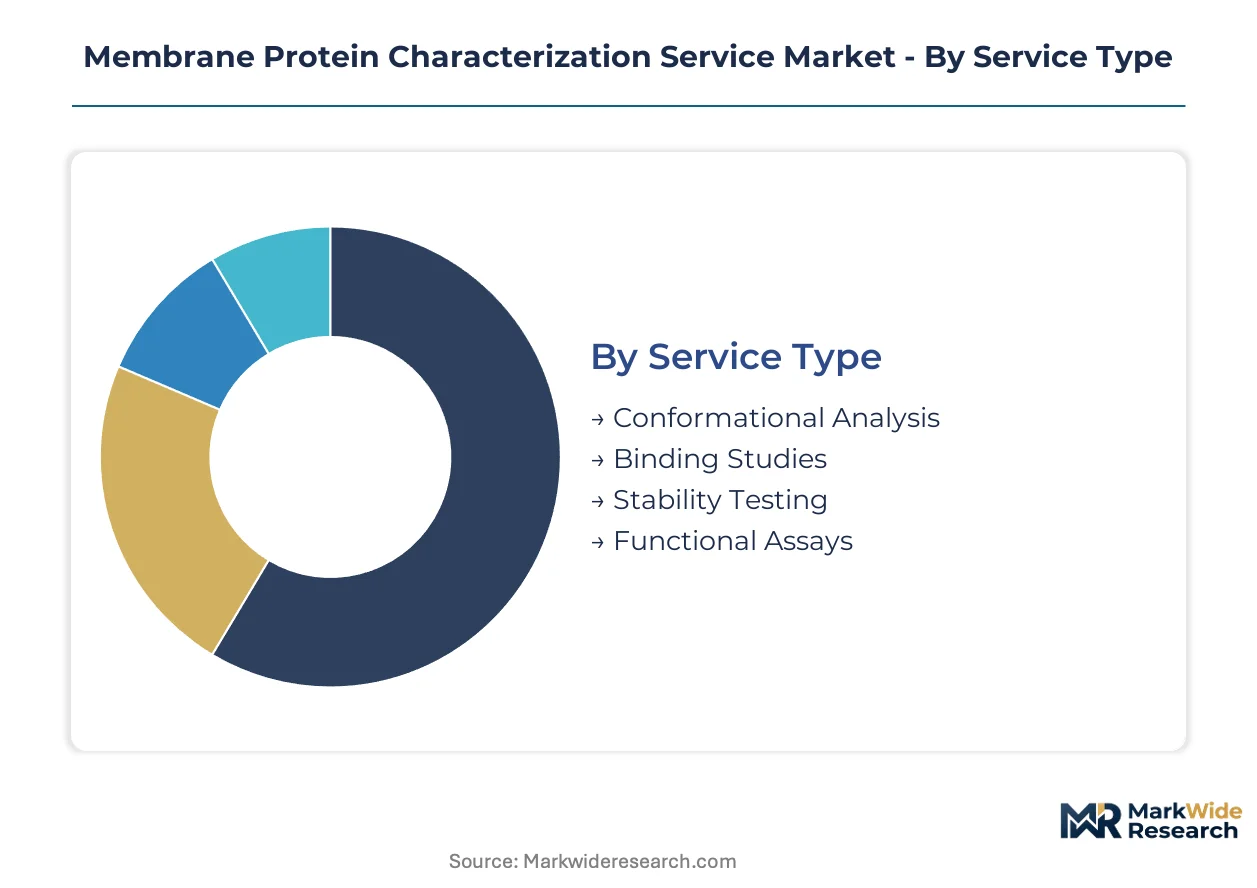
Membrane protein characterization services fragment across four distinct dimensions that shape procurement patterns and vendor positioning. Service type and technology selections drive pricing tiers, while end-user category and delivery mode determine contract structure and relationship longevity.
Service Type:
Volume deployment concentrates in standardized analytical workflows, while premium capture attaches to complex multi-method integration and regulatory-grade documentation packages.
- Conformational Analysis:Structural determination workflows map three-dimensional architecture of integral membrane proteins through hydrogen-deuterium exchange and crosslinking mass spectrometry. Demand clusters with pharmaceutical companies in the United States developing antibody-drug conjugates against GPCR targets, where epitope mapping requires sub-angstrom precision for regulatory submission packages.
- Binding Studies:Kinetic and thermodynamic characterization of ligand-receptor interactions using surface plasmon resonance and microscale thermophoresis. Biotechnology firms in Germany are expanding procurement for lead optimization campaigns, driven by ADC pipeline expansion against membrane-bound tumor antigens.
- Stability Testing:Thermal and chemical denaturation profiling to assess formulation compatibility and shelf-life predictions.
- Functional Assays:Cell-based and reconstituted system validation of membrane protein activity for pharmacological proof-of-concept.
Mature deployment sits with Conformational Analysis. Newer deployment is concentrated in Functional Assays.
Technology:
Capital intensity and resolution capabilities create a three-tier supplier landscape, with cryo-EM infrastructure requirements filtering market participation.
- Cryo-EM:Single-particle electron microscopy delivers near-atomic resolution for conformationally flexible targets without crystallization constraints. Academic consortia in Japan are prioritizing facility investments, supported by PMDA guidance on complex biologics characterization that elevates structural data requirements for regenerative medicine submissions.
- Mass Spectrometry:Proteomic and native MS workflows enable high-throughput screening and post-translational modification mapping with lower capital barriers. Research organizations across multiple geographies sustain broad adoption for routine quality attribute monitoring.
- NMR Spectroscopy:Solution-state and solid-state nuclear magnetic resonance for dynamic regions and membrane-mimetic environments.
- X-ray Crystallography:Diffraction-based structure determination for well-diffracting membrane protein crystals.
Platform consolidation favors Mass Spectrometry for throughput. Cryo-EM commands the steepest expansion trajectory as resolution breakthroughs unlock previously intractable targets.
End User:
Contract value and duration diverge sharply between commercial sponsors seeking regulatory-grade packages and academic investigators prioritizing method access over documentation.
- Pharmaceutical Companies:Large-scale outsourcing of structural biology workflows with stringent quality management system requirements and audit protocols. Sponsors in New Jersey and Massachusetts are piloting preferred provider agreements that lock multi-year capacity allocations and standardized data deliverables.
- Biotechnology Firms:Agile development programs requiring rapid turnaround for investor milestones and partnership due diligence. Cell therapy developers in Boston clusters are driving demand for integrated expression-to-characterization workflows.
- Academic Institutions:Grant-funded access to specialized instrumentation and expertise without capital investment.
- Research Organizations:Government and non-profit laboratories supporting target validation for public health priorities.
Revenue concentration aligns with Pharmaceutical Companies. Fastest share gains are emerging from Biotechnology Firms.
Delivery Mode:
Physical sample logistics versus data transmission economics reshape margin structures and geographic service radius.
- On-site Services:Client personnel embedded within provider facilities for proprietary method development and technology transfer. CDMOs in Hyderabad are building captive structural biology capabilities through training partnerships with established European providers.
- Remote Analysis:Cloud-based data processing pipelines decentralizing computational infrastructure requirements for mid-sized sponsors without captive high-performance computing clusters.
- Consultation Services:Advisory engagement for experimental design and regulatory strategy.
- Online Reporting:Digital delivery of analytical results with interactive data visualization.
Relationship stickiness is strongest with On-site Services. Remote Analysis is climbing the fastest as cloud infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Service consumption concentrates in established biopharma clusters while production capacity expands through technology transfer partnerships in emerging manufacturing hubs. The United States and Germany anchor procurement volume for regulatory-grade characterization packages. Japan and India represent the fastest capacity buildout through academic consortia and CDMO infrastructure investments.
United States
FDA guidance on quality attributes for complex biologics drives demand for ISO 17025-accredited structural biology workflows. Large pharmaceutical sponsors in New Jersey and Massachusetts pilot preferred provider agreements locking multi-year cryo-EM capacity allocations. Greater Boston anchors the densest concentration of biotechnology firms seeking integrated expression-to-characterization services for cell therapy programs.
Germany
EMA reflection papers on structure-activity relationships tighten documentation requirements for higher-order structure characterization. Heidelberg and Munich academic consortia coordinate facility investments in single-particle electron microscopy infrastructure. Frankfurt-Rhine-Main pharmaceutical clusters expand ADC pipeline development against membrane-bound tumor antigens requiring extensive epitope mapping.
Japan
PMDA accelerated pathways for induced pluripotent stem cell therapies expand demand for membrane protein target validation in immunogenicity protocols. Tokyo and Osaka biopharma clusters prioritize cryo-EM facility investments supported by national regenerative medicine initiatives. Kansai region academic consortia anchor public-private partnerships for GPCR structural biology programs.
India
CDSCO regulatory harmonization with ICH guidelines elevates structural data requirements for biosimilar submissions. Hyderabad and Bangalore contract development organizations build captive structural biology capabilities through European technology transfer partnerships. Karnataka biopharma parks attract investment in bioreactor-linked expression systems for upstream membrane protein production.
United Kingdom
Medicines and Healthcare products Regulatory Agency alignment with EMA quality standards sustains demand for GLP-compliant characterization services. Oxford and Cambridge life science clusters maintain strong procurement for hydrogen-deuterium exchange mass spectrometry in antibody discovery. London pharmaceutical headquarters consolidate outsourcing with accredited providers possessing established validation packages.
Membrane Protein Characterization Service Market Competitive Environment
Top-tier vendors anchor integrated workflow portfolios spanning expression systems through multi-modal analytics, while mid-tier specialists compete on turnaround velocity and technology-specific expertise. The vendor base stratifies across three tiers: diversified life science conglomerates with captive instrumentation platforms, contract research organizations with GLP-compliant infrastructure, and boutique structural biology shops with cryo-EM specialization. Dominant competitive moves include strategic partnerships for cloud-based data processing access and capacity reservation agreements locking sponsor allocation.
Within the diversified instrumentation tier, Thermo Fisher Scientific Inc. and Bruker Corporation exemplify platform-anchored competitive positioning. Agilent Technologies Inc. occupies a complementary position in mass spectrometry-centric analytical workflows. Charles River Laboratories Inc. and Sartorius AG represent the contract research organization archetype with integrated biology infrastructure. These five entities collectively illustrate how vendor positioning diverges across instrumentation ownership versus service delivery models.
| Leading Market Players |
|---|
| Bruker Corporation |
| Sartorius AG |
| Thermo Fisher Scientific Inc. |
| Parker Hannifin Corp. |
| Merck and Co. Inc. |
| Agilent Technologies Inc. |
| Charles River Laboratories Inc. |
| Pentair Plc |
| Waters Corporation |
| Others |
Value Chain & Pricing Dynamics
ISO 17025 accreditation tiers bifurcate service pricing into premium-validated and standard-research brackets, with certified workflows commanding substantial markups that reflect both specialized labor costs and helium-intensive cryo-EM infrastructure. This certification ladder concentrates supply chain leverage among established providers in Boston and Basel, while price-sensitive academic buyers gravitate toward shared-facility access models that redistribute capital burden across consortia.
Pricing Analysis
Margin tightening in cryo-EM services reflects helium supply volatility and superconducting magnet maintenance escalations that compress returns on ten-million-dollar instrument deployments. Project-based contracts with milestone-based payments dominate pharmaceutical procurement, while biotechnology firms negotiate preferred provider agreements locking multi-year capacity allocations. Price differentiation rests on GLP compliance grade and ISO 17025 certification status, with regulatory-grade packages capturing substantial premiums over research-use workflows. Academic institutions exhibit highest price sensitivity, driving demand for cloud-based data processing subscriptions that displace capital-intensive captive infrastructure.
Supply Chain Analysis
Regional distribution centers for liquid helium anchor cryo-EM operations in the United States, Germany, and Japan, with hub-and-spoke patterns radiating from academic consortia to satellite biotechnology clusters. Equipment manufacturing concentrates in the Netherlands and Japan for electron microscope components, while reagent supply draws from specialized detergent and lipid nanodisc producers in Switzerland and the United States. Single-source vulnerability in helium refining exposes European facilities to allocation disruptions from Qatar and Algeria supply concentration. Distribution runs through on-site service embedding and remote cloud-based data transmission, with biopharma sponsors consolidating procurement through accredited laboratory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane protein characterization capacity remains structurally constrained by cryo-EM facility capital intensity, with ten-to-fifteen-million-dollar upfront investments and helium infrastructure requirements propping premium pricing for qualified providers.
For Market Incumbents: Anticipate displacement pressure from AlphaFold-derived structure prediction tools by deepening captive biology expertise and GLP-compliant infrastructure that AI-augmented pipelines cannot replicate for regulatory submissions. Lock multi-year preferred provider agreements with large pharmaceutical sponsors in New Jersey and Massachusetts before biotechnology firms consolidate procurement. Prioritize certification investment in ISO 17025 and OECD GLP standards that emerging entrants cannot rapidly duplicate. For New Entrants and Emerging Players: Mid-sized biotechnology firms in Greater Boston represent the most penetrable buyer archetype, with unmet demand for integrated expression-to-characterization workflows and rapid turnaround for investor milestones. CDMOs in Hyderabad and Bangalore offer white-space entry through technology transfer partnerships that build captive structural biology capabilities for biosimilar developers. Pursue cloud-based cryo-EM data processing platforms as a service-led go-to-market angle that sidesteps instrument capital barriers. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified life science conglomerates seeking integrated workflow portfolios, with platform-anchored positioning commanding valuation premiums over pure-service models. Target contract research organizations possessing established GLP infrastructure and validated method packages that reduce regulatory risk for acquirers. Watch helium supply stabilization and AI structure prediction accuracy benchmarks as inflection indicators that could compress experimental determination demand or extend addressable target classes respectively.| Strategic Initiative | Industry Significance |
|---|---|
| Cryo-EM Facility Capacity Expansion | Locks multi-year pharmaceutical sponsor allocations in Boston and Basel clusters. |
| ISO 17025 Accreditation Investment | Enables regulatory submission support for complex biologics under FDA and EMA guidance. |
| Cloud-Based Data Processing Platform | Decentralizes computational infrastructure for mid-sized biotechnology firms without captive HPC clusters. |
| Bioreactor-Linked Expression System Integration | Streamlines upstream membrane protein production for downstream characterization workflows. |
| India Technology Transfer Partnership | Builds captive structural biology capabilities in Hyderabad CDMOs for biosimilar developers. |
Study Parameters
Independent corroboration across drug development executives, regulatory affairs leads at contract characterization providers, academic principal investigators, and biopharma procurement officers underwrites the qualitative findings in this study. Primary interviews with membrane biochemistry specialists and structural biology facility directors combined with secondary validation from FDA guidance documents, EMA reflection papers, PMDA regenerative medicine pathways, and ISO 17025 accreditation databases. Bottom-up triangulation across service provider revenue segmentation and top-down cross-checks against biopharma R&D expenditure patterns anchored the market sizing framework.
Comparable-period anchoring to historical cryo-EM adoption curves and ADC pipeline expansion rates established the forecast baseline across the projection horizon. Segmentation modeling incorporated service type, technology modality, end-user category, and delivery mode dimensions alongside regional regulatory cluster differentiation. CAGRs derived from instrument installation trajectories, helium supply elasticity, and AI structure prediction substitution rates. Industry-specific inputs included GPCR structural biology publication velocity and regenerative medicine immunogenicity protocol expansion under PMDA accelerated pathways.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to helium market liberalization, AlphaFold accuracy breakthroughs for membrane protein classes, and CDSCO regulatory harmonization pace in India. Outputs reflect documented assumptions around cryo-EM resolution advancement timelines and biotechnology firm consolidation patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Research Antibodies Market
Biotechnology Services
Cell Characterization Assays Kits Market
Biotechnology Services
Transport Protein Assays Kits Market
Biotechnology Services
Global Custom Antibody Market
Biotechnology Services
Global Vero Cell Media Market
Biotechnology Services
Biobank Market
Biotechnology Services
Feruloyl Esterase Market
Biotechnology Services
TSG6 Antibody Market
Biotechnology Services
Global Protein Purification and Isolation Market
Biotechnology Services
Spain Specialty Enzymes Market
Biotechnology Services
Stable Cell Line Development Market
Biotechnology Services
Antibody Drug Conjugates Contract Manufacturing Market
Biotechnology Services
Marine Polysaccharides Fucoidan Alginate Market
Biotechnology Services
Isothermal Nucleic Acid Amplification Technology (INAAT) Market
Biotechnology Services
Aptamers Market
Biotechnology Services
Global Protein Binding Assay Market