
 Global Drug Discovery Market | 2026-2036
Global Drug Discovery Market Size, Share, and Industry Trends Forecast 2026-2036
Global Drug Discovery Market Analysis
Market Context
Artificial intelligence integration across target identification and lead optimization is fragmenting traditional drug discovery workflows into modular, computationally intensive stages. Pfizer Inc. leverages its internal AI platforms to compress early-stage timelines, while Merck & Co. Inc. sustains competitive position through deep proteomics expertise and strategic external partnerships. Eli Lilly and Company anchors its pipeline in antibody engineering specialization, occupying distinct therapeutic territory against broader-platform rivals.
Technical Definition and Segment Structure
Drug discovery encompasses the systematic identification, validation, and optimization of molecular candidates with therapeutic activity against defined biological targets, employing techniques ranging from high-throughput biochemical assays to structure-based computational design. The process serves the pharmaceutical industry's need to replenish pipelines with novel mechanisms of action amid generic erosion and rising clinical failure costs. Artificial Intelligence segments command premium valuation multiples as predictive modeling displaces brute-force screening, while Services categories expand fastest as pharmaceutical companies outsource specialized capabilities to contract research organizations. Reagents maintain stable margin pools due to recurring consumable demand, though Instruments face elongated replacement cycles in capital-constrained research environments.
Regulatory Environment and Outlook
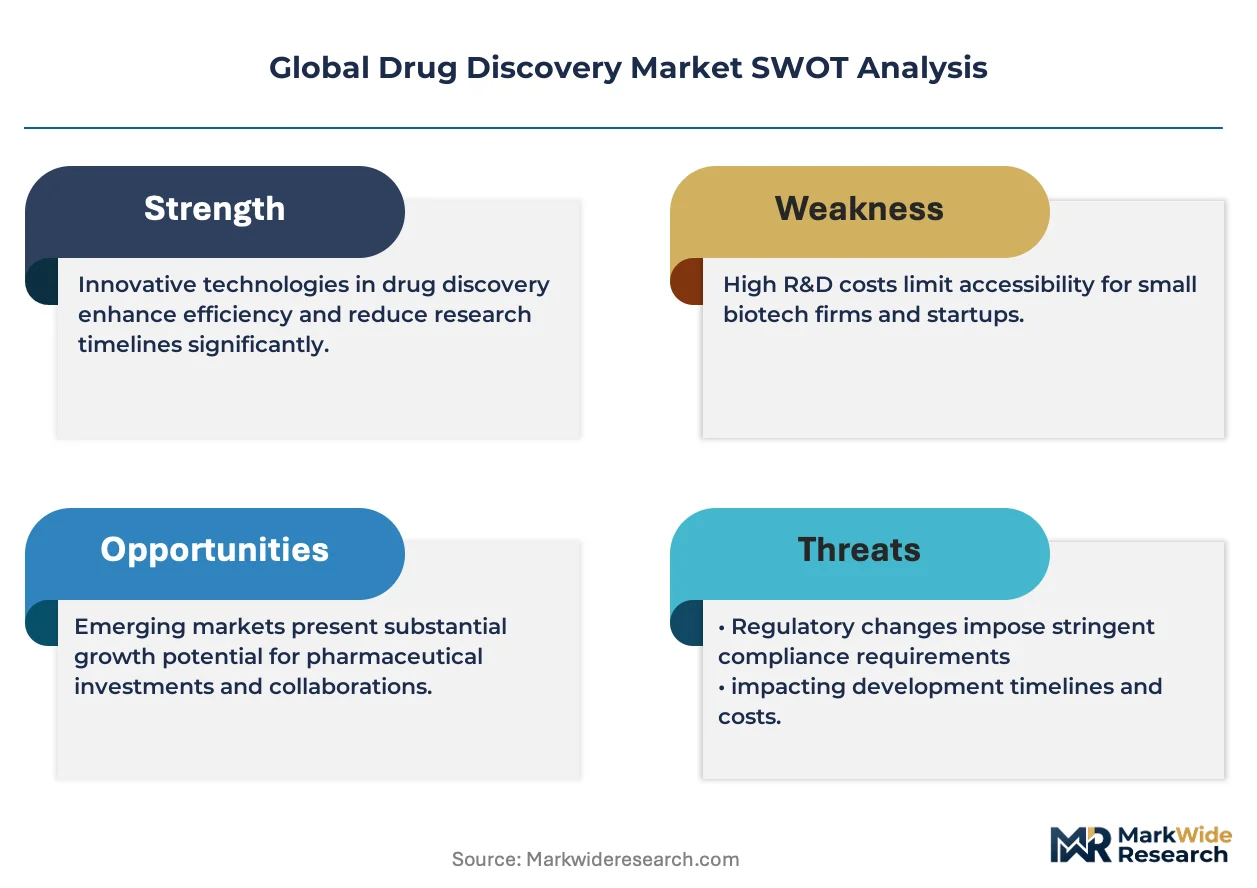
The FDA's breakthrough therapy designation and the EMA's PRIME scheme compress development timelines for qualifying candidates, directly incentivizing investment in platform technologies that accelerate proof-of-concept. China's NMPA reform trajectory and Japan's PMDA Sakigake designation system are converging toward faster, data-driven approval frameworks that reward predictive biomarker strategies. Stakeholders must monitor how divergent data localization requirements under GDPR, China's cybersecurity law, and FDA 21 CFR Part 11 reshape cross-border computational collaboration architectures.
Market Dynamics
Generative AI platforms are compressing target identification timelines from years to months, forcing pharmaceutical companies to restructure R&D organizations around computational biology capabilities rather than traditional medicinal chemistry hierarchies.
Growth Catalysts
- FDA Breakthrough Therapy Designation:The accelerated approval pathway incentivizes investment in platform technologies that compress proof-of-concept timelines for qualifying candidates.
- Antibody-drug conjugates:Oncology pipelines are expanding rapidly as bioconjugation technologies enable precision delivery of cytotoxic payloads to tumor-specific antigens.
- Cambridge-Boston corridor:Concentration of venture capital, academic research institutions, and contract research organizations creates self-reinforcing innovation density.
Market Restraints
- Clinical failure cost escalation:Phase III attrition rates impose capital intensity that restricts pipeline diversification to well-capitalized incumbents.
- Specialized talent scarcity:Computational biologists with dual expertise in machine learning and disease biology command compensation premiums that inflate fixed R&D costs.
- China's data localization mandates:Cross-border transfer restrictions under cybersecurity law fragment collaborative AI training datasets and complicate multi-site trials.
Strategic Opportunities
- India's contract research expansion:CDSCO regulatory harmonization and cost-competitive chemistry capabilities position the country for integrated discovery-to-IND service offerings.
- Gene editing convergence:CRISPR-based target validation combined with AI-driven compound generation creates closed-loop optimization workflows.
- Rare disease incentives:FDA orphan drug tax credits and EMA PRIME scheme eligibility reduce effective development costs for precision therapeutics.
Industry Challenges
- Legacy IT integration:Pharmaceutical data architectures built for small-molecule workflows require costly reconfiguration to accommodate biological data types and real-time AI inference.
- Reproducibility standards:Preclinical model validation protocols lag behind computational prediction speeds, creating bottlenecks at IND-enabling study stages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Drug Discovery Market |
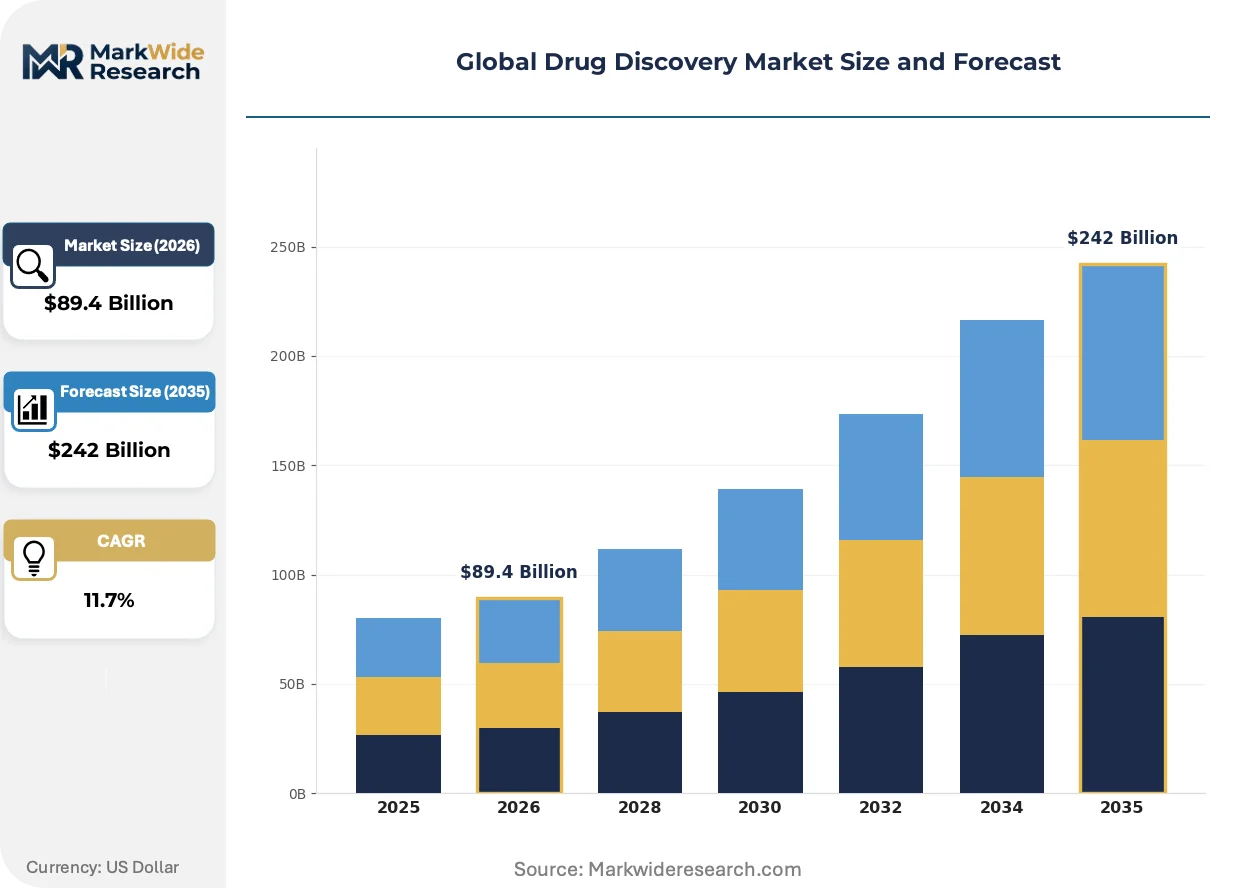
| Market Size in 2026 | $89.4 Billion |
| Market Size in 2035 | $242 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: High-Throughput Screening, Artificial Intelligence, Bioinformatics, Nanotechnology Product Type: Reagents, Instruments, Software, Services End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutions, Contract Research Organizations Application: Target Identification, Lead Optimization, Preclinical Development, Toxicity Testing |
| Companies Covered | Pfizer Inc., Merck & Co. Inc., GlaxoSmithKline PLC, AstraZeneca PLC, F. Hoffmann-La Roche Ltd, Eli Lilly and Company, Bayer AG, Agilent Technologies Inc., Abbott Laboratories Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Drug Discovery Market Emerging Trajectories
Computational methods are displacing physical screening infrastructure as the primary engine of molecular discovery, with cloud-based platforms enabling distributed research teams to access shared simulation resources.
AlphaFold-derived structural predictions are rendering obsolete traditional crystallography-dependent lead optimization cycles. Mid-sized biotechnology firms are adopting these tools fastest, bypassing capital-intensive protein production facilities. Structure-based drug design timelines compress from 18-24 months to 6-9 months for validated targets.
EMA's PRIME scheme is accelerating conditional marketing authorization pathways for medicines addressing unmet medical needs. Pharmaceutical sponsors are front-loading biomarker strategy investments to qualify for priority scientific advice. Oncology and gene therapy pipelines show highest qualification rates under this framework.
Biopharmaceutical procurement is consolidating vendor relationships around full-stack platform providers capable of spanning target identification through preclinical candidate nomination. Large pharmaceutical buyers are reducing contract research organization panels from 15-20 partners to 3-5 strategic alliances. This concentration is most pronounced in United States and Germany, where procurement functions have centralized under chief scientific officers.
Global Drug Discovery Market Segmentation
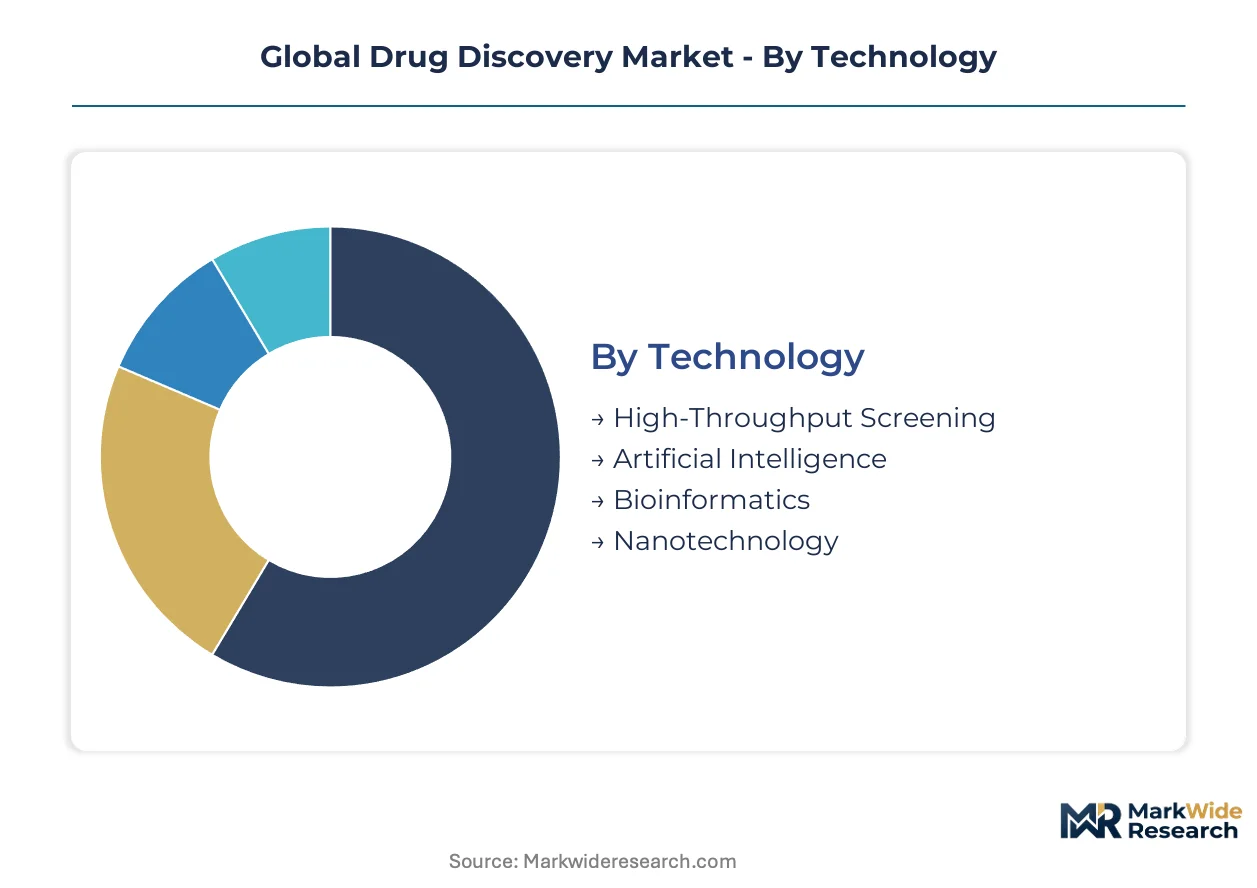
Segmentation in drug discovery reflects the modular restructuring of R&D workflows. Technology categories capture the shift from physical screening to computational prediction. Product and end-user dimensions reveal how value pools redistribute between in-house platforms and outsourced services.
Technology:
Technology segments span the full spectrum from brute-force biochemical testing to generative molecular design, with each approach commanding distinct capital intensity and timeline compression profiles.
- High-Throughput Screening:Automated robotic systems process millions of compounds against validated targets using microplate-based biochemical assays. Demand concentrates among established pharmaceutical companies in Germany and Switzerland seeking to amortize sunk infrastructure investments despite longer cycle times.
- Artificial Intelligence:Machine learning architectures predict target druggability, generate novel scaffolds, and optimize ADMET properties through neural network training on proprietary datasets. United States biopharmaceutical companies anchor demand, driven by FDA breakthrough therapy designation timelines that reward predictive accuracy.
- Bioinformatics:Computational pipelines integrate multi-omics data for target prioritization and patient stratification biomarker identification.
- Nanotechnology:Engineered delivery vehicles and formulation platforms enable tissue-specific targeting of previously undruggable mechanisms.
The dominant share belongs to High-Throughput Screening, while Artificial Intelligence is closing the gap fastest.
Product Type:
Product categories stratify by margin stability, with consumables generating recurring revenue against capital equipment's lumpy replacement cycles.
- Reagents:Biochemical assay components, cell culture media, and molecular biology consumables sustain stable margin pools through repeat purchase patterns. Contract research organizations in India and South Korea drive volume expansion as global pharmaceutical companies shift chemistry manufacturing to cost-competitive jurisdictions.
- Instruments:Mass spectrometry platforms, automated liquid handlers, and high-content imaging systems face elongated replacement timelines in capital-constrained academic environments. Demand clusters in the United States and Germany where national research funding agencies maintain equipment grant programs.
- Software:Molecular modeling suites, electronic laboratory notebooks, and AI inference platforms command subscription-based pricing models.
- Services:Integrated discovery-to-IND offerings span target validation, medicinal chemistry, and regulatory submission preparation.
Reagents capture the largest revenue base, though Services demonstrates the steepest expansion trajectory.
End User:
End-user segmentation maps the fragmentation of R&D execution across organizational boundaries and capital availability tiers.
- Pharmaceutical Companies:Integrated drug developers maintain internal discovery capabilities for core therapeutic franchises while outsourcing specialized modalities. United States and Japanese headquarters anchor procurement decisions, with FDA and PMDA regulatory familiarity shaping vendor selection criteria.
- Biotechnology Firms:Venture-backed developers concentrate resources on single-asset pipelines, relying heavily on contract research organizations for IND-enabling studies. Cambridge-Boston and San Francisco Bay Area clusters concentrate this segment's purchasing power.
- Research Institutions:Academic laboratories generate foundational target biology insights through publicly funded basic science.
- Contract Research Organizations:Outsourced service providers aggregate specialized capabilities across multiple sponsor relationships.
Pharmaceutical Companies retain the dominant procurement volume, while Contract Research Organizations are gaining share fastest through platform consolidation.
Application:
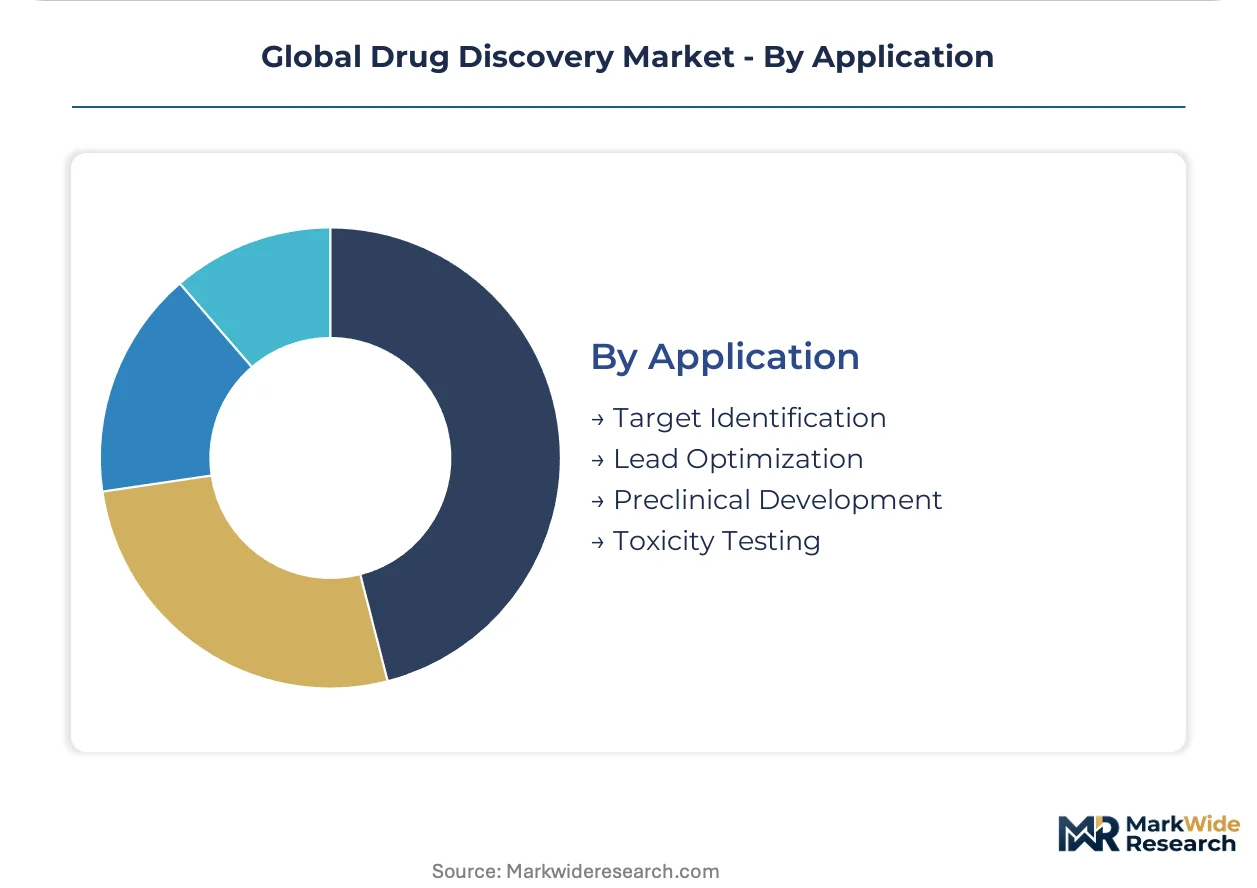
Application stages trace the progression from biological hypothesis to regulatory submission, with computational methods penetrating earliest phases most aggressively.
- Target Identification:Systematic validation of disease-modifying biological mechanisms through genetic association, CRISPR screening, and pathway analysis. Artificial intelligence platforms in the United States and United Kingdom compress traditional multi-year timelines to months, enabling rapid portfolio pivots.
- Lead Optimization:Iterative refinement of molecular properties including potency, selectivity, and metabolic stability. Structure-based design tools leveraging AlphaFold predictions displace crystallography-dependent workflows across European and North American laboratories.
- Preclinical Development:IND-enabling pharmacology and toxicology studies establish safety margins for human dosing.
- Toxicity Testing:Regulatory-mandated safety assessment identifies organ-specific liabilities and genotoxic risks.
Target Identification commands the largest technology investment, while Lead Optimization is expanding most quickly through structural biology convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports contract research services to United States and European pharmaceutical developers, while Switzerland ships high-value instrumentation to German and Japanese laboratories. Trade corridors concentrate specialized capabilities in cost-competitive jurisdictions and premium manufacturing hubs.
United States
FDA breakthrough therapy designation compresses development timelines for qualifying candidates, incentivizing platform technology investments. The 21 CFR Part 11 framework governs electronic records in computational drug discovery workflows. Boston and San Francisco anchor the largest research clusters, where venture capital fuels biotechnology firm formation.
Germany
EMA scientific advice procedures attract sponsors seeking parallel US-EU development strategies. Federal research funding through the Deutsche Forschungsgemeinschaft sustains academic drug discovery infrastructure. Heidelberg and Munich concentrate proteomics expertise alongside pharmaceutical headquarters in the Rhine-Ruhr corridor.
Switzerland
Swissmedic's accelerated assessment pathway rewards precision therapeutic development with condensed review timelines. Federal technology transfer programs bridge academic structural biology with commercial applications. Basel anchors pharmaceutical headquarters density, while Zurich sustains specialized contract manufacturing capabilities.
China
NMPA reform trajectories converge toward data-driven approval frameworks that reward predictive biomarker strategies. Cybersecurity law data localization mandates fragment collaborative AI training datasets across multi-site trials. Shanghai and Suzhou concentrate biologics manufacturing investments alongside Beijing's computational biology research institutes.
India
CDSCO regulatory harmonization positions the country for integrated discovery-to-IND service offerings. Production-linked incentive schemes for pharmaceuticals attract contract research organization capacity expansion. Hyderabad and Mumbai anchor chemistry manufacturing clusters serving North American and European sponsor demand.
Global Drug Discovery Market Vendor Landscape
On the supply side, the industry is consolidating around platform providers capable of spanning target identification through preclinical candidate nomination. Large pharmaceutical buyers reduce vendor panels from fifteen to twenty partners to three to five strategic alliances. Three archetypes dominate: integrated pharmaceutical developers with captive AI platforms, specialized biotechnology firms leveraging externalized discovery, and full-stack contract research organizations. Competitive moves center on strategic partnerships for capability gaps and geographic expansion into cost-competitive jurisdictions.
Among integrated pharmaceutical developers, Pfizer Inc., Merck & Co. Inc., and Eli Lilly and Company exemplify distinct strategic positioning within the competitive structure. Pfizer occupies a position emphasizing internal AI platform deployment for timeline compression. Merck & Co. represents proteomics-centric discovery specialization sustained through external partnership networks. Eli Lilly anchors antibody engineering focus, differentiating against broader-platform rivals through therapeutic modality concentration.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Merck & Co. Inc. |
| GlaxoSmithKline PLC |
| AstraZeneca PLC |
| F. Hoffmann-La Roche Ltd |
| Eli Lilly and Company |
| Bayer AG |
| Agilent Technologies Inc. |
| Abbott Laboratories Inc. |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on CRISPR reagent suppliers from China exposes contract research organizations to tariff-driven cost spikes that compress both standard-tier service margins and force geographic diversification of supply networks. This vulnerability widens pricing spreads between premium integrated platforms and economy-tier chemistry services while reshaping vendor consolidation strategies.
Pricing Analysis
The technology-generation pricing gap separates legacy high-throughput screening contracts from AI-augmented discovery subscriptions and emerging generative chemistry platforms. Project-based pricing dominates traditional medicinal chemistry outsourcing, while SaaS-tiered subscriptions capture AI platform value through annual licenses scaled to molecule throughput. Price differentiation rests on computational prediction accuracy and biomarker integration depth. Pricing pressure intensifies in standard-tier chemistry services as Indian contract research organizations expand capacity. Biotechnology firms show highest price sensitivity due to single-asset capital constraints, while integrated pharmaceutical developers prioritize timeline compression over unit cost.
Supply Chain Analysis
Extended payment terms from United States pharmaceutical sponsors now stretch to ninety days for contract research organizations, compressing working capital and favoring larger vendors with supply-chain finance facilities. Reagent manufacturing concentrates in China, India, and Germany, with oligonucleotide synthesis drawing from specialized chemical feedstock suppliers in Switzerland and South Korea. Supply chain risk centers on single-source dependency for gene editing enzymes amid export control tightening. Distribution runs through direct procurement teams at pharmaceutical headquarters rather than distributor intermediaries, with vendor panels consolidating around three to five strategic alliances.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits at a cyclical recovery phase driven by FDA breakthrough therapy designation volume returning to pre-correction levels, creating favorable conditions for platform technology deployment.
For Market Incumbents: Insulate core discovery franchises by deepening captive AI platform capabilities and securing exclusive access to AlphaFold-derived structural datasets before mid-tier competitors license equivalent tools. Consolidate vendor relationships from fifteen-plus contract research organizations to three strategic alliances, locking in capacity at Indian chemistry hubs before cost-competitive entrants capture share. Prioritize regulatory compliance infrastructure for 21 CFR Part 11 data integrity as FDA inspection intensity rises. For New Entrants and Emerging Players: Geographic underpenetration in Japan's PMDA Sakigake pathway creates white-space for specialized antibody engineering boutiques serving domestic pharmaceutical sponsors seeking faster approval timelines. Target India's CDSCO-harmonized contract research segment with integrated discovery-to-IND offerings that combine computational biology with chemistry manufacturing. Establish go-to-market presence through partnership with established United States biotechnology firms lacking internal medicinal chemistry capacity. For Investors and Strategic Acquirers: The market sits at an early-cycle expansion phase that favors acquisition of AI-native target identification platforms with validated pharmaceutical partnerships over traditional high-throughput screening infrastructure. Long-term viability over the next decade hinges on generative chemistry capability integration and biomarker strategy depth. Monitor FDA breakthrough therapy designation approval velocity as the primary inflection signal for platform technology demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| AI Platform Licensing Agreement | Grants pharmaceutical developers access to generative molecular design capabilities without captive R&D infrastructure investment. |
| CDSCO Regulatory Harmonization | Enables Indian contract research organizations to offer integrated discovery-to-IND services meeting United States FDA submission standards. |
| Breakthrough Therapy Designation Pathway | Compresses clinical development timelines and rewards sponsors with predictive biomarker strategies and platform technology investments. |
| AlphaFold Structural Prediction Integration | Displaces crystallography-dependent lead optimization cycles and reduces protein production facility capital requirements. |
| Vendor Panel Consolidation | Centralizes procurement under chief scientific officers and reduces contract research organization relationships to strategic alliances. |
Methodological Framework
Operator-level perspectives from drug development executives, regulatory affairs leads, formulary directors, and contract research organization commercial heads anchored the qualitative base for this analysis. Primary interview insights combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and pharmaceutical company SEC disclosures. Bottom-up segmentation modeling and top-down market sizing triangulated volume estimates across technology, product type, end user, and application dimensions.
Scenario-bracketing around regulatory approval velocity and AI platform adoption curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include technology generation, therapeutic modality, development stage, and regional regulatory cluster. CAGRs derived from historical growth rate analysis adjusted for technology penetration curves and pipeline value erosion patterns. Forecast inputs incorporated biomarker qualification rates under FDA breakthrough therapy and EMA PRIME schemes.
Macroeconomic conditions sit as an overlay; deviation in venture capital availability for biotechnology formation or pharmaceutical R&D budget allocation would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway expansion and computational prediction accuracy improvements. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Atipamezole Market
Biopharmaceuticals
Drug Discovery Outsourcing Market
Biopharmaceuticals
Global Myelodysplastic Syndrome (MDS) Drugs Market
Biopharmaceuticals
Single-Domain Antibody Platforms Market
Biopharmaceuticals
Bioequivalence Studies Market
Biopharmaceuticals
Paediatric Oncology Therapeutics Market
Biopharmaceuticals
Latin America Human Insulin Drugs Market
Biopharmaceuticals
BRAF Kinase Inhibitors Market
Biopharmaceuticals
Global Resistant Pseudomonas Aeruginosa Infections Drugs Market
Biopharmaceuticals
Global Biopharmaceuticals Contract Manufacturing Market
Biopharmaceuticals
Large Macrolide Drugs Market
Biopharmaceuticals
Generic Drugs Market
Biopharmaceuticals
Rhu Albumin Market
Biopharmaceuticals
Clindamycin Phosphate Market
Biopharmaceuticals
Global Pegylated Proteins Market
Biopharmaceuticals
Tyrosine Kinase Inhibitors Market