
 North America Passive Radar Market | 2026-2036
North America Passive Radar Market Size, Share, and Industry Trends Forecast 2026-2036
North America Passive Radar Market Insights
Buyer concentration in North American defense procurement is decoupling from legacy prime-contractor relationships as smaller system integrators and specialized technology vendors gain program access. SRC Inc. leverages its Syracuse-based manufacturing footprint to dominate domestic multistatic array production. HENSOLDT AG anchors European-origin technology penetration through its U.S. subsidiary operations. Lockheed Martin Corporation competes by extending its Skunk Works heritage into low-observable sensor networks.
Passive radar detects and tracks objects by processing reflections from third-party illuminators of opportunity—commercial broadcast towers, satellite signals, or cellular base stations—without emitting detectable electromagnetic energy, typically operating across VHF through L-band frequencies with receiver sensitivity thresholds below −110 dBm. The technology serves military stealth detection, civil aviation gap-filling, and critical infrastructure perimeter security where active emissions compromise operational security. Frequency Modulated Continuous Wave architectures occupy the mature core of installed base revenue while Digital Beamforming segments capture disproportionate R&D allocation due to software-defined upgrade paths. Maritime Surveillance applications lead absolute deployment volume around the Gulf of Mexico and Atlantic littorals though Border Surveillance commands premium pricing through classified program structures.
The FAA coordinates civilian passive radar trials under NextGen modernization while the Department of Defense navigates NTIA spectrum allocation rulings that protect illuminator-of-opportunity bandwidth integrity. NIST calibration standards and DOD MIL-STD-461G electromagnetic compatibility requirements shape hardware qualification timelines and vendor eligibility. Stakeholders must monitor emerging FCC rulings on 5G spectrum coexistence that could expand or constrain illuminator density available for passive exploitation.
Market Dynamics
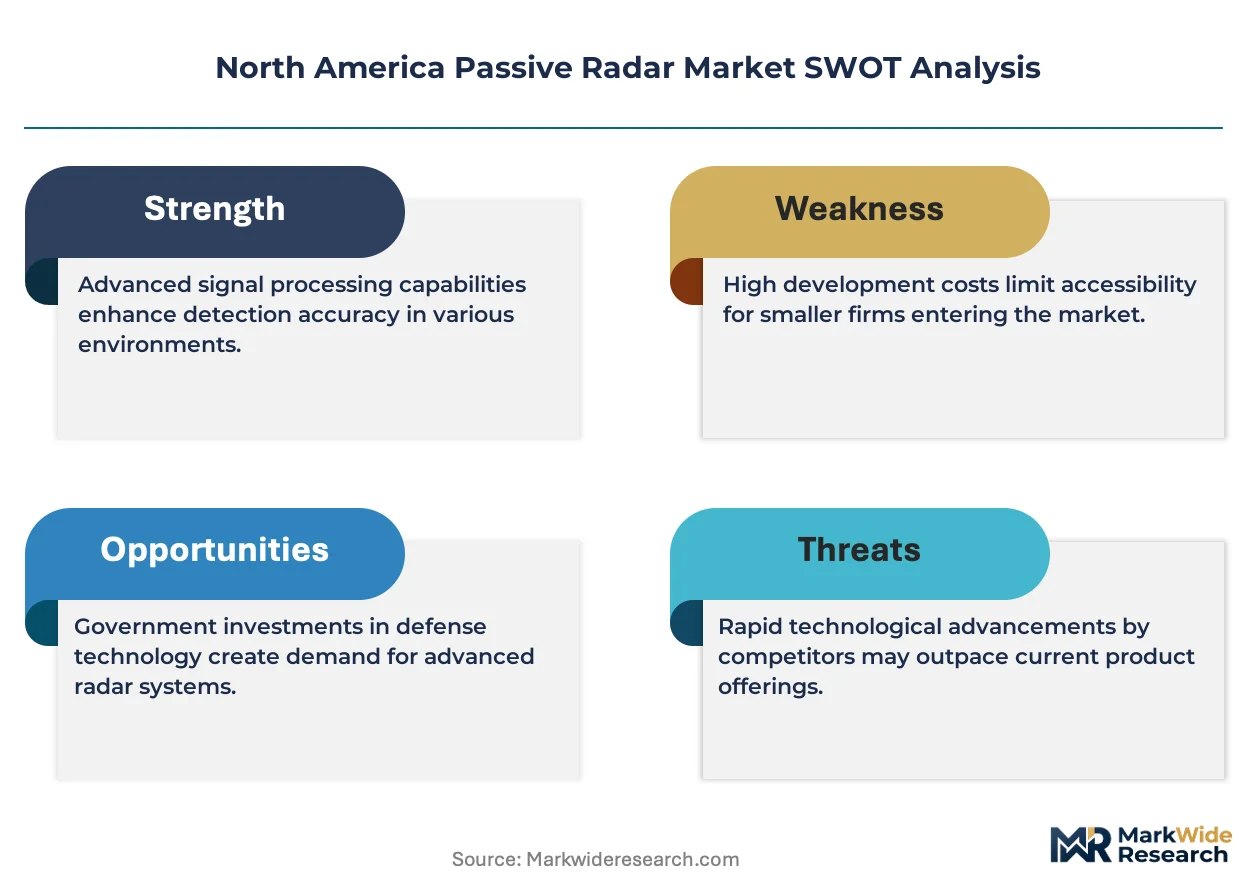
Defense procurement across the United States and Canada is decoupling from traditional active radar platforms and migrating toward covert surveillance architectures. This structural shift compresses vendor qualification timelines while elevating electromagnetic compatibility standards.
Growth Catalysts
- FAA NextGen Modernization:Federal Aviation Administration mandates for airspace surveillance gap-filling accelerate passive radar integration into civilian air traffic management systems across congested corridors.
- Cellular Illuminator Density:5G base station rollout along the southwestern United States border corridor creates exploitable third-party signal environments for multistatic array deployment.
- Maritime Domain Awareness:Great Lakes and Gulf of Mexico vessel traffic monitoring requirements drive demand for non-emitting coastal surveillance where active radar compromises operational security.
Market Restraints
- Receiver Component Concentration:High-sensitivity RF front-end manufacturing concentrates among specialized semiconductor foundries, creating single-source vulnerability for sub−110 dBm sensitivity thresholds.
- Spectrum Allocation Friction:NTIA rulings protecting illuminator-of-opportunity bandwidth integrity constrain frequency agility in L-band exploitation zones.
- Digital Signal Processing Costs:Real-time correlation processing for multistatic geometries requires specialized FPGA arrays that elevate unit economics above legacy active radar alternatives.
Strategic Opportunities
- Canadian Arctic Surveillance:NORAD modernization priorities create demand for passive coverage across underpenetrated northern maritime routes where active emissions reveal sensor positions.
- 5G Spectrum Coexistence:Emerging FCC rulings on cellular band sharing protocols could expand illuminator density available for passive exploitation in urban surveillance applications.
- Critical Infrastructure Perimeter Security:Power generation and telecommunications facilities adopt non-emitting detection for intrusion monitoring where electromagnetic silence preserves site security.
Industry Challenges
- Multistatic Algorithm Talent Scarcity:Bistatic and multistatic target tracking expertise concentrates among defense laboratory personnel, constraining commercial system integrator hiring pipelines.
- MIL-STD-461G Qualification Timelines:Electromagnetic compatibility certification cycles extend vendor eligibility windows, compressing competitive response speed for emerging procurement opportunities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Passive Radar Market |
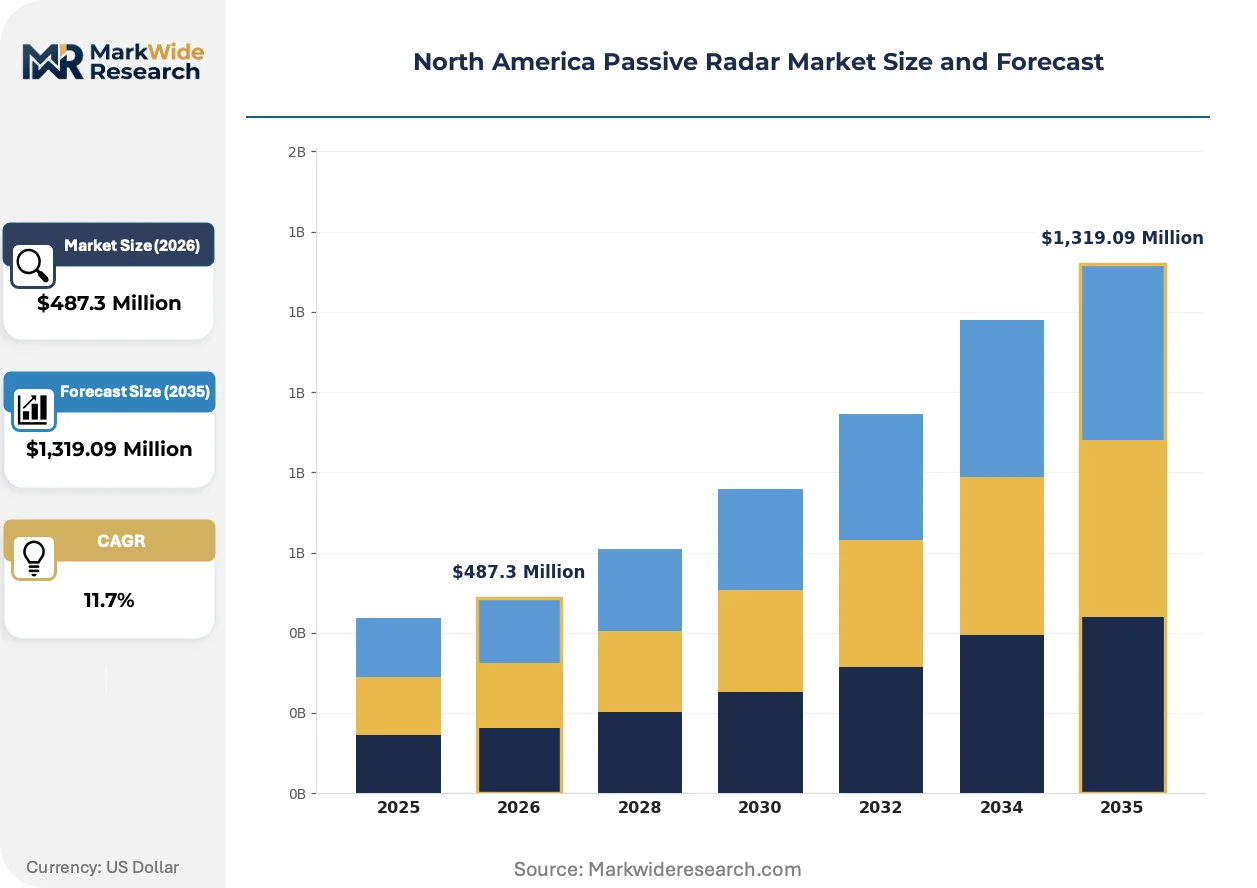
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Frequency Modulated Continuous Wave, Multistatic, Monostatic, Digital Beamforming Application: Air Traffic Control, Maritime Surveillance, Security Monitoring, Border Surveillance End User: Government, Defense, Civil Aviation, Commercial Deployment: On-premises, Cloud-based, Hybrid, Edge |
| Companies Covered | SRC Inc., ERA AS, HENSOLDT AG, RTX Corporation, Indra Sistemas, L3Harris Technologies, Lockheed Martin Corporation, Thales Group, BAE Systems, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Passive Radar Market Trends and Innovations
Software-defined receiver architectures are displacing hardware-fixed analog front-ends across North American passive radar procurement. This transition compresses upgrade cycles while fragmenting vendor competitive moats.
Digital Beamforming is consolidating multistatic signal processing into unified software-defined pipelines. SRC Inc. and specialized integrators deploy these architectures for rapid beam reconfiguration without hardware swap. The technology is consolidating competitive differentiation around firmware upgrade velocity rather than fixed hardware specifications.
FCC spectrum-sharing protocols are reshaping illuminator exploitation rights across commercial broadcast and cellular bands. These rulings determine which third-party signals remain legally stable for passive correlation processing. Border surveillance programs in the southwestern United States adapt procurement specifications to anticipated 5G band allocations.
Defense buyers are fragmenting procurement authority away from centralized prime-contractor relationships toward direct technology vendor engagement. Smaller system integrators now access classified program structures previously reserved for tier-one contractors. This pattern concentrates most visibly in maritime surveillance applications around Atlantic littorals where specialized multistatic expertise commands premium positioning.
North America Passive Radar Market Segmentation
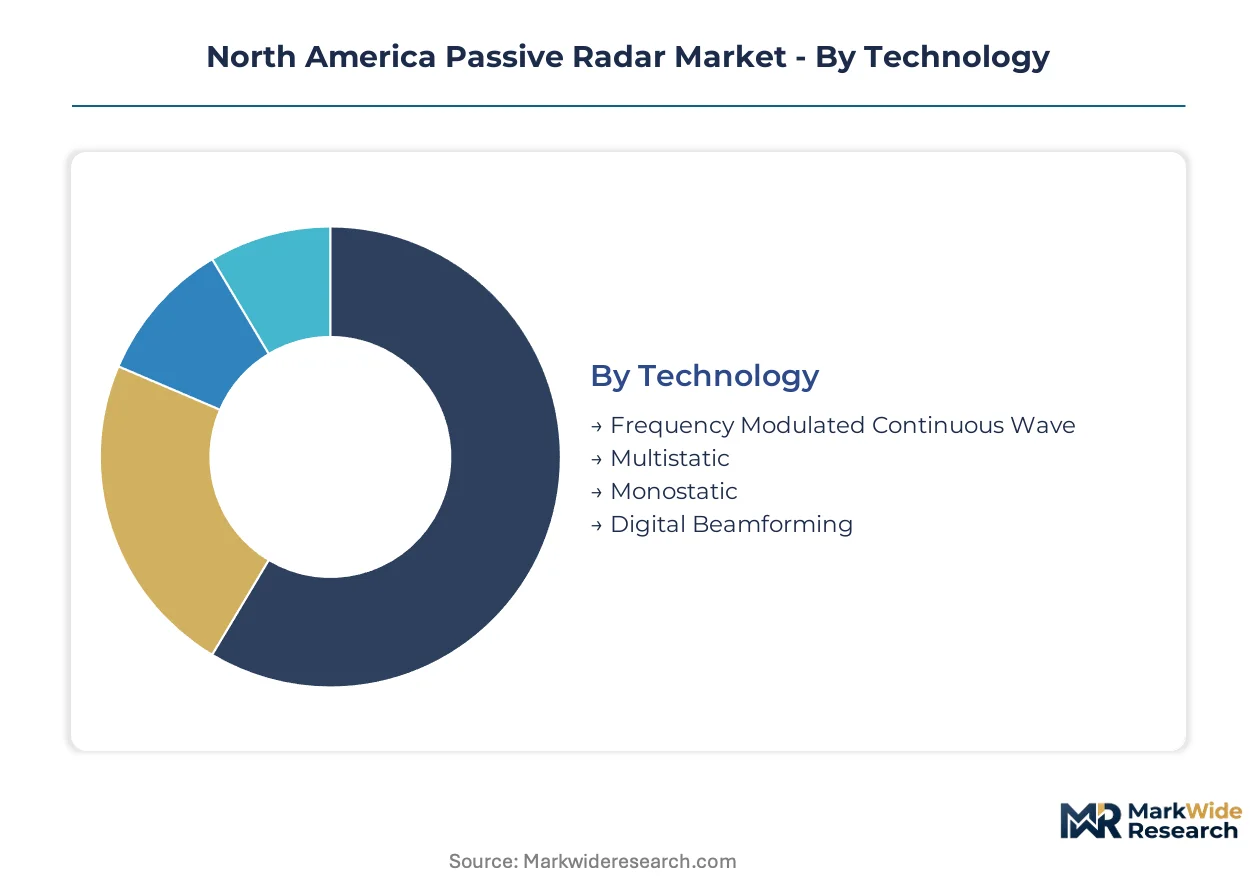
Passive radar procurement patterns diverge sharply across technology maturity, operational security requirements, and signal processing infrastructure. Understanding these segment boundaries clarifies why certain architectures dominate defense budgets while others accelerate in civilian applications.
Technology:
Defense buyers prioritize detection range and covertness; civil operators weight upgrade flexibility and spectrum adaptability.
- Frequency Modulated Continuous Wave:Mature architectures using continuous waveform illumination from broadcast or cellular towers. Demand concentrates in Great Lakes maritime zones where proven reliability outweighs upgrade costs for Coast Guard perimeter monitoring.
- Digital Beamforming:Software-defined receiver arrays enable rapid beam reconfiguration without hardware swap. Southwestern border corridor deployments favor this architecture for multistatic adaptation to shifting 5G illuminator density.
- Multistatic:Distributed receiver networks exploiting multiple third-party transmitters. NORAD modernization programs drive Canadian Arctic installations where emitter triangulation compensates for sparse infrastructure.
- Monostatic:Single-receiver configurations using one illuminator of opportunity. Commercial security adopters favor simplified deployment for critical infrastructure perimeter monitoring.
Frequency Modulated Continuous Wave leads volumes today; Digital Beamforming is gaining share fastest.
Application:
Operational security requirements and illuminator availability reshape deployment economics across use cases.
- Maritime Surveillance:Coastal and inland waterway monitoring exploits dense cellular tower coverage along populated littorals. Gulf of Mexico vessel traffic systems prioritize non-emitting detection where active radar reveals sensor positions to adversarial observers.
- Border Surveillance:Classified program structures command premium pricing for covert southwestern corridor coverage. Multistatic arrays process reflections from Mexican and U.S. cellular infrastructure without detectable emissions.
- Air Traffic Control:FAA NextGen gap-filling trials integrate passive receivers into congested corridor surveillance. Chicago and Atlanta hub approaches test coverage redundancy where primary radar blind spots persist.
- Security Monitoring:Power generation and telecommunications facilities adopt electromagnetic-silent intrusion detection. Site operators value undetectable perimeter coverage that preserves facility security posture.
Maritime Surveillance leads volumes today; Border Surveillance commands steepest expansion trajectory.
End User:
Budget cycles and electromagnetic compatibility standards fragment procurement authority across institutional buyers.
- Defense:Classified programs prioritize multistatic architectures with sub−110 dBm sensitivity. Pentagon procurement compresses vendor qualification timelines while elevating MIL-STD-461G compliance barriers.
- Government:Civilian agencies balance covertness requirements against commercial off-the-shelf availability. Department of Homeland Security maritime programs favor rapid deployment over custom development.
- Civil Aviation:FAA modernization mandates accelerate passive radar trials for airspace gap-filling. Airport authorities in Texas and California evaluate spectrum-sharing protocols for 5G illuminator exploitation.
- Commercial:Critical infrastructure operators seek turnkey perimeter solutions without classified program overhead. Telecommunications carriers test edge-deployed receivers for site security.
Defense leads volumes today; Civil Aviation is climbing the fastest.
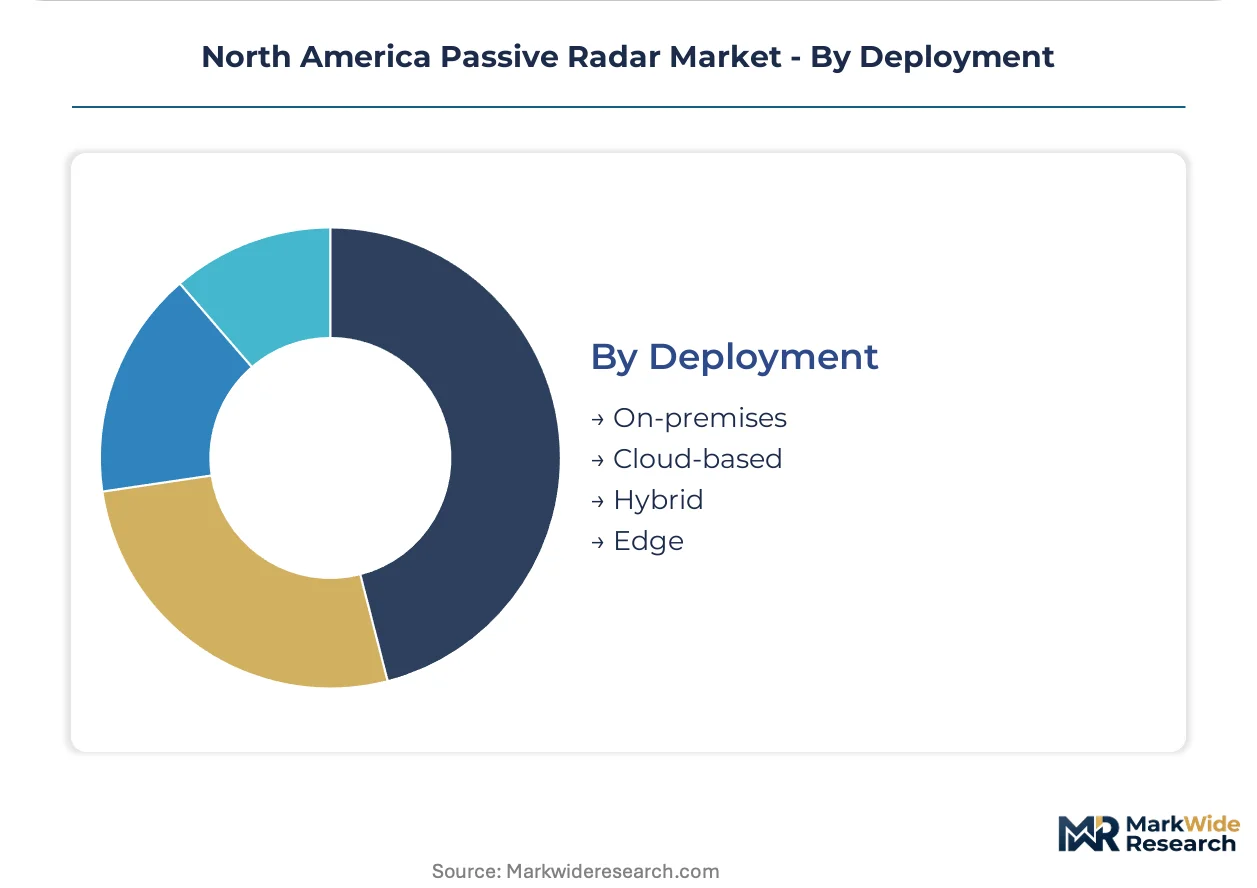
Deployment:
Processing latency requirements and data sovereignty rules determine infrastructure location for signal correlation.
- Edge:Real-time target tracking at receiver nodes minimizes backhaul bandwidth for time-critical applications. Border surveillance programs favor local processing to reduce network vulnerability.
- On-premises:Dedicated processing facilities serve classified defense installations with air-gapped security. NORAD sites mandate physical infrastructure control for Arctic coverage.
- Hybrid:Split architectures process raw signals locally while centralized systems handle multistatic correlation. Great Lakes maritime networks balance latency against computational scale.
- Cloud-based:Scalable correlation processing attracts civilian trials with lower security classification. FAA NextGen experiments evaluate cloud elasticity for traffic surge handling.
On-premises leads volumes today; Edge is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's Arctic surveillance priorities contrast with Mexico's border corridor illuminator density, revealing divergent passive radar deployment logics across the continent. FAA modernization in the United States creates civilian demand alongside classified defense procurement. The analysis examines three national markets driving North American adoption patterns.
United States
Southwestern border states deploy multistatic arrays exploiting cellular tower density for covert tracking. FAA NextGen mandates accelerate passive radar trials in Chicago and Atlanta hub corridors. Syracuse, New York hosts concentrated manufacturing for domestic multistatic array production.
Canada
NORAD modernization drives demand for non-emitting Arctic coverage across underpenetrated northern maritime routes. Canadian defense procurement prioritizes electromagnetic silence to preserve sensor positions in contested northern approaches. Ontario-based system integrators access classified program structures for Great Lakes maritime surveillance.
Mexico
Northern border states present exploitable third-party signal environments from cross-border cellular infrastructure. Mexican telecommunications density supports multistatic geometries for cooperative surveillance arrangements. Baja California and Chihuahua concentrate deployment trials addressing Gulf of Mexico littoral coverage gaps.
North America Passive Radar Market Competitive Landscape
United States producers anchor one tier; European-origin specialists hold established positions through subsidiary operations. The vendor base concentrates among defense primes with Skunk Works heritage and specialized system integrators with multistatic expertise. Two strategic archetypes dominate: vertically integrated defense contractors with classified program access, and technology-focused integrators with rapid firmware upgrade capabilities. Competitive moves center on electromagnetic compatibility certification acceleration and direct vendor engagement bypassing traditional prime-contractor channels.
Within the specialized integrator tier, SRC Inc. exemplifies domestic manufacturing footprint advantages, while HENSOLDT AG represents European-origin technology penetration through U.S. subsidiary structures. Lockheed Martin Corporation occupies a position extending defense prime heritage into low-observable sensor network architectures.
| Leading Market Players |
|---|
| SRC Inc. |
| ERA AS |
| HENSOLDT AG |
| RTX Corporation |
| Indra Sistemas |
| L3Harris Technologies |
| Lockheed Martin Corporation |
| Thales Group |
| BAE Systems |
| Others |
Pricing and Supply Chain Analysis
High-sensitivity RF front-end component costs cascade through three distinct pricing tiers, with specialized semiconductor foundry capacity in the United States and Germany anchoring premium multistatic array quotations while commercial security adopters face compressed margins on simplified monostatic configurations.
Pricing Analysis
Capacity additions in domestic Syracuse manufacturing corridors are reshaping price floors for FCC-certified Digital Beamforming systems. Three-tier pricing structure across premium, standard, and economy levels separates classified defense programs from Department of Homeland Security maritime procurements and commercial perimeter security installations. Pricing pressure stems from FPGA array shortages elevating unit economics above legacy active radar alternatives. Civil aviation buyers exhibit highest price sensitivity due to budget-constrained FAA trial programs.
Supply Chain Analysis
Domestic-content mandates under Pentagon procurement guidelines are reshaping sourcing patterns for MIL-STD-461G qualification components. Manufacturing concentrates in the United States, Germany, and Taiwan for sub−110 dBm sensitivity thresholds. Supply chains draw from gallium nitride substrates, high-speed ADC converters, and radiation-hardened FPGA arrays. Single-source vulnerability concentrates in specialized RF front-end foundries. Distribution runs through defense prime-contractor channels and direct technology vendor engagement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American passive radar procurement represents a late-cycle quality story, with defense buyers migrating toward premium Digital Beamforming specifications that prioritize firmware upgrade velocity over fixed hardware lifecycles.
For Market Incumbents: Acquire multistatic algorithm talent pools to counter scarcity constraints among defense laboratory personnel. Incumbents should accelerate electromagnetic compatibility certification cycles to compress vendor eligibility windows against emerging specialized integrators. Lockheed Martin and SRC Inc. can leverage existing classified program access to anchor premium positioning. For New Entrants and Emerging Players: Capture Canadian Arctic surveillance white space where NORAD modernization priorities outpace established vendor deployment capacity. New entrants should target Great Lakes maritime zones with rapid-deployment commercial off-the-shelf offerings. A direct vendor engagement model bypassing traditional prime-contractor channels offers fastest program access. For Investors and Strategic Acquirers: Consolidation pressure builds where firmware-defined upgrade capabilities separate sustainable competitive positioning from hardware-locked obsolescence. Investors should target specialized system integrators with rapid beam reconfiguration expertise. The signal to monitor is FCC 5G spectrum coexistence rulings expanding illuminator density for passive exploitation.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Beamforming Platform Integration | Unifies multistatic signal processing into software-defined pipelines for rapid reconfiguration. |
| Acquisition of Multistatic Algorithm Specialist | Addresses talent scarcity constraining commercial system integrator hiring pipelines. |
| MIL-STD-461G Certification Acceleration | Compresses vendor eligibility timelines for emerging Pentagon procurement opportunities. |
| 5G Spectrum Coexistence Partnership | Positions vendors for FCC rulings expanding cellular illuminator exploitation rights. |
| Canadian Arctic Deployment Expansion | Captures NORAD modernization demand across underpenetrated northern maritime routes. |
Research Methodology
Multiple input streams — defense procurement databases, electromagnetic compatibility certification records, and spectrum allocation filings — were reconciled to construct market estimates. Primary interviews with radar system engineers, Pentagon program officers, FAA modernization leads, and semiconductor foundry procurement managers were validated against secondary sources including NTIA spectrum rulings, DOD budget justification documents, and FCC docket proceedings. Bottom-up unit deployment estimates and top-down defense budget allocation analysis were triangulated to anchor projections.
Data-stream reconciliation across technology, application, end user, and deployment segmentation dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from multivariate regression incorporating illuminator density trajectories, NORAD modernization spending profiles, and FAA NextGen gap-filling trial expansion rates. Modeled inputs included 5G base station rollout curves along the southwestern border corridor and Great Lakes vessel traffic monitoring requirements.
NTIA spectrum reallocation decisions, FPGA component supply disruptions, and multistatic algorithm talent availability are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding illuminator-of-opportunity bandwidth integrity and defense procurement timeline compression. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Surveillance
Europe Intelligence Surveillance and Reconnaissance Market
Military Surveillance
Global Military Electro-Optical and Infrared Systems Market
Military Surveillance
Global Airborne Warning and Control System Market
Military Surveillance
EO/IR Gimbal Market
Military Surveillance
Air-Based Military Electro-Optical and Infrared Systems Market
Military Surveillance
Infrared Anti-Sniper Detection Software Market
Military Surveillance
Maritime Surveillance and Intervention Market
Military Surveillance
Military Manportable Surveillance Radar Market
Military Surveillance
Hydrographic Equipment Market
Military Surveillance
Land Based Military Electro Optical & IR Systems Market
Military Surveillance
Drone Surveillance Market
Military Surveillance
Manportable Surveillance and Target Acquisition Radar Market
Military Surveillance
Manportable Radar Market
Military Surveillance
Early Warning Radar Market
Military Surveillance
Military Jammer Market
Military Surveillance
Military Radar Market