
 North America Signals Intelligence (SIGINT) Market | 2026-2036
North America Signals Intelligence (SIGINT) Market Size, Share, and Industry Trends Forecast 2026-2036
North America Signals Intelligence (SIGINT) Market Insights
Cyber defense application demand is hardening across the North American SIGINT landscape. Lockheed Martin Corporation leverages its Bethesda, Maryland headquarters to anchor classified program execution for Pentagon clients. Northrop Grumman Corporation competes through advanced electronic warfare integration with airborne platforms. L3Harris Technologies, Inc. specializes in tactical communications intercept systems for special operations forces.
Signals Intelligence encompasses the interception, collection, analysis, and exploitation of electronic signals and emissions across radio frequency, microwave, and digital spectrums, typically operating across bandwidths from HF through millimeter-wave frequencies with real-time processing latencies under ten milliseconds. Its primary purpose is to derive actionable intelligence from adversary communications, radar systems, and data networks for national security decision-making. ELINT and COMINT technologies dominate current procurement budgets, while cyber signals and data analytics segments capture the fastest-growing investment flows as artificial intelligence-enabled pattern recognition reshapes operator workflows. Cloud-based and hybrid deployment architectures are gaining traction among intelligence organizations seeking elastic compute for signal processing workloads.
The National Security Agency, Department of Defense cyber directives, and NIST cybersecurity frameworks collectively shape product standards and vendor qualification pathways across the North American SIGINT supply base. FCC spectrum allocation rulings and ITAR export control regimes further constrain technology transfer and foreign participation in sensitive programs. Stakeholders must monitor evolving CMMC certification requirements and congressional appropriations for space-based signals collection platforms.
Market Dynamics
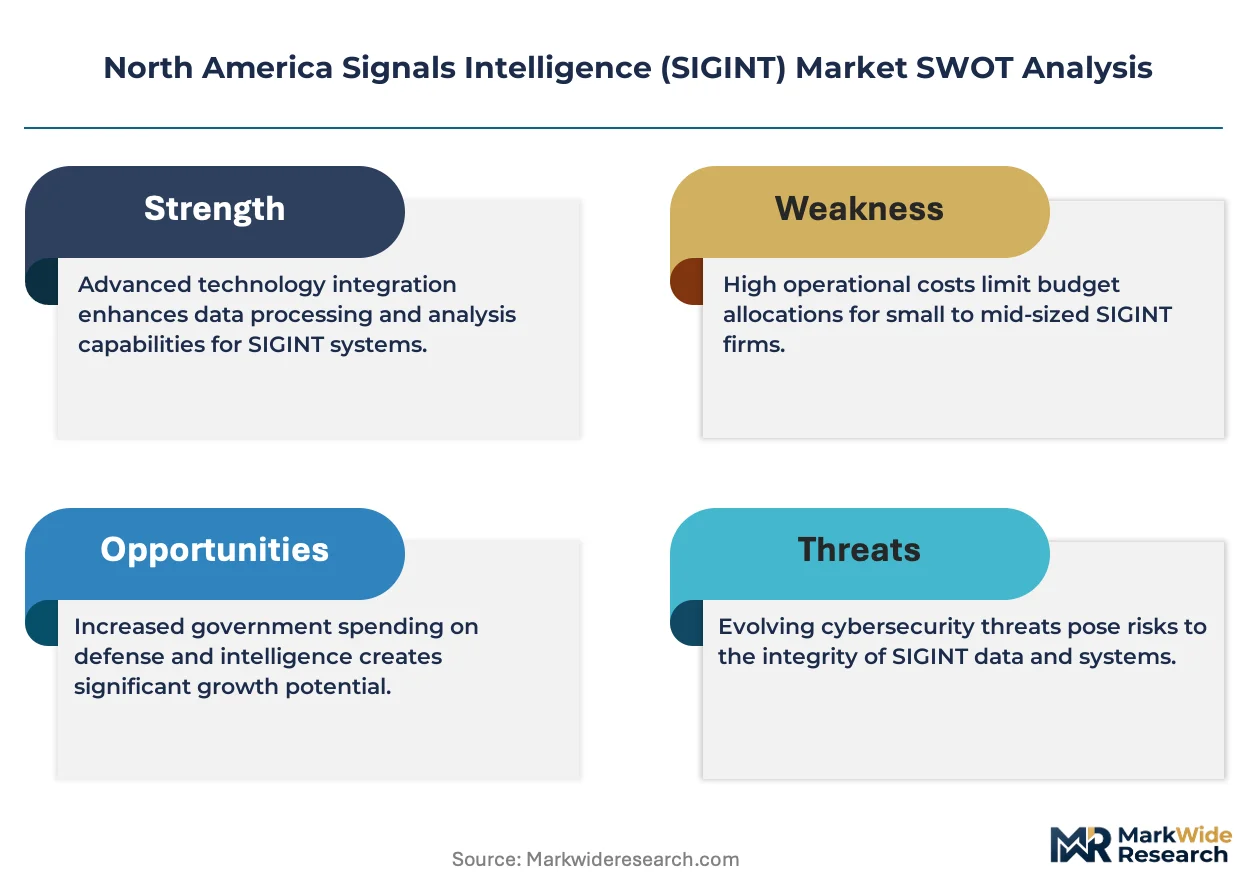
The Department of Defense cyber directives are compressing procurement cycles for SIGINT platforms, forcing vendors to align product roadmaps with classified interoperability mandates rather than proprietary architectures.
Growth Catalysts
- CMMC Certification Mandates:The Cybersecurity Maturity Model Certification framework now gates defense contract eligibility, compelling prime contractors to harden supply chains across Maryland and Virginia corridors.
- Space-Based Collection Architectures:Congressional appropriations for low-earth orbit signals platforms are redirecting terrestrial R&D budgets toward satellite payload miniaturization and cross-link processing.
- Special Operations Forces Demand:Tactical communications intercept requirements from SOCOM units are accelerating field-deployable system development with sub-ten-millisecond processing latencies.
Market Restraints
- ITAR Export Controls:State Department licensing regimes block foreign participation in sensitive programs, shrinking the addressable talent pool for cleared engineering positions.
- Gallium Nitride Supply Concentration:Domestic fabrication capacity for high-frequency RF components remains concentrated among a handful of DOD-trusted foundries.
- Spectrum Allocation Friction:FCC rulings on commercial 5G bands encroach on military SIGINT operating windows, forcing costly receiver redesigns.
Strategic Opportunities
- Canadian Arctic Surveillance:NORAD modernization funding creates demand for signals collection platforms hardened against extreme cold and magnetic interference.
- AI-Enabled Pattern Recognition:Machine learning convergence with traditional ELINT processing is opening workflow automation contracts among intelligence community analysts.
- Cloud-Native Deployment Models:Elastic compute architectures for signal processing workloads are penetrating agencies previously wedded to on-premise classified enclaves.
Industry Challenges
- Cleared Workforce Scarcity:Polygraph-ready software engineers and signals analysts command premium compensation in Northern Virginia, constraining program scaling.
- Legacy System Interoperability:Decades-old COMINT archives resist migration to modern analytics platforms without expensive format translation layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Signals Intelligence (SIGINT) Market |
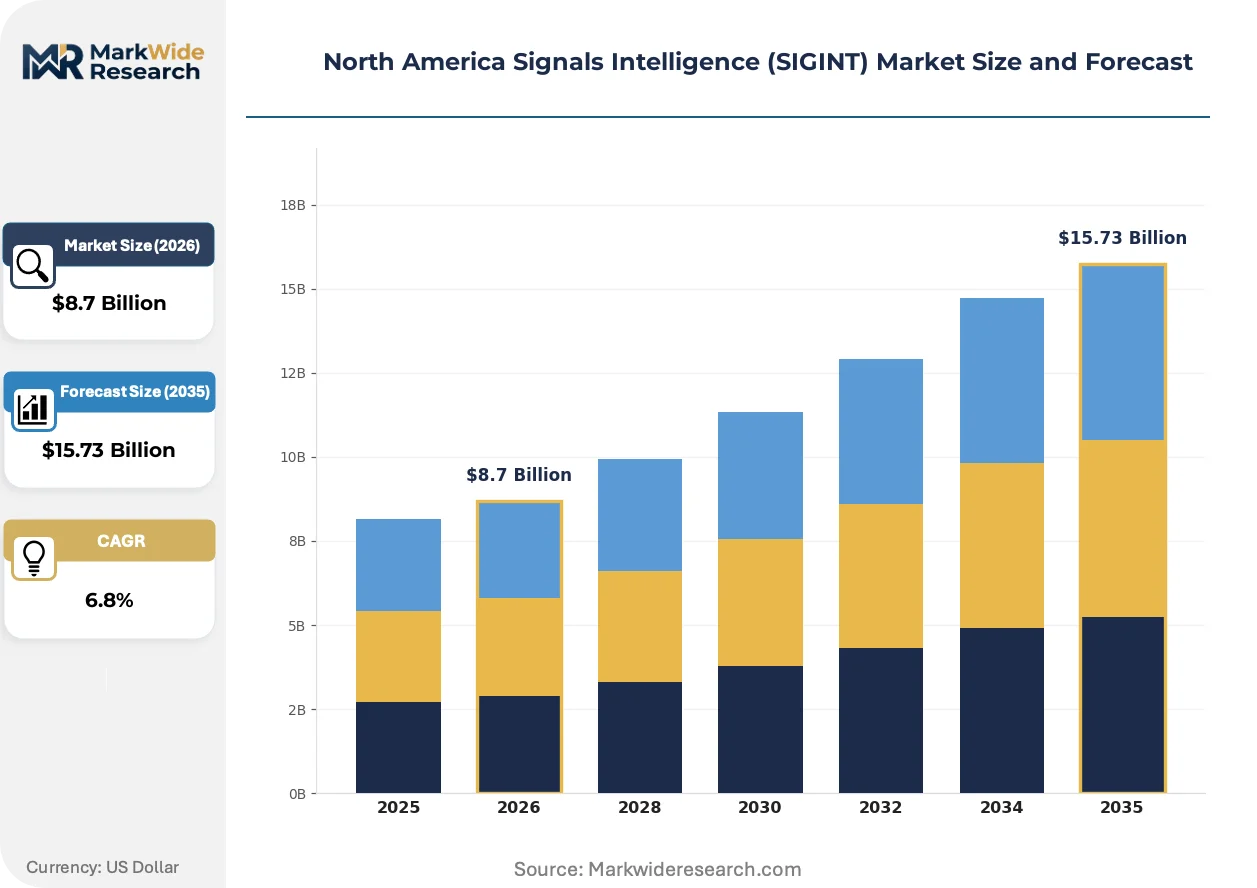
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: ELINT, COMINT, Cyber Signals, Data Analytics Application: National Security, Cyber Defense, Law Enforcement, Counterterrorism End User: Government Agencies, Military, Intelligence Organizations, Private Sector Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services |
| Companies Covered | Lockheed Martin Corporation, Northrop Grumman Corporation, L3Harris Technologies, Inc., Raytheon Technologies Corporation, General Dynamics Mission Systems, Inc., BAE Systems PLC, Mercury Systems, Parsons Corporation, Boeing, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Signals Intelligence (SIGINT) Market Trends and Innovations
Artificial intelligence architectures are compressing analyst workflows across the SIGINT value chain, replacing manual correlation tasks with automated emitter identification and geolocation triangulation.
Quantum-resistant encryption protocols are integrating into tactical radio intercept systems, addressing the threat that adversary quantum computing poses to current cryptanalytic methods. NSA-directed migration timelines are forcing vendors to retrofit fielded equipment with post-quantum cryptographic modules. This upgrade cycle is integrating new supply chain requirements for radiation-hardened processors and tamper-resistant firmware.
The NIST cybersecurity framework revision is tightening authentication requirements for signals processing infrastructure, mandating zero-trust architectures across classified and unclassified networks. Defense contractors in Maryland must now segment development environments from production systems through hardware-enforced boundaries. Prime integrators are responding by restructuring facility clearances and personnel access protocols.
Consolidated buying patterns among Pentagon cyber commands are displacing fragmented service-specific procurement, concentrating multi-year platform awards among cleared primes with existing facility infrastructure. Program offices now favor single-vendor accountability over subsystem competition. This concentration is most visible in Northern Virginia, where the Intelligence Community has centralized next-generation signals architecture decisions at Fort Meade.
North America Signals Intelligence (SIGINT) Market Segmentation
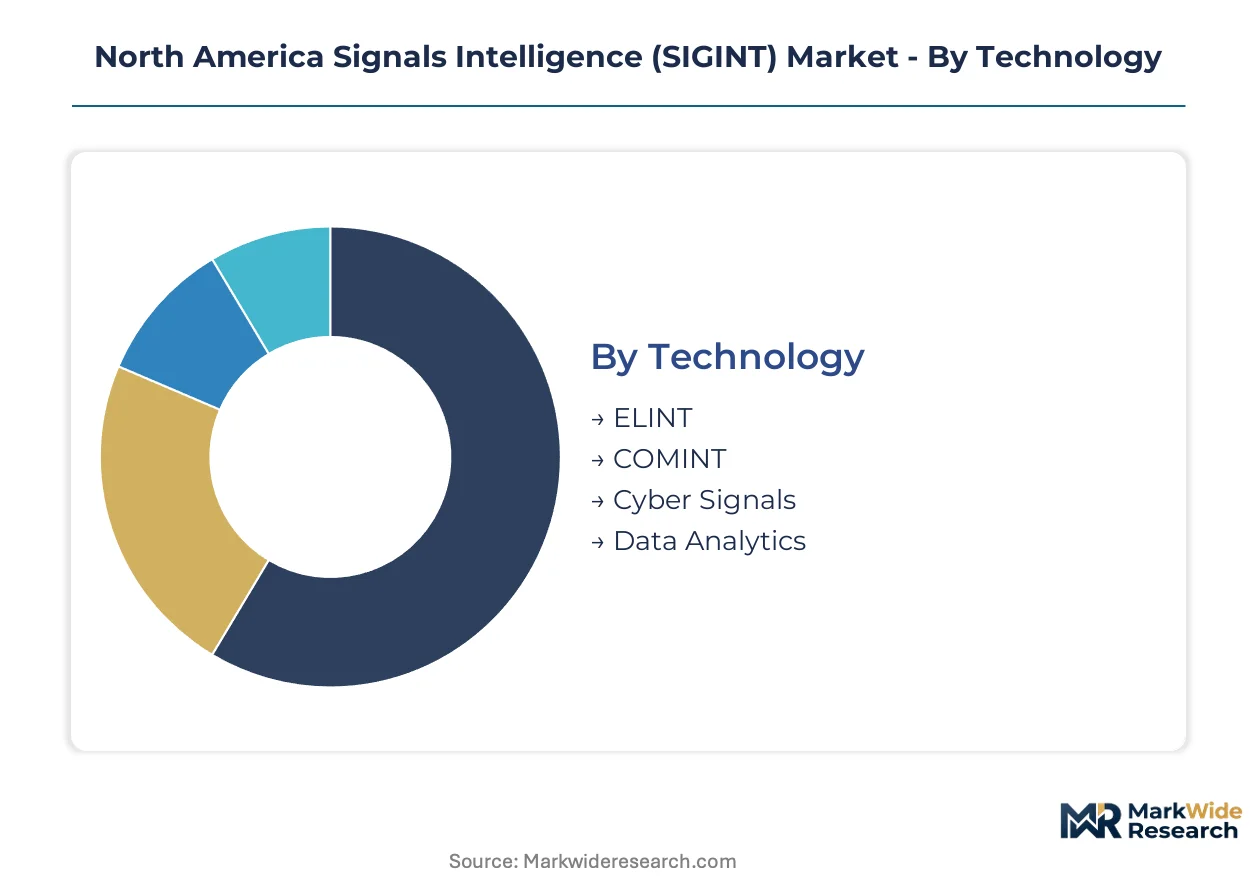
SIGINT procurement patterns diverge sharply across technology layers and deployment models. Capital allocation decisions hinge on clearance requirements, processing latency demands, and interoperability with legacy intelligence infrastructure.
Technology:
Capital intensity peaks in hardware-dependent intercept disciplines requiring specialized RF front-ends and classified fabrication facilities.
- ELINT:Electronic intelligence systems capture non-communications emissions from radar and weapon systems across microwave frequencies. The Pentagon's Northern Virginia corridor concentrates demand for airborne ELINT platforms, driven by NORAD modernization mandates and Pacific theater surveillance requirements.
- COMINT:Communications intelligence intercepts voice, data, and messaging traffic through terrestrial, airborne, and satellite collection. Maryland-based program offices prioritize COMINT for counterterrorism tasking, though spectrum congestion from commercial 5G deployments complicates receiver design specifications.
- Cyber Signals:Network-based intercept platforms targeting adversary infrastructure and data exfiltration patterns.
- Data Analytics:AI-enabled pattern recognition and automated emitter identification tools.
ELINT absorbs the bulk of installed capacity; Data Analytics is expanding most quickly.
Application:
Threat vector prioritization determines budget allocation, with nation-state adversaries commanding larger program increments than non-state actors.
- National Security:Strategic intelligence collection against peer adversaries, encompassing long-term infrastructure monitoring and order-of-battle analysis. Fort Meade-directed programs dominate this segment, with funding concentrated in multi-year platform acquisitions rather than annual service contracts.
- Cyber Defense:Real-time network monitoring and intrusion detection for critical infrastructure protection. Canadian Cyber Centre demand is hardening alongside US Cyber Command requirements, creating cross-border procurement standardization pressure.
- Law Enforcement:Domestic intercept capabilities for federal and state agencies operating under warrant authorities.
- Counterterrorism:Tactical collection against dispersed non-state networks requiring rapid deployment architectures.
National Security commands the largest program of record; Cyber Defense is climbing the fastest.
End User:
Clearance infrastructure and facility accreditation create steep barriers between customer tiers, concentrating vendor relationships among pre-qualified primes.
- Government Agencies:Civilian intelligence and homeland security organizations with specialized collection mandates. The National Security Agency and Department of Homeland Security anchor demand, with procurement flowing through Maryland and Virginia contracting offices.
- Military:Service-specific commands and combatant commands with tactical and strategic requirements. Special Operations Command drives compact, low-latency system specifications, while Air Force Space Command prioritizes satellite payload integration.
- Intelligence Organizations:Five Eyes partner agencies and domestic fusion centers with shared intercept responsibilities.
- Private Sector:Critical infrastructure operators and defense contractors with threat intelligence requirements.
Military end-users anchor platform development; Private Sector adoption is gaining share fastest.
Deployment:
Security classification levels and data sovereignty requirements fragment cloud migration timelines across the user base.
- On-Premises:Air-gapped classified enclaves processing signals at the highest sensitivity levels. NSA-certified facilities in Maryland and Texas maintain the majority of deployed capacity, with hardware refresh cycles tied to congressional appropriations.
- Cloud-Based:Elastic compute architectures for unclassified and collateral processing workloads. Intelligence Community agencies are piloting FedRAMP-authorized platforms, though full-spectrum signals remain restricted to on-premise infrastructure.
- Hybrid:Segmented architectures routing sensitive processing to classified enclaves while leveraging commercial cloud for storage and analytics.
- Managed Services:Contractor-operated collection and processing systems reducing government capital expenditure.
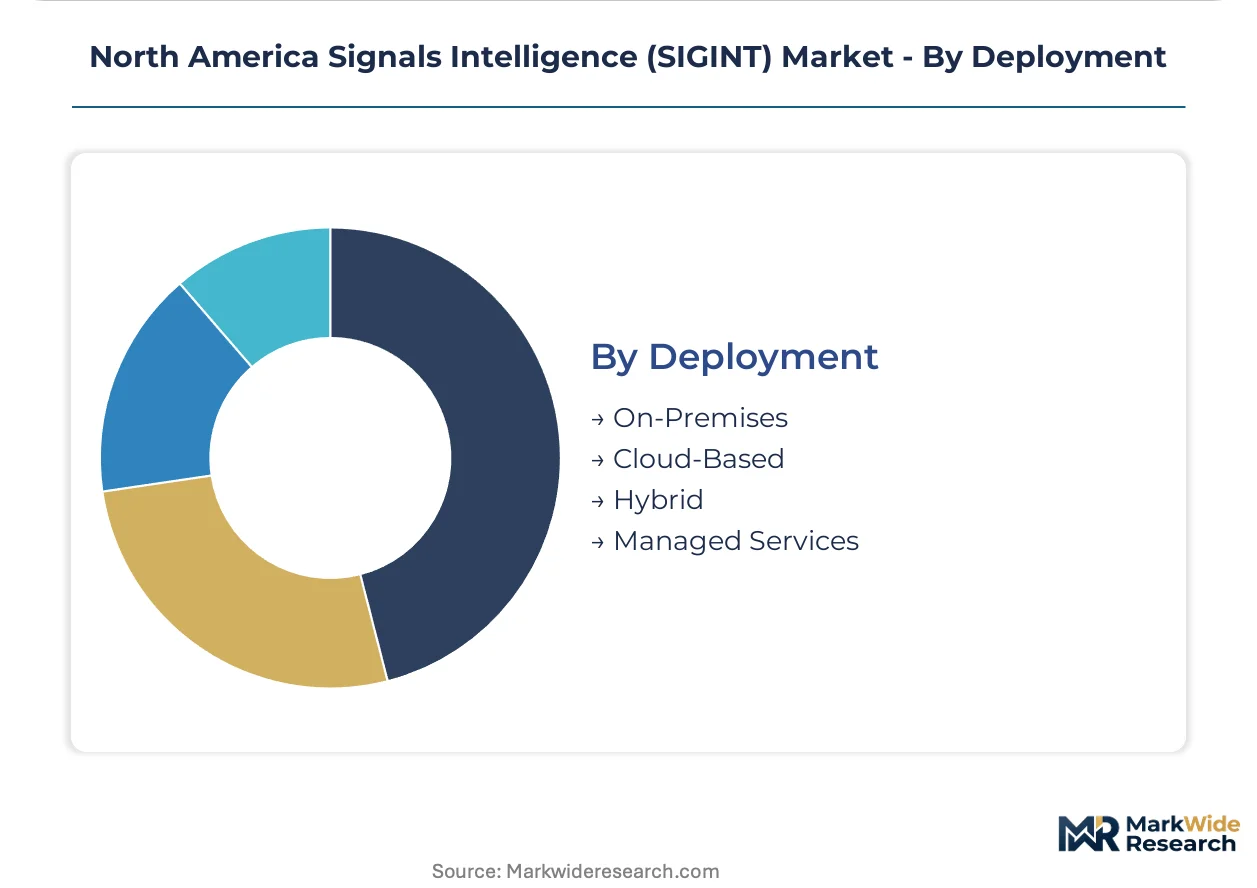
On-Premises retains the dominant installed base; Hybrid architectures are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes the bulk of North American SIGINT capacity, while Canada concentrates specialized Arctic surveillance development. Mexico contributes emerging cyber defense coordination through regional security partnerships.
United States
Pentagon cyber directives and NSA program requirements drive procurement concentration in Maryland and Northern Virginia. The Cybersecurity Maturity Model Certification framework gates contract eligibility for vendors serving Fort Meade-directed programs. Bethesda and Annapolis Junction host classified development facilities where cleared engineering talent commands premium compensation.
Canada
NORAD modernization funding creates demand for cold-hardened signals collection platforms across Arctic territories. The Canadian Cyber Centre shapes technical standards alongside US Cyber Command interoperability mandates. Ottawa and Calgary anchor development corridors where contractors address magnetic interference challenges in extreme climate conditions.
Mexico
Cross-border counterterrorism tasking generates tactical communications intercept requirements for special operations coordination. The Secretariat of National Defense participates in regional security frameworks with standardized equipment protocols. Mexico City concentrates liaison functions while northern border states host joint training infrastructure.
North America Signals Intelligence (SIGINT) Market Competitive Landscape
Top-tier vendors anchor classified program execution, while mid-tier specialists compete for subsystem integration roles. The vendor base stratifies between cleared primes with facility infrastructure and emerging players seeking CMMC accreditation. Three archetypes dominate: Bethesda-based systems integrators, Virginia corridor electronic warfare specialists, and Canadian Arctic platform developers. Consolidation pressure and supply chain hardening represent the dominant competitive moves.
Within the cleared prime tier, Lockheed Martin Corporation and Northrop Grumman Corporation exemplify Maryland-anchored program execution archetypes. L3Harris Technologies, Inc. occupies a position representing tactical communications specialization for special operations demand. These entities sit within a contracting environment where facility clearances and existing accreditation create steep barriers to new market entry.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| L3Harris Technologies, Inc. |
| Raytheon Technologies Corporation |
| General Dynamics Mission Systems, Inc. |
| BAE Systems PLC |
| Mercury Systems |
| Parsons Corporation |
| Boeing |
| Others |
Pricing and Supply Chain Analysis
Captive in-house fabrication of radiation-hardened processors anchors both supply security and pricing power for cleared primes serving Fort Meade-directed programs. Maryland and Northern Virginia facility clearances create steep barriers that insulate incumbent margins from price erosion.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent CMMC-compliant deployments from standard procurement cycles, with cleared primes commanding premiums for sub-twelve-month delivery windows. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade, facility clearance tier, and after-sales service bundling. Pricing pressure stems from congressional appropriations uncertainty for space-based platforms, compressing multi-year contract visibility. Military end-users show lowest price sensitivity due to mission-critical mandates, while private sector critical infrastructure operators negotiate hardest on total cost of ownership.
Supply Chain Analysis
Cleared workforce scarcity in Maryland and Northern Virginia manufacturing corridors constrains production scaling for specialized RF front-end components. Supply draws from domestic DOD-trusted foundries for gallium nitride semiconductors, Canadian cold-hardened payload specialists, and Texas-based radiation-hardened processor fabricators. Single-source vulnerability concentrates in high-frequency RF component supply, with tariff exposure minimal due to ITAR-constrained domestic sourcing mandates. Distribution runs through prime contractor direct sales teams and intelligence community contracting offices rather than channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players are pursuing backward integration into classified semiconductor fabrication to secure supply and capture margin from DOD-trusted foundry capacity.
For Market Incumbents: Hedge against emerging AI-native signals analytics competitors by acquiring pattern-recognition software specialists before cloud-native deployment models mature. Fortify CMMC certification infrastructure across Maryland and Virginia supplier networks to maintain contract eligibility gates. Lock in multi-year gallium nitride supply agreements with domestic foundries before congressional appropriations redirect budgets toward satellite payload miniaturization. For New Entrants and Emerging Players: CMMC certification mandates in the United States open a window for cybersecurity consulting services that harden mid-tier subsystem vendors for prime contractor supply chains. Target Canadian Arctic surveillance hardware as the most penetrable geography, where NORAD modernization funding outpaces cleared prime capacity. Lead with cold-hardened payload engineering credentials to bypass entrenched Maryland facility advantages. For Investors and Strategic Acquirers: Exit pathways concentrate in prime contractor acquisition of AI-enabled analytics specialists with existing intelligence community pilot contracts. Long-term viability hinges on positioning upstream of cloud-native deployment transitions, with five-to-ten-year value creation tied to post-quantum cryptographic module retrofit cycles. Watch for NSA-directed migration timeline acceleration as the signal indicating consolidation urgency.| Strategic Initiative | Industry Significance |
|---|---|
| CMMC Supply Chain Hardening | Cybersecurity Maturity Model Certification compliance gates contract eligibility for Maryland and Virginia corridor vendors. |
| Post-Quantum Cryptographic Retrofit | NSA-directed migration timelines force field equipment upgrades with radiation-hardened processor supply chain implications. |
| Arctic Platform Specialization | NORAD modernization funding creates demand for cold-hardened signals collection systems across Canadian territories. |
| AI Pattern Recognition Acquisition | Machine learning convergence with ELINT processing opens workflow automation contracts among Fort Meade analysts. |
| Hybrid Cloud Deployment Pilot | FedRAMP-authorized platforms penetrate intelligence agencies previously restricted to on-premise classified enclaves. |
Research Methodology
Multi-period observation of CMMC certification adoption rates, congressional appropriations flows, and prime contractor facility clearance expansions anchored the trend analysis, supplemented by interviews with program officers at Fort Meade, cleared engineering directors at Maryland-based primes, Canadian Cyber Centre procurement leads, and special operations requirements officers at SOCOM. Secondary validation drew from Department of Defense cyber directive filings, NSA budget justification documents, FCC spectrum allocation rulings, and congressional appropriations committee reports. Bottom-up segment sizing triangulated against top-down defense expenditure macro indicators.
Segment-weighting across technology layers, deployment models, and end-user clearance tiers structured the analytical framework. The model applied differential growth assumptions to hardware-intensive ELINT platforms versus software-centric data analytics segments across the projection horizon. CAGRs derived from trend extrapolation of program of record funding profiles, adjusted for procurement cycle compression effects from Pentagon cyber directives. Forecast inputs incorporated satellite payload miniaturization roadmaps and quantum-resistant encryption migration timelines.
The model assumes a particular technology adoption path; alternative pathways for cloud-native signals processing would alter the outlook if intelligence community security accreditation accelerates beyond current FedRAMP pilot scope. Forecasts reflect assumptions about sustained congressional support for space-based collection architectures and stable ITAR export control regimes. Material deviation in NSA-directed cryptographic migration timelines or NORAD modernization funding appropriations warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Surveillance
EO/IR Gimbal Market
Military Surveillance
Target Acquisition Systems Market
Military Surveillance
Infrared Anti-Sniper Detection Software Market
Military Surveillance
Global Military Thermal Imaging Market
Military Surveillance
Military Manportable Surveillance Radar Market
Military Surveillance
Laser Telemetry Binoculars Market
Military Surveillance
Airborne Target Acquisition Systems Market
Military Surveillance
UXO Detection Market
Military Surveillance
Passive Radar Market
Military Surveillance
Manportable Surveillance and Target Acquisition Radar Market
Military Surveillance
Tactical Optics Market
Military Surveillance
Manportable Radar Market
Military Surveillance
Global Airborne Surveillance Market
Military Surveillance
Military Jammer Market
Military Surveillance
Drone Surveillance Market
Military Surveillance
North America Hydrographic Survey Equipment Market