
 Military Electro-Optics/Infrared (EO/IR) Systems Market | 2026-2036
Military Electro-Optics/Infrared (EO/IR) Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Military Electro-Optics/Infrared (EO/IR) Systems Market Foresight
The United States is reshaping competitive dynamics through accelerated domestic foundry investment for cooled infrared detector substrates. Lockheed Martin leverages vertical integration across focal plane array design and precision gimbal production to sustain program margins on long-range targeting systems. Northrop Grumman anchors the airborne laser targeting segment with deep proprietary expertise in stabilized turret architectures. Raytheon Technologies competes through classified programs linking distributed aperture sensors to missile defense cueing networks.
Military electro-optics/infrared systems integrate photonic sensors, stabilized platforms, and digital signal processors to detect, track, and identify objects across visible through long-wave infrared spectra, typically operating at 3-5 μm or 8-12 μm wavebands for thermal imaging. These systems serve primarily to extend operator vision beyond unaided human capability in degraded visual environments or nighttime conditions. Thermal imaging product types command the largest installed base due to mature supply chains for vanadium oxide microbolometers, while quantum dots technology represents the fastest-expanding segment as epitaxial growth techniques improve operating temperature flexibility. Targeting systems applications concentrate the highest value per unit, though surveillance systems generate greater aggregate volume through persistent border monitoring requirements.
The US Department of Defense imposes ITAR-controlled export restrictions that fragment supplier eligibility and limit technology transfer to allied nations. European procurement through the European Defence Agency increasingly references CE marking and EU AI Act conformity for autonomous targeting algorithms, compressing development timelines for multinational programs. Stakeholders must monitor how ITAR reform discussions and European defense industrial strategy harmonization reshape subcontractor qualification requirements and cross-border teaming arrangements.
Market Dynamics
The Joint All-Domain Command and Control framework is redirecting procurement budgets toward networked sensor architectures, forcing prime contractors to restructure around distributed aperture integration rather than standalone platform sales.
Growth Catalysts
- ITAR-controlled technology retention:Congressional defense appropriations in the United States prioritize domestic infrared countermeasure modernization, insulating domestic suppliers from foreign competition.
- Multi-spectral targeting pod procurement:NATO member states are expanding fighter aircraft upgrade programs requiring cooled detector arrays and precision stabilization.
- Vanadium oxide microbolometer maturation:Thermal imaging supply chains have achieved cost efficiencies that enable widespread deployment across surveillance and targeting applications.
Market Restraints
- Mercury cadmium telluride substrate concentration:Limited domestic foundry capacity for cooled detector materials creates supply vulnerability concentrated in specialized semiconductor fabrication.
- ITAR export restriction fragmentation:Technology transfer limitations to allied nations compress addressable market scope for US-based subsystem suppliers.
- Quantum dot epitaxial yield limitations:Operating temperature flexibility improvements remain constrained by manufacturing repeatability at scale.
Strategic Opportunities
- EU AI Act conformity pathways:European Defence Agency procurement increasingly mandates algorithmic transparency for autonomous targeting, creating first-mover advantage for compliant developers.
- Border surveillance persistent monitoring:Aggregate volume expansion in ground-based surveillance systems outpaces platform-limited targeting pod growth.
- Networked EO/IR node integration:Distributed sensing architectures enable new revenue streams through software-defined sensor fusion and cross-platform cueing.
Industry Challenges
- Cleared workforce scarcity:Security clearance timelines for electro-optics engineers extend program staffing cycles beyond competitive benchmarks.
- Legacy platform integration complexity:Retrofitting distributed aperture architectures onto existing aircraft and vehicle fleets demands customized mechanical and electrical interface engineering.
- CE marking timeline compression:European certification requirements for autonomous systems compress development schedules for multinational program participation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Electro-Optics/Infrared (EO/IR) Systems Market |
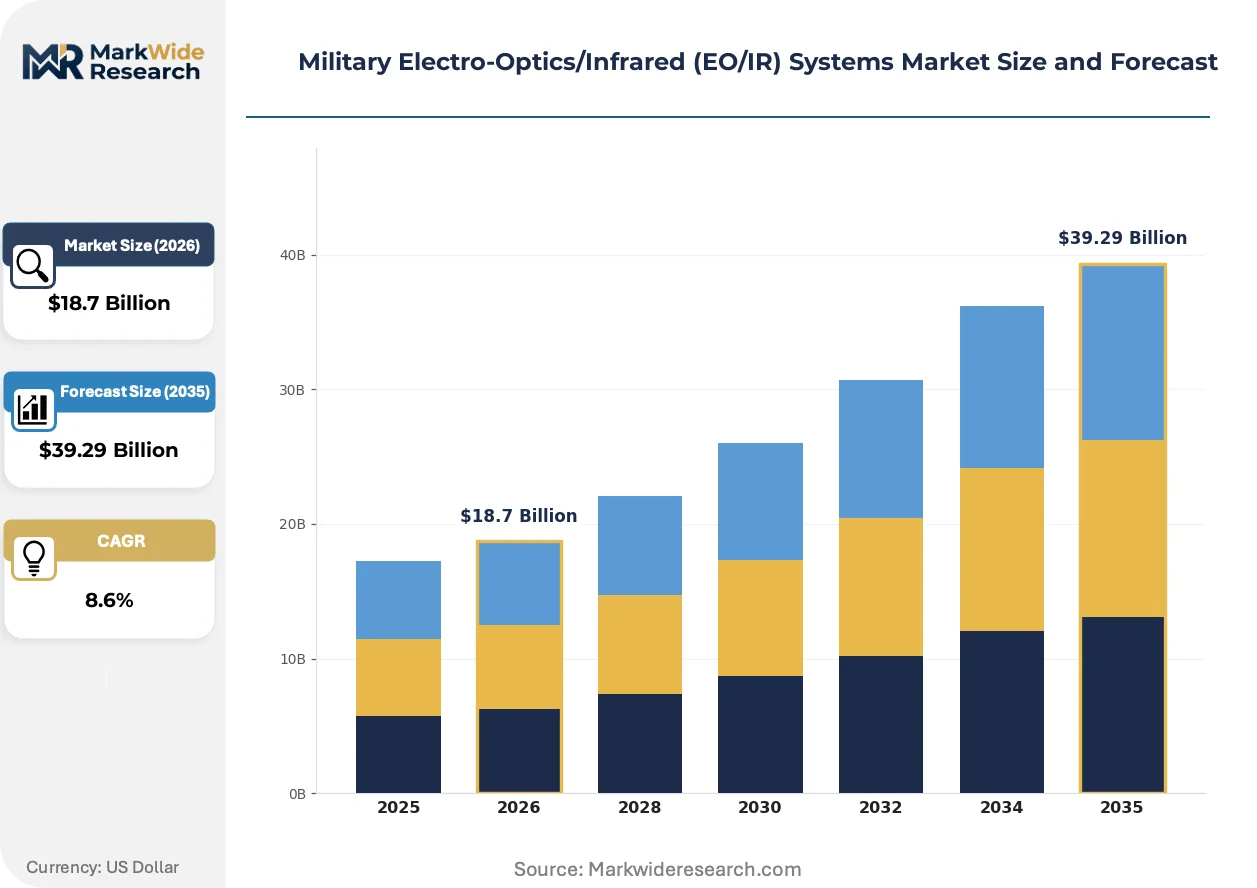
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Imaging, Night Vision, Targeting Systems, Surveillance Systems Technology: Active Infrared, Passive Infrared, Quantum Dots, Microbolometers End User: Defense Forces, Security Agencies, Research Institutions, Private Contractors Application: Border Security, Threat Detection, Reconnaissance, Situational Awareness |
| Companies Covered | Lockheed Martin Corporation, Northrop Grumman Corporation, Raytheon Technologies Corporation, L3Harris Technologies Inc., BAE Systems plc, Teledyne FLIR LLC, Thales Group, Elbit Systems Ltd., Leonardo S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Electro-Optics/Infrared (EO/IR) Systems Market Shifts & Advancements
Quantum dot infrared photodetectors are advancing through epitaxial growth refinements that promise operating temperature flexibility without cryogenic cooling infrastructure.
Quantum dot focal plane arrays detect infrared radiation through tunable intersubband transitions rather than thermal resistance changes. Naval aviation programs are evaluating uncooled alternatives for maritime patrol endurance missions. This technology is rendering obsolete the mechanical cryocoolers that currently dominate size-weight-power budgets on tactical platforms.
EU AI Act algorithmic conformity requirements now extend to autonomous targeting decision chains. European Defence Agency tender specifications increasingly reference explainability thresholds for machine-learning-based track classification. Airborne laser targeting segments face compressed development timelines as prime contractors restructure software architectures for auditability.
Defense procurement offices are consolidating sensor subsystem buys under platform-prime umbrella contracts. Tier-two electro-optics specialists face margin compression as Lockheed Martin and Northrop Grumman internalize gimbal and detector production. This concentration is most visible in United States Navy F/A-18 and F-35 upgrade programs, where sole-source targeting pod awards have displaced competitive subsystem sourcing.
Military Electro-Optics/Infrared (EO/IR) Systems Market Segmentation
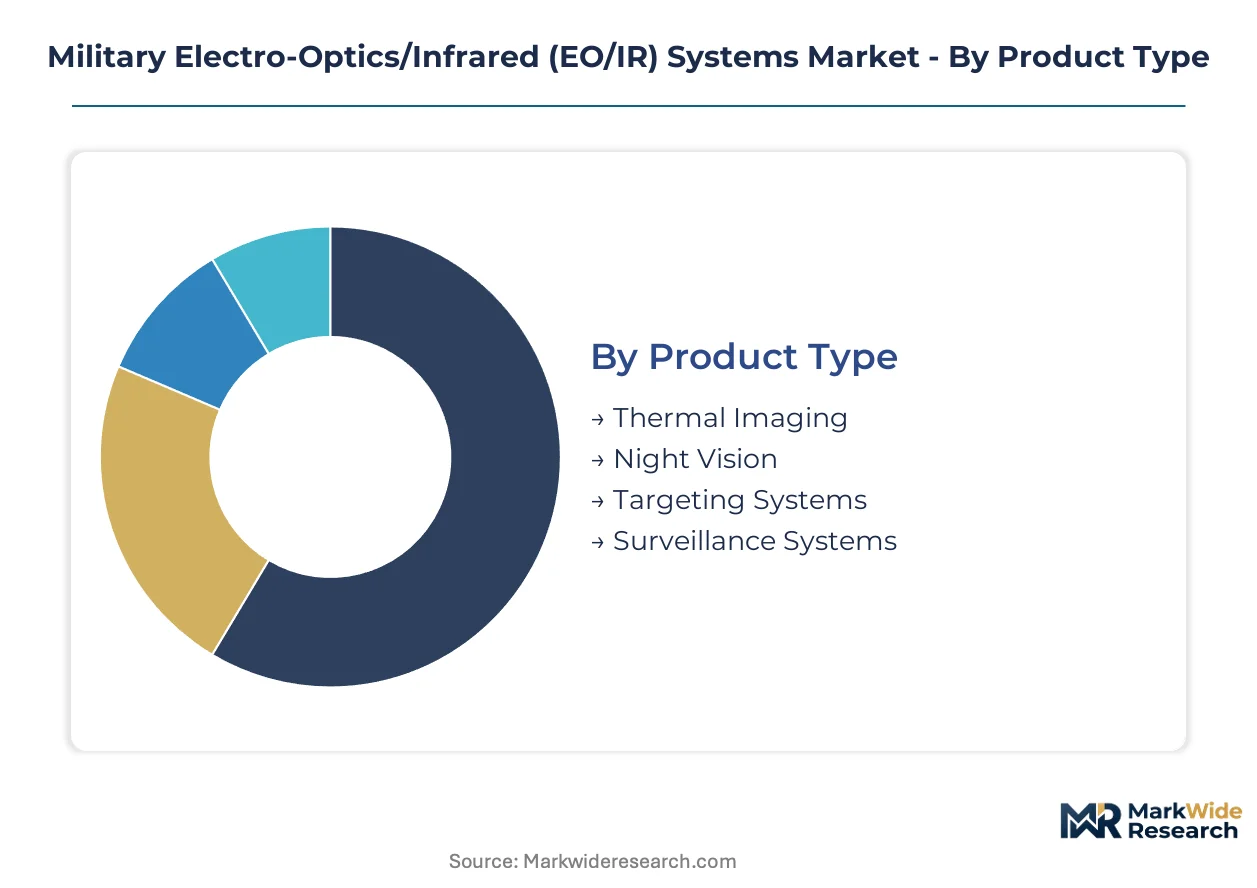
Military EO/IR procurement divides sharply between platform-integrated systems and dismounted or fixed-site deployments. Understanding these segment boundaries clarifies where technology investments concentrate and where supply chain bottlenecks threaten program schedules.
Product Type:
Use-case spectrum spans dismounted soldier enhancement through strategic persistent surveillance, with cost and integration complexity rising across that range.
- Targeting Systems:Cooled detector arrays mounted on stabilized gimbals deliver precision laser designation for fighter aircraft and rotary-wing platforms. NATO fighter upgrade programs in Germany, Italy, and Poland drive concentrated demand for multi-spectral pods with 8-12 μm long-wave infrared capability. Congressional defense appropriations prioritize these systems for infrared countermeasure modernization, insulating domestic suppliers from foreign competition.
- Thermal Imaging:Vanadium oxide microbolometers operate without cryogenic cooling, enabling widespread deployment across ground vehicles and handheld devices. Mature supply chains achieve cost efficiencies that support volume expansion in United States Army and Marine Corps equipment refresh cycles. Manufacturing repeatability constraints on quantum dot alternatives preserve microbolometer dominance in near-term procurement.
- Night Vision:Image intensification tubes amplify residual light for dismounted infantry operations.
- Surveillance Systems:Persistent ground-based monitoring generates aggregate volume through border monitoring requirements in United States, Israel, and South Korea.
The dominant share belongs to Thermal Imaging, while Targeting Systems is closing the gap fastest through precision-strike modernization.
Technology:
Cost tier separation runs from uncooled, low-unit-cost microbolometers through cryogenically cooled mercury cadmium telluride and emerging quantum dot architectures.
- Quantum Dots:Tunable intersubband transitions enable operating temperature flexibility without mechanical cryocoolers. Naval aviation programs in the United States and United Kingdom evaluate uncooled alternatives for maritime patrol endurance missions. Epitaxial growth refinements promise to render obsolete the size-weight-power burdens that currently constrain tactical platform designs.
- Microbolometers:Thermal resistance changes in vanadium oxide thin films detect infrared radiation without cooling infrastructure. Foundry concentration in the United States and France supports cost curves that enable widespread surveillance and targeting deployment. Supply vulnerability remains limited for this segment due to dual-source substrate availability.
- Passive Infrared:Detects thermal emissions from targets without active illumination, minimizing detection risk.
- Active Infrared:Employs laser or LED illumination for enhanced identification range in specific engagement scenarios.
Microbolometers command installed base leadership, though Quantum Dots is expanding most quickly through epitaxial yield improvements.
End User:
Customer type determines specification stringency, with defense forces imposing ITAR-controlled requirements that fragment supplier eligibility.
- Defense Forces:Formal military services specify hardened systems with electromagnetic interference shielding and nuclear survivability. United States Department of Defense distributed sensing architectures under Joint All-Domain Command and Control redirect investment toward networked EO/IR nodes. Procurement consolidation under platform-prime umbrella contracts compresses margins for tier-two subsystem specialists.
- Security Agencies:Border patrol and coast guard organizations prioritize persistent monitoring over precision targeting.
- Research Institutions:National laboratories advance focal plane array materials and signal processing algorithms.
- Private Contractors:Security firms and training organizations acquire commercial derivatives with reduced classification requirements.
Defense Forces anchor procurement value, while Security Agencies is gaining share fastest through persistent border monitoring expansion.
Application:
Volume concentrates in defensive perimeter tasks, while offensive reconnaissance commands premium unit economics.
- Reconnaissance:Deep-penetration missions demand lightweight, long-range sensors with low probability of intercept. Israeli Air Force and Royal Air Force programs emphasize compact gimbal designs for unmanned platforms. Stabilized turret expertise at Northrop Grumman and Lockheed Martin internalization of precision mechanical production shapes competitive access.
- Border Security:Ground-based towers and aerostats require continuous operation with minimal maintenance access. United States Customs and Border Protection and Saudi Border Guard generate aggregate volume that outpaces platform-limited targeting pod growth. EU AI Act conformity requirements for autonomous track classification compress development timelines for multinational program participation.
- Threat Detection:Missile warning and hostile fire indication systems protect mobile platforms.
- Situational Awareness:Distributed aperture sensors cue defensive countermeasures and pilot vision systems.
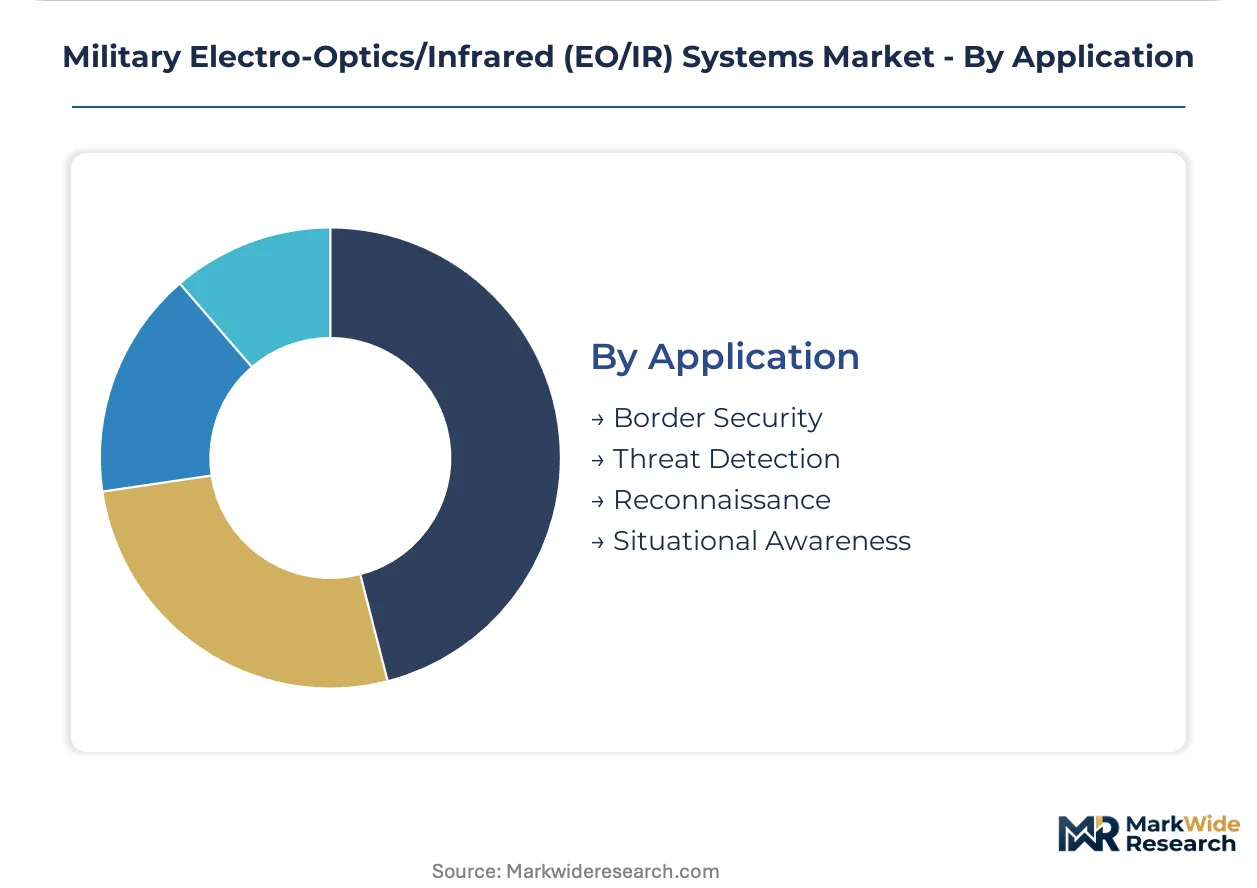
Border Security leads aggregate deployment, though Reconnaissance is climbing the fastest through unmanned platform proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Department of Defense anchors procurement value through ITAR-controlled programs that redirect allied nation sourcing patterns. Congressional defense appropriations prioritize domestic infrared countermeasure modernization, insulating domestic suppliers from foreign competition while fragmenting technology transfer eligibility.
United States
Fighter aircraft upgrade programs and distributed aperture sensor networks drive concentrated demand. The Department of Defense's Joint All-Domain Command and Control framework mandates networked EO/IR node integration. Arizona and Florida host prime contractor final assembly operations for multi-spectral targeting pods.
Germany
NATO fighter modernization programs require cooled detector arrays for precision strike capabilities. EU AI Act conformity requirements compress development timelines for autonomous targeting algorithms. Bavaria's defense industrial cluster coordinates multinational subsystem integration for Eurofighter upgrades.
Israel
Unmanned platform proliferation and border surveillance modernization generate dual-track demand. The country's national defense procurement office prioritizes compact gimbal designs for persistent monitoring missions. Tel Aviv metropolitan engineering centers advance stabilized turret architectures for export markets.
United Kingdom
Maritime patrol endurance missions evaluate uncooled quantum dot alternatives for size-weight-power reduction. Ministry of Defence procurement references CE marking and algorithmic transparency standards. Scotland's aerospace corridor hosts focal plane array testing facilities for naval aviation programs.
South Korea
Indigenous fighter development and coastal surveillance expansion drive cooled detector procurement. The country's national defense acquisition program administration prioritizes domestic foundry capacity for infrared substrates. Seoul-Incheon industrial complexes integrate microbolometer supply chains for regional export.
Military Electro-Optics/Infrared (EO/IR) Systems Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another, producing a bifurcated structure where prime contractors internalize subsystem production while tier-two specialists face margin compression. Defense procurement consolidation under platform-prime umbrella contracts has displaced competitive sourcing for major programs. Three archetypes dominate: vertically integrated primes controlling gimbal and detector production; stabilized turret specialists with proprietary mechanical expertise; and distributed aperture integrators linking sensors to command networks. Competitive moves center on backward integration into focal plane array foundries and software-defined sensor fusion architectures.
Among US-based defense primes, Lockheed Martin Corporation and Northrop Grumman Corporation exemplify the vertically integrated archetype through captive control over precision mechanical production. Raytheon Technologies Corporation occupies a position linking distributed aperture sensors to missile defense cueing networks. These three anchors illustrate how ITAR-controlled technology retention and sole-source awards reshape subcontractor access.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| Raytheon Technologies Corporation |
| L3Harris Technologies Inc. |
| BAE Systems plc |
| Teledyne FLIR LLC |
| Thales Group |
| Elbit Systems Ltd. |
| Leonardo S.p.A. |
| Others |
Supply & Pricing Matrix
Mercury cadmium telluride foundry undercapacity in the United States concentrates pricing power among domestic substrate suppliers, forcing prime contractors to accept cost-plus contracting terms while accelerating backward integration into focal plane array production. This utilization squeeze propagates through the value chain, elevating unit economics for cooled detector arrays while compressing margins for tier-two gimbal specialists lacking captive supply.
Pricing Analysis
Transatlantic price spreads of 15-30% separate ITAR-compliant US systems from European CE-marked equivalents, reflecting certification-grade differentiation and domestic content mandates. Three-tier pricing structure across ITAR-restricted, NATO-qualifying, and commercial-derivative levels segments buyer access, with defense forces least price-sensitive and private security contractors most responsive to cost compression. Pricing pressure stems from sole-source consolidation under platform-prime umbrella contracts, eroding competitive subsystem bidding. Volume-scale discounts dominate long-term Department of Defense procurement, while customization premiums attach to rapid fielding requests.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for rare-earth magnet components in stabilized gimbal motors. Geographic supply concentration centers on the United States for mercury cadmium telluride substrates, France for vanadium oxide microbolometer foundries, and South Korea for precision optical coatings. Raw material dependencies span indium antimonide crystals, germanium lenses, and cryocooler helium charges. Single-source vulnerability persists in epitaxial growth equipment for quantum dot arrays. Distribution runs through prime contractor final assembly facilities in Arizona, Florida, and Bavaria with direct military logistics integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined sensor fusion and predictive maintenance contracts expand faster than hardware replacement cycles, repositioning EO/IR value capture toward recurring service revenue streams. This service-attach dynamic favors vendors with installed base visibility and platform-integrator relationships.
For Market Incumbents: Pre-empt quantum dot displacement of cryocooled architectures by acquiring epitaxial growth specialists before yield improvements democratize access. Lock sole-source positions on Joint All-Domain Command and Control node integration to forestall margin compression from open-architecture competition. Prioritize cleared workforce pipelines in Arizona and Florida engineering clusters to defend program execution timelines against staffing delays.
For New Entrants and Emerging Players: Pursue EU AI Act conformity certification as a wedge into European Defence Agency multinational programs, where algorithmic transparency requirements have compressed incumbent development schedules. Target border surveillance persistent monitoring applications in Israel and South Korea, where aggregate volume expansion outpaces platform-limited targeting pod saturation. Lead with uncooled quantum dot alternatives for maritime patrol endurance missions to bypass cryocooler supply bottlenecks.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because platform-prime umbrella contracting concentrates procurement leverage with three vertically integrated anchors, squeezing tier-two specialists into distressed sale positions. Acquisition target archetype: stabilized turret specialists with proprietary mechanical expertise and existing NATO qualification. Watch quantum dot epitaxial yield improvements as the inflection signal—manufacturing repeatability at scale would render mechanical cryocoolers obsolete and reshuffle competitive positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Focal Plane Array Foundries | Captive mercury cadmium telluride supply insulates Lockheed Martin and Northrop Grumman from substrate shortages. |
| EU AI Act Algorithmic Conformity Investment | Explainability thresholds for autonomous targeting compress development timelines for European Defence Agency access. |
| Distributed Aperture Sensor Network Deployment | Joint All-Domain Command and Control integration creates software-defined recurring revenue beyond hardware sales. |
| Quantum Dot Epitaxial Yield Scale-Up | Operating temperature flexibility without cryocooling renders mechanical cryocoolers obsolete in maritime patrol applications. |
| Cleared Workforce Pipeline Development | Security clearance timelines for electro-optics engineers in Arizona and Florida determine program execution competitiveness. |
Research Methodology
Operator-level perspectives from program managers at prime contractors, procurement officers at the Department of Defense, electro-optics engineers at national laboratories, and subsystem specialists at tier-two suppliers anchored the qualitative base. Secondary validation drew from congressional defense appropriations documentation, ITAR-controlled export license filings, European Defence Agency tender specifications, and SEC 10-K disclosures from publicly traded defense primes. Bottom-up unit economics modeling triangulated against top-down procurement budget allocations across the analysis window.
Scenario-bracketing around Joint All-Domain Command and Control adoption pace and quantum dot epitaxial yield improvement timelines bounded the forecast range. Segmentation dimensions spanned product type, technology architecture, end-user classification, and application mission profile with regional regulatory cluster overlays. CAGRs derived from procurement pipeline visibility and platform upgrade cycle timing. Industry-specific inputs included fighter aircraft fleet modernization schedules and border surveillance tower deployment rates.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by tier-two specialists or rapid quantum dot yield breakthroughs by non-traditional entrants would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Surveillance
Land Based Military Electro Optical & IR Systems Market
Military Surveillance
Global Airborne Warning and Control System Market
Military Surveillance
Global Military Electro-Optical and Infrared Systems Market
Military Surveillance
Electronically Scanned Array Radar Market
Military Surveillance
Global Military Thermal Imaging Market
Military Surveillance
Target Acquisition Systems Market
Military Surveillance
Military Jammer Market
Military Surveillance
North America Hydrographic Survey Equipment Market
Military Surveillance
Europe Hydrographic Survey Equipment Market
Military Surveillance
Laser Telemetry Binoculars Market
Military Surveillance
Drone Surveillance Platform Market
Military Surveillance
Maritime Surveillance Market
Military Surveillance
North America Signals Intelligence (SIGINT) Market
Military Surveillance
Global Mine Detection System Market
Military Surveillance
Long Range Radar Systems Market
Military Surveillance
Sea-Based Military Electro-Optical and Infrared Systems Market