
 Drinking Water Pipe Repair Market | 2026-2036
Drinking Water Pipe Repair Market Size, Share, and Industry Trends Forecast 2026-2036
Drinking Water Pipe Repair Market Analysis
Modular repair kits are decoupling traditional bundled service contracts, letting municipalities procure trenchless liners and joint seals separately from installation labor. Mueller Water Products leverages its foundry heritage to anchor ductile iron replacement programs across the Midwest. Uponor competes through cross-linked polyethylene expertise in residential repiping. Pure-Line Plumbing specializes in epoxy relining applications for commercial building retrofits.
Drinking water pipe repair encompasses the restoration, sealing, or replacement of pressurized potable water distribution infrastructure, typically involving cured-in-place pipe liners with minimum 3-millimeter structural wall thickness or mechanical clamps rated for 150 psi operating pressure. The practice extends service life without full excavation, preserving road surfaces and reducing service disruption. Trenchless technology leads the technology dimension as municipalities prioritize non-disruptive methods beneath urban corridors. Pipe relining represents the fastest-expanding repair type as epoxy and felt-composite liners gain acceptance for corrosion sealing. Municipalities occupy the dominant end-user position given their stewardship of buried distribution networks and access to federal infrastructure funding streams.
The EPA Lead and Copper Rule and AWWA C600 installation standards shape material selection and contractor qualification requirements across the United States. State-level primacy agencies enforce maximum contaminant level compliance, driving systematic inventory and replacement of lead service lines. OSHA excavation safety protocols and DOT traffic control regulations add compliance layers to open-cut repair methods. Stakeholders must monitor the pace of SRF and BIL fund disbursement against contractor capacity constraints to calibrate procurement timing and workforce scaling.
Market Dynamics
Municipal procurement departments are decoupling materials from labor, breaking bundled service contracts that once locked cities into single-source trenchless rehabilitation providers. This unbundling is redistributing margin across the value chain and forcing contractors to compete on installation speed rather than material markup.
Growth Catalysts
- EPA Lead and Copper Rule revisions:Federal mandates compel systematic inventory and replacement of lead service lines across thousands of municipal water systems.
- Trenchless cured-in-place pipe technology:CIPP liners with structural wall thickness above 3 millimeters enable road surface preservation and service continuity beneath urban corridors.
- Great Lakes region infrastructure age:Century-old cast-iron networks in Milwaukee, Cleveland, and Detroit require urgent structural intervention.
Market Restraints
- Epoxy resin price volatility:Petrochemical feedstock fluctuations compress margins for CIPP liner manufacturers.
- Specialized contractor concentration:Trenchless installation expertise clusters in the Upper Midwest, creating regional capacity bottlenecks.
- AWWA C600 qualification barriers:Ductile iron installation certification requirements limit contractor pool expansion.
Strategic Opportunities
- Bipartisan Infrastructure Law disbursement:SRF funding streams create procurement windows for municipalities with deferred maintenance backlogs.
- Commercial building epoxy relining:High-rise residential and hospital retrofits represent underpenetrated verticals beyond municipal utilities.
- Cross-linked polyethylene residential repiping:PEX materials gain share in single-family home service line replacement.
Industry Challenges
- CIPP installer certification timelines:NASSCO MACP and PACP training requirements extend workforce scaling cycles.
- Legacy cast-iron network mapping:Incomplete as-built records complicate pre-rehabilitation condition assessment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drinking Water Pipe Repair Market |
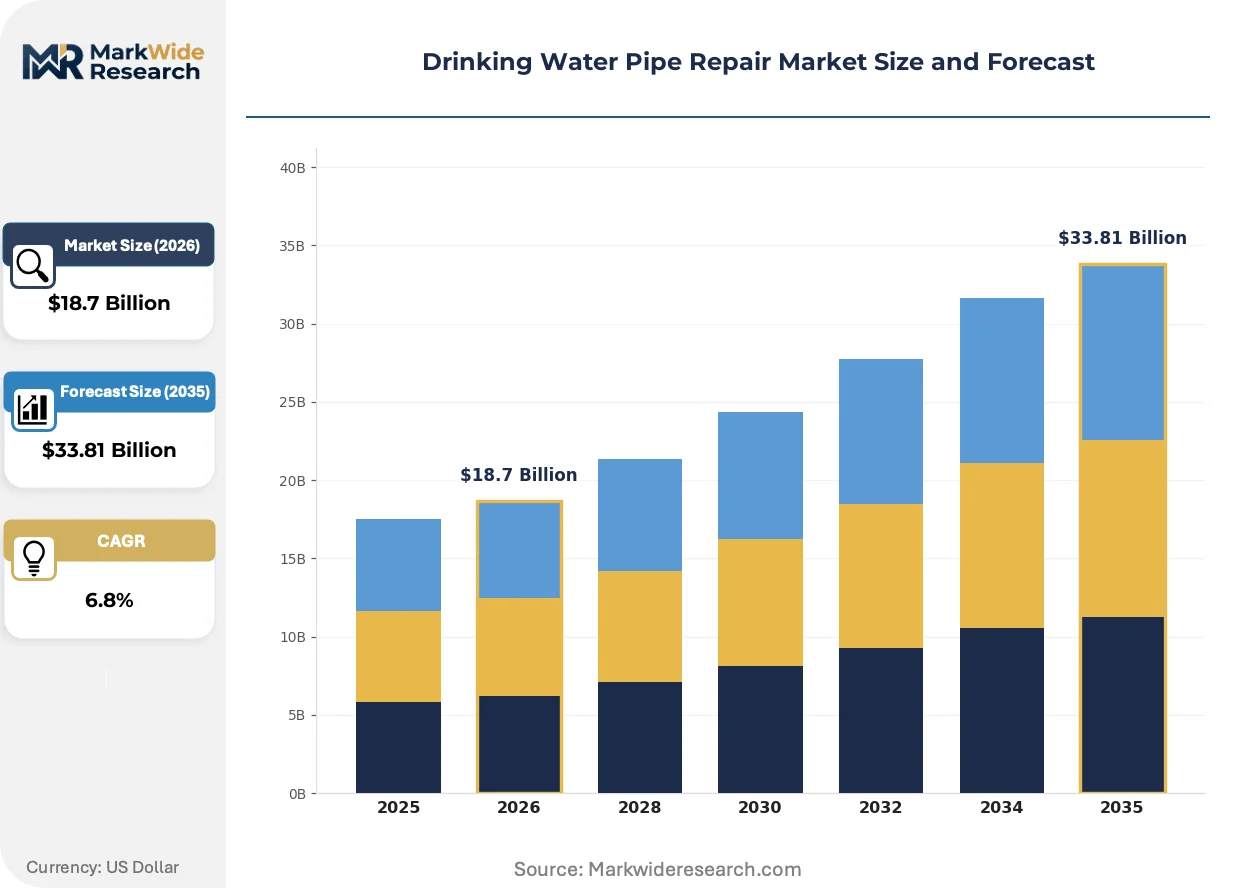
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Repair Type: Leak Repair, Joint Replacement, Corrosion Repair, Structural Reinforcement Material: Polyethylene, PVC, Ductile Iron, Copper End User: Municipalities, Commercial Buildings, Residential Properties, Industrial Facilities Technology: Trenchless Technology, Pipe Relining, Traditional Repair, Inspection Technology |
| Companies Covered | Bell Cow Services, Pure-Line Plumbing, Sweetwater Plumbing, Uponor, Michael & Son, Progressive Service Company, Poseidon Plumbing, Mueller Water Products, Streamline Plumbing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drinking Water Pipe Repair Market Emerging Trajectories
Material science advances and procurement digitization are compressing project timelines while elevating performance specifications for pressure-rated rehabilitation systems.
UV-cured fiberglass CIPP liners are expanding into high-pressure transmission mains previously reserved for open-cut replacement. Water utilities in Texas and Arizona are specifying these liners for 150 psi operating environments. The technology is expanding into steel and concrete cylinder pipe rehabilitation, displacing cement-mortar lining for corrosion protection.
The EPA Lead and Copper Rule revisions are accelerating lead service line replacement mandates across all 50 states. State primacy agencies must enforce maximum contaminant level compliance through systematic inventory deadlines. Midwestern cities with pre-1950 housing stock face the steepest replacement schedules and are pre-qualifying contractors eighteen months ahead of construction windows.
Modular component sourcing is fragmenting traditional bundled contracts. Municipal procurement officers now issue separate RFPs for liner materials, joint seals, and installation labor. This unbundling is most advanced in Ohio and Michigan, where cooperative purchasing agreements let smaller cities aggregate demand and bypass incumbent contractor relationships.
Drinking Water Pipe Repair Market Segmentation
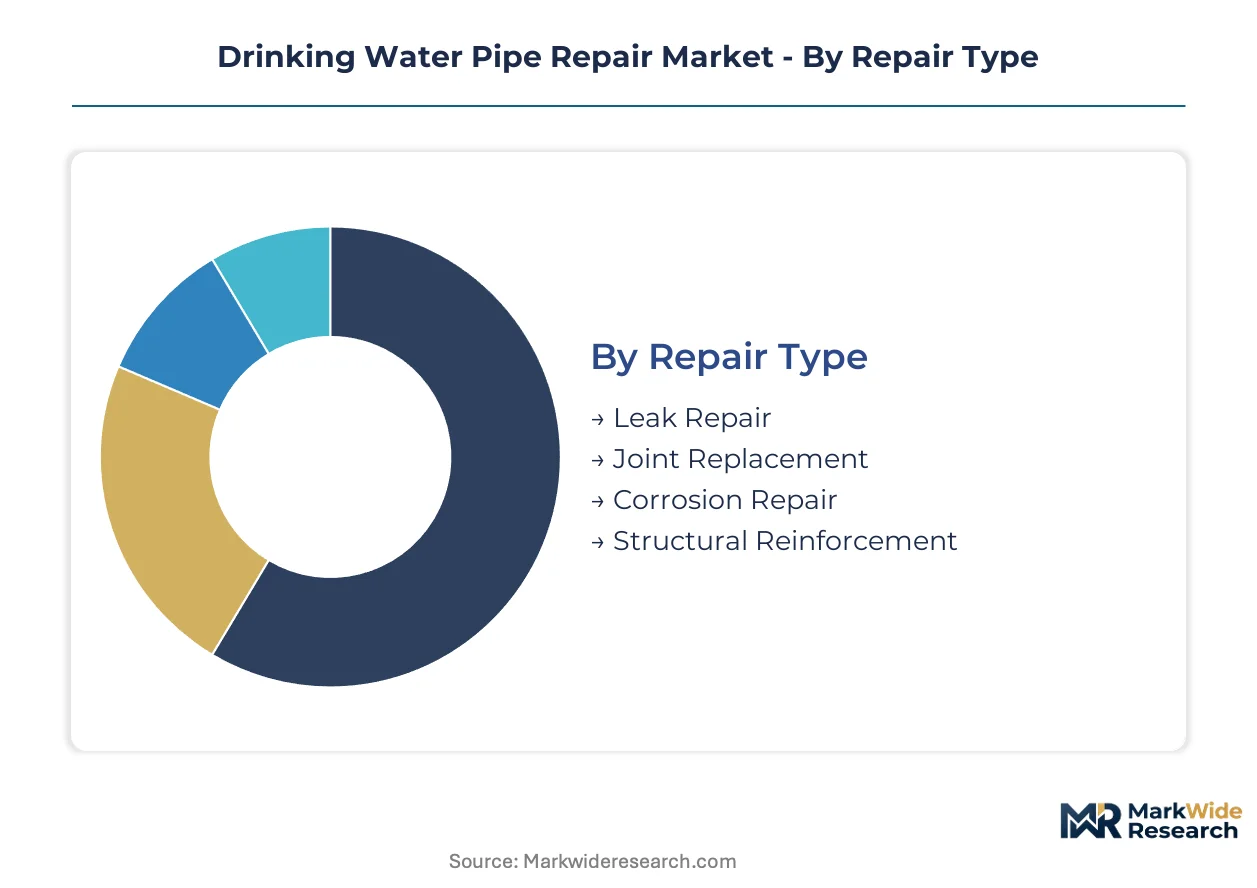
Segmentation in the drinking water pipe repair market reveals how procurement fragmentation is redistributing margin across specialized contractors and material suppliers. Understanding these divides clarifies where unbundling creates entry points for new competitors.
Repair Type:
Customization intensity varies sharply across repair types, from standardized clamp installations to engineered structural interventions requiring site-specific design.
- Leak Repair:Mechanical clamps and compression couplings address circumferential cracks and pinhole failures in pressurized mains. Demand clusters in the Great Lakes region where Milwaukee, Cleveland, and Detroit utilities confront century-old cast-iron networks with deteriorated bell-and-spigot joints.
- Structural Reinforcement:Cured-in-place pipe liners with minimum 3-millimeter structural wall thickness restore full pressure capacity without excavation. CIPP contractors in Ohio and Michigan are pre-qualifying crews eighteen months ahead of construction windows to meet EPA Lead and Copper Rule replacement mandates.
- Joint Replacement:Bell-and-spigot rehabilitation using elastomeric gaskets or welded sleeves.
- Corrosion Repair:Epoxy lining and cement-mortar applications for internal diameter restoration.
Most installed capacity flows through Leak Repair. Expansion is steepest in Structural Reinforcement.
Material:
Material selection tracks pressure rating requirements and soil chemistry, with cost tiers separating transmission mains from distribution laterals.
- Ductile Iron:Centrifugally cast iron with nodular graphite morphology delivers 350 psi pressure ratings for transmission mains. AWWA C600 installation standards govern joint assembly and hydrostatic testing, limiting contractor pool expansion in the Upper Midwest where specialized crews concentrate.
- Polyethylene:High-density and cross-linked formulations enable trenchless slip-lining and directional drilling beneath urban corridors. PEX materials gain share in single-family home service line replacement programs across suburban municipalities with lead inventory deadlines.
- PVC:C900 and C905 pressure pipe for gravity and low-pressure applications.
- Copper:Type K and L tubing for building service lines and interior plumbing.
Volume concentrates in Ductile Iron for municipal transmission. Polyethylene is climbing the fastest in residential service line replacement.
End User:
Customer type determines procurement complexity, from federal-fund-driven municipal RFPs to owner-direct commercial contracts.
- Municipalities:Public water utilities steward buried distribution networks and access State Revolving Fund and Bipartisan Infrastructure Law financing. Procurement officers in Ohio and Michigan now issue separate RFPs for liner materials, joint seals, and installation labor, fragmenting traditional bundled contracts.
- Commercial Buildings:High-rise residential towers, hospitals, and institutional facilities require epoxy relining for corrosion sealing without occupancy disruption. This vertical remains underpenetrated relative to municipal utilities, with specialized contractors targeting vertical riser and branch line retrofits.
- Residential Properties:Single-family service line replacement and interior repiping.
- Industrial Facilities:Process water and cooling water system maintenance.
Procurement volume flows through Municipalities. Commercial Buildings show the steepest expansion trajectory as building owners accelerate deferred maintenance.
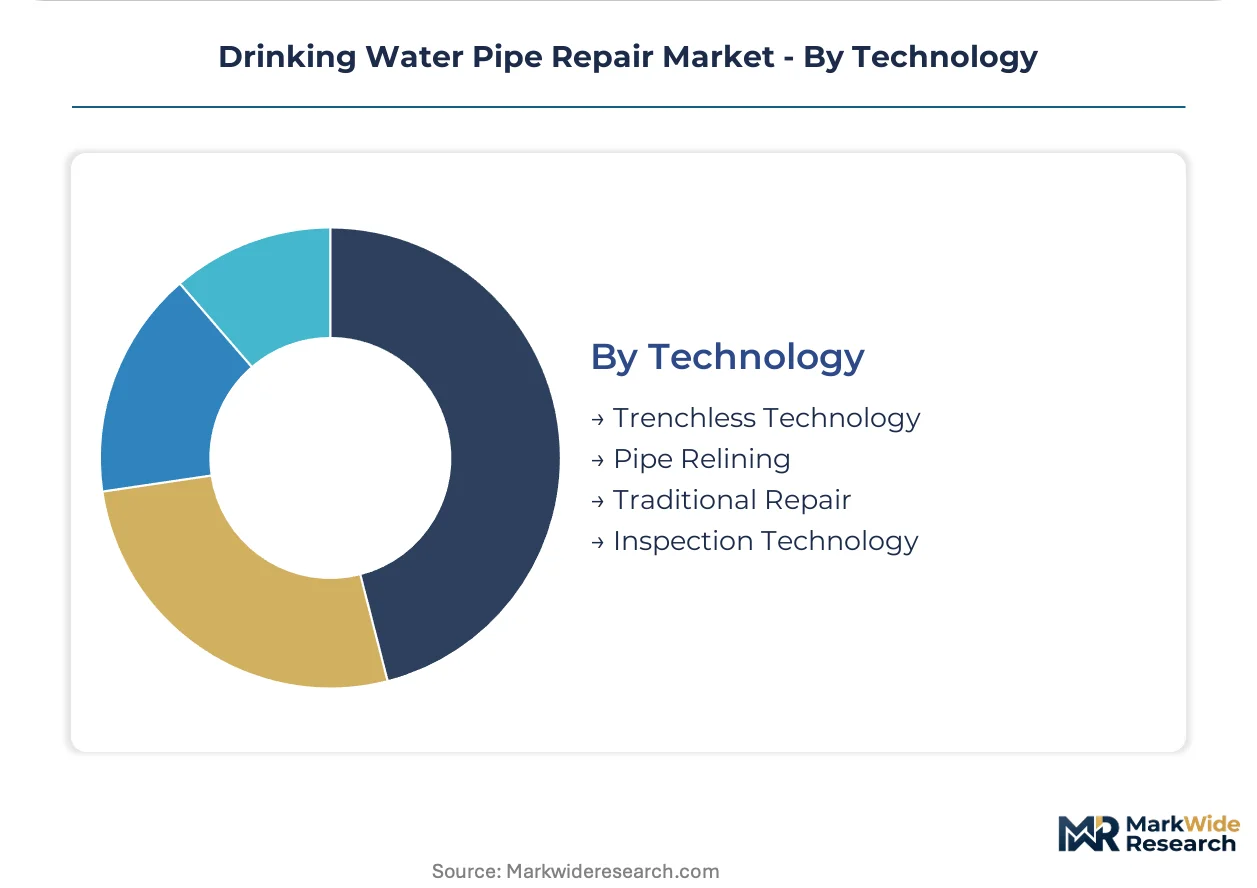
Technology:
Technology maturity separates legacy open-cut methods from capital-intensive trenchless systems with steep installer certification barriers.
- Trenchless Technology:Directional drilling, pipe bursting, and slip-lining eliminate surface excavation beneath roads and railways. UV-cured fiberglass CIPP liners are expanding into 150 psi transmission mains in Texas and Arizona, displacing cement-mortar lining for steel and concrete cylinder pipe rehabilitation.
- Pipe Relining:Epoxy and felt-composite liners create structural new pipe within host mains. Felt-composite saturation with vinyl ester or epoxy resin enables corrosion sealing and pressure containment, though petrochemical feedstock price volatility compresses manufacturer margins.
- Traditional Repair:Open-cut excavation with backfill and surface restoration.
- Inspection Technology:CCTV, sonar, and laser profiling for pre-rehabilitation condition assessment.
Most project volume flows through Trenchless Technology. Pipe Relining is expanding most quickly as acceptance spreads for pressure-rated rehabilitation systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The modern trenchless rehabilitation industry traces its commercial origins to British civil engineering innovations of the 1970s, where cured-in-place pipe technology first demonstrated structural renewal without surface excavation. This lineage shaped subsequent regulatory frameworks and contractor certification systems that now govern municipal procurement across developed markets.
United States
Great Lakes utilities confront century-old cast-iron networks in Milwaukee, Cleveland, and Detroit where bell-and-spigot joint deterioration drives emergency repair volume. EPA Lead and Copper Rule revisions compel systematic lead service line inventories with replacement deadlines stretching through 2035. Ohio and Michigan procurement officers now unbundle liner materials from installation labor, fragmenting traditional single-source contracts.
Germany
Rhineland municipal utilities manage post-war steel and ductile iron infrastructure now exceeding seventy years of service life. The country's national water regulator enforces strict drinking water quality standards that accelerate corrosion-related rehabilitation cycles. Bavarian cities including Munich and Nuremberg specify UV-cured fiberglass liners for pressure-rated transmission main renewal beneath dense urban cores.
United Kingdom
London's Victorian-era cast-iron distribution network suffers elevated leakage rates that drive non-revenue water reduction targets. The national economic regulator mandates performance commitments linking infrastructure investment to customer bill controls. Thames Water and regional utilities in the Midlands deploy trenchless slip-lining beneath historic road surfaces where open-cut excavation faces heritage preservation constraints.
Japan
Tokyo's earthquake-resistant water grid requires seismic joint rehabilitation and ductile iron replacement programs across Kanto region distribution networks. METI infrastructure resilience directives prioritize service continuity during seismic events. Osaka-area utilities specify epoxy relining for aged steel mains in high-density commercial corridors where excavation disrupts rail and utility interdependencies.
Australia
Sydney and Melbourne utilities confront cast-iron and asbestos-cement pipe networks installed during mid-twentieth century urban expansion. State-level water regulators enforce infrastructure leakage reduction targets that elevate trenchless rehabilitation priority. Queensland regional utilities deploy directional drilling and pipe bursting beneath flood-prone topography where surface restoration costs compound seasonal weather damage.
Drinking Water Pipe Repair Market Vendor Landscape
The competitive structure tilts toward specialized contractors with certified installation crews rather than integrated material manufacturers. Municipal procurement unbundling has redistributed margin from bundled service providers toward standalone liner suppliers and independent installation firms. Three archetypes dominate: legacy foundry-based ductile iron suppliers, cross-linked polyethylene material specialists, and epoxy relining contractors targeting commercial verticals. Dominant competitive moves include geographic crew pre-qualification ahead of funding disbursement windows and portfolio diversification from municipal utilities into commercial building retrofits.
Among North American service contractors, Mueller Water Products, Uponor, and Pure-Line Plumbing occupy distinct positioning vectors. Mueller Water Products exemplifies the foundry-heritage archetype anchoring ductile iron replacement programs. Uponor represents material science specialization through cross-linked polyethylene expertise. Pure-Line Plumbing sits within the commercial-focused relining tier targeting building retrofit applications. Each archetype confronts different margin pressures as procurement fragmentation accelerates.
| Leading Market Players |
|---|
| Bell Cow Services |
| Pure-Line Plumbing |
| Sweetwater Plumbing |
| Uponor |
| Michael & Son |
| Progressive Service Company |
| Poseidon Plumbing |
| Mueller Water Products |
| Streamline Plumbing |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between AWWA C600-qualified ductile iron installers and uncertified general contractors splits pricing power across the Great Lakes market, concentrating premium margins with specialized crews while commodity trenchless labor faces persistent cost compression. This tier divergence manifests in procurement patterns: Ohio and Michigan municipalities now unbundle materials from installation, forcing price transparency on liner suppliers while allowing certified contractors to command project-based premiums tied to EPA Lead and Copper Rule compliance deadlines.
Pricing Analysis
Project-based contracting with performance-guarantee clauses dominates municipal procurement, separating premium-rated CIPP installers from commodity leak-repair providers. Price differentiation rests on NASSCO MACP/PACP certification status and structural liner thickness ratings above 3 millimeters. Cost compression in standard epoxy relining is intensifying because petrochemical feedstock volatility squeezes manufacturer margins. Municipal utilities show highest price sensitivity in bundled service contracts, while hospital and high-rise commercial clients absorb premium pricing for occupancy-preserving trenchless methods.
Supply Chain Analysis
Regional distribution centers in Ohio, Michigan, and Illinois anchor hub-and-spoke patterns for liner materials and mechanical repair components. Manufacturing concentration clusters in the United States for ductile iron foundries, Germany for UV-cured fiberglass systems, and China for epoxy resin feedstocks. Raw material dependencies include petrochemical-derived vinyl ester resins, nodular graphite iron ingots, and cross-linked polyethylene pellets. Single-source vulnerability in specialized CIPP liner manufacturing creates supply chain risk. Distribution runs through cooperative purchasing agreements and municipal procurement consortiums.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The drinking water pipe repair market functions as a regulatory compounder where EPA Lead and Copper Rule revision timelines lock in replacement demand through systematic inventory mandates across all fifty states.
For Market Incumbents: Deploy geographic crew pre-qualification ahead of SRF and BIL fund disbursement windows. Incumbents should secure NASSCO certification capacity in the Upper Midwest to defend against emerging specialized contractors from Texas and Arizona. Backward integration into epoxy resin saturation facilities preserves margin as procurement unbundling accelerates.
For New Entrants and Emerging Players: Municipal cooperative purchasing networks offer the most penetrable channel for liner material suppliers seeking to bypass incumbent contractor relationships. Commercial building epoxy relining for high-rise residential towers and hospital retrofits represents underpenetrated white space beyond municipal utilities. New entrants should pursue direct sales to facility engineering departments with turnkey occupancy-preserving proposals.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized CIPP contractors holding NASSCO MACP/PACP certification capacity in EPA enforcement-heavy states. Long-term viability hinges on replacement cycle duration tied to lead service line inventory deadlines. Acquisition targets should display crew scaling capability and pre-qualified municipal relationships. Watch BIL fund disbursement velocity against contractor capacity constraints as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Capacity Expansion | NASSCO MACP/PACP training programs secure EPA-mandated replacement contract eligibility in Ohio and Michigan. |
| Backward Integration into Resin Saturation | In-house liner manufacturing captures margin redistribution from unbundled municipal procurement patterns. |
| Commercial Building Vertical Entry | Hospital and high-rise residential relining diversifies revenue beyond SRF-dependent municipal utilities. |
| Cooperative Purchasing Network Participation | Aggregate demand aggregation bypasses incumbent contractor lock-in across smaller Midwestern cities. |
| UV-Cured Fiberglass Technology Licensing | 150 psi pressure-rated systems enable transmission main expansion in Texas and Arizona markets. |
Methodological Framework
Multiple input streams — primary interviews with municipal procurement officers, CIPP installation contractors, and epoxy liner manufacturing executives, alongside secondary validation through EPA enforcement records, AWWA technical standards, and SRF disbursement databases — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured procurement fragmentation patterns across Ohio and Michigan cooperative purchasing agreements. Secondary sources included NASSCO certification registries, state primacy agency lead inventory filings, and municipal bond prospectuses for infrastructure funding.
Data-stream reconciliation across repair type, material grade, end-user category, and technology maturity dimensions structured the analytical framework over the projection horizon. CAGRs were derived from replacement cycle modeling tied to EPA Lead and Copper Rule compliance deadlines and century-old cast-iron network deterioration curves. Industry-specific forecast inputs incorporated petrochemical feedstock price volatility coefficients and contractor certification capacity constraints.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to BIL fund appropriation continuity and epoxy resin supply chain stability. Forecasts reflect documented assumptions regarding municipal procurement unbundling velocity and NASSCO training pipeline throughput. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
US Plywood Market
Building & Construction Materials
North America Industrial Flooring Market
Building & Construction Materials
Wood Panel Market
Building & Construction Materials
India Roofing Market
Building & Construction Materials
North America Balustrade Market
Building & Construction Materials
Bollard Market
Building & Construction Materials
Porcelain Tiles Market
Building & Construction Materials
Non-Residential Polished Concrete Market
Building & Construction Materials
North America Concrete Superplasticizer Market
Building & Construction Materials
Global Formwork Market
Building & Construction Materials
Door Hardware Market
Building & Construction Materials
Global Rainscreen Cladding Market
Building & Construction Materials
Polished Concrete Market
Building & Construction Materials
Window Film Market
Building & Construction Materials
Softwood Lumber Market
Building & Construction Materials
Mexico Oriented Strand Board Market