
 Torque Limiting Couplings Market | 2026-2036
Torque Limiting Couplings Market Size, Share, and Industry Trends Forecast 2026-2036
Torque Limiting Couplings Market Analytics
Precision-grade torque limiting specification is redrawing competitive boundaries across the industry. KTR Systems GmbH leverages its German engineering heritage to dominate high-performance mechanical coupling segments. Rexnord Corporation sustains broad geographic coverage through extensive distributor networks. Chr. Mayr GmbH + Co. KG specializes in safety-critical applications where overload protection carries regulatory weight.
Torque limiting couplings are mechanical devices engineered to disconnect or slip at predetermined torque thresholds, typically incorporating spring-loaded friction plates, shear pins, or magnetic particle mechanisms to protect drivetrain components from damage. These devices serve primarily to prevent catastrophic equipment failure in rotating machinery by interrupting power transmission when operational loads exceed calibrated limits. Mechanical couplings occupy the largest installed base due to proven reliability and lower capital requirements, while smart couplings represent the fastest-expanding technology category as Industry 4.0 architectures embed sensor diagnostics directly into power transmission components. Electromechanical variants command premium positioning where real-time torque monitoring integrates with plant-wide control systems.
ISO 9001 quality management standards and EU Machinery Directive safety requirements shape product certification pathways for European suppliers, while OSHA machine guarding regulations in the United States mandate overload protection in heavy industrial settings. China's GB standards for mechanical transmission components increasingly influence export specifications as domestic manufacturers scale technical capabilities. Stakeholders must weigh smart coupling R&D commitments against the extended replacement cycles of conventional installed equipment when allocating capital across technology portfolios.
Market Dynamics
The torque limiting couplings market is undergoing a fundamental restructuring as predictive maintenance architectures displace reactive replacement cycles. Equipment manufacturers now specify embedded sensor compatibility as a baseline procurement criterion, forcing coupling suppliers to reengineer mechanical cores with digital instrumentation layers.
Growth Catalysts
- EU Machinery Directive overload mandates:Safety-critical machinery in German automotive stamping plants now requires certified torque limiting devices, creating specification pull-through across OEM supply tiers.
- Magnetic particle torque limiters:These electromechanical variants enable real-time torque telemetry integration with SCADA systems, accelerating adoption in continuous-process industries.
- China's industrial machinery upgrade wave:Domestic equipment manufacturers in Jiangsu and Zhejiang provinces are retrofitting legacy production lines with overload protection to reduce unplanned downtime.
Market Restraints
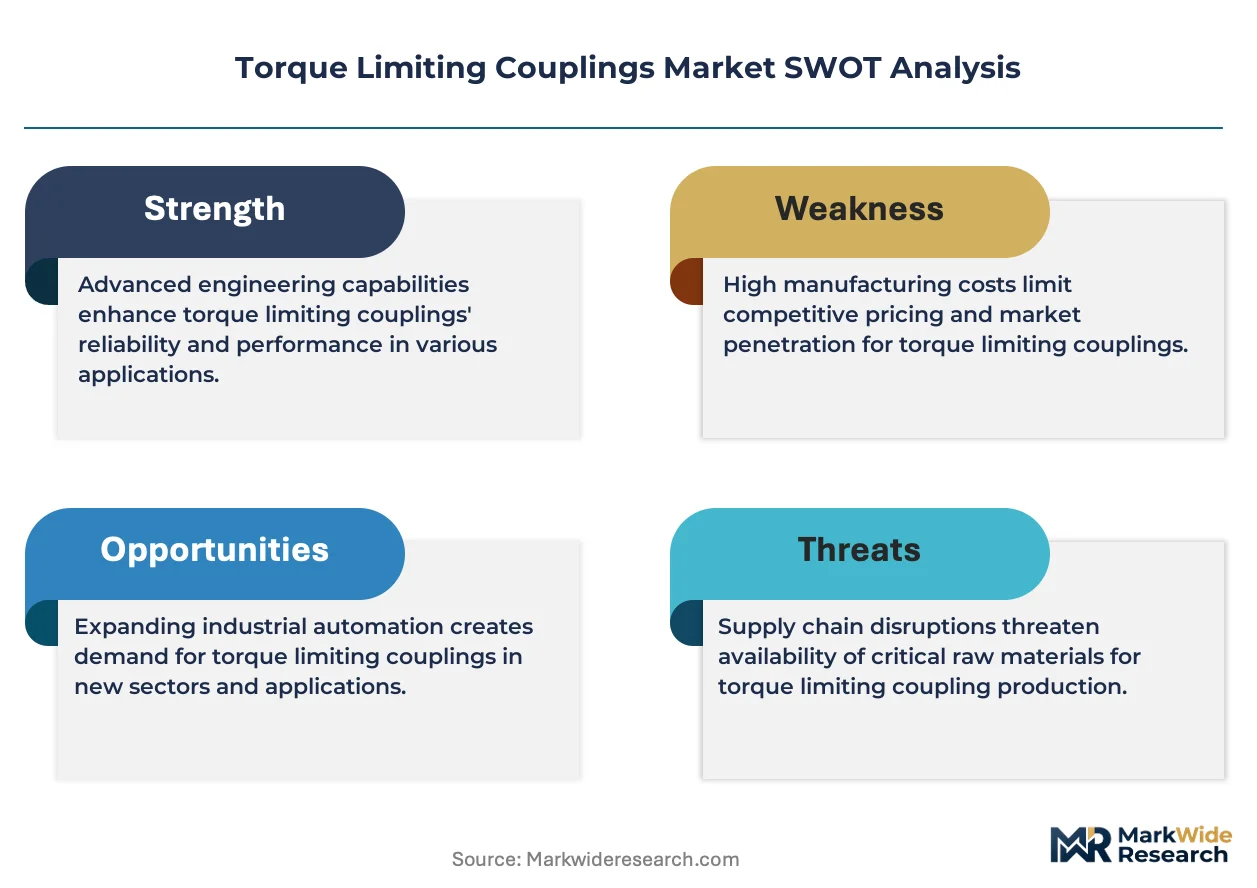
- Specialized alloy supply concentration:High-performance friction plate substrates depend on nickel-chromium-molybdenum steel mills concentrated in specific European and Asian supply basins.
- Smart coupling R&D capital intensity:Sensor miniaturization and wireless power harvesting for rotating components demand sustained engineering investment with extended payback horizons.
- Extended replacement cycles of mechanical couplings:Proven 15-20 year service lives in installed industrial equipment compress near-term upgrade demand.
Strategic Opportunities
- Wind turbine drivetrain protection:Offshore installations in the North Sea and Baltic Sea require maintenance-accessible torque limiting with remote diagnostic capability.
- Food and beverage hygienic design:Stainless steel torque limiters with sealed housings address washdown compliance in dairy processing and brewing applications.
- India's PLI scheme for capital goods:Domestic production incentives for precision mechanical components reduce import dependency for torque limiting devices in textile and packaging machinery.
Industry Challenges
- Mechatronics engineering talent scarcity:Coupling manufacturers struggle to recruit professionals fluent in both mechanical torque transmission physics and embedded firmware development.
- Legacy system integration complexity:Retrofitting smart couplings into pre-digital rotating machinery requires custom mechanical adapters and signal conditioning hardware.
- ISO 9001 and ATEX certification timelines:Multi-month approval processes for explosion-proof variants delay product launches in oil and gas applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Torque Limiting Couplings Market |
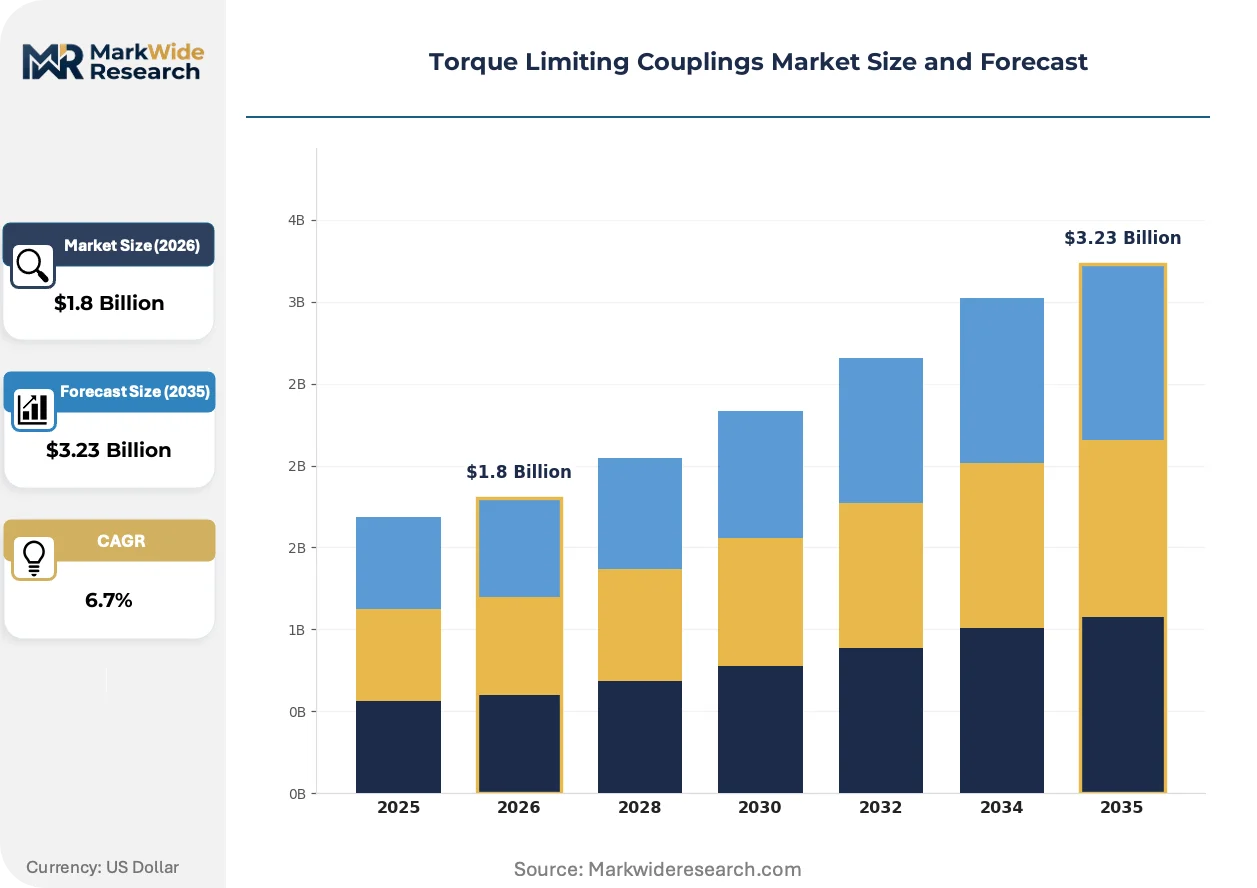
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromechanical, Hydraulic, Mechanical, Pneumatic Application: Industrial Machinery, Automotive, Aerospace, Marine End User: Manufacturers, Repair Shops, OEMs, Distributors Technology: Smart Couplings, Conventional Couplings, Adjustable Couplings, Fixed Couplings |
| Companies Covered | KTR Systems GmbH, Rexnord Corporation, Altra Industrial Motion Corp., Voith GmbH, Chr. Mayr GmbH + Co. KG, NU Teck Couplings, R+W Antriebselemente GmbH, Nexen Group, Inc., Regal Rexnord Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Torque Limiting Couplings Market Evolving Landscape
Digital instrumentation is penetrating mechanical power transmission components at an accelerating pace. Three interconnected developments are redefining how torque limiting couplings are engineered, specified, and monetized across industrial end-uses.
Sensor-embedded torque limiters are bifurcating the product landscape into connected and non-connected variants. Automotive powertrain test stands and semiconductor manufacturing equipment now specify real-time torque telemetry as standard. This capability split is compressing margins for purely mechanical suppliers while creating service revenue streams for diagnostics-enabled competitors.
REACH substance restrictions on hexavalent chromium plating are forcing friction surface treatment migrations. German and French coupling manufacturers are transitioning to tungsten carbide coatings and ceramic composite interfaces. The regulatory pressure is most acute in precision engineering clusters where export certification depends on EU environmental compliance.
Specification authority is migrating from maintenance departments to corporate engineering centers with centralized vendor rationalization mandates. Large industrial conglomerates in the United States and Germany now negotiate framework agreements covering torque limiting devices across multiple facility locations. This consolidation is visible most prominently in chemical processing and pulp and paper verticals where capital expenditure approval thresholds have risen.
Torque Limiting Couplings Market Segmentation
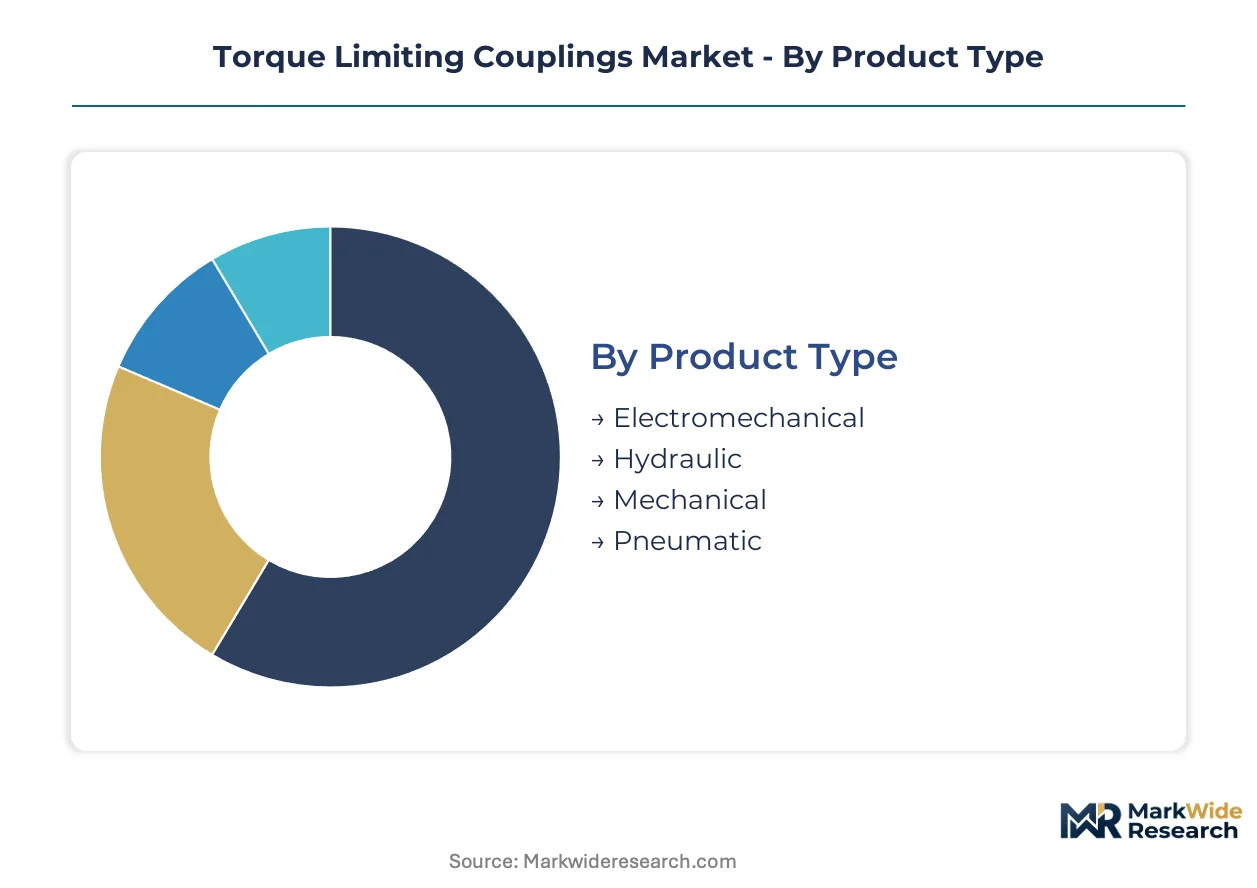
Torque limiting couplings serve divergent operational requirements across industrial verticals, with specification authority migrating toward centralized engineering procurement functions. Segmentation reveals how regulatory mandates, maintenance architectures, and supply chain configurations reshape vendor positioning across product categories.
Product Type:
EU Machinery Directive overload protection mandates and OSHA machine guarding requirements create divergent certification burdens across electromechanical and mechanical variants, with ATEX compliance timelines stretching to six months for explosion-proof electromechanical designs.
- Mechanical:Spring-loaded friction plates and shear pin configurations deliver calibrated torque interruption without external power dependencies. German automotive stamping plants and Chinese Jiangsu province equipment retrofits drive specification volume for proven 15-20 year service life designs.
- Electromechanical:Magnetic particle mechanisms enable real-time torque telemetry integration with SCADA and plant-wide control systems. Continuous-process industries in North Sea offshore wind installations specify these variants for remote diagnostic access.
- Hydraulic:Fluid-based torque transmission suits heavy-load industrial machinery with smooth engagement requirements.
- Pneumatic:Compressed air actuation serves applications demanding rapid disengagement cycles in packaging and textile machinery.
Established volume favors mechanical designs; emerging adoption favors electromechanical variants with embedded instrumentation layers.
Application:
Cost tier differentiation separates safety-critical specifications from standard industrial procurement, with aerospace and marine applications commanding 3-5x capital multiples over general machinery installations due to redundant protection requirements.
- Industrial Machinery:Conveyor systems, pumps, and compressors in chemical processing and pulp and paper verticals represent the installed base concentration. Predictive maintenance architectures now mandate sensor compatibility as baseline procurement criteria.
- Automotive:Powertrain test stands and stamping press protection systems specify precision-grade torque limiting with real-time telemetry. OEM supply tier consolidation in Germany creates framework agreement opportunities across multi-facility deployments.
- Aerospace:Flight control surface actuation and landing gear systems require redundant overload protection with documented traceability.
- Marine:Propulsion shaft protection and winch systems demand corrosion-resistant housings for saltwater exposure.
Procurement concentration clusters in industrial machinery; specification premiums concentrate in aerospace validation protocols.
End User:
Customer type determines specification authority location, with OEMs and manufacturers exercising centralized vendor rationalization while repair shops respond to reactive replacement cycles with shorter lead time requirements.
- Manufacturers:Capital expenditure approval thresholds have risen across large industrial conglomerates, consolidating torque limiting procurement into corporate engineering centers with multi-location framework agreements.
- OEMs:Original equipment manufacturers integrate torque limiting into drivetrain designs during development phases, locking in supplier relationships through production lifecycles.
- Repair Shops:Maintenance departments specify replacement units with compatibility constraints from legacy installed equipment.
- Distributors:Inventory positioning strategies balance mechanical coupling stock depth against smart coupling technical support requirements.
Volume flow concentrates through OEM channels; margin expansion concentrates in manufacturer direct relationships.
Technology:
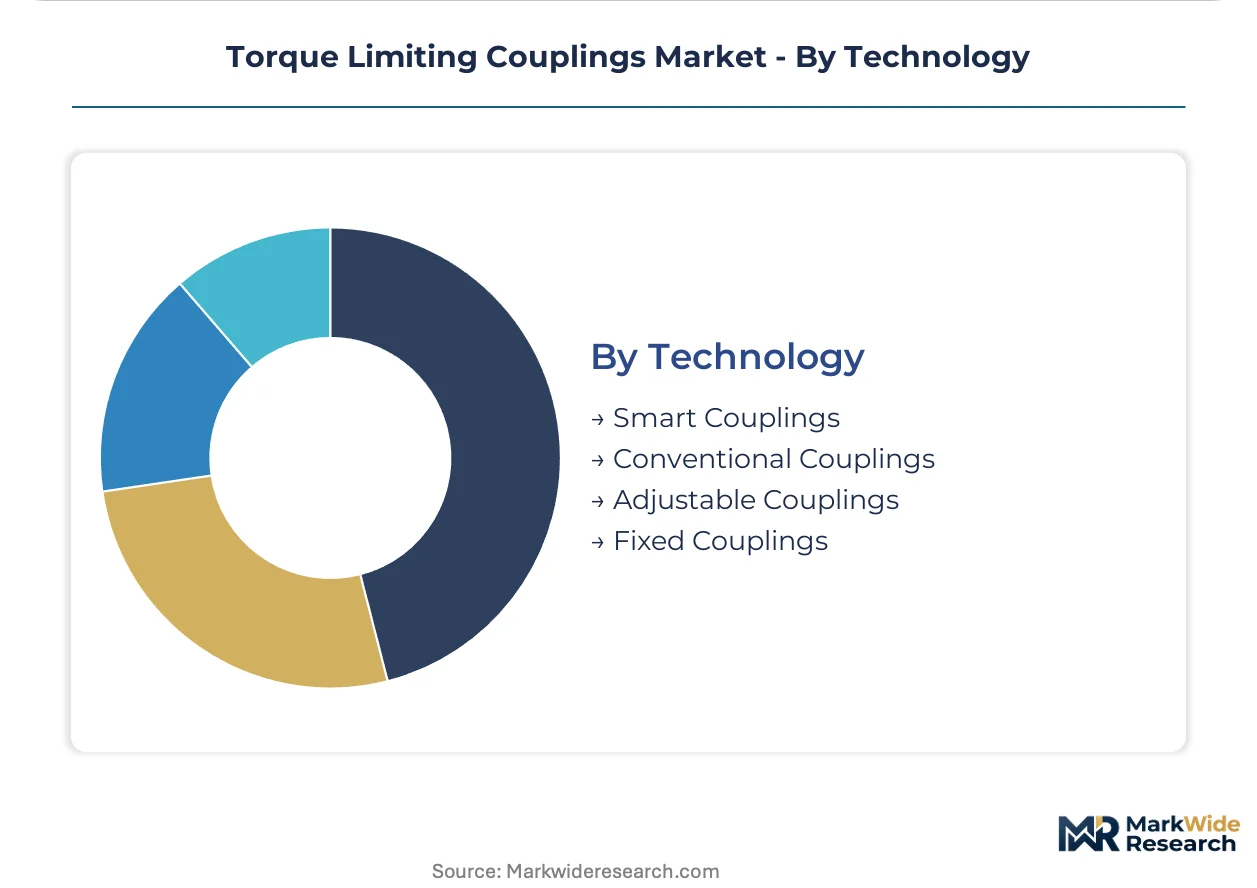
Maturity gradients separate decades-proven mechanical designs from emerging smart coupling architectures, with Industry 4.0 integration requirements accelerating R&D capital intensity for sensor-embedded variants.
- Smart Couplings:Embedded diagnostics and wireless power harvesting for rotating components enable condition-based maintenance transitions. Semiconductor manufacturing equipment and automotive test stands now specify real-time torque telemetry as standard.
- Conventional Couplings:Non-instrumented mechanical designs retain dominant installed base share due to lower capital requirements and proven reliability in pre-digital rotating machinery.
- Adjustable Couplings:Field-recalibration capability serves applications with variable load profiles across production cycles.
- Fixed Couplings:Preset torque thresholds suit standardized production equipment with consistent operational parameters.
Service revenue potential favors smart coupling architectures; replacement cycle compression favors conventional mechanical designs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics favor precision-engineered coupling producers in Germany and Japan, while China's industrial machinery upgrade wave reduces import dependency for mid-tier mechanical designs. Supply chain reconfigurations are accelerating regional sourcing mandates across automotive and wind energy verticals.
Germany
Automotive OEM supply chains and precision engineering clusters in Stuttgart and Munich drive specification upgrades for torque limiting devices. The EU Machinery Directive mandates certified overload protection in safety-critical machinery, tightening compliance requirements across stamping press installations. Baden-Württemberg's mechanical engineering concentration anchors high-performance coupling R&D and production.
United States
OSHA machine guarding regulations mandate overload protection in heavy industrial settings, particularly in chemical processing and pulp and paper facilities. Corporate engineering centers in Houston and Chicago consolidate procurement through multi-location framework agreements. The Southeast's expanding automotive manufacturing footprint generates specification pull-through for precision-grade devices.
China
Domestic equipment manufacturers in Jiangsu and Zhejiang provinces retrofit legacy production lines with overload protection to reduce unplanned downtime. GB standards for mechanical transmission components increasingly influence export specifications as technical capabilities scale. Yangtze River Delta industrial clusters concentrate mid-tier coupling fabrication capacity.
Japan
Semiconductor manufacturing equipment and automotive test stands specify real-time torque telemetry as standard procurement criteria. METI industrial policy supports smart manufacturing adoption, embedding sensor diagnostics into power transmission components. Nagoya's automotive engineering concentration and Tokyo's precision equipment sector drive premium-tier demand.
India
The PLI scheme for capital goods reduces import dependency for precision mechanical components in textile and packaging machinery. Maharashtra and Gujarat industrial corridors attract domestic coupling fabrication investments. Repair shop networks in Delhi-NCR and Chennai manage reactive replacement cycles with shorter lead time requirements.
Torque Limiting Couplings Market Competitive Landscape
Listed leaders compete with private specialists across technology maturation curves, with public companies commanding scale advantages in smart coupling development and family-owned German firms retaining premium positioning in safety-critical applications. The vendor base organizes into three tiers: diversified industrial conglomerates with broad power transmission portfolios, precision engineering specialists focused on overload protection, and regional fabricators serving price-sensitive replacement markets. Dominant competitive moves include M&A consolidation of sensor technology capabilities and geographic expansion through distributor network deepening.
Within the German engineering specialist tier, KTR Systems GmbH and Chr. Mayr GmbH + Co. KG exemplify precision-grade positioning anchored in automotive and safety-critical industrial applications. Rexnord Corporation represents the diversified conglomerate archetype with extensive North American distribution coverage. These three entities occupy distinct competitive spaces—family-owned German precision versus transatlantic scale—without direct segment overlap in specification authority.
| Leading Market Players |
|---|
| KTR Systems GmbH |
| Rexnord Corporation |
| Altra Industrial Motion Corp. |
| Voith GmbH |
| Chr. Mayr GmbH + Co. KG |
| NU Teck Couplings |
| R+W Antriebselemente GmbH |
| Nexen Group, Inc. |
| Regal Rexnord Corporation |
| Others |
Value Network & Pricing Analysis
Forty-five-day lead times for nickel-chromium-molybdenum friction plate substrates concentrate pricing power with German and Japanese specialty steel mills, compressing margins for coupling assemblers while amplifying cost pass-through to automotive OEM buyers. This inventory-to-delivery gap shapes procurement behavior across the torque limiting couplings market, forcing specification trade-offs between certified European alloys and lower-grade Asian alternatives.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. ATEX-certified electromechanical variants with embedded torque telemetry command top-tier positioning against non-instrumented mechanical designs. Price differentiation rests on certification grade and volume scale, with framework agreements across multi-facility deployments securing 15-20% cost compression. Cost compression in mid-tier mechanical couplings is intensifying because Jiangsu province fabricators are scaling stainless steel production capacity. Repair shops and aftermarket distributors exhibit highest price sensitivity, while semiconductor equipment manufacturers prioritize specification compliance over unit economics.
Supply Chain Analysis
Strait of Malacca transit vulnerability concentrates risk exposure for specialty alloy shipments bound for European precision engineering clusters. Geographic supply concentration centers on Germany, Japan, and China for friction plate substrates, magnetic particle fluids, and sensor instrumentation modules. Raw material dependencies draw from nickel-chromium-molybdenum steel, rare-earth magnetic powders, and hermetic sealing ceramics. Single-source vulnerability persists in explosion-proof ATEX certification testing capacity. Distribution runs through authorized distributor networks in North America and direct OEM relationships in German automotive supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Torque limiting couplings sit in early-cycle expansion as predictive maintenance architectures displace reactive replacement cycles across installed industrial equipment. Smart coupling penetration remains below 15% of addressable machinery base, creating sustained specification upgrade runway.
For Market Incumbents: Fortify sensor technology capabilities through targeted acquisition of embedded diagnostics specialists, defending against pure-play IoT entrants. Deepen backward integration into magnetic particle fluid formulation to secure supply continuity against Japanese chemical supplier concentration. Prioritize ATEX certification capacity expansion to reduce six-month approval bottlenecks constraining oil and gas revenue capture.
For New Entrants and Emerging Players: Anchor in India's PLI-subsidized capital goods fabrication, where domestic production incentives reduce import dependency for precision mechanical components in textile and packaging machinery. Target food and beverage hygienic design specifications as the most penetrable white space, with stainless steel torque limiters for dairy processing commanding 40% gross margins. Pursue co-development partnerships with Jiangsu province equipment retrofitters to bypass entrenched German distributor relationships.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming power transmission divisions holding dormant smart coupling IP. Long-term viability favors vendors with demonstrated mechatronics engineering integration across mechanical torque physics and embedded firmware development. Monitor semiconductor capital equipment order backlogs as the critical inflection signal for precision-grade torque telemetry demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Technology Acquisition | Embedded diagnostics capability secures specification authority in automotive test stand procurement. |
| ATEX Certification Expansion | Reduced approval timelines capture revenue from North Sea offshore wind installations. |
| India PLI Manufacturing Footprint | Domestic production incentives lower cost position in textile machinery replacement cycles. |
| Hygienic Design Product Line | Stainless steel sealed housings address washdown compliance in dairy processing applications. |
| Framework Agreement Negotiation | Multi-facility corporate contracts consolidate procurement across chemical processing conglomerates. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, EU Machinery Directive implementation guidance, and industrial equipment customs databases. Primary interviews engaged maintenance directors at German automotive stamping plants, OEM procurement teams in Stuttgart and Munich engineering clusters, and aftermarket service heads managing legacy equipment retrofit programs. Secondary validation drew from ISO 9001 certification registries, ATEX notified body approval records, and Yangtze River Delta industrial production statistics. Bottom-up coupling shipment data triangulates against top-down industrial machinery investment flows.
Segmentation dimensions modeled span product type, application vertical, end-user category, and technology maturity across the projection horizon. Electromechanical and mechanical variant splits, smart versus conventional coupling adoption curves, and regional regulatory cluster differentiation anchor the analytical framework. CAGRs derive from equipment replacement cycle analysis overlaid with Industry 4.0 capital expenditure trajectories. Forecast inputs incorporate semiconductor capital equipment order patterns and wind turbine drivetrain installation pipelines.
Decision-makers should treat outputs as directional under assumptions of sustained EU Machinery Directive enforcement and continued German automotive OEM supply chain concentration; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as REACH substance restriction timelines and China GB standard harmonization efforts evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Chain-Driven Roller Conveyors Market
Material Handling Equipment
Pug Mill Mixers Market
Material Handling Equipment
Wagon Tipplers Market
Material Handling Equipment
Hook Loader Market
Material Handling Equipment
Tube Rotator Market
Material Handling Equipment
Log Stackers Market
Material Handling Equipment
Spiral Fitting Machines Market
Material Handling Equipment
Loading Platform Canopies Market
Material Handling Equipment
Air Classifying Mill Market
Material Handling Equipment
US Forklift Market
Material Handling Equipment
Precision Gearbox Machinery Market
Material Handling Equipment
Overhead Conveyor Systems Market
Material Handling Equipment
Global Metal Expansion Joints Market
Material Handling Equipment
Slag Handling Equipment Market
Material Handling Equipment
Rotating Fork Clamp Market
Material Handling Equipment
Eye and Eye Turnbuckle Market