
 Pipe Relining Machine Market | 2026-2036
Pipe Relining Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Pipe Relining Machine Market Analysis
Specialized distributor networks for trenchless equipment is reshaping how contractors access relining technology in North America and Europe. HammerHead Trenchless Equipment leverages direct regional dealer partnerships to sustain strong presence across the United States. NordiTube Technologies anchors its competitive position through deep product specialization in cured-in-place liner manufacturing systems. Aegion Corporation competes by controlling integrated service-to-equipment channels that bundle machine supply with liner material logistics.
A pipe relining machine is a mechanized system that installs structural liners within existing damaged pipelines, typically operating at pressures between 5-15 bar and temperatures up to 180°C depending on curing method, to create a new pipe-within-a-pipe without excavation. Its primary industrial purpose is to rehabilitate deteriorated sewer, stormwater, and pressure pipelines while minimizing surface disruption in urban environments. Cured-in-Place technology dominates installed equipment bases due to proven performance in circular sewer mains up to 1200mm diameter, while UV Curing represents the fastest-growing segment as municipalities specify faster cure cycles and lower energy consumption. Trenchless methods command premium pricing in dense metropolitan applications where open-cut excavation faces strict traffic management and restoration cost penalties.
EPA's Clean Water State Revolving Fund criteria, Germany's DWA worksheet A-143 technical standards, and the EU's Urban Wastewater Treatment Directive collectively shape equipment specifications and procurement eligibility across major markets. These frameworks mandate structural design life minimums and installation quality documentation that filter out non-compliant machine suppliers. Stakeholders must monitor evolving polymer emissions regulations and liner recyclability requirements that will determine next-generation equipment R&D priorities.
Market Dynamics
The EU Green Deal's infrastructure resilience mandates are compressing cure cycle requirements and forcing equipment manufacturers to redesign thermal management systems for lower energy consumption. Municipal procurement departments now specify UV-curing compatibility as a mandatory qualification criterion, eliminating steam-only system suppliers from tender eligibility.
Growth Catalysts
- Combined Sewer Overflow Remediation:The Rhine-Ruhr industrial corridor drives concentrated equipment procurement as German water authorities face DWA worksheet A-143 compliance deadlines for aging interceptor networks.
- EPA Clean Water State Revolving Fund:US municipal utilities access below-market financing that accelerates trenchless rehabilitation program expansion and specifies structural liner design life minimums.
- UV Curing Technology Maturation:LED-UV lamp systems achieve cure speeds under 45 minutes for 150mm-600mm diameter mains, satisfying traffic management restrictions in dense metropolitan construction windows.
Market Restraints
- Specialized Resin Supply Concentration:Vinyl ester and epoxy formulations for pressure-rated applications depend on petrochemical feedstocks subject to European refinery capacity constraints.
- Equipment Capital Intensity:Multi-cure platform machines capable of steam, hot water, and UV operation require capital commitments exceeding typical mid-size contractor balance sheet capacity.
- Polymer Emissions Scrutiny:Evolving styrene emission thresholds under EU REACH implementation create compliance uncertainty for traditional polyester-based liner systems.
Strategic Opportunities
- Industrial Pressure Pipeline Extension:Chemical processing facilities in the US Gulf Coast seek structural rehabilitation solutions for corroded carbon steel process lines without production shutdown.
- Liner Material Logistics Integration:Contractors bundle equipment supply with just-in-time liner delivery, capturing margin from material handling coordination previously outsourced to third-party distributors.
- EU AI Act Infrastructure Classification:Smart curing control systems with real-time temperature and pressure monitoring qualify for accelerated public procurement pathways under digital infrastructure investment frameworks.
Industry Challenges
- Certified Installer Pipeline:UV-curing equipment operation requires technician training programs that lag equipment deployment timelines, creating deployment bottlenecks for municipal contracts.
- Legacy Network Condition Assessment:Pre-lining CCTV inspection and cleaning specifications vary across German federal states, forcing equipment suppliers to maintain multiple calibration protocols.
- Cross-Platform Maintenance Complexity:Contractors operating mixed fleets of steam and UV systems face spare parts inventory duplication and divergent preventive maintenance schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pipe Relining Machine Market |
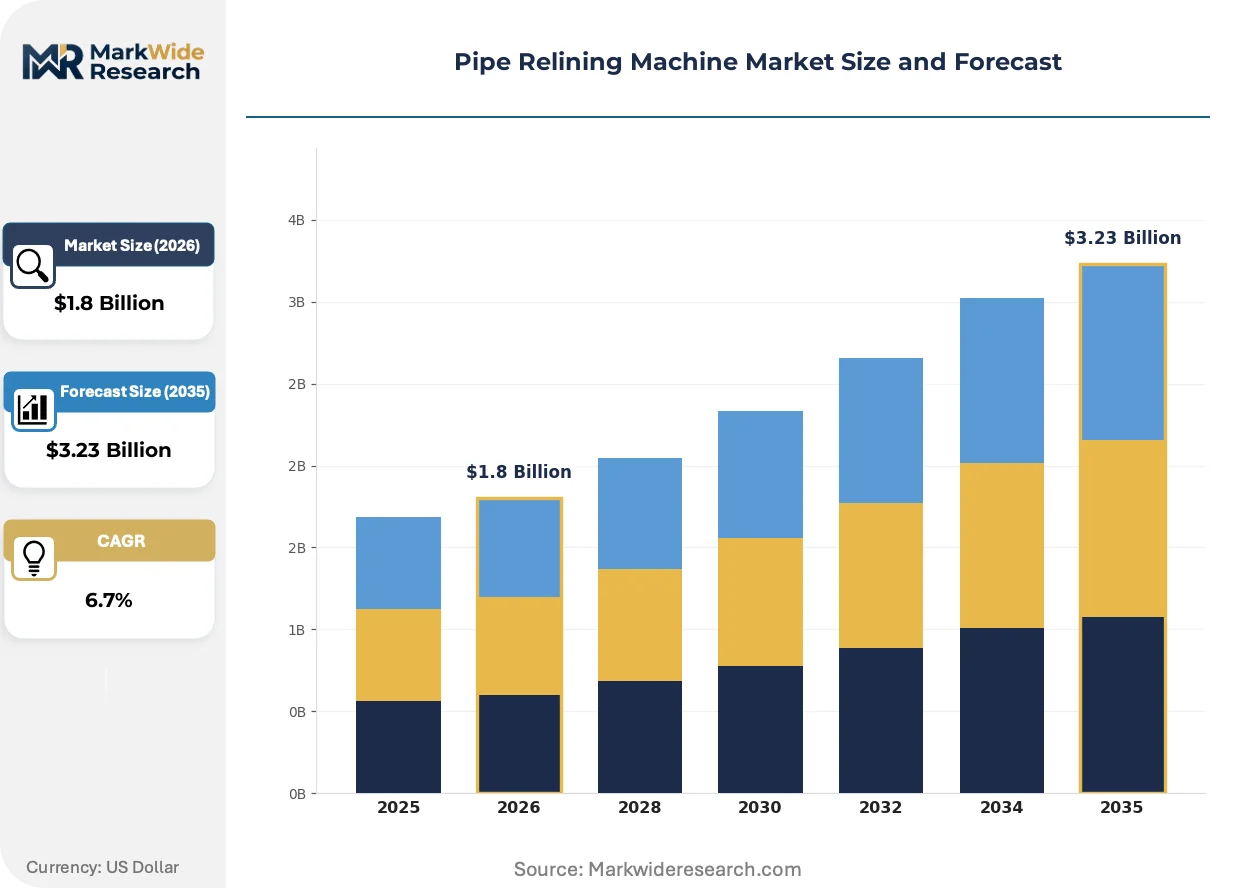
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Trenchless, Cured-in-Place, Pull-in-Place, Patch Repair Technology: UV Curing, Steam Curing, Hot Water Curing, Epoxy Resin End User: Municipalities, Plumbing Contractors, Industrial, Residential Application: Sewer Maintenance, Stormwater Management, Pipeline Rehabilitation, Infrastructure Repair |
| Companies Covered | Trelleborg Seals & Profiles, Pow-R Mole Trenchless Solutions, Picote Group, Aegion Corporation, HammerHead Trenchless Equipment, Dancutter, NordiTube Technologies, Waterline Renewal Technologies, Vortex Companies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pipe Relining Machine Market Emerging Trajectories
Equipment intelligence and energy efficiency are converging to redefine competitive differentiation in pipe relining systems. Manufacturers now embed IoT-enabled process control as standard rather than premium configuration.
LED-UV curing systems are collapsing the traditional trade-off between cure speed and energy consumption. German municipal utilities specify these platforms for 24-hour construction window compliance in high-traffic urban corridors. The technology is collapsing project timelines from three-day steam cures to same-day reinstatement, compressing contractor crew allocation and traffic management cost structures.
The EU Green Deal's Urban Wastewater Treatment Directive amendments mandate structural design life documentation and installation quality traceability. Equipment suppliers must integrate automated data logging and cloud-based reporting to maintain tender eligibility. German water authorities now reject bids lacking ISO 9001-aligned quality management system certification for liner installation equipment.
Service bundling is displacing standalone equipment sales in North American municipal procurement. Contractors demand turnkey packages combining machine supply, liner material logistics, and technical field support. The US Pacific Northwest exhibits the strongest concentration of bundled procurement, where Seattle and Portland water utilities specify single-source accountability for rehabilitation project outcomes.
Pipe Relining Machine Market Segmentation
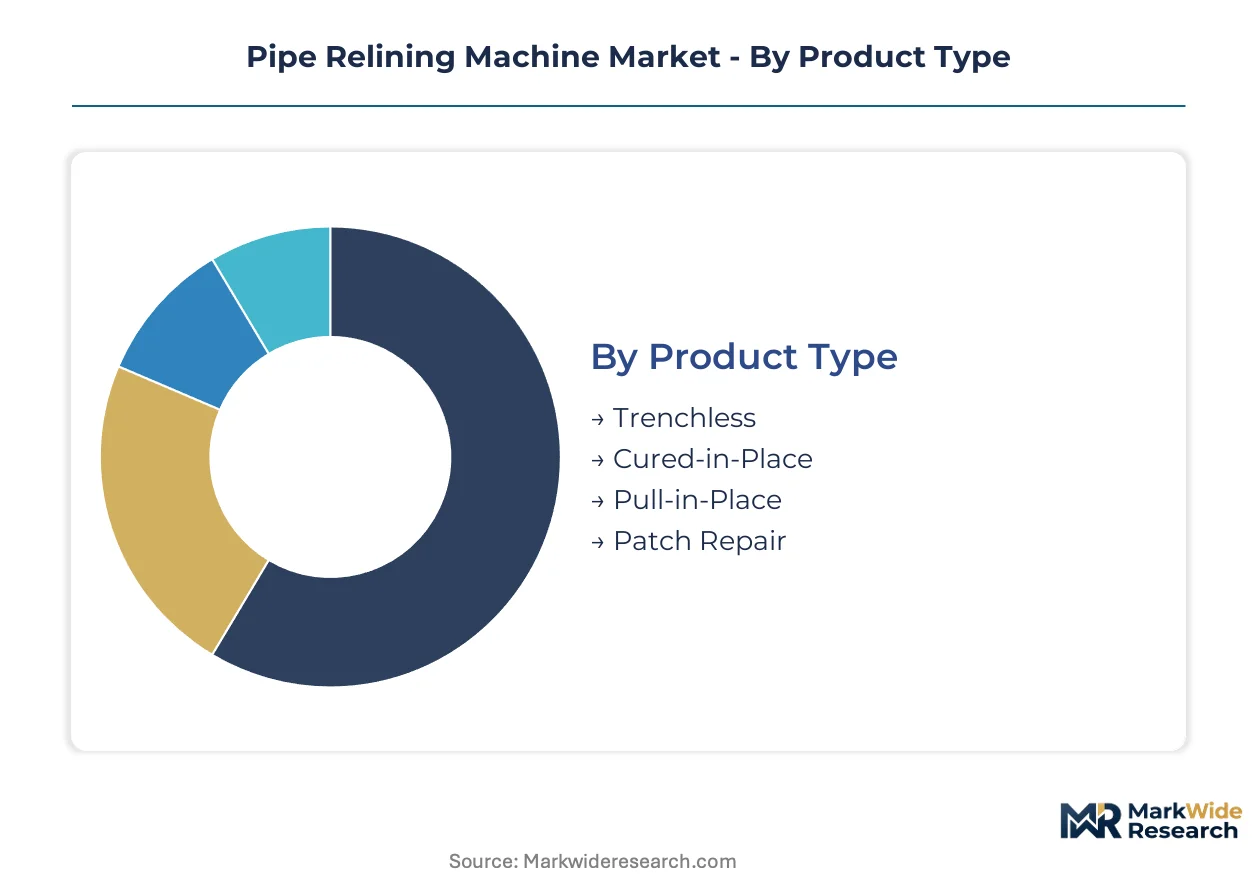
Equipment specifications in pipe relining diverge sharply by installation environment and curing chemistry, creating distinct procurement channels that manufacturers must navigate simultaneously. Segmentation reveals where technology investments concentrate and which customer types drive platform development priorities.
Product Type:
Mature trenchless platforms dominate installed bases while emerging methods reshape contractor capability requirements.
- Cured-in-Place:Structural liners saturated with thermosetting resin are inverted or pulled into damaged pipes, then cured to form a seamless new pipe wall. German municipal authorities in the Rhine-Ruhr corridor specify CIPP for interceptor rehabilitation under DWA worksheet A-143 compliance deadlines.
- Trenchless:Broad category encompassing all no-dig rehabilitation methods, with equipment designed for minimal surface disruption in dense urban corridors. US metropolitan utilities leverage trenchless specifications to avoid traffic management penalties and surface restoration costs in downtown Seattle and Portland procurement frameworks.
- Pull-in-Place:Pre-shaped liners are mechanically drawn through host pipes and expanded to fit, suited for pressure-rated applications where resin saturation occurs before insertion.
- Patch Repair:Localized spot repair systems address isolated defects without full-length relining, serving cost-sensitive residential and small-diameter municipal applications.
Cured-in-Place handles the majority of throughput; Patch Repair is the fastest mover on share as spot interventions displace full-length relining in aging network maintenance programs.
Technology:
Cost tier differentiation separates premium UV platforms from established thermal curing systems.
- UV Curing:LED-UV lamp arrays achieve cure cycles under 45 minutes for 150mm-600mm diameter mains, slashing energy consumption and traffic management costs. German utilities specify UV compatibility as mandatory tender qualification under EU Green Deal infrastructure mandates.
- Steam Curing:Pressurized steam delivers consistent heat distribution for large-diameter and thick-wall liner applications, retaining dominance in 800mm+ sewer main rehabilitation where cure depth requirements exceed UV penetration limits.
- Hot Water Curing:Circulating heated water provides uniform temperature control for sensitive resin formulations, common in epoxy-based pressure pipe applications.
- Epoxy Resin:Chemical curing systems operate at ambient temperatures, serving industrial process line rehabilitation where thermal curing risks adjacent equipment damage.
Steam Curing retains the largest installed equipment base; UV Curing represents the fastest-growing trajectory as municipalities compress construction windows and mandate energy efficiency.
End User:
Customer type determines equipment scale, financing structure, and technical support intensity.
- Municipalities:Public water authorities procure multi-cure platforms through EPA Clean Water State Revolving Fund financing, bundling equipment with 20-year liner design life guarantees and automated quality documentation systems.
- Plumbing Contractors:Mid-size service firms drive demand for compact, trailer-mounted systems serving residential and commercial lateral connections, with procurement concentrated in suburban US markets.
- Industrial:Chemical processing and power generation facilities seek pressure-rated rehabilitation without production shutdown, creating demand for specialized epoxy and vinyl ester curing systems.
- Residential:Single-family and small multi-family properties generate demand for portable patch repair equipment and liner kits distributed through plumbing supply channels.
Municipalities command the largest equipment procurement volumes; Industrial is gaining share fastest as process line rehabilitation expands beyond traditional sewer applications.
Application:
Volume concentration varies by infrastructure age and regulatory pressure intensity.
- Sewer Maintenance:Combined sewer overflow remediation drives concentrated equipment deployment in aging interceptor networks, with German federal states facing EU Urban Wastewater Treatment Directive enforcement deadlines.
- Pipeline Rehabilitation:Pressure-rated industrial and water main applications require specialized resin formulations and curing protocols, expanding the addressable market beyond gravity sewer systems.
- Stormwater Management:Separate storm sewer rehabilitation addresses inflow and infiltration reduction targets, with procurement concentrated in US Great Lakes region municipalities under MS4 permit requirements.
- Infrastructure Repair:Emergency response and post-disaster rehabilitation creates episodic demand for rapid-deployment equipment capable of same-day mobilization.
Sewer Maintenance accounts for the dominant share of equipment utilization hours; Pipeline Rehabilitation is expanding most quickly as industrial pressure applications adopt trenchless methods.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's infrastructure resilience mandates and the EPA's Clean Water State Revolving Fund create divergent but equally potent procurement accelerants across major economies. National regulations filter equipment eligibility through structural design life requirements and emissions thresholds. Industrial corridor concentration determines where deployment capital concentrates.
United States
Municipal utilities in Seattle and Portland specify bundled procurement combining machine supply with liner material logistics under EPA Clean Water State Revolving Fund financing. The Pacific Northwest leads US adoption of UV-curing compatibility as mandatory tender qualification. Contractors leverage below-market federal financing to expand trenchless rehabilitation programs for aging combined sewer systems.
Germany
The Rhine-Ruhr industrial corridor drives concentrated equipment procurement as water authorities face DWA worksheet A-143 compliance deadlines for interceptor network rehabilitation. EU Green Deal mandates compress cure cycle requirements and eliminate steam-only system suppliers from tender eligibility. LED-UV platforms satisfy 24-hour construction window restrictions in high-traffic urban corridors across North Rhine-Westphalia.
China
Yangtze River Delta municipalities deploy trenchless methods for dense metropolitan sewer rehabilitation without surface excavation disruption. National dual carbon goals accelerate specification of energy-efficient UV curing over traditional thermal methods. Shanghai's infrastructure renewal programs create demand for multi-cure platform machines capable of steam, hot water, and UV operation.
Japan
Tokyo Metropolitan Government procurement frameworks prioritize automated quality documentation systems for liner installation equipment under ISO 9001-aligned certification requirements. METI standards for infrastructure resilience mandate structural design life traceability. Kanto region contractors specify compact trailer-mounted systems for residential and commercial lateral connections in suburban markets.
Australia
New South Wales and Victoria water authorities adopt cured-in-place pipe technologies for stormwater inflow and infiltration reduction under MS4 permit requirements. State-level procurement frameworks emphasize installation quality documentation and cloud-based reporting systems. Sydney's infrastructure resilience programs specify UV-curing compatibility to compress construction timelines in high-density corridors.
Pipe Relining Machine Market Vendor Landscape
On the supply side, the industry is consolidating around equipment manufacturers capable of integrating multi-cure platforms with automated process control systems. The vendor base separates into three strategic archetypes: full-line trenchless equipment houses, specialized liner manufacturing system producers, and integrated service-to-equipment bundlers. Dominant competitive moves include strategic partnerships with resin suppliers for formulation exclusivity and geographic expansion through regional distributor networks.
Among North American and European equipment specialists, HammerHead Trenchless Equipment, NordiTube Technologies, and Aegion Corporation occupy distinct positioning vectors. HammerHead exemplifies the regional dealer partnership model sustaining presence across United States municipal markets. NordiTube anchors the product specialization archetype through cured-in-place liner manufacturing systems. Aegion represents integrated service-to-equipment channel control bundling machine supply with liner material logistics. These three illustrate how competitive differentiation converges on distribution architecture rather than core curing technology.
| Leading Market Players |
|---|
| Trelleborg Seals & Profiles |
| Pow-R Mole Trenchless Solutions |
| Picote Group |
| Aegion Corporation |
| HammerHead Trenchless Equipment |
| Dancutter |
| NordiTube Technologies |
| Waterline Renewal Technologies |
| Vortex Companies |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese UV-curing platform manufacturing is compressing margins for mid-tier equipment suppliers while concentrating pricing power with German and US manufacturers holding proprietary LED-lamp thermal management patents. This utilization asymmetry forces procurement departments to navigate a bifurcated market where premium multi-cure systems command substantial premiums over commoditized single-method units.
Pricing Analysis
Volume-discount tiering structures separate municipal utility fleet purchases from mid-size contractor single-unit acquisitions by 25-40 percent at equivalent specifications. Price differentiation hinges on ISO 9001-aligned quality certification status and bundled after-sales technical support intensity. Cost compression in the standard-equipment tier is intensifying because Chinese manufacturers are exporting surplus UV-platform capacity into Southeast Asian and Middle Eastern markets. Plumbing contractors exhibit highest price sensitivity due to limited balance sheet capacity, while German municipal authorities prioritize compliance documentation over unit cost.
Supply Chain Analysis
Upstream vinyl ester and epoxy resin formulations draw from petrochemical feedstocks concentrated in Germany, the Netherlands, and South Korea, creating regional supply dependencies for pressure-rated liner applications. LED-UV lamp arrays and precision thermal sensors hinge on semiconductor component sourcing from Taiwan and Japan. Single-source vulnerability runs through German-engineered control system modules that dominate high-reliability municipal specifications. Distribution runs through specialized trenchless equipment dealers in North America and direct manufacturer relationships in European procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified UV-curing technician pipelines are constraining deployment velocity faster than equipment manufacturing capacity can expand, creating a capability-scarcity environment where training infrastructure ownership becomes a strategic asset.
For Market Incumbents: Build certification-program moats by acquiring or partnering with regional technical training institutes to control installer pipeline flow. Deepen backward integration into proprietary resin formulations to secure supply continuity against European refinery capacity constraints. Defensive positioning against emerging Chinese UV-platform exporters requires accelerating R&D in smart-curing control systems that qualify for EU AI Act accelerated procurement pathways. For New Entrants and Emerging Players: Pursue industrial pressure-pipeline rehabilitation as the most penetrable white-space segment, where chemical processing facilities in the US Gulf Coast seek structural solutions without production shutdown. Target compact trailer-mounted patch-repair systems for residential and commercial lateral markets in suburban US corridors where incumbent coverage remains thin. A go-to-market angle bundling equipment with just-in-time liner logistics captures margin from coordination services previously outsourced to third-party distributors. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across multi-cure platform manufacturing as EU Green Deal mandates force redundant thermal management system redesigns. Long-term viability over the coming decade favors equipment suppliers with demonstrated integration capabilities spanning machine supply, resin formulation partnerships, and cloud-based quality documentation systems. The acquisition target archetype is mid-size German or US manufacturers holding DWA worksheet A-143 or EPA compliance track records but lacking UV-curing platform portfolios. The signal to watch is municipal tender specification language shifting from "UV-compatible" to "UV-mandatory" as construction window restrictions tighten.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Cure Platform Development | Steam-hot water-UV flexibility satisfies divergent municipal procurement requirements across German federal states. |
| Resin Formulation Partnership | Exclusive vinyl ester supply agreements secure pressure-rated application eligibility against petrochemical feedstock volatility. |
| Smart Curing Control Integration | IoT-enabled temperature-pressure logging maintains tender eligibility under EU Urban Wastewater Treatment Directive amendments. |
| Certified Installer Network Expansion | Training program scale determines deployment velocity for UV-curing municipal contracts with compressed construction windows. |
| Regional Dealer Partnership Deepening | Direct distribution presence in the US Pacific Northwest captures bundled procurement specifications from Seattle and Portland utilities. |
Methodological Framework
A standing panel of municipal procurement officers, trenchless contractor operations managers, resin formulation technical directors, and aftermarket service heads provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with equipment deployment observations at Rhine-Ruhr and US Pacific Northwest rehabilitation sites. Secondary validation drew from EPA Clean Water State Revolving Fund disbursement records, German DWA technical standard publications, EU Green Deal implementation guidance documents, and customs trade data for trenchless equipment imports. Bottom-up equipment unit demand estimates were triangulated against top-down municipal capital expenditure budgets.
Scenario-bracketing framed low, baseline, and high growth cases across the projection horizon without presuming single-point precision. Segmentation dimensions modeled included curing technology type, end-user procurement scale, liner diameter application range, and regional regulatory compliance tier. CAGRs were derived from equipment replacement cycle analysis and municipal program expansion trajectories rather than extrapolated trend lines. Industry-specific forecast inputs incorporated DWA worksheet A-143 compliance deadline clustering and LED-UV lamp efficiency improvement curves.
Macroeconomic conditions sit as an overlay; deviation in municipal bond financing costs or European petrochemical feedstock pricing would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement intensity and technology substitution rates. Cross-checking against EPA State Revolving Fund obligation data and German federal state procurement disclosure databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Canada Metal Fabrication Equipment Market
Construction Equipment and Machinery
ASEAN Construction Machinery Market
Construction Equipment and Machinery
Global Metal Embossing Machine Market
Construction Equipment and Machinery
Global Laundry Folding Machine Market
Construction Equipment and Machinery
Latin America Injection Molding Machines Market
Construction Equipment and Machinery
Africa Heavy Construction Equipment Rental Market
Construction Equipment and Machinery
Lattice Cranes Market
Construction Equipment and Machinery
Crushing, Screening, and Mineral Processing Equipment Market
Construction Equipment and Machinery
Double Decker Roll Forming Machine Market
Construction Equipment and Machinery
Road Construction Machinery Market
Construction Equipment and Machinery
Aluminum Die Casting Machinery Market
Construction Equipment and Machinery
Engineering Machinery Counterweight Iron Market
Construction Equipment and Machinery
Wire Mesh Welding Machines Market
Construction Equipment and Machinery
Dredge Automation Market
Construction Equipment and Machinery
Global Hydraulic Ironworker Machine Market
Construction Equipment and Machinery
Used Machine Tools Market