
 Anaerobic Digestion Equipment Market | 2026-2036
Anaerobic Digestion Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Anaerobic Digestion Equipment Market Analysis
Buyer concentration among European agricultural cooperatives is shifting as fragmented livestock farms consolidate procurement into shared digester cooperatives. WELTEC BIOPOWER GmbH anchors its position through German engineering standards and turnkey plant delivery. EnviTec Biogas AG differentiates via proprietary membrane upgrading technology for biomethane injection. Hitachi Zosen Inova competes on large-scale waste-to-energy integration in urban waste complexes.
Anaerobic digestion equipment encompasses sealed reactor vessels, mixing systems, gas handling infrastructure, and control instrumentation designed to break down organic matter in oxygen-free environments at mesophilic or thermophilic temperatures, typically producing biogas with methane concentrations of 50-70%. Continuous flow systems dominate commercial installations due to predictable throughput and lower labor intensity, while plug flow configurations occupy a specialized niche in high-solids agricultural feedstock processing. Monitoring solutions represent the fastest-growing technology segment as operators deploy IoT-enabled biogas composition sensors to optimize retention times and prevent process instability.
The EU Green Deal and national implementations of the F-Gas Regulation shape equipment specifications by mandating leak detection and biomethane purity thresholds for grid injection. Germany's Federal Environment Agency enforces strict approval protocols under the Renewable Energy Sources Act, while the EMA's sustainability reporting requirements under CSRD compel food processors to document Scope 3 methane reductions through verified digester outputs. Stakeholders must weigh feedstock security against technology lock-in as substrate diversification requirements intensify across European permitting regimes.
Market Dynamics
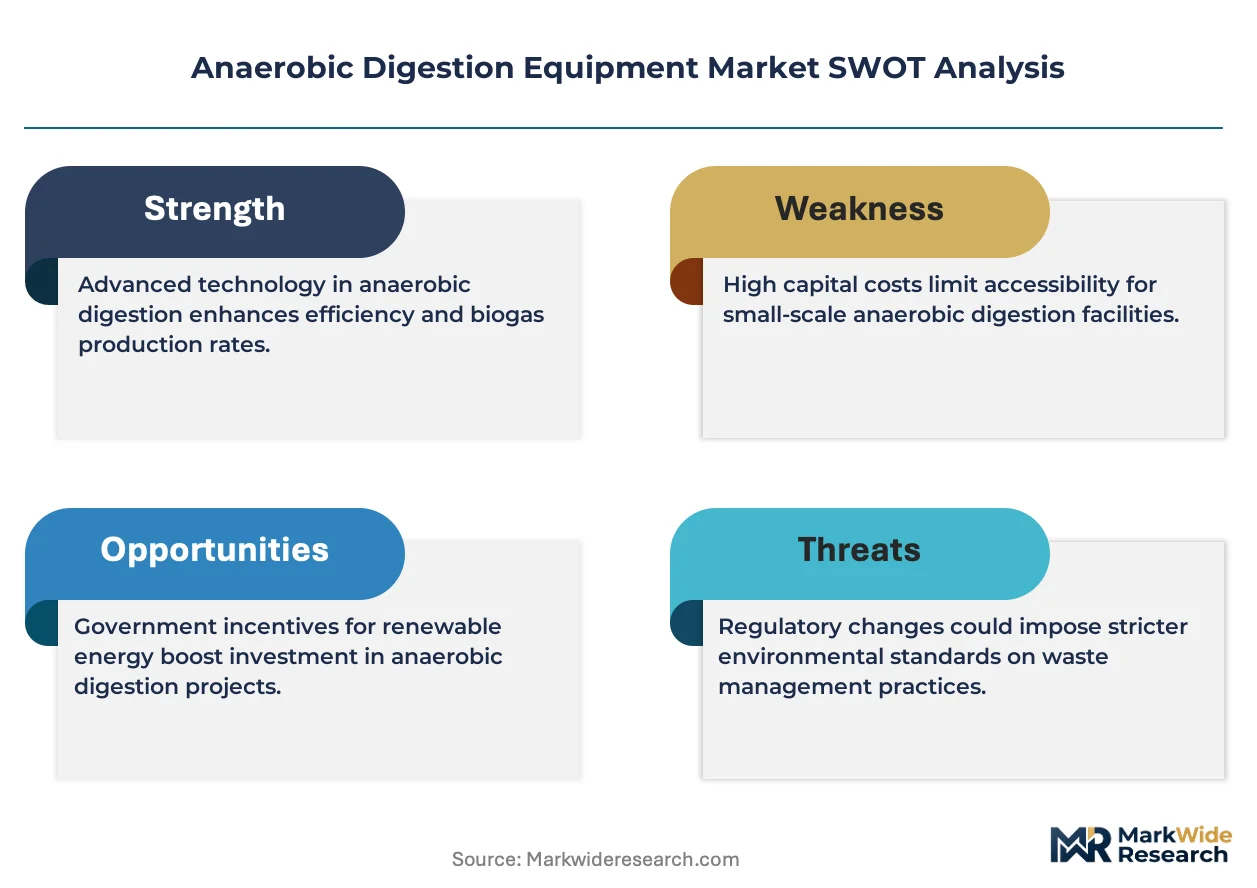
EU methane reduction mandates under the Green Deal are compressing project timelines and forcing equipment standardization across member states, while feedstock diversification requirements are rewriting reactor design specifications.
Growth Catalysts
- Agricultural cooperative consolidation:Dairy collectives in Denmark pool procurement for shared digester infrastructure under national carbon accounting frameworks.
- F-Gas Regulation implementation:Leak detection mandates for biomethane grid injection are accelerating sensor deployment across EU member states.
- CSRD reporting obligations:Food processors document Scope 3 methane reductions through verified digester outputs, creating equipment pull from industrial waste streams.
Market Restraints
- Stainless steel input volatility:Reactor vessel fabrication depends on nickel and chromium supply concentration from South African and Indonesian mining operations.
- Permitting fragmentation:Germany's Federal Environment Agency approval protocols under the Renewable Energy Sources Act create multi-year project delays.
- Biomethane substitution pressure:Green hydrogen injection targets in EU gas grid planning divert infrastructure investment from anaerobic digestion upgrading equipment.
Strategic Opportunities
- IoT-enabled process control:Biogas composition sensors and predictive retention time algorithms are expanding into municipal wastewater retrofits.
- Membrane upgrading convergence:Proprietary separation technology integration with carbon capture systems creates biomethane-to-bio-LNG pathways.
- Agri-waste valorization channels:Direct equipment leasing models to fragmented livestock farms bypass traditional cooperative procurement structures.
Industry Challenges
- Process biology expertise scarcity:Operators lack trained microbiologists to manage thermophilic system instability during feedstock transitions.
- Legacy SCADA integration friction:Brownfield biogas plants require custom protocol bridges to connect new IoT sensors with existing control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anaerobic Digestion Equipment Market |
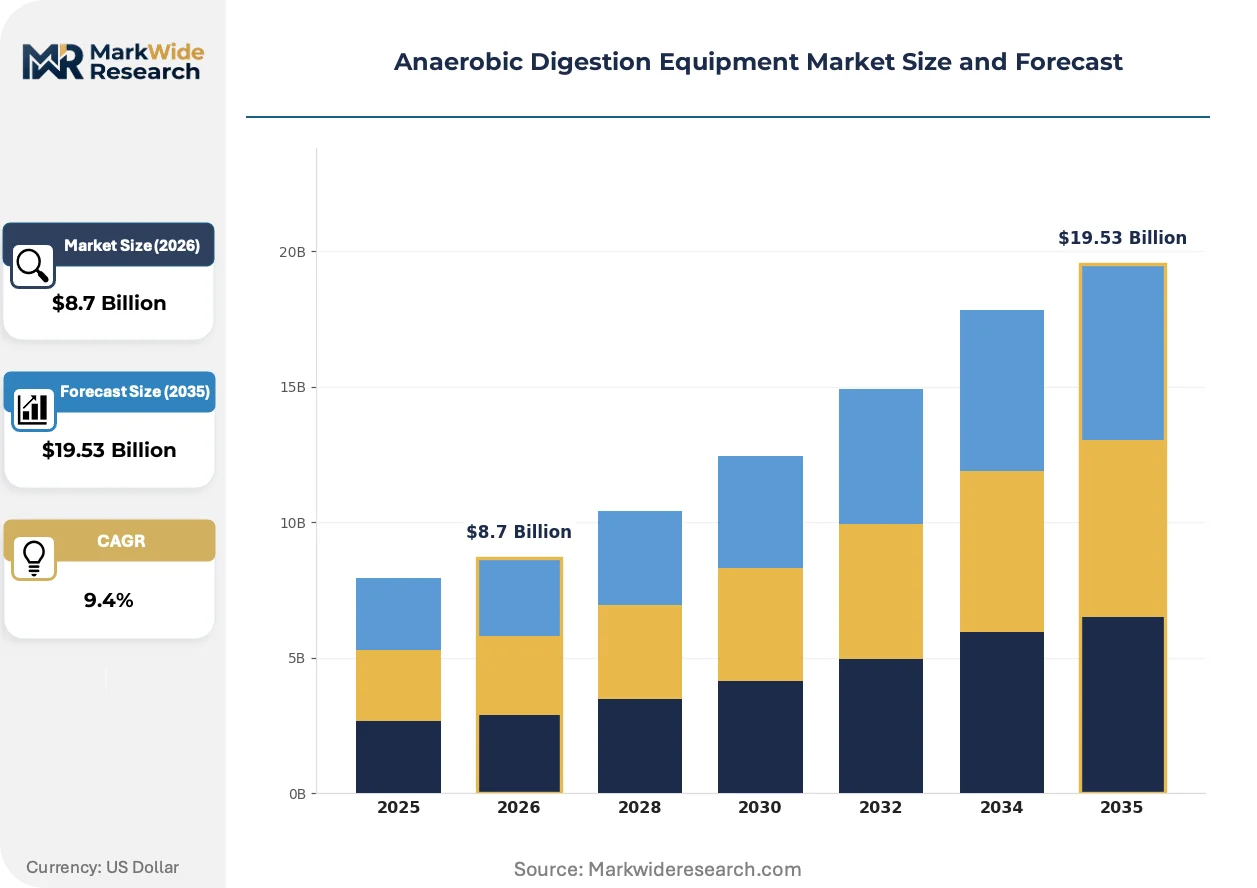
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Flow, Batch Systems, Hybrid Systems, Plug Flow Technology: Biogas Production, Feedstock Preprocessing, Digestate Management, Monitoring Solutions End User: Agriculture, Wastewater Treatment Plants, Food Processing, Livestock Capacity: Small Scale, Medium Scale, Large Scale, Modular Systems |
| Companies Covered | WELTEC BIOPOWER GmbH, JDV Equipment Corporation, EnviTec Biogas AG, ADI Systems Inc., Ovivo, PlanET Biogas, DVO Inc., Renergon Biogas AG, Hitachi Zosen Inova, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anaerobic Digestion Equipment Market Emerging Trajectories
Equipment intelligence layers are displacing manual process control, while substrate flexibility requirements are driving modular reactor architectures that accommodate agricultural, industrial, and municipal waste streams within single installations.
Continuous flow anaerobic digestion systems with automated solids separation are expanding into high-solids agricultural feedstock processing previously dominated by plug flow configurations. Dairy cooperatives in Denmark and the Netherlands adopt these hybrid designs to handle variable manure-to-food-waste ratios. The technology is compressing capital expenditure per unit of biogas output while extending equipment service intervals.
The EU Green Deal's methane reduction mandates are forcing leak detection instrumentation into all new biomethane grid injection projects. Equipment suppliers must certify sensor arrays under F-Gas Regulation protocols before German Federal Environment Agency approval. Agricultural cooperatives in northern Europe absorb compliance costs through carbon credit revenue streams.
Food processors now specify digester output verification systems that automate Scope 3 emissions documentation for CSRD sustainability reporting. Engineering procurement departments replace traditional equipment-only contracts with performance-guaranteed service agreements spanning ten-year operational periods. This restructuring is most visible in Germany's meat processing and dairy manufacturing sectors.
Anaerobic Digestion Equipment Market Segmentation
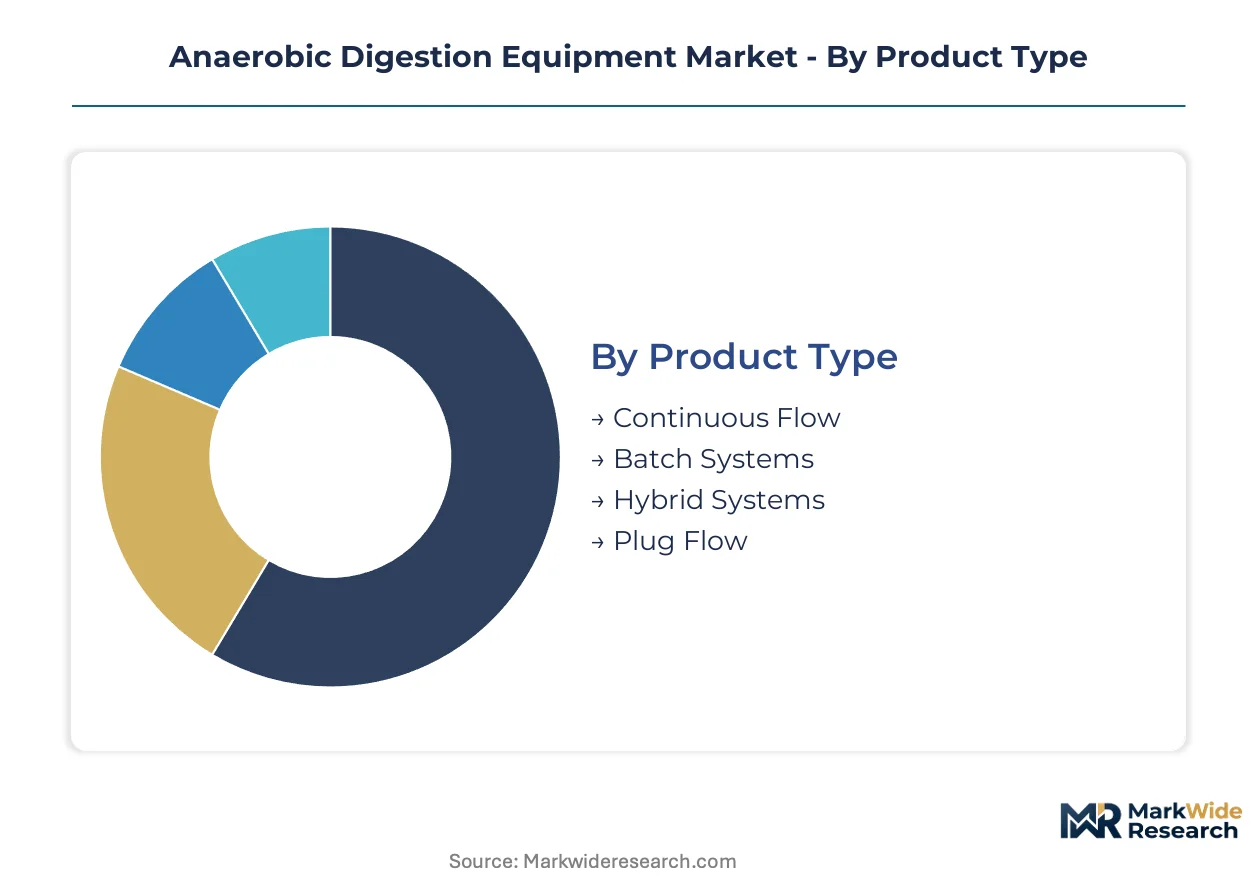
Equipment segmentation in anaerobic digestion reflects divergent certification burdens across reactor configurations and monitoring tiers. German Federal Environment Agency protocols under the Renewable Energy Sources Act impose distinct approval timelines for continuous flow versus batch architectures, while F-Gas Regulation mandates reshape sensor array requirements.
Product Type:
Continuous flow and plug flow systems carry divergent German Federal Environment Agency certification burdens under Renewable Energy Sources Act protocols, with hybrid architectures triggering dual compliance tracks.
- Continuous Flow:Sealed reactor vessels with automated substrate feeding achieve mesophilic or thermophilic decomposition through controlled hydraulic retention times. Municipal wastewater utilities in Germany specify these for biogas capture retrofits under EU Green Deal methane mandates, prioritizing predictable throughput over feedstock flexibility.
- Plug Flow:Horizontal reactors with progressive solids movement accommodate high-solids agricultural feedstock at 20-40% total solids concentration. Dairy cooperatives in Denmark deploy farm-scale units to monetize manure streams under national carbon accounting rules, though thermophilic operation demands scarce microbiological expertise.
- Batch Systems:Sequential loading protocols suit seasonal agricultural waste streams with intermittent availability.
- Hybrid Systems:Dual-stage configurations combine continuous liquid handling with high-solids batch processing for feedstock diversification.
Continuous flow sits at the top of the volume ranking, with hybrid systems climbing the fastest as substrate diversification requirements intensify.
Technology:
Cost tiering separates capital-intensive biogas upgrading infrastructure from sensor arrays that scale linearly with reactor count.
- Biogas Production:Core reactor vessels, gas handling infrastructure, and methane separation systems producing 50-70% CH4 concentration biogas. Agricultural cooperatives in northern Europe absorb compliance costs through carbon credit revenue streams tied to grid injection purity thresholds.
- Monitoring Solutions:IoT-enabled biogas composition sensors and predictive retention time algorithms optimize process stability. F-Gas Regulation leak detection mandates accelerate deployment across EU member states, with certification requirements compressing vendor qualification timelines.
- Feedstock Preprocessing:Maceration, pasteurization, and contaminant removal systems condition variable organic inputs.
- Digestate Management:Solid-liquid separation and nutrient recovery equipment closes material loops for agricultural reuse.
Biogas production commands the highest absolute equipment spend, while monitoring solutions gain share fastest on regulatory compulsion.
End User:
Application-specific performance guarantees drive contract restructuring toward decade-long service agreements with verified output documentation.
- Agriculture:Farm-scale and cooperative digesters processing manure, crop residues, and agro-industrial byproducts. Denmark's dairy collectives pool procurement for shared infrastructure under national carbon accounting frameworks, consolidating fragmented livestock operations.
- Wastewater Treatment Plants:Municipal utilities retrofitting sludge handling for biogas capture under EU Green Deal methane reduction mandates. Germany's expanded biogas capture programs concentrate demand in this segment.
- Food Processing:Industrial waste stream digestion with automated Scope 3 emissions documentation for CSRD reporting.
- Livestock:Manure management systems at concentrated animal feeding operations with direct equipment leasing uptake.
Agriculture maintains volume leadership, with food processing expanding most quickly on sustainability reporting obligations.
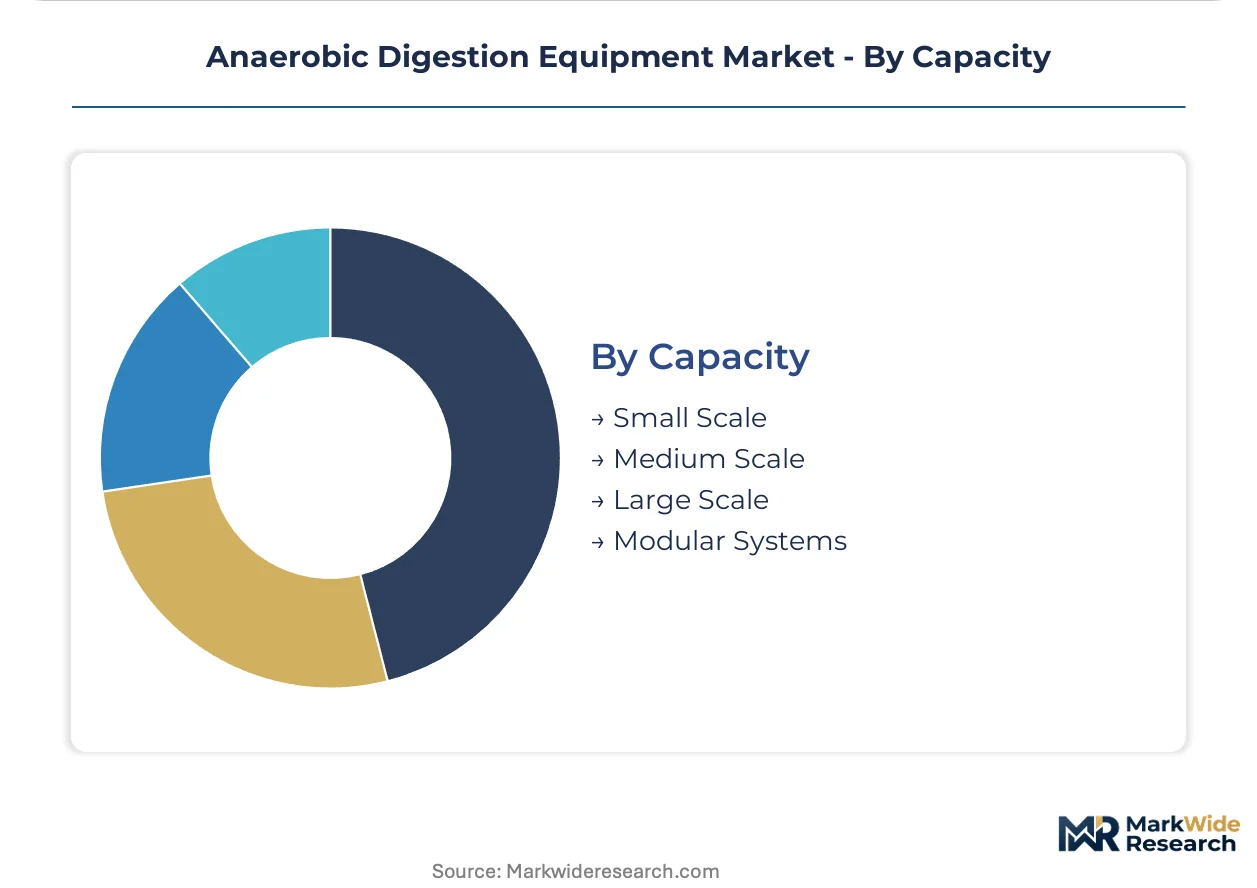
Capacity:
Customer type stratification separates cooperative procurement pools from fragmented farm-level leasing arrangements.
- Large Scale:Centralized digesters exceeding 500 kW electrical capacity serving multiple feedstock suppliers. Urban waste complexes integrate these with waste-to-energy infrastructure under multi-source supply agreements.
- Modular Systems:Containerized or skid-mounted units enabling rapid deployment and capacity expansion. Direct equipment leasing models to fragmented livestock farms bypass traditional cooperative procurement structures in emerging deployment channels.
- Small Scale:Sub-100 kW units for individual farm or small cooperative operation.
- Medium Scale:100-500 kW configurations serving single large farms or small cooperative clusters.
Large scale retains the dominant share, with modular systems ascending fastest through leasing penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's biogas capture retrofits outpace Denmark's cooperative digester buildouts, though both operate under shared EU Green Deal methane mandates. Equipment procurement concentrates where national carbon accounting frameworks and federal approval protocols create distinct investment timelines.
Germany
Municipal wastewater utilities drive biogas capture retrofits under Federal Environment Agency protocols. The Renewable Energy Sources Act imposes strict equipment approval timelines that compress project windows. The Ruhr industrial corridor concentrates demand for large-scale reactor vessels serving urban waste complexes.
Denmark
Dairy collectives pool procurement for shared digester infrastructure under national carbon accounting rules. Agricultural cooperative consolidation accelerates farm-scale deployments across Jutland's livestock belt. Copenhagen's equipment engineering cluster supplies turnkey membrane upgrading systems for biomethane grid injection.
Netherlands
Food processors specify automated Scope 3 emissions documentation systems for CSRD reporting obligations. The EMA's sustainability requirements compel industrial waste stream digestion investments. Rotterdam's port-industrial complex integrates biogas upgrading with carbon capture pilot projects.
France
Agricultural cooperatives in Brittany and Normandy deploy farm-scale digesters to monetize manure streams under EU methane reduction targets. ANSM leak detection mandates for biomethane injection reshape sensor array specifications. The Paris Basin concentrates engineering procurement for hybrid reactor architectures.
Italy
Agri-waste valorization channels expand through direct equipment leasing models to fragmented livestock farms in Emilia-Romagna. National transposition of F-Gas Regulation protocols accelerates certification requirements for grid injection projects. Lombardy's dairy processing belt drives demand for digestate management systems.
Anaerobic Digestion Equipment Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across reactor fabrication and gas upgrading segments. The vendor base stratifies into three tiers: German engineering houses with turnkey delivery capabilities, membrane technology specialists with proprietary separation systems, and Japanese industrial conglomerates with waste-to-energy integration expertise. Consolidation pressures intensify as substrate diversification requirements favor modular reactor architectures. Competitive moves center on technology licensing partnerships and backward integration into stainless steel fabrication.
Among German-based engineering specialists, WELTEC BIOPOWER GmbH and EnviTec Biogas AG occupy positions anchored in federal approval expertise and membrane upgrading technology respectively. Hitachi Zosen Inova represents the diversified industrial conglomerate archetype with waste-to-energy integration capabilities. JDV Equipment Corporation exemplifies North American-focused reactor fabrication specialists serving agricultural and municipal segments. These three archetypes—engineering pure-plays, technology licensors, and integrated conglomerates—define competitive positioning as EU regulatory harmonization accelerates equipment standardization.
| Leading Market Players |
|---|
| WELTEC BIOPOWER GmbH |
| JDV Equipment Corporation |
| EnviTec Biogas AG |
| ADI Systems Inc. |
| Ovivo |
| PlanET Biogas |
| DVO Inc. |
| Renergon Biogas AG |
| Hitachi Zosen Inova |
| Others |
Supply Flow & Price Mechanics
Family-owned German engineering houses anchor reactor vessel fabrication, transmitting stainless steel input volatility directly into equipment pricing while maintaining margin discipline through long-term municipal utility contracts.
Pricing Analysis
Capacity additions in Poland and the Czech Republic are reshaping price floors for standardized reactor components, pressuring incumbent German fabricators. Three-tier pricing structure across premium, standard, and economy levels separates turnkey EPC packages from equipment-only procurement and direct-to-farm leasing arrangements. Price differentiation hinges on Federal Environment Agency certification status and after-sales service bundling. Dairy cooperatives in Denmark exhibit highest price sensitivity due to carbon credit revenue dependency, while German wastewater utilities absorb premium pricing for guaranteed approval timelines.
Supply Chain Analysis
Skilled welder shortages in northern Italy and eastern Germany constrain reactor vessel output despite stainless steel availability. Manufacturing gravity centers on Germany, Denmark, and the Netherlands for precision-engineered components. Nickel and chromium feedstock draws from South African and Indonesian mining operations. Single-source vulnerability in membrane upgrading technology creates procurement risk for biomethane injection projects. Distribution runs through engineering-procurement-construction contractors with direct municipal utility relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Germany's stringent approval premiums and Italy's emerging leasing channels, exploiting regulatory cost differentials under shared EU methane mandates.
For Market Incumbents: To counter modular system entrants from Eastern Europe, WELTEC BIOPOWER GmbH and EnviTec Biogas AG should deepen backward integration into stainless steel fabrication and secure captive membrane supply agreements. Certification investment under F-Gas Regulation protocols preserves pricing power in grid injection segments. For New Entrants and Emerging Players: Capture direct equipment leasing white space among fragmented livestock farms in Italy's Emilia-Romagna and Spain's Castile-León regions, bypassing cooperative procurement structures. Agri-waste valorization partnerships with food processors offer lowest competitive density. For Investors and Strategic Acquirers: Industrial conglomerates with waste-to-energy capabilities are the most active acquirer in this space, seeking membrane technology tuck-ins. Target pure-play monitoring solution providers with IoT-enabled sensor platforms. Watch biomethane-to-bio-LNG pathway development as inflection signal for upgrading equipment demand.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Technology Licensing | Proprietary separation systems unlock biomethane grid injection under F-Gas Regulation mandates. |
| IoT Sensor Platform Acquisition | Predictive retention algorithms address process biology expertise scarcity in thermophilic operations. |
| Stainless Steel Fabrication Integration | Captive supply of nickel-chromium alloys insulates margins from South African mining volatility. |
| Direct Farm Leasing Expansion | Equipment-as-a-service models penetrate Italy's fragmented livestock sector beyond cooperative structures. |
| Carbon Capture Pilot Partnerships | Rotterdam's port-industrial complex demonstrates biomethane-to-bio-LNG pathway commercialization. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement covered digester operators at Danish dairy cooperatives, procurement officers at German municipal wastewater utilities, engineering directors at membrane technology specialists, and sustainability leads at Netherlands food processors. Secondary validation drew from Federal Environment Agency approval databases, EU Green Deal implementation trackers, F-Gas Regulation certification registries, and stainless steel trade flow data. Bottom-up equipment shipment tallies and top-down carbon credit revenue estimates were cross-referenced.
Historical reference periods anchored the projection horizon to pre-pandemic capital expenditure baselines and post-Green Deal regulatory acceleration phases. Segmentation modeling spanned reactor configuration, technology tier, end-use application, and capacity scale. CAGRs were derived from equipment order book trajectories and biomethane injection target compliance deadlines. Forecast inputs incorporated CSRD reporting obligation timelines and national carbon accounting framework adoption rates.
Feedstock security disruptions, membrane supply concentration, and hydrogen substitution policy shifts are the dominant revision risks to equipment demand assumptions. Forecasts reflect documented regulatory implementation trajectories and stainless steel price assumptions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste to Energy Systems
Brazil Waste to Energy Market
Waste to Energy Systems
ORC Waste Heat to Power Market
Waste to Energy Systems
North America Waste to Energy Market
Waste to Energy Systems
China Waste to Energy Market
Waste to Energy Systems
Nuclear Waste Management Market
Waste to Energy Systems
Asia-Pacific Waste-To-Energy Market
Waste to Energy Systems
Drilling Waste Management Services Market
Waste to Energy Systems
United States Waste to Energy Market
Waste to Energy Systems
Japan Waste to Energy Market
Waste to Energy Systems
ORC Industrial Waste Heat to Power Market
Waste to Energy Systems
Marine Incinerators Market
Waste to Energy Systems
APAC Waste Heat Recovery Systems Market
Waste to Energy Systems
Nuclear Waste Recycling Market
Waste to Energy Systems
Waste to Diesel Market
Waste to Energy Systems
Southeast Asia Waste-To-Energy Market
Waste to Energy Systems
Europe Waste-To-Energy Market