
 Azerbaijan Oil and Gas Downstream Market | 2026-2036
Azerbaijan Oil and Gas Downstream Market Size, Share, and Industry Trends Forecast 2026-2036
Azerbaijan Oil and Gas Downstream Market Outlook
Advanced hydrocracking and residue upgrading technology is reshaping how Azerbaijan's refineries process heavy sour crudes into higher-value products. SOCAR leverages its integrated upstream-to-retail structure to dominate domestic fuel supply. LUKOIL Azerbaijan anchors its position through technology transfer from Russian refining complexes. BP Azerbaijan competes by applying international project standards to downstream joint ventures.
Azerbaijan oil and gas downstream operations encompass refining crude oil into transportation fuels, producing olefins and aromatics for chemical synthesis, and blending lubricants and asphalts for industrial use. Modern downstream facilities achieve conversion rates exceeding 90% through catalytic cracking and hydrotreating units designed to meet Euro-5 sulfur specifications. Refined fuels leads product type demand due to sustained automotive and power generation consumption across the Caspian corridor. Petrochemicals represents the fastest-expanding segment as SOCAR Polymer and Azerikimya Production Union build polyethylene and methanol capacity for export to Turkey and Georgia.
Azerbaijan's Ministry of Ecology and Natural Resources enforces emission limits aligned with EU F-Gas Regulation principles for industrial refrigerants and process gases. The State Oil Fund of Azerbaijan channels hydrocarbon revenues into downstream infrastructure while the country's national standards body applies BIS-equivalent technical regulations for petroleum product quality. Stakeholders must monitor regulatory alignment with European Green Deal carbon border adjustments as these will determine export competitiveness for refined products and petrochemical intermediates.
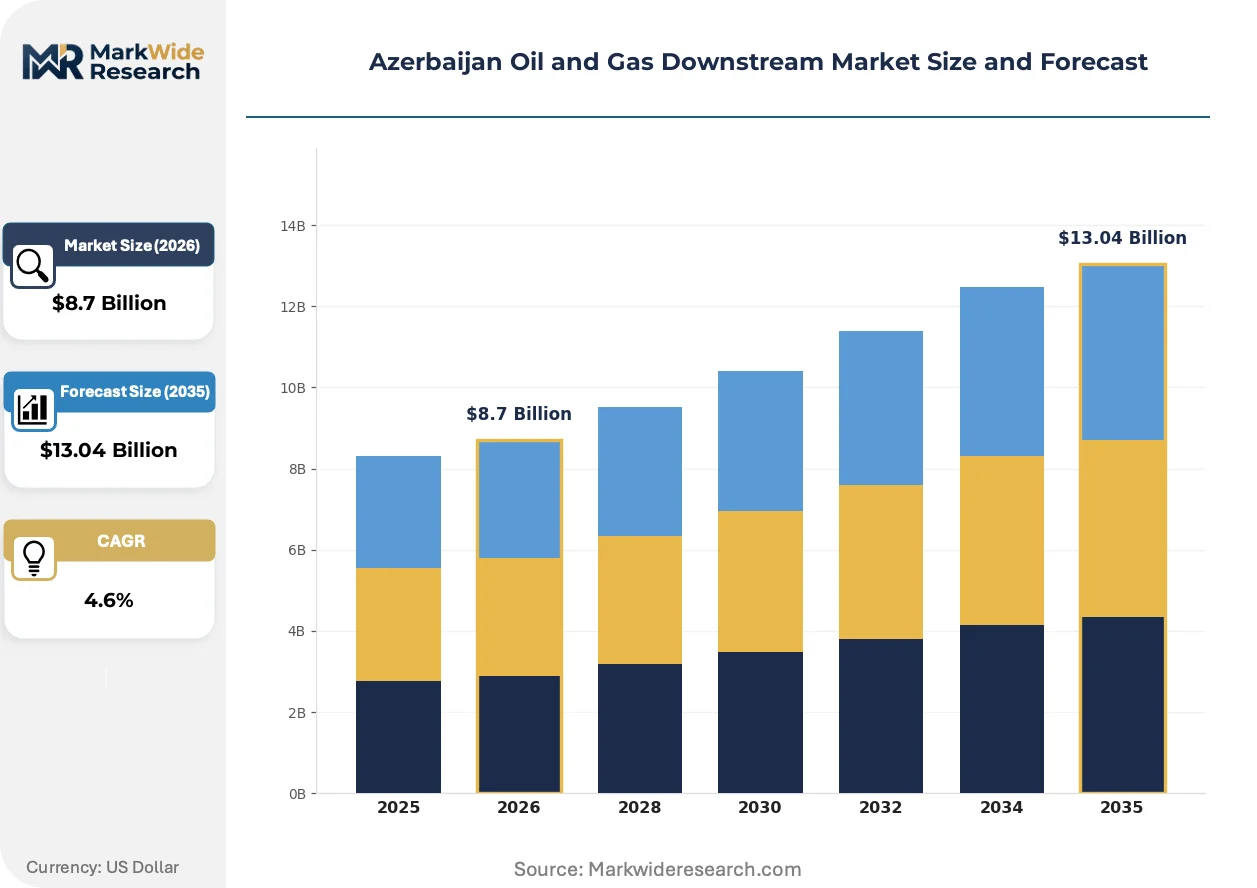
Market Dynamics
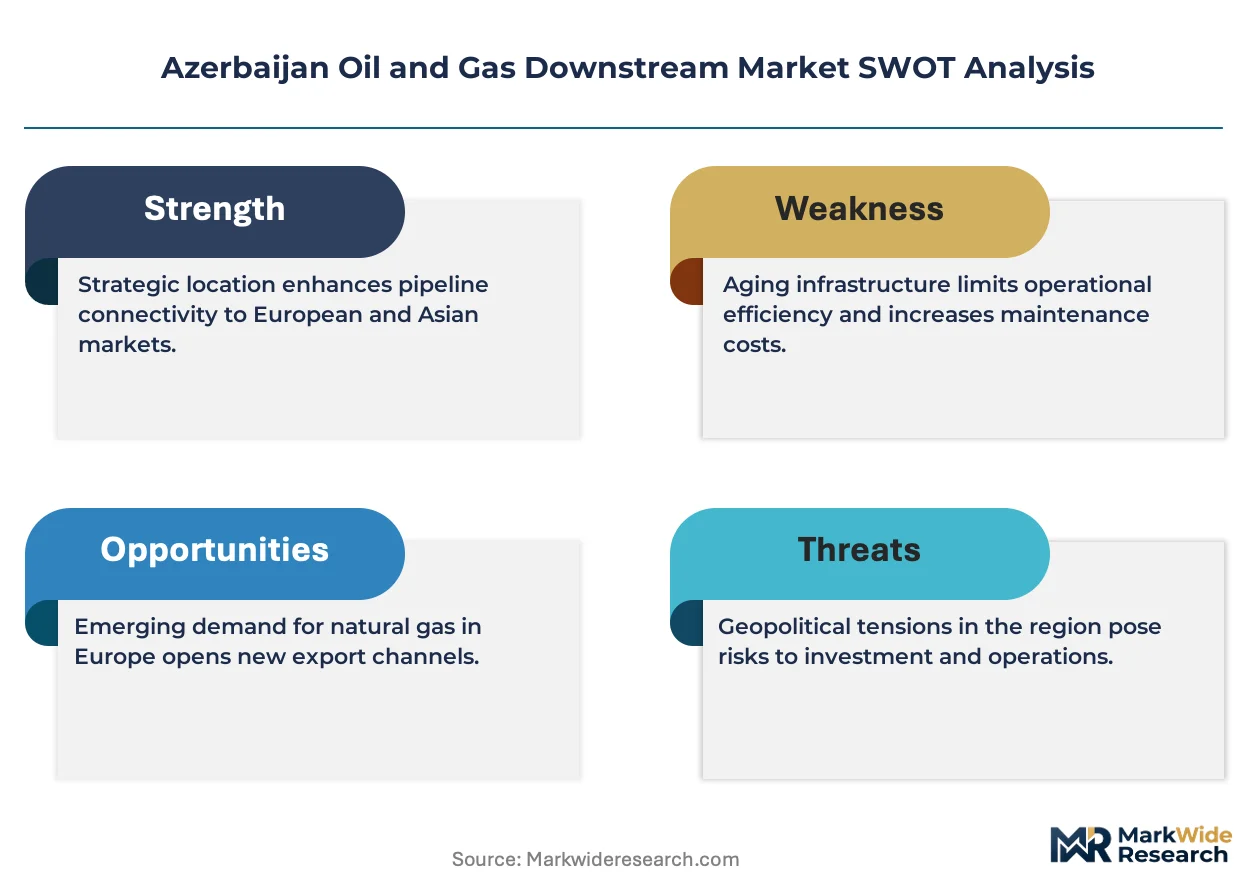
Refinery modernization programs and Euro-5 sulfur specifications are compressing margins for facilities lacking residue upgrading capacity, forcing capital allocation toward hydrocracking and coker units.
Growth Catalysts
- Domestic automotive fuel consumption:Rising vehicle ownership across Baku and Ganja sustains demand for gasoline and diesel through SOCAR's retail network.
- EU F-Gas Regulation alignment:Azerbaijan's Ministry of Ecology enforces emission limits that position refined products for European export eligibility.
- Catalytic cracking upgrades:New reactor configurations at Heydar Aliyev Baku Oil Refinery push conversion rates past legacy thresholds.
Market Restraints
- Heavy sour crude dependency:Limited access to light sweet grades forces higher hydrogen consumption and processing costs.
- Single-supplier catalyst risk:Specialized hydroprocessing catalysts concentrate with Russian and German vendors, creating supply vulnerability.
- Carbon border adjustment exposure:EU Green Deal mechanisms threaten export competitiveness for high-carbon-intensity refined products.
Strategic Opportunities
- Georgia-Turkey pipeline corridor:Petrochemical intermediates face limited regional competition for polyethylene and methanol offtake.
- Dual-carbon technology pairing:Carbon capture integration with steam methane reforming offers low-carbon hydrogen for hydrotreating units.
- Industrial feedstock pivot:Chemical manufacturers in Sumqayit seek localized olefin supply to replace Black Sea imports.
Industry Challenges
- Specialized welding and pressure vessel certification:Construction of high-temperature reactor units requires ASME-qualified fabricators in short supply across the Caspian basin.
- Legacy DCS integration:Honeywell and Yokogawa control systems at Soviet-era refineries resist seamless migration to modern distributed architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Azerbaijan Oil and Gas Downstream Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Fuels, Petrochemicals, Lubricants, Asphalts Service Type: Transportation, Distribution, Storage, Retail End User: Automotive, Industrial, Residential, Commercial Application: Heating, Power Generation, Manufacturing, Fuel Supply |
| Companies Covered | SOCAR, SOCAR Heydar Aliyev Oil Refinery, SOCAR Petroleum, Azerikimya Production Union, Azpetrol Ltd, SOCAR Polymer, LUKOIL Azerbaijan, TotalEnergies Marketing Azerbaijan, BP Azerbaijan, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Azerbaijan Oil and Gas Downstream Market Strategic Shifts
Downstream operations in Azerbaijan are converging around digital process optimization, regulatory carbon accounting, and shifting offtake patterns toward chemical synthesis feedstocks.
Residue fluid catalytic cracking with integrated olefin recovery is hybridizing traditional fuel production with petrochemical output. SOCAR Polymer's procurement teams specify units yielding 40% propylene alongside gasoline. This configuration is hybridizing refinery economics away from pure transportation fuel margins.
EU F-Gas Regulation principles are reshaping refrigerant and process gas management across Azerbaijani industrial facilities. The Ministry of Ecology mandates leak detection protocols and phasedown schedules for high-GWP substances. Petrochemical cold chain operations face retrofit timelines compressing capital planning cycles.
Long-term offtake contracting is displacing spot market trading for polyethylene and methanol volumes. Turkish packaging manufacturers now secure three-year supply agreements directly with Azerikimya Production Union. This pattern concentrates negotiation leverage with integrated producers possessing dedicated logistics infrastructure.
Azerbaijan Oil and Gas Downstream Market Segmentation
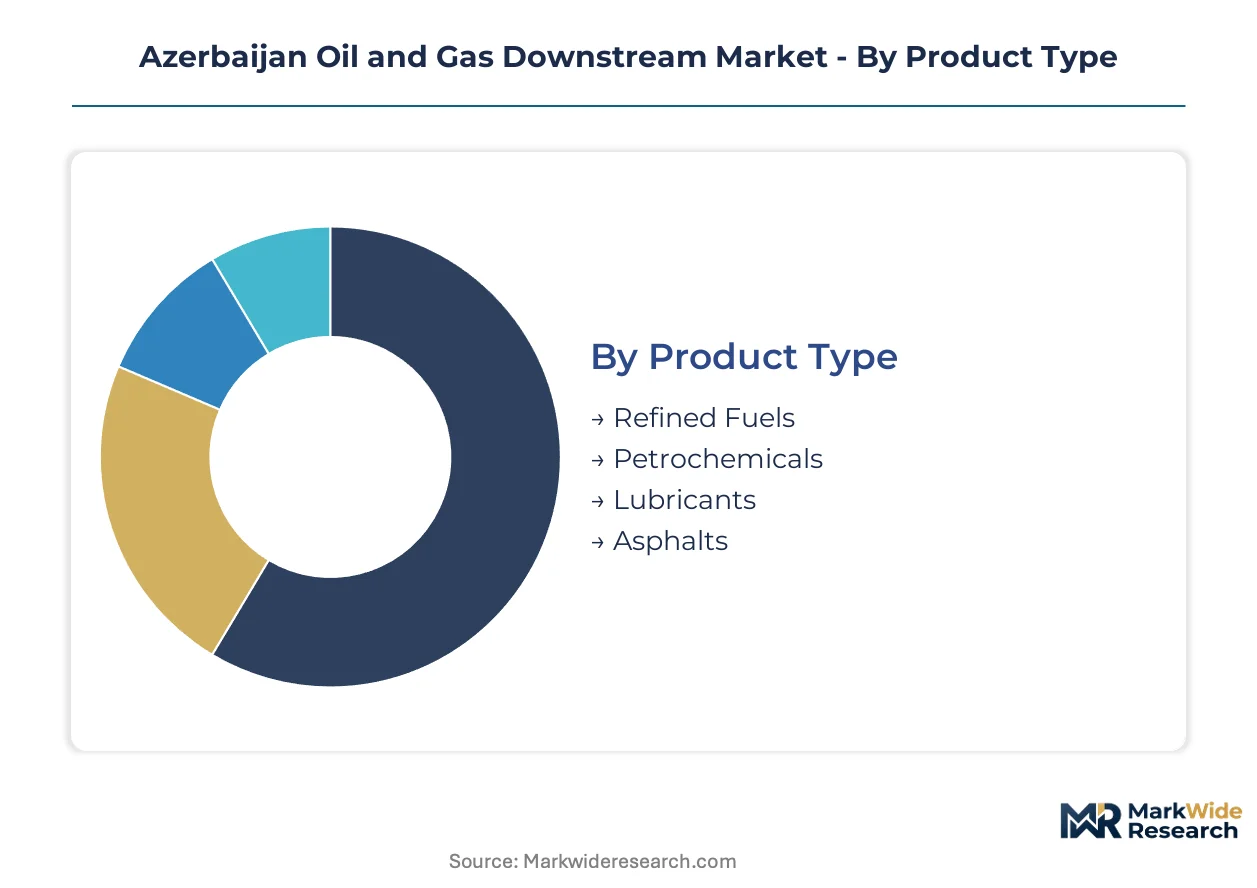
Downstream segmentation in Azerbaijan reveals how SOCAR's integrated operations allocate capital across fuel production, chemical synthesis, and logistics infrastructure. Each dimension captures distinct margin profiles and regulatory exposure that shape investment prioritization across the Caspian corridor.
Product Type:
Cost tier differentiation separates commodity fuels from specialty chemicals with divergent margin structures and capital intensity requirements.
- Refined Fuels:Gasoline, diesel, and kerosene processed at Heydar Aliyev Baku Oil Refinery through catalytic cracking and hydrotreating units meeting Euro-5 sulfur specifications. Demand concentrates in Baku's automotive sector and Ganja's transport corridors as vehicle ownership expands across western Azerbaijan.
- Petrochemicals:Polyethylene, methanol, and olefins manufactured at SOCAR Polymer and Azerikimya Production Union facilities for export to Turkish packaging manufacturers and Georgian chemical processors. This segment is climbing the fastest as long-term offtake contracts displace spot trading.
- Lubricants:Base oils and finished lubricant blends formulated for industrial machinery and automotive engines operating in Caspian climate conditions.
- Asphalts:Paving and roofing bitumen derived from vacuum residue processing for domestic road construction and infrastructure projects.
Refined fuels holds installed capacity. Petrochemicals is rotating up the share rankings.
Service Type:
Application scope spans the value chain from bulk commodity movement to final delivery at point of consumption.
- Transportation:Pipeline networks, rail tankers, and coastal vessels moving crude feedstock and refined products across the Caspian basin. Baku-Tbilisi-Ceyhan pipeline connectivity positions Azerbaijane volumes for Mediterranean offtake.
- Distribution:Terminal operations and secondary logistics coordinating bulk transfers to industrial consumers and retail networks throughout Absheron and Ganja regions.
- Storage:Strategic petroleum reserves and commercial tankage at Sangachal Terminal and private depots managing inventory for supply security.
- Retail:SOCAR-branded service stations and commercial fuel card programs covering gasoline, diesel, and compressed natural gas dispensing across urban centers.
Transportation commands infrastructure lock-in. Retail is rotating up the share rankings.
End User:
Customer type segmentation aligns product formulation and delivery logistics with consumption scale and technical specifications.
- Automotive:Individual vehicle owners and fleet operators purchasing gasoline, diesel, and lubricants through SOCAR's retail network and commercial supply contracts.
- Industrial:Manufacturing facilities in Sumqayit Chemical Industrial Park consuming petrochemical feedstocks and process fuels for polymer and synthetic material production.
- Residential:Household heating oil and liquefied petroleum gas demand concentrated in rural Azerbaijan beyond pipeline gas distribution coverage.
- Commercial:Hotels, retail complexes, and service businesses procuring diesel for backup power generation and heating across Baku's commercial districts.
Industrial holds installed capacity. Automotive is rotating up the share rankings.
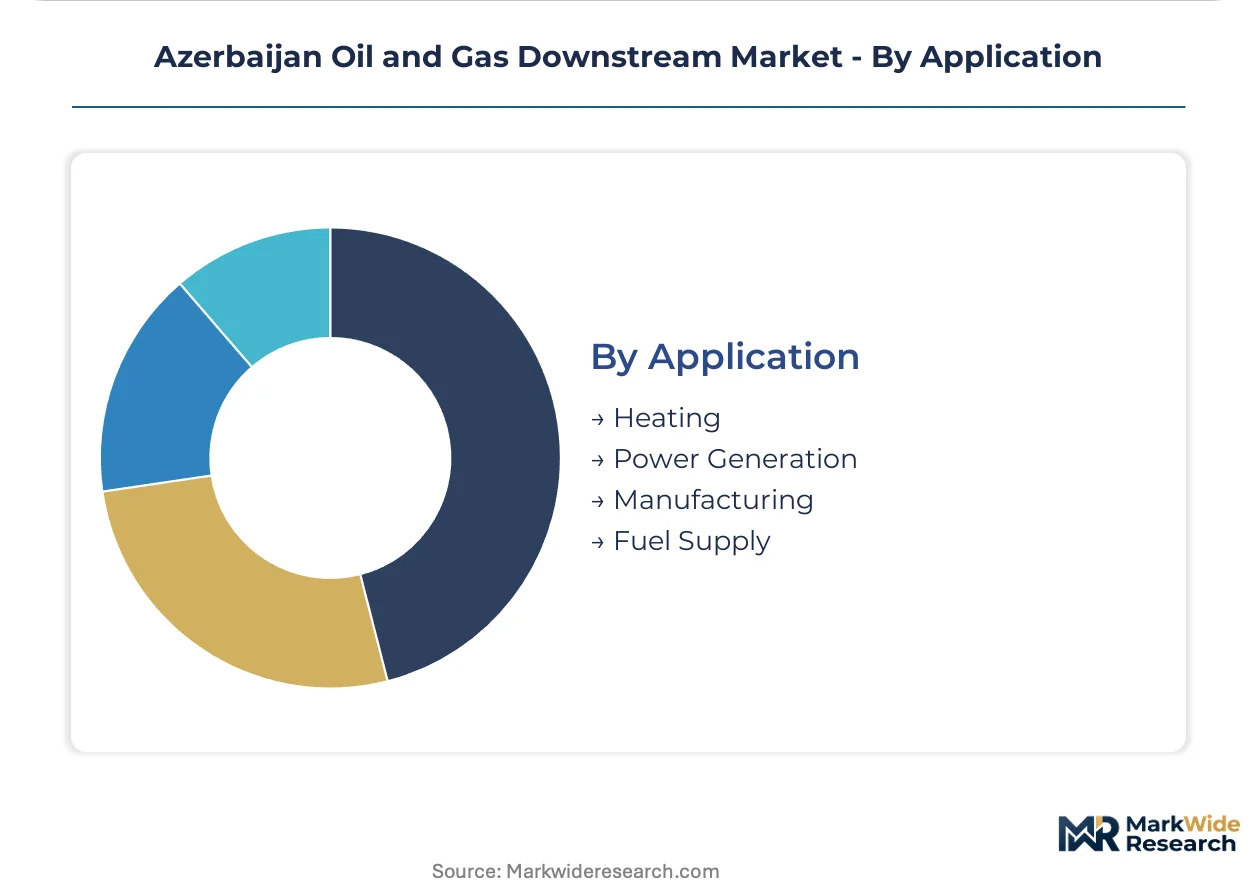
Application:
Volume concentration patterns reveal how downstream output splits between energy conversion and material synthesis end-uses.
- Heating:Fuel oil and natural gas combustion for residential and commercial thermal demand during Azerbaijan's winter heating season.
- Power Generation:Diesel and fuel oil firing at backup generators and remote industrial facilities lacking grid connectivity in Nakhchivan and offshore platforms.
- Manufacturing:Petrochemical feedstocks supplying polyethylene extrusion, methanol derivative synthesis, and synthetic rubber production at Sumqayit chemical complexes.
- Fuel Supply:Transportation energy delivered through retail stations, bulk terminals, and direct industrial offtake agreements across the domestic market.
Fuel supply holds installed capacity. Manufacturing is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Azerbaijan's downstream exports flow primarily through the Georgia-Turkey corridor toward Black Sea and Mediterranean markets, with SOCAR's integrated logistics infrastructure anchoring cross-border petrochemical and refined product movements.
Absheron Peninsula
Baku's automotive fleet expansion and Ganja's transport corridor development sustain gasoline and diesel consumption through SOCAR's retail network. The Ministry of Ecology enforces Euro-5 sulfur specifications that align refined products with EU export eligibility. Heydar Aliyev Baku Oil Refinery processes heavy sour crudes through upgraded catalytic cracking units.
Sumqayit Chemical Industrial Park
Polyethylene and methanol manufacturers seek localized olefin supply to replace Black Sea imports for polymer extrusion operations. The State Oil Fund channels hydrocarbon revenues into downstream infrastructure expansion. Azerikimya Production Union supplies Turkish packaging manufacturers through long-term offtake agreements.
Sangachal Terminal Zone
Strategic petroleum reserves and commercial tankage manage inventory for supply security across the Caspian basin. National standards bodies apply BIS-equivalent technical regulations for petroleum product quality. Coastal vessels and pipeline networks coordinate bulk transfers to industrial consumers.
Nakhchivan Autonomous Republic
Remote industrial facilities lacking grid connectivity depend on diesel and fuel oil for backup power generation. The national petroleum regulator oversees product quality certification for cross-border movements. Localized distribution networks bridge supply gaps beyond main pipeline coverage.
Shirvan-Ganja Corridor
Western Azerbaijan's vehicle ownership expansion drives retail fuel demand through SOCAR's commercial supply contracts. Environmental emission limits for industrial refrigerants reshape process gas management protocols. Road construction projects consume paving bitumen derived from vacuum residue processing.
Azerbaijan Oil and Gas Downstream Market Competitive Environment
On the supply side, the industry is consolidated around state-backed integrated operators with captive upstream access and international joint venture partners applying foreign technology standards. Three archetypes dominate: national oil companies controlling refining and retail infrastructure, international majors contributing project expertise through partnerships, and specialized petrochemical producers serving export markets. Competitive moves center on refinery modernization programs and long-term offtake contracting for polyethylene and methanol volumes.
Among state-integrated operators, SOCAR, SOCAR Polymer, and Azerikimya Production Union exemplify the vertically consolidated archetype, occupying positions that span crude procurement through refined product retail. LUKOIL Azerbaijan and BP Azerbaijan represent the international partnership model, anchoring technology transfer and standards alignment within joint venture structures. Azpetrol Ltd and TotalEnergies Marketing Azerbaijan sit within the specialized distribution tier, focusing on terminal operations and retail network logistics rather than upstream integration.
| Leading Market Players |
|---|
| SOCAR |
| SOCAR Heydar Aliyev Oil Refinery |
| SOCAR Petroleum |
| Azerikimya Production Union |
| Azpetrol Ltd |
| SOCAR Polymer |
| LUKOIL Azerbaijan |
| TotalEnergies Marketing Azerbaijan |
| BP Azerbaijan |
| Others |
Value Chain & Pricing Dynamics
Single-supplier catalyst dependency for hydroprocessing units concentrates pricing power with Russian and German vendors, compressing margin spreads between legacy fuel production and upgraded petrochemical-capable refining while forcing procurement teams toward long-term offtake contracting to lock in feedstock security.
Pricing Analysis
Prior-generation catalytic cracking configurations trade at steep discounts to residue-upgraded hydrocracking units capable of 90% conversion rates. Three-tier pricing structure across premium Euro-5 certified products, standard domestic-grade fuels, and economy-tier vacuum residue separates SOCAR's retail network from spot-market traders. Cost compression in the economy tier intensifies because heavy sour crude dependency forces higher hydrogen consumption per barrel. Industrial manufacturers in Sumqayit exhibit highest price sensitivity due to import substitution pressures, while Turkish packaging buyers securing polyethylene offtake show lowest sensitivity due to logistics reliability premiums.
Supply Chain Analysis
Export control regimes on advanced hydrocracking catalysts and pressure vessel fabrication technology limit flows from Germany and the United States into Caspian basin projects. Manufacturing concentration in Russia, Germany, and South Korea for specialized reactor components creates procurement bottlenecks for ASME-qualified fabricators. Raw material dependencies on vacuum gas oil, hydrogen feedstock, and metallurgical coke expose margins to commodity volatility in global energy markets. Distribution runs through Baku-Tbilisi-Ceyhan pipeline corridors and coastal vessel networks coordinating bulk transfers to Black Sea terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrification of transport fleets and renewable diesel substitution threaten refined fuel demand, forcing incumbents to defend petrochemical pivot positions while new entrants exploit logistics infrastructure gaps.
For Market Incumbents: Build regulatory certification moats around EU F-Gas Regulation alignment and carbon border adjustment readiness to defend export eligibility. SOCAR should deepen backward integration into olefin production at Sumqayit to capture margin migrating from fuels to chemical synthesis. Incumbents must secure ASME-qualified welding capacity through captive training programs or joint venture partnerships before construction bottlenecks worsen. For New Entrants and Emerging Players: Mid-scale lubricant blending facilities serving Ganja's industrial corridor represent the most penetrable entry point given limited SOCAR retail presence in western Azerbaijan. New entrants should target petrochemical logistics services—specialized tankage and cold chain refrigerant management—where incumbent infrastructure shows coverage gaps. A go-to-market angle anchored on dual-carbon hydrogen supply contracts for hydrotreating units bypasses direct refining competition. For Investors and Strategic Acquirers: The market sits at a capital-intensive modernization phase that favors integrated operators with captive upstream access and state-backed financing capacity. Long-term viability hinges on petrochemical capacity utilization rates and Turkish offtake contract renewals. Investors should monitor carbon border adjustment implementation timelines as the critical inflection signal for refined product export competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Residue Upgrading Capacity Expansion | Heydar Aliyev Baku Oil Refinery conversion rate targets past 90% through hydrocracker installation. |
| Backward Integration into Olefin Production | SOCAR Polymer polyethylene capacity captures margin migrating from transportation fuels to chemical feedstocks. |
| Long-term Supply Agreement Structuring | Three-year Turkish packaging manufacturer contracts displace spot trading and concentrate negotiation leverage. |
| Carbon Capture Integration Partnership | Dual-carbon hydrogen production for hydrotreating units addresses EU Green Deal carbon intensity thresholds. |
| ASME Certification Pipeline Development | Specialized welding capacity buildup mitigates construction bottlenecks for high-temperature reactor units. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with refinery operations managers, petrochemical procurement leads, and Ministry of Ecology regulatory officers, combined with secondary validation through customs trade records, SOCAR infrastructure disclosures, and EU F-Gas Regulation implementation documentation. Bottom-up capacity utilization modeling triangulated against top-down hydrocarbon revenue allocation patterns from State Oil Fund reports anchored volume estimates.
Forecast inputs considered refinery modernization capex cycles, catalytic cracking upgrade deployment timelines, and polyethylene offtake contract renewal patterns across the projection horizon. Segmentation modeling captured product type tiers, service type logistics structures, end-user consumption scales, and application-based demand splits. CAGRs derived from capacity expansion schedules and regional demand elasticity assumptions for automotive fuel and industrial feedstock segments.
Practitioners should monitor EU carbon border adjustment implementation schedules and Turkish petrochemical import policy shifts for early signals of demand displacement. Forecasts reflect assumptions around SOCAR modernization program execution rates and Black Sea logistics corridor stability. Material shifts in EU Green Deal enforcement stringency or Caspian basin geopolitical access would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Colombia Oil and Gas Downstream Market
Oil & Gas
US Sand Control Systems Market
Oil & Gas
Middle-East and Africa Frac Stack Market
Oil & Gas
Downhole Equipment Market
Oil & Gas
Canada LNG Market
Oil & Gas
Southeast Asia Oil and Gas EPC Market
Oil & Gas
Seismic Survey Equipment Market
Oil & Gas
Mexico Wireline Services Market
Oil & Gas
Oman Directional Drilling Market
Oil & Gas
Tricone Bits Market
Oil & Gas
Southeast Asia Oil and Gas Downstream Market
Oil & Gas
GCC Natural Gas Market
Oil & Gas
United States Natural Gas Market
Oil & Gas
Oil and Gas Refinery Maintenance Services Market
Oil & Gas
Oil and Gas Swell Packers Market
Oil & Gas
Whipstocks Market